
 Chordoma Disease Market | 2026-2036
Chordoma Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Chordoma Disease Market Analysis
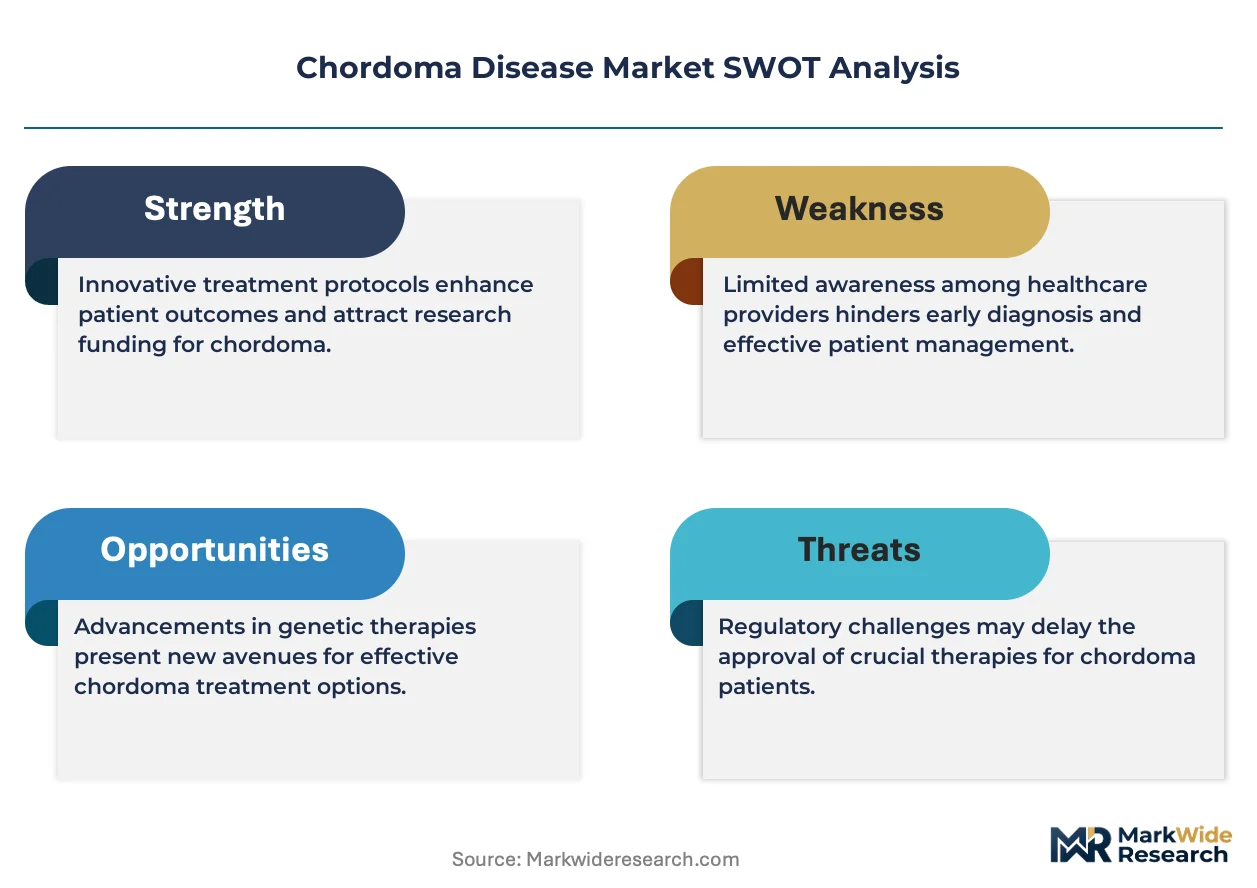
Specialized oncology care tier is rotating toward precision-directed protocols for rare bone malignancies. Pfizer leverages its targeted therapy infrastructure to address kinase-driven chordoma subpopulations. Bavarian Nordic sustains vaccine-platform expertise that translates into differentiated immuno-oncology positioning. Bristol-Myers Squibb anchors its presence through checkpoint inhibitor portfolios applicable to refractory cases.
Chordoma is a rare malignant bone tumor arising from notochordal remnants, characterized by brachyury transcription factor expression and typical midline skeletal distribution from clivus to coccyx. Its primary clinical purpose demands multimodal management combining maximal surgical resection with advanced radiation techniques due to local invasiveness and recurrence propensity. Treatment type segmentation shows surgery and radiation therapy occupying established standard-of-care positions, while immunotherapy represents the fastest-growing category driven by brachyury-targeted vaccine trials. Drug class segmentation reveals targeted therapy commanding premium margin pools, with biologics gaining traction through monoclonal antibody and vaccine constructs.
FDA orphan drug incentives and EMA's priority medicines scheme shape development economics by compressing trial timelines and extending market exclusivity for chordoma therapeutics. The EU AI Act and FDA's digital health guidance increasingly govern radiomics-based diagnosis and AI-assisted surgical planning that chordoma centers deploy. Japan's PMDA Sakigake designation accelerates access for novel radiation sensitizers in skull-base applications. Stakeholders must monitor brachyury biomarker standardization and decentralized proton therapy capacity as determinants of future competitive positioning.
Market Dynamics
FDA Breakthrough Therapy designations for brachyury-targeted vaccines are compressing clinical development timelines and redirecting R&D capital toward precision immunotherapy platforms for this ultra-rare indication.
Growth Catalysts
- Orphan Drug Incentives:FDA's extended market exclusivity provisions and tax credits de-risk development economics for chordoma therapeutics, attracting venture funding into early-stage programs.
- Proton Therapy Infrastructure:United States academic medical centers are commissioning dedicated skull-base radiation suites, expanding referral capacity for complex chordoma resections requiring adjuvant particle therapy.
- Biomarker Standardization:Brachyury immunohistochemistry protocols are achieving cross-laboratory harmonization, enabling patient stratification for targeted clinical trial enrollment.
Market Restraints
- Clinical Trial Recruitment:Incidence below 0.08 per 100,000 population creates enrollment bottlenecks, forcing sponsors to maintain multi-year, multi-site commitment horizons.
- Reimbursement Complexity:Proton therapy coverage determinations vary across US commercial payers and CMS local contractors, creating access friction for skull-base cases.
- Specialized Surgical Capacity:En-bloc sacral resection expertise concentrates at fewer than 40 global referral centers, limiting patient throughput for high-complexity cases.
Strategic Opportunities
- Japan's Sakigake Pathway:PMDA priority review vouchers for rare cancers accelerate regulatory timelines, creating first-mover positioning for novel radiation sensitizers in clival applications.
- Radiomics Integration:AI-assisted surgical margin prediction algorithms trained on chordoma MRI signatures enable personalized resection planning at decentralized treatment sites.
- Adjuvant Vaccine Protocols:Post-surgical brachyury peptide immunotherapy represents addressable white space between standard radiation and salvage systemic options.
Industry Challenges
- Skull-Base Surgical Training:Extended learning curves for endoscopic endonasal approaches limit workforce scalability at expanding academic networks.
- Cross-Border Trial Coordination:Divergent EMA and FDA biomarker qualification requirements fragment protocol design for international chordoma studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chordoma Disease Market |
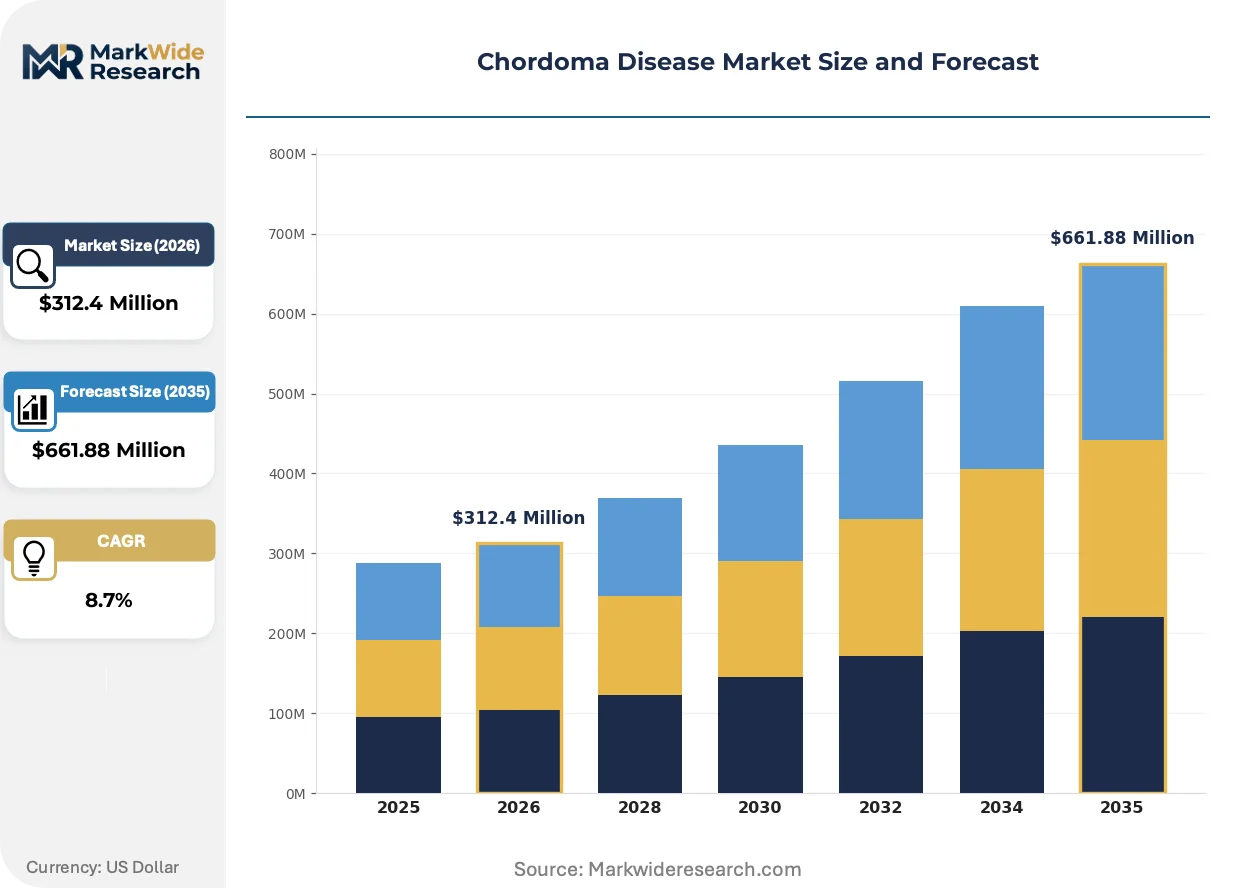
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Surgery, Radiation Therapy, Chemotherapy, Immunotherapy Drug Class: Targeted Therapy, Pain Management, Biologics, Antineoplastics End User: Hospitals, Clinics, Research Laboratories, Rehabilitation Centers Diagnosis Method: Imaging Tests, Biopsy, Genetic Testing, Histopathology |
| Companies Covered | Pfizer, Bavarian Nordic, Bristol-Myers Squibb, Eli Lilly and Company, Amgen, Novartis, AstraZeneca, Bayer, Merck & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chordoma Disease Market Emerging Trajectories
Precision medicine architectures are displacing anatomical staging systems in rare bone malignancy management, with molecular stratification now governing treatment sequencing decisions across major referral networks.
Brachyury-directed CAR-T cell engineering is bifurcating adoptive immunotherapy development for chordoma. Early-phase academic sponsors are advancing construct optimization against this lineage-specific transcription factor. The approach is compressing traditional antibody-drug conjugate timelines as cellular platforms demonstrate durable responses in refractory sacral presentations.
EMA's priority medicines scheme is accelerating assessment timelines for orphan oncology assets, compressing the gap between phase II readouts and conditional marketing authorization. Sponsors are restructuring development programs to align with PRIME eligibility criteria, prioritizing biomarker-enriched cohorts. Germany's reference pricing corridors for hospital-administered radiopharmaceuticals are adapting to accommodate novel isotope conjugates in skull-base protocols.
Patient advocacy networks are consolidating referral pattern intelligence, creating direct-to-specialist navigation that bypasses primary care gatekeepers. Chordoma Foundation registries in the United States and Europe are channeling diagnosed patients toward molecular profiling programs and trial-matching services. This channel compression is most pronounced in Germany, where centralized rare disease centers coordinate cross-border second opinions.
Chordoma Disease Market Segmentation
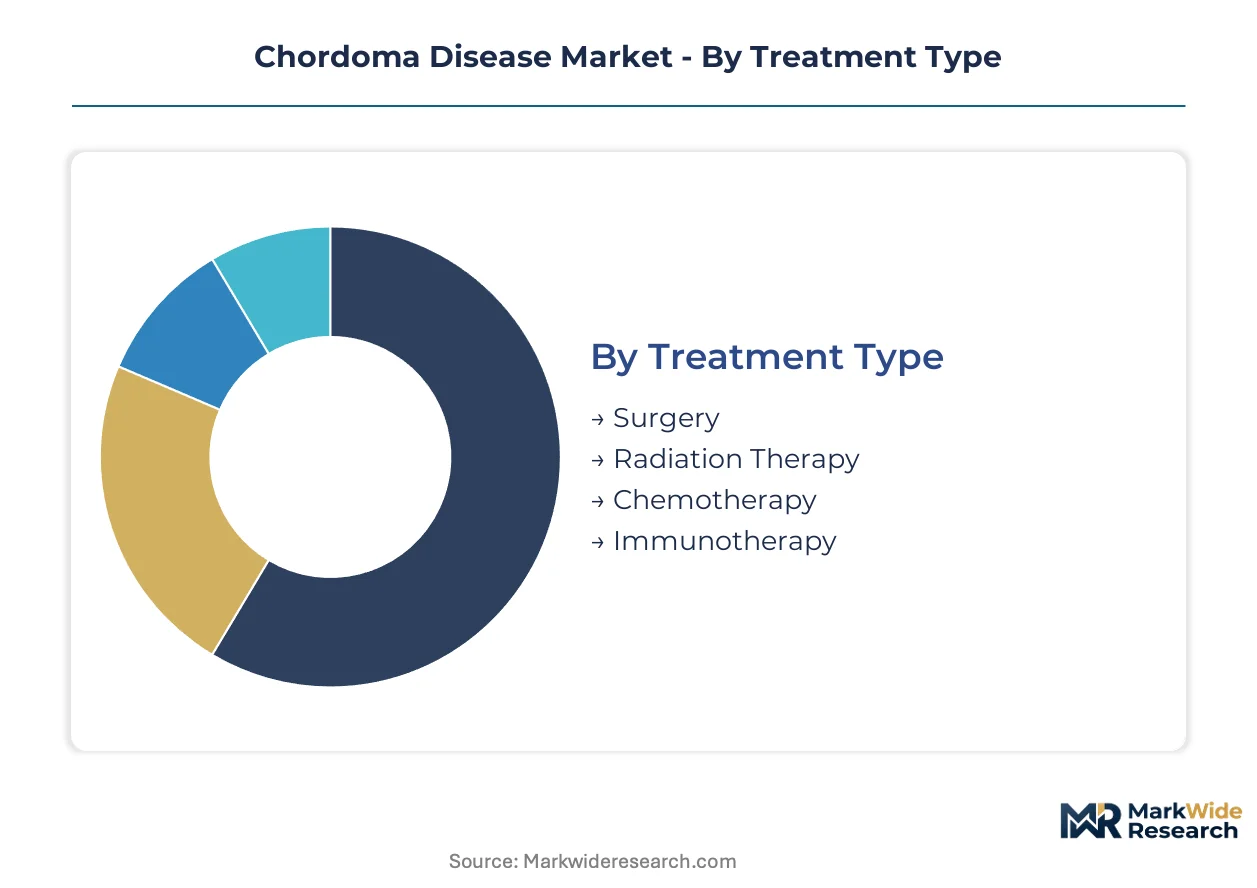
Chordoma care pathways fragment across specialized intervention modalities, each governed by distinct reimbursement codes and facility certification requirements. Treatment sequencing decisions at academic medical centers now hinge on molecular stratification rather than anatomical staging alone.
Treatment Type:
FDA Breakthrough Therapy designations and CMS proton therapy coverage determinations create divergent access economics across intervention categories.
- Surgery:En-bloc resection with negative margins remains the foundational intervention for sacral and mobile spine presentations. Demand concentrates at the University of Texas MD Anderson Cancer Center and Heidelberg University Hospital, where dedicated skull-base teams maintain sub-5% positive margin rates through intraoperative navigation protocols.
- Radiation Therapy:Proton beam and carbon-ion modalities deliver dose escalation with reduced exit toxicity for clival and cervical chordomas. Germany's Heidelberg Ion-Beam Therapy Center and Japan's National Institute of Radiological Sciences anchor referral networks for particle therapy, though US commercial payer coverage variability creates access friction.
- Chemotherapy:Conventional cytotoxic agents demonstrate limited efficacy against brachyury-driven tumor biology. Academic protocols at Memorial Sloan Kettering Cancer Center explore platinum-taxane combinations for dedifferentiated subtypes.
- Immunotherapy:Brachyury-targeted peptide vaccines and checkpoint inhibitors represent the steepest expansion trajectory, with NCI-sponsored trials compressing development timelines through orphan drug incentives.
Established volume favors surgery; emerging adoption favors immunotherapy.
Drug Class:
Margin structures vary sharply between small-molecule kinase inhibitors and biologic constructs, with manufacturing complexity driving pricing stratification.
- Targeted Therapy:CDK4/6 and PI3K pathway inhibitors command premium positioning through companion diagnostic requirements. Pfizer's palbociclib infrastructure and Novartis's alpelisib portfolios address chordoma-relevant kinase dependencies, though brachyury-specific targets remain preclinical.
- Pain Management:Long-acting opioid formulations and neuropathic agents support palliative protocols for unresectable sacral presentations. Cleveland Clinic's supportive oncology programs integrate multimodal analgesia with radiation sequencing.
- Biologics:Monoclonal antibodies and vaccine platforms gain traction through Bavarian Nordic's MVA-BN-brachyury construct and academic CAR-T engineering at Stanford University. Manufacturing scale constraints limit near-term volume.
- Antineoplastics:Alkylating agents and antimetabolites occupy salvage therapy positioning following progression on targeted protocols. Memorial Sloan Kettering maintains compassionate-use pathways for temozolomide combinations.
Revenue concentration sits with targeted therapy; pipeline momentum concentrates in biologics.
End User:
Facility reimbursement tiers and case volume thresholds determine competitive positioning across care settings.
- Hospitals:Academic medical centers with dedicated sarcoma programs capture complex resections requiring intraoperative MRI and proton adjuvancy. The University of California San Francisco and Massachusetts General Hospital maintain annual case volumes exceeding 30 chordoma procedures.
- Clinics:Community oncology practices manage surveillance protocols and systemic therapy administration for stable disease. EMA's cross-border healthcare directives enable German patients to access French proton facilities through prior authorization.
- Research Laboratories:NCI-designated cancer centers and European Reference Networks conduct biomarker qualification studies. The Chordoma Foundation's biorepository at Duke University supplies annotated specimens for brachyury assay validation.
- Rehabilitation Centers:Spinal cord injury specialists at Craig Hospital and Shepard Center address sacrectomy-related pelvic floor dysfunction. Outcome measurement protocols remain institution-specific.
Complex case concentration favors hospitals; longitudinal care coordination favors clinics.
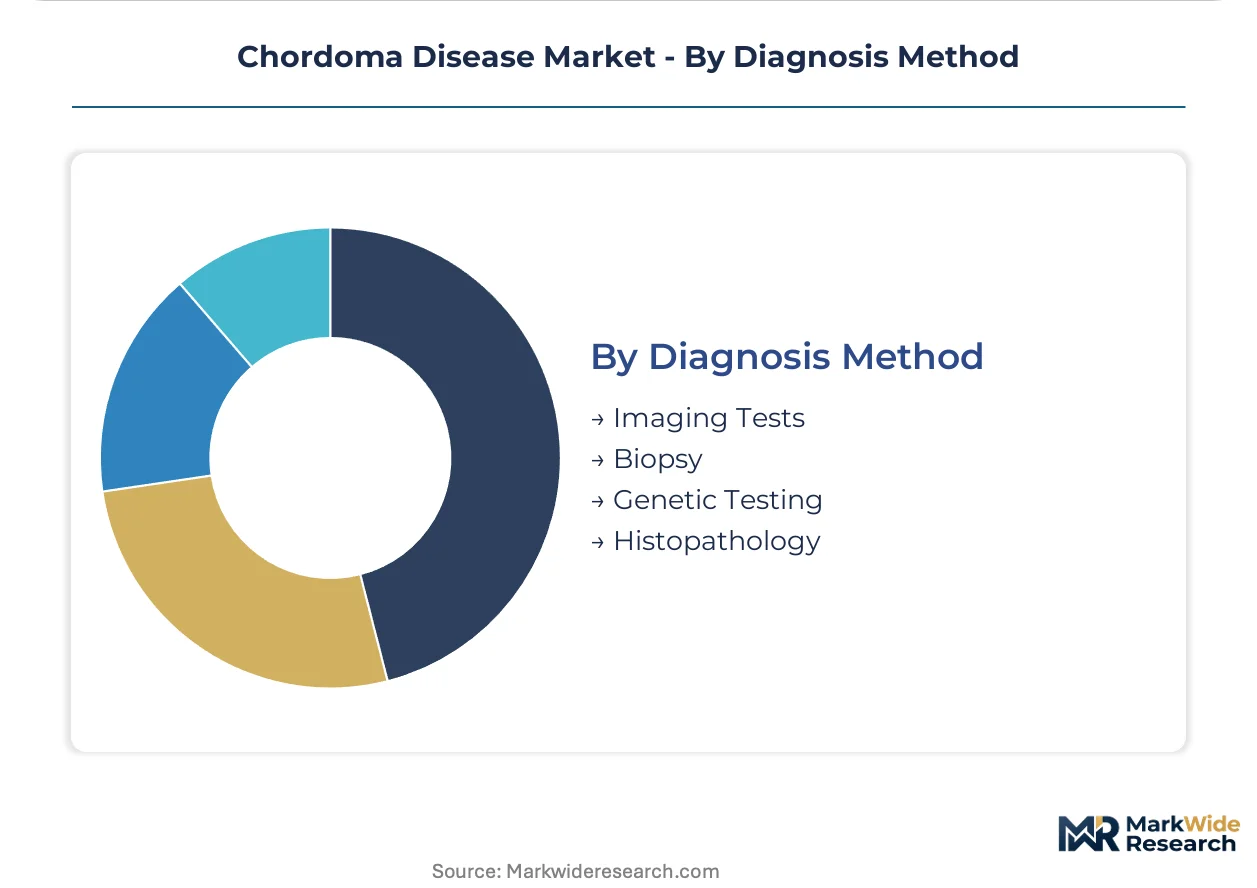
Diagnosis Method:
Regulatory pathways for AI-assisted interpretation diverge between FDA's software-as-medical-device framework and EMA's in-vitro diagnostic regulations.
- Imaging Tests:MRI with diffusion-weighted sequences and CT angiography define tumor extent and vascular relationships. Stanford's radiomics group deploys machine learning classifiers trained on chordoma MRI signatures to differentiate from chondrosarcoma.
- Biopsy:CT-guided core needle sampling at experienced centers achieves diagnostic yield above 90% for sacral lesions. The French Sarcoma Group mandates central pathology review for trial eligibility.
- Genetic Testing:Next-generation sequencing panels identify actionable alterations in PI3K-AKT and MAPK pathways. Foundation Medicine's comprehensive genomic profiling reports brachyury expression status for clinical trial matching.
- Histopathology:Brachyury immunohistochemistry serves as the diagnostic gold standard, with CAP proficiency testing programs addressing inter-laboratory variability. Japan's PMDA recognizes brachyury IHC as a companion diagnostic for vaccine trials.
Diagnostic standardization favors histopathology; precision enrollment favors genetic testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chordoma treatment demand exhibits sharp elasticity variation across geographies. United States patients face the highest out-of-pocket exposure for proton therapy, while Japanese and German systems compress price sensitivity through comprehensive public coverage. This divergence shapes where novel therapies launch first versus where volume accumulates.
United States
Academic medical centers at MD Anderson, Massachusetts General Hospital, and UCSF anchor surgical referral networks for complex skull-base and sacral resections. FDA Breakthrough Therapy designations for brachyury-targeted vaccines compress development timelines, attracting venture capital into early-phase programs. Proton therapy capacity concentrates at 42 operational centers, though CMS local coverage determinations create reimbursement friction for clival cases.
Germany
Heidelberg University Hospital and Charité Berlin maintain Europe's highest annual chordoma resection volumes through dedicated sarcoma programs. EMA's priority medicines scheme accelerates assessment timelines for orphan oncology assets, with Germany's reference pricing corridors adapting to novel radiopharmaceuticals. The Heidelberg Ion-Beam Therapy Center anchors particle therapy referral flows from across the European Union.
Japan
National Institute of Radiological Sciences and University of Tokyo Hospital lead skull-base chordoma management through carbon-ion and proton modalities. PMDA's Sakigake designation accelerates regulatory timelines for novel radiation sensitizers, creating first-mover positioning for clival applications. Japan's 0.08 per 100,000 incidence rate nonetheless constrains trial enrollment for indigenous drug development.
United Kingdom
Royal National Orthopaedic Hospital and The Christie NHS Foundation Trust coordinate sacral and skull-base case flows through centralized rare disease networks. NICE technology appraisals govern access to targeted therapies, with provisional recommendations pending brachyury biomarker standardization. London's academic medical centers participate in EORTC chordoma trials, channeling patients toward molecular profiling programs.
Switzerland
University Hospital Zurich and Geneva University Hospital maintain specialized skull-base surgery programs serving cross-border French and Italian patients. Swissmedic's expedited access pathways for orphan drugs compress time-to-market for targeted therapies, though small domestic patient volumes limit indigenous trial infrastructure. Basel's pharmaceutical cluster provides proximity to Novartis and Roche oncology development networks.
Chordoma Disease Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the chordoma therapeutic landscape. Large-cap pharmaceutical companies command targeted therapy infrastructure and kinase inhibitor portfolios, while biotechnology specialists occupy immuno-oncology positioning through vaccine platforms and cellular engineering. The market structure bifurcates between consolidated oncology majors and emerging precision medicine players. Strategic moves center on biomarker-driven trial design and proton therapy network partnerships rather than traditional therapeutic area M&A.
Within the large-cap oncology tier, Pfizer and Bristol-Myers Squibb occupy positions anchored by targeted therapy and checkpoint inhibitor infrastructure applicable to refractory chordoma populations. Bavarian Nordic represents the biotechnology archetype, translating vaccine-platform expertise into brachyury-directed immunotherapy development. These three entities exemplify the competitive divergence between kinase-driven small-molecule approaches and transcription factor-targeted biologic platforms.
| Leading Market Players |
|---|
| Pfizer |
| Bavarian Nordic |
| Bristol-Myers Squibb |
| Eli Lilly and Company |
| Amgen |
| Novartis |
| AstraZeneca |
| Bayer |
| Merck & Co. |
| Others |
Supply Flow & Price Mechanics
Particle therapy suite utilization rates above 85% at Heidelberg Ion-Beam Therapy Center and MD Anderson Cancer Center create cost absorption advantages that compress per-procedure pricing floors for proton-based chordoma protocols while elevating entry barriers for new facility investment.
Pricing Analysis
FDA's Breakthrough Therapy designation dictates the pricing tier structure for brachyury-targeted immunotherapies, creating premium positioning for vaccine platforms against standard-of-care radiation protocols. Pricing stratifies across academic medical center, community oncology, and salvage therapy tiers based on companion diagnostic requirements and administration complexity. Cost compression in radiation therapy is intensifying because proton beam capacity expansion outpaces referral volume growth in select US markets. Community oncology practices exhibit highest price sensitivity due to reimbursement lag for novel systemic agents, while academic centers absorb premium positioning through bundled episode payments.
Supply Chain Analysis
Radioisotope inventory lead times extending 12-18 months for lutetium-177 and actinium-225 constrain radiopharmaceutical manufacturing schedules for targeted alpha therapy programs. Active pharmaceutical ingredient production for kinase inhibitors concentrates in Switzerland, Ireland, and Singapore, with biologic drug substance manufacturing anchored in Massachusetts, North Carolina, and Bavaria. Supply chain risk centers on single-source dependency for brachyury peptide synthesis and specialized cold-chain logistics for cellular therapy distribution. Distribution runs through hospital-administered channels with specialty pharmacy intermediation for oral targeted agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among US academic medical centers and European reference networks as chordoma referral patterns consolidate at fewer than 50 global institutions, fragmenting pricing leverage for device and drug suppliers.
For Market Incumbents: Secure exclusive proton therapy network partnerships at NCI-designated cancer centers to lock in adjuvant radiation workflows before carbon-ion competition intensifies. Defend biomarker assay franchises through CAP proficiency testing program sponsorship that embeds brachyury IHC standardization into trial eligibility criteria. For New Entrants and Emerging Players: FDA's expanded access program offers the fastest certification fast-track for pre-commercial biologics in refractory sacral chordoma, where no approved systemic options exist. Target post-surgical adjuvant vaccine protocols as the most penetrable white space between en-bloc resection margins and salvage radiation failure. Pursue direct-to-patient navigation through Chordoma Foundation registries to bypass entrenched academic gatekeepers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract manufacturing organizations with radiopharmaceutical capabilities and multi-product peptide synthesis platforms. Long-term viability hinges on regulatory exclusivity duration rather than volume scale in this ultra-rare indication. Watch for PMDA Sakigake designations as the inflection signal for first-mover positioning in Asian proton therapy markets.| Strategic Initiative | Industry Significance |
|---|---|
| Brachyury Biomarker Standardization | CAP proficiency testing harmonizes diagnostic criteria across MD Anderson, Heidelberg, and Tokyo referral networks. |
| Proton Therapy Network Expansion | US commercial payer contracting at new particle facilities in Florida and Texas reshapes geographic access patterns. |
| Adjuvant Vaccine Protocol Development | NCI-sponsored trials compress timelines between phase II readouts and FDA Breakthrough Therapy designation. |
| CAR-T Manufacturing Scale-Up | Stanford's academic GMP facility anchors cellular therapy supply for refractory sacral presentations. |
| Cross-Border Trial Coordination | EMA-FDA biomarker qualification alignment reduces protocol fragmentation for international chordoma studies. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with sarcoma program directors, proton therapy physicists, regulatory affairs specialists at orphan drug sponsors, and payer formulary managers; and secondary validation through FDA Breakthrough Therapy designation records, EMA PRIME eligibility decisions, ClinicalTrials.gov protocol registries, and CMS local coverage determination documents. Bottom-up procedure volume modeling at 42 US proton centers triangulated against top-down epidemiology-based incidence projections.
Across the analysis window, the analytical framework segmented volume and value by treatment modality, drug class molecular target, end-user facility tier, and diagnostic method complexity. CAGRs derived from logistic diffusion curves for novel immunotherapy adoption, calibrated to historical orphan oncology uptake patterns. Forecast inputs incorporated brachyury assay penetration rates and decentralized proton therapy capacity buildout timelines.
Underlying assumptions cover stable orphan drug incentive continuity and biomarker assay reimbursement parity, with deviation risk concentrated in CMS national coverage determination reversals for proton therapy and EMA conditional marketing authorization withdrawal triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
CNS Treatment and Therapy Market
Neurology
Neuropsychiatric Disorders and Treatment Market
Neurology
Global Neuroblastoma Market
Neurology
North America Neurology Monitoring Market
Neurology
Arachnoiditis Market
Neurology
Grand Mal Seizure Treatment Market
Neurology
Neurology Software Market
Neurology
Multiple Sclerosis Therapies Market
Neurology
Tourette Syndrome Market
Neurology
Narcolepsy Treatment Market
Neurology
North America Traumatic Brain Injuries Assessment Market
Neurology
Mild Cognitive Impairment Market
Neurology
Netherlands Neurology Devices Market
Neurology
Vocal Cord Paralysis Market
Neurology
Interventional Neurology Market
Neurology
Benign Positional Vertigo Treatment Market