
 Asia-Pacific Cyanoacrylate Adhesives Market | 2026-2036
Asia-Pacific Cyanoacrylate Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cyanoacrylate Adhesives Market Outlook
Skilled polymer chemist availability across East Asia is unwinding as regional universities expand materials science programs. Henkel AG & Co KGaA leverages its German-Asian R&D bridge to sustain high-purity medical-grade output. ThreeBond Holdings Co Ltd anchors Japanese automotive OEM supply chains with specialized anaerobic-cyanoacrylate hybrid formulations. Kangda New Materials (Group) Co Ltd competes on cost-optimized ethyl variants for domestic electronics contract manufacturers.
Asia-Pacific cyanoacrylate adhesives are single-component, moisture-curing thermoplastics based on cyanoacrylate monomers that polymerize on contact with surface humidity to form high-tensile bonds within seconds, typically achieving lap shear strengths of 15–30 MPa on metal substrates. Industrial applications dominate volume consumption across the region, while medical-grade formulations command premium positioning due to biocompatibility certification requirements for wound closure and surgical devices. Ethyl cyanoacrylate occupies the broadest use profile in general assembly and consumer repair segments, whereas specialty cyanoacrylates with rubber-toughened or thermal-resistant modifications are gaining traction in automotive underhood and power electronics applications.
China's SAMR enforces GB standards governing volatile organic compound limits in industrial adhesive formulations, while Japan's METI oversees chemical substance reporting under its industrial safety framework. India's BIS certification mandates product testing for cyanoacrylate imports, creating compliance barriers for unqualified suppliers. Stakeholders must monitor evolving medical device registration pathways across South Korea's MFDS and Australia's TGA as healthcare applications expand beyond traditional wound care into surgical instrumentation bonding.
Market Dynamics
China's SAMR enforcement of tightened GB standards for volatile organic compound limits is compressing formulation flexibility while simultaneously accelerating R&D investment in low-VOC alkoxy-ethyl hybrid chemistries across domestic manufacturers.
Growth Catalysts
- Electronics miniaturization:Southeast Asian contract manufacturers are expanding adhesive procurement for micro-component assembly in smartphones and wearables, driving volume consumption of ultra-thin bond-line formulations.
- Automotive lightweighting:India's automotive hub around Chennai and Pune is displacing mechanical fasteners with cyanoacrylate solutions in interior trim and sensor mounting applications.
- Japan's METI chemical reporting framework:Industrial safety substance documentation requirements are formalizing supply chain traceability, creating competitive advantage for compliant domestic formulators.
Market Restraints
- Monomer supply concentration:Ethyl cyanoacrylate feedstock production clusters in eastern China, exposing formulators to regional logistics disruptions and input cost volatility.
- Medical-grade certification barriers:India's BIS mandatory product testing for imports creates compliance friction for unqualified foreign suppliers seeking wound-care market entry.
- UV-curable adhesive substitution:Electronics assembly lines in South Korea are piloting light-curing alternatives for transparent substrate bonding, threatening cyanoacrylate share in display manufacturing.
Strategic Opportunities
- Vietnam electronics manufacturing expansion:Underpenetrated northern industrial zones around Bac Ninh offer first-mover positioning for medical-grade and thermal-resistant formulation suppliers.
- South Korea MFDS surgical device pathway:Expanding medical device registration categories beyond traditional wound closure into instrumentation bonding creates premium pricing potential.
- Rubber-toughened hybrid convergence:Automotive underhood applications combining anaerobic and cyanoacrylate chemistries address thermal cycling demands in power electronics modules.
Industry Challenges
- Polymer chemist talent scarcity:Regional universities are expanding materials science programs, yet skilled formulation specialists with medical-grade purity experience remain concentrated in Japan and Germany.
- Biocompatibility certification timelines:Australia's TGA medical device registration pathways extend 18-24 months for new adhesive entrants, compressing product launch windows against established suppliers.
- Legacy inventory system integration:Electronics contract manufacturers in Malaysia and Thailand face friction retrofitting moisture-sensitive adhesive handling protocols into existing ERP workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cyanoacrylate Adhesives Market |
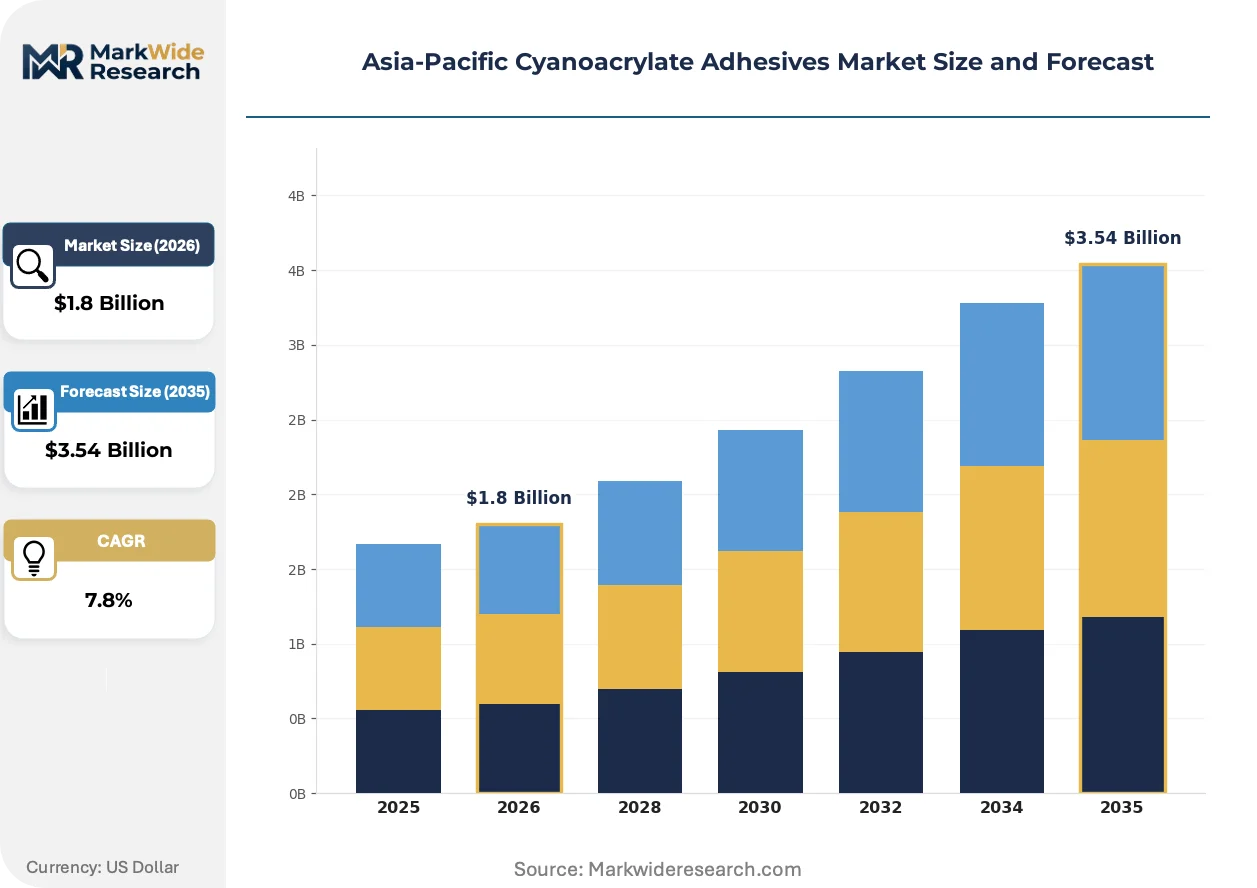
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethyl Cyanoacrylate, Methyl Cyanoacrylate, Butyl Cyanoacrylate, Specialty Cyanoacrylates Technology: Instant Adhesives, Multiple Bonding, Medical Grade, Industrial Applications End User: Automotive, Electronics, Healthcare, Construction Application: Packaging, Woodworking, Assembly, Repair |
| Companies Covered | Aica Kogyo Co Ltd, Arkema Group, 3M, Kangda New Materials (Group) Co Ltd, Hubei Huitian New Materials Co Ltd, Henkel AG & Co KGaA, Pidilite Industries Ltd, ThreeBond Holdings Co Ltd, H B Fuller Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cyanoacrylate Adhesives Market Strategic Shifts
Formulation chemistry, regulatory compliance architecture, and procurement behavior are converging to reshape competitive positioning across Asia-Pacific adhesive markets, with technology miniaturization and sustainability mandates as dominant vectors.
Alkoxy-ethyl cyanoacrylate formulations with reduced odor and blooming characteristics are displacing conventional ethyl variants in consumer electronics assembly. Japanese automotive OEMs are specifying these chemistries for interior applications where aesthetic finish requirements have tightened. This technology is miniaturizing bond-line tolerances in camera module assembly, enabling sub-50-micron gap filling without capillary spread onto optical surfaces.
China's GB standards for industrial chemical safety are tightening volatile organic compound limits in adhesive formulations, forcing domestic manufacturers to reformulate solvent-containing products. The SAMR enforcement timeline is compressing R&D cycles, with compliant alkoxy variants now required for electronics export certification. Medical-grade suppliers serving wound-care markets face parallel pressure from MEE environmental inspections targeting manufacturing emissions.
Electronics contract manufacturers are consolidating adhesive procurement through direct partnerships with formulators rather than distributor intermediaries. This channel compression is most visible in Vietnam and Indonesia, where smartphone assemblers are establishing captive technical service relationships for just-in-time delivery. Volume commitments now bundle formulation customization, on-site application training, and bonded inventory programs that displace traditional stock-and-sell distribution economics.
Asia-Pacific Cyanoacrylate Adhesives Market Segmentation
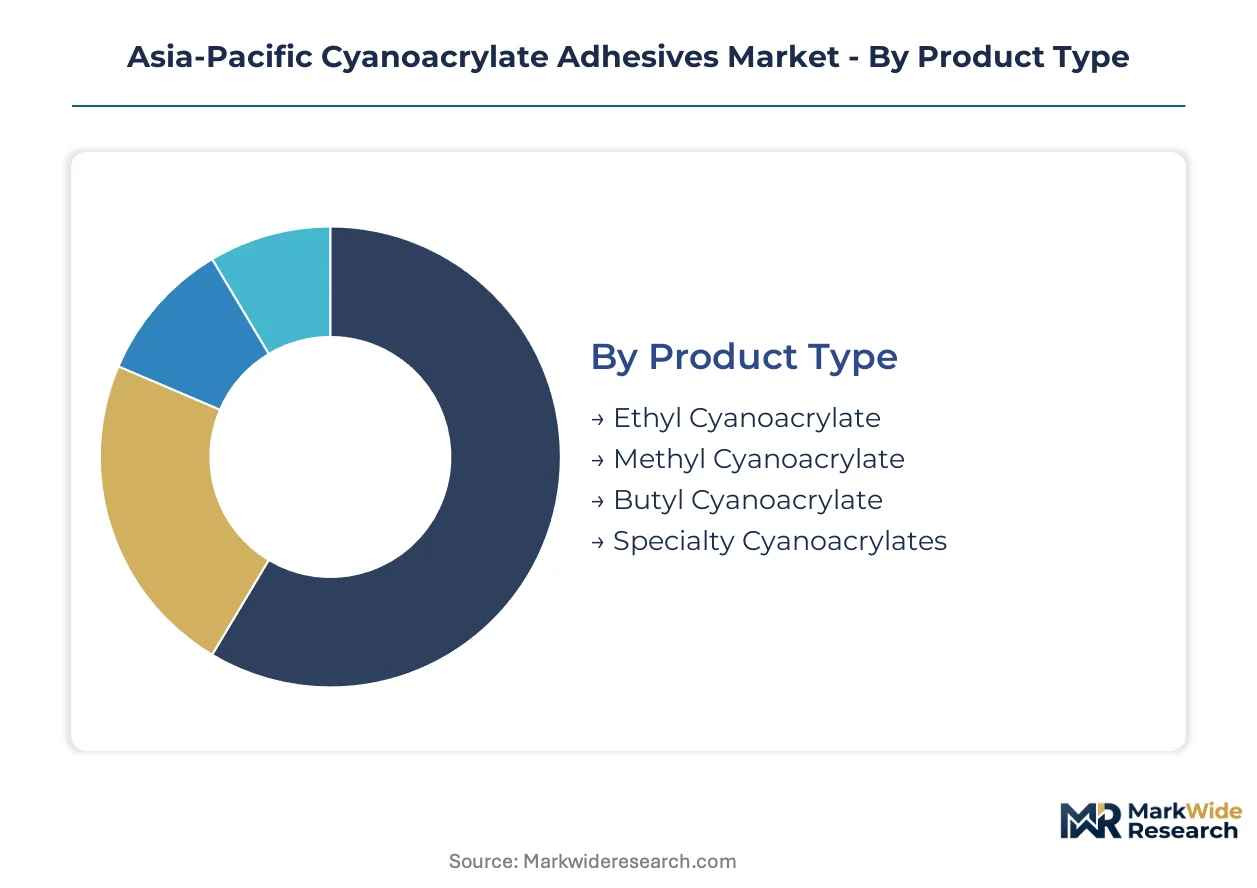
Segmentation in Asia-Pacific cyanoacrylate adhesives reveals divergent supply chain configurations across product chemistries and end-use verticals. Understanding these splits enables suppliers to align formulation investments with regulatory requirements and procurement patterns specific to electronics, automotive, and healthcare demand centers.
Product Type:
Domestic consumption in China and India favors commodity ethyl variants, while export-oriented electronics manufacturers in Vietnam and Malaysia drive demand for low-odor alkoxy-ethyl hybrids.
- Ethyl Cyanoacrylate:Standard formulations based on ethyl ester monomers deliver rapid polymerization and high bond strength on metals and plastics. Volume concentrates in India's automotive hub around Chennai and Pune, where cost-sensitive assembly operations displace mechanical fasteners in interior trim applications. SAMR's tightened GB standards for volatile organic compounds are forcing domestic Chinese suppliers to reformulate solvent-containing variants.
- Specialty Cyanoacrylates:Rubber-toughened and thermal-resistant modifications incorporate elastomeric additives to withstand thermal cycling and impact loading. Japanese automotive OEMs specify these chemistries for underhood power electronics modules, where anaerobic-cyanoacrylate hybrid formulations address vibration and temperature extremes. METI chemical substance reporting requirements favor domestic formulators with established compliance documentation.
- Methyl Cyanoacrylate:Faster-curing ester variants with higher rigidity serve metal-to-metal bonding in precision assembly operations across South Korean electronics manufacturing.
- Butyl Cyanoacrylate:Lower-odor formulations with reduced blooming characteristics target consumer repair segments and aesthetic-sensitive applications in Southeast Asian smartphone assembly.
Ethyl cyanoacrylate holds the largest share; momentum sits with specialty cyanoacrylates.
Technology:
Cost tiers separate commodity instant adhesives from premium medical-grade certifications requiring biocompatibility testing and extended regulatory timelines.
- Instant Adhesives:Single-component moisture-curing systems polymerize within seconds upon contact with surface humidity. Electronics contract manufacturers in Vietnam and Indonesia consolidate procurement through direct formulator partnerships, bundling just-in-time delivery with on-site application training for ultra-thin bond-line smartphone assembly.
- Medical Grade:Biocompatibility-certified formulations for wound closure and surgical devices command premium positioning due to ISO 10993 testing requirements and extended registration pathways. Australia's TGA and South Korea's MFDS are expanding device categories beyond traditional wound care into surgical instrumentation bonding, creating pricing power for compliant suppliers despite 18-24 month approval timelines.
- Multiple Bonding:Engineered systems enabling sequential or gap-filling adhesion serve construction and repair segments requiring adjustable working times.
- Industrial Applications:High-volume formulations optimized for automated dispensing equipment feed automotive and general assembly lines across Thailand and Malaysia.
Instant adhesives dominate volume throughput; medical grade commands the steepest expansion trajectory.
End User:
Customer procurement maturity varies sharply: automotive and electronics buyers enforce direct technical partnerships, while healthcare purchasing flows through regulated distribution channels.
- Electronics:Miniaturized component assembly in smartphones, wearables, and camera modules drives consumption of sub-50-micron bond-line formulations. Southeast Asian contract manufacturers in Bac Ninh and Batam are retrofitting moisture-sensitive adhesive handling protocols into ERP workflows to support just-in-time production.
- Automotive:Lightweighting initiatives displace mechanical fasteners in sensor mounting, interior trim, and power electronics thermal management. India's BIS certification mandates product testing for cyanoacrylate imports, creating compliance barriers for unqualified foreign suppliers seeking entry into the Chennai-Pune manufacturing corridor.
- Healthcare:Wound closure, surgical devices, and dental applications require biocompatibility certification under MFDS and TGA frameworks.
- Construction:Structural bonding and repair applications favor cost-optimized formulations with extended open times for manual application.
Electronics captures the highest volume intensity; automotive is gaining share fastest.
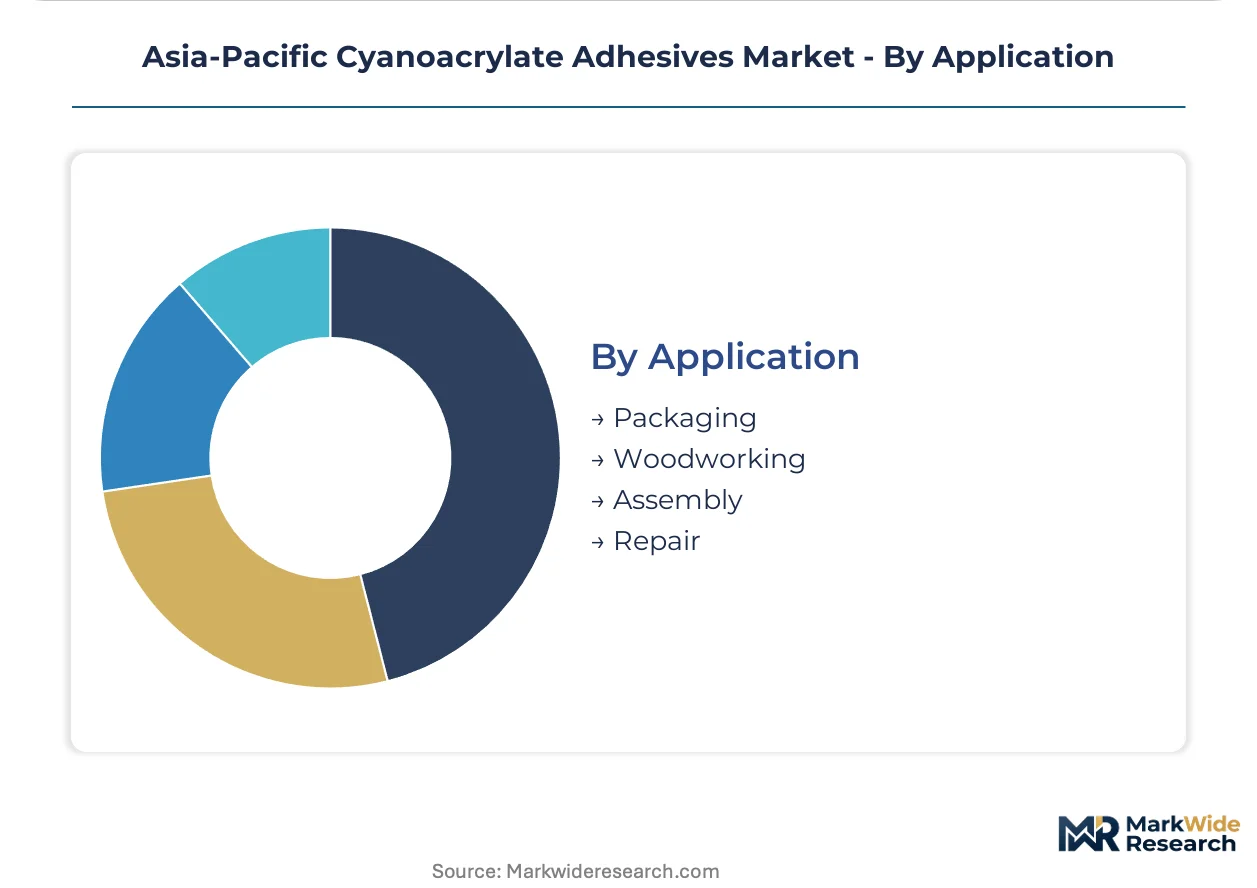
Application:
Supply concentration in eastern China for ethyl cyanoacrylate monomers shapes procurement economics differently across high-volume assembly versus fragmented repair demand.
- Assembly:Automated production line bonding of electronics, automotive components, and medical devices requires consistent viscosity and cure speed. China's MEE environmental inspections target manufacturing emissions, pressuring domestic suppliers serving export-certified electronics production.
- Packaging:High-speed carton sealing and label attachment operations favor low-cost ethyl variants with rapid green strength development.
- Woodworking:Furniture and fixture manufacturing in Indonesia and Thailand uses general-purpose formulations for joint assembly and veneer bonding.
- Repair:Consumer and maintenance applications span household fixes, industrial equipment maintenance, and aftermarket automotive servicing across dispersed retail and distributor channels.
Assembly commands the largest revenue pool; repair offers the most fragmented margin structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR anchors regulatory enforcement across the dominant geography, with GB standards for volatile organic compounds compressing formulation flexibility for domestic manufacturers while accelerating R&D investment in compliant alkoxy-ethyl hybrid chemistries.
China
Electronics export certification and automotive lightweighting drive demand for low-VOC formulations. SAMR's tightened GB standards force domestic suppliers to reformulate solvent-containing products ahead of MEE environmental inspections. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta are retrofitting production lines to serve smartphone assemblers with sub-50-micron bond-line capabilities.
India
Automotive interior trim and sensor mounting applications displace mechanical fasteners in cost-sensitive assembly operations. BIS mandatory product testing for cyanoacrylate imports creates compliance barriers for unqualified foreign suppliers. The Chennai-Pune manufacturing corridor concentrates procurement from domestic electronics contract manufacturers expanding adhesive volumes for consumer device assembly.
Japan
Automotive OEMs specify rubber-toughened and thermal-resistant modifications for underhood power electronics modules. METI chemical substance reporting requirements under the industrial safety framework formalize supply chain traceability. Domestic formulators in the Chubu region around Nagoya leverage established compliance documentation to sustain hybrid anaerobic-cyanoacrylate supply relationships.
South Korea
Electronics assembly lines pilot UV-curable alternatives for transparent substrate bonding while medical device registration expands beyond wound closure. MFDS pathways for surgical instrumentation bonding create premium pricing potential for compliant adhesive suppliers. Seoul Capital Area manufacturers balance display manufacturing substitution risk against healthcare application expansion.
Vietnam
Smartphone assemblers establish captive technical service relationships for just-in-time delivery in underpenetrated northern industrial zones. Direct formulator partnerships displace traditional distributor economics through bundled formulation customization and on-site application training. Bac Ninh province offers first-mover positioning for medical-grade and thermal-resistant formulation suppliers serving export-oriented electronics manufacturing.
Asia-Pacific Cyanoacrylate Adhesives Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the market structure consolidating around formulation expertise and regulatory compliance capabilities rather than raw scale. Three strategic archetypes dominate: multinational chemical conglomerates with German-Japanese R&D bridges, domestic Chinese cost-optimized suppliers serving commodity electronics segments, and Japanese automotive-tier specialists with hybrid chemistry portfolios. Competitive moves concentrate on backward integration into monomer supply and geographic expansion through direct technical partnerships with contract manufacturers.
Among Asia-Pacific-based material suppliers, Kangda New Materials (Group) Co Ltd and Hubei Huitian New Materials Co Ltd exemplify the cost-optimized domestic tier competing on ethyl variants for electronics contract manufacturers. ThreeBond Holdings Co Ltd occupies a position within the Japanese automotive specialist archetype, anchoring OEM supply chains with established compliance documentation under METI frameworks. Henkel AG & Co KGaA represents the integrated multinational tier, sustaining high-purity medical-grade output through German-Asian R&D coordination.
| Leading Market Players |
|---|
| Aica Kogyo Co Ltd |
| Arkema Group |
| 3M |
| Kangda New Materials (Group) Co Ltd |
| Hubei Huitian New Materials Co Ltd |
| Henkel AG & Co KGaA |
| Pidilite Industries Ltd |
| ThreeBond Holdings Co Ltd |
| H B Fuller Company |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at eastern Chinese ethyl cyanoacrylate monomer plants anchors regional price floors, with scale concentration in Jiangsu and Shandong provinces enabling domestic formulators to undercut import alternatives by 15-25% on commodity grades while simultaneously constraining margin expansion for mid-tier suppliers lacking captive monomer supply.
Pricing Analysis
Geographic price spreads between Japanese medical-grade formulations and Chinese commodity ethyl variants exceed 3x on a per-kilogram basis, with premium-mid-economy pricing differentiation driven by ISO 10993 biocompatibility certification tiers and volume scale commitments from electronics contract manufacturers. Cost compression in India's automotive hub intensifies as domestic suppliers displace European imports in Chennai-Pune interior trim applications, while medical device assemblers in South Korea exhibit lowest price sensitivity due to MFDS registration barriers limiting qualified supplier pools.
Supply Chain Analysis
Inventory lead times for moisture-sensitive cyanoacrylate formulations compress to 72-96 hours for just-in-time electronics assembly in Vietnam and Indonesia, with feedstock production drawing from eastern China, Japan, and South Korea as primary monomer sources. Raw material dependencies center on cyanoacrylate ester monomers, stabilizer packages, and rubber-toughening elastomers, while single-source vulnerability concentrates in Jiangsu province ethyl monomer capacity. Distribution runs through direct formulator partnerships with contract manufacturers, displacing traditional distributor intermediaries in smartphone assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
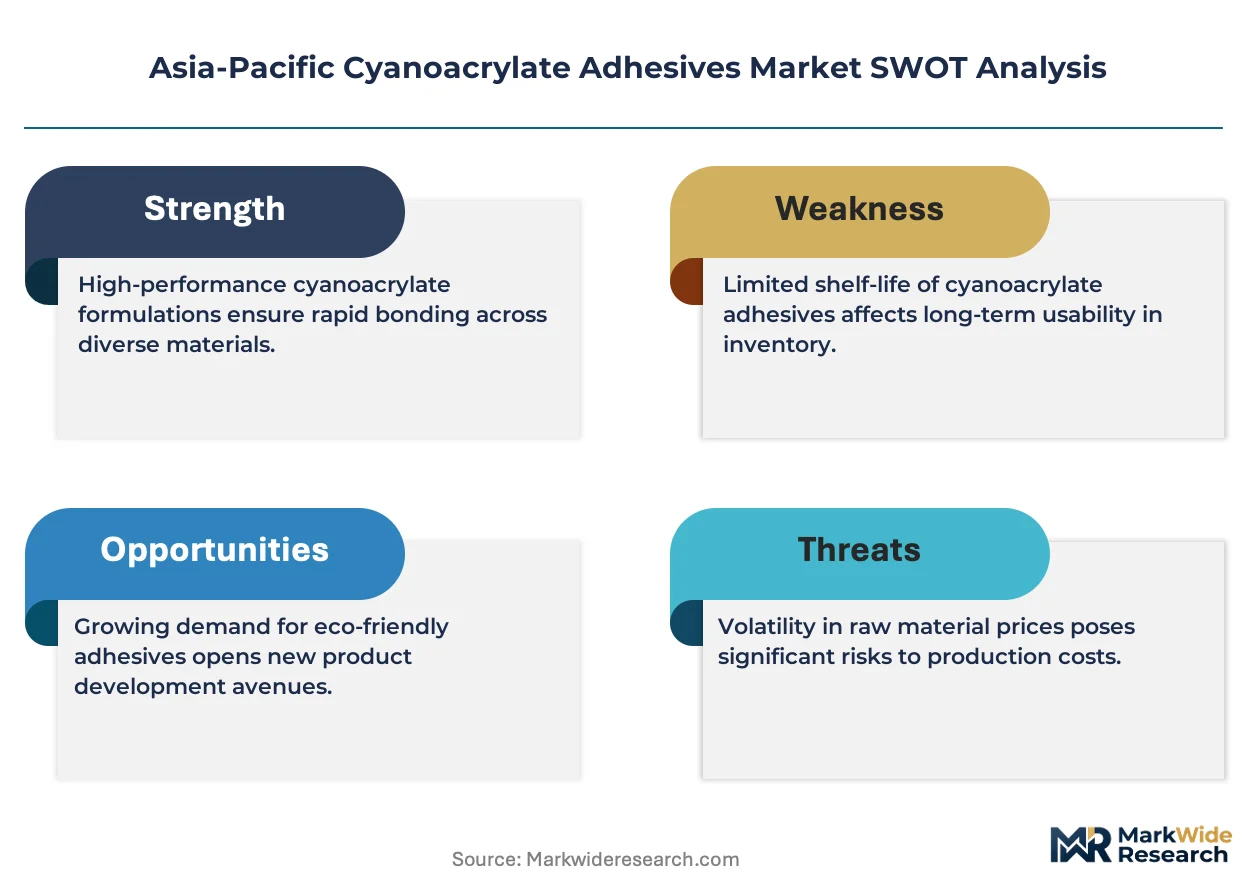
Buyer power is concentrating among Southeast Asian electronics contract manufacturers consolidating procurement through captive technical partnerships, fragmenting pricing leverage for non-integrated adhesive suppliers unable to bundle formulation customization with on-site service capabilities.
For Market Incumbents: Compound defensive positioning by deepening backward integration into monomer supply and accelerating low-VOC alkoxy-ethyl R&D ahead of SAMR enforcement timelines. Henkel and ThreeBond archetypes should lock in medical-grade certification pipelines with Australia's TGA and South Korea's MFDS to defend against emerging domestic Chinese suppliers achieving biocompatibility parity. Channel control through bonded inventory programs with Vietnamese smartphone assemblers represents the priority retention lever against distributor disintermediation. For New Entrants and Emerging Players: Lead with thermal-resistant hybrid formulations targeting underpenetrated northern Vietnamese industrial zones around Bac Ninh, where export-oriented electronics manufacturing lacks qualified local suppliers for automotive-grade anaerobic-cyanoacrylate combinations. India's BIS certification friction creates white-space for domestic Indian formulators achieving import-substitution positioning in the Chennai-Pune corridor. A technical service-led go-to-market model bundling application training with just-in-time delivery penetrates faster than price-only competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulators with hybrid chemistry portfolios spanning cyanoacrylate-anaerobic convergence and medical-grade purity capabilities. Long-term viability over the next decade hinges on regulatory compliance architecture rather than raw scale, with acquisition targets clustering around Japanese automotive-tier specialists and German-Asian R&D bridge operators. The signal to watch is MFDS expansion of surgical device registration categories beyond wound closure, which would inflect premium pricing power for early-certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive ethyl cyanoacrylate production insulates margins from Jiangsu supply disruptions. |
| Medical-Grade Certification Investment | TGA and MFDS pathways create 18-24 month competitive moats in wound-care markets. |
| Direct Technical Partnership Model | Bac Ninh smartphone assemblers consolidate procurement through bundled service relationships. |
| Low-VOC Formulation Transition | SAMR GB standards compliance becomes mandatory for China electronics export certification. |
| Rubber-Toughened Hybrid Development | Japanese automotive OEMs specify thermal-resistant chemistries for power electronics modules. |
Study Parameters
Operator-level perspectives from polymer chemists at Japanese automotive-tier suppliers, procurement leads at Vietnamese electronics contract manufacturers, plant managers at Chinese monomer facilities, and regulatory affairs specialists at South Korean medical device firms anchored the qualitative base. Primary interview insights triangulated against secondary validation from SAMR GB standard filings, METI chemical substance reports, BIS certification databases, and customs trade records for cyanoacrylate monomer flows. Bottom-up demand modeling across electronics, automotive, and healthcare verticals converged with top-down capacity assessments at major formulation plants.
Sensitivity analysis tested forecast outputs against alternative scenarios for SAMR enforcement timing, monomer supply disruption probability, and UV-curable substitution rates in display manufacturing. Segmentation dimensions spanned product chemistry tiers, technology grades, end-use verticals, and regional production clusters, with CAGRs derived from elasticity-adjusted volume projections and price trajectory assumptions. Industry-specific inputs incorporated electronics miniaturization bond-line tolerance trends and automotive lightweighting fastener displacement rates.
Underlying assumptions cover sustained electronics manufacturing expansion in Vietnam and Indonesia, stable ethyl monomer supply from eastern China, and gradual MFDS regulatory pathway expansion, with deviation risk concentrated in UV-curable adhesive substitution acceleration and unexpected SAMR environmental inspection intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Laser Self-Adhesive Tear Market
Adhesives & Sealants
Die Cut Adhesive Market
Adhesives & Sealants
Polyurethane (PU) Adhesives in Electronics Market
Adhesives & Sealants
Low Trauma/Skin Friendly Adhesives Market
Adhesives & Sealants
Waterproofing Admixture Market
Adhesives & Sealants
Global Glass Bonding Adhesive Market
Adhesives & Sealants
United States Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
South America Epoxy Adhesives Market
Adhesives & Sealants
Global Construction Adhesives and Sealants Market
Adhesives & Sealants
Brazil Sealants Market
Adhesives & Sealants
Middle East & Africa Automotive Adhesives & Sealants Market
Adhesives & Sealants
Middle East and Africa Flock Adhesives Market
Adhesives & Sealants
Acrylic Glue Market
Adhesives & Sealants
Europe Contact Adhesives Market
Adhesives & Sealants
Global Silicone Adhesives Market
Adhesives & Sealants
Instant Adhesive Market