
 Marine Life Raft Market | 2026-2036
Marine Life Raft Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Life Raft Market Foresight
A capital-intensity divergence between fully integrated manufacturers and assembly-focused competitors is bifurcating competitive dynamics in the marine life raft sector. Survitec sustains broad regulatory certification coverage across SOLAS, USCG, and ISO standards, enabling uniform supply to multinational shipping lines. Winslow LifeRaft specializes in hand-crafted, high-durability designs for military and expedition yacht segments where customization commands premium positioning. Datrex leverages long-standing USCG approval pathways and domestic manufacturing to dominate North American coastal and fishing vessel procurement channels.
Marine life rafts are self-contained, inflatable or rigid evacuation platforms engineered from chloroprene-coated nylon or thermoplastic polyurethane fabrics, designed to deploy automatically or manually and sustain survivors with canopy protection, ballast pockets, and survival equipment for prescribed durations at sea. Their primary purpose is to provide emergency flotation and shelter when vessels sink or become uninhabitable in commercial, recreational, and offshore environments. Inflatable rafts lead volume shipments due to compact stowage requirements and broad SOLAS compliance, while rigid raft variants occupy niche demand from ice-class vessels and platforms where puncture resistance outweighs space constraints. SOLAS-compliant certification categories anchor procurement specifications for international commercial fleets, though CE-marked products are gaining traction among European recreational boaters seeking dual-standards flexibility.
The US Coast Guard enforces strict approval protocols under 46 CFR subchapter Q that dictate construction materials, capacity ratings, and inspection intervals for vessels operating under US flag. ISO 9650 and SOLAS LSA Code frameworks administered by classification societies shape international type-approval requirements and influence insurer premium calculations for fleet operators. The EU Marine Equipment Directive and MED wheel-mark certification create additional conformity obligations for rafts installed on European-registered ships. Stakeholders must monitor evolving harmonization gaps between USCG and ISO testing protocols, as divergence in inflation performance standards could fragment procurement strategies for global fleet managers operating across multiple registry jurisdictions.
Market Dynamics
Vacuum-sealed valise packing technology is compressing service intervals and reshaping fleet procurement economics, while SOLAS compliance deadlines concentrate upgrade demand among commercial shipping operators.
Growth Catalysts
- SOLAS LSA Code mandates:International shipping fleets face mandatory evacuation system upgrades, forcing replacement cycles for aging inflatable raft inventories ahead of certification expiry.
- Offshore support vessel construction:North Sea safety mandates from Norway's Petroleum Safety Authority drive procurement of self-righting rafts with enhanced stability specifications.
- Chloroprene-coated nylon:Advanced fabric formulations extend operational lifespans in harsh marine environments, reducing total cost of ownership for fleet managers.
Market Restraints
- TPU raw material concentration:Thermoplastic polyurethane supply chains cluster among Asian petrochemical producers, exposing raft manufacturers to input cost volatility and geographic concentration risk.
- USCG-ISO protocol divergence:Inflation performance testing gaps between 46 CFR subchapter Q and ISO 9650 standards force dual certification investments, fragmenting procurement strategies for multinational operators.
- Rigid raft space constraints:Puncture-resistant rigid variants face substitution pressure from improved inflatable designs, limiting penetration beyond ice-class vessels and Arctic platforms.
Strategic Opportunities
- Expedition yacht segment:Hand-crafted, high-durability designs command premium positioning among ultra-high-net-worth owners seeking customization beyond standard SOLAS specifications.
- EU Marine Equipment Directive harmonization:MED wheel-mark certification creates pathway for CE-marked products to capture European recreational boater demand seeking dual-standards flexibility.
- Digital inspection integration:RFID-enabled raft tracking converges with fleet management software, enabling predictive maintenance models that reduce downtime for commercial operators.
Industry Challenges
- Certification timeline compression:Classification society backlogs extend type-approval cycles, delaying product launches and constraining manufacturer throughput.
- Specialized fabrication skills:Hand-sealed seam welding and pressure-testing expertise concentrates among aging technician cohorts, constraining quality-controlled production scaling.
- Legacy fleet retrofit complexity:Cradle and davit system incompatibility with modern inflatable packings forces expensive deck modifications during upgrade cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Life Raft Market |
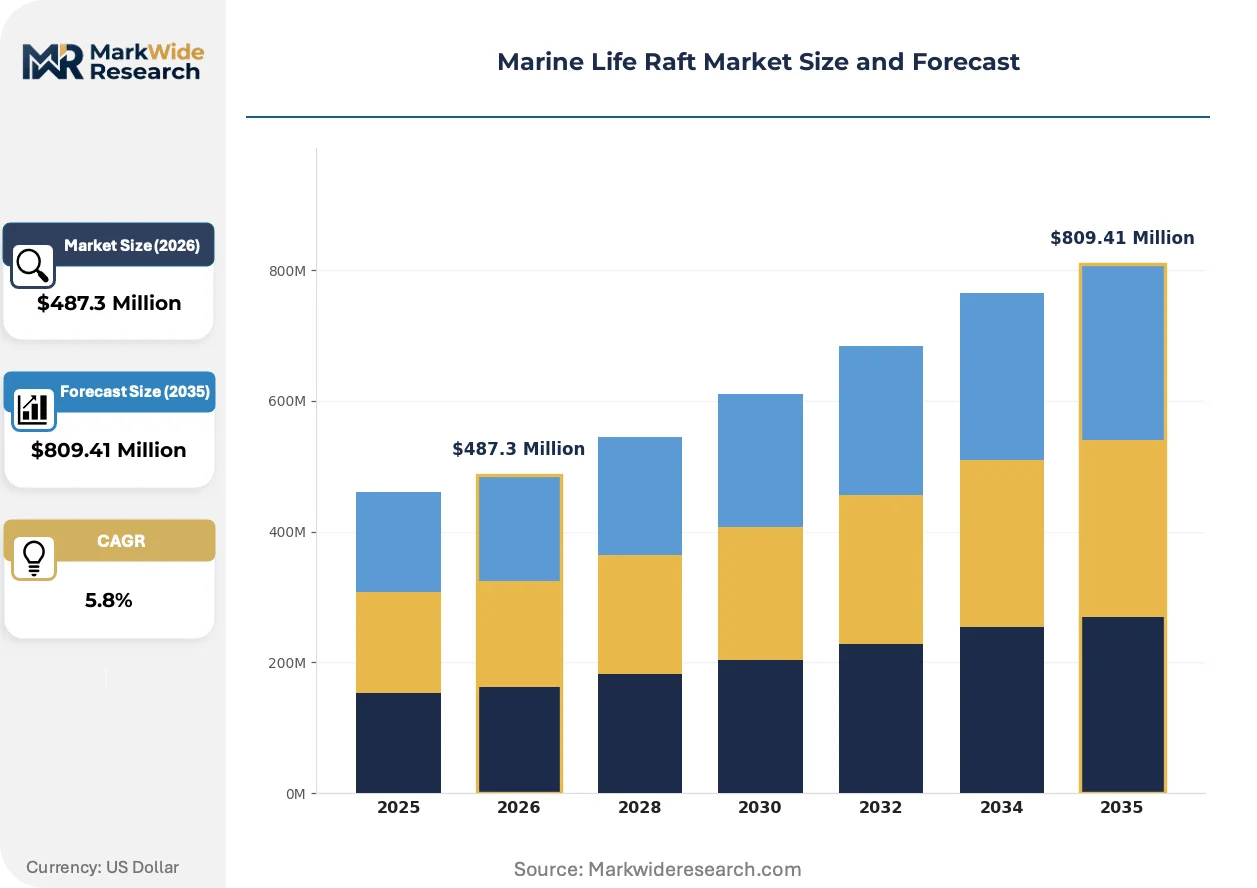
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable Rafts, Rigid Rafts, Coastal Rafts, Survival Rafts End User: Commercial Shipping, Recreational Boating, Fishing Vessels, Offshore Oil Platforms Certification: ISO Certified, USCG Approved, SOLAS Compliant, CE Marked Deployment Type: Automatic Deployment, Manual Deployment, Static Deployment, Mobile Deployment |
| Companies Covered | Switlik, Crewsaver, Survitec, Viking Life-Saving Equipment, Arimar, Datrex, Winslow LifeRaft, Alnmaritec Ltd, Revere Survival Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Life Raft Market Shifts & Advancements
Material science advances and regulatory harmonization pressures are restructuring competitive advantage around durability metrics and certification agility rather than legacy manufacturing scale.
Self-righting ballast pocket configurations are supplanting traditional flat-bottom designs in offshore sector procurement. North Sea operators now specify automatic capsize recovery as standard, compressing demand for conventional raft architectures. This technology shift is enabling specialized manufacturers to capture share from volume producers lacking stability engineering expertise.
REACH chemical compliance frameworks are restricting legacy chloroprene formulations across European-registered fleets. ECHA substance evaluation processes are accelerating substitution toward halogen-free TPU coatings. Mediterranean and Baltic charter operators are responding by front-loading procurement of certified-low-toxicity rafts ahead of anticipated restriction expansion.
Leasing models for evacuation equipment are disrupting traditional capital purchase patterns among mid-size shipping lines. Third-party fleet service providers now bundle raft provision, inspection, and replacement under per-vessel annual contracts. Greek and Singaporean container operators have adopted this structure most aggressively, outsourcing compliance risk to specialized maritime safety lessors.
Marine Life Raft Market Segmentation
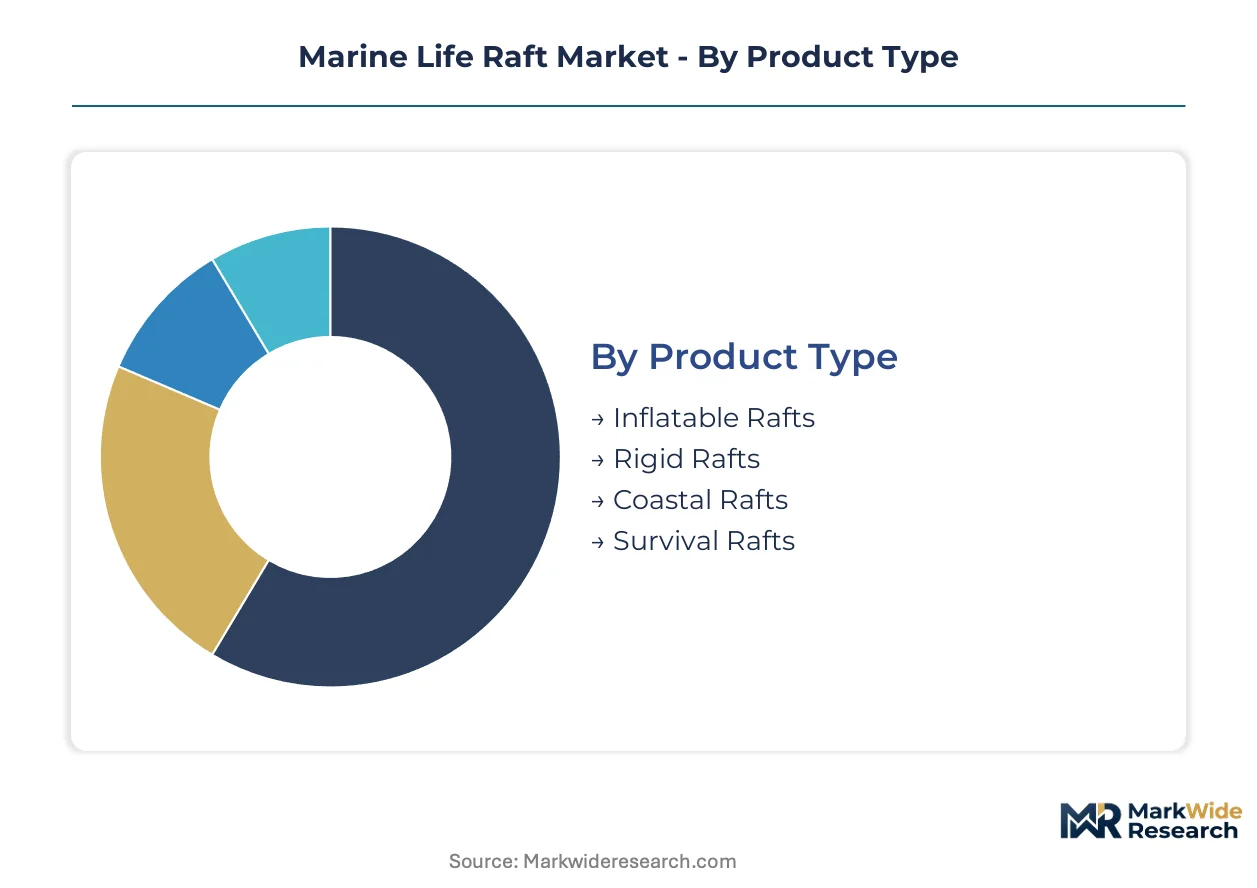
Segmentation in the marine life raft sector reveals how regulatory divergence and operational environment shape procurement patterns. Fleet managers select configurations based on certification jurisdiction, vessel type, and deployment mechanism rather than price alone.
Product Type:
Substitution pressure concentrates most intensely on rigid raft architectures as inflatable designs improve puncture resistance and thermal performance.
- Inflatable Rafts:Constructed from chloroprene-coated nylon or thermoplastic polyurethane fabrics with automatic inflation systems. SOLAS-mandated commercial fleets in Greece and Singapore concentrate procurement here, driven by compact stowage requirements and vacuum-sealed valise technology extending service intervals.
- Rigid Rafts:Molded fiberglass or composite hulls with foam-filled buoyancy chambers. Ice-class vessels operating in Norwegian Arctic waters and Russian northern terminals specify these for puncture resistance where ice contact probability exceeds inflatable tolerance thresholds.
- Coastal Rafts:Reduced-capacity designs for near-shore operations under 20 nautical miles from land.
- Survival Rafts:Extended-duration platforms with integrated desalination and medical kits for isolated ocean passages.
Inflatable rafts anchor the volume base while rigid rafts gain share at the steepest rate among specialized Arctic and ice-class operators.
End User:
Cost tier stratification separates capital-rich offshore operators from price-sensitive coastal fishing fleets.
- Commercial Shipping:Container and bulk carriers operating under multinational flags. Norwegian Petroleum Safety Authority mandates and SOLAS compliance deadlines in Singapore and Greece drive replacement cycles for aging evacuation inventories.
- Recreational Boating:Private yacht owners and charter operators. Mediterranean and Baltic operators front-load procurement of REACH-compliant low-toxicity rafts ahead of ECHA restriction expansion.
- Fishing Vessels:Small-scale and industrial fleets with constrained deck space and inspection budgets.
- Offshore Oil Platforms:Fixed and floating production facilities. North Sea operators specify self-righting ballast configurations as standard, compressing demand for conventional flat-bottom architectures.
Commercial shipping contributes the dominant revenue share while offshore oil platforms expand most quickly on safety mandate tightening.
Certification:
Supply concentration around approved testing laboratories creates bottlenecks for manufacturers seeking multi-jurisdictional coverage.
- SOLAS Compliant:International Life-Saving Appliance Code certification administered by classification societies. Mandatory for vessels on international voyages; insurer premium calculations in London and Singapore markets reward SOLAS-grade inventory.
- USCG Approved:46 CFR subchapter Q protocols enforced for US-flagged vessels. Domestic manufacturing concentration and long-standing approval pathways dominate North American coastal procurement channels.
- ISO Certified:ISO 9650 standards for recreational and commercial inflatable devices.
- CE Marked:EU Marine Equipment Directive wheel-mark certification. European recreational boaters seek dual-standards flexibility combining CE marking with SOLAS compliance.
SOLAS-compliant products retain the broadest addressable market while CE-marked configurations climb the fastest on European recreational demand.
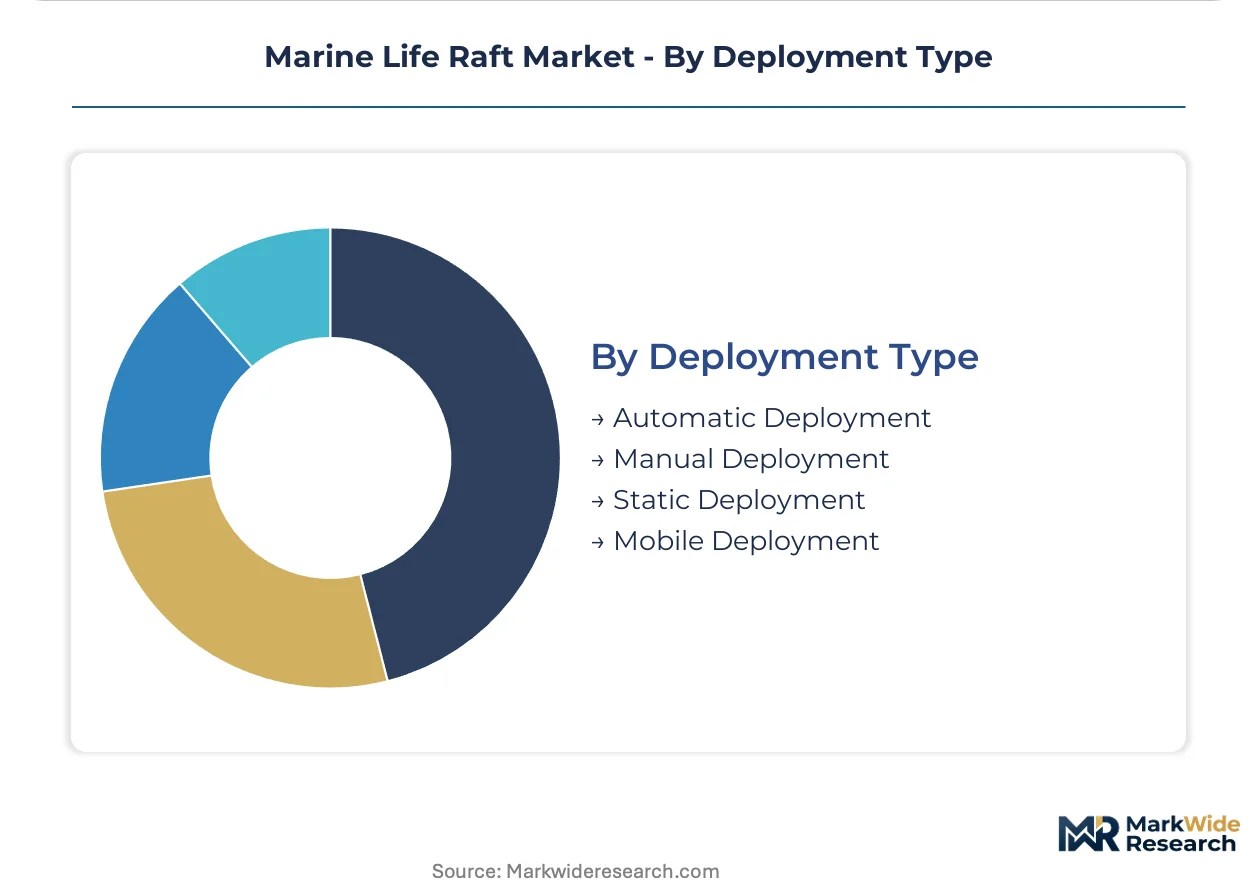
Deployment Type:
Application environment dictates mechanism selection, with automatic systems commanding premium positioning in crew-reduced operations.
- Automatic Deployment:Hydrostatic release units triggering inflation at specified depth thresholds. Offshore platforms and unmanned vessels in the North Sea specify these where rapid crew evacuation exceeds manual response capability.
- Manual Deployment:Hand-pulled inflation lanyards with backup mechanical systems. Fishing vessels and coastal operators prefer these for simplicity and reduced maintenance complexity.
- Static Deployment:Fixed cradle-mounted systems for permanent platform installation.
- Mobile Deployment:Throw-overboard or davit-launched configurations for variable stowage requirements.
Manual deployment retains the largest installed base while automatic systems gain share fastest on offshore platform construction and crew minimization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in marine safety equipment tilt toward manufacturing clusters with established classification society proximity and raw material access. Norway, Singapore, the United States, Germany, and Japan concentrate procurement decisions and fabrication capacity.
Norway
North Sea offshore support vessel construction drives self-righting raft procurement at Stavanger and Bergen shipyards. The Petroleum Safety Authority mandates enhanced stability specifications for floating production facilities. Aker Solutions and Equinor contracting clusters in Rogaland county specify automatic deployment systems for unmanned platform evacuation.
Singapore
Container fleet operators at Tuas mega-port face compressed SOLAS compliance deadlines for aging inflatable inventories. The Maritime and Port Authority enforces inspection protocols aligned with London insurance market premium calculations. Jurong shiprepair clusters handle raft upgrade cycles for Greek and Chinese-flagged vessels undergoing Southeast Asian dry-docking.
United States
Domestic manufacturing concentration around USCG approval pathways dominates coastal and fishing vessel procurement. 46 CFR subchapter Q protocols dictate construction materials and capacity ratings for vessels operating under US flag. Louisiana offshore supply base and Pacific Northwest fishing fleet clusters sustain replacement demand for manually deployed coastal configurations.
Germany
REACH chemical compliance frameworks restrict legacy chloroprene formulations across European-registered fleets. ECHA substance evaluation processes accelerate substitution toward halogen-free TPU coatings. Hamburg and Bremerhaven maritime service clusters manage MED wheel-mark certification for Baltic and Mediterranean charter operators.
Japan
Ice-class vessel specifications from Russian northern terminal operators penetrate Japanese shipyard subcontracting networks. METI industrial standards influence fabric durability testing protocols for harsh marine environments. Nagoya and Kobe manufacturing clusters supply thermoplastic polyurethane coatings to Southeast Asian raft assembly operations.
Marine Life Raft Market Competitive Landscape
Concentration sits with fully integrated manufacturers holding multi-jurisdictional certification coverage. The vendor base spans three tiers: global safety conglomerates with uniform SOLAS-USCG-ISO supply capability; regional specialists dominating single-certification domestic channels; and hand-craft ateliers serving expedition yacht customization. Strategic moves center on backward integration into TPU fabric coating and leasing model partnerships with third-party fleet service providers.
Among UK-based safety equipment conglomerates, Survitec exemplifies the certification-broad archetype enabling multinational shipping line contracts. Winslow LifeRaft occupies the hand-crafted premium tier where customization commands positioning beyond standard specifications. Datrex anchors the USCG-focused domestic channel dominance through long-standing approval pathways and coastal manufacturing proximity.
| Leading Market Players |
|---|
| Switlik |
| Crewsaver |
| Survitec |
| Viking Life-Saving Equipment |
| Arimar |
| Datrex |
| Winslow LifeRaft |
| Alnmaritec Ltd |
| Revere Survival Products |
| Others |
Supply & Pricing Matrix
Capacity utilization at chloroprene-coated nylon fabricators in Japan and Germany sets price floors for finished raft assemblies, concentrating bargaining power among manufacturers with captive coating operations while forcing assembly-only competitors toward margin compression.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure across commercial shipping procurement. Price differentiation separates SOLAS-grade certified inventory from CE-marked recreational configurations, with volume scale and customization level as secondary tiering factors. Cost compression in standard inflatable tiers is intensifying because TPU raw material volatility feeds through from Asian petrochemical producers. Coastal fishing fleets exhibit highest price sensitivity due to constrained inspection budgets, while offshore oil platforms accept premium positioning for self-righting stability specifications.
Supply Chain Analysis
China, South Korea, and Japan anchor thermoplastic polyurethane coating production for marine fabric applications. Raw material dependencies center on chloroprene rubber feedstocks, hydrostatic release unit mechanisms, and vacuum-sealing equipment. Single-source vulnerability concentrates in Asian petrochemical intermediates where geographic concentration risk exposes manufacturers to input disruption. Distribution runs through classification society-certified service stations and third-party fleet lessors bundling inspection with equipment provision.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine life raft market is recovering from cyclical fleet upgrade compression as SOLAS compliance deadlines force replacement cycles for aging inflatable inventories across international shipping.
For Market Incumbents: Compound certification agility advantages by accelerating MED wheel-mark pathways for European recreational demand while deepening backward integration into TPU fabric coating to offset raw material volatility. Threat substitution from leasing model disruption by third-party fleet service providers demands channel control investments in predictive maintenance software integration.
For New Entrants and Emerging Players: USCG fast-track approval for coastal fishing vessel configurations opens white-space penetration in North American procurement channels underserved by dominant domestic manufacturers. Target expedition yacht customization demand where hand-crafted positioning commands premium separation from volume SOLAS production. Go-to-market through direct shipyard partnerships at Stavanger and Bergen construction clusters bypasses established distributor relationships.
For Investors and Strategic Acquirers: Regional specialists holding single-certification dominance in high-barrier jurisdictions represent acquisition targets with defensive moat characteristics. Long-term viability hinges on regulatory harmonization trajectory between USCG and ISO protocols across the analysis window. Signal to monitor: classification society backlog compression indicating manufacturer throughput constraints easing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into TPU Coating | Captive supply from Nagoya and Kobe manufacturing clusters insulates margin from petrochemical volatility. |
| Leasing Model Partnership | Third-party fleet service bundling at Tuas mega-port shifts compliance risk from operators to equipment providers. |
| Self-Righting Ballast Certification | North Sea Petroleum Safety Authority mandates compress demand for conventional flat-bottom architectures. |
| REACH-Compliant Formulation Transition | ECHA substance evaluation processes accelerate substitution toward halogen-free TPU for Baltic and Mediterranean fleets. |
| RFID-Enabled Inspection Integration | Predictive maintenance convergence with fleet management software reduces downtime for Greek and Singaporean container operators. |
Research Methodology
Cross-validation between primary interviews with shipyard procurement managers, classification society surveyors, and fleet safety officers anchors the qualitative findings against secondary validation from customs trade data, Lloyd's Register certification records, and SEC filings of marine safety conglomerates. Bottom-up vessel inventory analysis triangulates against top-down fleet operator expenditure surveys to constrain estimate variance.
Sensitivity analysis around TPU input cost trajectories and SOLAS compliance deadline phasing shapes projection reliability across the modeling period. Segmentation dimensions include product architecture, certification jurisdiction, deployment mechanism, and vessel class tier. CAGRs derive from replacement cycle modeling against fleet age distributions and regulatory mandate schedules, with offshore platform construction pipelines and ice-class vessel specifications as industry-specific demand inputs.
Decision-makers should treat outputs as directional under stable regulatory harmonization assumptions; material deviation in USCG-ISO protocol convergence would warrant model refresh. Recalibration cycles align with material shifts in classification society approval timelines and petrochemical feedstock pricing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Aquaculture Cage Market
Aquaculture Innovations
Aquaculture Additives Market
Aquaculture Innovations
North America Shrimp Market
Aquaculture Innovations
Global Aquafeed and Aquaculture Additives Market
Aquaculture Innovations
Ornamental Tropical Fish Feed Market
Aquaculture Innovations
Global Aquaculture Vaccine Market
Aquaculture Innovations
Salmon Feed Market
Aquaculture Innovations
Aquaculture Pumps Market
Aquaculture Innovations
Tilapia Market
Aquaculture Innovations
China Aquafeed Market
Aquaculture Innovations
Global Precision Aquaculture Market
Aquaculture Innovations
Seaweed Cultivation Market
Aquaculture Innovations
Global Aquafeed Market
Aquaculture Innovations
Aquaculture Products Market
Aquaculture Innovations
Ecuador Shrimp Feed Market
Aquaculture Innovations
Smart Aquaculture Systems Market