
 Saudi Arabia Aquaculture Market | 2026-2036
Saudi Arabia Aquaculture Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Aquaculture Market Intelligence
Maintenance contracts for water quality monitoring and aeration infrastructure is repositioning how producers monetize long-term relationships with buyers. National Aquaculture Group (NAQUA) leverages its integrated hatchery-to-harvest model across the Red Sea coast. Saudi Fisheries Company (SFC) anchors government supply agreements that sustain volume commitments to institutional buyers. Tabuk Fisheries Company specializes in cold-chain logistics that extend shelf reach into inland population centers.
Saudi Arabia aquaculture encompasses the controlled cultivation of finfish, crustaceans, and mollusks in marine, brackish, and freshwater environments, typically operating at salinities between 15-35 ppt and temperatures optimized for tropical species metabolism. The sector serves domestic protein substitution goals, reducing import dependency for a nation that consumes over seafood per capita. Shrimp dominates production value given established hatchery protocols and established export pathways to Asian markets. Recirculating Aquaculture Systems command premium capital allocation due to their water efficiency and biosecurity advantages in an arid kingdom where freshwater scarcity constrains expansion. Food Service channels absorb the fastest volume growth as hotel and restaurant chains localize procurement under national sourcing directives.
SFDA and the Ministry of Environment, Water and Agriculture jointly enforce aquaculture licensing, veterinary drug residue limits, and hatchery biosecurity protocols that determine which operations achieve commercial scale. The Saudi Standards, Metrology and Quality Organization (SASO) mandates labeling and cold-chain certification that filter subscale producers from retail distribution. MOHAP alignment with Gulf Cooperation Council harmonized standards shapes cross-border trade access for processed seafood. Stakeholders must track how evolving environmental impact assessments for coastal zone leases redistribute production capacity between established Red Sea operators and emerging Gulf of Aqaba entrants.
Market Dynamics
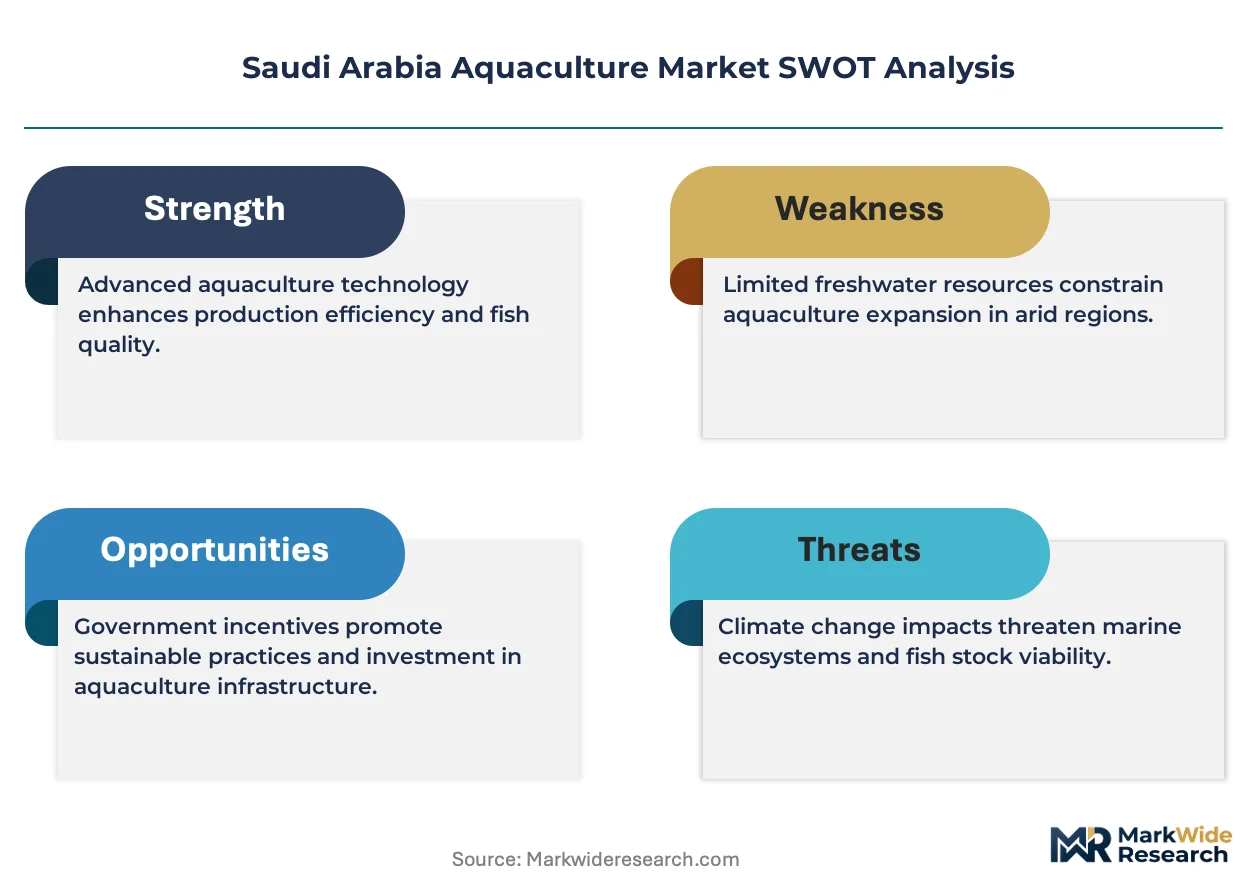
Recirculating Aquaculture Systems technology is compressing the capital recovery timeline for coastal operators while SFDA licensing protocols filter subscale hatcheries from commercial expansion zones.
Growth Catalysts
- Vision 2030 Food Security Mandates:Government procurement quotas for domestic seafood anchor volume commitments from institutional buyers including hospital and military catering networks.
- Red Sea Coastal Zone Leasing:Designated aquaculture development corridors near Jazan and Tabuk concentrate infrastructure investment and technical talent pools.
- RAS Water Efficiency Standards:Closed-loop system protocols enable production expansion in freshwater-scarce regions where open-water farming faces hydrological constraints.
Market Restraints
- Feed Input Cost Volatility:Marine protein and soy-based aquafeed prices fluctuate with global commodity markets, compressing margin predictability for shrimp and finfish operators.
- Broodstock Import Dependency:Domestic hatcheries rely on live post-larvae shipments from Southeast Asian suppliers, creating biosecurity vulnerability and supply interruption risk.
- SASO Cold-Chain Certification:Refrigerated transport and processing facility standards exclude smaller producers from retail distribution channels.
Strategic Opportunities
- Gulf of Aqaba Frontier Zones:Underdeveloped coastline north of Tabuk offers untapped lease capacity for integrated hatchery-to-harvest operations with direct Red Sea export access.
- Hotel and Restaurant Localization Directives:National sourcing requirements for hospitality chains create captive demand for domestically farmed shrimp and seabream.
- RAS-Photovoltaic Hybrid Systems:Solar-powered recirculating infrastructure convergence reduces energy opex for inland desert farming facilities.
Industry Challenges
- Specialized Technician Scarcity:Water quality management and system engineering expertise pools remain shallow relative to RAS facility rollout timelines.
- Multi-Agency Licensing Coordination:SFDA veterinary protocols, Ministry of Environment coastal leases, and SASO processing certifications require sequential approvals that extend project commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Aquaculture Market |
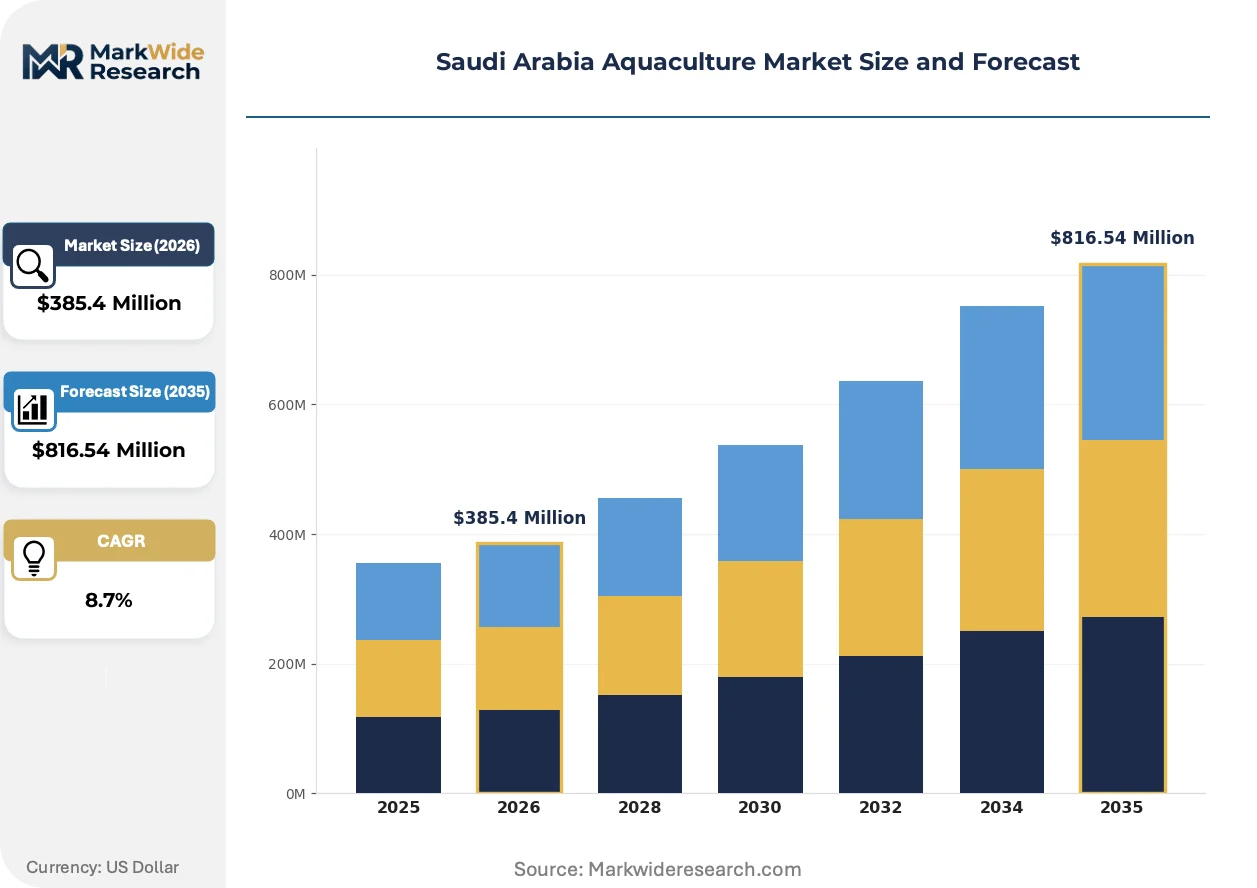
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shrimp, Fish, Mollusks, Crustaceans Technology: Recirculating Aquaculture Systems, Extensive Systems, Semi-Intensive Systems, Integrated Multi-Trophic Aquaculture End User: Wholesale, Retail, Food Service, Exporters Sales Channel: Direct Sales, Distributors, Online Sales, Marketplaces |
| Companies Covered | Arabian Shrimp Company, Jazan Energy, and Development Company (Jazadco), National Aquaculture Group (NAQUA), ARASCO Aquaculture, Aqua Bridge Farms, Saudi Fisheries Company (SFC), Asmak Holdings, National Prawn Company, Tabuk Fisheries Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Aquaculture Market Strategic Shifts & Innovations
Automation and renewable energy integration are compressing operating cost structures while regulatory alignment with Gulf Cooperation Council standards opens cross-border processed seafood pathways.
Recirculating Aquaculture Systems with biofloc technology is expanding into coastal shrimp operations previously dependent on flow-through water exchange. Major Red Sea producers are retrofitting existing pond infrastructure with closed-loop filtration and probiotic water treatment protocols. This technology is expanding into disease-vulnerable grow-out stages where biosecurity failure previously triggered catastrophic inventory loss.
SFDA veterinary drug residue monitoring protocols now mandate batch-level testing for export-certified product streams. Processing facilities must maintain chain-of-custody documentation from hatchery through harvest to qualify for Asian market access. Shrimp exporters targeting South Korean and Japanese buyers face the strictest enforcement, with MFDS-equivalent standards becoming the de facto compliance benchmark.
Hotel procurement teams now specify domestic farm certification as a contract eligibility condition rather than a preference. Large hospitality groups operating in Riyadh and Jeddah are consolidating supplier relationships with vertically integrated aquaculture operations that control hatchery, grow-out, and processing stages. This concentration is most visible in the Red Sea coastal corridor where NAQUA and Tabuk Fisheries anchor multi-year volume agreements with international hotel chains.
Saudi Arabia Aquaculture Market Segmentation
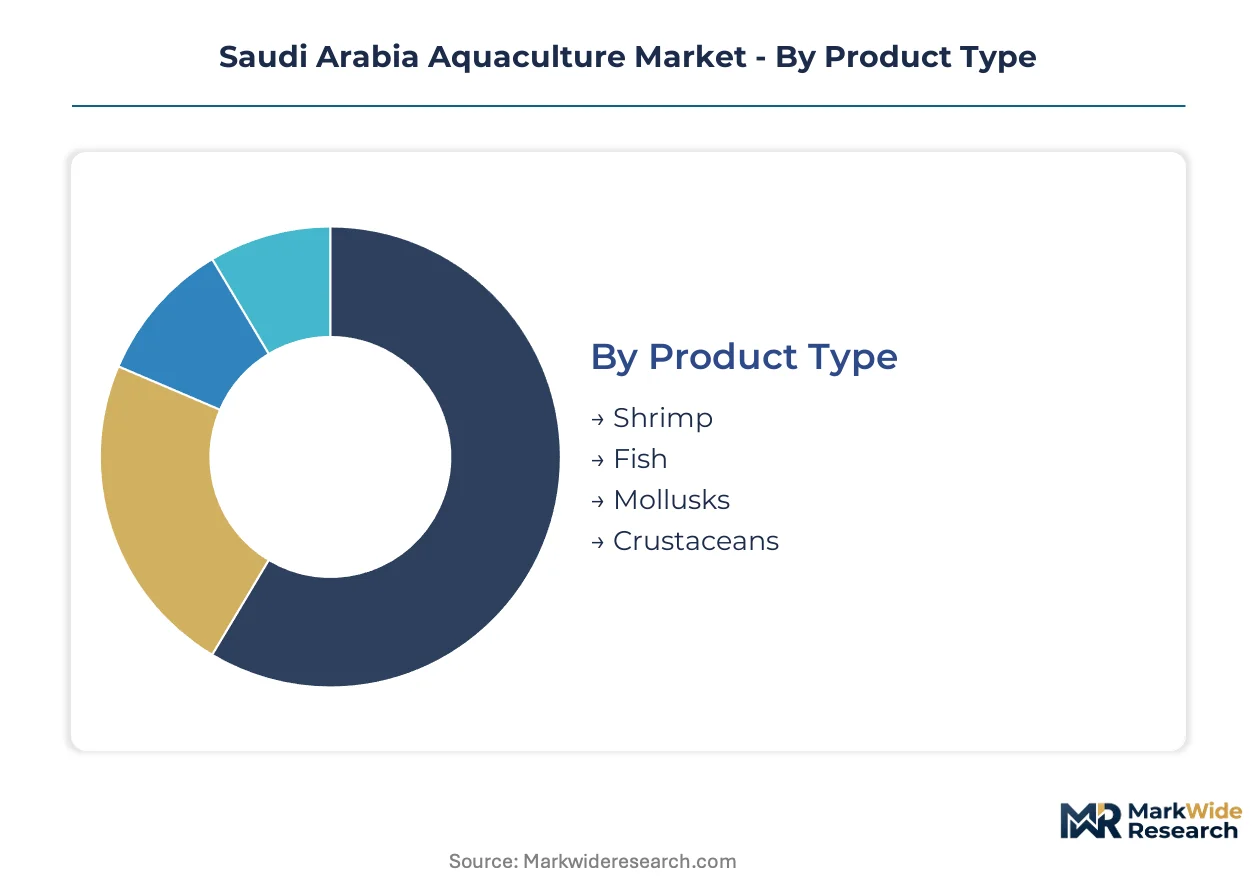
Segmentation in Saudi aquaculture reveals how production technology, species selection, and channel strategy intersect with Vision 2030 procurement mandates. Buyers prioritize traceability, biosecurity certification, and cold-chain reliability when selecting suppliers across institutional and retail segments.
Product Type:
Species selection divides buyers by protein substitution goals and export market access requirements.
- Shrimp:Penaeus indicus and P. monodon dominate hatchery output with established broodstock protocols and Asian export pathways. Red Sea coastal farms concentrate grow-out capacity near Jazan to serve Korean and Japanese buyers under MFDS-equivalent standards.
- Fish:Seabream and seabass command premium positioning in hotel procurement contracts where domestic sourcing directives apply. RAS facilities near Tabuk optimize water temperature for tropical species metabolism in freshwater-scarce environments.
- Mollusks:Oyster and clam cultivation remains limited by SASO shellfish sanitation protocols.
- Crustaceans:Mud crab and lobster farming occupies niche experimental stations without commercial scale.
Shrimp leads volumes today; fish is gaining share fastest under hospitality localization directives.
Technology:
Capital intensity and water efficiency separate coastal lease applicants from inland desert operators.
- Recirculating Aquaculture Systems:Closed-loop filtration with biofloc protocols enables production in regions where hydrological constraints block open-water expansion. Jazan and Tabuk zones attract premium capital allocation for shrimp and finfish operations requiring biosecurity isolation.
- Extensive Systems:Low-density pond culture without mechanical aeration persists in legacy coastal leases where SFDA veterinary oversight remains lighter.
- Semi-Intensive Systems:Partial water exchange with supplemental feeding occupies mid-tier producers seeking scale without full RAS capital burden.
- Integrated Multi-Trophic Aquaculture:Seaweed and filter-feeder co-culture trials proceed at experimental stations without commercial deployment.
RAS commands investment attention; semi-intensive systems retain installed base dominance.
End User:
Volume commitment predictability and certification requirements shape supplier relationships across buyer categories.
- Food Service:Hotel and restaurant chains operating in Riyadh and Jeddah specify domestic farm certification as contract eligibility conditions. NAQUA and Tabuk Fisheries anchor multi-year volume agreements with international hospitality groups under national sourcing mandates.
- Wholesale:Institutional buyers including hospital and military catering networks absorb volume through government procurement quotas anchored by Vision 2030 food security targets.
- Retail:Supermarket chains require SASO cold-chain certification that filters subscale producers from shelf placement.
- Exporters:Asian market access demands batch-level SFDA residue testing with chain-of-custody documentation from hatchery through harvest.
Food Service absorbs capital fastest; wholesale anchors volume stability through state procurement.
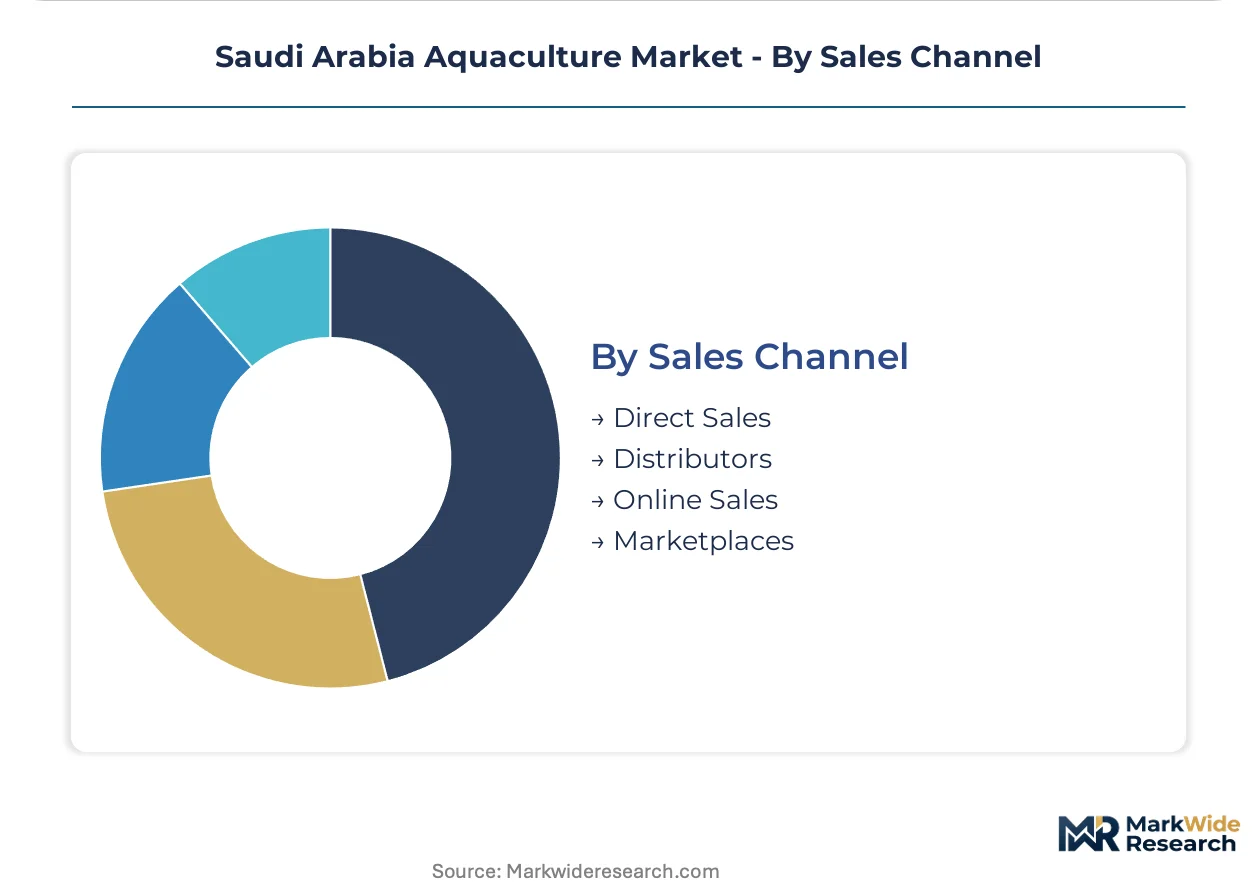
Sales Channel:
Relationship depth and logistics control determine margin capture for producers at different scale tiers.
- Direct Sales:Vertically integrated operations with captive hatchery and processing stages contract directly with hotel procurement teams and institutional buyers. This channel bypasses distributor margins but requires dedicated sales infrastructure.
- Distributors:Cold-chain logistics specialists extend shelf reach into inland population centers from Red Sea production zones.
- Online Sales:E-commerce platforms for fresh seafood remain limited by last-mile temperature control reliability.
- Marketplaces:Centralized wholesale markets in Jeddah and Riyadh handle spot transactions for uncertified product streams.
Direct Sales concentrates premium volume; distributors retain intermediation power in retail expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While Saudi Arabia's aquaculture sector commands the largest installed capacity in the Gulf Cooperation Council, the United Arab Emirates operates more intensive recirculating systems per coastline kilometer. Both kingdoms prioritize domestic protein substitution under national food security frameworks.
Western Region
Red Sea coastal zones near Jazan and Tabuk absorb the majority of private capital allocation for shrimp and finfish operations. SFDA veterinary protocols and Ministry of Environment coastal leases determine which producers achieve commercial scale. Jazan Energy and Development Company anchors integrated operations that combine hatchery, grow-out, and processing stages under single ownership.
Eastern Province
Gulf coastline operations face higher salinity fluctuations that constrain species selection to salt-tolerant finfish varieties. Government procurement quotas for institutional buyers sustain volume commitments from established producers. Dammam-based cold-chain distributors extend shelf reach into Riyadh and other inland population centers.
Riyadh
Desert-adjacent RAS facilities exploit photovoltaic hybrid configurations to reduce energy operating expenditure. Hotel and restaurant procurement teams in the capital specify domestic farm certification as contract eligibility conditions. National Aquaculture Group maintains multi-year volume agreements with international hospitality chains operating in the metropolitan area.
NEOM Northwest
Emerging aquaculture development corridors along the Gulf of Aqaba attract experimental integrated multi-trophic trials. Renewable energy integration and desalination co-location create unique infrastructure economics for prospective operators. Tabuk Fisheries Company evaluates lease applications for expanded hatchery-to-harvest capacity with direct Red Sea export access.
Saudi Arabia Aquaculture Market Key Industry Players
Top-tier vendors anchor integrated hatchery-to-harvest operations, while mid-tier producers concentrate on single-stage specialization within coastal lease zones. The market structure reflects moderate consolidation around vertically integrated Red Sea operators and fragmented semi-intensive pond culture in legacy holdings. Two strategic archetypes dominate: full-stack producers controlling biology through processing, and logistics specialists capturing margin through cold-chain intermediation. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure government procurement quotas and hospitality supply contracts.
Within the integrated producer tier, National Aquaculture Group and Tabuk Fisheries Company exemplify full-stack operators with captive hatchery, grow-out, and processing infrastructure. Saudi Fisheries Company occupies a position as a government-contracted supplier anchoring institutional volume commitments. Jazan Energy and Development Company represents the energy-integrated archetype, leveraging co-located power generation for operational cost structure optimization.
| Leading Market Players |
|---|
| Arabian Shrimp Company |
| Jazan Energy, and Development Company (Jazadco) |
| National Aquaculture Group (NAQUA) |
| ARASCO Aquaculture |
| Aqua Bridge Farms |
| Saudi Fisheries Company (SFC) |
| Asmak Holdings |
| National Prawn Company |
| Tabuk Fisheries Company |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between SFDA-export-certified and domestic-only product streams manifests in pricing spreads that track cold-chain infrastructure investment and batch-level residue testing compliance. Premium tiers command positioning in Korean and Japanese export channels where MFDS-equivalent standards apply, while commodity-grade volumes flow through government procurement quotas at compressed margins.
Pricing Analysis
Capacity additions in Jazan and Tabuk are reshaping price floors for shrimp and seabream as RAS facility rollouts intensify competition for hospitality contracts. Contract-based long-term offtake dominates institutional channels, with price differentiation driven by certification level and vertical integration depth. Pricing pressure stems from soy and marine protein feed input volatility, with wholesale buyers exhibiting highest price sensitivity while export-certified segments maintain pricing power.
Supply Chain Analysis
Vision 2030 domestic-content mandates are reshaping sourcing patterns for hatchery equipment and aeration infrastructure toward local fabrication partnerships. Supply concentration centers on Thailand and Indonesia for live post-larvae broodstock, with Norway and Denmark anchoring RAS technology components. Feed formulation draws from global commodity markets, creating tariff exposure on soy imports. Distribution runs through Dammam and Jeddah cold-chain hubs to Riyadh and Tabuk inland centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia aquaculture functions as a stable compounder underpinned by irreversible food security procurement quotas that institutionalize volume absorption regardless of cyclical protein price swings.
For Market Incumbents: Lock in multi-year hospitality supply contracts before RAS capacity floods the Red Sea corridor with certified volume. Secure backward integration into hatchery broodstock through Southeast Asian partnerships to neutralize biosecurity interruption risk. Defend margin position by investing in photovoltaic-hybrid energy systems that reduce operating expenditure exposure to grid tariff adjustments. For New Entrants and Emerging Players: Recirculating Aquaculture Systems with biofloc protocols offer the most penetrable wedge for Gulf of Aqaba lease applications where established operators lack presence. Target experimental integrated multi-trophic trials at NEOM Northwest to secure preferential coastal zone access before regulatory capacity caps harden. Pursue direct sales channel establishment with Riyadh hotel procurement teams under national sourcing directive eligibility. For Investors and Strategic Acquirers: Consolidation pressure builds where semi-intensive legacy pond operators face SASO cold-chain certification exclusion from retail distribution. Mid-term viability favors vertically integrated hatchery-to-harvest operations with captive processing and export certification. Monitor SFDA veterinary protocol enforcement intensity as the signal indicating regulatory barrier height for subscale competitor elimination.| Strategic Initiative | Industry Significance |
|---|---|
| RAS Facility Retrofit with Biofloc Integration | Enables water-efficient expansion in Tabuk's freshwater-scarce environment under SFDA biosecurity protocols. |
| Photovoltaic-Hybrid Energy System Deployment | Reduces energy opex for desert-adjacent facilities serving Riyadh hospitality procurement networks. |
| Broodstock Import Partnership Structuring | Secures live post-larvae supply chains from Thai and Indonesian hatcheries against biosecurity interruption. |
| Export Certification Infrastructure Investment | Qualifies batch-level residue testing capacity for Korean and Japanese market access under MFDS-equivalent standards. |
| Direct Hotel Procurement Channel Establishment | Bypasses distributor margins by contracting with Jeddah and Riyadh hospitality groups under localization directives. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hatchery operations managers, SFDA regulatory affairs officers, hotel procurement directors, cold-chain logistics specialists, and Ministry of Environment coastal lease administrators with secondary validation from customs trade records, SFDA veterinary protocol filings, SASO certification databases, and Vision 2030 food security procurement disclosures. Bottom-up facility capacity tallies triangulated against top-down protein consumption substitution models.
Historical production volumes and capital expenditure patterns across the analysis window anchored forward projections segmented by species type, technology tier, end-user channel, and regional production cluster. CAGRs derived from fitted growth curves incorporating RAS adoption rates, coastal lease issuance velocity, and hospitality sector localization compliance timelines. Feed input cost indices and renewable energy integration rates supplied industry-specific forecast modifiers.
The model holds under sustained Vision 2030 procurement quota enforcement and stable Southeast Asian broodstock supply; deviation in SFDA veterinary protocol stringency or Red Sea coastal lease availability would shift capacity expansion trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Japan Aquafeed Market
Aquaculture Innovations
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market
Aquaculture Innovations
Mariculture Market
Aquaculture Innovations
Tilapia Market
Aquaculture Innovations
Bacterial Diagnostics in Aquaculture Market
Aquaculture Innovations
Sandfish Market
Aquaculture Innovations
Vietnam Aquaculture Market
Aquaculture Innovations
Aquaculture Pumps Market
Aquaculture Innovations
Bahrain Fisheries and Aquaculture Market
Aquaculture Innovations
Oman Aquaculture Market
Aquaculture Innovations
Global Aquafeed Market
Aquaculture Innovations
Global Plant Based Fish Feed Market
Aquaculture Innovations
Salmon Feed Market
Aquaculture Innovations
Crab Market
Aquaculture Innovations
North America Aqua Feed Market
Aquaculture Innovations
Smart Aquaculture Systems Market