
 Brazil Fisheries and Aquaculture Market | 2026-2036
Brazil Fisheries and Aquaculture Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Fisheries and Aquaculture Market Analysis
Premium-grade seafood certification is rotating through Brazilian supply chains as export buyers tighten specifications. GeneSeas Aquacultura dominates southern Brazil's tilapia corridor with vertically integrated hatchery-to-processing operations. C.Vale Cooperativa Agroindustrial leverages its cooperative network to secure feed inputs and channel access for member producers. JBS SA extends its protein platform into aquaculture through processing scale and cold-chain distribution.
Brazil fisheries and aquaculture encompasses the commercial harvesting, farming, processing, and distribution of finfish, crustaceans, and mollusks for human consumption, with products typically graded by size class, freshness index, and residue compliance for domestic and export sale. Marine fish and crustaceans lead production value, while freshwater fish sustains volume leadership through tilapia pond systems across the Paraná River basin. Intensive farming methods capture margin concentration as biofloc and recirculating aquaculture systems reduce land and water intensity per kilogram produced.
ANVISA sets maximum residue limits for veterinary inputs and processing additives, directly shaping which chemistries producers can deploy and which markets accept Brazilian product. IBAMA environmental licensing and the EU IUU Regulation compliance requirements determine farm expansion permissions and export market access eligibility. Stakeholders must monitor evolving traceability mandates and water quality standards as these determine competitive participation in premium destination markets.
Market Dynamics
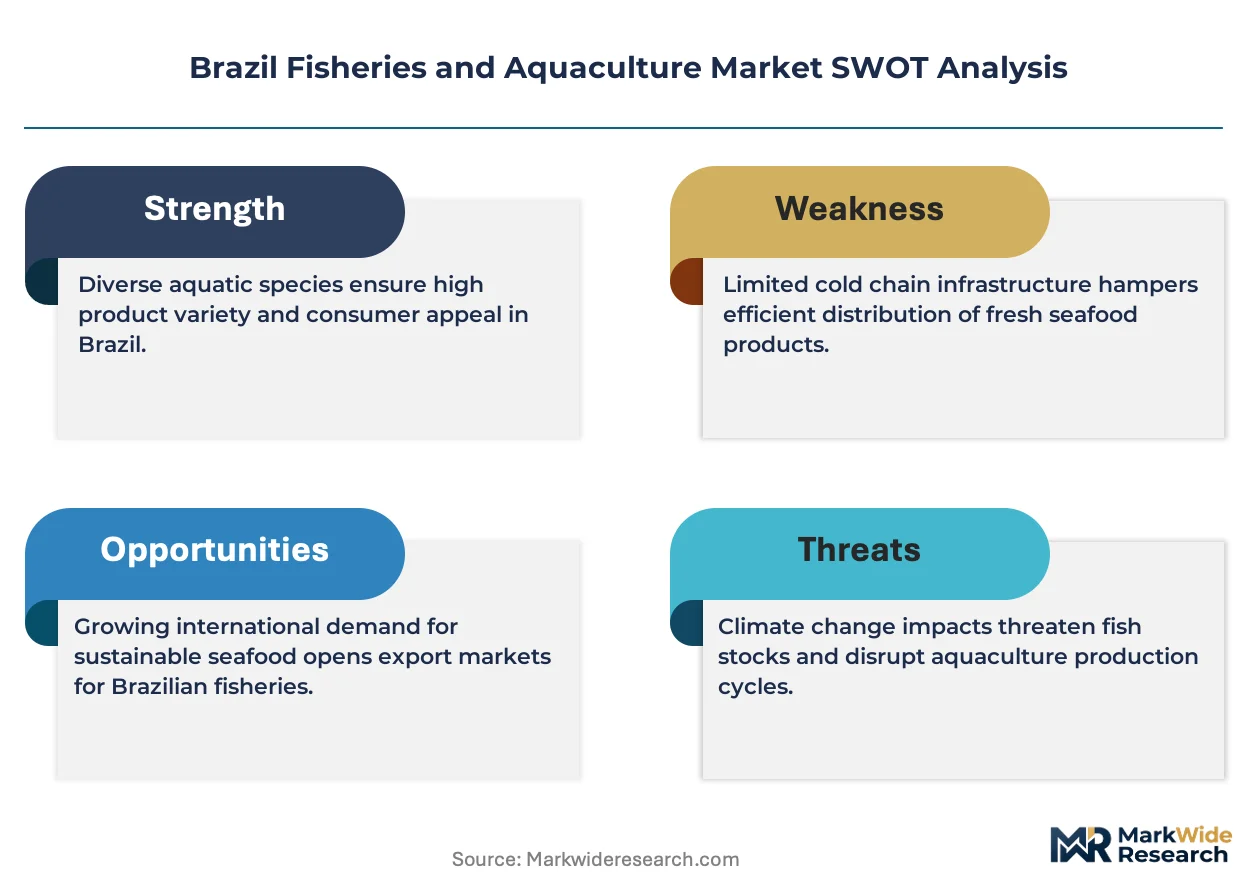
IBAMA's environmental licensing backlog is compressing farm expansion timelines across Santa Catarina and Rio Grande do Sul, forcing producers toward intensive recirculating systems that bypass greenfield permit dependencies.
Growth Catalysts
- Biofloc technology adoption:Southern Brazilian tilapia operators deploy biofloc systems to reduce water exchange rates and land requirements per ton harvested.
- EU IUU Regulation alignment:Export-oriented processors invest in vessel monitoring and catch documentation to maintain access to European seafood buyers.
- Paraná River basin concentration:Pond farming clusters in Mato Grosso do Sul leverage integrated feed mills and processing infrastructure to compress logistics costs.
Market Restraints
- Soybean meal price volatility:Aquafeed formulations depend on Brazilian soybean derivatives, exposing margins to agricultural commodity swings.
- IBAMA licensing delays:Environmental permit backlogs stretch farm development timelines to 18-24 months in sensitive watershed zones.
- Wild capture substitution:Artisanal marine fisheries supply competing protein at lower price points in Northeast Brazilian retail channels.
Strategic Opportunities
- Amazon basin frontier:Underdeveloped freshwater resources in Pará and Amazonas states offer untapped pond expansion potential with lower land costs.
- ANVISA residue compliance:Stricter veterinary input tracking creates first-mover advantage for integrated operators with captive laboratories.
- Direct foodservice contracting:Large restaurant chains bypass traditional wholesale channels to secure traceable, certified product volumes.
Industry Challenges
- Aquaculture veterinary specialization gap:Brazil trains insufficient fish health professionals to service expanding intensive farm densities.
- ASC certification timeline compression:Shrimp exporters face 12-18 month audit cycles to maintain supermarket supply contracts in European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Fisheries and Aquaculture Market |
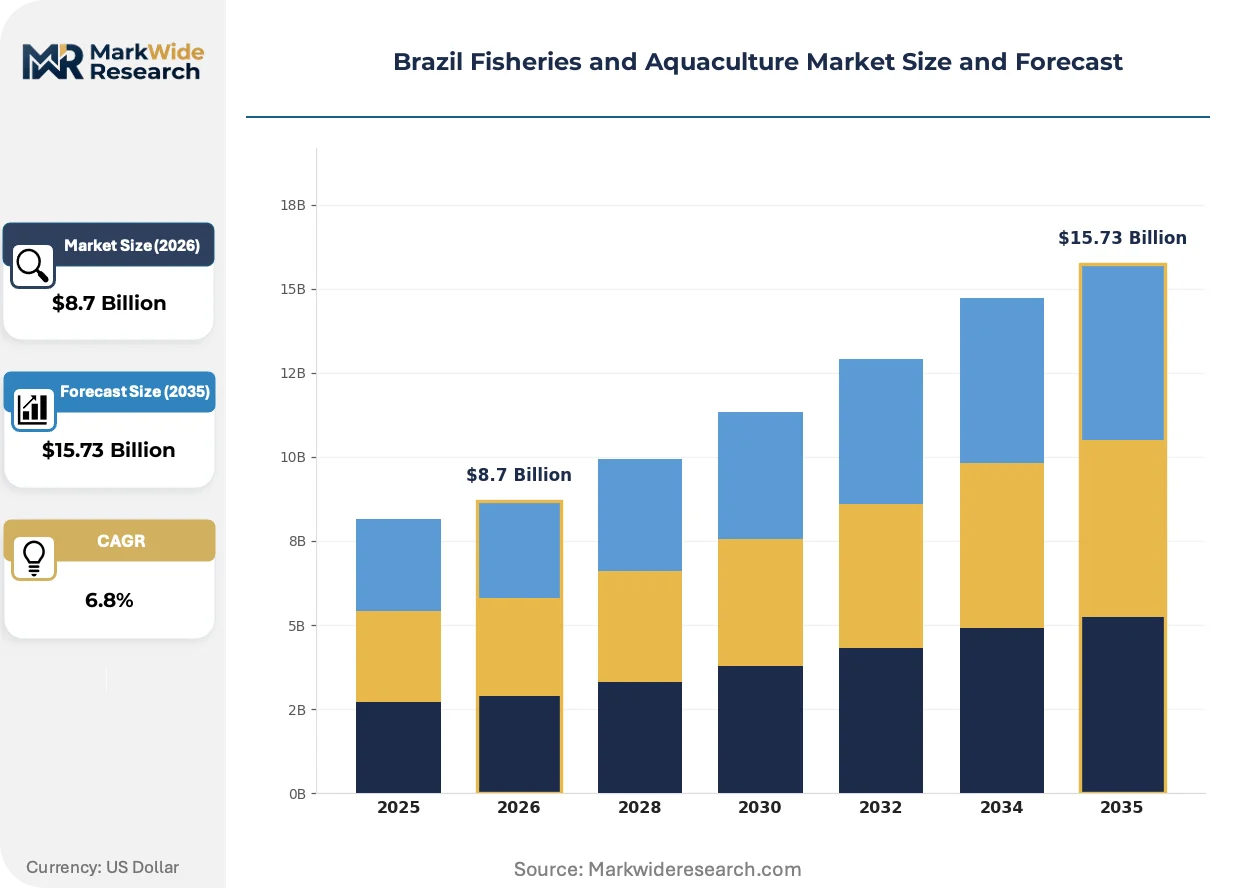
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Marine Fish, Freshwater Fish, Crustaceans, Mollusks Farming Method: Traditional, Semi-Intensive, Intensive, Organic End User: Retail, Wholesale, Food Service, Export Distribution Channel: Direct Sales, Online, Supermarkets, Specialty Stores |
| Companies Covered | C.Vale Cooperativa Agroindustrial, GeneSeas Aquacultura, BRF, Netuno Brasil, Mar and Terra, Frescatto, JBS SA, Cooke Aquaculture, Blue Ridge Aquaculture, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Fisheries and Aquaculture Market Emerging Trajectories
Production intensification is compressing the traditional extensive-to-semi-intensive transition, with automation and biological water treatment converging to reshape farm economics across Brazil's southern corridor.
Recirculating aquaculture systems (RAS) are displacing flow-through pond infrastructure in land-constrained municipalities near Florianópolis. Mid-scale tilapia operators adopt modular RAS units to circumvent IBAMA's riparian setback requirements. The technology is displacing greenfield pond development by enabling production density above 50 kg per cubic meter on sub-hectare footprints.
ANVISA's 2023 updated residue monitoring protocols expand testing matrices for banned antibiotics in shrimp and finfish exports. The regulation forces feed mills to reformulate prophylactic additive packages and maintain batch traceability records. Santa Catarina processors bear the heaviest compliance burden, with EU-bound product requiring third-party laboratory verification at landing.
Certification-driven procurement now dominates Brazilian foodservice purchasing, with large restaurant groups requiring ASC or BAP documentation for contracted volumes. Traditional spot-market buying through São Paulo wholesale terminals loses share to direct farm partnerships with embedded traceability. The shift is most visible in Rio Grande do Sul, where tilapia cooperatives integrate harvest scheduling with chain restaurant demand forecasting.
Brazil Fisheries and Aquaculture Market Segmentation
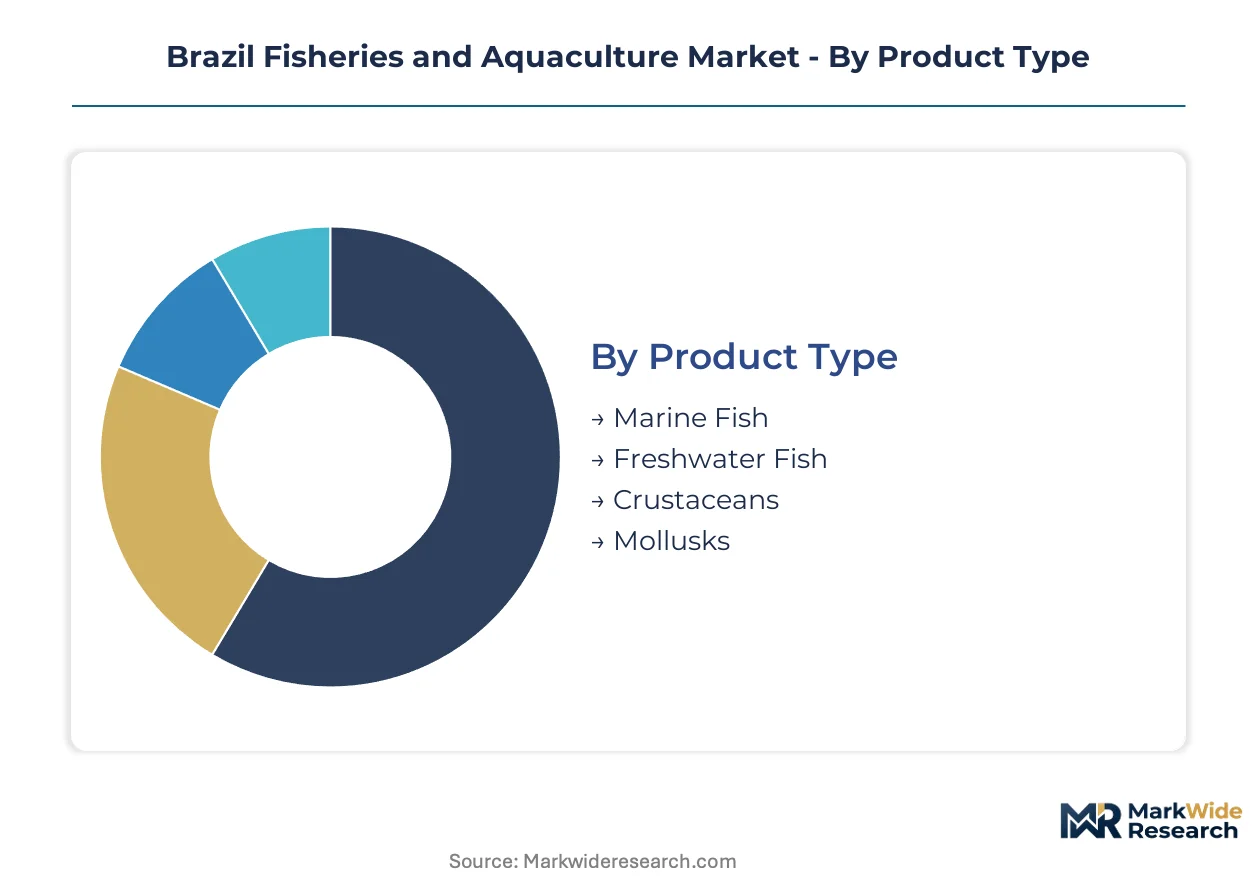
Segmentation in Brazilian fisheries and aquaculture reveals where capital is concentrating and which production configurations capture premium pricing. Each dimension shapes regulatory exposure, margin structure, and export eligibility differently across Santa Catarina and Rio Grande do Sul production clusters.
Product Type:
Marine fish commands the highest unit margins in Brazilian seafood, driven by export quota scarcity and EU IUU compliance costs that filter out lower-value competitors.
- Marine Fish:Snapper, grouper, and sardine species dominate landed value. Santa Catarina purse-seine and longline fleets supply São Paulo foodservice buyers with same-day freshness protocols. ANVISA residue limits and EU catch documentation requirements compress eligible supply volumes.
- Freshwater Fish:Tilapia pond systems across the Paraná River basin sustain volume leadership. Mato Grosso do Sul integrators deploy biofloc technology to reduce water exchange and land intensity per kilogram harvested.
- Crustaceans:Marine shrimp farming clusters in Rio Grande do Sul face ASC certification timelines of 12-18 months for European supermarket contracts.
- Mollusks:Oyster and mussel cultivation concentrates in Florianópolis coastal lagoons with lower capital requirements than finfish or shrimp operations.
Freshwater fish holds installed capacity. Crustaceans is rotating up the share rankings.
Farming Method:
Production intensity correlates directly with permit complexity—IBAMA licensing backlogs favor methods that minimize greenfield land requirements.
- Traditional:Extensive pond systems with minimal feeding and low stocking densities persist in Northeast Brazil artisanal fisheries. Wild capture substitution pressure from these operations compresses pricing in domestic retail channels.
- Semi-Intensive:Moderate feeding regimes and mechanical aeration characterize transitional operations in Paraná state. These farms face margin pressure from both input cost volatility and intensive-system competition.
- Intensive:Recirculating aquaculture systems achieve production densities above 50 kg per cubic meter on sub-hectare footprints near Florianópolis. Biofloc technology adoption accelerates as operators circumvent riparian setback permitting delays.
- Organic:Certified organic production remains nascent, constrained by feed input traceability requirements and limited domestic price premiums.
Intensive systems are climbing the fastest. Traditional methods retain volume share but lose margin contribution.
End User:
Channel selection determines traceability burden and payment terms, with foodservice and export buyers imposing the strictest certification requirements.
- Retail:Supermarket chains in São Paulo and Rio de Janeiro increasingly require ASC or BAP documentation for shelf placement. Price competition from artisanal marine fisheries limits premium capture in Northeast Brazil.
- Wholesale:Traditional spot-market buying through São Paulo wholesale terminals loses share to direct farm partnerships with embedded traceability.
- Food Service:Large restaurant groups bypass traditional wholesale channels to secure traceable, certified product volumes. Rio Grande do Sul tilapia cooperatives integrate harvest scheduling with chain restaurant demand forecasting.
- Export:EU-bound shipments require vessel monitoring systems and catch documentation under IUU Regulation compliance. Santa Catarina processors bear the heaviest third-party laboratory verification burden.
Food service holds contract volume. Export is expanding most quickly as certification infrastructure matures.
Distribution Channel:
Cold-chain reliability and traceability documentation separate channel economics, with direct sales capturing the highest per-unit margins.
- Direct Sales:Farm-to-processor and farm-to-restaurant contracting eliminates wholesale margin extraction. Large cooperatives in southern Brazil leverage this channel for certified volume commitments.
- Online:E-commerce seafood platforms remain underdeveloped due to cold-chain fragmentation and consumer freshness skepticism.
- Supermarkets:Hypermarket chains in Southeast Brazil drive standard-grade tilapia and shrimp volumes with private-label programs.
- Specialty Stores:Premium seafood retailers in São Paulo concentrate on certified marine fish and organic-labeled products with higher service intensity.
Direct sales holds margin concentration. Specialty stores are gaining share fastest as urban premium consumption expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's seafood trade balance tilts toward deficit, with high-value marine imports from Argentina and Chile competing against domestic tilapia and shrimp exports bound for Europe and North America. Regional production clusters concentrate where IBAMA licensing, feed mill proximity, and cold-chain infrastructure intersect.
São Paulo
São Paulo state absorbs the largest share of domestic seafood consumption, with restaurant chains and retail hypermarkets driving certified product procurement. ANVISA residue monitoring protocols shape supplier qualification for distributors serving the metropolitan region. Santos port handles the bulk of imported marine fish entering the Southeast market.
Santa Catarina
Santa Catarina anchors Brazil's marine capture and shrimp farming output, with Florianópolis processing clusters supplying EU-bound exports under IUU Regulation compliance. IBAMA environmental licensing backlogs compress expansion timelines, pushing operators toward recirculating aquaculture systems. Joinville and Itajaí concentrate cold-storage and value-added processing capacity.
Rio Grande do Sul
Rio Grande do Sul dominates tilapia cooperative production, with member networks integrating feed procurement through C.Vale-linked operations. The state's southern corridor connects pond farming clusters to Porto Alegre foodservice buyers demanding ASC-certified volumes. Rio Grande port infrastructure supports frozen shrimp export logistics.
Paraná
Paraná's Paraná River basin sustains extensive tilapia pond systems transitioning toward biofloc intensification. Mato Grosso do Sul integrators leverage nearby feed mills to compress production costs. Londrina and Maringá serve as distribution nodes for fresh product moving toward São Paulo and Curitiba markets.
Pará
Pará represents the Amazon basin frontier for freshwater aquaculture expansion, with underdeveloped land resources offering lower site acquisition costs versus southern states. IBAMA licensing complexity remains elevated in protected watershed zones. Belém processing infrastructure currently limits large-scale commercial development despite biological production potential.
Brazil Fisheries and Aquaculture Market Vendor Landscape
Listed protein conglomerates compete with private aquaculture specialists across feed-to-retail integration depth. Market structure tilts toward cooperative networks in tilapia and concentrated processing scale in shrimp, with three archetypes dominating: vertically integrated hatchery-to-plate operators, feed-linked cooperative systems, and diversified meat processors extending into seafood. Capacity expansion and certification infrastructure investment constitute the dominant competitive moves, as export eligibility hinges on audit-ready traceability systems.
Within the cooperative tier, C.Vale Cooperativa Agroindustrial anchors feed-input security and channel access for member producers across southern Brazil. GeneSeas Aquacultura occupies a position exemplifying hatchery-to-processing vertical control in the tilapia corridor. JBS SA represents diversified protein platform extension into aquaculture through processing scale and distribution infrastructure.
| Leading Market Players |
|---|
| C.Vale Cooperativa Agroindustrial |
| GeneSeas Aquacultura |
| BRF |
| Netuno Brasil |
| Mar and Terra |
| Frescatto |
| JBS SA |
| Cooke Aquaculture |
| Blue Ridge Aquaculture |
| Others |
Supply Flow & Price Mechanics
EU IUU Regulation compliance gates both supply qualification and price differentiation simultaneously, filtering out non-compliant operators while enabling certified exporters to command premium positioning in European foodservice channels. ANVISA residue monitoring protocols add parallel domestic barriers that concentrate pricing power among integrated operators with captive laboratory infrastructure.
Pricing Analysis
Industrial OEM buyers anchor contract pricing through direct farm partnerships that bypass wholesale margin extraction. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and traceability depth, with ASC-certified shrimp and EU-compliant marine fish capturing the top tier. Cost compression in standard-grade tilapia is intensifying because soybean meal price volatility feeds directly into aquafeed formulations. Northeast Brazilian retail channels exhibit highest price sensitivity due to wild capture substitution, while São Paulo foodservice buyers show lowest sensitivity when ASC or BAP documentation is embedded.
Supply Chain Analysis
Santos port congestion and container availability constraints on the Asia-South America trade lane elevate inbound logistics costs for Argentine and Chilean marine imports competing against domestic production. Geographic supply concentration centers on Brazil, Argentina, and Chile for the regional seafood trade balance, with Brazilian tilapia and shrimp exports flowing outbound while high-value marine species move inbound. Raw material dependencies rest on Brazilian soybean derivatives for aquafeed, imported fishmeal for marine diets, and veterinary inputs subject to ANVISA residue limits. Single-source vulnerability in IBAMA environmental licensing creates farm expansion bottlenecks. Distribution runs through direct farm-to-processor contracting for certified volumes, with cold-chain fragmentation limiting e-commerce penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's fisheries and aquaculture sector is positioned for cyclical recovery as soybean meal prices normalize from agricultural commodity peaks and intensive system adoption compresses per-unit production costs.
For Market Incumbents: Shield margin position by deepening backward integration into hatchery and feed mill operations to offset input cost volatility, while accelerating ASC certification timelines to defend against emerging Peruvian and Ecuadorian shrimp exporters capturing European supermarket shelf space. Prioritize captive laboratory investment for ANVISA residue compliance to maintain export eligibility as regulatory stringency intensifies. For New Entrants and Emerging Players: Traceability-as-a-service gaps in the Amazon basin frontier present white-space opportunity where incumbent operators under-serve due to Belém processing infrastructure limitations. Target Pará and Amazonas states for pond development with lower land acquisition costs versus Santa Catarina and Rio Grande do Sul. Pursue direct foodservice contracting with large restaurant chains seeking certified volumes outside traditional cooperative networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across recirculating aquaculture system deployments as modular unit economics improve and permit bypass advantages compound. Long-term viability favors operators with demonstrated IBAMA licensing navigation capability and embedded cold-chain infrastructure. Acquisition target archetype: mid-scale tilapia integrators with biofloc technology adoption and existing European export relationships. Signal to monitor: IBAMA permitting backlog resolution timelines as inflection indicator for greenfield expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Production | C.Vale-linked cooperatives secure soybean meal supply against agricultural commodity swings for member producers. |
| ASC Certification Acceleration | Shrimp exporters compress audit cycles to maintain European supermarket contracts under tightening procurement standards. |
| Modular RAS Deployment | Florianópolis-area operators circumvent IBAMA riparian setbacks while achieving production densities above 50 kg per cubic meter. |
| Direct Foodservice Contracting | Rio Grande do Sul tilapia cooperatives integrate harvest scheduling with chain restaurant demand forecasting for volume commitments. |
| Amazon Basin Frontier Expansion | Pará-based developers leverage underdeveloped freshwater resources with lower land costs versus southern state clusters. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with aquaculture farm managers, feed mill procurement leads, IBAMA licensing officers, and São Paulo foodservice buyers; and secondary validation through ANVISA regulatory filings, IBAMA environmental permit databases, EU IUU Regulation compliance records, and Brazilian customs trade statistics. Bottom-up farm-level production estimates and top-down consumption flow analysis were triangulated to reconcile supply-side capacity with demand-side channel absorption.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product type, farming method intensity tier, end-user channel, and distribution configuration. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Forecast inputs incorporated soybean meal price elasticity coefficients, IBAMA permit issuance velocity assumptions, and ASC certification adoption curves specific to Brazilian shrimp and tilapia operations.
Material uncertainties — IBAMA regulatory backlog duration, EU IUU enforcement intensity shifts, and veterinary input residue detection protocol revisions — sit outside the modeled envelope. Forecasts reflect assumptions about continued certification infrastructure investment and cold-chain reliability maintenance. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
South Korea Aquaculture Market
Aquaculture Innovations
United Arab Emirates Fisheries and Aquaculture Market
Aquaculture Innovations
Asia Pacific Aqua Feed Market
Aquaculture Innovations
Aquaculture Therapeutics Market
Aquaculture Innovations
North America Aqua Feed Market
Aquaculture Innovations
Shrimp Feed Market
Aquaculture Innovations
Japan Aquafeed Market
Aquaculture Innovations
Aquaculture Healthcare Market
Aquaculture Innovations
Aquaculture Feed and Pharmaceuticals Market
Aquaculture Innovations
North America Shrimp Market
Aquaculture Innovations
Mariculture Market
Aquaculture Innovations
China Shrimp Market
Aquaculture Innovations
United States Ornamental Fish Market
Aquaculture Innovations
GCC Fish Farming Market
Aquaculture Innovations
Aquaculture UAE in Market
Aquaculture Innovations
Aquaponics Market