
 Ghana Agriculture Market | 2026-2036
Ghana Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Ghana Agriculture Market Insights
Market Context
Input subscription bundles covering seeds, fertilizers, and extension advisories is restructuring how smallholders access productive assets across Ghana's agricultural landscape. Olam Agri leverages its coastal processing infrastructure to dominate sheanut and sesame value chains. Wienco sustains its position through integrated distribution of certified seeds and crop protection products. Agrocenta differentiates via its digital platform connecting farmers directly to wholesale buyers.
Technical Definition and Segment Structure
Ghana Agriculture encompasses crop cultivation, animal husbandry, and aquaculture production systems operating across tropical savanna and forest agro-ecological zones, with outputs ranging from raw commodities to semi-processed ingredients for industrial use. The sector functions as the primary domestic food security mechanism and a foreign exchange generator through cocoa, cashew, and vegetable exports. Crops occupies the dominant revenue position due to cocoa's entrenched export infrastructure, while Livestock is gaining structural importance as urban protein demand intensifies around Kumasi and Tamale. Food Processing channels command premium margin pools through traceability requirements from European importers.
Regulatory Environment and Outlook
Ghana's Ministry of Food and Agriculture enforces seed certification protocols through the national seed council, while the Ghana Standards Authority mandates pesticide residue thresholds for export-bound commodities. The Planting for Food and Jobs initiative redirects input subsidy flows toward mechanization and irrigation, tightening market access for uncertified agrochemical suppliers. Stakeholders must monitor how the Ghana Cocoa Board's living income differential enforcement reshapes farmer loyalty and processor procurement economics.
Market Dynamics
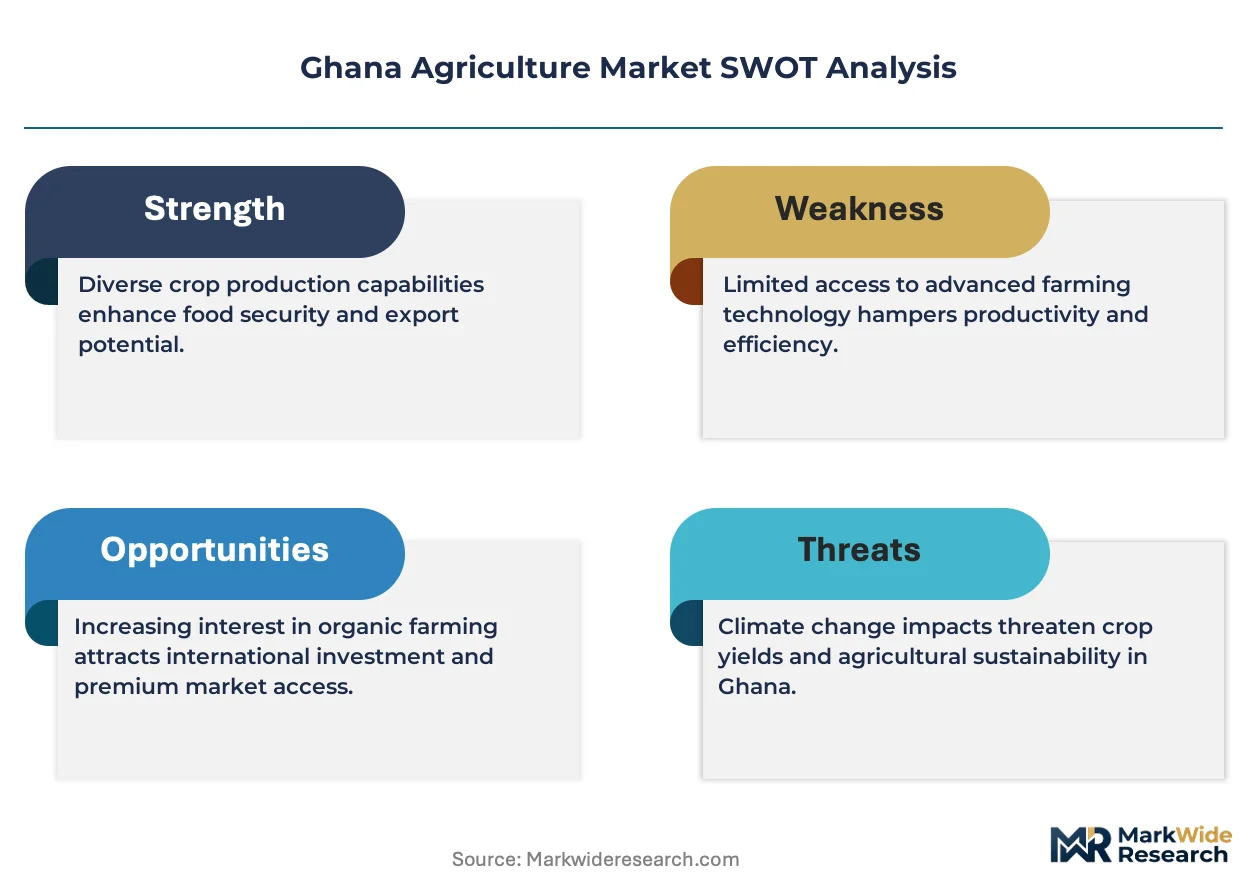
The Planting for Food and Jobs program is restructuring input subsidy flows toward mechanization and irrigation, tightening market access for uncertified suppliers while concentrating procurement power around Accra-Tema industrial corridors and northern savanna production zones.
Growth Catalysts
- Input Subscription Bundles:Integrated packages covering seeds, fertilizers, and extension advisories are restructuring how smallholders access productive assets across Ghana's agricultural landscape.
- Food Processing Expansion:Buyers in the maize and soybean value chains serving Accra-Tema industrial corridors are expanding offtake volumes as traceability requirements from European importers intensify.
- Mechanization Subsidies:The Ministry of Food and Agriculture's redirection of subsidy flows toward mechanization and irrigation is accelerating capital formation in the Northern Region.
Market Restraints
- Fertilizer Price Volatility:Import-dependent supply chains expose Ghanaian farmers to global urea and NPK price swings that compress working capital cycles.
- Seed Certification Bottlenecks:The national seed council's enforcement protocols create multi-season lag times for varietal approval, constraining yield improvement trajectories.
- Logistics Fragmentation:Road infrastructure gaps between northern production zones and coastal processing clusters inflate post-harvest losses and working capital requirements.
Strategic Opportunities
- Digital Platform Convergence:Mobile payment integration with farm management applications is opening direct wholesale buyer connections that bypass traditional aggregator layers.
- Export Traceability Premiums:The Ghana Standards Authority's pesticide residue thresholds for export-bound commodities create certified supply chain premiums for compliant operators.
- Urban Protein Demand:Kumasi and Tamale consumption clusters are intensifying demand for structured livestock value chains that integrate feed production with cold chain distribution.
Industry Challenges
- Extension Service Capacity:The ratio of agricultural extension officers to farm households in the Northern Region limits technology transfer velocity for improved seed varieties.
- Cold Chain Infrastructure Gaps:Perishable horticulture exports to European markets require capital-intensive refrigerated logistics that smallholder cooperatives struggle to finance.
- Living Income Differential Enforcement:The Ghana Cocoa Board's pricing mechanisms are reshaping farmer loyalty calculations and processor procurement economics in ways that strain contract stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ghana Agriculture Market |
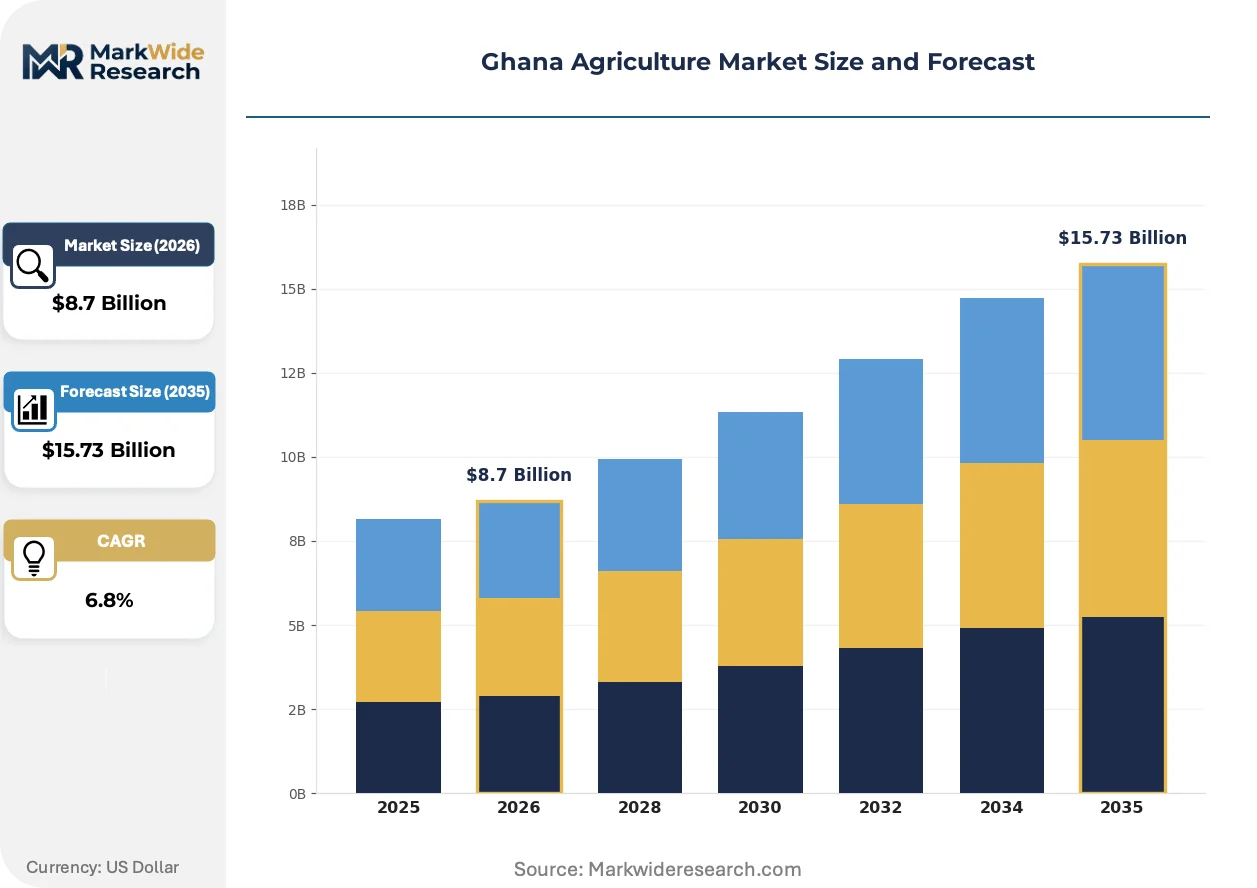
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crops, Livestock, Aquaculture, Agrochemicals End Use Industry: Food Processing, Export, Feed Production, Biofuel Distribution Channel: Direct Sales, Wholesale, Retail, Online Packaging Type: Bags, Bulk, Jars, Containers |
| Companies Covered | Complete Farmer, African Golden Food Ltd, Olam Agri, Wienco, Agricare, Louis Dreyfus Company, Wilmar International, Nestlé, Agrocenta, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ghana Agriculture Market Trends and Innovations
Digital infrastructure penetration is converging with input financing innovation to compress transaction layers between smallholders and wholesale buyers across Ghana's agricultural value chains.
Drone-based crop monitoring and variable-rate input application is overtaking manual scouting methods in medium-scale maize and soybean operations. Commercial farming enterprises near Tamale are adopting these systems to reduce labor costs and optimize fertilizer placement. The technology is enabling precision agriculture at sub-hectare resolution that was previously inaccessible outside estate farming structures.
The Ghana Standards Authority's pesticide residue thresholds for export-bound commodities are tightening compliance requirements across vegetable and sheanut value chains. Exporters to European markets must now maintain chain-of-custody documentation from farm gate to port. Smallholder cooperatives in the Northern Region are responding by consolidating into larger certification pools that share audit costs and traceability infrastructure.
Buyer concentration around Accra-Tema industrial corridors is compressing traditional aggregator margins as food processors establish direct contracting relationships with farmer groups. Maize and soybean value chains are witnessing the fastest displacement of spot market transactions by forward purchase agreements. This pattern is most visible in supply chains serving the brewing and animal feed manufacturing clusters along the Tema industrial axis.
Ghana Agriculture Market Segmentation
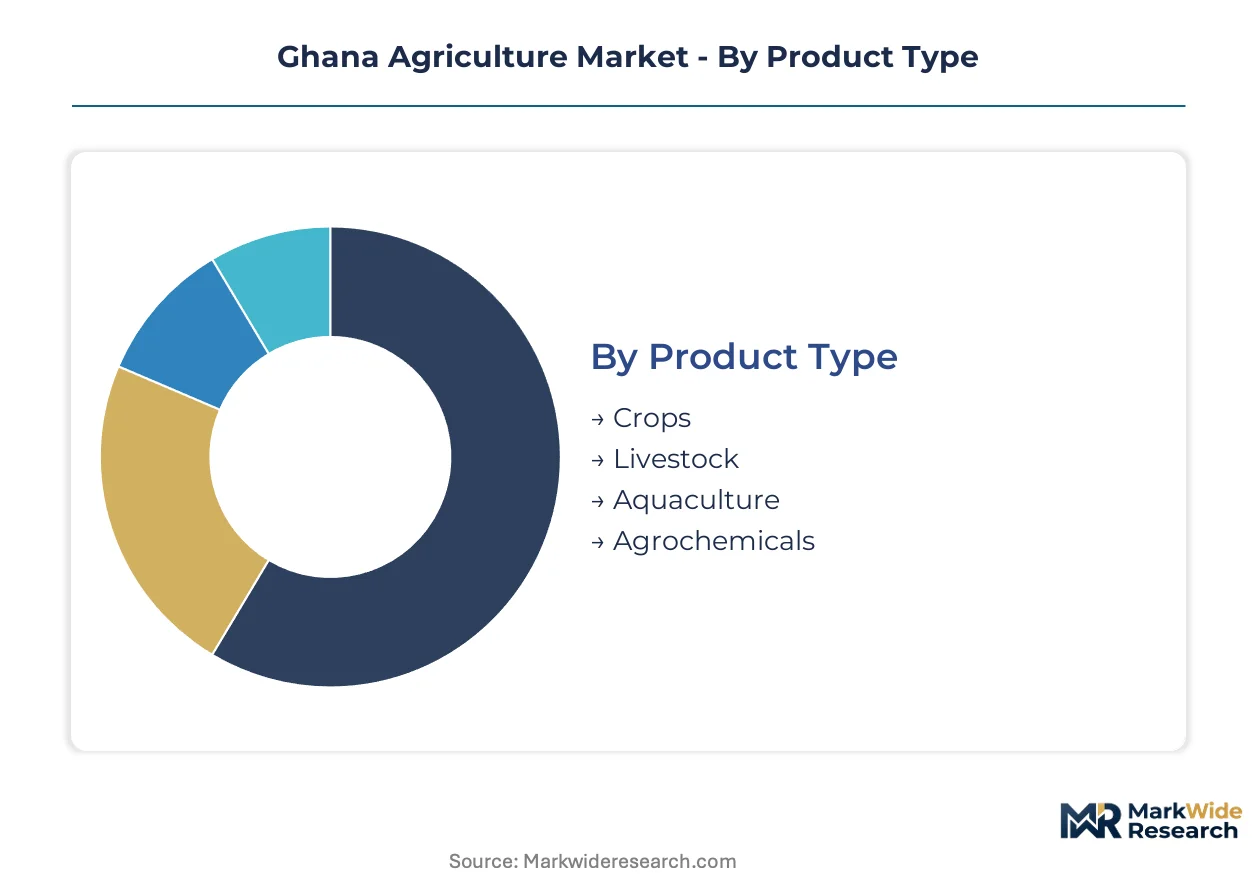
Segmentation in Ghana's agricultural landscape reveals how value capture differs across commodity types, buyer channels, and logistics configurations. Each dimension exposes distinct margin pools and capital requirements that shape competitive positioning for operators from smallholder cooperatives to coastal processors.
Product Type:
Standardized bulk commodities dominate volume flows, while specialized segments command traceability premiums and input-intensive cultivation protocols.
- Crops:Field cultivation of cereals, legumes, and tree crops across Ghana's forest-savanna transition zones. Cocoa, maize, and soybean value chains concentrate procurement power around the Ghana Cocoa Board and Accra-Tema industrial processors. The Planting for Food and Jobs program is redirecting subsidy flows toward mechanized cultivation in the Northern Region.
- Livestock:Ruminant and poultry production systems serving urban protein demand clusters around Kumasi and Tamale. Demand is intensifying for structured value chains integrating feed production with cold chain distribution as consumption shifts from informal slaughter to processed retail formats.
- Aquaculture:Pond and cage-based fish farming concentrated in Volta Region water bodies. Tilapia production scales through cooperative clusters accessing fingerling supply and formulated feed inputs.
- Agrochemicals:Crop protection products and fertilizers distributed through certified dealer networks under Ghana Standards Authority registration protocols. Import-dependent supply chains expose working capital cycles to global urea and NPK price volatility.
Most installed capacity flows through Crops. Expansion is steepest in Livestock as urban consumption patterns formalize.
End Use Industry:
Channel selection determines compliance burden and price realization, with export-facing segments carrying certification costs that domestic channels avoid.
- Food Processing:Industrial buyers in brewing, milling, and oil extraction serving Accra-Tema manufacturing corridors. Traceability requirements from European importers are tightening chain-of-custody documentation from farm gate to processor intake.
- Export:Cocoa, cashew, and vegetable shipments bound for European and Asian markets. The Ghana Standards Authority's pesticide residue thresholds create certified supply chain premiums for compliant operators consolidating into larger audit pools.
- Feed Production:Maize and soybean offtake for poultry and livestock compound manufacturing. Buyer concentration along the Tema industrial axis is displacing spot market transactions with forward purchase agreements.
- Biofuel:Jatropha and cassava feedstock channels for domestic ethanol blending programs. Policy support remains contingent on fuel pricing mechanisms and import substitution targets.
Revenue concentration sits with Food Processing. Certified Export channels are climbing the fastest as compliance infrastructure spreads through cooperative networks.
Distribution Channel:
Channel structure maps directly to working capital intensity, with direct and wholesale formats dominating value-dense commodities while retail fragmentation persists in peri-urban consumption zones.
- Direct Sales:Processor contracting with farmer groups and cooperative unions, bypassing traditional aggregator layers. Digital platform convergence through mobile payment integration is accelerating this channel's penetration in maize and soybean value chains.
- Wholesale:Aggregator-mediated bulk flows from northern production zones to coastal processing clusters. Road infrastructure gaps inflate post-harvest losses and compress margins for uncertified intermediaries.
- Retail:Market stall and shop-front sales of fresh produce and packaged inputs in urban and peri-urban centers. Fragmented logistics limit scale economies for perishable horticulture.
- Online:Digital marketplace transactions connecting smallholders to input suppliers and wholesale buyers. Agrocenta's platform exemplifies this channel's displacement of traditional dealer networks for certified seeds and crop protection products.
Transaction volume concentrates in Wholesale. Digital infrastructure investment is expanding Online most aggressively.
Packaging Type:
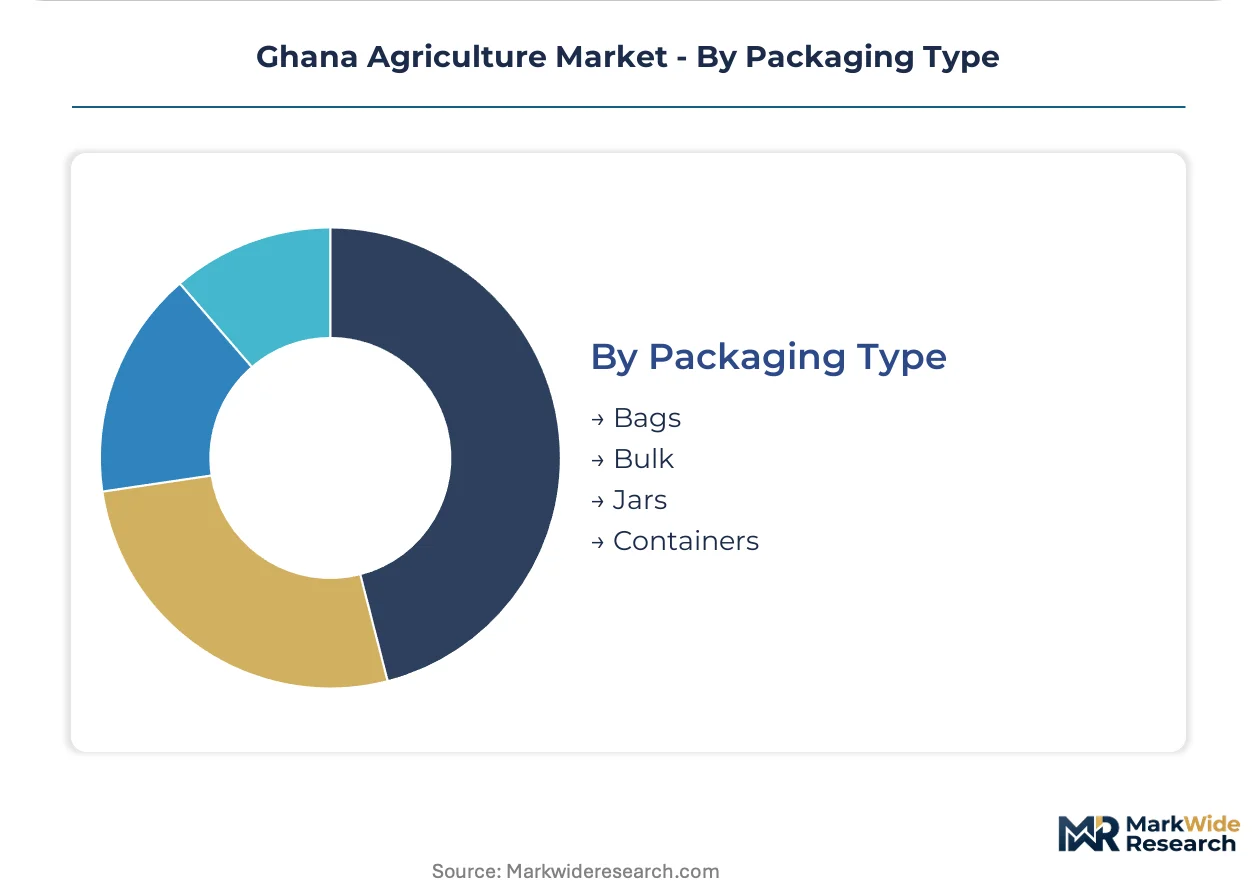
Packaging selection reflects transport distance, buyer specification, and shelf-life requirements across commodity categories.
- Bags:Woven polypropylene and jute sacks for grain, seed, and fertilizer handling. Standard unitization for road transport from northern savanna production zones to Accra-Tema corridors.
- Bulk:Loose-load shipment of cereals and oilseeds for industrial processing intake. Tanker and hopper configurations serve brewing and feed manufacturing clusters with minimal handling costs.
- Jars:Glass and plastic containers for honey, processed sheanut oil, and specialty condiments. Premium positioning for urban retail and export consignment channels.
- Containers:Refrigerated and ventilated units for perishable horticulture and aquaculture products. Capital-intensive cold chain infrastructure limits smallholder cooperative participation in export-bound vegetable segments.
Material throughput flows predominantly through Bags and Bulk. Containerized cold chain investment is gaining share fastest in vegetable export corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ivory Coast's cocoa sector expansion contrasts with Ghana's more regulated living income differential enforcement, while both West African neighbors face similar infrastructure constraints linking northern savanna production zones to coastal export corridors.
Ivory Coast
Cocoa bean demand from European chocolate manufacturers drives farmgate price competition with Ghana. The Conseil du Café-Cacao regulates export licensing and quality grading protocols. Abidjan and San-Pédro port clusters concentrate bean processing and shipping infrastructure for Asian and European markets.
Nigeria
Cassava and maize cultivation scales through mechanized farming cooperatives in the Middle Belt. The Central Bank of Nigeria's Anchor Borrowers Program channels input credit through commercial bank partnerships. Kano and Kaduna industrial corridors host flour milling and animal feed manufacturing clusters displacing informal grain traders.
Burkina Faso
Cotton and sesame exports to Asian textile and food oil processors sustain northern savanna farm incomes. The Société Burkinabè des Fibres Textiles enforces ginning standards and producer price floors. Bobo-Dioulasso logistics hubs connect Sahel production zones to Abidjan and Lomé port corridors.
Mali
Livestock transhumance routes from Inner Niger Delta pastures supply Bamako and Dakar urban protein markets. The Direction Nationale de l'Élevage monitors veterinary certification for cross-border cattle trade. Ségou and Mopti riverine zones concentrate rice irrigation schemes competing with imported Asian grain.
Togo
Phosphate fertilizer production at Kpémé mines reduces input cost exposure for regional cotton and maize growers. The Ministère de l'Agriculture coordinates seed certification with Ghana's national seed council for cross-border varietal approval. Lomé port infrastructure handles transshipment for landlocked Burkina Faso and Mali agricultural exports.
Ghana Agriculture Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated agribusiness conglomerates commanding cocoa and oilseed processing while digital platform operators capture input distribution margins. The vendor base organizes around three strategic archetypes: coastal processors with established export infrastructure, inland distributors controlling certified seed and agrochemical channels, and technology-enabled marketplaces collapsing transaction layers between smallholders and wholesale buyers. Competitive moves concentrate on backward integration into farming operations and strategic partnerships with Planting for Food and Jobs program implementers.
Among the integrated processor tier, Olam Agri and Wilmar International exemplify scale-driven operators leveraging coastal infrastructure for sheanut and sesame value chains. Wienco occupies a position within the input distribution archetype, while Agrocenta represents the digital platform convergence segment connecting farmers directly to buyers.
| Leading Market Players |
|---|
| Complete Farmer |
| African Golden Food Ltd |
| Olam Agri |
| Wienco |
| Agricare |
| Louis Dreyfus Company |
| Wilmar International |
| Nestlé |
| Agrocenta |
| Others |
Pricing and Supply Chain Analysis
Backward integration into seed multiplication and mechanization services anchors both supply security and margin control for operators across Ghana's agricultural landscape. The Planting for Food and Jobs program's subsidy redirection toward certified input bundles concentrates procurement leverage among integrated distributors while compressing spot-market margins for fragmented intermediaries.
Pricing Analysis
Capacity additions in the Northern Region are reshaping price floors for maize and soybean as mechanized farming cooperatives expand hectarage under cultivation. Three-tier pricing structure across premium, standard, and economy levels separates certified seed and traceable supply chains from informal market transactions. Cost compression in the economy tier is intensifying because uncertified agrochemical suppliers face tightened market access under Ghana Standards Authority enforcement. Smallholder cooperatives exhibit the highest price sensitivity, while food processors serving Accra-Tema industrial corridors prioritize traceability premiums over unit cost.
Supply Chain Analysis
Road freight costs between northern savanna production zones and coastal processing clusters inflate working capital requirements and compress margins for perishable horticulture. Supply draws from Ghana's Northern Region, Ivory Coast's cocoa belt, and Burkina Faso's cotton-growing Sahel zones for cross-border input and commodity flows. Working capital cycles rest on imported urea and NPK fertilizers, certified seed stock, and cold chain equipment. Single-source vulnerability runs through the Tema port corridor for export-bound cocoa and sheanut shipments. Distribution runs through wholesale aggregator networks consolidating smallholder output for industrial processor intake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ghana Agriculture functions as a late-cycle quality story where European importer traceability requirements are shifting procurement premiums toward certified supply chains. This demand pivot rewards operators with invested compliance infrastructure and penalizes fragmented spot-market players.
For Market Incumbents: Anchor backward integration into seed multiplication and mechanization services to defend margin position against digital platform disintermediation. Deepen captive supply relationships with Planting for Food and Jobs program implementers to secure subsidy-linked procurement volumes. Prioritize certification investment for Ghana Standards Authority compliance to capture export traceability premiums.
For New Entrants and Emerging Players: The Planting for Food and Jobs initiative in Ghana opens a window for digital platform operators to collapse transaction layers between northern smallholders and Accra-Tema wholesale buyers. Target underpenetrated livestock value chains around Kumasi and Tamale where cold chain infrastructure gaps limit incumbent scale. Deploy mobile payment-integrated farm management applications as the primary go-to-market mechanism.
For Investors and Strategic Acquirers: Roll-up economics work for regional input distributors because seed certification bottlenecks create multi-season lag times that favor scaled operators with regulatory relationships. Focus acquisition screening on mechanized farming cooperatives with planted hectarage expansion trajectories. Monitor Ghana Cocoa Board living income differential enforcement as the signal for contract stability and processor procurement economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Multiplication | Captures margin pools from certified varietal distribution under national seed council protocols. |
| Digital Platform Convergence | Agrocenta's mobile payment integration displaces traditional aggregator layers in input distribution. |
| Certification Infrastructure Investment | Chain-of-custody documentation satisfies Ghana Standards Authority thresholds for European export. |
| Mechanization Service Expansion | Planting for Food and Jobs subsidy redirection accelerates capital formation in the Northern Region. |
| Cold Chain Network Development | Refrigerated logistics unlock perishable horticulture export premiums previously inaccessible to smallholders. |
Research Methodology
Multiple input streams — primary stakeholder interviews, customs and trade records, and ministry policy documentation — were reconciled to construct this analysis. Conversations with agricultural extension officers, input distributor procurement leads, food processing plant managers, and cooperative union representatives supplied ground-level operating data. Secondary validation drew from Ghana Cocoa Board export statistics, Ghana Standards Authority regulatory filings, Planting for Food and Jobs program implementation reports, and West African trade corridor customs data. Bottom-up hectarage and yield estimates were triangulated against top-down commodity flow assessments.
Data-stream reconciliation across the projection horizon applied segment-specific growth drivers to derive volume and value trajectories. Segmentation dimensions modeled include product type, end-use industry, distribution channel, and packaging format alongside agro-ecological zone production clusters. CAGRs were computed from reconciled baseline estimates and scenario-weighted growth assumptions. Industry-specific forecast inputs incorporated cocoa living income differential enforcement patterns and mechanization subsidy uptake rates.
Revisions become necessary when fertilizer import price volatility, seed certification protocol changes, or cocoa board pricing mechanism shifts materialize beyond modeled assumptions. Forecasts reflect documented assumptions about subsidy continuity and European importer traceability requirement evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Asia Pacific Poultry Feed Market
Agriculture and Agri Products
Pure Plant Oil Market
Agriculture and Agri Products
Fish Feed Market
Agriculture and Agri Products
Marine Seaweed Market
Agriculture and Agri Products
Cut Flower Market
Agriculture and Agri Products
Malaysia Floriculture Market
Agriculture and Agri Products
Alfalfa Pellets Market
Agriculture and Agri Products
Italy Compound Feed Market
Agriculture and Agri Products
Centella Asiatica Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Organic Soymeal Market
Agriculture and Agri Products
Sugar Beet Market
Agriculture and Agri Products
Compound Horse Feedstuff Market
Agriculture and Agri Products
Thailand Compound Feed Market
Agriculture and Agri Products
Canada Ornamental Horticulture Market
Agriculture and Agri Products
Prunus Africana Market