
 China Shrimp Feed Market | 2026-2036
China Shrimp Feed Market Size, Share, and Industry Trends Forecast 2026-2036
China Shrimp Feed Market Intelligence
The gap between premium functional feeds and commodity bulk formulations is realigning procurement patterns across China's shrimp farming belt. Tongwei Co., Ltd. leverages its integrated aquaculture-feed platform to control input costs across Sichuan and Guangdong bases. Guangdong Haid Group anchors the southern market through specialized extruded feed lines optimized for high-density pond systems. Charoen Pokphand Foods competes via its Thai-Chinese supply corridor, sustaining traceability standards that differentiate its product in coastal dealer networks.
China shrimp feed denotes compounded aquaculture nutrition formulated with protein levels ranging from 35% to 45% and lipid content of 6% to 10%, manufactured through extrusion or pelleting processes to achieve water stability exceeding two hours for pond-based delivery. Extruded feed leads volume due to superior digestibility in intensive Penaeus vannamei operations, while soybean meal displaces fish meal as the dominant protein source amid import cost pressures and sustainability protocols. Pelleted feed occupies the economy tier serving semi-intensive farms in Jiangsu and Shandong, whereas liquid feed gains traction in hatchery applications where precise larval nutrition dictates survival rates.
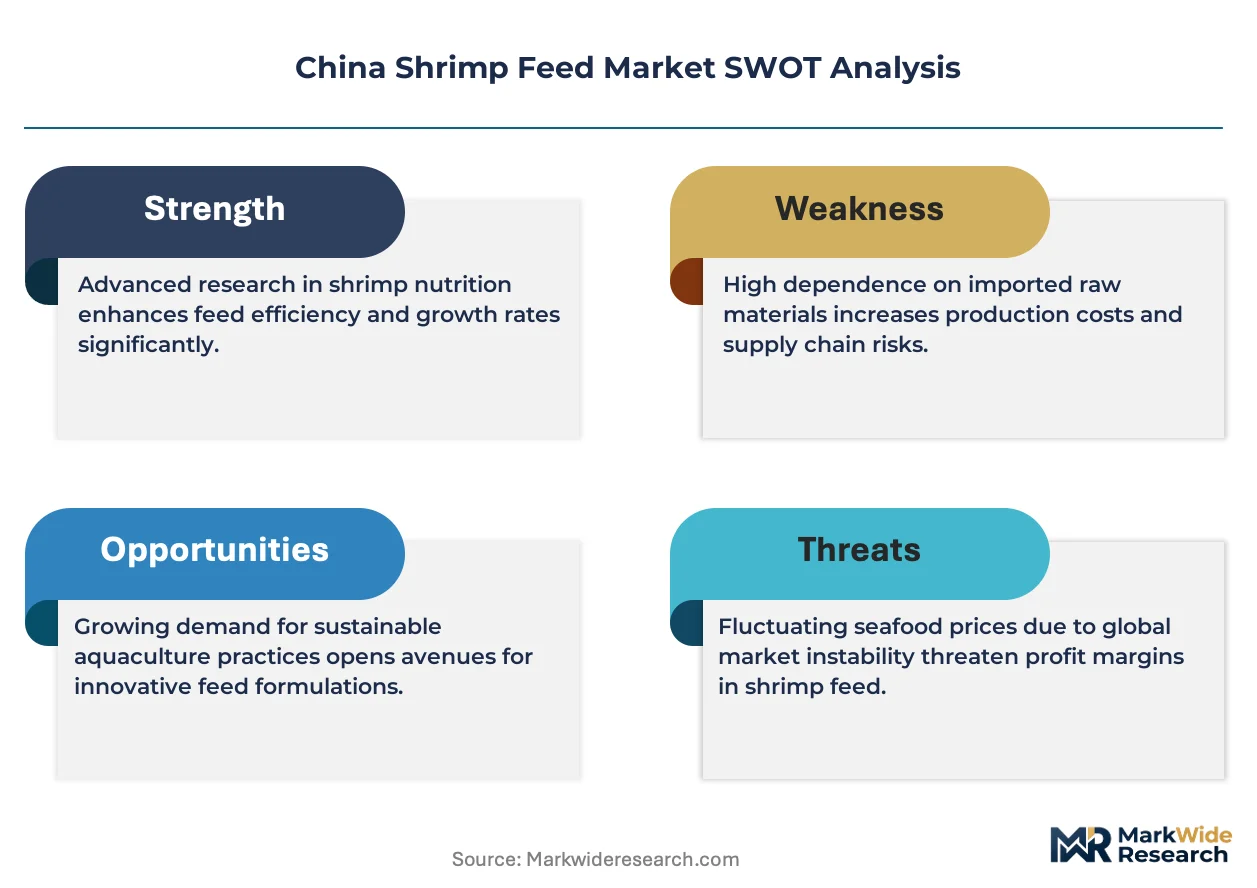
MEE enforces wastewater discharge standards that restrict unprocessed feed leachate from pond effluent, compelling mills to reformulate for lower nitrogen output. BIS-aligned GB standards for feed safety and MIIT directives on aquaculture mechanization jointly elevate barrier thresholds for new entrants lacking certified production lines. Stakeholders must monitor how China's carbon intensity targets reshape ingredient sourcing rules and whether southern province governments tighten carrying-capacity limits on coastal aquaculture zones.
Market Dynamics
MEE wastewater discharge standards are forcing feed mills to reformulate protein matrices, compressing nitrogen output while maintaining growth rates in intensive Penaeus vannamei ponds across Guangdong and Hainan.
Growth Catalysts
- Dual carbon goals:MIIT directives accelerate plant-protein substitution, redirecting procurement toward domestic soybean meal and corn gluten meal processors.
- Guangdong-Hainan coastal clusters:Intensive aquaculture zones concentrate demand for high-protein extruded feeds with water stability exceeding two hours.
- Extrusion technology maturation:Superior digestibility in high-density pond systems drives replacement of pelleted formulations across southern provinces.
Market Restraints
- Fish meal import cost volatility:Peruvian and Chilean supply fluctuations strain formulations still dependent on marine protein sources.
- GB standards compliance:BIS-aligned feed safety certifications require capital-intensive production line upgrades that exclude smaller regional mills.
- Pellet feed substitution:Economy-tier semi-intensive farms in Jiangsu and Shandong retain lower-margin demand that compresses blended portfolio returns.
Strategic Opportunities
- Liquid feed hatchery applications:Precise larval nutrition protocols in Zhanjiang and Beihai spawning facilities create premium formulation demand.
- MIIT aquaculture mechanization directives:Automated feeding systems integration opens channel partnerships with pond technology providers.
- Fujian province expansion:Underpenetrated coastal zones between established Guangdong and Zhejiang production belts offer greenfield dealer network establishment.
Industry Challenges
- Formulation biochemistry expertise:Shortage of nutritionists capable of balancing amino acid profiles under reduced nitrogen constraints limits mill technical capacity.
- Certification timeline compression:GB standard renewal cycles and MEE environmental audits create parallel compliance windows that strain quality assurance departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Shrimp Feed Market |
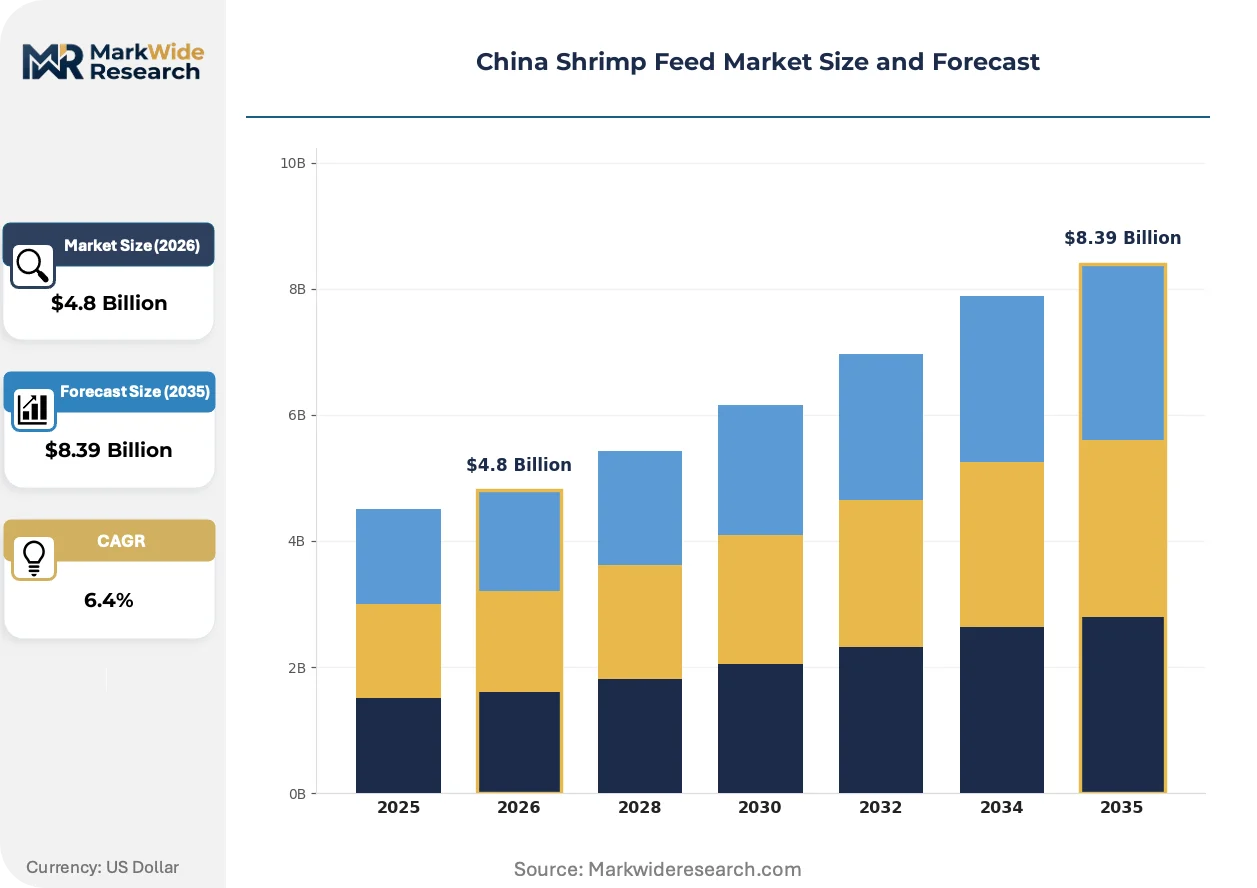
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extruded Feed, Pelleted Feed, Liquid Feed, Powdered Feed Ingredient: Fish Meal, Soybean Meal, Wheat Flour, Corn Gluten Meal Distribution Channel: Online Retail, Local Dealers, Supermarkets, Direct Sales End User: Aquaculture Farms, Research Institutions, Hatcheries, Coastal Communities |
| Companies Covered | Guangdong Haid Group, Tongwei Co., Ltd., Guangdong Hengxing Feed Industry Co., Ltd., Yuehai Feed Group, Aohua Group, Charoen Pokphand Foods, New Hope Liuhe Co., Ltd., Cargill Inc., Guangdong Yuehai Feeds Group Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Shrimp Feed Market Strategic Shifts & Innovations
Formulation chemistry and regulatory compliance are converging to reshape ingredient sourcing, processing technology, and farm-level delivery systems across China's southern shrimp belt.
Micro-encapsulated lipid technology is expanding into larval and nursery-stage feeds, protecting sensitive fatty acids from oxidation during pond immersion. Hatcheries in Zhanjiang and Beihai are adopting these formulations at accelerating rates to improve post-larval survival metrics. The technology is expanding into grow-out phase trials, potentially compressing the performance gap between premium and standard feed tiers.
MEE nitrogen discharge limits now enforce maximum unprocessed feed leachate thresholds in coastal aquaculture effluent. Mills must reformulate protein matrices or install wastewater pre-treatment systems at pond level. Guangdong-based intensive operations face the steepest compliance curves, with some facilities trialing in-pond biofloc systems to metabolize residual nutrients.
Dealer consolidation across the Pearl River Delta is compressing distribution layers, with larger aquaculture supply platforms absorbing independent county-level distributors. Direct mill-to-farm contracting is displacing traditional credit-extending intermediaries in Hainan. This restructuring is most visible in Leizhou Peninsula clusters, where feed manufacturers now operate captive technical service teams embedded at pond sites.
China Shrimp Feed Market Segmentation
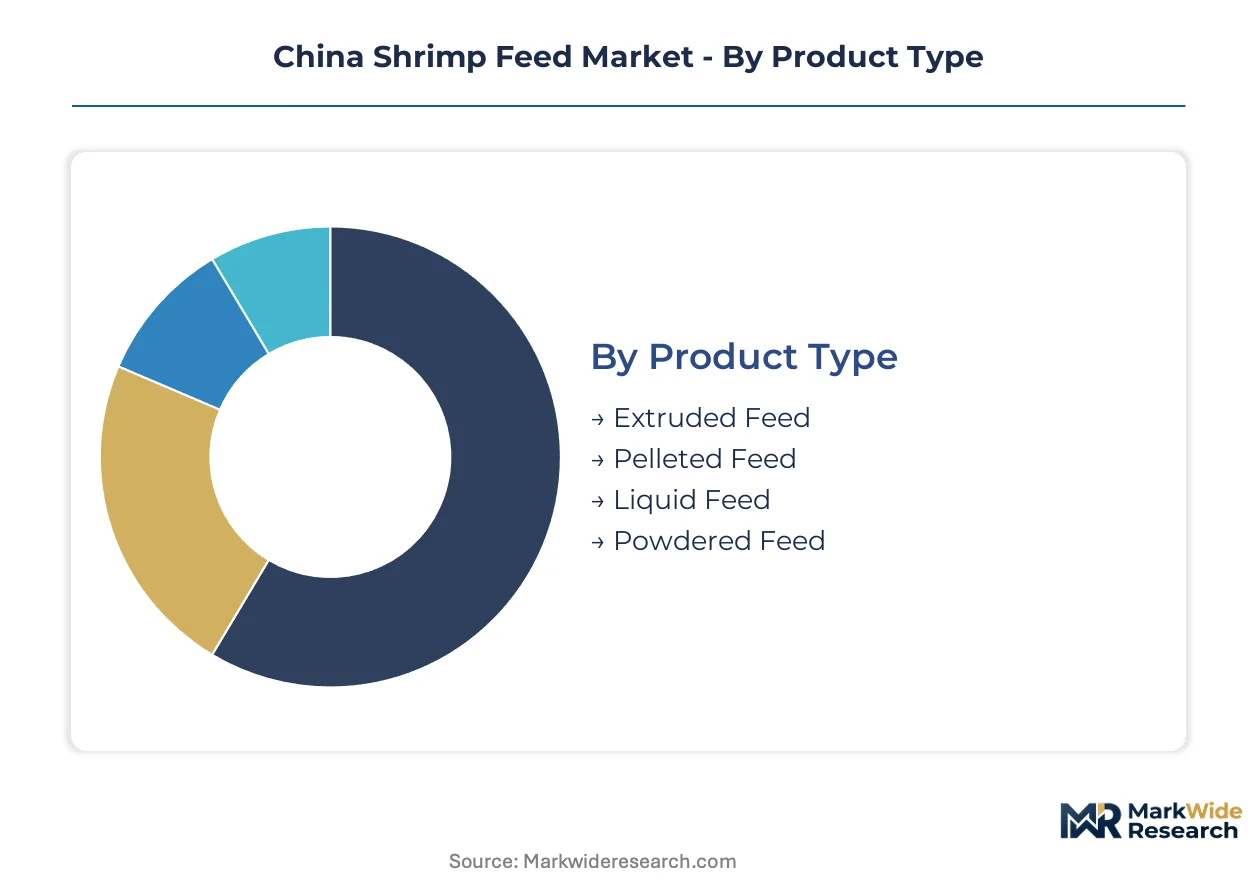
Feed form and ingredient sourcing dictate water stability, digestibility, and nitrogen discharge profiles across China's southern shrimp belt. Procurement channels and end-user specifications further fragment demand between intensive coastal operations and semi-intensive inland systems.
Product Type:
Customization intensity runs from precision-engineered extrusion lines to commodity pelleting, with liquid formulations representing the highest technical specification tier.
- Extruded Feed:High-temperature processing achieves protein levels of 35% to 45% with water stability exceeding two hours. Guangdong and Hainan intensive farms drive volume for Penaeus vannamei operations where digestibility directly correlates with feed conversion ratios under MIIT mechanization directives.
- Pelleted Feed:Compression-formed economy tier serves semi-intensive farms in Jiangsu and Shandong with lower capital requirements. Provincial feed safety audits under GB standards compress margins for mills lacking certified extrusion capacity.
- Liquid Feed:Suspended micronutrient solutions for larval stages in Zhanjiang hatcheries.
- Powdered Feed:Dried crumble formulations for nursery-phase transition stocking.
Leading the category by volume: Extruded Feed. Expanding most quickly: Liquid Feed.
Ingredient:
Protein source selection now pivots on import cost exposure versus domestic supply security under dual carbon compliance protocols.
- Soybean Meal:Domestic crushing capacity expansion displaces marine protein across Guangdong formulations. MEE nitrogen discharge limits accelerate adoption as plant-based matrices generate lower effluent loading than fish meal equivalents.
- Fish Meal:Peruvian and Chilean supply volatility constrains formulations still requiring complete amino acid profiles. Coastal dealers stock premium grades for high-density operations where growth rate premiums justify import cost exposure.
- Wheat Flour:Binder and carbohydrate source from domestic grain reserves.
- Corn Gluten Meal:Byproduct protein from ethanol processing with regional supply concentration in northeastern provinces.
Dominant by tonnage: Soybean Meal. Gaining share fastest: Corn Gluten Meal.
Distribution Channel:
Channel structure reflects credit extension needs versus technical service intensity across farm scale tiers.
- Local Dealers:County-level distributors with pond-side credit terms and seasonal inventory financing. Pearl River Delta consolidation is absorbing independent operators into larger aquaculture supply platforms with captive technical teams.
- Direct Sales:Mill-to-farm contracting eliminates intermediary margins for Hainan operations above 50 hectares. Leizhou Peninsula clusters demonstrate embedded service models where manufacturer staff monitor feeding protocols directly.
- Online Retail:E-procurement platforms for standardized formulations with transparent pricing.
- Supermarkets:Consumer-facing channels for hobbyist and ornamental shrimp segments.
Highest transaction volume: Local Dealers. Channel restructuring deepest: Direct Sales.
End User:
User sophistication spans from research-calibrated protocols to subsistence coastal operations with diverging specification requirements.
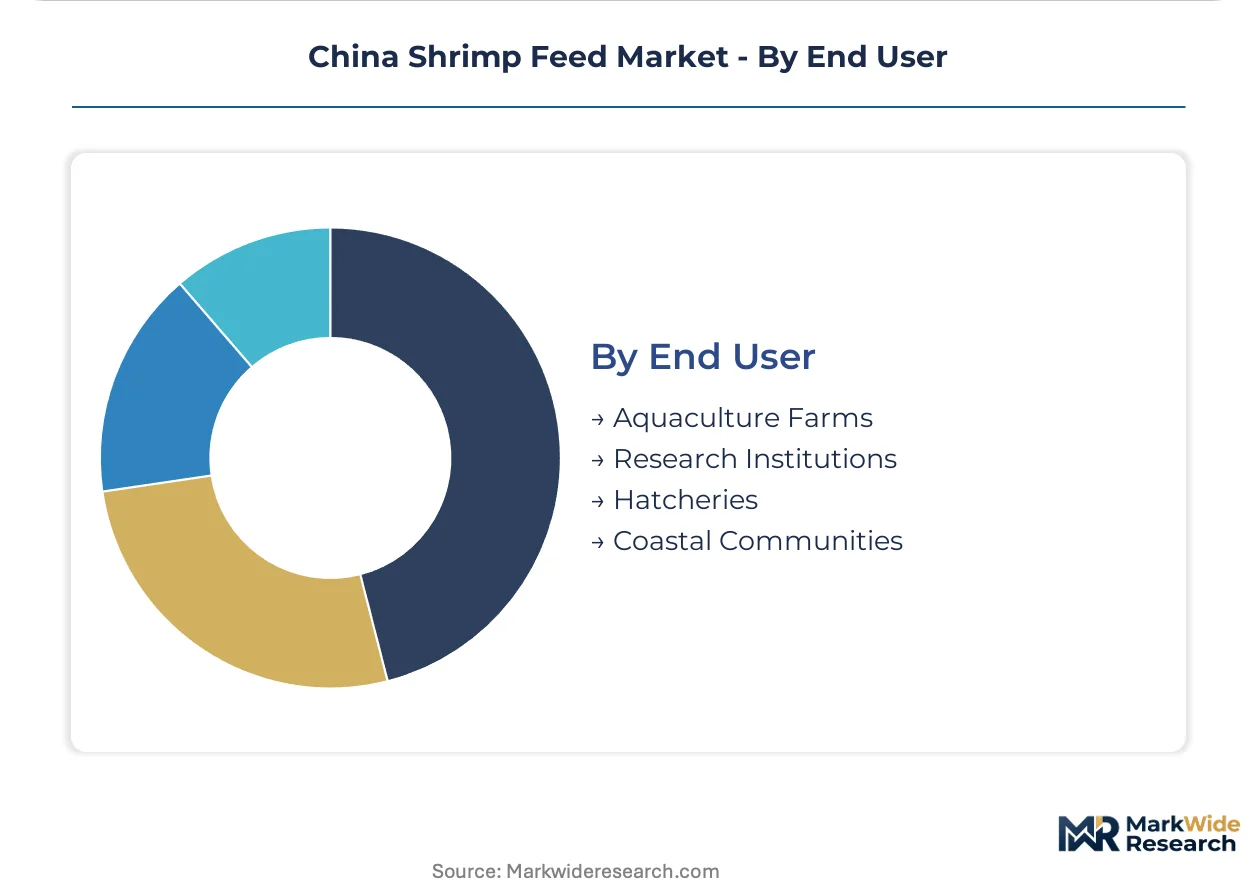
- Aquaculture Farms:Commercial operations across Guangdong, Hainan, and Fujian provinces purchasing bulk extruded and pelleted feeds. Farm scale determines whether procurement runs through dealer networks or direct mill contracts with technical service attachments.
- Hatcheries:Zhanjiang and Beihai spawning facilities requiring micro-encapsulated lipid technology for larval survival optimization. Precision nutrition protocols command premium formulation pricing with batch-specific quality certification.
- Research Institutions:Experimental diet development for breeding program support.
- Coastal Communities:Smallholder operations with seasonal production cycles.
Primary revenue source: Aquaculture Farms. Steepest specification escalation: Hatcheries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhanjiang anchors production gravity for formulated shrimp feeds across southern China's coastal aquaculture belt. Guangdong and Hainan provinces concentrate intensive Penaeus vannamei operations that drive procurement of high-protein extruded formulations. Provincial environmental regulators enforce divergent discharge standards that reshape mill location decisions and formulation chemistry.
Guangdong Province
Intensive pond clusters in Zhanjiang and Leizhou Peninsula consume bulk extruded feeds with protein levels above 40%. MEE wastewater discharge standards compel mills to reformulate nitrogen matrices or install pre-treatment systems at farm level. The Pearl River Delta dealer consolidation absorbs independent county-level distributors into larger aquaculture supply platforms with captive technical teams.
Hainan Province
Island aquaculture zones above 50 hectares increasingly bypass traditional credit-extending intermediaries through direct mill-to-farm contracting. Dual carbon goals under MIIT oversight accelerate substitution of imported fish meal with domestic soybean meal in coastal formulations. Lingao and Wenchang spawning facilities drive liquid feed demand for larval survival optimization protocols.
Fujian Province
Underpenetrated coastal zones between established Guangdong and Zhejiang production belts attract greenfield dealer network establishment. Provincial aquaculture bureaus promote standardized feed safety certifications that elevate barrier thresholds for new market entrants. Xiamen and Zhangzhou processing hubs concentrate extrusion capacity serving semi-intensive farms transitioning toward intensive systems.
Jiangsu Province
Economy-tier pelleted feed demand persists among semi-intensive operations with lower capital requirements and seasonal production cycles. GB standards compliance audits compress margins for mills lacking certified extrusion capacity or in-house quality assurance laboratories. Yancheng and Nantong coastal counties retain mixed procurement patterns splitting between local dealers and emerging direct sales channels.
Shandong Province
Northern shrimp farming belts exhibit slower feed form transition due to colder water temperatures and lower stocking densities. Provincial feed safety regulators align enforcement timelines with GB standard renewal cycles that strain smaller regional mills. Weihai and Qingdao aquaculture zones demonstrate procurement concentration toward established brands with demonstrated water stability performance in pond trials.
China Shrimp Feed Market Key Industry Players
Premium-margin players sit above commodity-margin players across formulation sophistication and technical service intensity. The vendor base organizes into three tiers: integrated aquaculture-feed platforms controlling input costs, specialized extrusion mills optimized for high-density pond systems, and diversified agribusiness conglomerates leveraging procurement scale. Strategic archetypes include captive supply chain operators, regional formulation specialists, and transnational nutrition companies. Competitive moves concentrate on dealer network consolidation and embedded technical service deployment at pond sites.
Within the integrated platform tier, Tongwei Co., Ltd. and Guangdong Haid Group exemplify archetypes combining feed manufacturing with captive aquaculture operations. Tongwei represents backward integration into input cost control across Sichuan and Guangdong production bases. Guangdong Haid anchors the southern market through specialized extrusion capacity serving high-density pond systems. Charoen Pokphand Foods occupies a position linking Thai-Chinese supply corridors with traceability differentiation in coastal dealer networks.
| Leading Market Players |
|---|
| Guangdong Haid Group |
| Tongwei Co., Ltd. |
| Guangdong Hengxing Feed Industry Co., Ltd. |
| Yuehai Feed Group |
| Aohua Group |
| Charoen Pokphand Foods |
| New Hope Liuhe Co., Ltd. |
| Cargill Inc. |
| Guangdong Yuehai Feeds Group Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Soybean meal import parity pricing cascades through Guangdong extrusion mills into three-tier feed economics, compressing margins at pelleted-formulation tiers while premium extruded lines absorb cost volatility through feed conversion ratio guarantees to intensive pond operators.
Pricing Analysis
Feed conversion ratio performance anchors value-based pricing contracts across southern China's intensive aquaculture zones. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein specification, water stability certification under GB standards, and embedded technical service intensity. Cost compression in pelleted tiers is intensifying because semi-intensive farms in Jiangsu and Shandong retain price-sensitive procurement patterns. Hatcheries demonstrate least price sensitivity due to larval survival rate premiums attached to micro-encapsulated formulations.
Supply Chain Analysis
GB standards certification gates mill participation in Guangdong and Hainan dealer networks, excluding uncertified regional processors from premium channel access. Soybean crushing capacity concentrates in domestic northeastern provinces and imported Brazilian supply corridors. Fish meal sourcing draws from Peruvian and Chilean fisheries with single-source vulnerability during El Niño disruption cycles. Distribution runs through consolidating Pearl River Delta aquaculture supply platforms absorbing independent county-level dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GB standards compliance timelines and MEE nitrogen discharge enforcement are accelerating exit pressure on sub-scale mills lacking certified extrusion capacity or in-house formulation expertise.
For Market Incumbents: Cement dealer network control through captive technical service teams embedded at Leizhou Peninsula pond sites. Acquire extrusion-capable regional mills in Fujian before provincial aquaculture bureaus tighten feed safety certification windows. MIIT mechanization directives threaten traditional credit-extending intermediaries; preempt channel displacement with direct contracting infrastructure for Hainan operations above 50 hectares. For New Entrants and Emerging Players: Mid-scale hatcheries in Zhanjiang and Beihai represent the most penetrable buyer archetype for liquid feed specialization. Fujian's underpenetrated coastal zones between established Guangdong and Zhejiang production belts offer greenfield dealer establishment with lower incumbent saturation. Lead with micro-encapsulated lipid technology partnerships spawning facilities seeking larval survival optimization protocols. For Investors and Strategic Acquirers: Charoen Pokphand Foods' Thai-Chinese supply corridor expansion pace is the leading indicator that traceability-differentiated feed platforms command acquisition premiums over commodity extrusion assets. Long-term viability centers on integrated aquaculture-feed platforms controlling input costs across multiple provincial bases. Watch for MIIT aquaculture mechanization directive implementation intensity as the signal for automated feeding system integration demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soybean Crushing | Domestic protein sourcing secures margin control against Peruvian fish meal volatility under MEE oversight. |
| Extrusion Capacity Expansion | GB-certified production lines capture share from pelleted-tier mills failing environmental audit compliance. |
| Hatchery Technical Partnership | Micro-encapsulated lipid co-development locks in premium formulation demand at Zhanjiang spawning facilities. |
| Direct Mill-to-Farm Contracting | Eliminates intermediary margins in Hainan while embedding service teams for feeding protocol optimization. |
| Fujian Dealer Network Establishment | Greenfield presence in coastal zones between Guangdong and Zhejiang production belts precedes incumbent saturation. |
Research Approach
Independent corroboration across feed mill operations directors, provincial aquaculture bureau regulators, and Pearl River Delta dealer network managers underwrites the qualitative findings. Secondary validation draws from MEE wastewater discharge filings, MIIT mechanization directive texts, GB standards certification databases, and customs trade records for soybean meal and fish meal imports. Bottom-up demand modeling from pond stocking density trends triangulates against top-down production capacity estimates from extrusion line counts across Guangdong, Hainan, and Fujian provinces.
Historical reference periods spanning pre-pandemic baseline through dual carbon policy implementation anchor the forecast window. Segmentation dimensions modeled include feed form tier, protein source composition, distribution channel structure, and farm scale intensity across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating feed conversion ratio improvement trajectories and provincial environmental carrying capacity constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MEE nitrogen discharge standard tightening, Peruvian fish meal supply disruptions, and MIIT aquaculture mechanization subsidy allocation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Global Plant Based Fish Feed Market
Aquaculture Innovations
United States Shrimp Market
Aquaculture Innovations
Thailand Aquafeed Market
Aquaculture Innovations
Seaweed Cultivation Market
Aquaculture Innovations
United Arab Emirates Fisheries and Aquaculture Market
Aquaculture Innovations
Salmon Feed Market
Aquaculture Innovations
South Korea Aquaculture Market
Aquaculture Innovations
Aquaculture Feed and Pharmaceuticals Market
Aquaculture Innovations
Egypt Aquafeed Market
Aquaculture Innovations
Oman Aquaculture Market
Aquaculture Innovations
Smart Aquaculture Systems Market
Aquaculture Innovations
Fish Breeding Tank Market
Aquaculture Innovations
Bahrain Fisheries and Aquaculture Market
Aquaculture Innovations
Sandfish Market
Aquaculture Innovations
Crab Market
Aquaculture Innovations
Aquaculture Therapeutics Market