
 Smart Farming Machine Market | 2026-2036
Smart Farming Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Farming Machine Market Insights
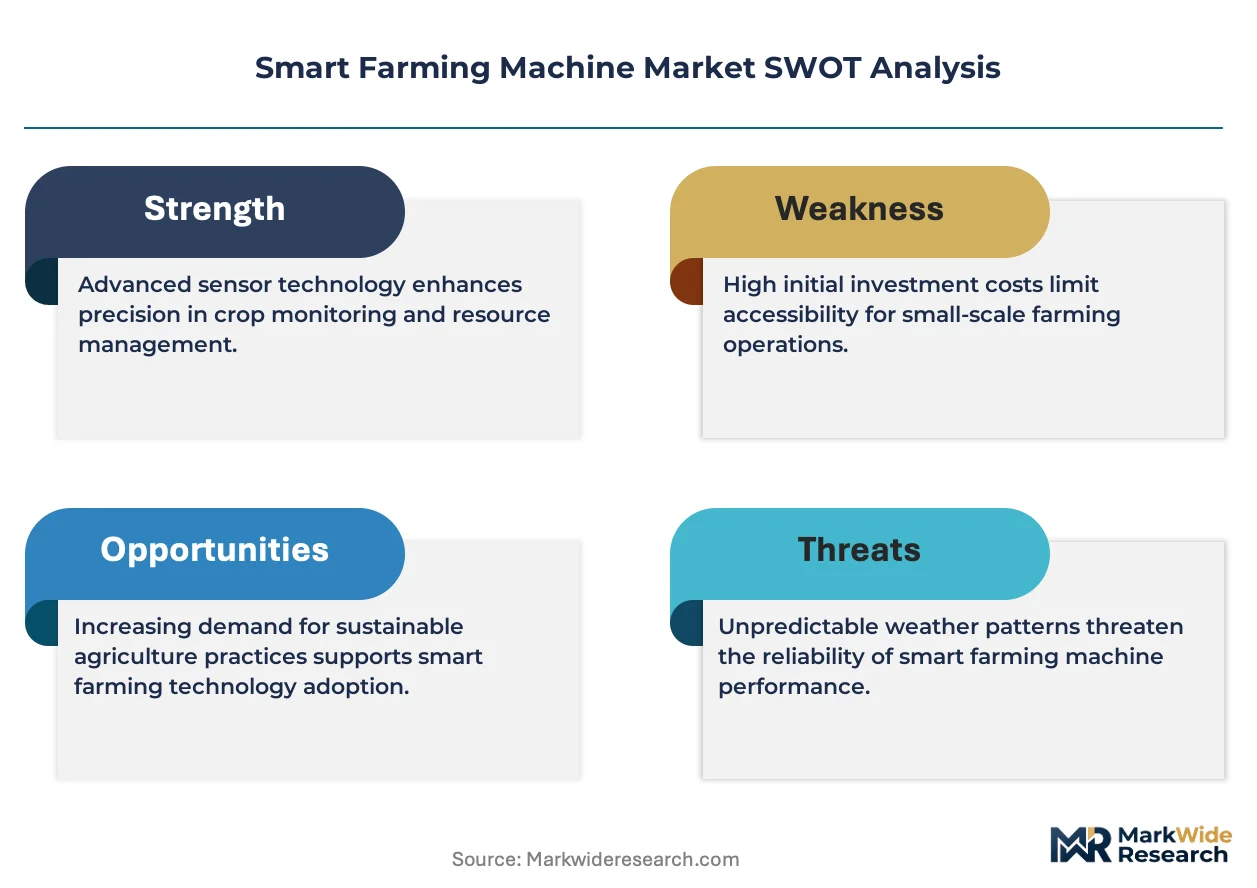
The EU Green Deal is recalibrating the cost-of-entry calculus for European equipment manufacturers, forcing compliance investments that favor scaled producers. Deere & Company leverages its integrated technology stack to sustain premium positioning across North American dealerships. AGCO Corporation anchors its competitiveness through specialized Fendt and Massey Ferguson brand architectures serving distinct farmer tiers. Kubota Corporation dominates compact tractor segments in Asian rice-cultivation markets with localized manufacturing footprints.
Smart farming machines integrate sensor arrays, GPS guidance, and autonomous control systems into mechanized equipment for precision agricultural operations, typically operating with sub-inch accuracy through real-time kinematic positioning and variable-rate application controllers. Their primary purpose is to optimize input efficiency—seed, fertilizer, chemicals, fuel—while reducing labor dependency across planting, cultivation, and harvest cycles. Tractors equipped with autosteering and implement control capture the largest installed base, though drones for crop monitoring represent the fastest-expanding technology segment as aerial imagery resolution improves and flight endurance extends. Robotics applications in selective harvesting and weeding concentrate margin pools where labor scarcity drives payback periods below three growing seasons.
The US EPA regulates off-road diesel emissions under Tier 4 Final standards, while the EU F-Gas Regulation governs refrigerants in climate-controlled cab systems; both frameworks elevate engineering costs but create compliance-based differentiation for established OEMs. India's CEA and BIS are developing indigenous smart equipment standards under the PLI scheme, reshaping market access rules for foreign suppliers. Stakeholders must monitor how fragmented national certification regimes evolve, as harmonization failures would fragment supply chains and force region-specific product architectures.
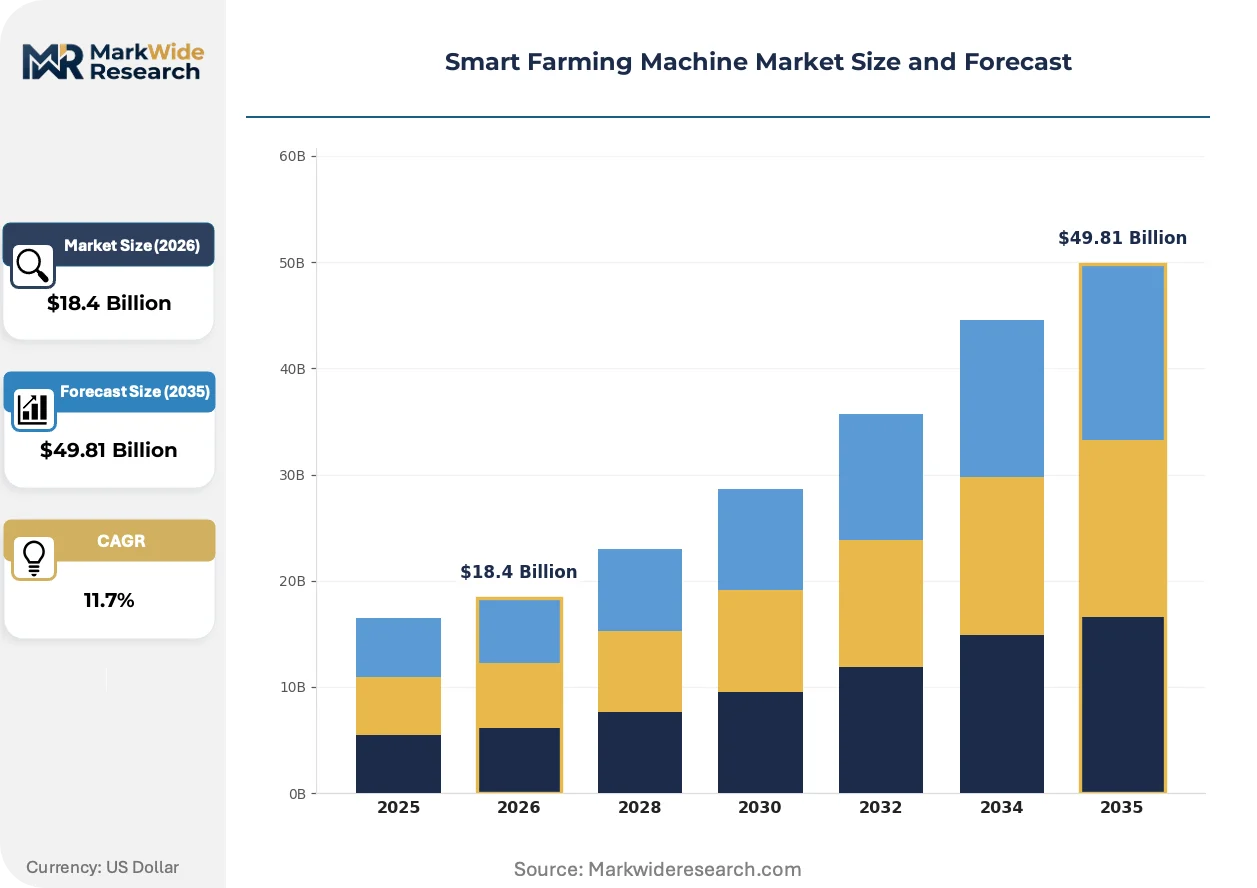
Market Dynamics
Autonomous control systems are compressing operator-to-machine ratios across row-crop operations, forcing OEMs to restructure dealer service models around predictive maintenance rather than reactive repair revenue.
Growth Catalysts
- US Corn Belt automation:Large-scale operations in Iowa and Illinois are replacing seasonal labor with autosteering tractors and implement control systems that operate 22-hour cycles.
- EU F-Gas Regulation:Mandatory refrigerant phase-downs in climate-controlled cabs are accelerating electric powertrain development for compliance-ready equipment portfolios.
- RTK positioning networks:Sub-inch accuracy guidance systems reduce seed and fertilizer overlap waste, delivering input cost savings that justify premium machinery pricing.
Market Restraints
- Lithium supply concentration:Battery pack sourcing depends on Chilean and Australian lithium carbonate supply chains vulnerable to export policy shifts.
- Tier 4 Final compliance costs:US EPA diesel after-treatment systems add $15,000-$25,000 per tractor unit, eroding margins on sub-100 horsepower segments.
- Technical service scarcity:Diagnostic capability for sensor-integrated hydraulics concentrates at dealership clusters, leaving remote farms with 72-hour repair windows.
Strategic Opportunities
- Mato Grosso precision expansion:Brazil's soybean belt lacks sufficient RTK base station density, creating infrastructure-as-a-service openings for equipment-linked correction signal subscriptions.
- Selective weeding robotics:Computer vision systems targeting herbicide-resistant weed patches capture margin pools where manual labor availability has collapsed.
- India PLI scheme:Domestic manufacturing incentives for precision agriculture equipment are reshaping market access rules for foreign OEMs seeking tariff advantages.
Industry Challenges
- Mechatronics technician shortage:Dealer networks struggle to recruit technicians capable of diagnosing CAN bus faults alongside hydraulic failures.
- ISO 11783 compatibility gaps:Proprietary implement control protocols fragment ISOBUS interoperability, forcing farmers into single-brand equipment stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Farming Machine Market |
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $49.81 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Drones, Harvesters, Planters Technology: IoT, AI, Robotics, Automation Application: Crop Monitoring, Soil Management, Pest Control, Yield Prediction End User: Farmers, Agricultural Cooperatives, Agronomists, Research Institutions |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial N.V., Kubota Corporation, Trimble Inc., Raven Industries, Topcon Corporation, Mahindra & Mahindra Limited, Claas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Farming Machine Market Trends and Innovations
Edge computing architectures are relocating data processing from cloud servers to machine-mounted units, cutting latency for real-time planting and spraying decisions while reducing cellular connectivity dependency in remote fields.
Multi-spectral imaging is converging with drone flight control systems to generate prescription maps for variable-rate nitrogen application. Agronomy cooperatives in Nebraska and Kansas are deploying fleet-scale UAV operations that feed imagery directly into planter controllers. This convergence is compressing the feedback loop between crop stress detection and corrective input application from weeks to hours.
The EU AI Act's risk classification framework is imposing conformity assessment requirements on autonomous navigation systems that make real-time path-planning decisions without human intervention. Machinery OEMs must now document algorithmic transparency and fail-safe protocols for equipment operating above 6 km/h in populated areas. German and Dutch manufacturers are responding by segregating AI-enabled product lines into separate legal entities to isolate liability exposure.
Farmer buying committees are consolidating equipment procurement across multi-site operations, displacing individual dealership relationships with enterprise-scale vendor management office structures. Input suppliers and grain elevators are capturing machinery specification influence through bundled financing programs. This concentration is most visible in Saskatchewan and Alberta, where 5,000-hectare operations now negotiate three-year fleet replacement cycles with direct manufacturer engagement rather than dealer intermediation.
Smart Farming Machine Market Segmentation
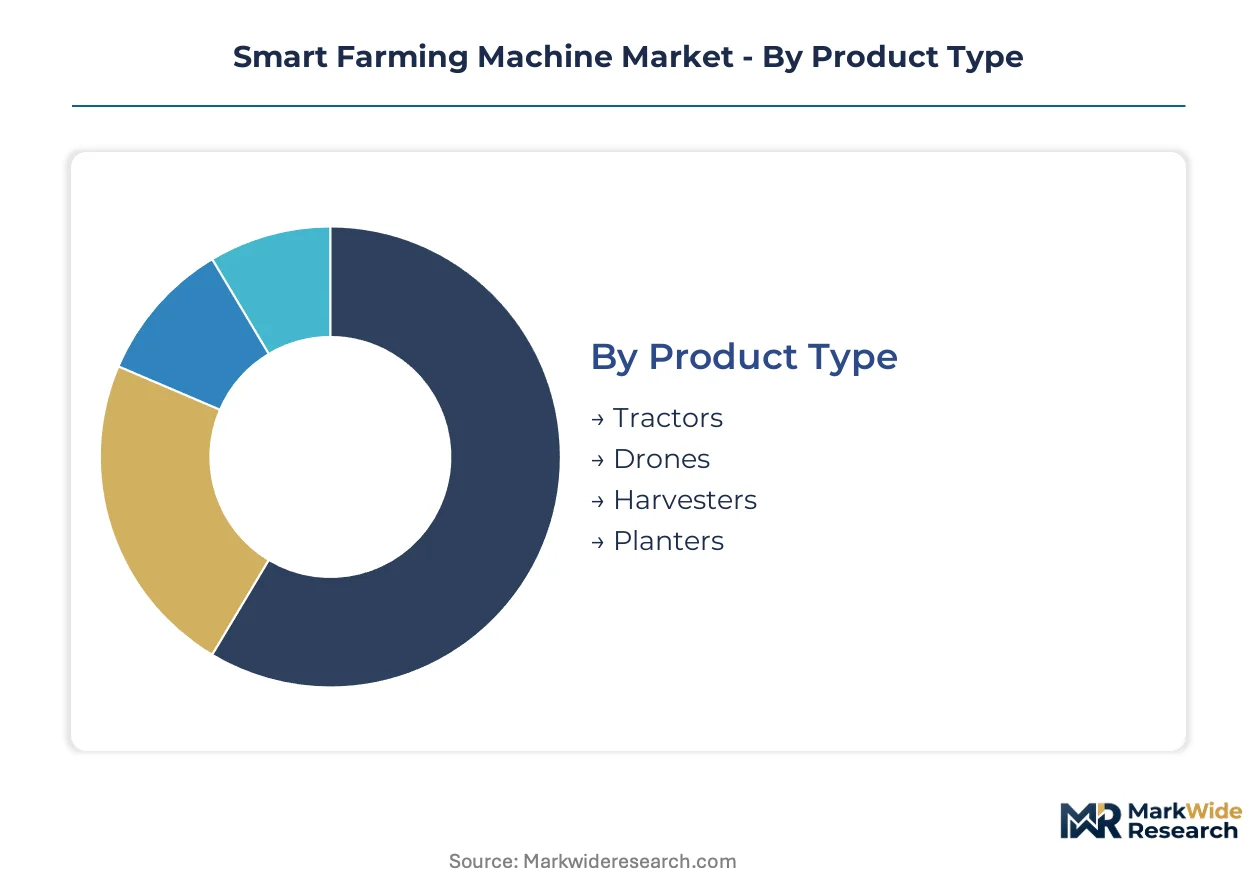
Segmentation in smart farming machines reveals how precision agriculture technology diffuses across equipment categories, operational scales, and agronomic functions. Equipment manufacturers calibrate feature bundles and price positioning to match the technical sophistication and capital intensity each segment demands.
Product Type:
The customization-standardization spectrum spans from configurable tractor platforms with modular implement interfaces to purpose-built autonomous harvesters with fixed mechanical architectures.
- Tractors:Autosteering-capable platforms with ISOBUS implement control dominate capital deployment across row-crop operations. Iowa and Illinois grain producers prioritize 300+ horsepower units with RTK guidance for 22-hour planting cycles.
- Drones:Multi-rotor and fixed-wing UAVs carrying multi-spectral cameras generate prescription maps for variable-rate nitrogen application. Nebraska agronomy cooperatives deploy fleet-scale operations feeding imagery directly into planter controllers.
- Harvesters:Self-propelled combines with yield monitoring and moisture sensing capture margin pools where harvest timing determines grain quality premiums.
- Planters:Precision seeding equipment with electric drive meters and section control reduces seed overlap waste in irregular field geometries.
Most installed capacity flows through tractors. Expansion is steepest in drones.
Technology:
Cost tier differentiation separates sensor-integrated entry systems from fully autonomous platforms requiring substantial R&D amortization.
- IoT:Connected sensor networks transmitting soil moisture, equipment telemetry, and weather data to cloud dashboards. Brazilian Mato Grosso soybean operations leverage cellular-enabled probes for irrigation scheduling decisions.
- AI:Machine learning models processing aerial imagery for weed detection and crop stress classification. The EU AI Act imposes conformity assessments on autonomous navigation systems making real-time path-planning decisions above 6 km/h.
- Robotics:Computer vision-guided selective weeding and harvesting systems target labor-scarce specialty crop segments.
- Automation:Programmable logic controllers executing pre-defined operational sequences without adaptive decision-making capabilities.
Highest unit volumes concentrate in IoT-enabled equipment. AI represents the fastest-growing trajectory as regulatory frameworks mature.
Application:
Volume-maturity alignment positions crop monitoring as the established use case while yield prediction remains nascent due to data integration complexity.
- Crop Monitoring:Continuous field observation through satellite, drone, and ground-based sensors detecting nutrient deficiencies and irrigation stress. Kansas wheat producers subscribe to imagery services updating prescription maps weekly during growing season.
- Soil Management:Variable-rate lime and fertilizer application guided by electrical conductivity mapping and grid sampling protocols.
- Pest Control:Targeted pesticide deployment triggered by pheromone trap counts and drone-scouted infestation hotspots.
- Yield Prediction:Machine learning models combining weather data, satellite indices, and historical performance to forecast harvest volumes for grain marketing decisions.
Farmer adoption concentrates in crop monitoring. Yield prediction is gaining share fastest as data pipeline integration improves.
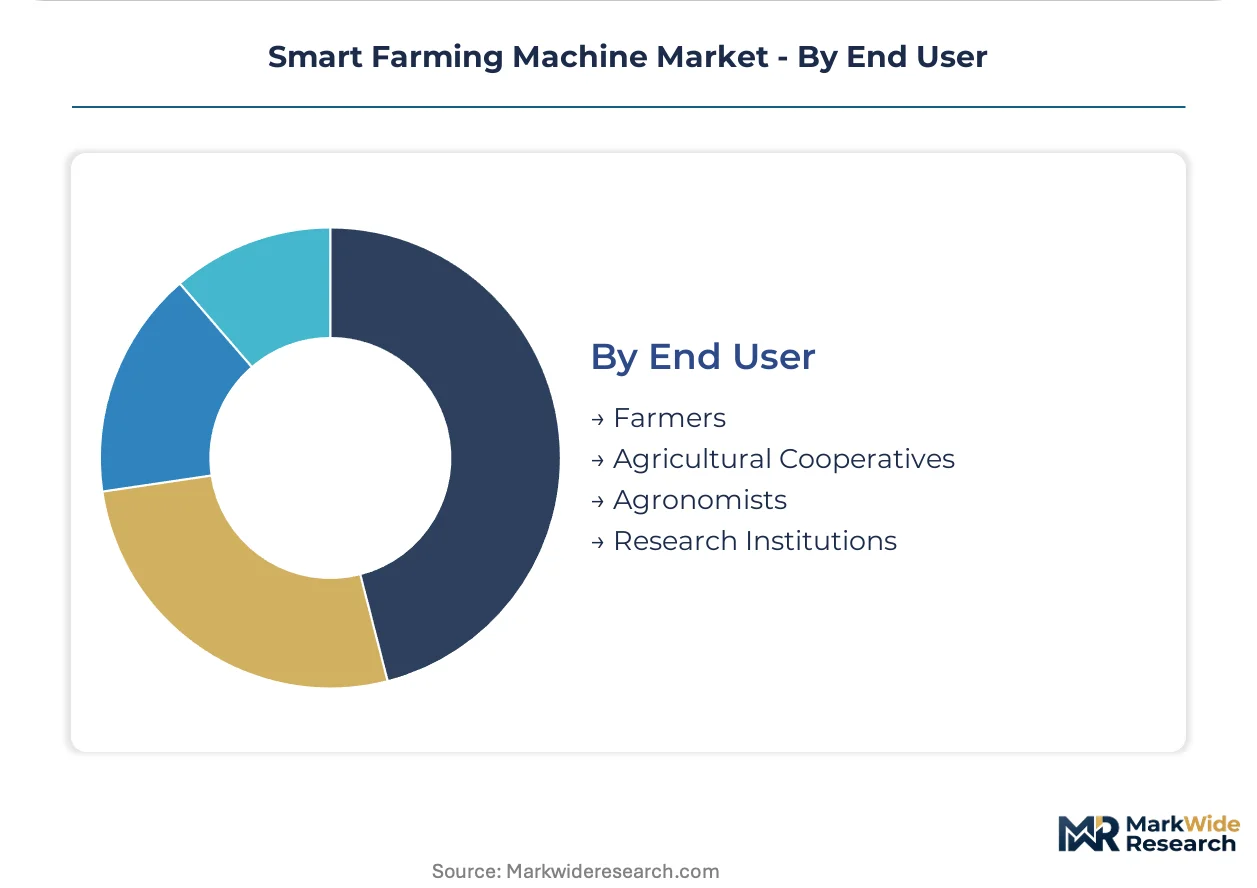
End User:
Customer type segmentation separates individual capital deployment from collective procurement structures reshaping manufacturer engagement models.
- Farmers:Owner-operators making equipment decisions based on payback period calculations against input cost savings and labor reduction. Saskatchewan and Alberta 5,000-hectare operations now negotiate three-year fleet replacement cycles with direct manufacturer engagement.
- Agricultural Cooperatives:Member-owned enterprises pooling machinery investment across multiple sites to capture scale discounts and specialized technical staffing.
- Agronomists:Crop consultants specifying precision equipment for client farms and interpreting sensor data to optimize input recommendations.
- Research Institutions:Universities and government experiment stations validating emerging technologies before commercial transfer to production agriculture.
Equipment revenue flows predominantly through farmers. Cooperative procurement is climbing the fastest as buying committees consolidate multi-site operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Germany's precision manufacturing belt and Iowa's agricultural engineering corridor anchor smart farming machine development. Equipment demand concentrates where large-scale row-crop operations intersect with tightening emissions regulations.
United States
Iowa and Illinois grain producers deploy 300+ horsepower autosteering tractors for 22-hour planting cycles. The EPA enforces Tier 4 Final diesel after-treatment standards that add $15,000-$25,000 per tractor unit. Nebraska agronomy cooperatives operate fleet-scale drone services feeding multi-spectral imagery directly into planter controllers.
Brazil
Mato Grosso soybean belt operations lack sufficient RTK base station density, creating infrastructure-as-a-service demand for correction signal subscriptions. ANVISA coordinates with agricultural regulators on equipment import certification. São Paulo-based machinery distributors are expanding precision agriculture rental fleets to capture mid-size farmer segments.
Germany
Fendt and Claas anchor premium tractor manufacturing in Baden-Württemberg and Lower Saxony. The EU AI Act imposes conformity assessments on autonomous navigation systems operating above 6 km/h. Bavarian manufacturers are segregating AI-enabled product lines into separate legal entities to isolate liability exposure.
India
Maharashtra and Gujarat tractor markets prioritize compact platforms for rice-cultivation smallholdings. The CEA and BIS develop indigenous smart equipment standards under the PLI scheme for domestic manufacturing incentives. Karnataka precision agriculture startups partner with state agricultural universities on sensor-integrated implement validation.
Japan
Kubota dominates compact tractor segments with localized manufacturing footprints serving Asian rice markets. METI coordinates agricultural robotics R&D consortia targeting labor-scarce specialty crop harvesting. Nagoya-area component suppliers specialize in hydraulic-electric hybrid actuation systems for precision implements.
Smart Farming Machine Market Competitive Landscape
The competitive structure tilts toward integrated technology stacks rather than pure equipment manufacturing. Deere & Company and AGCO Corporation anchor the premium tier through proprietary guidance and implement control ecosystems. Mid-scale specialists concentrate in regional tractor markets with localized service networks. Dominant competitive moves include strategic partnerships for RTK correction signal infrastructure and portfolio diversification into drone-based crop monitoring services.
Among North American equipment manufacturers, Deere & Company exemplifies the integrated technology archetype through its precision agriculture platform spanning autosteering, variable-rate application, and fleet management software. AGCO Corporation occupies a multi-brand position with Fendt and Massey Ferguson serving distinct farmer capital tiers. Kubota Corporation anchors the compact equipment segment across Asian rice-cultivation markets.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial N.V. |
| Kubota Corporation |
| Trimble Inc. |
| Raven Industries |
| Topcon Corporation |
| Mahindra & Mahindra Limited |
| Claas |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate feedstock from Chilean and Australian spodumene operations flows through three distinct pricing tiers before reaching farm equipment OEMs, with battery pack costs concentrating premium positioning in autonomous tractor segments while Tier 4 Final compliance expenses compress margins on sub-100 horsepower units.
Pricing Analysis
The bundled-vs-unbundled service split separates hardware-only transactions from subscription-linked precision agriculture packages. Three-tier pricing structure across premium, standard, and economy levels tracks RTK correction signal inclusion and predictive maintenance bundling. Cost compression in compact tractor segments is intensifying because Indian PLI scheme incentives enable domestic manufacturers to undercut import pricing. Smallholder rice-cultivation operations in Asia demonstrate highest price sensitivity, while North American row-crop enterprises prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Single-source vulnerability sits with Chilean lithium carbonate processors and Taiwanese semiconductor foundries serving CAN bus controller fabrication. Raw material sourcing draws from Australian spodumene mines, Chinese rare earth refineries, and German precision hydraulic component manufacturers. Tariff exposure concentrates in battery cell imports subject to evolving trade policy between major manufacturing blocs. Distribution runs through authorized dealership networks with captive parts warehousing, though direct-to-fleet procurement from large-scale cooperatives is displacing traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Farming Machine Market functions as a stable compounder anchored by irreversible labor scarcity across major grain-producing regions, ensuring sustained equipment replacement cycles regardless of commodity price cyclicality.
For Market Incumbents: Hedge proprietary protocol exposure by accelerating ISOBUS interoperability investments before regulatory mandates fragment equipment stacks. Secure captive lithium supply through offtake agreements with Australian and Chilean producers to defend margin position against battery cost volatility. Dealer network consolidation in the US Corn Belt remains essential as buying committees displace individual procurement relationships.
For New Entrants and Emerging Players: Direct-to-farmer digital channels bypass established dealership gatekeepers in Brazil's Mato Grosso soybean belt, where RTK infrastructure-as-a-service gaps create immediate white-space opportunity. Target mid-scale operations with precision agriculture rental fleets rather than capital sales. Agronomy cooperative partnerships provide the most penetrable entry vector for sensor-integrated implement validation.
For Investors and Strategic Acquirers: Roll-up economics work for regional precision agriculture service providers because fragmented RTK base station ownership prevents single-vendor market capture. Five-to-ten year viability rests on autonomous navigation regulatory harmonization rather than technology maturation. Monitor EU AI Act conformity assessment timelines as the critical inflection signal for liability-capable autonomous equipment deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| RTK Infrastructure Partnership | Correction signal density gaps in Brazil and India create first-mover subscription revenue pools. |
| Autonomous Navigation Certification | EU AI Act compliance investments isolate liability exposure and accelerate market access. |
| Battery Supply Agreement | Lithium carbonate offtakes from Chilean and Australian sources secure cost predictability. |
| Dealer Service Model Restructuring | Predictive maintenance capabilities replace reactive repair revenue as operator-to-machine ratios compress. |
| ISOBUS Protocol Standardization | Interoperability investments preempt regulatory fragmentation and preserve multi-brand fleet flexibility. |
Research Methodology
Coverage spans North America, South America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with precision agriculture directors at major equipment OEMs, agronomy cooperative procurement leads, and dealership service operations managers. Secondary validation draws from EPA Tier 4 Final filings, EU F-Gas Regulation implementation guidance, ANVISA equipment import certifications, and Indian PLI scheme administrative records. Bottom-up equipment shipment estimates triangulate against top-down agricultural mechanization expenditure data.
Granularity-level modeling separates tractor horsepower tiers, drone payload categories, and autonomous navigation capability levels across the projection horizon. Segmentation dimensions include product architecture, technology integration depth, agronomic application, and customer procurement structure. CAGRs derive from equipment replacement cycle analysis, input cost savings quantification, and labor substitution economics. Forecast inputs incorporate RTK network deployment timelines, battery cost curves, and regulatory compliance phase-in schedules.
The model assumes a particular technology adoption path; alternative pathways for fully autonomous navigation without operator supervision would alter the outlook. Forecasts reflect assumptions regarding lithium supply chain stability, emissions regulation harmonization, and technician training pipeline adequacy. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Smart Harvest Market
Smart Agriculture
Europe Agrivoltaics Market
Smart Agriculture
Smart Farm Management Software Market
Smart Agriculture
Digital Agriculture Infrastructure Market
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
Smart Livestock Farming Market
Smart Agriculture
Global AI in Agriculture Market
Smart Agriculture
Connected Agriculture Market
Smart Agriculture
Global IoT in Agriculture Market
Smart Agriculture
Smart Farming Market
Smart Agriculture
Asia-Pacific Smart Agriculture Market
Smart Agriculture
Smart Cattle Market
Smart Agriculture
Qatar Agriculture Market
Smart Agriculture
Smart Irrigation Market
Smart Agriculture
Fertigation Monitoring Market
Smart Agriculture
Smart Tractor Market