
 Public Cloud Market | 2026-2036
Public Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Public Cloud Market Intelligence
Subscription-based software-defined networking is consolidating around recurring revenue models that bundle compute, storage, and managed security into unified contracts. Amazon Web Services (AWS) leverages its first-mover infrastructure footprint across availability zones to sustain pricing power in raw compute cycles. Microsoft Azure anchors enterprise loyalty through deep integration with productivity software and hybrid cloud orchestration tools. Google Cloud Platform differentiates its positioning with custom tensor processing units and data analytics engines optimized for machine learning workloads.
Public cloud denotes third-party IT infrastructure delivered over the internet through shared, multi-tenant data centers with automated resource provisioning, typically measured in virtual CPU cores, gigabytes of RAM, and terabytes of block storage with latency thresholds under 10 milliseconds for premium tiers. Its primary commercial purpose is to replace capital-intensive on-premises server ownership with operational expenditure models that scale elastically with transaction volumes. Infrastructure as a Service dominates absolute spending as enterprises lift and shift legacy workloads, while Platform as a Service captures expanding margin pools by abstracting middleware management from developer teams. Software as a Service remains the most mature segment with compressed differentiation, though vertical-specific applications in financial services compliance and healthcare interoperability command premium pricing.
Regulators including the European Data Protection Board under GDPR, the US Securities and Exchange Commission through cybersecurity disclosure rules, and China's Ministry of Industry and Information Technology via data localization mandates are reshaping where providers build regions and how customers architect failover. Compliance-driven procurement now requires documented encryption standards, audit logging, and cross-border transfer mechanisms before contract execution. Stakeholders must monitor evolving sovereignty requirements and assess whether single-provider dependency or multi-cloud redundancy better aligns with emerging jurisdictional enforcement patterns.
Market Dynamics
Hyperscaler capital expenditure commitments are compressing procurement cycles as federal cloud migration mandates in the United States accelerate enterprise workload transitions from on-premises data centers to multi-tenant infrastructure.
Growth Catalysts
- GDPR data residency requirements:European healthcare providers are migrating electronic health records to sovereign cloud regions to satisfy the EU AI Act and European Data Protection Board enforcement timelines.
- Real-time analytics infrastructure:Cloud-native architectures are displacing legacy batch processing systems in clinical settings where sub-10 millisecond latency thresholds enable predictive patient monitoring.
- Federal procurement mandates:United States government agencies are accelerating cloud migration timelines through FedRAMP certification requirements and Defense Department security clearance standards.
Market Restraints
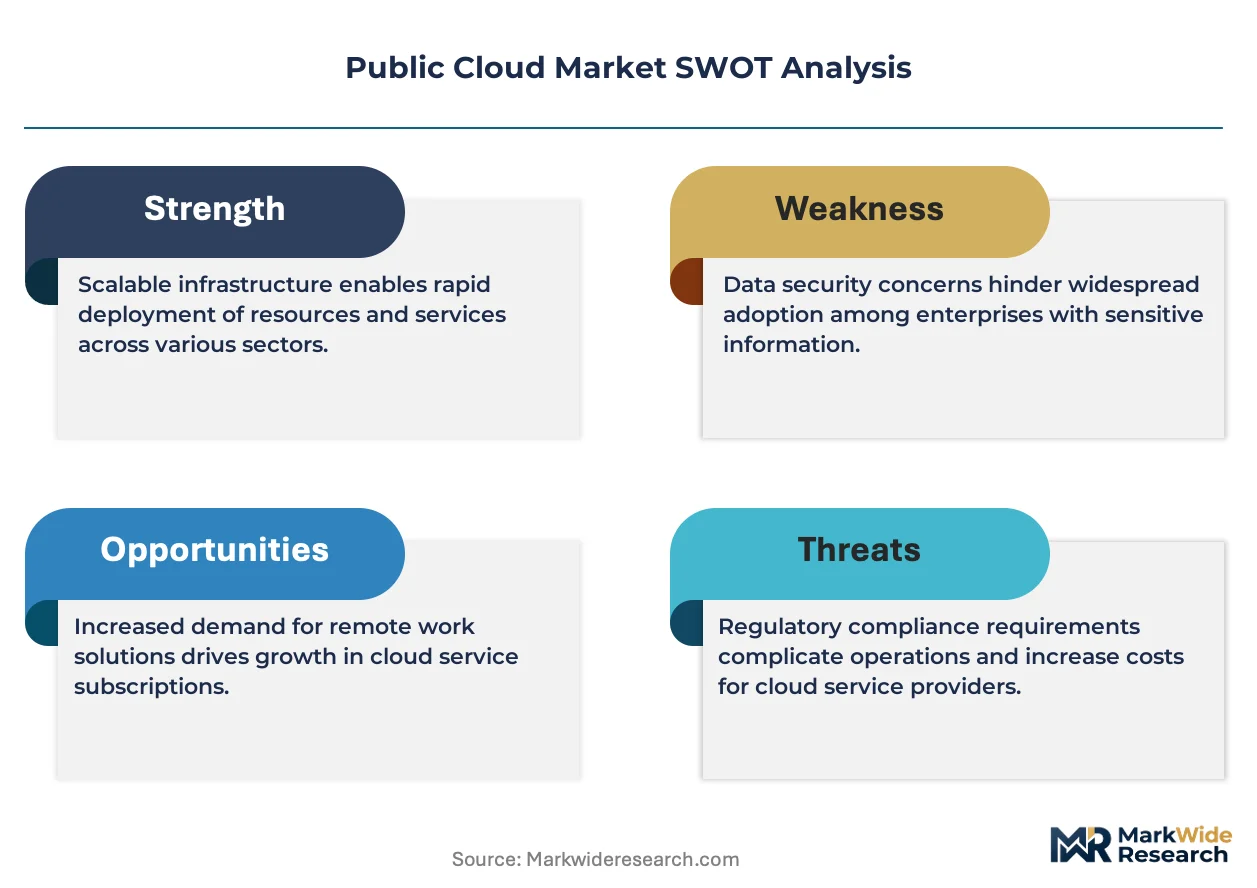
- Electricity cost volatility:Data center power consumption in Germany and Ireland faces input cost pressure from natural gas price fluctuations and grid capacity constraints.
- Hyperscaler concentration risk:Three providers control the majority of raw compute cycles in the United States, creating single-source dependency for enterprise failover architectures.
- Cross-border data friction:China's Ministry of Industry and Information Technology localization mandates fragment global workload orchestration and increase compliance overhead.
Strategic Opportunities
- India's underpenetrated enterprise segment:Mid-market manufacturers in Maharashtra and Karnataka lack hybrid cloud orchestration tools, creating whitespace for managed service providers.
- ISO 27001 certification tailwinds:Financial services compliance requirements in Singapore and Hong Kong are mandating documented encryption standards before contract execution.
- Edge-to-core convergence:Tensor processing units integrated with 5G network slicing are enabling factory-floor machine learning inference without round-trip latency to central regions.
Industry Challenges
- Multi-cloud skill scarcity:Kubernetes orchestration and FinOps cost optimization functions face talent shortages in secondary United States metro markets.
- Legacy system integration friction:Mainframe-dependent insurance carriers in Japan and Germany encounter API translation complexity when lifting COBOL workloads to containerized environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public Cloud Market |
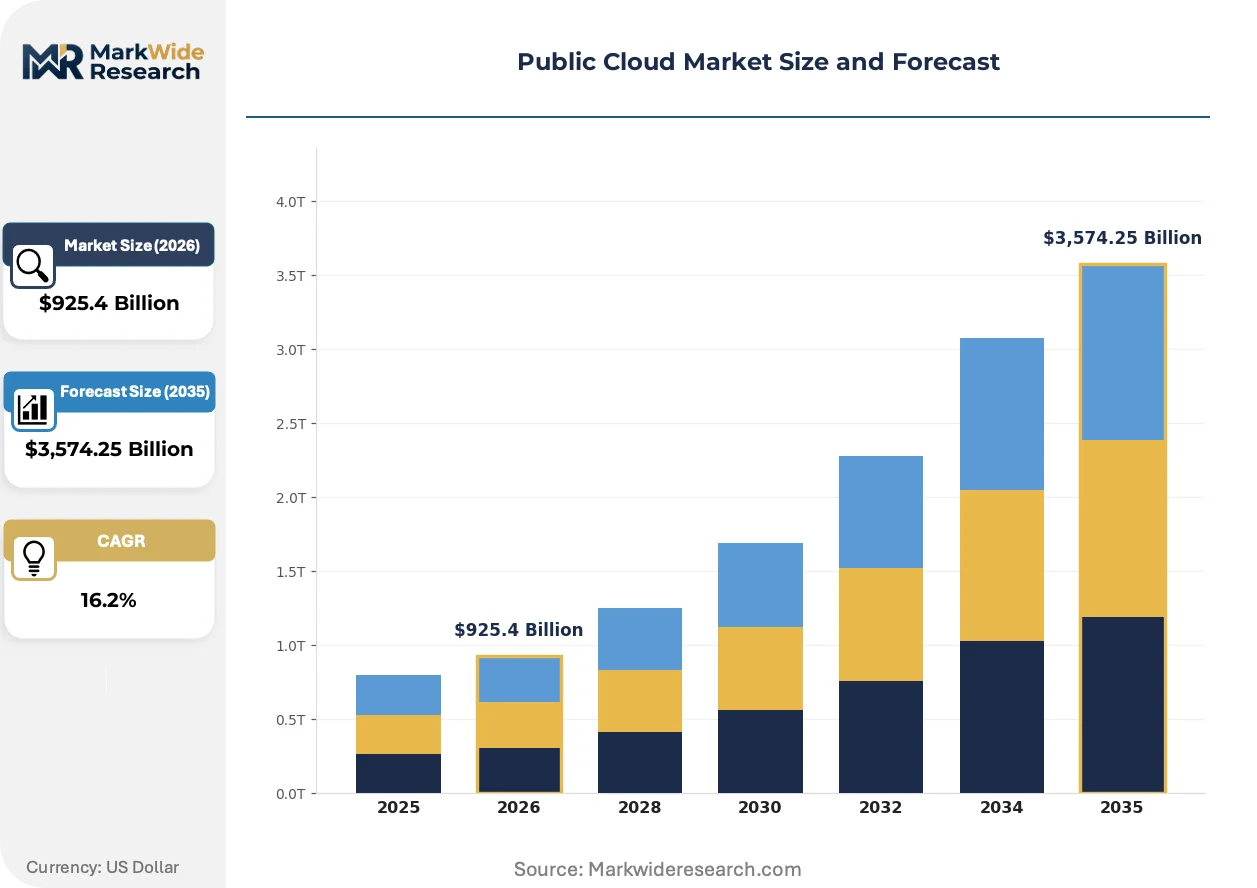
| Market Size in 2026 | $925.4 Billion |
| Market Size in 2035 | $3,574.25 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Infrastructure as a Service, Platform as a Service, Software as a Service, Function as a Service Service Type: Compute, Storage, Database, Networking End User: Small Businesses, Enterprises, Government Agencies, Educational Institutions Industry Vertical: Healthcare, Financial Services, Retail, Manufacturing |
| Companies Covered | Alibaba Cloud, IBM Cloud, Amazon Web Services (AWS), CoreWeave, Tencent Cloud, Microsoft Azure, Oracle Cloud Infrastructure, Huawei Cloud, Google Cloud Platform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public Cloud Market Strategic Shifts & Innovations
Workload portability standards are fragmenting as sovereign data requirements harden, forcing providers to engineer region-specific compliance layers rather than unified global platforms.
Serverless computing architectures are electrifying developer productivity by abstracting infrastructure management entirely. Healthcare software vendors in the United States are adopting function-as-a-service models at accelerated pace. This technology is compressing time-to-market for clinical trial management applications from quarters to weeks.
GDPR Article 44 transfer mechanism restrictions are compelling European enterprises to re-architect failover patterns entirely within EU jurisdictional boundaries. The European Data Protection Board's Schrems II enforcement is redirecting hyperscaler region buildout priorities toward Frankfurt, Dublin, and Stockholm clusters. Healthcare interoperability platforms face the steepest compliance recertification burdens under these constraints.
Consumption-based billing granularity is displacing reserved instance commitments among price-sensitive buyers. Mid-market retailers in France and Spain are unbundling managed security from compute contracts to optimize operational expenditure. This behavioral shift is most visible in seasonal demand verticals where transaction volumes fluctuate by an order of magnitude across calendar quarters.
Public Cloud Market Segmentation
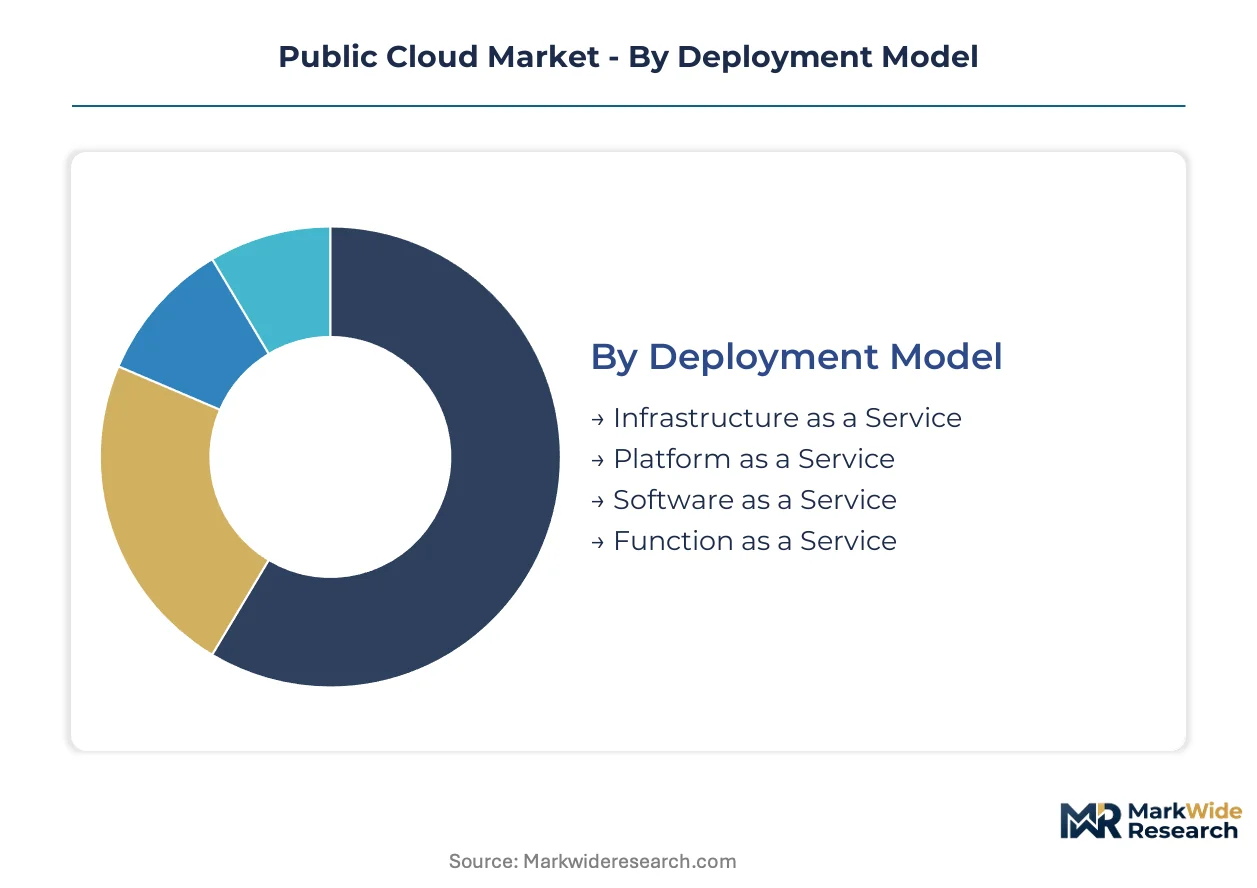
Segmentation in the Public Cloud Market reveals how procurement patterns diverge across technical abstraction layers and organizational maturity. Deployment models separate capital-heavy infrastructure buyers from developers seeking managed platforms. End-user scale and industry vertical dictate compliance requirements that reshape regional buildout priorities.
Deployment Model:
Upgrade cycles from on-premises virtualization to cloud-native architectures are compressing as container orchestration matures and FinOps practices standardize cost accountability.
- Infrastructure as a Service:Raw compute, storage, and networking resources delivered through virtualized abstraction layers with automated provisioning APIs. Demand concentrates among United States federal agencies executing FedRAMP-mandated workload migrations, driven by congressional pressure to shutter legacy data centers.
- Platform as a Service:Managed middleware and runtime environments that eliminate infrastructure configuration overhead for developer teams. European healthcare software vendors in Germany and France are adopting PaaS for clinical trial applications under GDPR Article 44 transfer restrictions.
- Software as a Service:Fully managed applications accessed through web interfaces with zero infrastructure visibility. United States mid-market retailers favor consumption-based SaaS contracts for seasonal demand elasticity.
- Function as a Service:Event-driven compute models executing code fragments without persistent server management. Healthcare interoperability platforms in the United States deploy FaaS for real-time patient data processing.
Volume placements concentrate in Infrastructure as a Service; the faster expansion belongs to Function as a Service.
Service Type:
Cost tier differentiation separates commodity raw resources from premium managed offerings with guaranteed latency thresholds and dedicated support channels.
- Compute:Virtual CPU cores and GPU instances provisioned through hyperscaler APIs with per-second billing granularity. United States defense contractors require compute with Defense Department security clearances.
- Storage:Block, object, and file systems with tiered durability guarantees and cross-region replication options. Healthcare providers in Ireland face electricity cost volatility affecting cold storage economics.
- Database:Managed relational and NoSQL engines with automated patching, backup, and scaling operations. Financial services compliance requirements in Singapore mandate documented encryption standards for database contracts.
- Networking:Software-defined connectivity with private backbone routing and DDoS protection services. India's underpenetrated enterprise segment in Maharashtra lacks hybrid cloud orchestration tools for network management.
Procurement volumes cluster in Compute services; Database offerings are climbing the fastest as legacy modernization accelerates.
End User:
Customer type determines contract structure complexity, with government mandates requiring sovereign data residency and educational institutions prioritizing cost optimization over performance guarantees.
- Small Businesses:Price-sensitive buyers favoring consumption-based billing and pre-configured solution templates. Retailers in France and Spain unbundle managed security from compute contracts to optimize operational expenditure.
- Enterprises:Multi-year committed use discounts with dedicated customer success teams and custom SLA negotiations. United States hyperscaler capex commitments are compressing procurement cycles for enterprise workload transitions.
- Government Agencies:FedRAMP certification requirements and data localization mandates dominate vendor selection. China's Ministry of Industry and Information Technology localization mandates fragment global workload orchestration for foreign providers.
- Educational Institutions:Grant-funded research computing with burst capacity for semester-bound project timelines. Tensor processing units integrated with 5G network slicing enable university laboratory machine learning without central region latency.
Enterprise commitments represent the largest revenue base; Government Agencies are gaining share fastest through federal procurement mandates.
Industry Vertical:
Application-specific compliance requirements create margin stratification, with regulated verticals commanding premium pricing for documented audit trails and jurisdictional data controls.
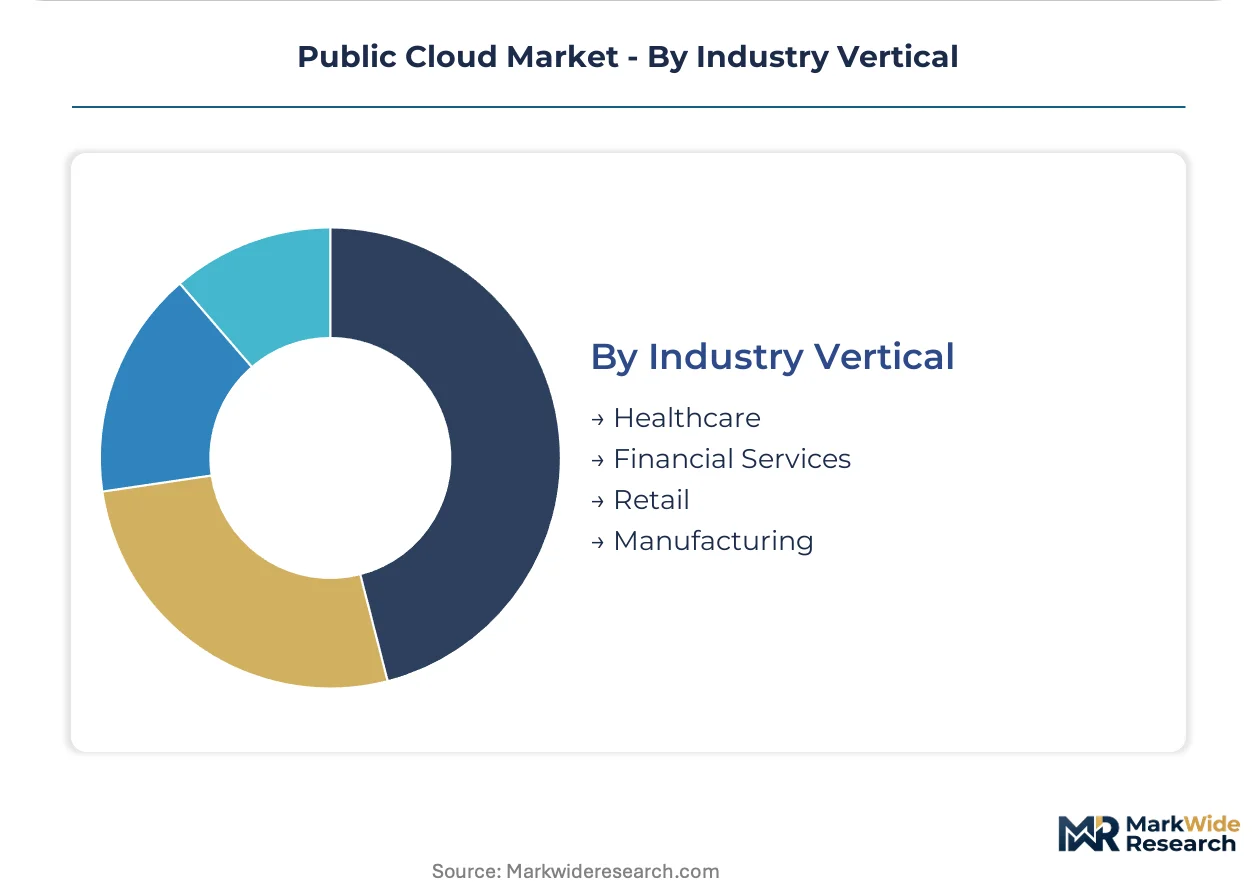
- Healthcare:Electronic health record migration to cloud-native architectures enabling real-time analytics with sub-10 millisecond latency thresholds. European providers are migrating to sovereign cloud regions under EU AI Act enforcement timelines.
- Financial Services:Real-time fraud detection and regulatory reporting with ISO 27001 certification requirements. Singapore and Hong Kong mandate documented encryption standards before contract execution.
- Retail:Seasonal demand elasticity with unbundled security and consumption-based billing optimization. Mid-market retailers in France and Spain exhibit this behavioral shift most visibly.
- Manufacturing:Edge-to-core convergence with factory-floor machine learning inference. Mid-market manufacturers in India's Karnataka state lack hybrid cloud orchestration tools, creating whitespace for managed service providers.
Healthcare captures the steepest compliance-driven premium; Manufacturing is expanding most quickly through industrial IoT integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure production concentrates in hyperscaler data center clusters, while consumption patterns fragment across regulatory jurisdictions with divergent data sovereignty requirements.
United States
Federal cloud migration mandates and Defense Department security clearance standards are accelerating procurement cycles for enterprise workload transitions. FedRAMP certification requirements dominate vendor selection criteria for government agencies. Northern Virginia's data center corridor hosts the densest concentration of hyperscale facilities, with power commitments exceeding 2 gigawatts across Ashburn and Loudoun County developments.
Germany
Electricity cost volatility from natural gas price fluctuations is pressuring data center economics in Frankfurt and Berlin metro areas. GDPR Article 44 transfer mechanism restrictions compel enterprises to re-architect failover patterns within EU jurisdictional boundaries. The Rhine-Main cluster anchors sovereign cloud region buildouts, with hyperscalers expanding Frankfurt availability zones to satisfy European Data Protection Board enforcement timelines.
India
Mid-market manufacturers in Maharashtra and Karnataka lack hybrid cloud orchestration tools, creating whitespace for managed service providers. The country's national IT regulator mandates data localization for sensitive categories through evolving compliance frameworks. Mumbai and Bangalore host the dominant cloud availability zones, with hyperscalers committing $8-12 billion in combined infrastructure investments through 2026.
China
MIIT localization mandates fragment global workload orchestration and increase compliance overhead for foreign providers. Dual carbon goals are reshaping data center siting decisions toward western provinces with renewable energy access. The Beijing-Tianjin-Hebei corridor and Yangtze River Delta concentrate domestic cloud capacity, with state-affiliated providers dominating sovereign infrastructure deployment.
Singapore
Financial services compliance requirements are mandating documented encryption standards before contract execution across banking and insurance verticals. The Monetary Authority of Singapore's technology risk management guidelines shape procurement specifications for critical systems. The city-state's data center cluster serves as ASEAN's primary cloud hub, with sub-10 millisecond latency connectivity to Jakarta, Bangkok, and Ho Chi Minh City.
Public Cloud Market Key Industry Players
Top-tier vendors anchor hyperscale infrastructure deployment, while specialized compute providers and regional sovereign clouds occupy differentiated positions. Three providers control the majority of raw compute cycles in developed markets, creating concentration risk for enterprise failover architectures. Strategic archetypes include vertically integrated hyperscalers with custom silicon, sovereign cloud specialists with government affiliations, and GPU-focused compute providers serving machine learning workloads. Competitive moves center on custom accelerator development and multi-cloud orchestration tooling acquisition.
Within the vertically integrated hyperscaler tier, Amazon Web Services (AWS), Microsoft Azure, and Google Cloud Platform exemplify distinct competitive positioning. AWS leverages first-mover infrastructure footprint across availability zones. Microsoft Azure anchors enterprise loyalty through productivity software integration. Google Cloud Platform differentiates with custom tensor processing units. Alibaba Cloud and Tencent Cloud occupy positions within China's sovereign market structure. CoreWeave represents the specialized compute archetype focused on GPU-intensive workloads.
| Leading Market Players |
|---|
| Alibaba Cloud |
| IBM Cloud |
| Amazon Web Services (AWS) |
| CoreWeave |
| Tencent Cloud |
| Microsoft Azure |
| Oracle Cloud Infrastructure |
| Huawei Cloud |
| Google Cloud Platform |
| Others |
Cost & Logistics Intelligence
Hyperscaler balance-sheet-financed infrastructure buildouts in the United States anchor supply-side discipline while compressing spot-market pricing elasticity for compute cycles. Sovereign-backed cloud initiatives in China and Germany are fragmenting global pricing benchmarks through data localization mandates that force regional capacity duplication.
Pricing Analysis
Margin tightening in raw compute tiers reflects hyperscaler capex commitments exceeding demand absorption in Northern Virginia and Frankfurt clusters. Three-tier pricing structure across premium latency-guaranteed, standard burstable, and economy spot-instance levels separates enterprise buyers from mid-market retailers and batch-workload developers. Cost-down pressure on managed database services accelerates because consumption-based billing granularity displaces multi-year reserved instance commitments. Small businesses in France and Spain exhibit the highest price sensitivity through unbundled security contracts, while United States defense contractors accept premium pricing for FedRAMP-certified sovereign capacity.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan Semiconductor Manufacturing for custom tensor processing units and NVIDIA for GPU accelerators feeding machine learning workloads. Hardware supply concentrates in Taiwan, South Korea, and the United States for advanced logic fabrication. Raw material dependencies span high-purity silicon wafers, cobalt-bearing substrates, and rare-earth magnet components for cooling systems. Tariff exposure on semiconductor manufacturing equipment imported into China fragments global workload orchestration. Distribution runs through hyperscaler-owned backbone networks with private fiber interconnects to enterprise customer premises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power grid capacity constraints in Germany and Ireland prop pricing for premium-tier sovereign cloud regions. Data center electricity input costs constitute the binding capacity bottleneck sustaining margin structures.
For Market Incumbents: Extend availability zone footprints into India's Maharashtra and Karnataka manufacturing corridors before managed service providers consolidate mid-market relationships. Fortify sovereign cloud certifications under EU AI Act timelines to preempt European healthcare provider defection. Deepen backward integration into custom silicon development to differentiate from GPU-rental specialists threatening raw compute margins. For New Entrants and Emerging Players: Managed service providers with hybrid cloud orchestration expertise represent the most penetrable channel partner type for India's underpenetrated enterprise segment. Target Japanese insurance carriers lifting COBOL mainframe workloads through API translation services. Pursue university laboratory contracts for tensor processing unit access with semester-bound burst capacity terms. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional sovereign cloud specialists with government affiliations in Germany and China facing electricity cost volatility. Long-term viability hinges on jurisdictional data residency enforcement hardening over a multi-decade horizon. ISO 27001 certification backlogs in Singapore and Hong Kong signal acquisition target scarcity for financial services compliance capabilities. Watch for FedRAMP authorization acceleration as inflection indicator for United States federal procurement momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Region Expansion | GDPR Article 44 enforcement redirects hyperscaler buildout priorities toward Frankfurt and Stockholm clusters. |
| Custom Silicon Development | Google's tensor processing units differentiate machine learning pricing from commodity GPU rental offerings. |
| Managed Security Unbundling | Mid-market retailers in France and Spain optimize operational expenditure through consumption-based contract restructuring. |
| Edge-to-Core Convergence | 5G network slicing with factory-floor tensor processing units eliminates round-trip latency for manufacturing inference workloads. |
| FinOps Tooling Acquisition | Kubernetes orchestration skill scarcity in secondary United States metros creates consolidation opportunity for cost optimization platforms. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with cloud infrastructure procurement officers, platform engineers at healthcare software vendors, and hyperscaler solution architects combined with hyperscaler capex disclosures, SEC 10-K infrastructure segments, and European Data Protection Board enforcement timelines. Bottom-up demand modeling across deployment modes triangulated against top-down IT spending surveys from enterprise CIOs.
Reconciliation of server shipment data, power purchase agreements for data center facilities, and cloud revenue disclosures informed the projection framework. Segmentation dimensions modeled include deployment abstraction layer, organization scale tier, industry vertical compliance requirements, and regional sovereignty jurisdiction across the analysis window. CAGRs derived from elasticity-adjusted demand curves incorporating federal procurement mandate acceleration and electricity cost volatility assumptions.
Caveats apply where MIIT localization mandate enforcement or natural gas price fluctuations could materially shift the outlook. Forecasts reflect documented assumptions regarding FedRAMP authorization velocity and GDPR transfer mechanism interpretation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Based-Batch Processing Market
Cloud Computing
North America Cloud Computing Market
Cloud Computing
AI Platform Cloud Service Market
Cloud Computing
Cloud Database Market
Cloud Computing
Application Hosting Market
Cloud Computing
Cloud Integration Software Market
Cloud Computing
Telecom Cloud Market
Cloud Computing
Cloud Applications Market
Cloud Computing
Distributed Cloud System Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
Europe Cloud Computing Market
Cloud Computing
China Cloud Computing Market
Cloud Computing
High-Performance Computing (HPC) As a Service Market
Cloud Computing
Cloud Computing Stack Layers Market
Cloud Computing
VM Service Market
Cloud Computing
Cloud VPN Market