
 Global Mobile Cloud Market | 2026-2036
Global Mobile Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Cloud Market Foresight
The EU AI Act is recalibrating how mobile cloud providers architect data processing pipelines across European member states. Amazon Web Services anchors its competitive position through extensive edge node deployment that reduces latency for mobile workloads. Microsoft Azure differentiates via deep enterprise integration with productivity suites that financial institutions and government agencies favor. Google Cloud specializes in AI-optimized infrastructure that supports real-time analytics on mobile endpoints.
Mobile cloud computing delivers virtualized compute, storage, and application services to smartphones, tablets, and IoT endpoints through cellular or Wi-Fi networks, typically operating with sub-100 millisecond latency thresholds for interactive workloads. Its primary commercial purpose is to extend enterprise-grade processing power to resource-constrained devices without local hardware expansion. Public cloud deployment captures the dominant revenue share due to hyperscaler economies of scale, though private cloud and hybrid configurations are gaining traction among financial institutions with strict data residency requirements. Mobile Backend as a Service and cloud security solutions command premium margins as enterprises prioritize rapid application development and endpoint protection.
The EU AI Act and GDPR impose strict data localization and algorithmic transparency requirements that reshape how mobile cloud providers design European infrastructure. The FCC in the United States and MIIT in China enforce spectrum allocation and cross-border data rules that determine market access for foreign cloud operators. Stakeholders must monitor evolving sovereign cloud mandates and edge computing standards that will determine which architectures gain regulatory approval in key jurisdictions.
Market Dynamics
Edge computing infrastructure is compressing latency thresholds below 50 milliseconds for interactive mobile workloads, forcing hyperscalers to rearchitect data sovereignty compliance across fragmented regulatory jurisdictions.
Growth Catalysts
- EU AI Act data localization mandates:Financial institutions across Germany and France must process mobile data within member-state boundaries, expanding sovereign cloud capacity investments.
- 5G network slicing:Telecommunications operators in South Korea and the United States are deploying dedicated bandwidth slices for enterprise mobile applications requiring guaranteed quality of service.
- Financial services mobile workforce expansion:Banking and insurance sectors are extending core trading and risk management applications to tablet and smartphone endpoints.
Market Restraints
- Cross-border data transfer restrictions:China's MIIT cybersecurity regulations and GDPR Article 44 create operational friction for multinational enterprises operating unified mobile cloud architectures.
- Specialized edge hardware costs:GPU-accelerated inference nodes for AI workloads at cellular base stations require capital commitments that mid-market enterprises struggle to justify.
- Spectrum allocation bottlenecks:FCC and national regulators in key markets control millimeter-wave bands that determine edge node deployment density.
Strategic Opportunities
- India's digital public infrastructure:The country's Unified Payments Interface and Aadhaar authentication systems create demand for mobile cloud backends serving 1.4 billion potential endpoints.
- AI inference at the edge:Convergence of lightweight neural network architectures with ARM-based mobile processors enables real-time computer vision on factory floors.
- Japan's METI smart manufacturing incentives:Subsidies for Industry 4.0 adoption are accelerating mobile cloud deployment among automotive and electronics suppliers.
Industry Challenges
- Multi-cloud orchestration expertise scarcity:Enterprise IT departments lack personnel capable of managing Kubernetes workloads across AWS, Azure, and Google Cloud simultaneously.
- GDPR algorithmic audit timelines:Mobile AI applications require documentation cycles that extend product release schedules by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Cloud Market |
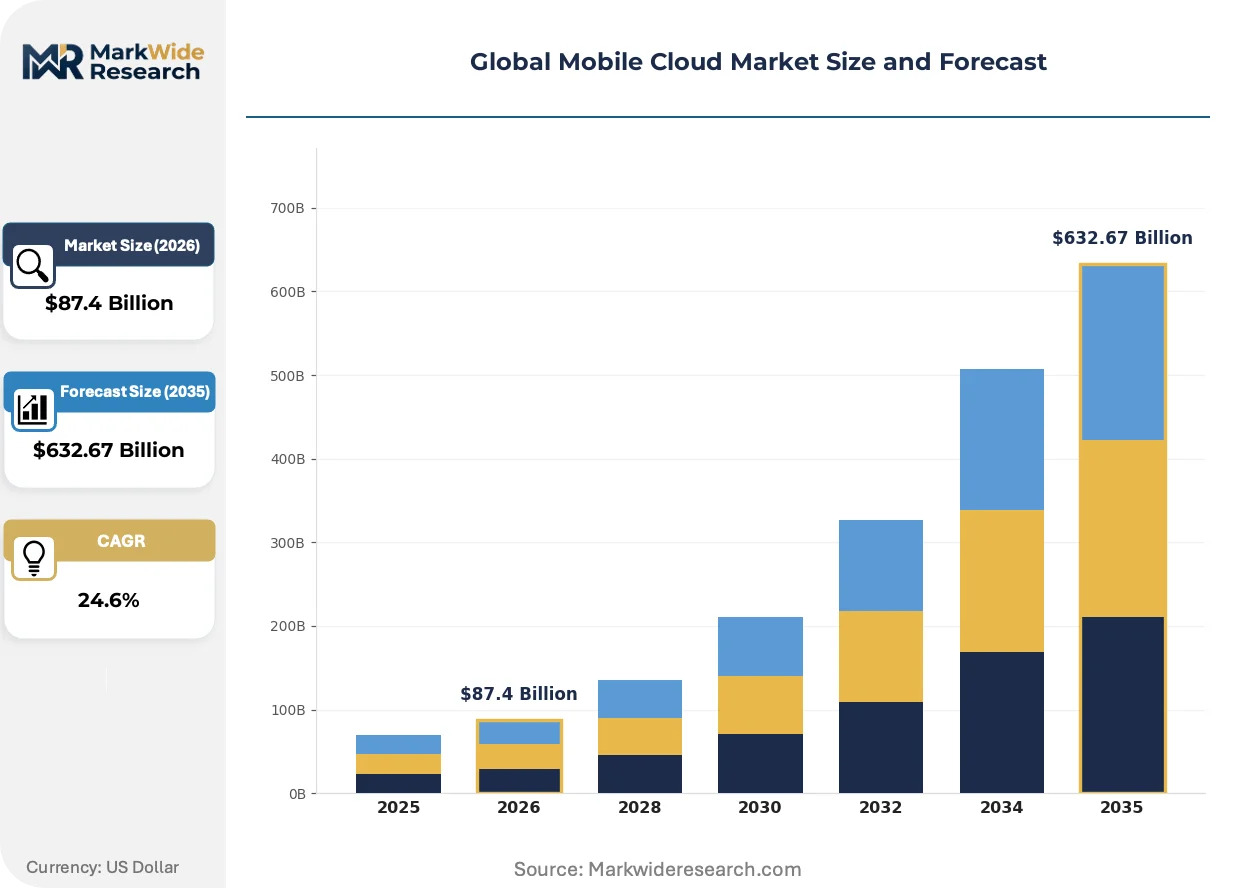
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $632.67 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Type: Mobile Backend as a Service, Cloud Storage, Cloud Security, Mobile Analytics, Mobile Enterprise Application Platform Use Case: Real-Time Collaboration, Content Delivery, Mobile Commerce, Social Networking, Location-Based Services Customer Type: Telecom Operators, Financial Institutions, Retail Chains, Educational Institutes, Government Agencies |
| Companies Covered | Alibaba Cloud, Oracle Cloud Infrastructure, Amazon Web Services, Cloudflare, IBM Cloud, Microsoft Azure, Tencent Cloud, Fastly, Google Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Cloud Market Shifts & Advancements
Serverless computing architectures are eliminating infrastructure management overhead for mobile backend development, while confidential computing hardware creates new possibilities for processing sensitive data on shared cloud infrastructure.
WebAssembly runtime environments are overtaking container-based deployment for mobile microservices. Fintech startups in Singapore and London are compiling Python and Rust code to WASM modules that initialize in under 100 milliseconds. This compression of cold-start latency is overtaking traditional serverless functions for payment processing and fraud detection workloads.
The EU AI Act's risk classification system is mandating human oversight interfaces for high-risk mobile AI applications. Healthcare providers deploying diagnostic algorithms on tablets must implement explainability dashboards that satisfy notified body requirements. German hospital networks are restructuring procurement specifications to prioritize vendors with established conformity assessment procedures.
Consumption-based billing for mobile backend services is displacing committed-use contracts among mid-market enterprises. SaaS vendors in the United States are unbundling API call pricing from storage fees, allowing retail and logistics customers to align cloud costs with seasonal transaction volumes. This flexibility is compressing sales cycles for mobile commerce platform providers.
Global Mobile Cloud Market Segmentation
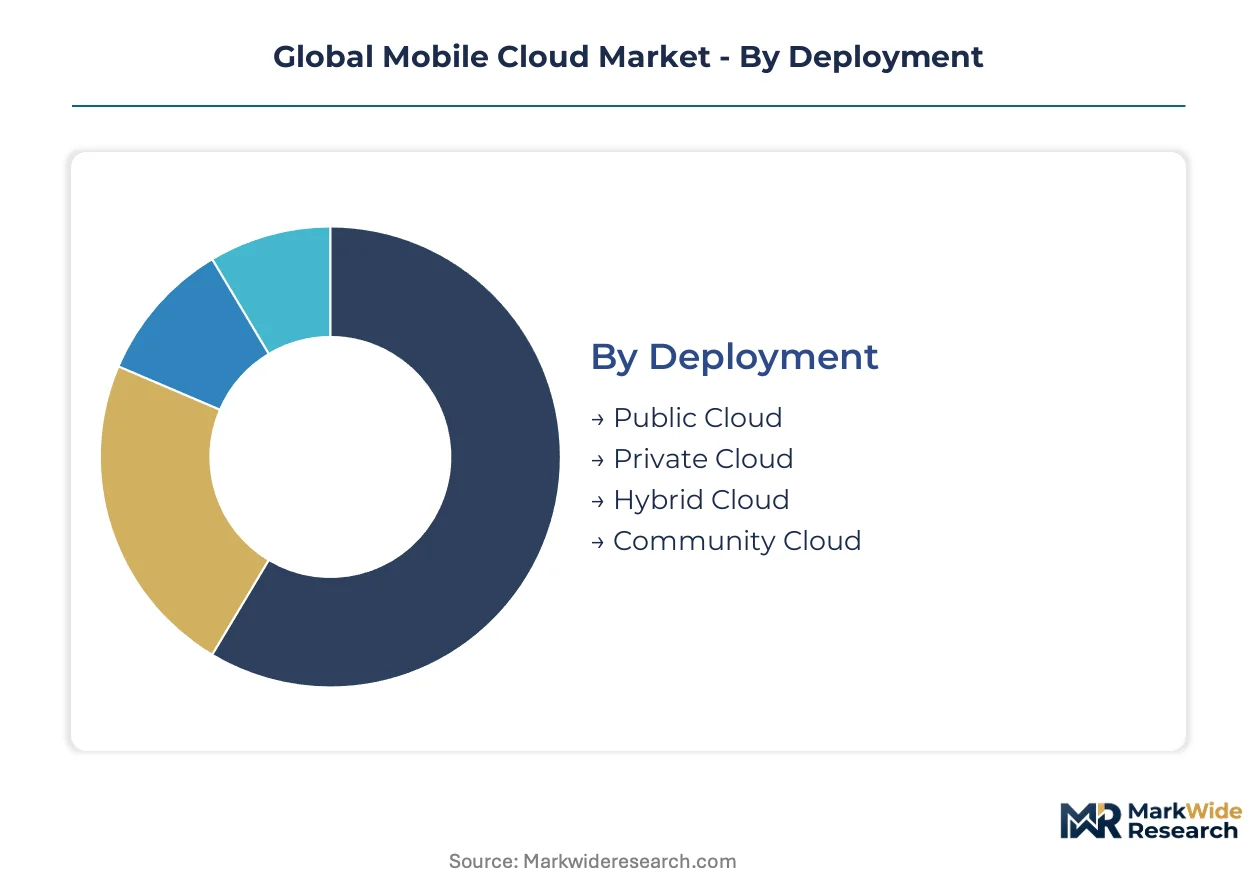
Mobile cloud segmentation reveals how infrastructure choices, solution architectures, and customer requirements fragment into distinct commercial battlegrounds. Deployment models and solution types determine margin structures, while use cases and customer verticals dictate latency thresholds and compliance burdens.
Deployment:
Public cloud captures volume through hyperscaler scale economics, while private and hybrid configurations command premium pricing from regulated verticals.
- Public Cloud:Shared infrastructure delivers compute and storage through multi-tenant architectures with automatic scaling. Financial institutions in Singapore and retail chains across Germany favor public deployments for customer-facing mobile applications where data residency requirements remain permissive.
- Private Cloud:Dedicated single-tenant environments isolate workloads on proprietary hardware or exclusive virtual partitions. German automotive suppliers and South Korean banks mandate private infrastructure for proprietary design data and trading algorithms under GDPR and domestic financial regulations.
- Hybrid Cloud:Orchestrated workload portability between public and private environments enables burst capacity during peak mobile transaction periods. Japanese manufacturers deploy hybrid architectures to keep sensitive IoT telemetry on-premises while pushing non-critical analytics to public endpoints.
- Community Cloud:Shared infrastructure serving organizations with common compliance requirements or industry affiliations. Healthcare networks in France and research consortia in Switzerland utilize community models to distribute HIPAA and GDPR compliance costs across member institutions.
Today's leader: Public Cloud. Tomorrow's challenger: Hybrid Cloud.
Solution Type:
Backend services and security solutions attract premium pricing as enterprises prioritize rapid deployment and endpoint protection over commodity storage.
- Mobile Backend as a Service:Pre-built server-side infrastructure eliminates custom API development for push notifications, user authentication, and data synchronization. Fintech startups in London and Singapore accelerate product launches through MBaaS platforms that abstract database management and scaling logic.
- Cloud Security:Endpoint detection, encryption key management, and zero-trust access controls protect mobile data in transit and at rest. German banks and U.S. healthcare providers mandate hardware security modules and confidential computing for high-risk mobile AI applications under EU AI Act and HIPAA requirements.
- Cloud Storage:Object and block storage services archive mobile-generated media, logs, and application state with tiered durability guarantees. Content creators in Brazil and logistics operators in India leverage cold storage tiers for cost-efficient retention of non-critical mobile telemetry.
- Mobile Analytics:Real-time processing pipelines extract behavioral patterns from mobile interaction streams. Retail chains in the United States deploy location-aware analytics to optimize in-store layouts based on smartphone movement patterns.
- Mobile Enterprise Application Platform:Integrated development environments streamline cross-platform mobile application deployment with centralized management. Government agencies in South Korea standardize on MEAP solutions to maintain consistent security policies across diverse device fleets.
Security and backend services expand most quickly as compliance complexity and development velocity demands intensify.
Use Case:
Latency-sensitive interactive workloads concentrate investment in edge-adjacent infrastructure, while batch-oriented services tolerate centralized processing.
- Real-Time Collaboration:Synchronous document editing and video conferencing demand sub-50 millisecond latency through geographically distributed edge nodes. Enterprise workforces in the United States and Germany rely on real-time collaboration as hybrid work models persist.
- Mobile Commerce:Payment processing, inventory lookup, and personalized recommendation engines require elastic backend capacity during promotional events. Retail operators in India and Southeast Asia scale mobile commerce infrastructure to accommodate festival-season transaction spikes.
- Content Delivery:Media streaming and software distribution leverage content delivery networks to cache popular assets near cellular base stations. Video platforms serving Brazilian and Indonesian subscribers optimize for variable network conditions through adaptive bitrate streaming.
- Social Networking:Feed generation, messaging, and notification systems balance consistency with availability across partitioned data stores. Younger demographics in Nigeria and Vietnam drive social networking data volumes through multimedia-rich mobile interactions.
- Location-Based Services:GPS-enabled navigation, geofencing, and proximity marketing process spatial queries against high-resolution map tiles. Logistics providers in Japan and ride-hailing platforms in Mexico depend on precise location services for fleet coordination.
Commerce and collaboration currently dominate infrastructure commitments, though location services gain share fastest as IoT endpoint density increases.
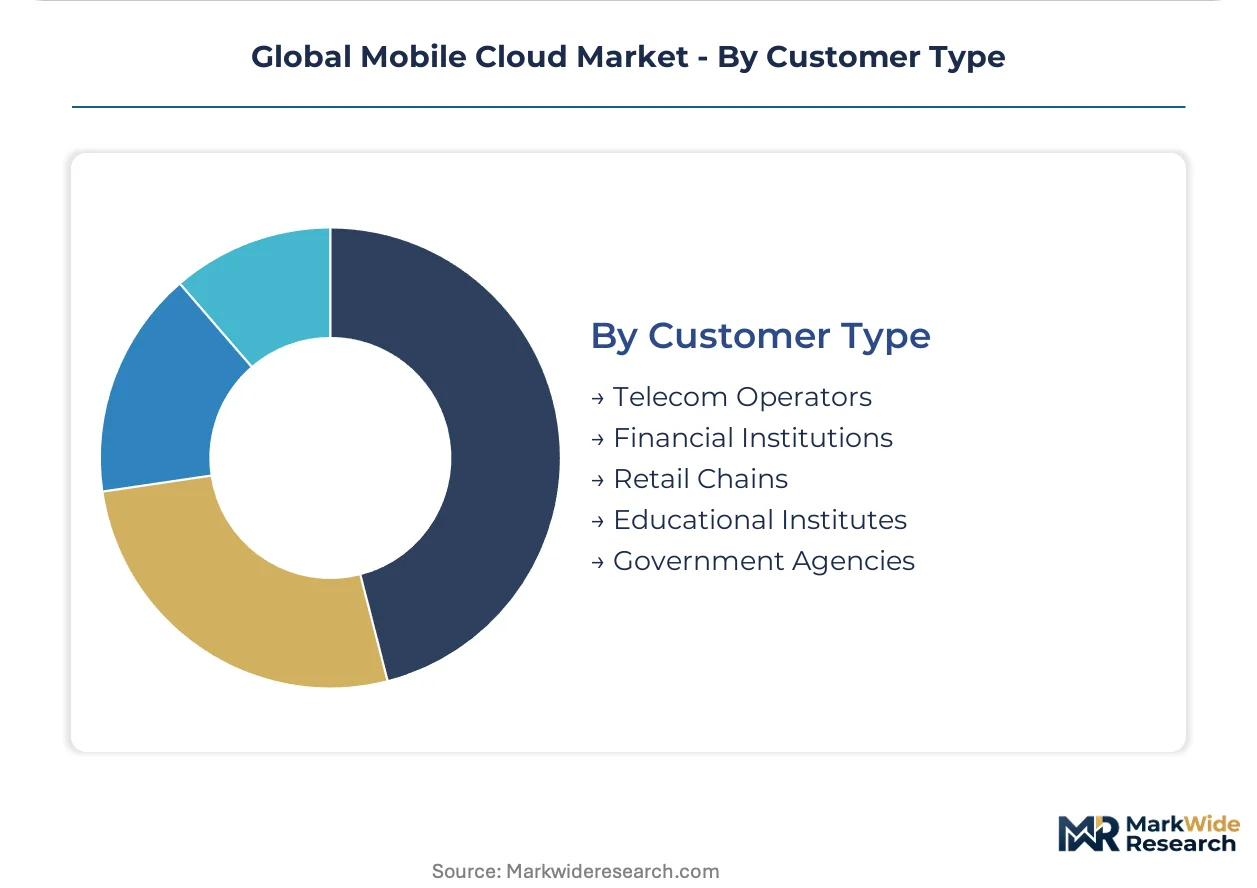
Customer Type:
Regulated industries absorb higher per-endpoint costs to satisfy data sovereignty mandates, while consumer-facing sectors prioritize unit economics at scale.
- Financial Institutions:Banks, insurers, and asset managers extend core systems to mobile endpoints with cryptographic authentication and transaction signing. Institutions across Switzerland, Luxembourg, and Singapore invest in sovereign cloud capacity to satisfy domestic financial regulator requirements.
- Telecom Operators:Mobile network providers deploy edge computing infrastructure to reduce backhaul costs and enable network slicing for enterprise customers. Operators in South Korea and the United States monetize 5G infrastructure through guaranteed-quality mobile cloud services.
- Government Agencies:Public sector entities mandate domestic data processing and supply chain verification for national security applications. Defense and civilian agencies in France, Germany, and Australia procure exclusively through certified sovereign cloud frameworks.
- Retail Chains:Brick-and-mortar and digital-native retailers unify inventory, loyalty, and payment systems across mobile point-of-sale and consumer applications. Grocery and fashion retailers in the United Kingdom and Spain optimize mobile cloud spend against seasonal revenue fluctuations.
- Educational Institutes:Universities and K-12 systems deliver learning management systems and remote examination platforms to student devices. Institutions in Canada and the Netherlands scale mobile infrastructure to support hybrid learning models with uneven campus density.
Financial services and telecom currently anchor infrastructure investment, with government agencies climbing the fastest as digital public service mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise software engineering talent clusters in Seattle, Bangalore, and Shenzhen anchor mobile cloud infrastructure development across three continents. These concentrations shape how hyperscalers architect data sovereignty solutions for financial services and government clients.
United States
Financial institutions in New York and San Francisco extend core trading systems to mobile endpoints, driving demand for sub-50 millisecond edge infrastructure. The FCC enforces spectrum allocation rules that determine millimeter-wave deployment density for cellular base stations. Seattle hosts the engineering headquarters of Amazon Web Services, where teams optimize latency for enterprise mobile workloads.
Germany
Automotive suppliers in Stuttgart and Munich deploy private cloud infrastructure for proprietary design data accessed via tablet endpoints. The EU AI Act mandates human oversight interfaces for high-risk mobile AI applications, extending procurement timelines for hospital networks in Berlin. Frankfurt's financial district anchors sovereign cloud capacity investments from domestic and foreign providers.
South Korea
Telecommunications operators in Seoul monetize 5G network slicing for guaranteed-quality enterprise mobile services. The Korea Communications Commission coordinates spectrum policy with industrial strategy under the Digital New Deal framework. Busan-Ulsan manufacturing corridors deploy edge computing for real-time quality control on smartphone-accessed production lines.
India
The Unified Payments Interface and Aadhaar authentication systems generate backend demand serving 1.4 billion potential mobile endpoints. TRAI regulates data localization requirements for payment processors and financial aggregators. Bangalore's technology corridor concentrates engineering talent for both domestic cloud providers and multinational development centers.
Japan
Automotive and electronics suppliers in Toyota City and Osaka accelerate mobile cloud deployment under METI smart manufacturing subsidies. The Act on Protection of Personal Information imposes consent requirements for cross-border data transfers from mobile endpoints. Nagoya's industrial belt integrates tablet-based maintenance systems with legacy factory automation.
Global Mobile Cloud Market Competitive Landscape
Capital-heavy infrastructure operators compete with asset-light platform specialists for enterprise mobile workloads. The market structure concentrates around three hyperscalers with global edge footprints, while regional specialists capture sovereign cloud mandates. Strategic archetypes include full-stack infrastructure providers, security-centric specialists, and vertical-focused platform vendors. Capacity expansion in European data centers and strategic partnerships with telecommunications operators dominate competitive moves.
Among hyperscale infrastructure providers, Amazon Web Services, Microsoft Azure, and Google Cloud occupy positions defined by edge node density and enterprise integration depth. Alibaba Cloud and Tencent Cloud exemplify regional champions with domestic market scale that translates to mobile backend specialization. Oracle Cloud Infrastructure and IBM Cloud sit within the enterprise legacy modernization tier, serving financial institutions with hybrid deployment requirements.
| Leading Market Players |
|---|
| Alibaba Cloud |
| Oracle Cloud Infrastructure |
| Amazon Web Services |
| Cloudflare |
| IBM Cloud |
| Microsoft Azure |
| Tencent Cloud |
| Fastly |
| Google Cloud |
| Others |
Supply & Pricing Matrix
The EU AI Act's algorithmic transparency mandates gate qualified supply for mobile cloud infrastructure serving European financial institutions, restricting premium-tier pricing access to providers with established conformity assessment procedures and sovereign cloud certifications.
Pricing Analysis
The bundled-vs-unbundled service split separates committed-use contracts from consumption-based API billing. SaaS-tiered subscription models dominate for mobile backend services, with price differentiation driven by GDPR compliance certification level and geographic edge node density. Pricing pressure stems from hyperscaler economies of scale compressing margins for regional specialists. Mid-market enterprises exhibit highest price sensitivity, while government agencies absorb premium sovereign cloud tariffs.
Supply Chain Analysis
Certification and qualification gating restricts hyperscaler edge hardware deployment to vendors meeting FCC spectrum allocation rules in the United States, EU AI Act conformity requirements in Germany, and MIIT cybersecurity regulations in China. GPU-accelerated inference chips draw from Taiwan and South Korea fabrication facilities, while ARM-based mobile processors hinge on semiconductor supply from China and Japan. Single-source vulnerability concentrates in advanced node lithography equipment. Distribution runs through telecommunications operator partnerships for cellular base station integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile cloud market functions as a regulatory compounder, with the EU AI Act's risk classification system driving demand for compliant infrastructure across European financial services.
For Market Incumbents: Deploy sovereign cloud capacity expansion as the primary lever. AWS, Azure, and Google Cloud should accelerate Frankfurt and Paris data center investments to satisfy GDPR Article 44 data localization mandates. Edge node densification in Stuttgart and Munich defends position against emerging European specialists capturing automotive private cloud contracts. For New Entrants and Emerging Players: Lightweight WebAssembly runtime environments offer a technology-first wedge into fintech fraud detection workloads. India's Unified Payments Interface backend infrastructure presents the most penetrable geography, with Aadhaar-authenticated mobile endpoints creating demand for compliant API gateways. A channel partnership strategy with domestic telecommunications operators accelerates market access. For Investors and Strategic Acquirers: Roll-up economics work for vertical-focused MBaaS specialists because mid-market enterprises lack multi-cloud orchestration expertise. The acquisition target archetype centers on confidential computing hardware vendors serving healthcare diagnostic applications. A model refresh is warranted upon material change in EU AI Act enforcement timelines for high-risk AI systems.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Capacity Expansion | Frankfurt and Paris data centers satisfy GDPR Article 44 mandates for German banks. |
| WebAssembly Runtime Deployment | Fintech startups in Singapore achieve sub-100 millisecond cold-start latency for payment processing. |
| 5G Network Slicing Partnership | South Korean telecommunications operators monetize guaranteed-quality enterprise mobile services. |
| Confidential Computing Hardware Integration | German hospital networks procure explainability dashboards for EU AI Act compliance. |
| Edge Node Densification | Seattle engineering teams optimize sub-50 millisecond latency for New York trading applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cloud infrastructure procurement officers, telecommunications network planners, financial services CTOs, and regulatory compliance leads with secondary validation against hyperscaler capex disclosures, SEC filings, TRAI spectrum allocation records, and EU AI Act implementation guidance. Bottom-up endpoint demand modeling and top-down infrastructure capacity analysis provided triangulation across data sources.
Comparable-period anchoring linked projection assumptions to historical deployment patterns across the analysis window. The analytical framework segmented by deployment model, solution type, use case latency threshold, and customer vertical regulatory intensity. CAGRs derived from installed base growth curves and average revenue per endpoint trajectories. Forecast inputs incorporated 5G spectrum auction timelines and sovereign cloud certification pipeline status.
The model holds under stable regulatory enforcement timelines; deviation in EU AI Act notified body capacity or FCC millimeter-wave allocation decisions would shift capacity expansion assumptions. Forecasts reflect documented assumptions about edge hardware cost curves and telecommunications operator partnership structures. A model refresh is warranted upon material change in GDPR cross-border data transfer adequacy determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Global Personal Cloud Market
Cloud Computing
Containers As a Service (Caas) Market
Cloud Computing
Public Finance Cloud Market
Cloud Computing
ASEAN Cloud Computing Market
Cloud Computing
Philippines ICT Market
Cloud Computing
Hadoop-As-A-Service (Haas) Market
Cloud Computing
Cloud Computing in Industrial IoT Market
Cloud Computing
North America Cloud Microservices Platform Market
Cloud Computing
Cloud Calling Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
Saudi Arabia Cloud Computing Market
Cloud Computing
Global Grid Computing Market
Cloud Computing
Cloudifier Market
Cloud Computing
AI and Blockchain Cloud Services Market
Cloud Computing
China Cloud Computing Market
Cloud Computing
Europe AI Cloud Computing in Automotive Market