
 Global Cloud Computing Iaas in Life Science Market | 2026-2036
Global Cloud Computing Iaas in Life Science Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Computing Iaas in Life Science Market Foresight
Usage-based leasing and consumption-billing models for high-performance computing clusters is reconfiguring capital deployment across the sector. Amazon Web Services leverages its specialized genomics pipelines to anchor workloads from large sequencing centers. Microsoft Azure sustains competitive positioning through integrated compliance frameworks that map directly to FDA validation requirements. Google Cloud specializes in AI-accelerated drug discovery workloads, differentiating its tensor processing infrastructure for molecular simulation demands.
Cloud computing IaaS in life science denotes on-demand provisioning of virtualized compute, storage, and networking resources over the internet, with infrastructure typically housed in geographically distributed data centers meeting ISO 27001 and SOC 2 Type II specifications. These platforms enable elastic scaling of genomic alignment pipelines, electronic trial master file repositories, and real-world evidence analytics without capital-intensive server ownership. Hybrid cloud deployments now capture the dominant margin pool as pharmaceutical developers balance burst-compute elasticity for drug discovery against private cloud mandates for patient-identifiable clinical records. Security services represent the fastest-expanding service type segment, driven by escalating data residency requirements and cross-border clinical protocol complexity.
FDA 21 CFR Part 11, HIPAA, and EMA GxP data integrity guidelines collectively shape platform architecture decisions and vendor qualification pathways across the United States and European markets. China's NMPA cybersecurity provisions for human genetic data further constrain cross-border infrastructure choices for multinationals operating in that jurisdiction. Stakeholders must evaluate sovereignty-aligned data center footprints against unified global analytics architectures as regulatory fragmentation intensifies.
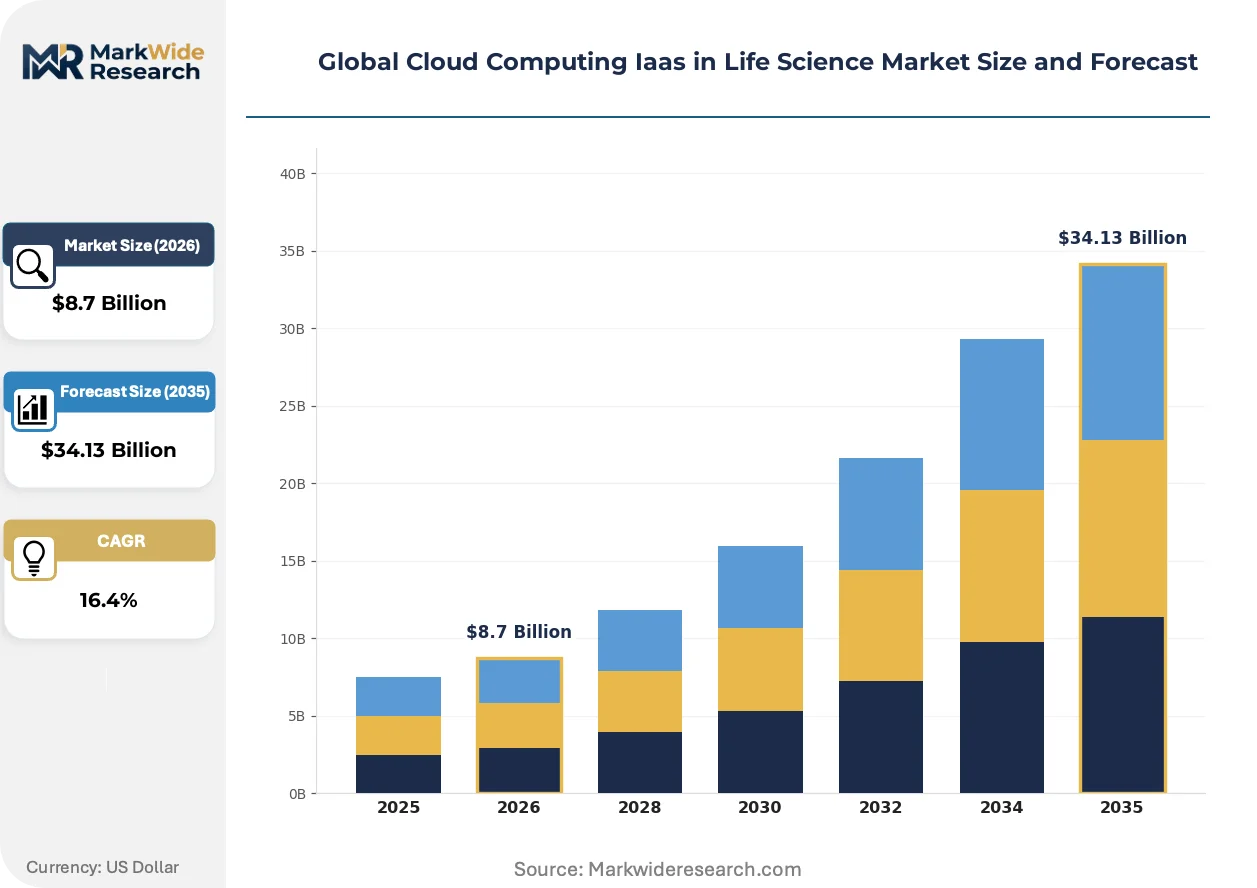
Market Dynamics
Hybrid cloud architectures are fragmenting infrastructure procurement decisions as pharmaceutical developers weigh burst-compute elasticity against sovereign data mandates for patient records.
Growth Catalysts
- FDA 21 CFR Part 11:Validated platform requirements accelerate enterprise-grade IaaS adoption for electronic records management in clinical trials.
- Genomic sequencing centers:Exponential data generation from CRISPR workflows and whole-genome analysis drives elastic storage demand.
- Real-world evidence analytics:Post-market surveillance requirements expand compute-intensive pharmacovigilance workloads onto cloud infrastructure.
Market Restraints
- Data residency mandates:China's NMPA cybersecurity provisions for human genetic data force duplicative regional infrastructure builds.
- Specialized compliance talent:Scarcity of professionals credentialed in both GxP frameworks and cloud architecture constrains deployment velocity.
- Legacy validation debt:On-premise electronic trial master file systems require costly requalification for hybrid cloud migration.
Strategic Opportunities
- India's CDSCO-aligned data centers:Emerging biopharma manufacturing hubs create demand for GxP-certified regional cloud infrastructure.
- AI-accelerated molecular simulation:Convergence of tensor processing units and physics-based drug design opens high-margin specialized compute tiers.
- Consumption-based HPC leasing:Pay-per-alignment models for genomic pipelines reduce capital barriers for mid-tier research institutions.
Industry Challenges
- Cross-border protocol complexity:Multi-regional clinical trials require simultaneous compliance with FDA, EMA, and NMPA data integrity guidelines.
- Interoperability with validated systems:Integration friction between cloud-native analytics and legacy 21 CFR Part 11-compliant document repositories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Computing Iaas in Life Science Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud End User: Biotechnology Firms, Pharmaceutical Developers, Academic Research Institutes, Contract Research Organizations Service Type: Compute Resources, Storage Solutions, Networking Infrastructure, Security Services, Data Analytics Application: Genomic Research, Clinical Data Management, Drug Discovery, Regulatory Compliance |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, IBM Corporation, Oracle Corporation, VMware, Inc., Dell Inc., Cleardata Networks, Inc., Carecloud Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Computing Iaas in Life Science Market Shifts & Advancements
Containerized workload orchestration is compressing deployment timelines for regulated environments while specialized silicon for biological computation reshapes vendor differentiation strategies.
Serverless computing architectures for genomic alignment pipelines are rendering obsolete fixed-capacity cluster provisioning in sequencing facilities. Large research centers in the United States and Germany now deploy burst-scale compute without perpetual infrastructure ownership. This shift is compressing capital allocation cycles from multi-year depreciation schedules to monthly operational expenditure lines.
EMA GxP data integrity guidelines now mandate audit trails extending to infrastructure-as-code configurations. European pharmaceutical developers must validate automated deployment scripts with the same rigor as analytical software. Contract research organizations operating across Germany, Switzerland, and the Netherlands are rebuilding quality management systems to capture infrastructure change controls.
Subscription-based access to pre-validated compliance environments is displacing custom-built private cloud installations among emerging biotech firms. These buyers prioritize time-to-inspection-readiness over architectural customization. The model concentrates demand in the United States and United Kingdom where venture-funded drug developers face accelerated IND filing timelines.
Global Cloud Computing Iaas in Life Science Market Segmentation
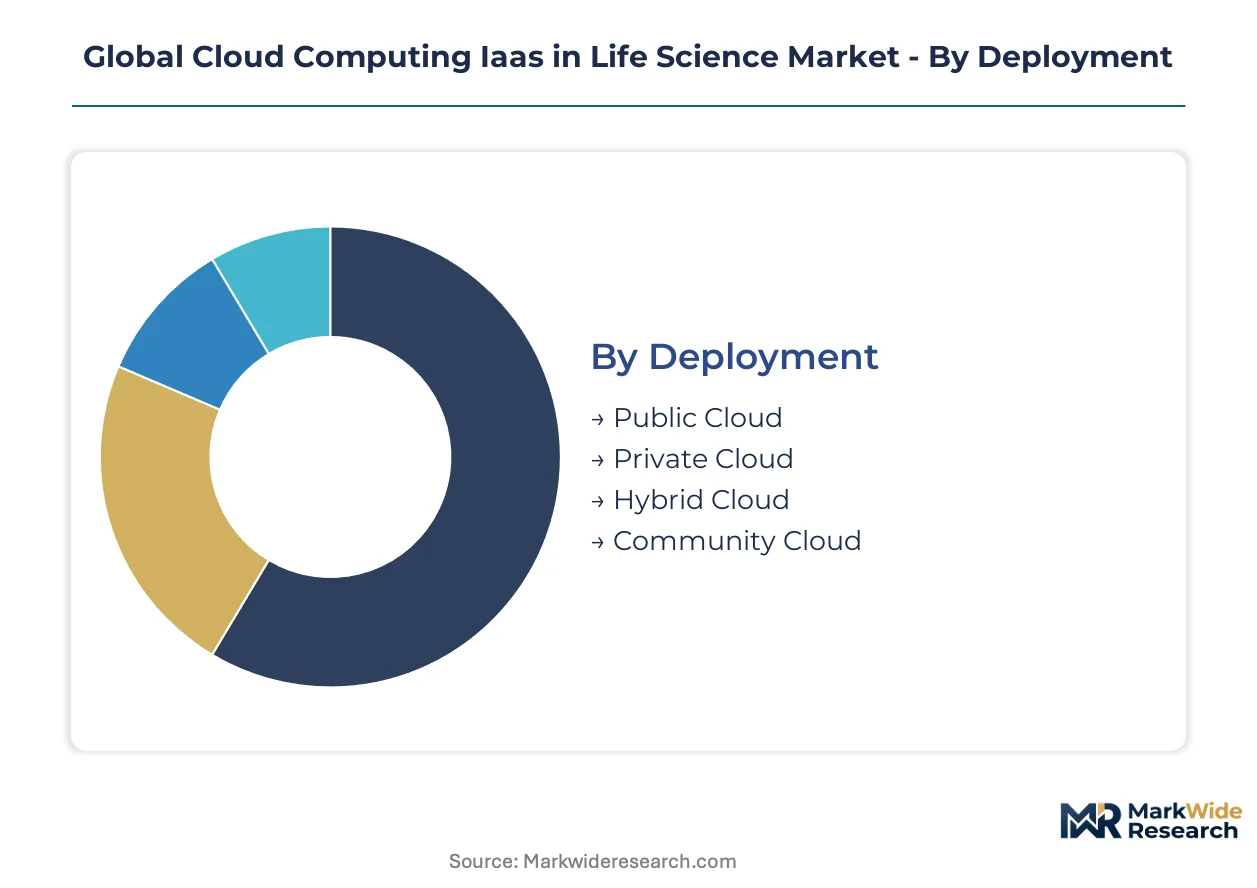
Cloud infrastructure procurement in life sciences fragments across deployment architectures, end-user sophistication, and regulatory exposure levels. Each segmentation dimension reveals distinct margin profiles and vendor qualification pathways that reshape competitive positioning.
Deployment:
Life science workloads span burst-compute genomics to sovereign-mandated patient records, creating divergent infrastructure ownership models.
- Hybrid Cloud:Elastic public resources for drug discovery pipelines pair with private enclaves for HIPAA-controlled clinical data. Pharmaceutical developers in the United States and Germany anchor procurement here, balancing FDA 21 CFR Part 11 validation against CRISPR workload scalability.
- Public Cloud:On-demand virtualized compute and storage without dedicated physical infrastructure. Academic sequencing centers and emerging biotech firms concentrate demand, drawn by consumption-billing models that eliminate capital depreciation cycles.
- Private Cloud:Single-tenant infrastructure with dedicated hardware for maximum data sovereignty control. Contract research organizations managing multi-site Phase III trials deploy this model to satisfy EMA GxP audit trail requirements.
- Community Cloud:Shared infrastructure among organizations with common compliance frameworks or research consortia. European rare disease research networks leverage this model to pool validated environments while maintaining GDPR-aligned data residency.
The dominant share belongs to Hybrid Cloud, while Public Cloud is closing the gap fastest among venture-funded drug developers.
End User:
Procurement sophistication varies sharply across buyer technical capacity and regulatory burden tolerance.
- Pharmaceutical Developers:Enterprise-scale buyers with dedicated cloud architecture teams and established FDA validation protocols. These organizations drive demand for pre-qualified GxP environments and integrated compliance documentation systems.
- Biotechnology Firms:Mid-scale innovators prioritizing time-to-inspection-readiness over architectural customization. United States and United Kingdom venture-backed developers concentrate here, accelerating IND filing timelines through subscription-based validated platforms.
- Contract Research Organizations:Multi-client service providers requiring simultaneous compliance with FDA, EMA, and NMPA data integrity guidelines. Cross-border protocol complexity forces redundant infrastructure builds across jurisdictions.
- Academic Research Institutes:Budget-constrained sequencers exploiting burst-scale compute without perpetual ownership. Serverless genomic alignment pipelines now displace fixed-capacity clusters at major United States and German university centers.
Pharmaceutical Developers command infrastructure spending volume, though Biotechnology Firms are expanding their share most steeply.
Service Type:
Margin concentration shifts toward specialized capabilities as generic compute commoditizes.
- Security Services:Encryption, identity management, and threat monitoring tailored to HIPAA and 21 CFR Part 11 requirements. Escalating data residency mandates and cross-border clinical protocol complexity propel expansion.
- Data Analytics:Real-world evidence processing, pharmacovigilance signal detection, and molecular simulation platforms. AI-accelerated drug discovery workloads differentiate tensor processing infrastructure offerings.
- Compute Resources:Virtualized CPU and GPU clusters for elastic workload scaling. Genomic alignment pipelines and electronic trial master file repositories anchor demand.
- Storage Solutions:Tiered data persistence for hot, warm, and cold genomic datasets. Exponential CRISPR workflow output drives petabyte-scale elastic capacity requirements.
- Networking Infrastructure:Low-latency interconnects for multi-site clinical data synchronization and hybrid cloud traffic management.
Security Services capture margin expansion fastest, while Compute Resources retain the largest revenue base.
Application:
Workload characteristics dictate infrastructure performance requirements and validation rigor.
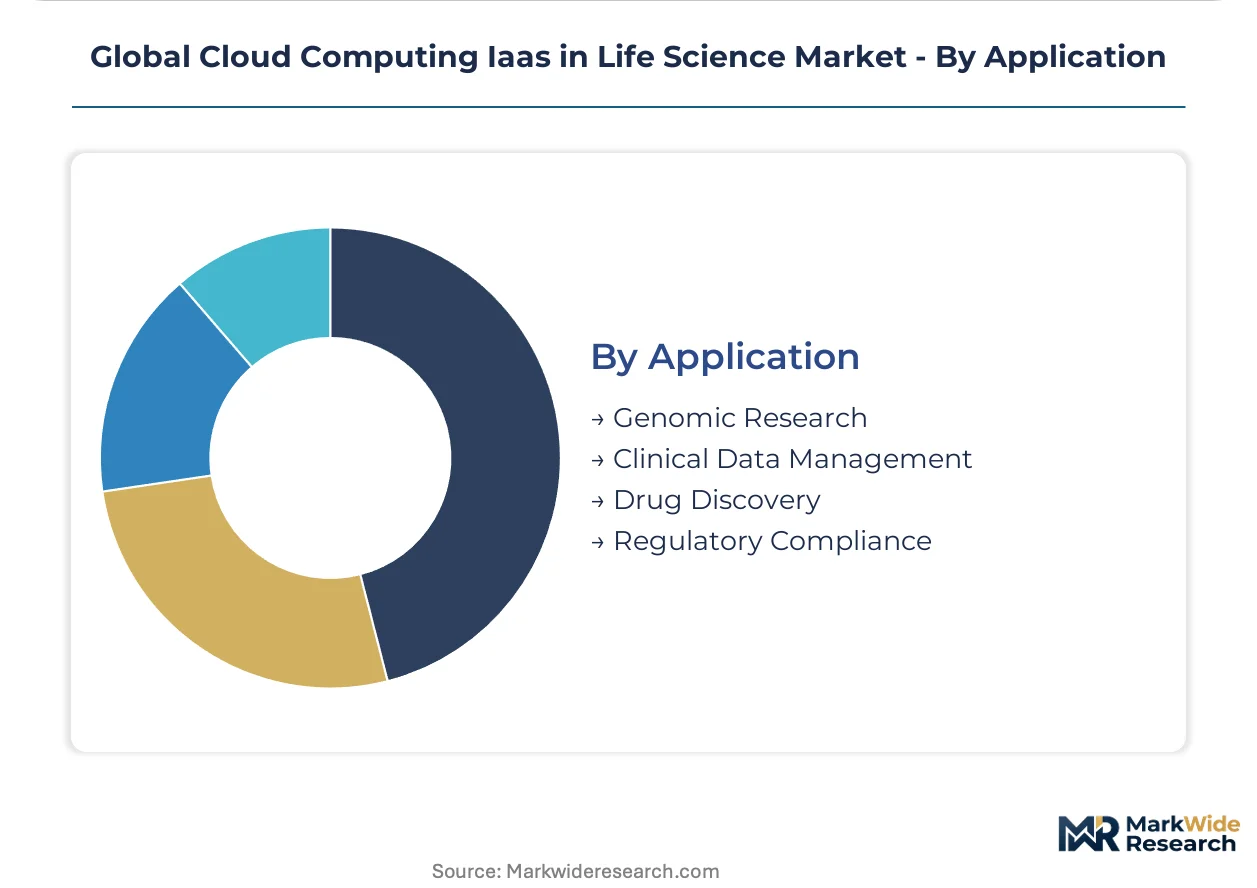
- Clinical Data Management:Electronic trial master file repositories, patient registries, and regulatory submission systems. FDA 21 CFR Part 11 and EMA GxP data integrity guidelines mandate validated platform investments with exhaustive audit trails.
- Genomic Research:Whole-genome sequencing alignment, variant calling, and CRISPR analysis pipelines. Burst-compute elasticity requirements favor hybrid architectures at major United States and China sequencing centers.
- Drug Discovery:Physics-based molecular simulation, AI-accelerated compound screening, and target identification workflows. Tensor processing unit specialization creates vendor differentiation in this high-margin segment.
- Regulatory Compliance:Automated quality management systems, infrastructure-as-code validation, and inspection-readiness documentation. EMA guidelines now mandate audit trails extending to deployment scripts themselves.
Clinical Data Management dominates procurement value, yet Genomic Research is scaling most rapidly as sequencing costs collapse.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where validated platform premiums offset infrastructure costs, while Chinese operators absorb duplicative regional build expenses under NMPA genetic data mandates.
United States
Pharmaceutical developers in Greater Boston and the San Francisco Bay Area anchor enterprise IaaS procurement for clinical trial data management. FDA 21 CFR Part 11 compliance requirements accelerate investments in pre-qualified GxP environments with exhaustive audit trails. Amazon Web Services and Microsoft Azure maintain dominant positions through specialized genomics pipelines and integrated validation frameworks.
Germany
Heidelberg and Munich host Europe's densest biopharma R&D clusters driving hybrid cloud demand for CRISPR workload elasticity. EMA GxP data integrity guidelines mandate infrastructure-as-code audit trails extending to automated deployment scripts. Contract research organizations across Baden-Württemberg and Bavaria rebuild quality management systems to capture these compliance requirements.
China
Shanghai and Beijing sequencing centers generate petabyte-scale genomic data requiring burst-compute elasticity. NMPA cybersecurity provisions for human genetic data force multinationals into duplicative regional infrastructure builds with strict data residency controls. Domestic cloud operators capture sovereign-mandated workloads while foreign vendors face jurisdictional constraints.
United Kingdom
Venture-funded biotech firms in Cambridge and London prioritize subscription-based validated platforms to accelerate IND filing timelines. GDPR-aligned data residency requirements intersect with MHRA post-Brexit regulatory autonomy. Emerging drug developers displace custom private cloud installations with inspection-readiness-focused procurement models.
India
Hyderabad and Bangalore biopharma manufacturing hubs create demand for CDSCO-aligned regional cloud infrastructure. Government production-linked incentive schemes expand contract research capacity requiring GxP-certified compute environments. Mid-tier research institutions adopt consumption-based HPC leasing to eliminate capital depreciation cycles for genomic pipelines.
Global Cloud Computing Iaas in Life Science Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying specialized compute and storage layers. The vendor base consolidates around three hyperscale providers with differentiated vertical specializations, while niche compliance-focused operators fragment the regulated sub-segment. Strategic archetypes include validated-environment specialists, AI-accelerated infrastructure providers, and sovereign-data-mandate regional operators. Competitive moves concentrate on compliance framework integration and tensor processing specialization for molecular simulation workloads.
Among hyperscale platform providers, Amazon Web Services, Microsoft Azure, and Google Cloud occupy distinct positioning vectors. Amazon Web Services anchors genomic sequencing center workloads through specialized pipeline architectures. Microsoft Azure exemplifies the compliance-integrated archetype with direct FDA validation requirement mappings. Google Cloud represents AI-accelerated specialization through tensor processing infrastructure for drug discovery applications.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| IBM Corporation |
| Oracle Corporation |
| VMware, Inc. |
| Dell Inc. |
| Cleardata Networks, Inc. |
| Carecloud Corporation |
| Others |
Supply & Pricing Matrix
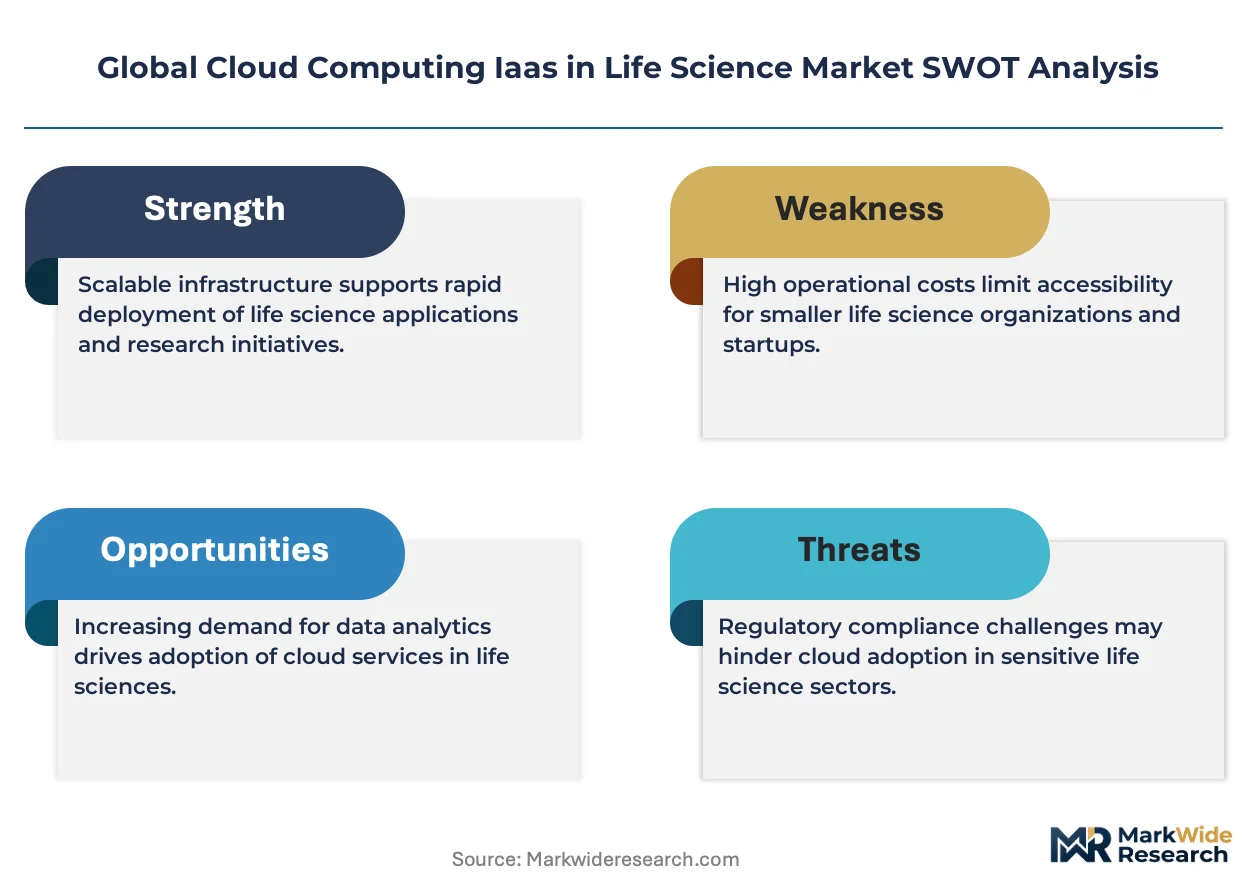
Regulatory chokepoint exposure at data sovereignty boundaries determines both tiered pricing spreads across validated environments and the geographic distribution of infrastructure assets. NMPA genetic data mandates and FDA 21 CFR Part 11 compliance requirements force pharmaceutical developers into duplicative regional builds that compress margins on standard compute tiers while amplifying premiums for pre-qualified GxP environments.
Pricing Analysis
Pharmaceutical developers anchor pricing structures around subscription-based validated platform tiers with consumption-billing overlays for burst-compute genomics. Price differentiation hinges on FDA pre-qualification status and data residency certification grade, with sovereign-mandated private enclaves commanding substantial premiums over standard public instances. Cost compression in mid-tier hybrid deployments is intensifying as hyperscale providers standardize compliance automation tooling. Academic sequencing centers exhibit the highest price sensitivity, while contract research organizations managing multi-regional Phase III trials demonstrate the lowest sensitivity due to pass-through client billing structures.
Supply Chain Analysis
Extended payment terms from hyperscale cloud providers to specialized silicon manufacturers are compressing working capital cycles for tensor processing unit suppliers. Infrastructure hardware concentrates in Taiwan, South Korea, and the United States for advanced semiconductor fabrication, while data center construction materials draw from China, Germany, and India. Single-source vulnerability in specialized AI accelerator chips creates exposure to export control restrictions. Distribution runs through direct enterprise sales teams for pharmaceutical developers and channel partners for mid-tier biotechnology firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of professionals credentialed simultaneously in GxP frameworks and cloud architecture is constraining deployment velocity and amplifying vendor switching costs across the sector.
For Market Incumbents: Harden compliance automation moats by embedding infrastructure-as-code validation directly into deployment pipelines, insulating against emerging specialists offering pre-validated subscription environments. Deepen upstream control over specialized silicon supply through long-term capacity reservations with Taiwan Semiconductor Manufacturing and Samsung Foundry, securing tensor processing unit allocation for molecular simulation workloads. For New Entrants and Emerging Players: Build out CDSCO-aligned regional cloud infrastructure in Hyderabad and Bangalore, capturing production-linked incentive scheme tailwinds as Indian biopharma manufacturing expands. Target mid-tier research institutions with consumption-based HPC leasing for genomic alignment pipelines, displacing fixed-capacity cluster ownership through pay-per-alignment pricing models. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors compliance-integrated platform specialists over pure infrastructure commodity providers. Acquisition targets should demonstrate validated-environment expertise with direct FDA 21 CFR Part 11 mapping capabilities and established quality management system documentation. Watch hyperscaler capex allocation shifts toward life science verticals as the primary inflection indicator for sector investment intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Validated Compliance Environment Launch | Reduces time-to-inspection-readiness for biotechnology firms facing accelerated IND filing timelines. |
| Tensor Processing Infrastructure Specialization | Captures high-margin AI-accelerated molecular simulation workloads from pharmaceutical developers. |
| Regional Data Sovereignty Buildout | Satisfies NMPA genetic data mandates and GDPR residency requirements for cross-border clinical trials. |
| Consumption-Based HPC Leasing Model | Eliminates capital depreciation barriers for academic sequencing centers and mid-tier research institutions. |
| Infrastructure-as-Code Validation Integration | Meets EMA GxP audit trail requirements extending to automated deployment scripts. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cloud architecture directors, regulatory affairs leads at pharmaceutical developers, GxP compliance officers, and sequencing center IT directors; and secondary validation against FDA 21 CFR Part 11 guidance documents, EMA GxP data integrity guidelines, NMPA cybersecurity provisions, hyperscaler capex disclosures, and clinical trial registration databases. Bottom-up demand modeling from end-user procurement patterns triangulated against top-down infrastructure spending estimates across the United States, Germany, China, United Kingdom, and India.
Forecast inputs incorporated deployment architecture splits, end-user sophistication tiers, service type margin trajectories, and application workload growth patterns across the projection horizon. Segmentation dimensions modeled include hybrid-public-private-community cloud deployment models, pharmaceutical developer-biotechnology firm-CRO-academic institute buyer archetypes, and clinical data management-genomic research-drug discovery-regulatory compliance application categories. CAGRs were derived from elasticity-adjusted infrastructure demand curves and validated platform adoption S-curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion moves by sovereign-data-mandate regional operators would shift outcomes substantially. Macroeconomic tightening in venture funding for biotechnology firms, regulatory fragmentation acceleration across FDA-EMA-NMPA jurisdictions, or breakthroughs in on-premise quantum computing for molecular simulation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Web Scale IT Market
Cloud Computing
Cloud Management Market
Cloud Computing
Cloud Backup Market
Cloud Computing
North America Professional Cloud Services Market
Cloud Computing
Cloud Applications Market
Cloud Computing
South Korea Cloud Computing Market
Cloud Computing
Multi-Cloud Architecture Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
Canada Cloud Computing Market
Cloud Computing
Global Hybrid and Community Cloud As a Service Market
Cloud Computing
Multi-Cloud Networking Market
Cloud Computing
Cloud Load Balancers Market
Cloud Computing
Android Cloud Phone Market
Cloud Computing
Philippines ICT Market
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
Community Cloud Market