
 Enterprise Application Market | 2026-2036
Enterprise Application Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Application Market Analysis
Subscription-based financing and asset-light SaaS licensing is reconfiguring competitive entry barriers for mid-sized vendors. Oracle Corporation leverages its database heritage to anchor high-margin ERP contracts with government and defense clients. SAP SE sustains deep R&D intensity in supply chain analytics, while Salesforce.com Inc. differentiates through vertical-specific CRM modules for healthcare and financial services.
Enterprise applications denote integrated software suites that automate core business processes through modular architectures, typically deployed via multi-tenant cloud infrastructure or on-premise server clusters with API-based interoperability standards. Their primary commercial purpose centers on unifying data workflows across finance, operations, and customer-facing functions to reduce latency in decision-making. Cloud-based and SaaS deployment models now capture the fastest expansion as enterprises abandon capital-intensive on-premise hardware refresh cycles, while ERP retains the largest installed base and renewal revenue pool among product types. CRM modules command premium pricing in regulated verticals where patient data or financial records require audit-trail compliance.
FDA oversight of clinical trial data integrity, HIPAA privacy safeguards, and SEC disclosure requirements for financial reporting systems collectively elevate compliance spending within enterprise software procurement. The EU AI Act and GDPR cross-border data transfer rules further constrain architecture choices for multinational deployments. Stakeholders must weigh jurisdictional fragmentation against platform consolidation when selecting deployment geography and vendor certification tiers.
Market Dynamics
Cloud migration mandates from HIPAA-covered healthcare entities and SEC-registered financial firms are compressing on-premise infrastructure refresh cycles while elevating compliance-certified SaaS procurement.
Growth Catalysts
- HIPAA Privacy Rule enforcement:Healthcare providers in the United States must demonstrate audit-trail integrity for patient data, accelerating demand for cloud-native ERP with built-in encryption and access logging.
- AI-enabled predictive analytics:Supply chain modules embedding machine learning for demand forecasting are capturing renewal premiums from manufacturing clients managing multi-tier supplier networks.
- India:PLI scheme incentives for electronics manufacturing are driving factory-floor digitization, creating fresh demand for MES-integrated ERP deployments among contract manufacturers.
Market Restraints
- EU AI Act cross-border friction:Risk-classification requirements for automated decision systems are forcing architectural fragmentation, raising deployment costs for multinational SaaS vendors serving European subsidiaries.
- Specialized compliance engineering talent:Scarcity of professionals certified in both FDA 21 CFR Part 11 and GDPR Article 32 technical measures is extending implementation timelines for life sciences clients.
- Legacy mainframe dependency:Core banking systems at regional financial institutions in Japan retain COBOL-based transaction processing, creating API interoperability gaps that block cloud-native CRM integration.
Strategic Opportunities
- Brazil:ANVISA's phased electronic submission mandates for pharmaceutical quality management are opening whitespace for validated document management modules with Portuguese-language localization.
- Edge-to-cloud orchestration:Convergence of 5G private networks with containerized microservices is enabling real-time inventory tracking for warehouse operators without full cloud dependency.
- CSRD sustainability reporting:The EU Corporate Sustainability Reporting Directive is mandating granular emissions data collection, creating attach-rate opportunities for ESG modules within existing ERP contracts.
Industry Challenges
- Multi-jurisdiction certification stacking:Vendors serving FDA-regulated biotechs with European operations must maintain parallel validation documentation for 21 CFR Part 11 and EMA Annex 11, doubling quality assurance overhead.
- Technical debt in custom code:Decades of client-specific ABAP and Java extensions in installed SAP and Oracle bases are blocking clean lift-and-shift migrations, forcing expensive refactoring or hybrid architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Application Market |
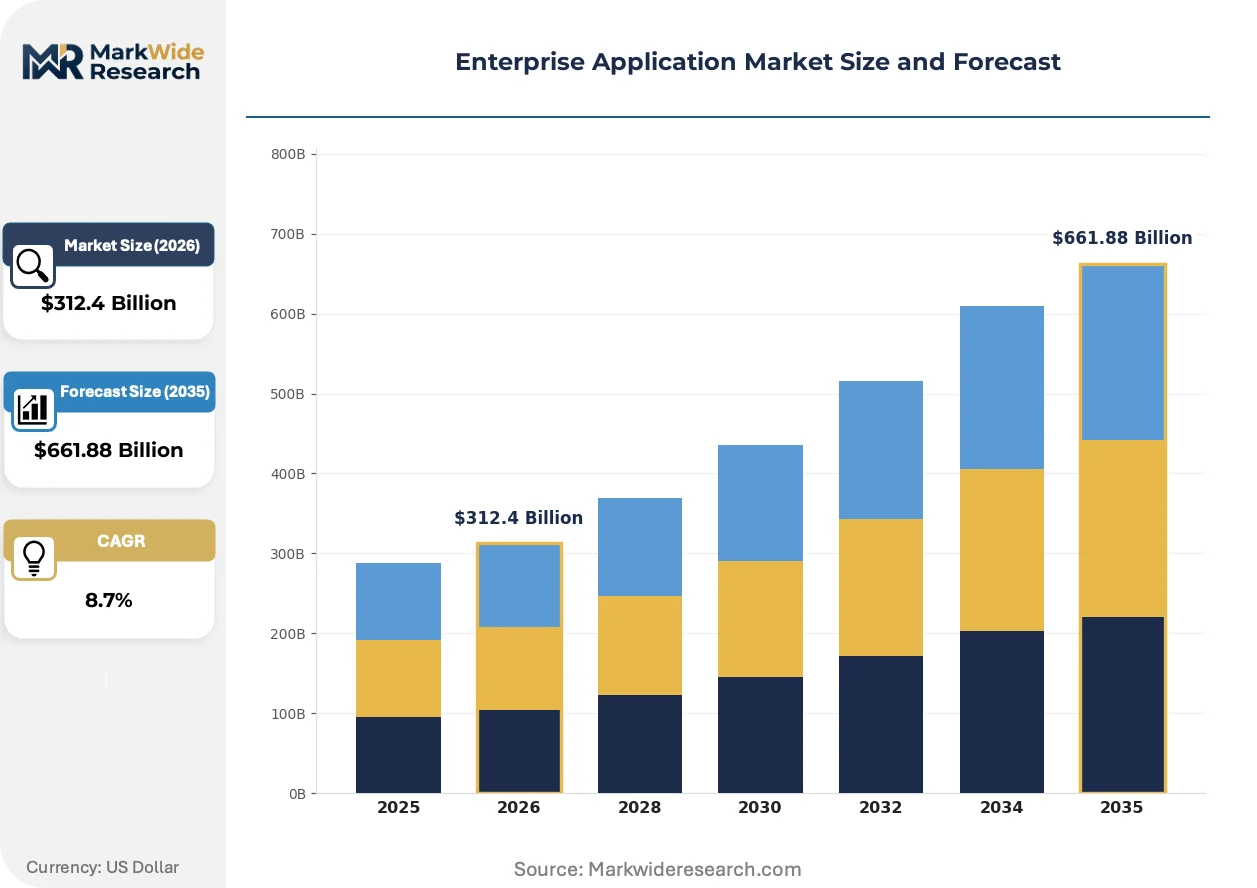
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $661.88 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CRM, ERP, SCM, HCM Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Small Enterprises, Medium Enterprises, Large Corporations, Startups Industry Vertical: Healthcare, Finance, Retail, Manufacturing |
| Companies Covered | Microsoft Corporation, Oracle Corporation, SAP SE, Salesforce.com Inc., International Business Machines Corporation, Google LLC, Amazon Web Services, ServiceNow Inc., Adobe Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Application Market Emerging Trajectories
Generative AI copilots and low-code configuration layers are compressing implementation timelines while redefining the boundary between platform and professional services revenue.
Containerized microservices architecture is virtualizing the traditional monolithic ERP stack. Mid-market manufacturers in Germany are adopting Kubernetes-orchestrated finance modules to isolate upgrade cycles from core operations. This decomposition is virtualizing vendor lock-in, allowing procurement teams to swap individual functional components without platform-wide renegotiation.
GDPR Article 44 adequacy decisions and the EU-US Data Privacy Framework are reshaping data residency architecture. SaaS providers must now maintain logically separated tenant environments with encryption key sovereignty guarantees for European healthcare clients. Financial services firms in France are responding by demanding CNIL-audited subprocessors with EU-only data processing commitments.
Subscription consumption models are displacing perpetual license maintenance for analytics workloads. Industrial equipment OEMs in the United States now meter BI dashboard access by query volume rather than named user count. This shift is most visible among defense contractors navigating DCAA audit requirements, where usage-based pricing aligns software costs with contract-funded project phases.
Enterprise Application Market Segmentation
Enterprise application procurement cycles vary dramatically across deployment modes and end-user scale. Understanding these velocity differences allows vendors to align R&D roadmaps with renewal timing and compliance refresh windows.
Product Type:
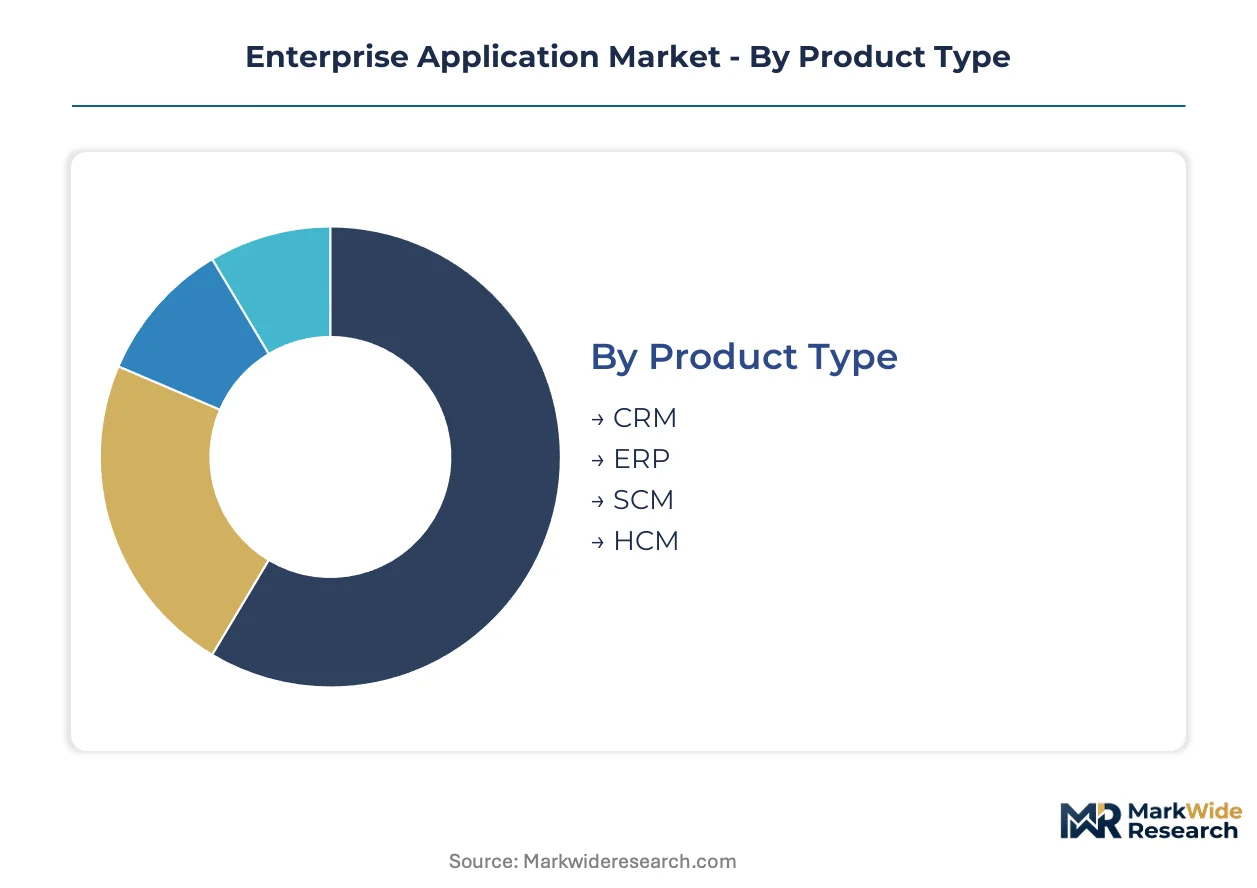
ERP modules carry the longest replacement cycles at seven to ten years, while CRM refreshes accelerate as customer data platforms evolve. SCM and HCM occupy intermediate positions shaped by supply chain disruption frequency and workforce regulatory changes.
- CRM:Customer relationship management suites integrate sales force automation, marketing orchestration, and service desk functionality into unified data repositories. HIPAA-covered healthcare providers in the United States are replacing legacy contact management with consent-aware engagement platforms that embed audit-trail logging for patient communications.
- ERP:Enterprise resource planning systems consolidate financial accounting, procurement, and human capital workflows through centralized ledger architectures. Manufacturing headquarters in Germany retain these as anchor investments, though modular decomposition is fragmenting renewal decisions across functional boundaries.
- SCM:Supply chain management applications optimize inventory positioning and supplier collaboration through demand-sensing algorithms.
- HCM:Human capital management platforms automate payroll, benefits administration, and talent acquisition pipelines.
ERP dominates installed base. CRM is where expansion concentrates.
Deployment:
Cost tier stratification separates capital-intensive on-premise installations from operational expenditure SaaS contracts, with hybrid architectures occupying a complex middle ground that preserves legacy integration while capturing cloud elasticity.
- Cloud-Based:Multi-tenant infrastructure delivers elastic compute and storage through subscription contracts with geographically distributed availability zones. SEC-registered financial firms are mandating cloud-native architectures with encryption key sovereignty to satisfy audit requirements for financial reporting systems.
- SaaS:Software-as-a-service models abstract infrastructure management entirely, delivering functional capabilities through browser-based interfaces with automatic feature updates. Defense contractors navigating DCAA audit requirements favor usage-based pricing that aligns software costs with contract-funded project phases.
- On-Premise:Self-managed server clusters retain data within organizational firewalls, preserving direct control over security patching and compliance certification.
- Hybrid:Split architectures maintain sensitive workloads on private infrastructure while bursting transactional volumes to public cloud resources.
On-premise retains renewal revenue concentration. SaaS is climbing the fastest.
End User:
Customer maturity and procurement sophistication create distinct engagement patterns, from startup experimentation with low-code configurations to large corporation enterprise architecture governance with multi-year vendor certification programs.
- Large Corporations:Global enterprises operate centralized procurement functions with dedicated vendor management offices and standardized security assessment frameworks. These organizations in France are demanding CNIL-audited subprocessors with EU-only data processing commitments for sensitive personnel records.
- Medium Enterprises:Mid-market manufacturers in Germany are adopting Kubernetes-orchestrated finance modules to isolate upgrade cycles from core operations without full platform replacement.
- Small Enterprises:Resource-constrained organizations prioritize rapid deployment and minimal IT overhead over customization depth.
- Startups:Venture-backed new entrants favor consumption-based pricing and API-first architectures that scale with headcount growth.
Large corporations anchor vendor profitability. Medium enterprises are gaining share fastest.
Industry Vertical:
Regulatory intensity and data sensitivity create divergent compliance engineering requirements, with healthcare and finance demanding certified modules while retail and manufacturing prioritize throughput optimization.
- Healthcare:Clinical and administrative systems must embed HIPAA Privacy Rule safeguards with encryption, access logging, and business associate agreement management. United States hospital systems are accelerating cloud-native ERP procurement to demonstrate audit-trail integrity for patient data under intensified enforcement.
- Finance:Banking and capital markets applications require SEC disclosure compliance, SOX internal controls, and real-time transaction processing with sub-second latency guarantees.
- Retail:Omnichannel commerce platforms integrate point-of-sale, inventory visibility, and customer loyalty programs across physical and digital touchpoints.
- Manufacturing:Factory-floor systems connect MES, quality management, and supplier portals through industrial IoT data streams.
Healthcare commands premium pricing. Manufacturing shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud migration mandates from HIPAA-covered healthcare entities and SEC-registered financial firms are compressing on-premise infrastructure refresh cycles while elevating compliance-certified SaaS procurement across national markets.
United States
Hospital systems are accelerating cloud-native ERP procurement to demonstrate audit-trail integrity for patient data under intensified HIPAA Privacy Rule enforcement. Defense contractors navigating DCAA audit requirements favor usage-based pricing that aligns software costs with contract-funded project phases. Industrial equipment OEMs in the Midwest now meter BI dashboard access by query volume rather than named user count.
Germany
Manufacturing headquarters retain ERP as anchor investments, though modular decomposition fragments renewal decisions across functional boundaries. Mid-market manufacturers are adopting Kubernetes-orchestrated finance modules to isolate upgrade cycles from core operations without full platform replacement. The KBA-regulated automotive sector drives demand for supply chain modules embedding machine learning for demand forecasting.
India
PLI scheme incentives for electronics manufacturing are driving factory-floor digitization, creating fresh demand for MES-integrated ERP deployments among contract manufacturers. CDSCO oversight of clinical trial data integrity elevates compliance spending within enterprise software procurement for pharmaceutical exporters. Bengaluru and Hyderabad host expanding delivery centers for global SaaS vendors serving healthcare and financial services verticals.
Brazil
ANVISA's phased electronic submission mandates for pharmaceutical quality management are opening whitespace for validated document management modules with Portuguese-language localization. Regional financial institutions retain COBOL-based transaction processing, creating API interoperability gaps that block cloud-native CRM integration. São Paulo anchors Latin American headquarters for multinational ERP vendors targeting regulated verticals.
Japan
Core banking systems at regional financial institutions retain COBOL-based transaction processing, creating API interoperability gaps that block cloud-native CRM integration. METI industrial digitization programs subsidize edge-to-cloud orchestration pilots for warehouse operators seeking real-time inventory tracking. Tokyo and Osaka concentrate R&D investment from vendors adapting supply chain analytics for multi-tier supplier networks.
Enterprise Application Market Vendor Landscape
Channel-controlling players compete with product-specialist players across deployment modes and vertical certifications. The vendor base stratifies into database-heritage platforms, cloud-native specialists, and vertical-specific module providers. Consolidation pressures favor incumbents with existing certification stacks over challengers facing multi-jurisdiction compliance overhead. Dominant competitive moves include M&A to acquire compliance engineering talent and strategic partnerships to embed AI copilots within existing install bases.
Within the database-heritage tier, Oracle Corporation and SAP SE exemplify platform consolidation strategies that leverage installed base renewal revenue to fund R&D intensity in supply chain analytics. Among cloud-native specialists, Salesforce.com Inc. occupies a position defined by vertical-specific CRM modules for healthcare and financial services. Microsoft Corporation anchors the productivity-integrated segment, representing the archetype of workspace-suite vendors extending into ERP adjacencies through subscription bundling.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| Salesforce.com Inc. |
| International Business Machines Corporation |
| Google LLC |
| Amazon Web Services |
| ServiceNow Inc. |
| Adobe Inc. |
| Others |
Supply Flow & Price Mechanics
Bengaluru and Hyderabad delivery centers concentrate global SaaS engineering talent, creating capacity bottlenecks that cascade into premium pricing for HIPAA-certified implementations. This geographic concentration of compliance engineering expertise directly shapes vendor pricing power across regulated verticals.
Pricing Analysis
Certification level (HIPAA/FDA-grade versus standard SOC 2) creates the primary spread between deployment tiers. Three-tier pricing structure across premium, standard, and economy levels segments by audit-trail depth and encryption key sovereignty. Cost compression in the standard tier intensifies because hyperscaler infrastructure commoditizes base compute. Large corporations exhibit lowest price sensitivity due to bundled professional services dependencies, while mid-market manufacturers negotiate hardest on per-seat licensing.
Supply Chain Analysis
Upstream cloud infrastructure feeds from hyperscaler data centers in the United States, Ireland, and Singapore, with compute capacity expansion tethered to renewable energy procurement timelines. Container orchestration platforms and API middleware rest on open-source foundations, while specialized compliance modules draw from certified engineering pools in India and Eastern Europe. Single-source vulnerability concentrates in encryption key management services. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards vendors who control scarce compliance engineering capabilities, particularly professionals certified across FDA 21 CFR Part 11 and EMA Annex 11 simultaneously. This talent bottleneck constrains expansion velocity more than capital availability.
For Market Incumbents: Entrench renewal revenue through embedded AI copilots that increase switching costs within existing ERP install bases. Acquire compliance engineering boutiques in Bengaluru and Dublin to preempt talent raids by cloud-native challengers. Prioritize Kubernetes-orchestrated module decomposition to fragment competitor replacement cycles. For New Entrants and Emerging Players: Brazil's ANVISA-validated document management whitespace offers the most penetrable entry point for Portuguese-localized SaaS modules. Target mid-market pharmaceutical exporters seeking cost alternatives to Oracle and SAP maintenance contracts. Lead with usage-based pricing aligned to electronic submission milestone payments. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate software divisions with dormant healthcare certification stacks but underutilized engineering benches. Five-to-ten-year viability hinges on AI-enabled workflow automation attach rates rather than license renewal pools. Monitor CDSCO enforcement intensity as inflection indicator for Indian pharmaceutical exporter software spending.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Certification Acquisition | FDA 21 CFR Part 11 validation shortcuts implementation timelines for life sciences clients. |
| AI Copilot Integration | Generative assistants embedded in CRM modules command renewal premiums from healthcare providers. |
| Geographic Delivery Expansion | Hyderabad engineering centers reduce HIPAA-certified implementation costs for US hospital systems. |
| Vertical Module Specialization | CSRD-aligned ESG modules attach to existing ERP contracts at European manufacturing headquarters. |
| Usage-Based Pricing Migration | Query-volume metering aligns software costs with DCAA-audited defense contract phases. |
Methodological Framework
Cross-validation between primary interviews with enterprise architects and secondary analysis of SEC 10-K filings anchors the qualitative findings. Chief technology officers, IT procurement officers, HIPAA compliance officers, and systems integration specialists provided deployment timeline and budget trajectory inputs. Bottom-up vendor revenue triangulation against top-down enterprise software spending estimates validates market sizing.
Calibration against historical replacement cycles and regulatory enforcement intensity shapes the projection framework. Segmentation dimensions span deployment model, organization size, vertical regulatory intensity, and geographic adoption pattern. CAGRs derive from fitted growth curves adjusted for compliance refresh windows. AI adoption curves and cloud migration mandates serve as primary demand-side inputs.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by hyperscaler challengers would shift outcomes. Model boundaries exclude custom code refactoring revenues and professional services attachments beyond initial implementation. Quarterly review of HIPAA enforcement actions and EU AI Act risk-classification rulings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
North America Enterprise Resource Planning Market
Software & Services
Global Time Tracking Software Market
Software & Services
Real Estate Software Market
Software & Services
Avionics Software Market
Software & Services
Global Enterprise Architecture Tools Market
Software & Services
Case Management Software (CMS) Market
Software & Services
Embedded Hypervisor Market
Software & Services
Global Smartphone Operating System (OS) Market
Software & Services
Global Award Management Software Market
Software & Services
Architecture, Engineering, and Construction (AEC) Software Market
Software & Services
Global Presentation Software Market
Software & Services
Global Journal App Market
Software & Services
Asia-Pacific Digital Signage Software Market
Software & Services
Spain Sports Management Software Market
Software & Services
Admission Management Software Market
Software & Services
Global OEE Software Market