
 Data Virtualization Cloud Market | 2026-2036
Data Virtualization Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Data Virtualization Cloud Market Analysis
Market Dynamics
The EU AI Act is broadening compliance requirements for cross-border data processing, compelling enterprises to deploy governed virtualization layers that maintain lineage and provenance across jurisdictions. IBM leverages its hybrid cloud footprint to anchor multi-tenant data fabric deployments in regulated European industries. Microsoft sustains competitive pressure through deep Azure integration, while Denodo Technologies specializes in logical data warehouse architectures that decouple physical storage from query optimization.
Technology Architecture
Data virtualization cloud denotes a middleware abstraction layer that federates queries across distributed sources—relational databases, data lakes, APIs, and streaming pipelines—without requiring physical extraction or transformation, typically operating through SQL-based query federation engines with real-time caching and semantic modeling. Hybrid Cloud deployment captures the dominant structural position as enterprises retain sensitive workloads on-premises while bursting analytics to public infrastructure; Financial Services leads industry vertical adoption due to Basel III data lineage requirements and real-time risk aggregation mandates. SMEs represent the fastest-expanding end-user tier as managed service offerings lower barrier-to-entry for governed data access.
Regulatory Environment
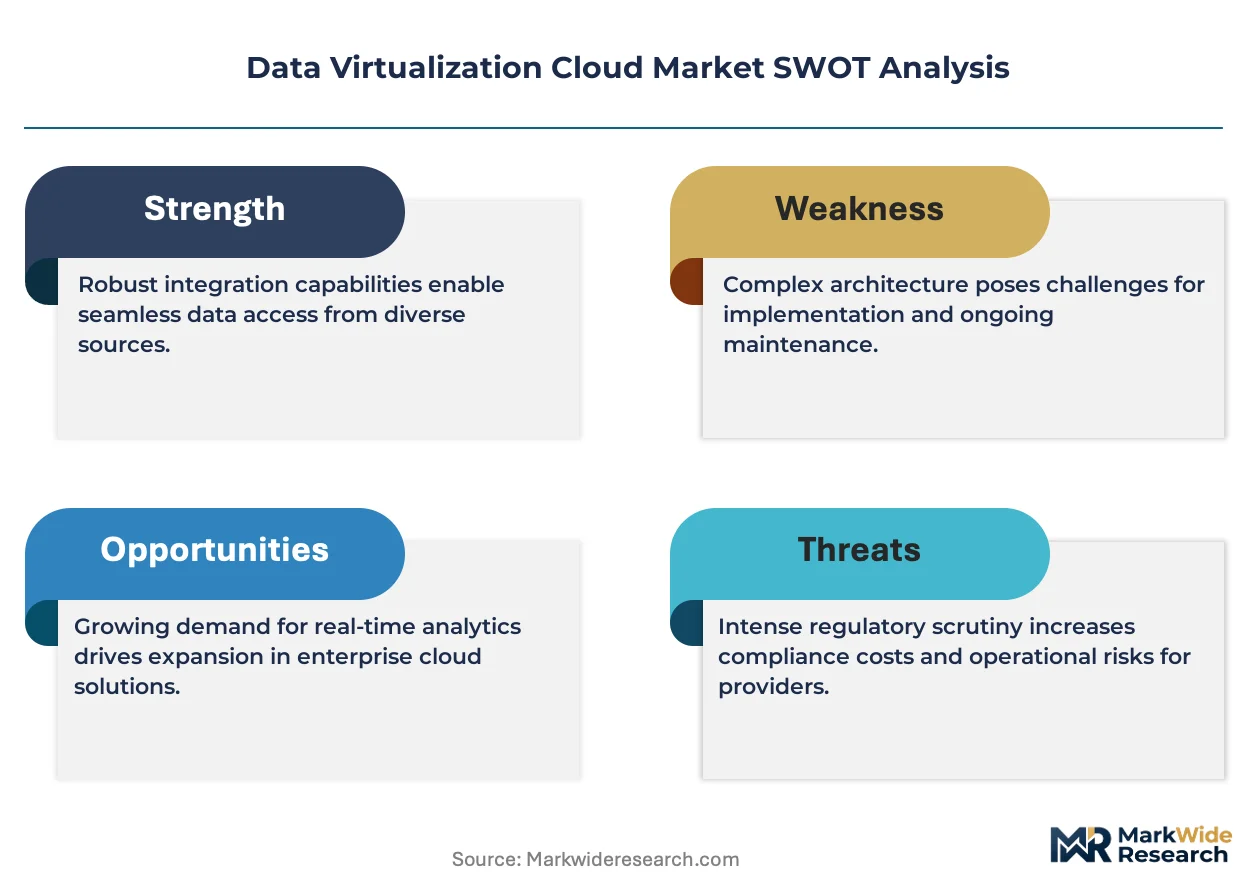
The EU GDPR and AI Act impose strict constraints on automated decision-making data flows, while the US SEC climate disclosure rules and HIPAA interoperability provisions shape product certification requirements for cloud-hosted virtualization platforms. China's Personal Information Protection Law and data localization directives add further complexity for vendors operating across jurisdictions. Stakeholders must evaluate whether their virtualization architectures can dynamically enforce jurisdiction-specific governance policies without fragmenting the unified semantic layer.
Market Dynamics
Financial institutions are consolidating fragmented analytics stacks into unified data fabrics to satisfy real-time risk aggregation mandates under Basel III, compressing procurement cycles for middleware abstraction layers that federate queries without physical data movement.
Growth Catalysts
- EU AI Act compliance:Automated decision-making governance requirements are compelling enterprises to deploy virtualization layers that maintain lineage and provenance across jurisdictions.
- Healthcare interoperability:HIPAA provisions in the United States are accelerating procurement of hybrid data platforms that enable secure cross-institutional analytics without data centralization.
- Real-time streaming pipelines:Capital markets firms require sub-millisecond query federation across distributed sources for algorithmic trading and dynamic risk scoring.
Market Restraints
- Query optimization complexity:Semantic modeling across heterogeneous schemas demands specialized engineering talent that concentrates in Silicon Valley and London financial technology clusters.
- Data residency friction:China's Personal Information Protection Law and localization directives fragment unified semantic layers, forcing redundant infrastructure deployment.
- Latency constraints:Real-time caching limitations at the edge degrade performance for geospatial analytics workloads in remote mining and logistics operations.
Strategic Opportunities
- Managed service penetration:SMEs in Germany and France are adopting consumption-based virtualization platforms that eliminate upfront infrastructure capital.
- Climate disclosure integration:The US SEC climate rules are creating demand for virtualization architectures that aggregate emissions data across supplier networks without direct system access.
- API economy convergence:GraphQL federation combined with semantic knowledge graphs is opening new application patterns in pharmaceutical supply chain traceability.
Industry Challenges
- Skill scarcity in query federation engineering:Enterprises struggle to hire architects proficient in SQL-based optimization across distributed relational and non-relational sources.
- Legacy data warehouse integration:Decades-old on-premises Teradata and Oracle installations resist seamless abstraction without costly schema refactoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Virtualization Cloud Market |
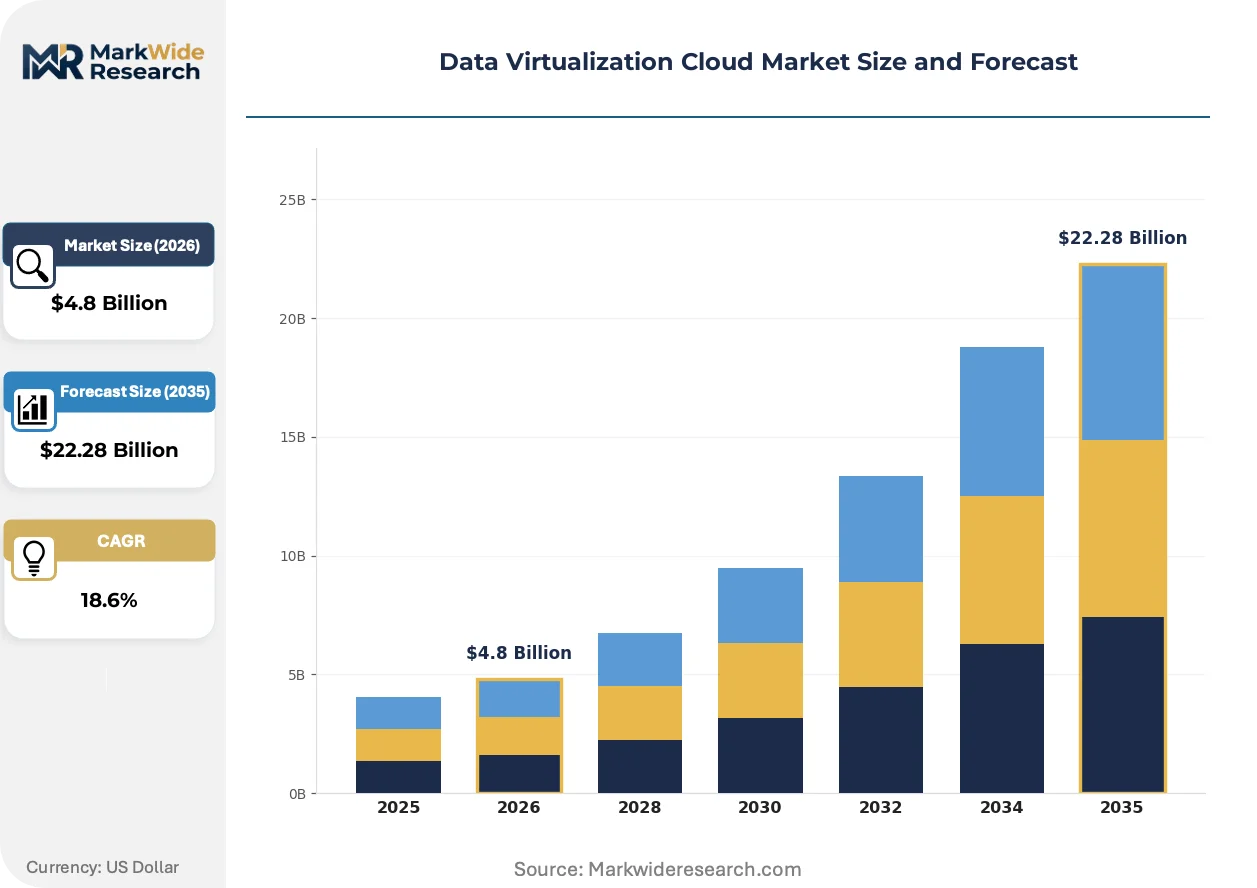
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: Enterprises, SMEs, Government Institutions, Educational Organizations Solution: Data Integration, Data Management, Analytics, Data Governance Industry Vertical: Healthcare, Retail, Financial Services, Telecommunications |
| Companies Covered | IBM, Microsoft, Oracle, Amazon Web Services, Google Cloud, Denodo Technologies, TIBCO Software, SAP, Informatica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Virtualization Cloud Market Emerging Trajectories
Semantic knowledge graphs are displacing traditional entity-relationship models as the preferred abstraction for cross-domain analytics, compressing time-to-insight for business users without technical query construction skills.
GraphQL query federation is decentralizing data access patterns by enabling frontend developers to compose unified queries across REST APIs, databases, and streaming sources without backend coordination. Retail and logistics firms in the Netherlands and Singapore are piloting these architectures for supply chain visibility. The approach collapses integration timelines from months to weeks by eliminating Extract-Transform-Load pipeline construction.
The EU AI Act's risk classification framework is mandating algorithmic audit trails that virtualization platforms must embed natively. High-risk automated decision-making systems in credit scoring and insurance underwriting now require immutable lineage records. Vendors are responding with embedded governance modules that enforce jurisdiction-specific policy enforcement without fragmenting semantic layers.
Subscription-based consumption models are displacing perpetual licensing for virtualization infrastructure, particularly among mid-market enterprises in the United Kingdom and Australia. Channel partners are bundling managed semantic modeling services with cloud compute commitments. This shift concentrates vendor revenue predictability while transferring operational complexity to service providers.
Data Virtualization Cloud Market Segmentation
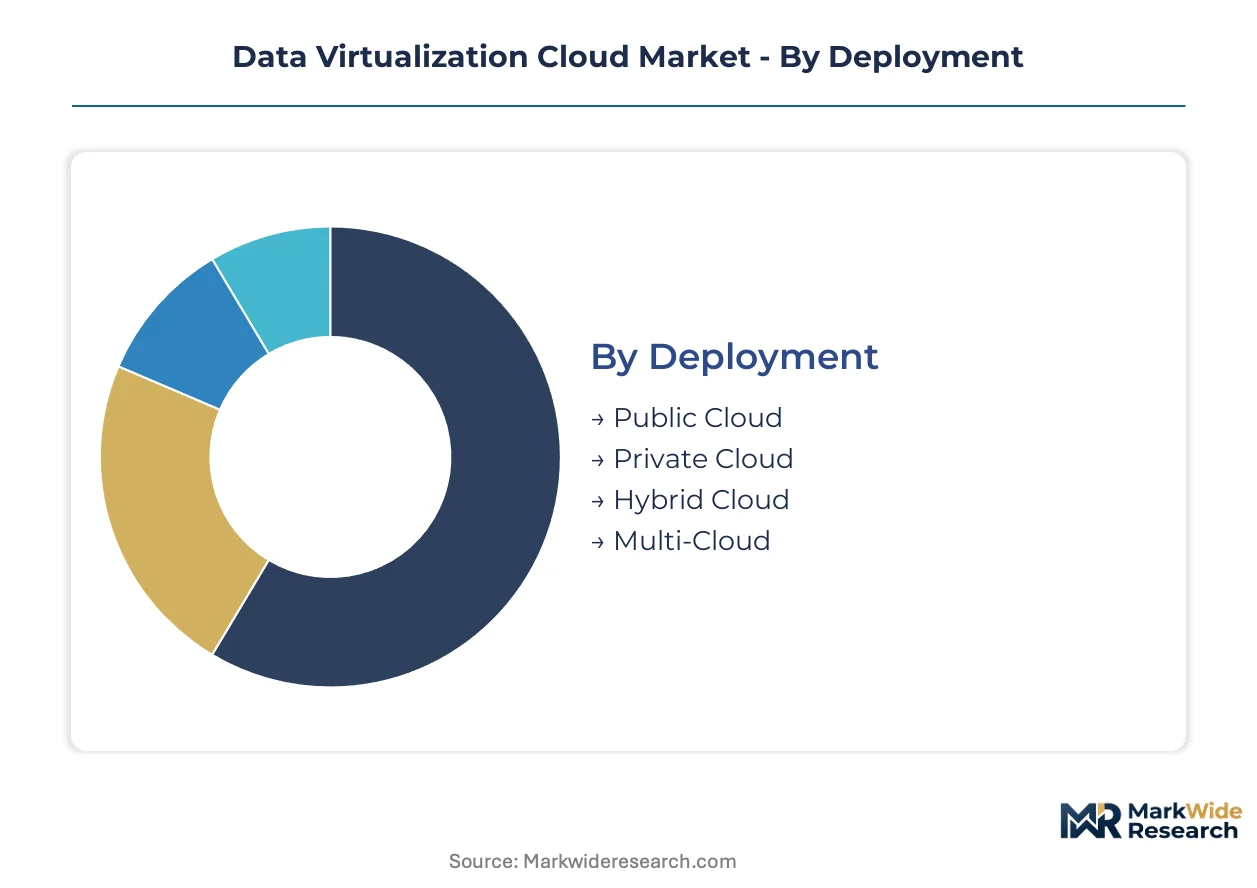
Segmentation in data virtualization cloud reveals distinct procurement patterns across infrastructure models and organizational maturity. Deployment architecture determines compliance posture and latency trade-offs, while end-user scale shapes pricing mechanics and service delivery models.
Deployment:
Standardization dominates public infrastructure, whereas private and hybrid configurations demand extensive customization for data residency and legacy integration.
- Public Cloud:Shared infrastructure pools deliver elastic compute for burst analytics workloads. Demand concentrates among US fintech startups seeking rapid provisioning without capital commitment, though EU AI Act lineage requirements are forcing retrofitted governance overlays.
- Private Cloud:Dedicated tenant environments enforce strict data sovereignty with physical isolation. German automotive suppliers and French healthcare networks deploy these for GDPR-critical workloads where cross-border movement is prohibited.
- Hybrid Cloud:Unified control planes orchestrate workloads across on-premises and public nodes. US federal agencies under cloud-smart mandates use this to retain classified data locally while bursting non-sensitive analytics to commercial infrastructure.
- Multi-Cloud:Abstraction layers federate queries across AWS, Azure, and GCP simultaneously. Singapore logistics firms pilot these architectures to avoid vendor lock-in and optimize spot pricing across regions.
Most installed capacity flows through Hybrid Cloud. Expansion is steepest in Multi-Cloud.
End User:
Cost tier stratification separates consumption-based SME offerings from enterprise procurement cycles with dedicated customer success layers.
- Enterprises:Global 2000 firms deploy data fabrics spanning 50+ source systems with centralized semantic modeling. US healthcare systems under HIPAA interoperability rules represent the most active procurement segment for governed cross-institutional analytics.
- SMEs:Mid-market manufacturers in Italy and Spain adopt managed service bundles eliminating upfront infrastructure capital. These deployments typically federate 5-10 operational databases without dedicated data engineering staff.
- Government Institutions:National statistical agencies and tax authorities require air-gapped environments with immutable audit trails. India's state-level digital transformation initiatives are driving regional procurement of localized virtualization nodes.
- Educational Organizations:Research universities federate siloed departmental databases for cross-disciplinary analytics. UK Russell Group institutions lead adoption for grant-funded data sharing consortia in climate and genomics research.
Enterprises currently absorb the majority of vendor revenue. SMEs are gaining share fastest as subscription pricing penetrates mid-market manufacturing.
Solution:
Application maturity varies from established data integration pipelines to emerging governance modules with embedded AI Act compliance.
- Data Integration:Real-time federation engines connect operational databases, APIs, and streaming sources without ETL construction. Capital markets firms in London and New York deploy these for sub-millisecond risk aggregation across distributed trading books.
- Data Management:Cataloging and lineage tools maintain semantic consistency across federated schemas. Pharmaceutical supply chains in Switzerland use these for batch traceability across contract manufacturing networks.
- Analytics:Query optimization layers accelerate business intelligence workloads without data centralization. Australian mining operators apply geospatial virtualization for remote exploration data accessed from Perth headquarters.
- Data Governance:Policy enforcement modules embed jurisdiction-specific controls directly into query execution paths. EU credit scoring platforms now require these for high-risk automated decision-making under algorithmic audit mandates.
Data Integration commands the largest existing footprint. Data Governance is climbing the fastest as regulatory deadlines approach.
Industry Vertical:
Customer type specialization separates regulated industries with compliance-driven procurement from retail's margin-optimized self-service models.
- Healthcare:Interoperability platforms enable secure analytics across hospital networks without centralizing protected health information. US health systems under 21st Century Cures Act provisions are replacing point-to-point interfaces with unified virtualization layers.
- Retail:Customer 360 initiatives federate e-commerce, loyalty, and supply chain data for real-time personalization. Dutch and Belgian omnichannel operators lead European adoption to unify online and in-store inventory visibility.
- Financial Services:Risk data aggregation mandates under Basel III compel real-time federation across trading, lending, and treasury systems. Singaporean and Hong Kong banks are consolidating decade-old data warehouse silos into unified fabrics.
- Telecommunications:Network operations centers federate subscriber, infrastructure, and billing data for predictive maintenance. South Korean carriers deploy edge-localized virtualization to minimize latency for 5G network analytics.
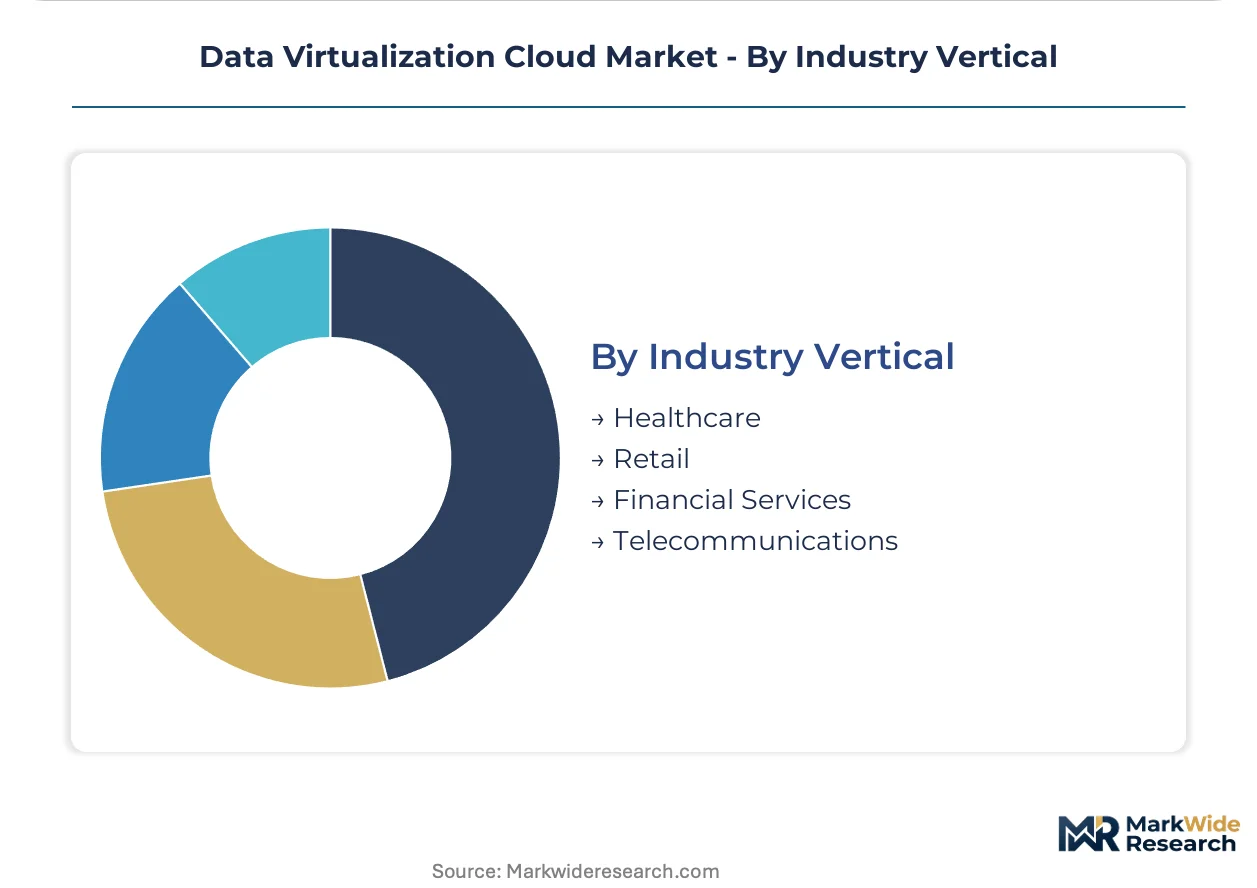
Financial Services retains the deepest installed base. Healthcare is expanding most quickly as interoperability deadlines activate procurement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data virtualization cloud infrastructure traces its commercial lineage to Silicon Valley's enterprise software laboratories, where early federated query engines emerged from database research consortia during the 2000s. The technology subsequently migrated to financial technology clusters in London and Singapore before achieving regulatory validation under European data governance frameworks.
United States
Federal cloud-smart mandates and HIPAA interoperability deadlines are accelerating procurement of hybrid data fabrics across healthcare systems and federal agencies. The SEC's climate disclosure rules require emissions data aggregation across supplier networks without direct system access. New York's financial technology corridor hosts the densest concentration of real-time risk aggregation deployments, with capital markets firms consolidating decade-old warehouse silos.
Germany
Automotive suppliers and healthcare networks are deploying private cloud virtualization to satisfy GDPR-critical workloads where cross-border data movement faces prohibition. The EU AI Act's algorithmic audit requirements are compelling credit scoring platforms to embed immutable lineage records. Bavaria's industrial software cluster around Munich anchors the deepest European concentration of governed semantic layer deployments for manufacturing analytics.
Singapore
Logistics firms and maritime operators are piloting multi-cloud federation architectures to optimize spot pricing across AWS, Azure, and GCP regions while avoiding vendor lock-in. The Monetary Authority of Singapore's digital banking guidelines encourage virtualization layers that maintain data residency for cross-border payment analytics. The island's trade finance technology district houses the Asia-Pacific's most advanced supply chain visibility implementations.
United Kingdom
Russell Group research universities are federating siloed departmental databases for grant-funded data sharing consortia in climate and genomics research. Subscription-based consumption models are displacing perpetual licensing among mid-market manufacturers in the Midlands. London's insurance underwriting district is consolidating legacy systems into unified fabrics to satisfy real-time risk aggregation mandates.
India
State-level digital transformation initiatives are driving regional procurement of localized virtualization nodes for national statistical agencies and tax authorities. The RBI's data localization guidelines for payment systems are compelling banks to deploy private cloud abstraction layers. Karnataka's Bangalore technology corridor hosts the fastest-growing concentration of managed service offerings for mid-market enterprises eliminating upfront infrastructure capital.
Data Virtualization Cloud Market Vendor Landscape
Capital-heavy infrastructure providers compete with asset-light software specialists across the data virtualization cloud market, creating a tiered structure where hyperscale cloud operators anchor the base layer while niche architects occupy premium integration segments. The vendor landscape consolidates around three strategic archetypes: hyperscale platform operators with native federation services, independent middleware specialists with semantic modeling expertise, and legacy enterprise software houses extending database franchises into abstraction layers. Dominant competitive moves include strategic partnerships between cloud operators and governance specialists, plus geographic expansion through localized data residency certifications.
Within the hyperscale tier, Amazon Web Services and Microsoft exemplify platform operators that have integrated query federation into core infrastructure offerings. IBM occupies a distinctive position bridging legacy enterprise installations with hybrid cloud orchestration, particularly in regulated European industries. Denodo Technologies represents the independent specialist archetype, with logical data warehouse architectures that decouple physical storage from query optimization. These three anchors illustrate the market's structural segmentation between integrated platforms and best-of-breed abstraction engines.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Oracle |
| Amazon Web Services |
| Google Cloud |
| Denodo Technologies |
| TIBCO Software |
| SAP |
| Informatica |
| Others |
Supply Flow & Price Mechanics
Query federation engine commoditization is compressing infrastructure margins while concentrating procurement power among hyperscale cloud operators in the United States and Western Europe. This technological shift simultaneously erodes traditional licensing premiums and rewards vendors with captive compute capacity.
Pricing Analysis
Consumption-based subscription tiers dominate data virtualization cloud procurement, with pricing stratifying across enterprise-grade governed fabrics, mid-market managed services, and developer-tier API access. Certification against HIPAA and EU AI Act audit mandates commands substantial premiums over uncertified deployments. Cost compression in mid-market tiers is intensifying because managed service providers are bundling semantic modeling labor with infrastructure commitments. Healthcare systems in the United States exhibit the highest price tolerance for compliance-guaranteed offerings, while mid-market manufacturers in Southern Europe prioritize cost minimization over advanced governance features.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Singapore anchor downstream fulfillment of data virtualization platforms, with hub-and-spoke patterns radiating from hyperscale cloud availability zones. Core infrastructure draws from semiconductor fabrication concentrated in Taiwan and South Korea, plus specialized networking hardware from China and the United States. Single-source vulnerability in AI accelerator supply creates concentration risk for vendors building real-time caching layers. Distribution runs through certified channel partners who embed localization and compliance customization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in data virtualization cloud rests on automated semantic modeling tools that collapse implementation labor costs while enabling premium pricing for AI Act-certified deployments.
For Market Incumbents: Deepen hybrid cloud orchestration capabilities to defend against hyperscale operators integrating federation natively. Prioritize EU AI Act pre-certification investments in Germany and France before regulatory deadlines activate. Extend vertical integration into edge computing hardware to capture latency-sensitive workloads in financial services. For New Entrants and Emerging Players: Begin with managed service bundles targeting mid-market manufacturers in Italy and Spain, where upfront capital constraints eliminate incumbent competition. Emphasize GraphQL federation expertise to differentiate against legacy SQL-optimized architectures. Pursue channel partnerships with regional systems integrators rather than direct enterprise sales. For Investors and Strategic Acquirers: Valuations sit cheapest among independent middleware specialists with semantic modeling IP but limited cloud infrastructure scale. Long-term viability favors vendors who can anchor multi-tenant deployments in regulated industries without hyperscale dependency. Monitor EU AI Act enforcement actions as the signal indicating which governance modules will command sustained premium pricing.| Strategic Initiative | Industry Significance |
|---|---|
| AI Act Compliance Certification | Unlocks premium pricing in EU financial services and healthcare procurement cycles. |
| Managed Service Bundle Launch | Eliminates upfront capital barriers for mid-market manufacturing adoption in Southern Europe. |
| Semantic Knowledge Graph Integration | Compresses time-to-insight for business users without SQL construction skills. |
| Multi-Cloud Federation Partnership | Avoids vendor lock-in for Singapore logistics firms optimizing spot pricing. |
| Edge Computing Hardware Investment | Captures sub-millisecond latency requirements in capital markets risk aggregation. |
Methodological Framework
Direct dialogue with chief data officers, cloud architects, regulatory compliance leads, and channel partners informed qualitative grounding, cross-referenced against hyperscaler capex disclosures, SEC filings, EU regulatory submissions, and healthcare interoperability mandate documents. Bottom-up sizing of deployment volumes across public, private, hybrid, and multi-cloud configurations triangulated against top-down market value estimates.
Segment-level projections across deployment architecture, end-user scale, solution type, and industry vertical populated the analytical framework over the projection horizon. CAGRs derived from fitted adoption curves incorporating regulatory deadline impacts, cloud migration trajectories, and managed service penetration rates. Model inputs included real-time query volume growth in financial services and semantic modeling automation advances.
Caveats apply where EU AI Act enforcement intensity, hyperscaler pricing aggression, or edge latency breakthroughs could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Computing in Industrial IoT Market
Cloud Computing
Cloud Integration Software Market
Cloud Computing
Global Distributed Cloud Market
Cloud Computing
Global Public Cloud Service Market
Cloud Computing
Hybrid Cloud in BFSI Market
Cloud Computing
South Korea Cloud Computing Market
Cloud Computing
Germany Cloud Computing Market
Cloud Computing
Cloud Management Market
Cloud Computing
Cloud Applications Market
Cloud Computing
Platform As a Service (Paas) Market
Cloud Computing
Cloud IT Service Management (ITSM) Market
Cloud Computing
Global Cloud Computing in Healthcare Market
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
Cloud VPN Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
Consumer Cloud Subscription Market