
 Global Cloud Management Software Market | 2026-2036
Global Cloud Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Management Software Market Foresight
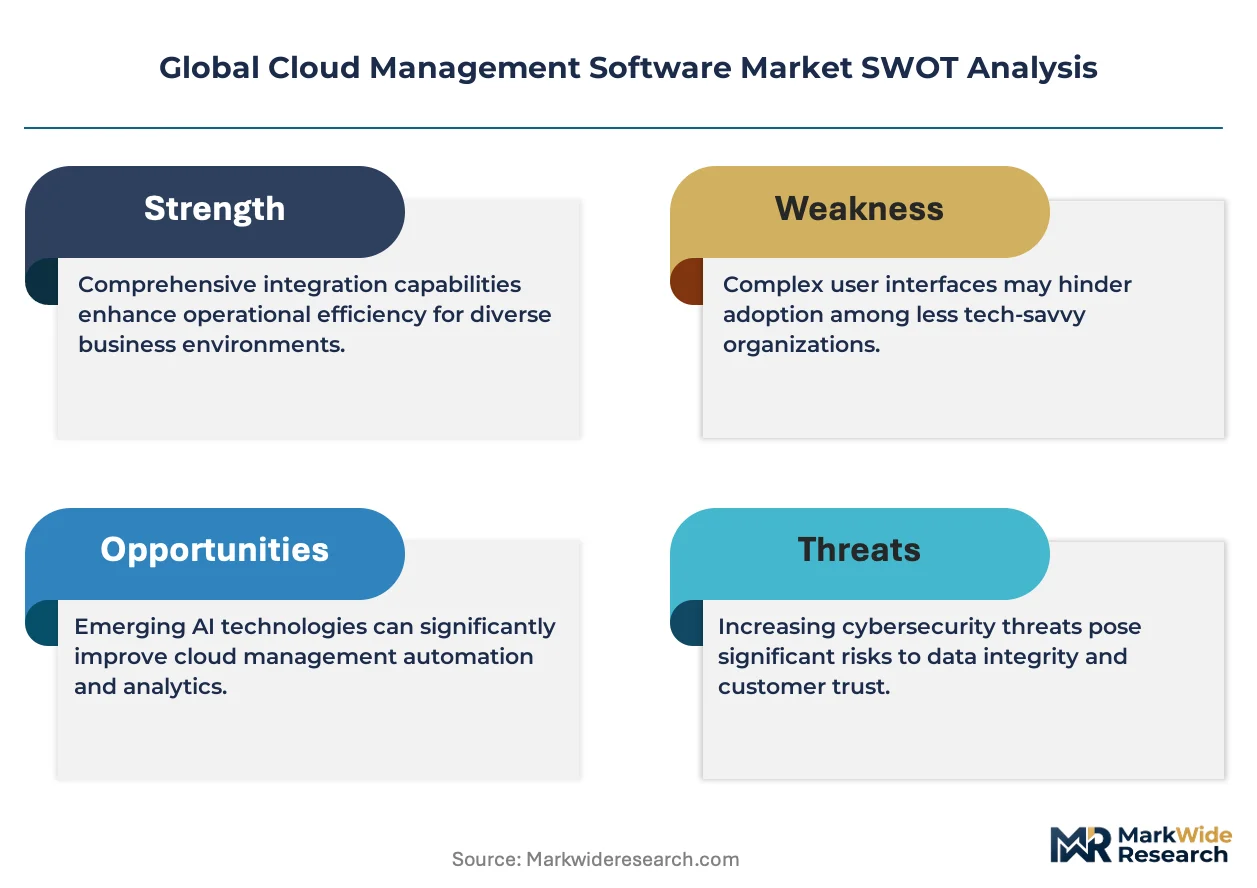
Hyperscaler capacity expansion in Northern Virginia is realigning how enterprise buyers evaluate cloud management suites. Microsoft Azure leverages its hybrid cloud integration depth to anchor large government contracts. AWS competes through extensive automation tooling that spans cost optimization and security posture management. Google Cloud Platform differentiates via native AI-infused performance monitoring capabilities.
Cloud management software encompasses platforms that provision, monitor, secure, and govern distributed computing resources across public, private, and hybrid environments, typically integrating APIs, policy engines, and analytics dashboards to enforce service-level objectives. These systems automate workload placement, cost allocation, and compliance verification across multi-tenant infrastructures. Hybrid cloud deployment structures command the widest enterprise uptake as organizations balance latency-sensitive workloads against regulatory data residency requirements. Security management and compliance management solution offerings capture disproportionate margin pools as breach notification mandates tighten across jurisdictions. DevOps and IT infrastructure management applications absorb the largest implementation budgets as platform engineering teams standardize infrastructure-as-code practices.
FDA guidelines on software-as-a-medical-device, EU GDPR cross-border transfer mechanisms, and India's DPDP Act data localization provisions each reshape how cloud management vendors architect regional instance controls and audit trails. ISO 27001 and SOC 2 Type II certifications have become baseline market access requirements rather than differentiators for enterprise procurement committees. Stakeholders must monitor evolving sovereign cloud certification schemes to anticipate where compliance automation investments will yield competitive separation.
Market Dynamics
Hybrid cloud orchestration is forcing enterprises to unify disparate control planes as workload portability becomes non-negotiable under sovereign data mandates. The EU AI Act and India's DPDP Act are accelerating investment in automated governance tooling that spans multi-cloud estates.
Growth Catalysts
- EU AI Act compliance automation:Financial services firms in Frankfurt and Amsterdam are deploying policy-as-code frameworks to satisfy algorithmic audit requirements. Automated evidence collection now anchors procurement specifications.
- Edge computing proliferation:Manufacturing facilities in Stuttgart and Detroit require localized orchestration to manage latency-sensitive industrial IoT workloads. Cloud management platforms extend control planes to factory floors.
- India's DPDP Act localization:Data fiduciaries in Mumbai and Bangalore must maintain verifiable audit trails for cross-border transfers. Native compliance modules are displacing manual spreadsheet-based tracking.
Market Restraints
- Specialized talent scarcity:Platform engineering expertise concentrates in Northern Virginia and Bengaluru, inflating implementation timelines for enterprises outside these clusters.
- API fragmentation:Proprietary control interfaces across AWS, Azure, and GCP impose integration tax on multi-cloud deployments. Abstraction layer development consumes disproportionate R&D resources.
- Input cost volatility:GPU-intensive observability workloads face pricing pressure from constrained NVIDIA H100 supply chains. Inference cost uncertainty delays budget approvals for AI-ops modules.
Strategic Opportunities
- Sovereign cloud certification:Germany's GAIA-X framework and France's SecNumCloud create compliant market segments where domestic vendors capture preference. Certification automation tooling addresses audit preparation bottlenecks.
- FinOps-native platforms:Unit economics visibility is converging with carbon accounting as CSRD disclosure requirements expand. Joint cost-sustainability dashboards attract ESG-mandated procurement committees.
- Healthcare vertical expansion:FDA software-as-a-medical-device guidelines in the United States require validated change control. GxP-compliant cloud management modules address life sciences quality assurance gaps.
Industry Challenges
- Legacy mainframe integration:Insurance and banking core systems in London and Tokyo resist API-native abstraction. Hybrid connectivity middleware demands specialized systems integration partnerships.
- SOC 2 Type II timeline compression:Enterprise procurement committees now require continuous monitoring evidence rather than point-in-time certification. Audit automation must satisfy both AICPA and ISO 27001 criteria simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Management Software Market |
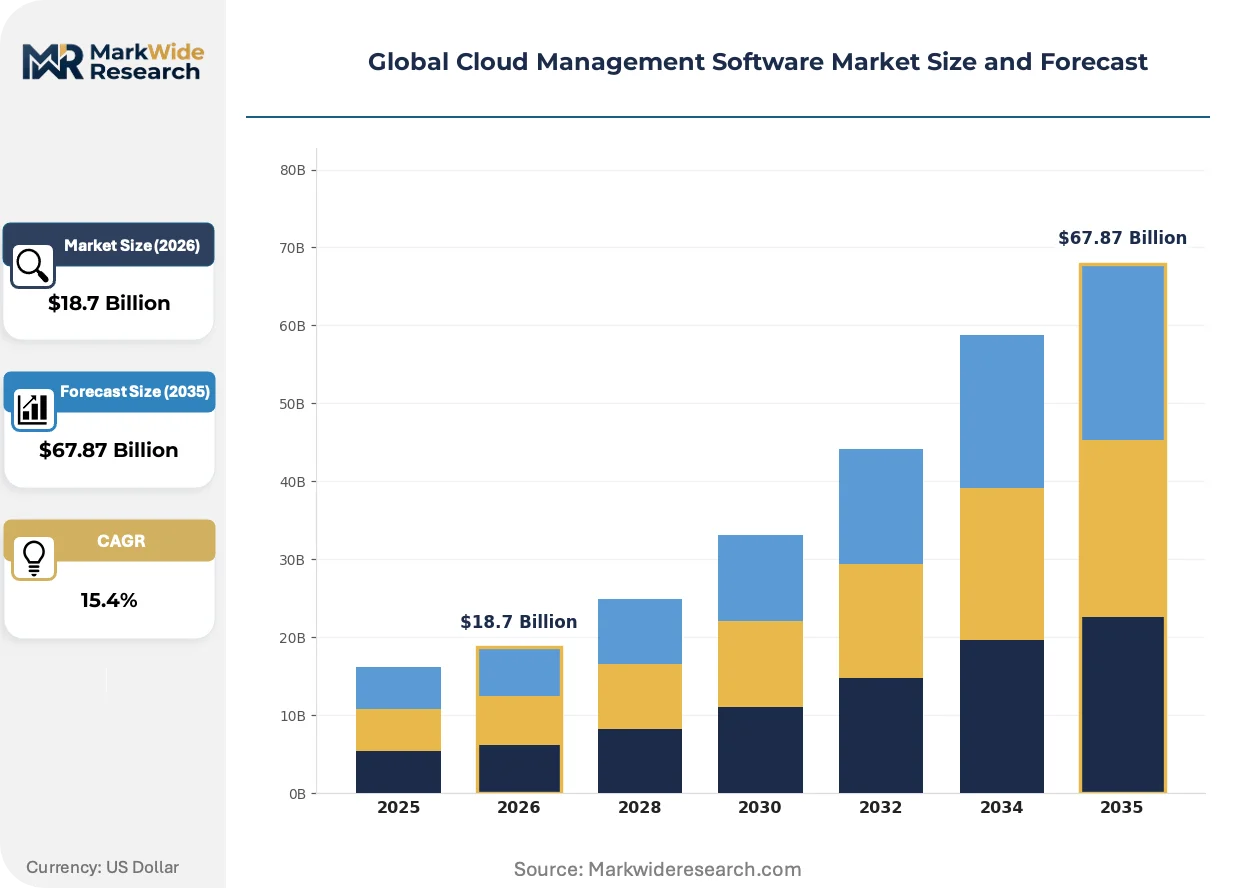
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $67.87 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Offering: Cost Management, Security Management, Performance Monitoring, Automation Tools, Compliance Management Application: IT Infrastructure Management, DevOps, Data Analytics, Disaster Recovery, Software Development End User: Telecommunications, Education Institutions, Government Agencies, Media Companies, Financial Services |
| Companies Covered | Amazon Web Services (AWS), Microsoft Azure, Google Cloud Platform, IBM Cloud, Oracle Cloud Infrastructure, Flexera, Datadog, Red Hat, New Relic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Management Software Market Shifts & Advancements
Artificial intelligence is embedding into every control plane function, compressing mean-time-to-resolution for infrastructure incidents. Vendors race to differentiate through autonomous remediation capabilities that reduce human-in-the-loop dependencies.
Agentic AI for infrastructure operations is converging with traditional event-driven automation. Large financial institutions in Singapore and New York are piloting self-healing systems that execute runbook procedures without manual authorization. This capability compression threatens to commoditize conventional monitoring dashboards and displace tier-1 support staffing models.
The EU AI Act's risk classification framework is mandating algorithmic impact assessments for automated workload placement decisions. Cloud management vendors must now embed explainability modules that document why specific provisioning choices occurred. High-risk system providers in the Netherlands and Sweden are accelerating procurement of audit-ready policy engines to satisfy national regulator interpretations.
Platform engineering teams are consolidating vendor relationships around internal developer portals that abstract cloud-native complexity. Self-service infrastructure provisioning through Backstage and Port is displacing traditional ticketing workflows in technology-intensive enterprises. This pattern is most visible among scale-ups in Tel Aviv and Berlin where developer experience metrics directly influence retention.
Global Cloud Management Software Market Segmentation
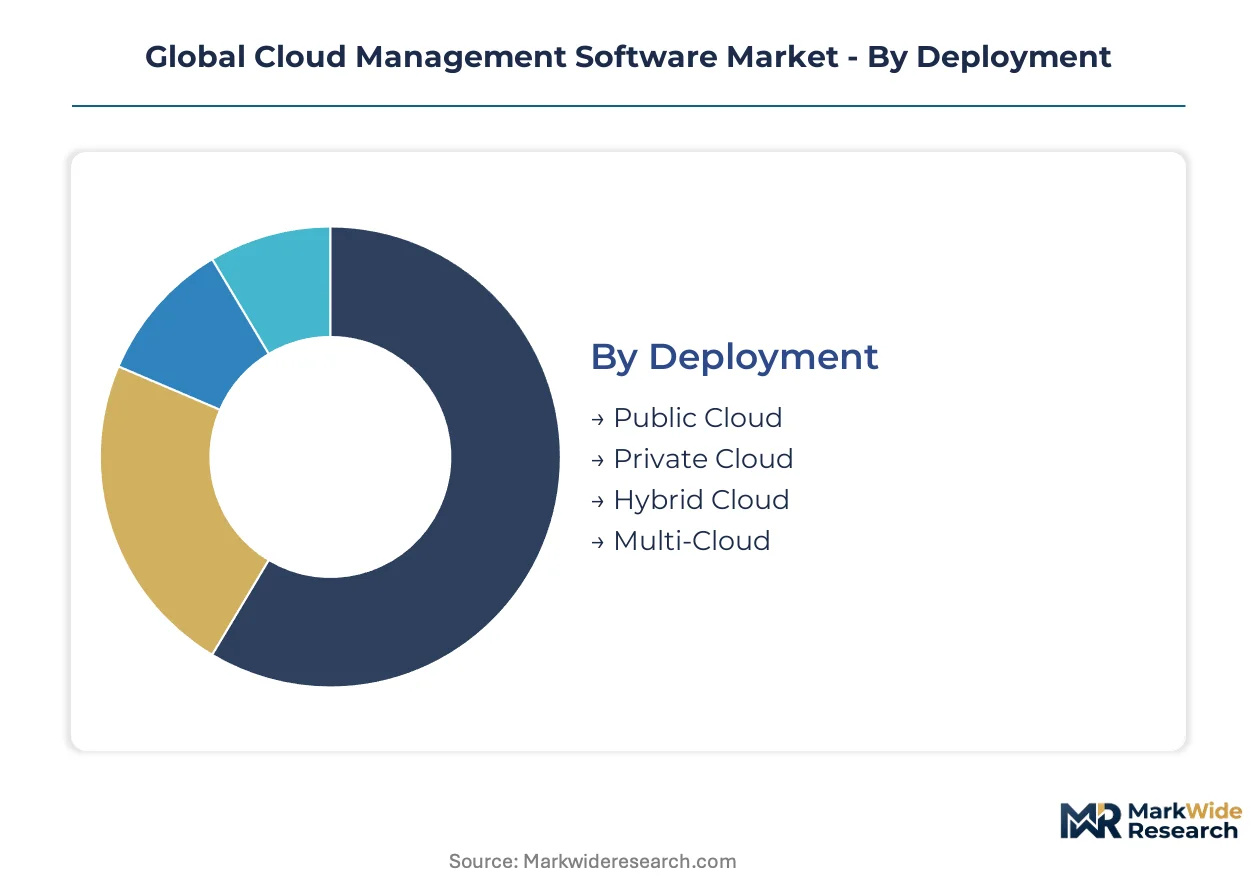
Cloud management software procurement patterns diverge sharply across deployment architectures and regulatory contexts. Enterprise buyers segment their vendor evaluations by control plane requirements, workload sensitivity, and compliance automation depth rather than feature checklists alone.
Deployment:
Platform refresh cycles now center on sovereignty-ready architectures as data residency mandates harden across jurisdictions.
- Public Cloud:Shared infrastructure models deliver elastic compute pools through hyperscaler APIs. Financial services firms in Singapore and retail platforms in São Paulo favor consumption-based scaling for variable workloads, though cross-border transfer restrictions constrain deployment in regulated segments.
- Hybrid Cloud:Unified control planes span on-premises data centers and public cloud instances through consistent policy engines. Manufacturing enterprises in Stuttgart and healthcare systems in Minneapolis prioritize this architecture to anchor latency-sensitive operations locally while bursting peak loads to hyperscaler capacity.
- Private Cloud:Dedicated infrastructure deployments isolate tenant resources through single-organization hardware stacks. Defense contractors in Arlington and central banks in Frankfurt mandate this model for classified transaction processing and monetary policy systems.
- Multi-Cloud:Abstraction layers normalize operations across AWS, Azure, and GCP control planes simultaneously. Technology scale-ups in Tel Aviv and enterprise platform teams in Bengaluru adopt this approach to avoid vendor lock-in and optimize spot pricing arbitrage.
Hybrid Cloud sits at the top of the volume ranking, with Multi-Cloud climbing the fastest.
Solution Offering:
Procurement committees weight solution modules by margin exposure and audit liability rather than functional breadth.
- Security Management:Identity governance, threat detection, and encryption key lifecycle tools protect distributed workloads. EU AI Act risk classification requirements in Amsterdam and FDA software-as-a-medical-device validation in Boston are accelerating automated posture management adoption.
- Compliance Management:Policy-as-code frameworks generate audit trails and evidence packages for regulator examination. India's DPDP Act data fiduciaries in Mumbai and GDPR Article 30 documentation requirements in Dublin are displacing manual spreadsheet tracking with native compliance modules.
- Cost Management:FinOps dashboards attribute cloud spend to business units and workloads with granular chargeback precision. Platform engineering teams in Sydney and Toronto deploy these tools to satisfy CFO scrutiny on unit economics.
- Performance Monitoring:AI-infused observability pipelines compress mean-time-to-resolution for infrastructure incidents. Gaming platforms in Seoul and algorithmic trading venues in New York demand sub-second anomaly detection for revenue-critical systems.
- Automation Tools:Infrastructure-as-code provisioning and self-healing runbook execution reduce human-in-the-loop dependencies. DevOps teams in Berlin and platform engineering groups in Austin standardize on GitOps workflows for deployment velocity.
Security Management commands the largest implementation budgets, while Compliance Management is gaining share fastest as sovereign data mandates proliferate.
Application:
Workload automation intensity varies by operational criticality and recovery time objective requirements.
- DevOps:Continuous integration and delivery pipelines demand infrastructure self-service through internal developer portals. Scale-ups in Tel Aviv and enterprise platform teams in London measure deployment frequency and lead time for changes as core operational metrics.
- IT Infrastructure Management:Legacy system integration and hybrid connectivity middleware anchor enterprise control plane investments. Insurance core systems in Tokyo and banking mainframes in London resist API-native abstraction, requiring specialized systems integration partnerships.
- Data Analytics:GPU-intensive observability and machine learning training workloads require cost-optimized resource scheduling. Research institutions in Zurich and pharmaceutical companies in Basel negotiate reserved instance contracts for predictable compute demand.
- Disaster Recovery:Automated failover and backup validation ensure business continuity across geographically distributed regions. Critical infrastructure operators in Riyadh and healthcare networks in Melbourne mandate validated recovery point objectives under national cybersecurity frameworks.
- Software Development:Ephemeral development environments and sandbox provisioning accelerate release cycles. Independent software vendors in Vancouver and embedded systems houses in Munich consume these capabilities through API-driven platform services.
IT Infrastructure Management retains the deepest installed base, with DevOps expanding most quickly as platform engineering practices standardize.
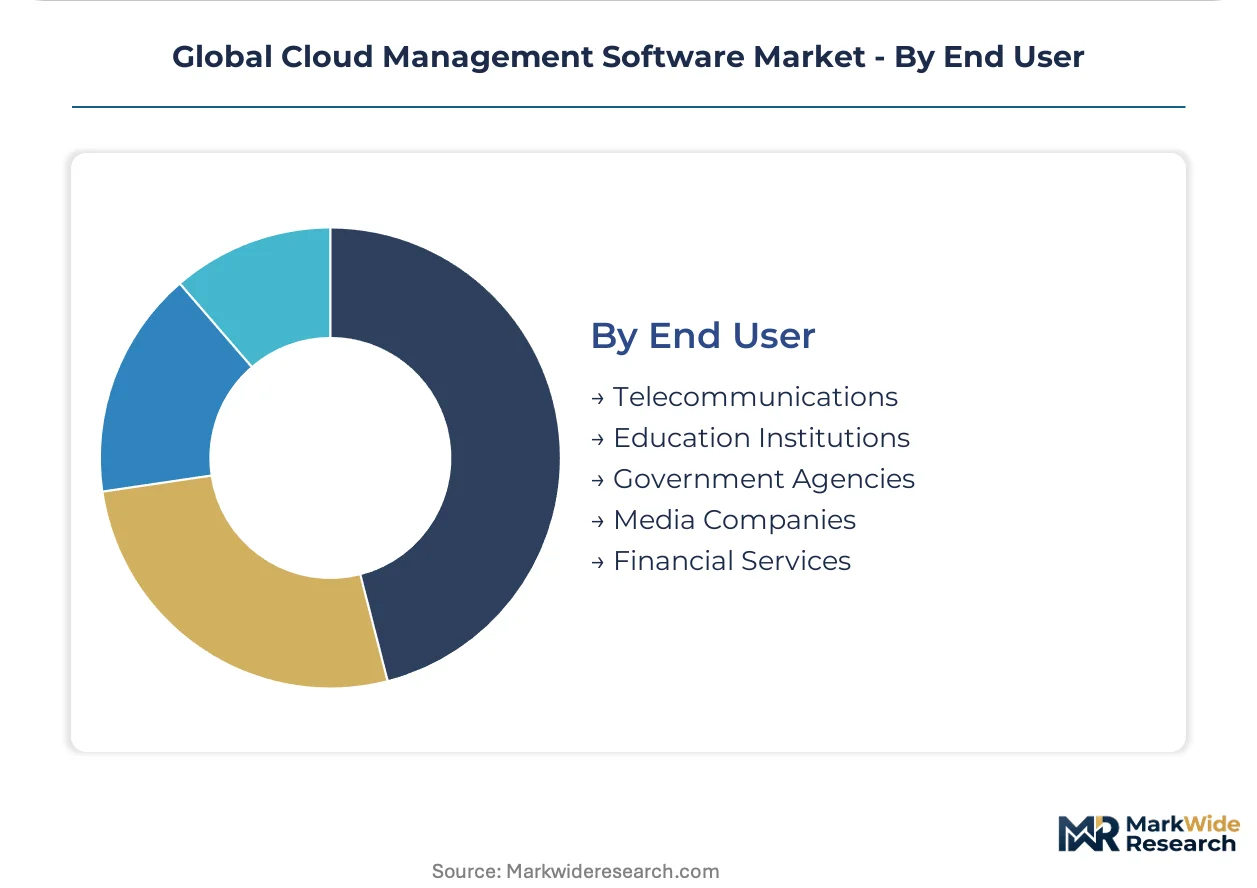
End User:
Sector-specific certification requirements and procurement authorization thresholds reshape vendor engagement models.
- Financial Services:Algorithmic trading platforms and payment networks demand sub-millisecond latency with validated change control. EU AI Act high-risk system classifications in Frankfurt and SEC cybersecurity disclosure rules in New York are mandating audit-ready policy engines.
- Government Agencies:Sovereign cloud certification and classified data handling requirements restrict vendor eligibility. Germany's GAIA-X framework and France's SecNumCloud create compliant market segments where domestic vendors capture procurement preference.
- Telecommunications:Network function virtualization and edge orchestration extend control planes to radio access networks. 5G standalone deployments in Seoul and Riyadh require localized cloud management for ultra-reliable low-latency communication services.
- Education Institutions:Research computing and learning management systems balance cost constraints against accessibility mandates. Universities in Melbourne and Toronto negotiate enterprise licensing for multi-tenant student environments.
- Media Companies:Content delivery optimization and rendering farm scheduling manage burst workloads for production pipelines. Streaming platforms in Los Angeles and visual effects studios in Wellington consume spot instance capacity for transcoding and simulation.
Financial Services anchors the highest average contract value, with Government Agencies climbing fastest on sovereign cloud investment waves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing cloud management procurement as compliance-cost differentials widen across jurisdictions. Enterprises migrate workload governance investments toward markets with clearer certification pathways and lower audit friction. This shift concentrates vendor engagement activity in specific national markets where sovereign data mandates create protected demand pools.
United States
Defense contractors and federal agencies in Arlington drive demand for private-cloud isolation and FedRAMP-authorized control planes. The SEC cybersecurity disclosure rules and FDA software-as-a-medical-device guidelines mandate validated change documentation. Northern Virginia's hyperscaler concentration anchors the world's densest platform engineering talent cluster, compressing implementation timelines for complex hybrid deployments.
Germany
Automotive manufacturers in Stuttgart and financial institutions in Frankfurt require latency-optimized orchestration for industrial IoT and algorithmic trading workloads. The GAIA-X framework and EU AI Act high-risk system classifications create preference for domestically certified vendors. Bavaria's manufacturing corridor generates concentrated demand for edge-extended cloud management that unifies factory-floor control planes with hyperscaler burst capacity.
India
Data fiduciaries in Mumbai and technology scale-ups in Bangalore must satisfy DPDP Act localization requirements for cross-border transfer audit trails. RBI and SEBI guidelines for financial infrastructure resilience accelerate investment in automated compliance modules. Karnataka's technology corridor hosts the densest concentration of multi-cloud abstraction engineering outside Northern Virginia.
Singapore
Wealth management platforms and commodity trading venues demand sub-millisecond latency with MAS Technology Risk Management compliance automation. The Personal Data Protection Commission's data localization guidance reshapes regional hub strategies for ASEAN-facing enterprises. Marina Bay's financial district anchors procurement of sovereign-ready cloud management for Southeast Asian market entry.
United Kingdom
Insurance core systems in London and fintech scale-ups require hybrid connectivity middleware that bridges legacy mainframe estates with cloud-native infrastructure. The Financial Conduct Authority's operational resilience rules mandate validated recovery capabilities. The City of London's regulatory technology cluster drives demand for audit-ready policy engines that satisfy both UK and EU compliance requirements simultaneously.
Global Cloud Management Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sovereign-cloud specialization and vertical-specific compliance modules. The market structures around three distinct maturity tiers: hyperscale infrastructure operators with native management layers, independent software vendors with multi-cloud abstraction focus, and regional specialists with domestic certification depth. Competitive positioning depends on API breadth, policy engine explainability, and pre-certified compliance templates. Primary competitive moves include strategic partnerships with systems integrators and geographic expansion through local certification acquisition.
Among hyperscale infrastructure operators, Amazon Web Services, Microsoft Azure, and Google Cloud Platform exemplify the integrated control plane archetype. These entities leverage captive infrastructure scale to embed management functionality at consumption points. Microsoft Azure occupies a distinctive position through hybrid integration depth that anchors large government contracts. AWS represents the automation-centric approach spanning cost optimization and security posture management. Google Cloud Platform sits within the AI-native tier through performance monitoring capabilities infused with machine learning inference. Independent vendors such as Flexera and Datadog compete by normalizing operations across these hyperscaler control planes simultaneously.
| Leading Market Players |
|---|
| Amazon Web Services (AWS) |
| Microsoft Azure |
| Google Cloud Platform |
| IBM Cloud |
| Oracle Cloud Infrastructure |
| Flexera |
| Datadog |
| Red Hat |
| New Relic |
| Others |
Supply & Pricing Matrix
EU AI Act compliance mandates for algorithmic audit trails are compressing procurement timelines for policy-as-code frameworks, forcing vendors to absorb certification engineering costs while hyperscalers leverage captive infrastructure to maintain subscription premiums.
Pricing Analysis
Distributor margins in the enterprise channel typically capture fifteen to twenty-five points before value-added resellers apply vertical specialization markups. Three-tier pricing structure across premium, standard, and economy levels stratifies by compliance automation depth and sovereign certification status. Pricing pressure stems from GPU-intensive observability modules facing NVIDIA H100 supply constraints that delay budget approvals. Financial services buyers in Frankfurt and Singapore exhibit lowest price sensitivity due to regulatory liability exposure, while education institutions in Melbourne and Toronto negotiate aggressively on enterprise licensing.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan's semiconductor foundries for AI inference accelerators and NVIDIA's captive packaging for H100 GPU supply. Engineering talent concentrates in Northern Virginia, Bengaluru, and Berlin, creating geographic chokepoints for platform implementation. Cloud management software draws from hyperscaler API ecosystems, open-source orchestration frameworks, and specialized compliance content libraries. Tariff exposure runs through US-China technology transfer restrictions on advanced computing components. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cloud management software rests on compliance automation premiumization as sovereign data mandates multiply audit preparation costs that vendors can capture through subscription tiers.
For Market Incumbents: Extend policy engine explainability modules to satisfy EU AI Act high-risk system documentation requirements before domestic competitors achieve GAIA-X or SecNumCloud certification. Deepen vertical integration into healthcare GxP validation content and financial services algorithmic audit tooling to defend against emerging sovereign-cloud specialists. For New Entrants and Emerging Players: Launch via embedded compliance modules for India's DPDP Act data fiduciaries and Germany's GAIA-X framework, targeting mid-market manufacturers in Stuttgart's industrial corridor lacking internal platform engineering capacity. White-space concentration sits with edge-extended orchestration for factory-floor latency-sensitive workloads. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing pre-certified sovereign cloud templates and vertical-specific audit content libraries. Long-term viability favors acquisition targets combining multi-cloud abstraction engineering with automated compliance evidence generation. Watch hyperscaler marketplace revenue share negotiations as the inflection signal for independent vendor margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying control planes across AWS, Azure, and GCP reduces integration tax for financial services firms in Amsterdam. |
| Geographic Expansion | GAIA-X and SecNumCloud certification acquisition opens protected procurement pools in Germany and France. |
| Strategic Partnership | Systems integrator alliances address legacy mainframe connectivity gaps in London insurance core systems. |
| Acquisition of Specialist Firm | Compliance content libraries accelerate FDA software-as-a-medical-device validation for Boston life sciences. |
| Product Launch | FinOps-native carbon accounting dashboards attract CSRD-mandated procurement committees in Frankfurt. |
Research Methodology
Bottom-up enterprise deployment modeling reconciled against top-down hyperscaler capacity tracking forms the analytical core of this study. Primary interviews with CTOs, platform engineering directors, IT procurement officers, and compliance automation specialists informed demand-side assumptions. Secondary validation drew from SEC filings, hyperscaler capex disclosures, EU regulatory guidance documents, and national data protection authority advisories. Triangulation across these sources anchored segmentation-specific adoption curves.
Historical trendline analysis identified inflection points in sovereign cloud investment and compliance automation procurement. The projection framework spans deployment architectures, solution offerings, vertical applications, and regional regulatory clusters. CAGR derivation rested on policy diffusion modeling for EU AI Act and DPDP Act implementation timelines, weighted by platform engineering talent concentration. Industry-specific inputs included hyperscaler region expansion announcements and sovereign certification scheme adoption rates.
Several conditions sit outside the modeled scope, including unforeseen regulatory reinterpretations, hyperscaler pricing restructuring, and breakthrough autonomous remediation capabilities that could displace conventional monitoring tiers. Forecasts reflect documented assumptions about compliance cost trajectories and talent supply elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Serverless Computing Market
Cloud Computing
Israel Cloud Computing Market
Cloud Computing
Indonesia Cloud Market
Cloud Computing
Hybrid Cloud Services Market
Cloud Computing
UAE Cloud Computing Market
Cloud Computing
Asia Pacific Cloud Computing Market
Cloud Computing
Cloud Computing in Industrial IoT Market
Cloud Computing
South Korea Cloud Computing Market
Cloud Computing
Hybrid Cloud in BFSI Market
Cloud Computing
Public Finance Cloud Market
Cloud Computing
Cloud Management Platform Market
Cloud Computing
Android Cloud Phone Market
Cloud Computing
Public Cloud in BFSI Market
Cloud Computing
Commercial Cloud Market
Cloud Computing
Cloud Microservices Market
Cloud Computing
Global Cloud Business Email Market