
 Bottled Tea Market | 2026-2036
Bottled Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Bottled Tea Market Analysis
Subscription-based replenishment services is restructuring how bottled tea reaches habitual consumers, shifting volume from impulse retail to scheduled direct delivery. PepsiCo leverages its beverage distribution network to sustain shelf dominance across mass retail channels. Nestle S.A. anchors premium positioning through mineral-enhanced and functional tea lines in European markets. ITO EN, LTD competes on green tea authenticity, controlling supply relationships with Japanese tea growers.
Bottled tea comprises brewed, extracted, or cold-infused tea leaves preserved in sterile containers, typically requiring acidification to pH levels below 4.6 for ambient shelf stability and thermal processing or aseptic filling to prevent microbial spoilage. Green tea commands the premium tier as antioxidant claims attract wellness-oriented buyers, while black tea occupies the volume base through established palatability across demographics. Supermarkets and convenience stores still capture the majority of transactions, though online retail registers the fastest structural expansion as subscription models reduce customer acquisition costs.
The FDA governs acidified food regulations and nutrition labeling for U.S. bottled tea, while the EFSA evaluates health claims across European markets, and Japan's Ministry of Agriculture, Forestry and Fisheries oversees geographic indication protections for domestic tea origins. These frameworks elevate compliance costs for new entrants but also create defensible positioning for established players with regulatory expertise. Stakeholders must monitor evolving sugar taxation proposals and packaging sustainability mandates as these forces determine which formulation and material choices survive channel access requirements.
Market Dynamics
Subscription replenishment models are restructuring bottled tea distribution, diverting volume from impulse retail toward scheduled direct delivery while compressing customer acquisition costs for digitally native brands.
Growth Catalysts
- Functional wellness positioning:Antioxidant and adaptogenic claims attract fitness-oriented consumers seeking beverage alternatives to supplements. Green tea variants command shelf premiums through perceived health credentials.
- FDA Nutrition Facts modernization:Updated labeling requirements for added sugars and serving sizes pressure reformulation toward reduced-calorie profiles, accelerating clean-label innovation across the category.
- Cold-brew extraction methods:Ambient-stable cold-infusion technologies preserve volatile flavor compounds without thermal degradation, enabling premium positioning for previously commoditized black tea bases.
Market Restraints
- Aluminum and PET resin volatility:Packaging material costs fluctuate with energy markets, squeezing margin structures for mid-tier producers lacking long-term supply contracts.
- Japanese green tea supply concentration:Authentic ceremonial-grade leaf sourcing depends on limited Shizuoka and Kagoshima prefecture growers, creating vulnerability to climate disruption and currency exposure.
- pH acidification requirements:FDA acidified food regulations mandate sub-4.6 pH levels for ambient stability, constraining formulation space for naturally alkaline herbal infusions without taste-compromising additives.
Strategic Opportunities
- Direct-to-subscription channel expansion:Replenishment services reduce retail slotting fee burdens while capturing lifetime value through predictable consumption patterns.
- Postbiotic and nootropic fortification:Convergence of brewed tea bases with functional ingredients creates white space between conventional beverages and supplement categories.
- Deposit-return scheme alignment:EU packaging sustainability mandates and emerging US state-level extended producer responsibility laws favor refillable glass and aluminum formats with established recycling infrastructure.
Industry Challenges
- Aseptic filling technician scarcity:Thermal processing and sterile packaging operations require specialized operator certification that outpaces vocational training pipeline output.
- Co-packer capacity constraints:Third-party manufacturing consolidation limits production flexibility for emerging brands seeking small-batch runs without capital-intensive facility investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottled Tea Market |
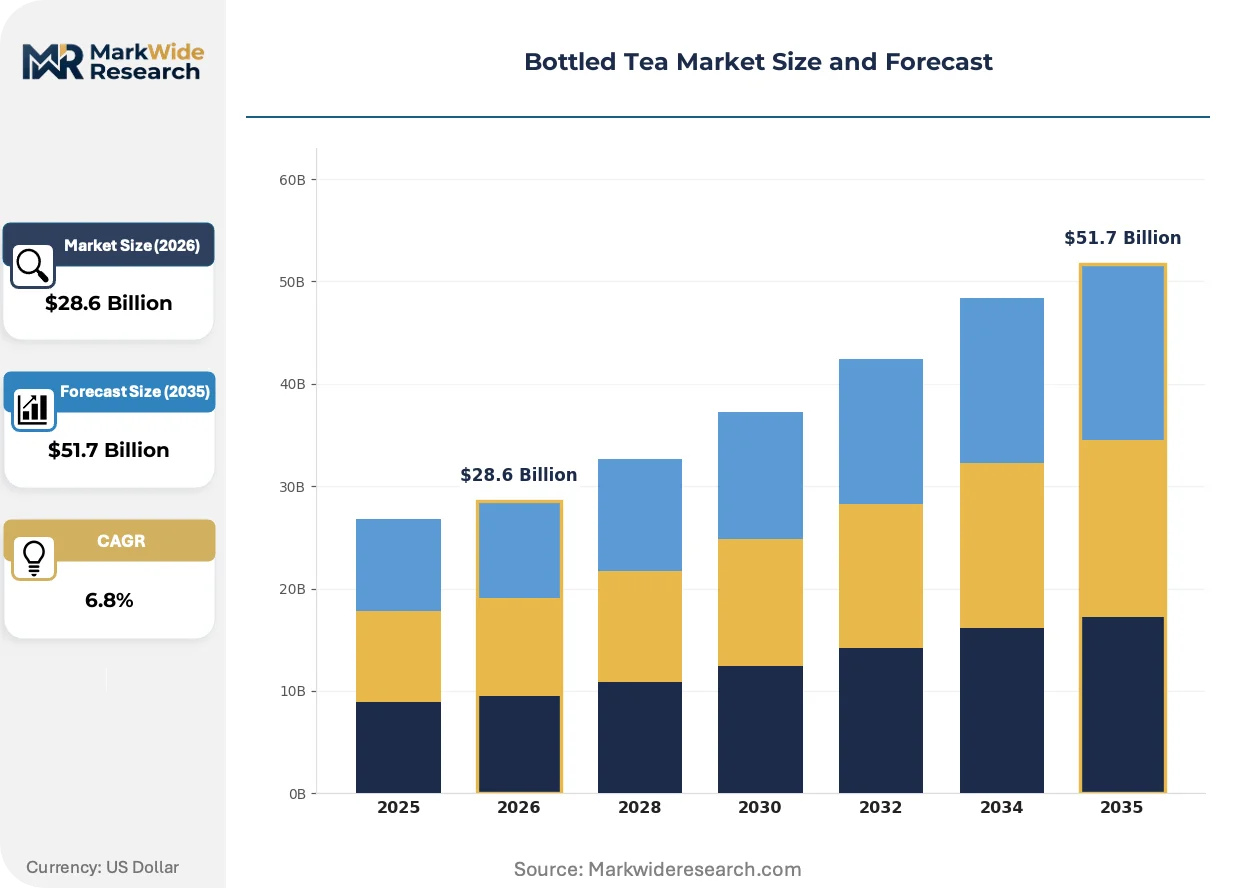
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Tea, Black Tea, Herbal Tea, Oolong Tea Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops End User: Health-conscious Consumers, Teens, Professionals, Athletes Flavor Profile: Citrus, Berry, Mint, Ginger |
| Companies Covered | Associated British Foods plc, PepsiCo, Unilever Plc, Bigelow Tea, Hain Celestial Group Inc., Nestle S.A., ITO EN, LTD, The Republic of Tea, Tata Consumer Products Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottled Tea Market Emerging Trajectories
Formulation science and packaging engineering are converging to extend shelf stability without synthetic preservatives, while digital channels rewrite how habitual consumption gets replenished.
Aseptic cold-filling technology is automating the intersection of flavor preservation and ambient distribution. Premium green tea processors deploy nitrogen-flushed sterile lines to eliminate thermal pasteurization. Wellness-oriented buyers adopt these products at accelerating velocity through specialty retail. The technology is automating what previously required refrigerated supply chains, collapsing cost structures for regional brands.
EU Green Deal packaging sustainability requirements are mandating recycled content minimums and extended producer responsibility frameworks. Bottled tea importers face compliance deadlines for rPET incorporation thresholds and deposit-return scheme participation. German and French markets experience the steepest compliance cost escalation, prompting reformulation toward concentrated formats that reduce material intensity per serving.
Habitual replenishment via subscription algorithms is displacing sporadic convenience store purchase patterns. Digital-native tea brands capture recurring revenue through predictive consumption analytics and flexible delivery cadences. Fitness and wellness program participants demonstrate the highest subscription attachment rates, particularly in US metropolitan corridors with established direct-to-consumer logistics infrastructure.
Bottled Tea Market Segmentation
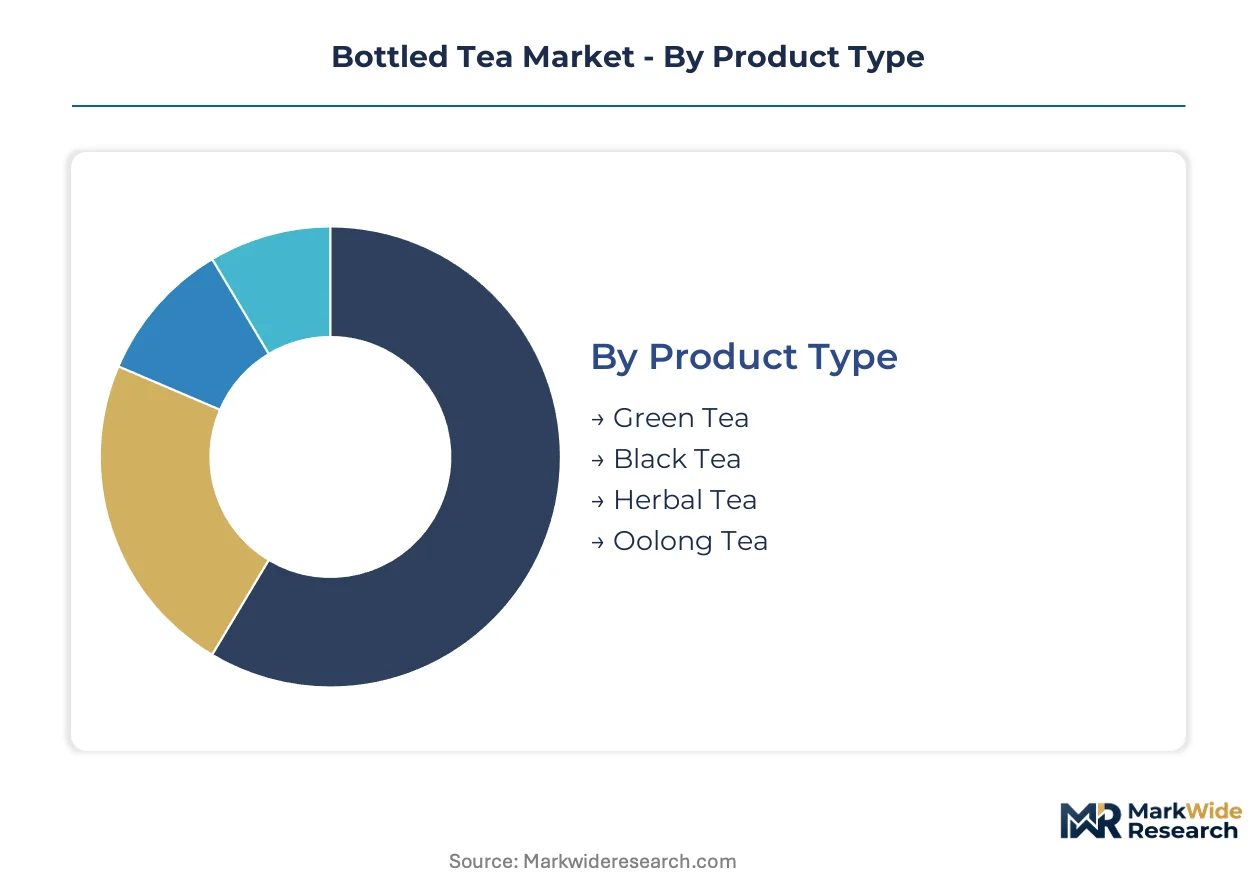
Segmentation in bottled tea reveals how formulation choices, channel access, and consumer identity intersect to determine pricing power and shelf positioning. Distinct technical requirements and purchasing behaviors across each dimension create divergent margin structures that reward specialized supply chain configurations.
Product Type:
Supply concentration around authentic leaf sourcing and extraction technology varies sharply across tea bases, with premium positioning hinging on provenance verification and processing method.
- Green Tea:Unoxidized Camellia sinensis leaves preserved through steaming or pan-firing retain catechin polyphenols for antioxidant positioning. Japanese cultivars from Shizuoka prefecture command sourcing premiums in US wellness channels where authenticity claims drive repeat purchase.
- Black Tea:Fully oxidized leaves undergo withering, rolling, fermentation, and drying to develop theaflavin compounds and stable shelf presence. Sri Lankan and Kenyan supply contracts anchor volume production for convenience retail across North American and European markets.
- Herbal Tea:Tisane infusions of rooibos, chamomile, or hibiscus operate outside true tea taxonomy, requiring separate FDA acidified food compliance pathways for ambient stability.
- Oolong Tea:Semi-oxidized processing spans 15-85% oxidation range, creating flavor complexity that attracts specialty shop distribution in Taiwan-influenced West Coast corridors.
Black tea absorbs the bulk of installed capacity; green tea is expanding most quickly.
Distribution Channel:
Channel economics determine whether brands pursue velocity through mass retail or margin through specialized access, with cold chain requirements and slotting fee structures filtering viable entrants.
- Supermarkets:Grocery chains demand case-stack efficiency and promotional fund participation, favoring established beverage conglomerates with direct store delivery infrastructure and trade spend budgets.
- Convenience Stores:Impulse-driven refrigerated sets prioritize grab-and-go packaging formats and localized brand recognition, with 7-Eleven and Circle K operators controlling regional assortment decisions.
- Online Retail:Direct-to-consumer platforms enable subscription replenishment models that bypass slotting fees while capturing consumption data for predictive inventory positioning.
- Specialty Shops:Curated tea boutiques and natural food cooperatives emphasize single-origin storytelling and small-batch credentials, accepting price premiums for limited distribution exclusivity.
Supermarkets and convenience stores together capture dominant transaction volume; online retail climbs the fastest.
End User:
Consumer identity segments align with distinct usage occasions and functional expectations, shaping whether marketing emphasizes performance claims, ritual authenticity, or accessible refreshment.
- Health-conscious Consumers:Fitness program participants and wellness practitioners prioritize low-sugar formulations with verified antioxidant content, driving demand for cold-brew green tea in subscription channels.
- Teens:Flavor-forward sweetened varieties in portable formats dominate school and recreation occasion purchasing, with brand heat and social currency influencing selection.
- Professionals:Workplace consumption favors ambient-stable bottles for desk storage, with caffeine content and label sophistication signaling personal brand alignment.
- Athletes:Electrolyte-fortified and adaptogenic variants target training recovery occasions, with sports nutrition retailers serving as gatekeepers for performance positioning claims.
Health-conscious consumers absorb the bulk of premium volume; athletes gain share fastest.
Flavor Profile:
Flavor innovation operates within acidification constraints, with natural extracts requiring careful pH management to maintain FDA compliance without synthetic preservative inclusion.
- Citrus:Lemon and yuzu extracts provide masking functionality for reduced-sugar formulations while delivering familiar refreshment cues across demographic segments.
- Berry:Acai, blueberry, and elderberry concentrates support antioxidant narrative cohesion with green tea bases, popular in wellness-oriented specialty retail.
- Mint:Peppermint and spearmint essential oils offer digestive positioning and palate-cleansing properties, particularly in post-meal consumption occasions.
- Ginger:Rhizome extracts deliver functional spice notes with anti-inflammatory marketing potential, concentrated in Asian-influenced North American markets.
Citrus and berry together absorb the bulk of flavor development resources; ginger shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan cultivates the raw leaf supply that premium brands source worldwide, while the United States consumes the largest ready-to-drink volumes outside East Asia. Germany and the United Kingdom import processed concentrates for private-label bottling. China's domestic bottlers now export cold-brew formats to Southeast Asian markets.
United States
Fitness program participants and workplace professionals drive subscription replenishment demand through direct-to-consumer channels. The FDA enforces acidified food regulations and updated Nutrition Facts labeling for added sugars. Southern California and Texas corridor bottlers deploy nitrogen-flushed aseptic lines to supply wellness-oriented retail chains.
Japan
Ceremonial-grade green tea authenticity commands sourcing premiums from Shizuoka and Kagoshima prefecture growers. The Ministry of Agriculture, Forestry and Fisheries oversees geographic indication protections for domestic tea origins. Kansai region processors control supply relationships with heritage cultivar farms for export-grade matcha extraction.
Germany
Private-label bottlers source black tea concentrates from Sri Lankan and Kenyan contracts for discount retail distribution. EU Green Deal packaging sustainability mandates impose recycled content minimums and extended producer responsibility frameworks. Bavarian co-packers face compliance cost escalation from deposit-return scheme participation deadlines.
China
Domestic cold-brew green tea adoption accelerates among urban health-conscious consumers seeking alternatives to carbonated beverages. SAMR regulates food safety standards and labeling requirements for functional beverage claims. Yangtze River Delta bottlers export ambient-stable formats to Vietnam and Thailand through established ASEAN trade corridors.
United Kingdom
Specialty retail channels emphasize single-origin storytelling and small-batch credentials for premium positioning. EFSA evaluates health claim substantiation for antioxidant and adaptogenic marketing. London and Southeast England distribution hubs consolidate import logistics for European market re-export.
Bottled Tea Market Vendor Landscape
Top-tier beverage conglomerates anchor mass retail shelf space, while mid-tier regional specialists and digital-native subscription brands occupy fragmented premium niches. Consolidation pressure intensifies as co-packer capacity constraints and aseptic filling technician scarcity elevate operational barriers. Two strategic archetypes dominate: diversified multinationals leveraging direct store delivery infrastructure, and authenticity-focused specialists controlling heritage supply relationships. Competitive moves concentrate on subscription algorithm development and sustainable packaging format alignment with EU regulatory deadlines.
Among diversified multinational beverage operators, PepsiCo and Nestle S.A. exemplify scale-driven distribution archetypes. ITO EN, LTD occupies a position within the authenticity-focused specialist tier, representing heritage supply chain control. These three entities illustrate how competitive positioning diverges between volume velocity through mass retail and premium pricing through provenance verification.
| Leading Market Players |
|---|
| Associated British Foods plc |
| PepsiCo |
| Unilever Plc |
| Bigelow Tea |
| Hain Celestial Group Inc. |
| Nestle S.A. |
| ITO EN, LTD |
| The Republic of Tea |
| Tata Consumer Products Limited |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap Japanese tea processors anchor premium green tea sourcing through hereditary supply relationships with Shizuoka prefecture growers, translating cultivation scarcity into pricing discipline that resists commoditization pressure from multinational volume players.
Pricing Analysis
Cost-down pressure on mid-tier black tea accelerates because aluminum and PET resin volatility squeezes margin structures for producers lacking long-term supply contracts. Three-tier pricing structure across premium, standard, and economy levels separates ceremonial-grade Japanese green tea from commodity Sri Lankan blends and private-label concentrates. Price differentiation rests on authenticity verification and cold-brew processing certification. Health-conscious consumers in subscription channels show lowest price sensitivity; teens purchasing convenience store singles demonstrate highest.
Supply Chain Analysis
EU Green Deal packaging sustainability mandates and emerging US state-level extended producer responsibility laws are reshaping sourcing toward rPET incorporation and refillable glass formats. Leaf supply concentrates in Japan, Sri Lanka, and Kenya, with extraction technology dependencies on nitrogen-flushed aseptic lines and acidification systems. Single-source vulnerability from Japanese ceremonial-grade cultivar concentration creates climate and currency exposure. Distribution runs through direct store delivery networks for mass retail and subscription algorithms for digital-native brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's acidified food regulations and updated Nutrition Facts labeling requirements construct a cost-of-compliance moat that favors established players with regulatory expertise and specialized aseptic filling capabilities.
For Market Incumbents: To counter co-packer capacity constraints and technician scarcity elevating operational barriers, secure captive production through backward integration into aseptic filling facilities in Southern California and Texas corridors. Deepen regulatory affairs investment to navigate evolving sugar taxation proposals and packaging sustainability mandates before compliance deadlines harden. For New Entrants and Emerging Players: Capture subscription replenishment white space among fitness program participants in US metropolitan corridors with established direct-to-consumer logistics infrastructure. Target postbiotic and nootropic fortification segments where functional ingredient convergence creates category ambiguity between beverages and supplements. Lead with cold-brew authenticity narrative and predictive consumption analytics. For Investors and Strategic Acquirers: Distressed-cycle entries favor heritage supply chain specialists with Shizuoka and Kagoshima prefecture grower relationships in Japan. Long-term viability across a five-to-ten-year window hinges on regulatory compliance infrastructure and sustainable packaging format alignment. Monitor EU deposit-return scheme participation deadlines as inflection indicator for format winners.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Cold-Filling Capacity Expansion | Nitrogen-flushed sterile lines eliminate thermal pasteurization for premium green tea positioning. |
| Subscription Algorithm Development | Predictive consumption analytics capture lifetime value through habitual replenishment patterns. |
| Sustainable Packaging Transition | rPET incorporation and refillable glass alignment with EU Green Deal compliance deadlines. |
| Heritage Supply Chain Acquisition | Shizuoka prefecture grower relationships authenticate premium positioning in wellness channels. |
| Functional Ingredient Fortification | Postbiotic and adaptogenic convergence creates white space between beverages and supplements. |
Methodological Framework
Multi-period observation of subscription adoption rates, aseptic filling capacity utilization, and regulatory compliance cost trajectories anchored the trend analysis, supplemented by interviews with beverage brand managers, category buyers at convenience retailers, aseptic processing technicians, and supply chain planners. Secondary validation drew from FDA acidified food guidance documents, EU Green Deal packaging directives, Japanese Ministry of Agriculture geographic indication filings, and customs trade data for tea leaf imports. Bottom-up volume modeling and top-down value reconciliation triangulated market estimates.
Segment-weighting across product type, distribution channel, end user identity, and flavor profile dimensions structured the analytical framework across the projection horizon. CAGRs derived from fitted growth curves applied to subscription penetration trajectories and cold-brew format adoption velocities. Industry-specific forecast inputs included co-packer capacity expansion timelines and state-level extended producer responsibility legislation progression.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aluminum and PET resin price volatility, Japanese climate disruption affecting ceremonial-grade leaf yields, and aseptic filling technician training pipeline output. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Matcha Products Market
Tea
Europe Tea Market
Tea
North America Ready-To-Drink Tea Market
Tea
Tea Polyphenols Market
Tea
US Ready to Drink Tea Market
Tea
Black Tea Market
Tea
Fermented Tea Market
Tea
Asia-Pacific Tea Market
Tea
Global Tea Extract Market
Tea
Africa Tea Market
Tea
Global Catechin Market
Tea
Europe Green Tea Market
Tea
Asia-Pacific Green Tea Market
Tea
Matcha Market
Tea
Nitro Tea Market
Tea
Green Tea Bag Market