
 Probiotic Tea Market | 2026-2036
Probiotic Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Probiotic Tea Market Analytics
Premium live-culture specifications is bifurcating the probiotic tea landscape into refrigerated perishables and shelf-stable alternatives. GT's Living Foods leverages its pioneer positioning in raw, unpasteurized kombucha to sustain consumer trust in live probiotic counts. Health-Ade LLC differentiates through small-batch brewing and organic ingredient sourcing, while KeVita anchors the mass-market channel with pasteurized, multi-strain formulations in mainstream grocery.
Probiotic tea denotes brewed beverages inoculated with live bacterial cultures, typically Lactobacillus or Bifidobacterium strains, delivering colony-forming units exceeding one billion per serving for digestive health claims. The production relies on controlled fermentation temperatures between 20°C and 30°C to preserve microbial viability through consumption. Fermented variants occupy the dominant margin pool due to higher perceived efficacy and artisanal positioning, while bottled packaging leads volume through convenience-driven repeat purchase behavior. Online distribution channels represent the fastest-growing access point, though supermarkets retain the largest transaction throughput for impulse and trial purchases.
The FDA regulates probiotic health claims under food and dietary supplement frameworks, creating compliance complexity for cross-category positioning. EFSA in Europe maintains stricter substantiation requirements for live culture benefits, limiting direct digestive health messaging in EU markets. USDA organic certification and non-GMO verification increasingly function as table-stakes for shelf placement in premium retail channels. Stakeholders must monitor evolving strain-specific approval pathways and refrigeration infrastructure investments as live-culture credibility becomes the central purchase determinant.
Market Dynamics
Live-culture credibility has emerged as the central purchase determinant, forcing manufacturers to invest in cold-chain infrastructure and strain-specific substantiation while navigating divergent regulatory frameworks across major markets.
Growth Catalysts
- EFSA Strain-Specific Pathways:The European Food Safety Authority's evolving qualified presumption of safety framework is creating clearer approval routes for documented probiotic strains, encouraging R&D investment in clinically validated cultures.
- Wellness-Focused Millennials:This demographic cohort in the United States demonstrates sustained willingness to pay premium prices for functional beverages with transparent ingredient sourcing and verified live culture counts.
- Controlled Fermentation Temperatures:Advances in precision brewing technology enabling consistent maintenance of 20°C to 30°C ranges are improving microbial viability and reducing batch failure rates in artisanal production.
Market Restraints
- Refrigeration Infrastructure Costs:Cold-chain requirements for raw unpasteurized variants impose significant capital expenditure on distribution networks, limiting market penetration in regions with unreliable electricity supply.
- FDA Claim Substantiation:The Food and Drug Administration's strict bifurcation between food and dietary supplement frameworks creates compliance complexity that delays product launches and increases legal review costs.
- Shelf-Stable Substitution:Pasteurized multi-strain formulations with extended ambient storage capability are capturing price-sensitive consumers despite lower perceived efficacy, compressing margins for live-culture premium positioning.
Strategic Opportunities
- Direct-to-Consumer Subscriptions:Online channels represent underexploited recurring revenue potential, with wellness-focused cohorts demonstrating high retention for scheduled delivery of refrigerated perishables.
- USDA Organic Certification:Federal organic verification is functioning as mandatory table-stakes for premium retail placement, creating first-mover advantage for early certifiers in mainstream grocery expansion.
- Functional Convergence with Adaptogens:Formulation innovation combining Lactobacillus strains with ashwagandha or reishi extracts is opening positioning in stress-management and cognitive performance segments beyond digestive health.
Industry Challenges
- Microbiome Strain Expertise Gap:Shortage of fermentation scientists capable of optimizing viability through consumption is constraining scale-up from artisanal to commercial production volumes.
- Non-GMO Verification Timelines:Third-party non-GMO Project certification processes are extending go-to-market schedules by four to six months, complicating seasonal flavor launches.
- Cross-Category Positioning Complexity:Simultaneous compliance with food beverage regulations and dietary supplement guidelines is forcing redundant testing protocols and label versioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Probiotic Tea Market |
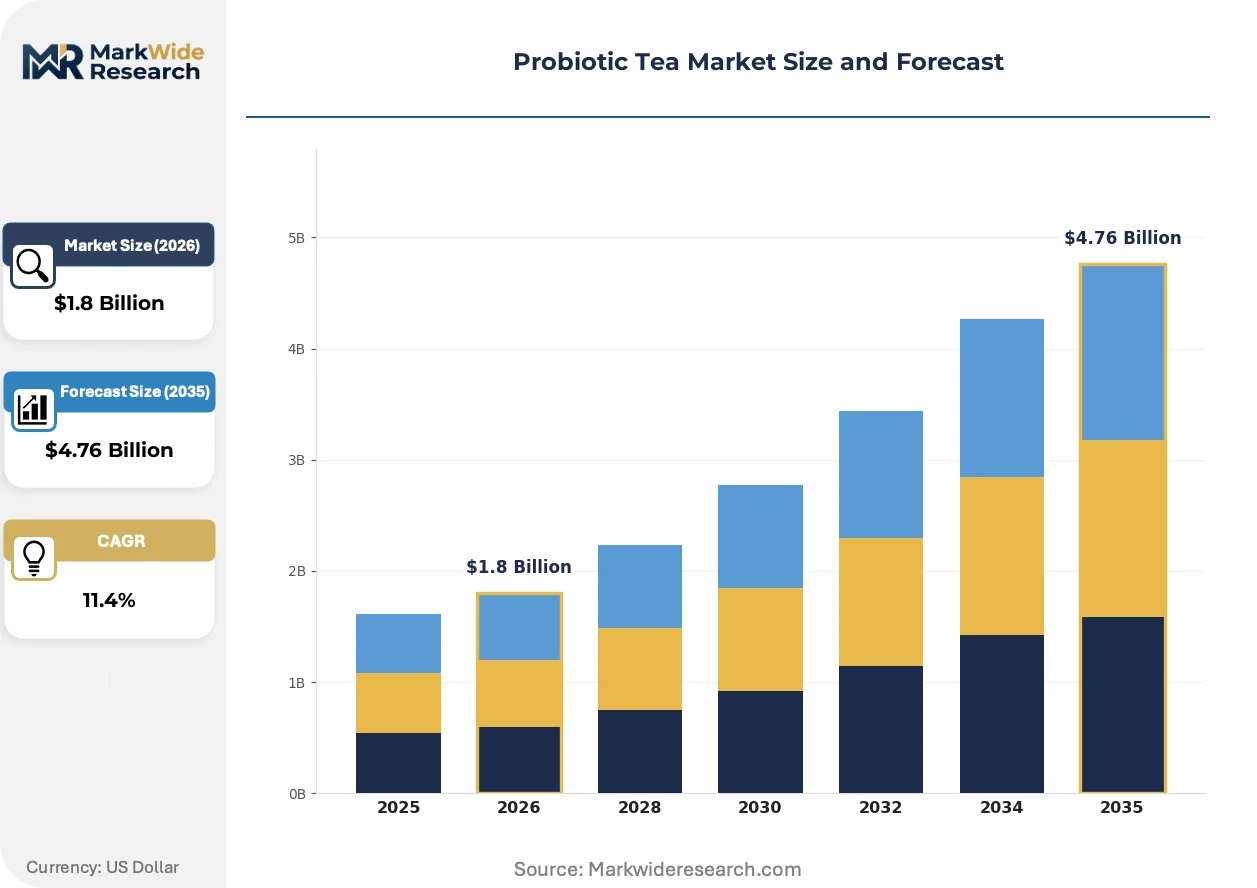
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fermented, Herbal, Green, Black Packaging Type: Bottled, Loose Leaf, Tea Bags, Cans Distribution Channel: Online, Supermarkets, Health Stores, Cafés Flavor Profile: Fruity, Spicy, Minty, Floral |
| Companies Covered | GT's Living Foods, KeVita, Health-Ade LLC, Brew Dr. Kombucha, Humm Kombucha, Yogi Tea, Celestial Seasonings, Bigelow Tea, The Kombucha Shop, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Probiotic Tea Market Evolving Landscape
Fermentation science and packaging technology are converging to redefine product stability claims, while regulatory divergence between major markets is forcing modular compliance strategies.
Microencapsulation technology is bifurcating the probiotic tea landscape between ambient-stable formulations and refrigerated live-culture products. Beverage manufacturers in Germany and the Netherlands are adopting spray-dried bacterial coatings at accelerated pace. This technological divide is enabling mass-market penetration through extended shelf life while simultaneously compressing artisanal producers into niche premium positioning.
The FDA's evolving enforcement discretion on structure-function claims is reshaping permissible messaging for digestive health benefits. Manufacturers must now navigate substantiation requirements that vary by product classification as conventional food versus supplement. Brands targeting United States mass retail are responding with conservative claim language and investment in clinical study partnerships.
Subscription-based replenishment models are displacing traditional trial-and-repeat purchase patterns in wellness-oriented households. Direct-to-consumer platforms are capturing recurring revenue from kombucha enthusiasts who prioritize convenience over supermarket browsing. This behavioral shift is most visible in urban coastal markets where cold-chain logistics infrastructure supports reliable home delivery of perishable live-culture products.
Probiotic Tea Market Segmentation
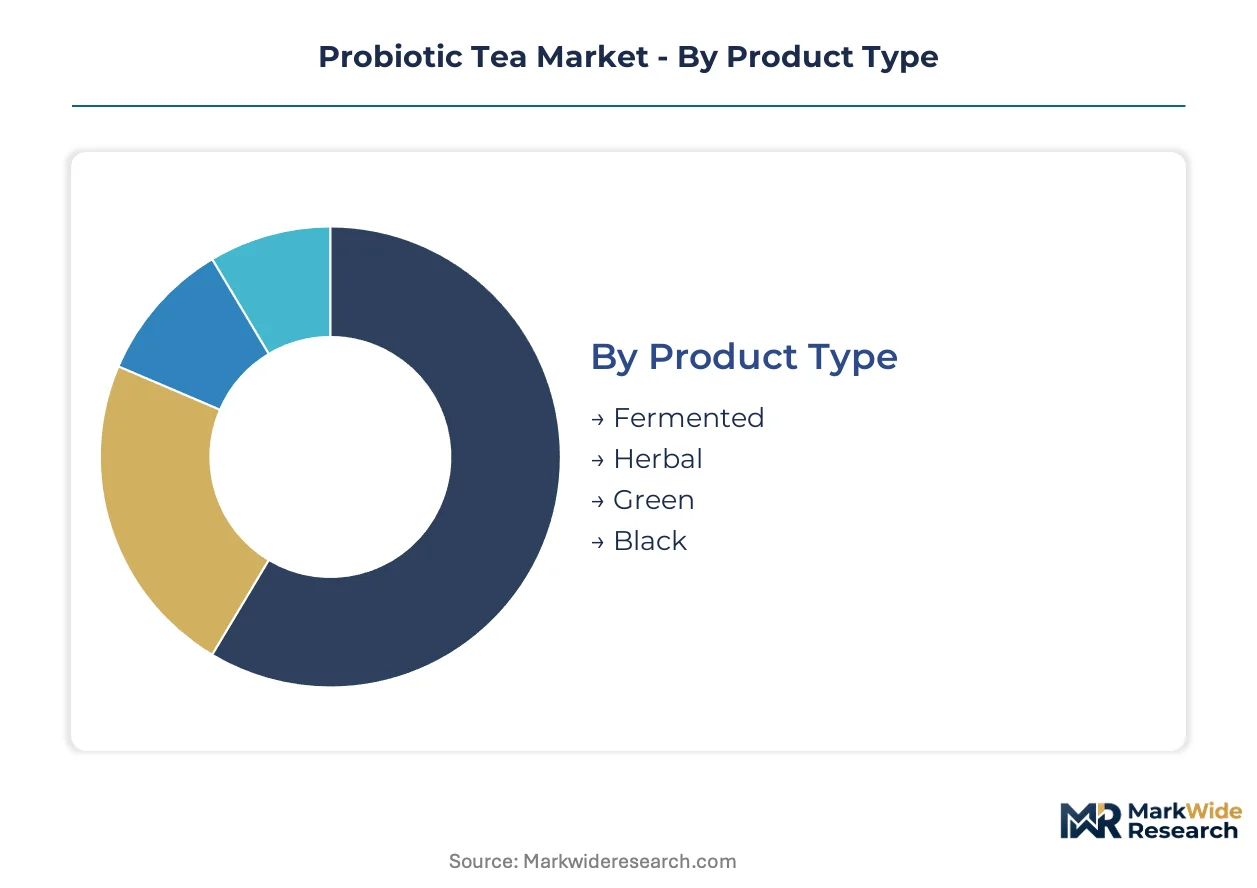
Segmentation in probiotic tea reveals how live-culture credibility, packaging convenience, and channel access create distinct competitive arenas. Manufacturers must align strain specifications, cold-chain requirements, and flavor innovation to capture specific consumption occasions and retail environments.
Product Type:
Fermented variants face the strongest substitution pressure from shelf-stable pasteurized alternatives, while non-fermented herbal and conventional tea formats compete against standard wellness beverages without probiotic premiums.
- Fermented:Kombucha and other live-culture brews rely on controlled anaerobic fermentation with SCOBY cultures to maintain viable bacterial counts through consumption. Demand concentrates in Germany and the Netherlands where traditional fermentation cultures support premium retail positioning, though cold-chain infrastructure costs constrain geographic expansion. Refrigerated distribution requirements limit mass-market penetration despite higher perceived efficacy.
- Herbal:Non-caffeinated botanical bases including chamomile, rooibos, and ginger provide gentler digestive support for evening consumption occasions. Demand clusters among wellness-focused millennials in the United States seeking caffeine-free functional alternatives, with organic certification functioning as table-stakes for shelf placement.
- Green:Catechin-rich camellia sinensis bases combined with Lactobacillus strains target antioxidant-conscious consumers in Japan and South Korea. L-theanine content supports cognitive positioning beyond digestive health.
- Black:Fully oxidized tea bases with robust flavor profiles appeal to traditional tea drinkers transitioning to functional formats. Higher tannin content requires strain selection optimized for acidic environments.
Fermented variants anchor the volume base while herbal formulations gain share at the steepest rate.
Packaging Type:
Cost tier differentiation separates convenience-driven single-serve formats from value-oriented bulk purchasing, with material sustainability emerging as a secondary sorting mechanism for premium positioning.
- Bottled:Ready-to-drink formats in glass or PET enable precise live-culture dosing and carbonation retention for kombucha variants. Demand concentrates in United States supermarkets where impulse purchase behavior drives trial, though aluminum and paperboard alternatives are displacing plastic for sustainability positioning.
- Loose Leaf:Bulk dried formulations with added probiotic powder require consumer brewing equipment but offer per-serving cost advantages. Home fermentation enthusiasts in Germany and Australia favor this format for customization control.
- Tea Bags:Single-serve sachets with microencapsulated bacteria enable ambient storage and broad retail distribution. Convenience positioning captures office and travel consumption in Japan and the United Kingdom.
- Cans:Aluminum formats with nitrogen flushing extend shelf life for pasteurized variants while supporting on-premise consumption. Craft positioning in United States cafés and bars drives adoption for social consumption occasions.
Bottled packaging commands the largest transaction throughput while cans expand most quickly into on-premise channels.
Distribution Channel:
Application-based channel selection determines whether brands pursue discovery-driven trial or loyalty-driven replenishment, with cold-chain capability filtering which products access which pathways.
- Online:Direct-to-consumer platforms and marketplace listings enable subscription-based replenishment with cold-chain home delivery. Urban coastal markets in the United States show highest retention for refrigerated perishables, with wellness-focused cohorts prioritizing convenience over supermarket browsing.
- Supermarkets:Mass retail placement requires pasteurized shelf-stable formulations or significant refrigeration infrastructure investment. Mainstream grocery in Germany and the United Kingdom drives volume through promotional pricing and impulse visibility.
- Health Stores:Specialty retailers with trained staff support premium live-culture positioning and strain-specific education. Independent natural grocers in California and New York function as gatekeepers for emerging brand credibility.
- Cafés:On-premise consumption creates experiential positioning for draft kombucha and customized blends. Third-wave coffee shops in Melbourne and Portland drive trend adoption through influencer visibility.
Supermarkets retain the largest transaction base while online channels climb the fastest in recurring revenue capture.
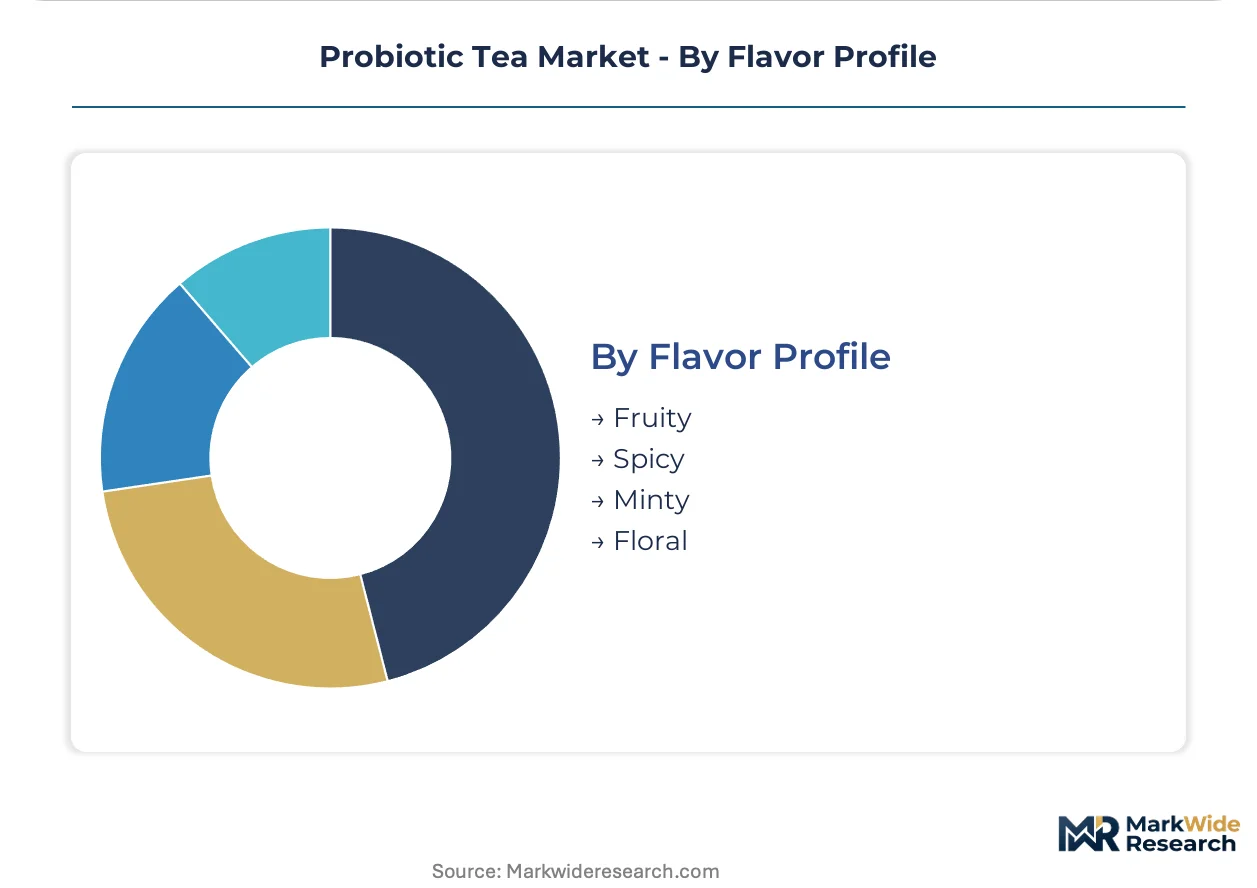
Flavor Profile:
Customer type differentiation separates adventurous experimentalists seeking novel combinations from traditionalists preferring familiar taste territories, with seasonal rotation strategies enabling year-round engagement.
- Fruity:Berry, citrus, and tropical infusions mask fermentation tang for novice consumers. Mango and passionfruit variants lead trial conversion in United States mass retail, with limited-edition seasonal releases driving social media engagement.
- Spicy:Ginger, turmeric, and cayenne formulations target inflammation-conscious consumers seeking functional intensity. Ayurveda-inspired positioning resonates in India and with South Asian diaspora communities in the United Kingdom.
- Minty:Peppermint and spearmint bases provide cooling sensory cues for digestive relief claims. Conventional flavor familiarity reduces purchase risk for mainstream transitioners in Germany and Australia.
- Floral:Lavender, hibiscus, and rose profiles support premium spa and wellness positioning. Instagram-worthy aesthetics drive gift purchasing and hospitality channel placement in France and Japan.
Fruity profiles anchor the volume base while spicy formulations gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in probiotic tea tilt toward net importing positions in North America and Asia-Pacific, while Germany and the Netherlands maintain export surplus through established fermentation infrastructure and EU regulatory harmonization.
United States
Wellness-focused millennials in coastal urban markets drive refrigerated perishable demand, with subscription replenishment models capturing recurring revenue in California and New York. FDA enforcement discretion on structure-function claims forces conservative labeling strategies and clinical study partnerships. Los Angeles and Brooklyn anchor craft kombucha clusters where third-wave cafés drive trend visibility through draft experiential positioning.
Germany
Kombucha and fermented tea cultures achieve mainstream retail penetration through Rewe and Edeka supermarket chains, with home fermentation enthusiasts concentrated in Berlin and Munich. EFSA qualified presumption of safety frameworks create clearer strain approval pathways, encouraging documented probiotic R&D investment. Bavaria hosts precision brewing technology clusters optimizing controlled fermentation temperatures between 20°C and 30°C for commercial scale-up.
Japan
Green tea catechin combinations with Lactobacillus strains target antioxidant-conscious consumers in Tokyo and Osaka, where L-theanine content supports cognitive health positioning beyond digestive claims. METI standards for functional food labeling govern permissible health messaging, requiring substantiation for live culture benefits. Kanto region beverage manufacturers lead microencapsulation adoption for ambient-stable tea bag formats.
Netherlands
Spray-dried bacterial coating technology spreads rapidly through Amsterdam and Rotterdam production facilities, enabling mass-market shelf-stable formulations. REACH compliance for novel strain introductions adds regulatory review timelines, though EU Green Deal sustainability incentives accelerate packaging material transitions. Randstad logistics infrastructure supports cold-chain distribution networks for premium live-culture exports to neighboring markets.
Australia
Loose leaf bulk formats with added probiotic powder capture home fermentation enthusiasts in Melbourne and Sydney, where per-serving cost advantages outweigh convenience premiums. TGA therapeutic goods frameworks create classification ambiguity for cross-category positioning between food and supplement claims. Victoria specialty retailers function as gatekeepers for emerging brand credibility through trained staff education on strain-specific benefits.
Probiotic Tea Market Competitive Landscape
Concentration sits with artisanal live-culture specialists and mass-market pasteurized formulators competing across divergent cold-chain investment requirements. Three to five established players anchor premium refrigerated positioning, while private label and regional bottlers fragment shelf-stable alternatives. Strategic moves cluster around USDA organic certification acquisition and direct-to-consumer subscription platform development, with selective partnerships bridging capability gaps in fermentation science expertise.
Within the live-culture specialist tier, GT's Living Foods and Health-Ade LLC exemplify premium refrigerated positioning through raw unpasteurized credibility, while KeVita occupies the mass-market pasteurized vector with multi-strain formulations. These three anchors demonstrate how strain specification transparency and organic certification function as table-stakes for shelf placement differentiation. Each represents a distinct archetype: pioneer heritage positioning, small-batch artisanal sourcing, and scaled grocery channel penetration respectively.
| Leading Market Players |
|---|
| GT's Living Foods |
| KeVita |
| Health-Ade LLC |
| Brew Dr. Kombucha |
| Humm Kombucha |
| Yogi Tea |
| Celestial Seasonings |
| Bigelow Tea |
| The Kombucha Shop |
| Others |
Value Network & Pricing Analysis
USDA organic certification gates both supplier qualification and price differentiation simultaneously, creating a bifurcated market where certified live-culture producers command refrigerated premium positioning while uncertified alternatives compete on convenience-driven shelf-stable value tiers.
Pricing Analysis
Wellness-focused millennials anchor subscription-based pricing structures for refrigerated perishables, with three-tier pricing stratification across raw unpasteurized premium, small-batch organic mid-tier, and mass-market pasteurized economy levels. Price differentiation rests on live-culture count verification and cold-chain reliability rather than flavor innovation alone. Cost compression in shelf-stable segments is intensifying because microencapsulation technology lowers production barriers. Price-sensitive mainstream grocery buyers drive volume at economy tiers, while subscription cohorts demonstrate lowest price elasticity for verified strain transparency.
Supply Chain Analysis
Inventory lead times for SCOBY cultures and precision fermentation equipment extend supplier qualification cycles, compressing margin recovery timelines for artisanal scale-ups. Supply concentrates in Germany, the Netherlands, and the United States, with Bavaria and Amsterdam anchoring controlled fermentation technology clusters. Raw material dependencies center on organic tea leaf sourcing, bacterial strain banks, and refrigerated logistics infrastructure. Single-source vulnerability in cold-chain distribution networks poses structural risk for perishable variants. Distribution runs through direct-to-consumer platforms for premium tiers and mainstream grocery for mass-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as post-pandemic wellness expenditure normalization intersects with sustained functional beverage premiumization, creating countervailing demand pressures that favor agile supply chain positioning.
For Market Incumbents: Consolidate cold-chain infrastructure investments in coastal urban clusters where subscription retention rates justify capital deployment. Acquire precision fermentation technology capabilities to reduce batch failure rates and defend margin position against emerging shelf-stable substitutes. Prioritize USDA organic certification maintenance as table-stakes for mainstream grocery expansion.
For New Entrants and Emerging Players: Direct-to-consumer subscription service gaps in secondary metropolitan markets offer white-space entry points with lower customer acquisition costs than saturated coastal corridors. Target Australia and Japan where home fermentation enthusiasm and green tea catechin combinations respectively show penetrable demand. Pursue microencapsulation-enabled ambient distribution to bypass incumbent cold-chain advantages.
For Investors and Strategic Acquirers: FDA strain-specific approval pathway evolution reshapes the acquisition landscape toward clinically validated culture documentation. Five-to-ten year viability favors targets with fermentation scientist depth and modular compliance capabilities across food and supplement frameworks. Monitor EFSA qualified presumption of safety framework expansion as inflection signal for European market access premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Investment | Refrigerated distribution networks in California and New York enable live-culture credibility claims that command subscription premiums. |
| USDA Organic Certification Acquisition | Federal verification unlocks placement in Rewe and Edeka supermarket chains where organic positioning drives impulse trial conversion. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models in urban coastal markets capture recurring revenue with higher lifetime value than supermarket trial patterns. |
| Precision Fermentation Technology Partnership | Bavaria-based brewing technology clusters reduce batch failure rates through consistent 20°C to 30°C temperature maintenance. |
| Microencapsulation R&D Investment | Spray-dried bacterial coatings from Amsterdam production facilities enable ambient shelf-stable formulations for price-sensitive mass retail. |
Research Methodology
A standing panel of brand managers, category buyers at natural grocers, fermentation scientists, and cold-chain logistics specialists provided ongoing calibration across the research cycle. Primary interviews with these stakeholders combined with secondary validation from FDA enforcement discretion filings, EFSA qualified presumption of safety registers, USDA organic certification databases, and Nielsen retail audit data. Bottom-up strain-specific demand modeling and top-down functional beverage category sizing enabled triangulation across independent analytical paths.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented demand by product type, packaging format, distribution channel, and flavor profile, with regional regulatory clusters as an additional modeled dimension. CAGRs derived from fitted growth curves incorporated live-culture credibility adoption rates, subscription platform penetration, and shelf-stable substitution elasticity as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA food and dietary supplement frameworks and EFSA strain approval pathways; material policy shifts would require re-modeling with revised compliance cost assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Pyramid Tea Bags Market
Tea
Organic Tea Market
Tea
Instant Tea Market
Tea
Tea Packaging Market
Tea
Bottled Milk Tea Market
Tea
Tea Polyphenols Market
Tea
Instant Tea Premixes Market
Tea
White Tea Market
Tea
Butterfly Pea Flower Tea Market
Tea
Matcha Products Market
Tea
Spray-Dried Tea Products Market
Tea
Tea Infuser Market
Tea
Light-Fermented Tea Market
Tea
Africa Ready to Drink Tea Market
Tea
Smart Tea Maker Market
Tea
Global Tea Extract Market