
 South America Tea Market | 2026-2036
South America Tea Market Size, Share, and Industry Trends Forecast 2026-2036
South America Tea Market Analytics
ISO 3720 certification for tea grading and quality assessment is rotating competitive access across the South America tea landscape, favoring producers with laboratory infrastructure and export documentation capabilities. Establecimiento Las Marías leverages its vertically integrated supply chain from Misiones plantations to finished goods. Taragüi sustains brand dominance through deep distribution in Argentine supermarkets and convenience channels. Unilever (Lipton) competes by extending its global black tea formulations into Brazilian and Chilean retail shelves.
South America tea encompasses Camellia sinensis-derived black, green, and white teas alongside native herbal infusions such as Ilex paraguariensis (yerba maté), typically processed through drying, milling, and thermal treatment to achieve moisture content below 8% for shelf stability. The product serves both ritual consumption and functional wellness applications across household and foodservice channels. Black tea and yerba maté occupy mature volume positions with entrenched consumer habits, while herbal tea segments attract margin expansion as wellness-positioned SKUs command pricing premiums in specialty stores. Online retail channels represent the fastest-growing distribution vector, though supermarkets still control the bulk of regional throughput.
Argentina's National Administration of Medicines, Foods and Medical Technology (ANMAT) governs food-contact safety and additive limits for packaged teas, while Brazil's National Health Surveillance Agency (ANVISA) enforces pesticide residue thresholds that directly shape sourcing requirements for imported leaf. MERCOSUR's harmonized technical regulations create cross-border compliance efficiencies but also raise barriers for non-member suppliers. Stakeholders must monitor evolving organic certification demands from European export destinations and the accelerating shift toward sustainable packaging mandates across Andean and Southern Cone markets.
Market Dynamics
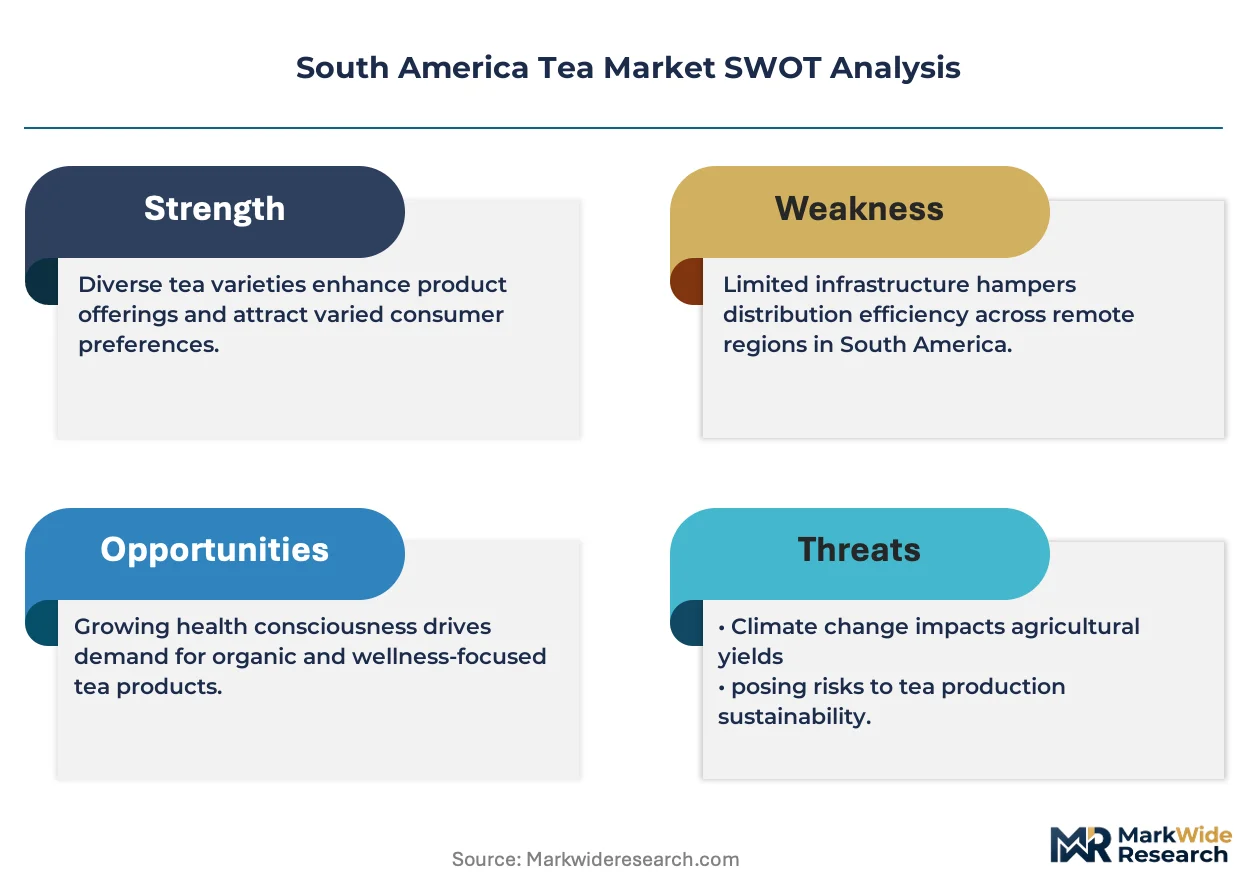
ISO 3720 certification requirements are reconfiguring competitive access across South America, elevating producers with laboratory infrastructure while marginalizing smallholders lacking export documentation capabilities. This structural filter is concentrating supply relationships toward vertically integrated plantation-to-package operations.
Growth Catalysts
- ANMAT harmonization protocols:Argentina's National Food Code alignment with MERCOSUR technical regulations is streamlining cross-border herbal infusion trade, reducing compliance duplication for packaged tea exporters.
- Specialty beverage channel expansion:Premium cafés in São Paulo and Buenos Aires are diversifying beyond coffee into curated tea menus, creating pull-through demand for ceremonial-grade yerba maté and single-origin Camellia sinensis.
- Moisture-controlled thermal processing:Advanced drying technologies achieving sub-8% moisture content are extending shelf stability for regional distribution, enabling Andean producers to reach Atlantic coast markets.
Market Restraints
- Misiones supply concentration:Argentina's yerba maté belt dominates raw leaf availability, creating geographic vulnerability to climate volatility and price transmission rigidities.
- ANVISA residue thresholds:Brazil's pesticide maximum limits for imported leaf impose sourcing constraints that exclude certain Asian and African suppliers from Mercosur-adjacent markets.
- Instant coffee substitution:Low-cost soluble coffee formulations retain household penetration advantages across Brazilian and Colombian working-class segments, compressing tea trial rates.
Strategic Opportunities
- Chilean wellness retail gap:Santiago's pharmacy and specialty store channels show underpenetration for functional herbal SKUs, presenting first-mover positioning for adaptogen-positioned blends.
- Direct-to-consumer subscription models:Online retail infrastructure is maturing across the Southern Cone, enabling brands to bypass supermarket slotting fees and capture recurring revenue.
- EU organic certification convergence:European import standards are creating compliance pull that rewards Argentine and Brazilian producers investing in certified organic cultivation.
Industry Challenges
- ISO 3720 laboratory scarcity:Certified grading facilities remain concentrated in Buenos Aires and São Paulo, creating logistical bottlenecks for regional producers seeking export documentation.
- Sustainable packaging capex requirements:Biodegradable and compostable material transitions demand retooling investment that strains mid-tier processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Tea Market |
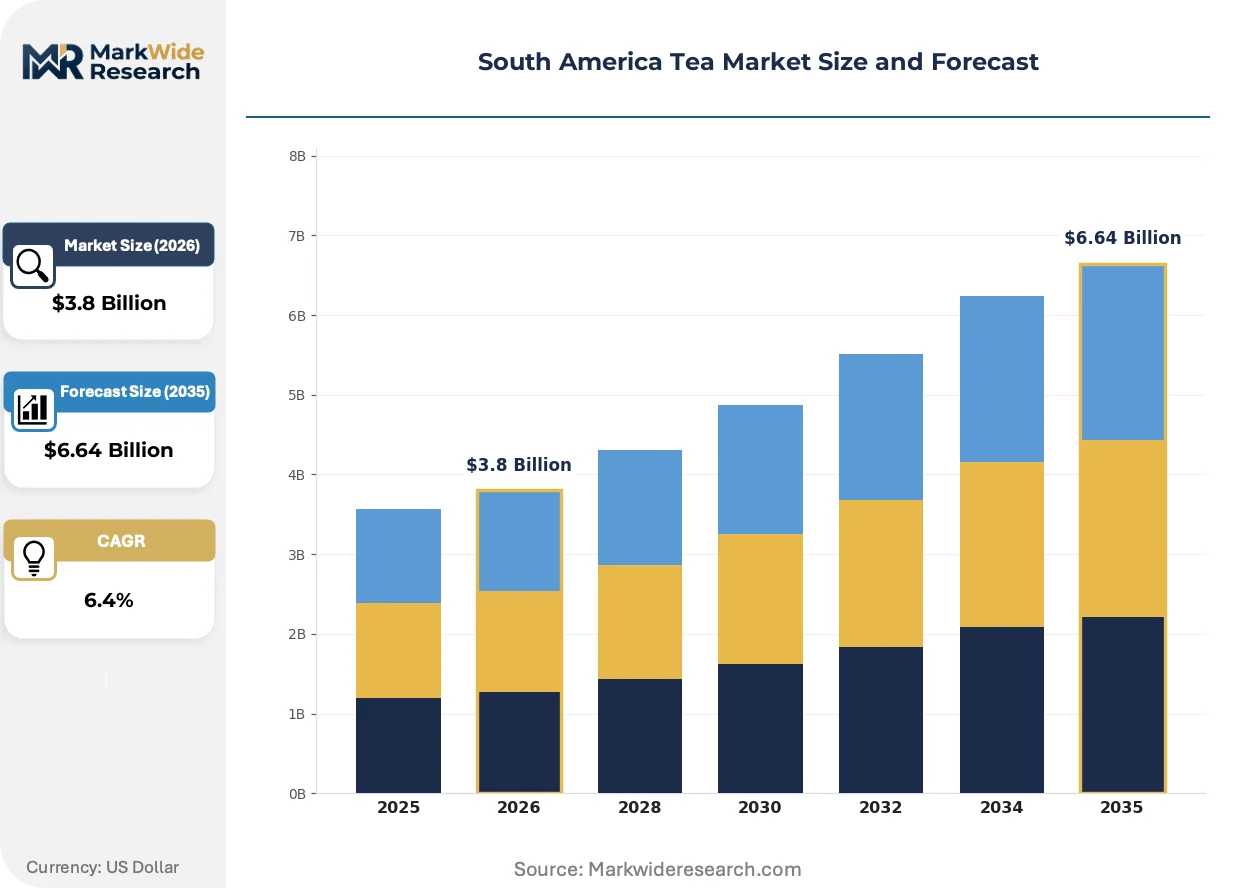
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Tea, Green Tea, Herbal Tea, White Tea Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores End User: Households, Cafés, Restaurants, Hotels Packaging Type: Loose Leaf, Tea Bags, Bottled, Tins |
| Companies Covered | Establecimiento Las Marías, Taragüi, La Virginia SA, Unilever (Lipton), Coca-Cola Company (Fuze Tea), CBSé, Matte Leão, Rosamonte, La Tranquera, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Tea Market Evolving Landscape
Active fermentation control technologies and precision moisture management are reshaping processing economics across the Southern Cone. These innovations are compressing traditional curing timelines while preserving organoleptic profiles.
Controlled-atmosphere fermentation systems is supplanting open-air traditional curing methods for premium yerba maté production. Argentine cooperatives in Misiones are adopting these systems to reduce weather dependency and standardize alkaloid content. The technology is compressing seasonal production windows and enabling year-round supply contracts with export buyers.
ANVISA's updated pesticide residue monitoring framework is tightening enforcement of maximum limits for imported Camellia sinensis leaf entering Brazilian ports. Industrial blenders are responding by diversifying sourcing toward domestic and Mercosur-origin suppliers with traceable cultivation records. This regulatory friction is elevating compliance costs for black tea formulations previously reliant on Asian bulk leaf.
Specialty retailers in Buenos Aires and Santiago are unbundling traditional supermarket tea assortments into curated single-origin and small-batch offerings. Independent shops are displacing mass-market SKUs with direct-trade relationships and origin storytelling. This channel fragmentation is most visible in Argentina's Palermo and Chile's Providencia districts, where consumer willingness-to-pay for provenance transparency exceeds regional averages.
South America Tea Market Segmentation
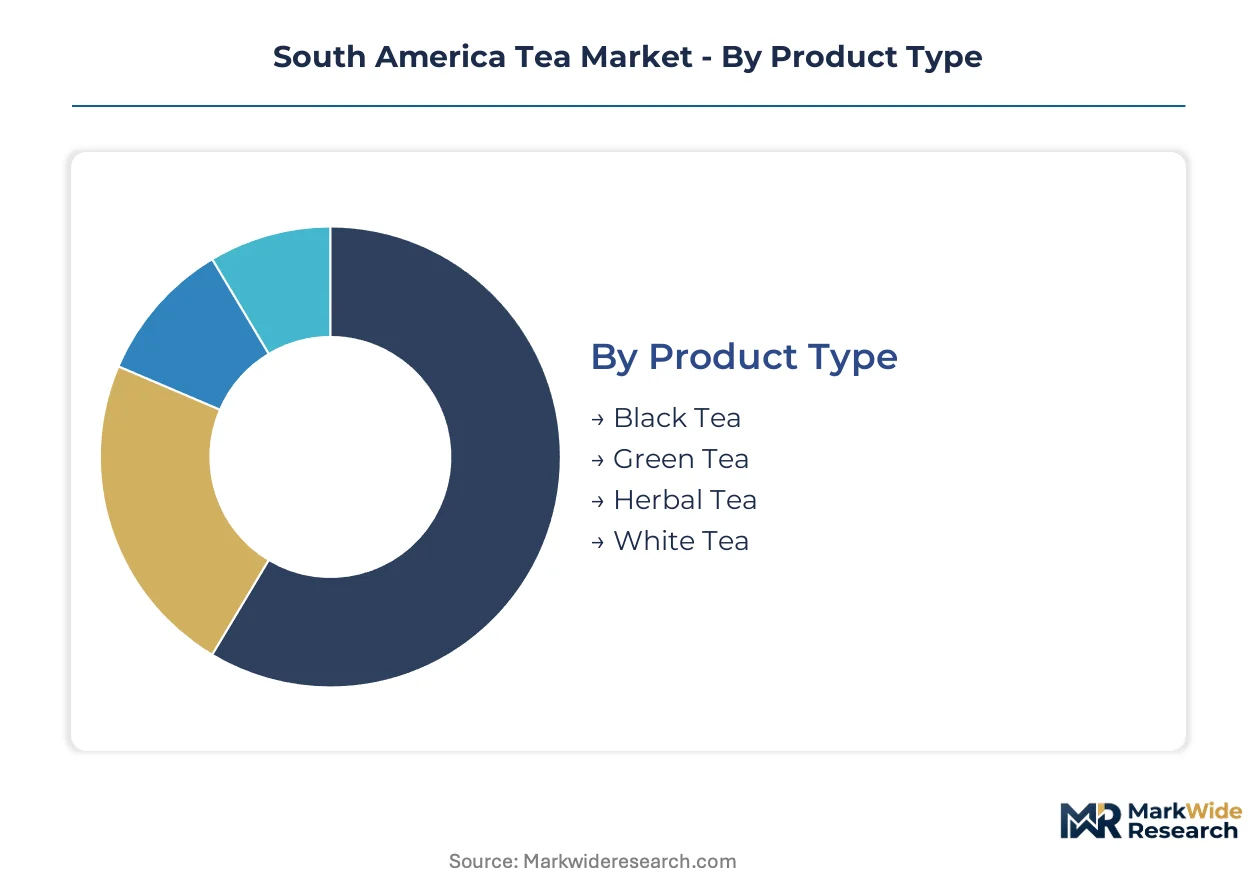
Tea consumption patterns across South America fragment sharply along ritual versus convenience axes. Yerba maté traditions, black tea imports, and wellness-positioned herbal infusions each command distinct supply chains and margin profiles. Understanding these fault lines reveals where substitution threats concentrate and where brand loyalty defends pricing power.
Product Type:
Black tea and yerba maté face the most acute substitution pressure from instant coffee and energy drinks, while premium-positioned segments exploit wellness differentiation to escape commodity traps.
- Black Tea:Camellia sinensis leaf oxidized to full color, typically sourced from Sri Lankan and Kenyan auctions for Brazilian blenders. Demand concentrates in São Paulo's working-class households where Unilever's Lipton formulations compete directly with soluble coffee sachets. ANVISA residue monitoring has forced sourcing shifts toward Mercosur-certified suppliers, elevating landed costs.
- Herbal Tea:Non-Camellia botanical infusions including chamomile, mint, and regional adaptogens like boldo and cedrón. Santiago's pharmacy channel shows underpenetration for functional SKUs, creating first-mover positioning for adaptogen-positioned blends targeting stress and sleep applications.
- Green Tea:Minimally oxidized leaf with elevated catechin content, predominantly imported from China and Japan. Brazilian wellness consumers drive demand through specialty retailers in Rio de Janeiro's Zona Sul.
- White Tea:Bud-only harvest with minimal processing, commanding the highest per-kilogram pricing in boutique channels. Palermo district cafés in Buenos Aires stock ceremonial-grade offerings for expatriate and affluent local clientele.
Black tea retains volume leadership across Brazilian retail shelves; herbal tea holds the steepest expansion curve as wellness positioning penetrates pharmacy and specialty channels.
Distribution Channel:
Channel selection directly determines margin capture, with supermarket slotting fees consuming 15-25% of wholesale value while direct models preserve full pricing control.
- Supermarkets:Dominant throughput channel controlling 60-70% of packaged tea volume across Argentina, Brazil, and Chile. Carrefour and Cencosud chains demand promotional participation that compresses net margins for mid-tier brands.
- Online Retail:Fastest-climbing vector enabling subscription models and origin storytelling that bypass retail intermediaries. Mercado Libre and dedicated brand sites capture recurring revenue from Southern Cone urban consumers.
- Specialty Stores:Curated assortments emphasizing single-origin provenance and direct-trade relationships. Buenos Aires' Palermo and Santiago's Providencia districts concentrate independent retailers with above-average willingness-to-pay.
- Convenience Stores:Impulse-oriented channel for single-serve sachets and ready-to-drink formulations. Petrobras and YPF station networks across Brazil and Argentina stock mass-market SKUs for travel consumption.
Supermarkets retain volume leadership through established distribution infrastructure; online retail holds the steepest expansion curve as logistics networks mature.
End User:
Foodservice procurement patterns diverge sharply from household purchasing, with institutional buyers prioritizing consistent supply over provenance storytelling.
- Households:Bulk purchasing of yerba maté in 1-kg packages dominates Argentine consumption, with Misiones-origin product commanding loyalty premiums. Brazilian households split between black tea bags and loose-leaf chimarrão traditions.
- Cafés:Specialty beverage shops in São Paulo and Buenos Aires are diversifying beyond coffee into curated tea menus, creating pull-through demand for ceremonial-grade yerba maté and single-origin Camellia sinensis.
- Restaurants:Mid-tier dining establishments prioritize cost-stable black tea formulations for post-meal service, with procurement centralized through foodservice distributors like Sysco and GFS.
- Hotels:Amenities programs and lobby tea service drive demand for individually wrapped sachets with branding opportunities. Chilean hospitality chains in Santiago and Valparaíso source premium offerings for international guest expectations.
Households retain volume leadership through yerba maté ritual consumption; cafés hold the steepest expansion curve as beverage menu diversification accelerates.
Packaging Type:
Packaging selection signals quality tier and determines shelf-life economics through moisture barrier performance.
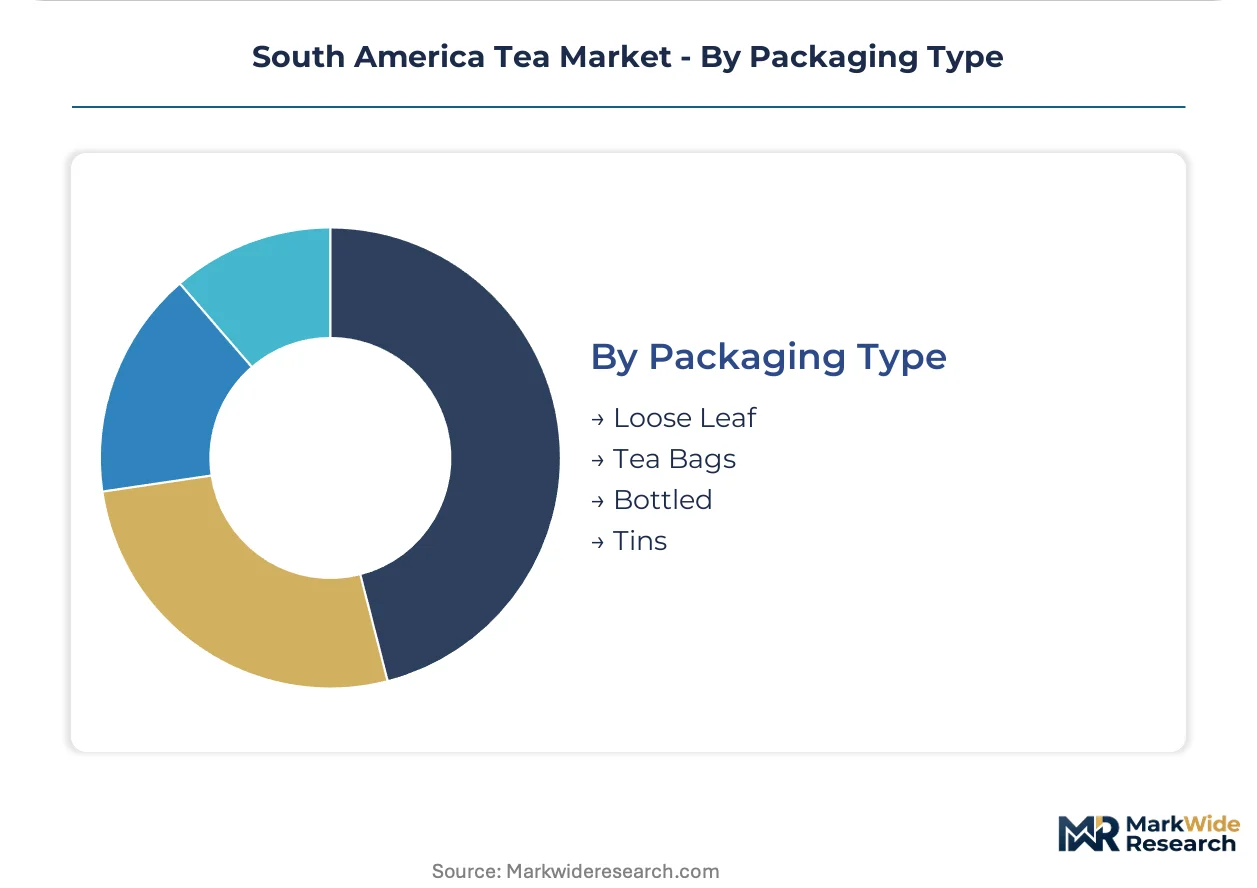
- Loose Leaf:Bulk presentation preferred for yerba maté consumption in Argentina, Uruguay, and southern Brazil. Requires calibrated humidity control below 8% moisture to prevent mold in subtropical storage conditions.
- Tea Bags:Convenience format dominating Brazilian and Chilean retail, with heat-sealed filter paper or nylon pyramid constructions. Twinings and Lipton compete on string-and-tag premiumization.
- Bottled:Ready-to-drink formulations in PET or glass, including tereré (cold yerba maté) variants popular in Paraguay and northeastern Argentina. Coca-Cola and local bottlers compete for refrigerator space.
- Tins:Premium positioning for gift markets and specialty retail, with Argentine and Chilean producers leveraging Patagonian imagery for export appeal. Reusability supports sustainability messaging.
Loose leaf retains volume leadership through yerba maté tradition; bottled formats hold the steepest expansion curve as ready-to-demand penetrates convenience channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANMAT harmonization with MERCOSUR technical regulations is streamlining cross-border trade for packaged tea exporters across the Southern Cone. This regulatory alignment reduces compliance duplication and accelerates market access for regional producers seeking to expand beyond domestic boundaries.
Argentina
Yerba maté ritual consumption anchors household demand through 1-kg bulk purchases of Misiones-origin product. ANMAT governs food-contact safety and additive limits for packaged teas under the National Food Code. The Misiones province plantation belt concentrates vertically integrated operations from raw leaf processing through finished goods distribution.
Brazil
Black tea bag consumption competes with soluble coffee sachets in São Paulo's working-class households while wellness consumers in Rio de Janeiro's Zona Sul drive green tea demand through specialty channels. ANVISA enforces pesticide residue thresholds that reshape sourcing requirements for imported Camellia sinensis leaf. São Paulo state hosts the dominant laboratory infrastructure for ISO 3720 certification testing.
Chile
Santiago's pharmacy and specialty store channels show underpenetration for functional herbal SKUs, creating positioning opportunities for adaptogen-positioned blends. The country's national food regulator aligns with MERCOSUR protocols for cross-border herbal infusion standards. Providencia district retailers concentrate independent shops with above-average willingness-to-pay for provenance transparency.
Uruguay
Loose-leaf yerba maté consumption traditions persist with calibrated humidity control requirements below 8% moisture for subtropical storage stability. MERCOSUR harmonized technical regulations facilitate duty-free movement of Argentine-processed maté across the border. Montevideo serves as the secondary distribution hub for premium-grade products destined for domestic and export markets.
Paraguay
Cold yerba maté tereré variants dominate ready-to-drink formulations in convenience and foodservice channels. The country's national standards body participates in MERCOSUR technical regulation alignment for regional trade facilitation. Asunción and Ciudad del Este processing facilities supply PET-bottled formulations for cross-border distribution into northeastern Argentina.
South America Tea Market Competitive Landscape
Player mix skews toward plantation-integrated heritage brands alongside multinational beverage conglomerates with global black tea formulations. Market structure concentrates around vertically integrated Misiones-origin producers controlling raw leaf supply and finished goods distribution. Three strategic archetypes dominate: heritage plantation-to-package operators, multinational FMCG platforms leveraging global brand equity, and specialty direct-trade retailers emphasizing origin storytelling. Competitive moves center on sustainable packaging transitions requiring retooling investment and direct-to-consumer subscription models bypassing supermarket slotting fees.
Among Argentine heritage producers, Establecimiento Las Marías and Taragüi exemplify the vertically integrated archetype with captive plantation supply chains. Unilever occupies a position representing multinational platform strategies through Lipton brand extension into Brazilian and Chilean retail shelves. These three anchors illustrate how supply control, brand equity, and regulatory compliance capabilities stratify competitive positioning across the Southern Cone.
| Leading Market Players |
|---|
| Establecimiento Las Marías |
| Taragüi |
| La Virginia SA |
| Unilever (Lipton) |
| Coca-Cola Company (Fuze Tea) |
| CBSé |
| Matte Leão |
| Rosamonte |
| La Tranquera |
| Others |
Value Network & Pricing Analysis
ISO 3720 certification gates both supply qualification and price differentiation simultaneously across the Southern Cone tea landscape, creating a structural filter where laboratory-equipped producers capture premium positioning while documentation-poor smallholders face margin compression. This regulatory architecture concentrates pricing power among vertically integrated plantation-to-package operators with export documentation capabilities.
Pricing Analysis
Certification level creates the primary spread between commodity and specialty tiers across South American tea markets. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 3720 compliance status, organic accreditation, and moisture-controlled processing precision. Price differentiation intensifies as ANVISA residue monitoring elevates compliance costs for imported leaf, compressing margins on black tea formulations. Brazilian working-class households exhibit highest price sensitivity, while Palermo district consumers in Buenos Aires demonstrate lowest sensitivity to provenance-premium positioning.
Supply Chain Analysis
Argentina and Brazil anchor raw leaf availability across the South American tea supply chain, with Misiones province plantations feeding regional processing capacity. Camellia sinensis leaf, Ilex paraguariensis harvests, and certified organic cultivation records constitute critical input dependencies. Single-source vulnerability concentrates in the Misiones yerba maté belt, exposing downstream blenders to climate volatility and price transmission rigidities. Distribution runs through vertically integrated heritage brands controlling supermarket shelf space, though online retail infrastructure is eroding traditional channel dominance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South American tea markets sit in early-cycle expansion as wellness-positioned herbal SKUs penetrate pharmacy and specialty channels previously dominated by commodity formats. Direct-to-consumer subscription models and sustainable packaging mandates create structural tailwinds for agile entrants.
For Market Incumbents: Compound brand equity through backward integration into certified organic cultivation, securing captive supply as European import standards tighten. Invest in ISO 3720 laboratory infrastructure to gatekeep export documentation access, defending margin position against emerging plantation-to-package competitors. Channel control through exclusive supermarket partnerships remains essential as slotting fees rise. For New Entrants and Emerging Players: Subscription-layer service gaps in direct-to-consumer fulfillment present first-mover opportunities for recurring revenue capture. Chile's pharmacy channel for functional herbal SKUs offers the most penetrable white-space target, with Santiago's Providencia district demonstrating above-average willingness-to-pay for adaptogen-positioned blends. Go-to-market through Mercado Libre marketplace integration bypasses traditional retail intermediaries. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sustainable packaging transitions, favoring acquisition targets with completed retooling investment. Long-term viability across the analysis window rests on organic certification convergence with EU import standards. Vertically integrated Misiones-origin producers with laboratory infrastructure represent the priority acquisition archetype. Signal to monitor: ANMAT harmonization protocol expansions accelerating cross-border consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captures EU export compliance premiums before certification scarcity intensifies. |
| ISO 3720 Laboratory Certification | Gates export documentation access, creating competitive moats against regional smallholders. |
| Direct-to-Consumer Subscription Launch | Bypasses Carrefour and Cencosud slotting fees while capturing recurring revenue from Southern Cone urban consumers. |
| Sustainable Packaging Transition | Aligns with emerging biodegradable mandates across Andean and Southern Cone markets. |
| Pharmacy Channel Expansion | Exploits underpenetration in Santiago's functional herbal SKU segment for first-mover positioning. |
Research Methodology
A spread of perspectives from plantation operations managers, ANMAT regulatory affairs specialists, supermarket category buyers, specialty café procurement heads, and export documentation coordinators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through ANVISA residue monitoring frameworks, MERCOSUR technical regulation harmonization protocols, customs trade records, and organic certification databases. Bottom-up volume modeling triangulated against top-down market sizing across product type, distribution channel, and end-user segmentation dimensions.
Segmentation dimensions modeled include product category, packaging format, distribution channel tier, and geographic regulatory cluster across the projection horizon. CAGRs derived from historical consumption pattern analysis, adjusted for channel shift acceleration and certification adoption curves. Forecast inputs incorporated ANMAT harmonization protocol implementation timelines and EU organic import standard convergence trajectories.
Forecasts assume regulatory continuity in ANMAT, ANVISA, and MERCOSUR technical regulation regimes; material policy shifts would require re-modeling. Climate volatility in the Misiones yerba maté belt and sudden pesticide residue threshold adjustments represent primary forecast revision risks. Recalibration cycles align with material shifts in certification adoption rates and cross-border trade facilitation developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Global Catechin Market
Tea
Slimming Tea Market
Tea
Instant Tea Premix Consumption Market
Tea
Matcha Market
Tea
Global Fruit Tea Market
Tea
Out of Home Tea Market
Tea
Pyramid Tea Bags Market
Tea
Herbal Tea Market
Tea
White Tea Extract Market
Tea
Black Tea Extracts Market
Tea
Smart Tea Set Market
Tea
Spray-Dried Tea Products Market
Tea
Ready-To-Drink (RTD) Tea Market
Tea
Africa Ready to Drink Tea Market
Tea
Asia-Pacific Green Tea Market
Tea
Global Ready-To-Drink Green Tea Market