
 Oolong Tea Market | 2026-2036
Oolong Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Oolong Tea Market Analysis
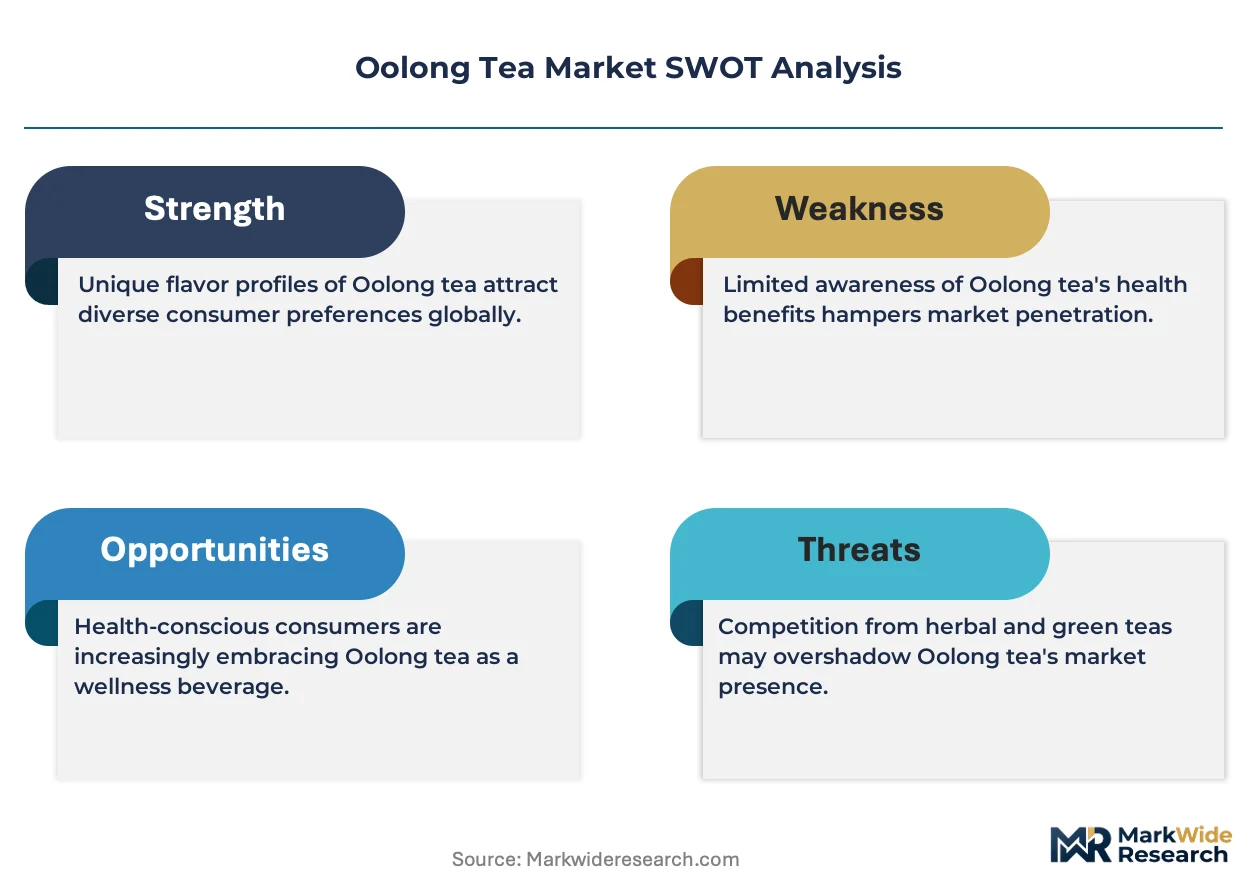
Sustainably sourced loose leaf material is recalibrating cost structures across premium oolong tiers. ITO EN Ltd. leverages its vertical integration from Taiwanese gardens to Japanese retail shelves, sustaining margin control through the full value chain. Harney and Sons Fine Teas anchors its competitive stance on direct-sourced Wuyi Mountain cultivars, while Rishi Tea and Botanicals differentiates through certified organic and Fair Trade supply relationships.
Oolong tea is a partially oxidized Camellia sinensis product, typically processed to oxidation levels between 15% and 85%, yielding aromatic complexity that bridges green and black tea categories. Its primary commercial purpose spans hot brewed consumption, ready-to-drink formulations, and functional ingredient applications in nutraceuticals. Loose leaf formats dominate margin pools in specialty channels, while ready-to-drink variants capture volume growth through convenience-oriented distribution. Semi-fermented oolong occupies the largest production share, though floral-infused variants are gaining traction among younger demographics in online retail channels.
China's SAMR enforces GB standards for pesticide residues and geographic indication labeling that directly shape export eligibility for Fujian and Guangdong producers. The FDA's import alert system and FSMA preventive controls govern US market access, filtering out non-compliant suppliers. Japan's Ministry of Agriculture, Forestry and Fisheries maintains positive list systems for agricultural chemicals that constrain sourcing flexibility. Stakeholders must monitor tightening maximum residue limits across these jurisdictions to preserve supply continuity and premium positioning.
Market Dynamics
China's tightening GB standards for pesticide residues and geographic indication labeling are compressing export eligibility for traditional Fujian and Guangdong producers, forcing supply chain reconfiguration toward certified organic cultivation and traceable origin documentation.
Growth Catalysts
- Functional beverage expansion:Ready-to-drink oolong formulations are penetrating convenience retail channels in the United States and Japan, capturing consumption occasions beyond traditional hot brewing.
- China's dual carbon goals:Energy-efficient processing subsidies are accelerating solar-powered withering and oxidation facility upgrades across Anxi and Wuyi Mountain production clusters.
- Nutraceutical ingredient demand:Polyphenol extraction for dietary supplements is creating incremental offtake from high-oxidation oolong cultivars in Taiwanese processing facilities.
Market Restraints
- Input cost volatility:Labor-intensive hand-rolling and multiple roasting cycles concentrate cost exposure in wage inflation across Fujian's Tieguanyin belt.
- Geographic supply concentration:Premium Wuyi Mountain terroir dependence creates single-point vulnerability to climate irregularity and localized drought.
- Japan's positive list system:Agricultural chemical restrictions constrain Taiwanese and Chinese supplier flexibility, disqualifying conventional cultivation batches from Japanese market entry.
Strategic Opportunities
- Direct-to-consumer subscription:Curated single-origin releases through proprietary e-commerce platforms bypass wholesale margin compression in North American specialty channels.
- Carbon-neutral certification:EU Green Deal-aligned farm-level auditing opens premium positioning in German and Dutch retail environments.
- Tea-tourism integration:Wuyi Mountain and Alishan experience-based retail captures visitor conversion through on-site processing demonstrations and limited-edition releases.
Industry Challenges
- Master roaster succession:Traditional charcoal roasting expertise concentrates among aging practitioners in Anxi and Phoenix Mountain, constraining quality replication.
- Organic conversion timelines:Three-year soil remediation requirements delay certified organic volume availability for export contract fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oolong Tea Market |
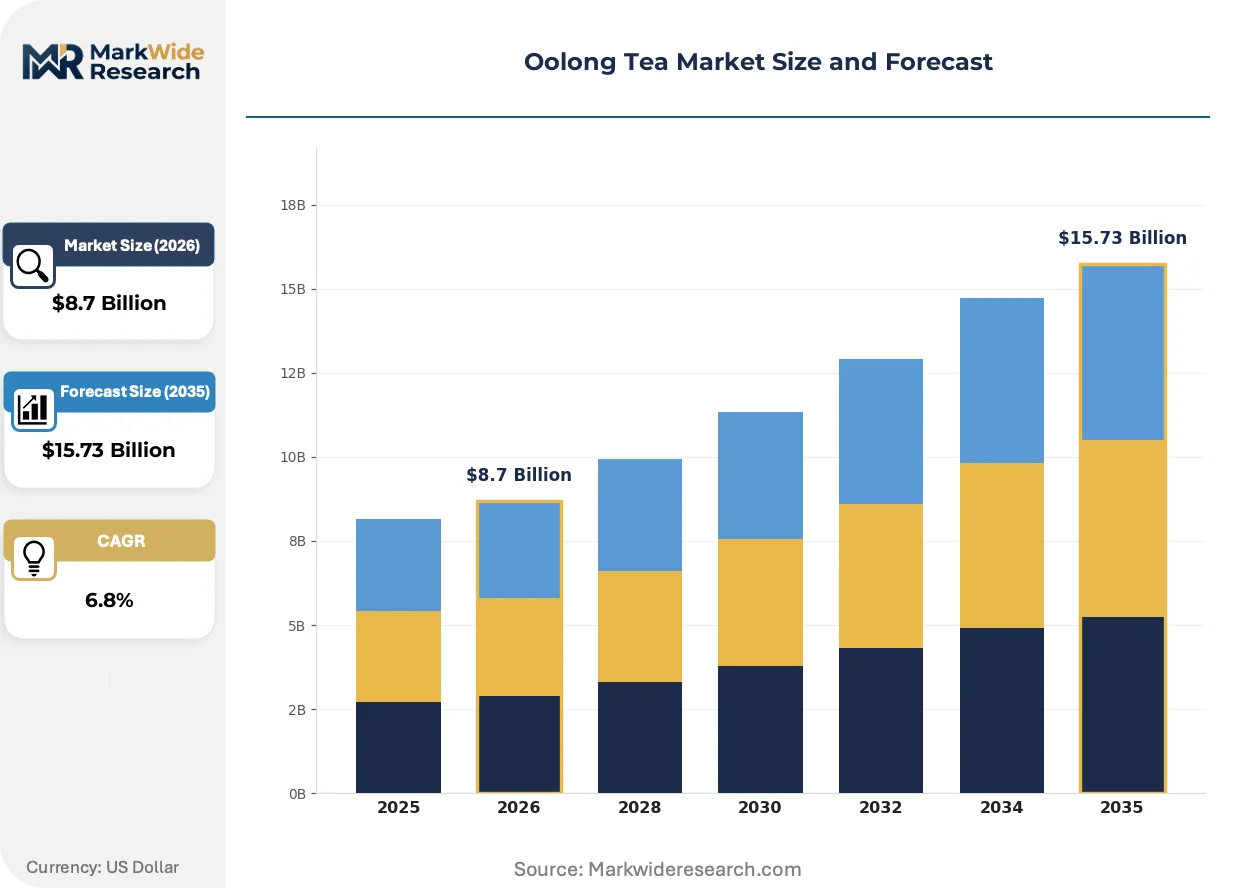
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Leaf, Tea Bags, Ready-to-Drink, Instant Powder Form: Fermented, Semi-Fermented, Floral, Fruity Packaging Type: Glass, Plastic, Carton, Pouch Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesalers |
| Companies Covered | ITO EN Ltd., East West Tea Company LLC, Harney and Sons Fine Teas, COFCO International, Adagio Teas, The Republic of Tea Inc., Dilmah Ceylon Tea Co. Plc, Harada Tea Processing Co Ltd., Rishi Tea and Botanicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oolong Tea Market Emerging Trajectories
Processing automation and origin verification technologies are compressing traditional craft timelines while expanding traceability depth, reshaping how premium positioning is constructed and defended across export markets.
Precision-controlled oxidation chambers with real-time humidity and temperature monitoring are overtaking open-air withering floors in mid-tier processing facilities. Taiwanese and Fujianese producers deploying these systems achieve batch consistency previously requiring decades of artisan expertise. The technology is compressing quality variance and enabling volume scaling without tiered pricing degradation.
China's SAMR enforcement of GB/T geographic indication standards is mandating blockchain-based origin documentation for Da Hong Pao and Tieguanyin export certification. Producers must integrate harvest-to-package tracking or forfeit premium market access. Fujian provincial authorities are subsidizing smallholder compliance infrastructure to preserve cluster competitiveness.
Specialty café and boutique hotel channels are unbundling traditional wholesale relationships in favor of direct farm partnerships with named-origin storytelling. This bypasses conventional import-distributor markups in United States and Australian urban markets. Roastery and hospitality buyers now specify cultivar, harvest date, and processing method in procurement contracts.
Oolong Tea Market Segmentation
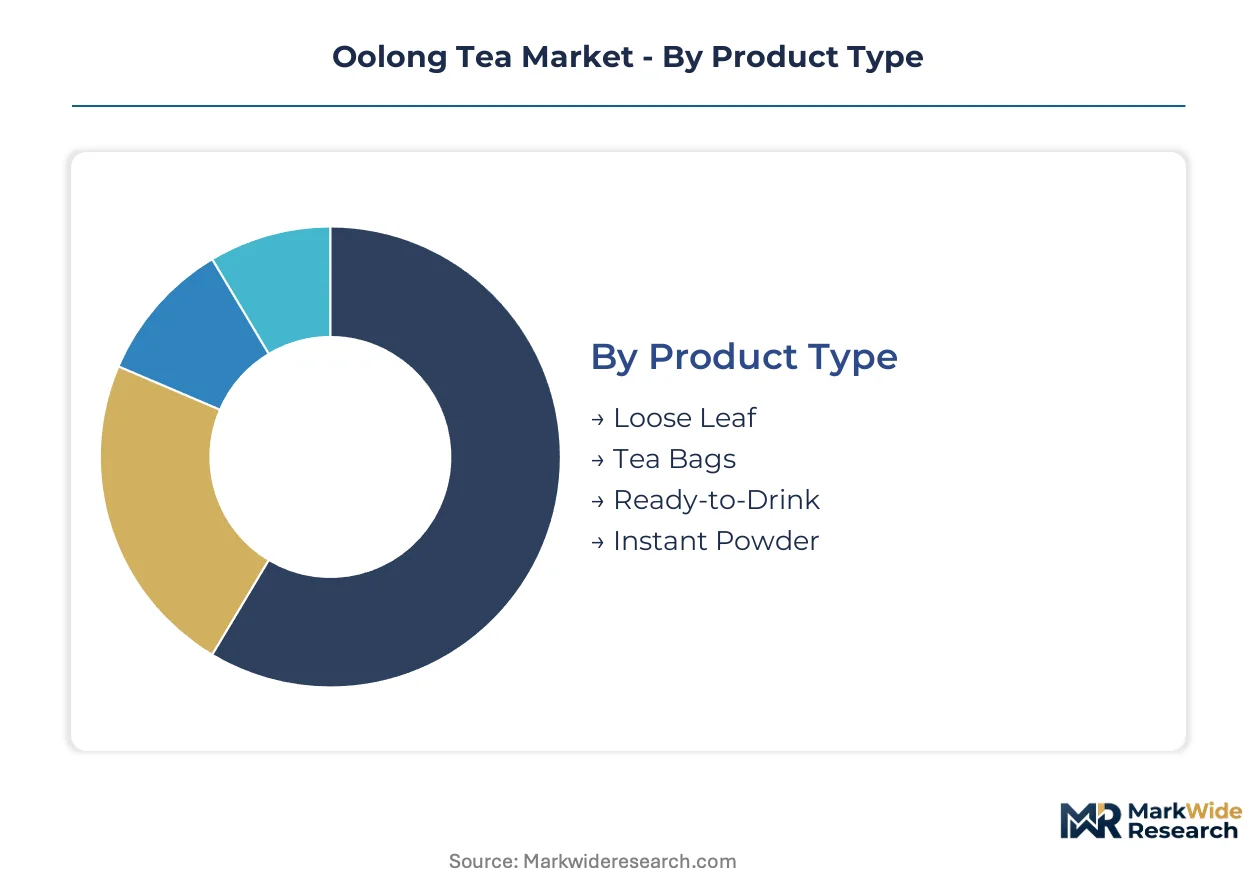
Oolong tea's diverse processing methods and consumption occasions create distinct commercial strata. Segmentation reveals how oxidation levels, packaging formats, and channel strategies align with margin profiles and customer acquisition costs across specialty and mass-market tiers.
Product Type:
Integration depth varies sharply: loose leaf commands standalone premium positioning while ready-to-drink embeds into convenience retail systems.
- Loose Leaf:Whole-leaf material with oxidation levels between 15% and 85% permits multiple steeping cycles and cultivar-specific brewing protocols. Specialty cafés in the United States and Japan concentrate procurement here, driven by tea-tourism storytelling and single-origin traceability requirements under China's SAMR GB/T standards.
- Ready-to-Drink:Pre-brewed formulations in stabilized packaging capture commute and workplace consumption. Japanese convenience chains and North American specialty beverage retailers anchor volume expansion, constrained by refrigerated distribution infrastructure and shorter shelf-life economics.
- Tea Bags:Standardized portioning in filter paper or silk pyramid formats serves hotel and office channels. Cost compression from automated filling equipment dominates procurement decisions.
- Instant Powder:Spray-dried or freeze-dried extracts dissolve in cold or hot water. Foodservice and nutraceutical blending applications in Taiwanese processing facilities drive niche offtake.
Loose leaf leads volumes today; ready-to-drink is gaining share fastest.
Form:
Cost tier stratification separates artisan processing premiums from scaled production efficiency.
- Semi-Fermented:Oxidation arrested at 20% to 70% yields the characteristic floral and creamy notes bridging green and black tea. Fujian's Tieguanyin and Taiwan's Alishan clusters concentrate output here, with China's dual carbon goals subsidizing energy-efficient oxidation facility upgrades.
- Fermented:Extended oxidation approaching black tea thresholds produces darker liquor and malted profiles. Guangdong's Phoenix Mountain dancong cultivars and aged storage programs in Hong Kong anchor demand.
- Floral:Jasmine, osmanthus, or rose infusion during final roasting targets younger demographics in online retail channels. Scenting labor costs and flower sourcing seasonality constrain margin stability.
- Fruity:Peach, lychee, or passionfruit flavoring via natural extraction or aroma coating. Ready-to-drink formulations and iced tea applications in Australian and United States markets concentrate offtake.
Semi-fermented dominates revenue contribution; floral variants are climbing the fastest.
Packaging Type:
Application context dictates material selection: gift and premium channels favor protective presentation while daily consumption prioritizes portability.
- Glass:Inert material preserves aromatic volatiles in premium loose leaf and ready-to-drink formats. Weight and fragility restrict e-commerce viability.
- Plastic:PET and multilayer barrier films enable lightweight ready-to-drink distribution. Japan's positive list system for food-contact materials constrains supplier flexibility.
- Carton:Paperboard with aluminum or plastic liners serves tea bag multipacks and gift assortments. EU Green Deal packaging waste directives are accelerating fiber-based innovation.
- Pouch:Flexible films with zip closures and degassing valves dominate loose leaf specialty retail. Stand-up formats reduce shelf space requirements in constrained urban stores.
Pouch formats lead specialty channel adoption; glass maintains premium positioning despite volume constraints.
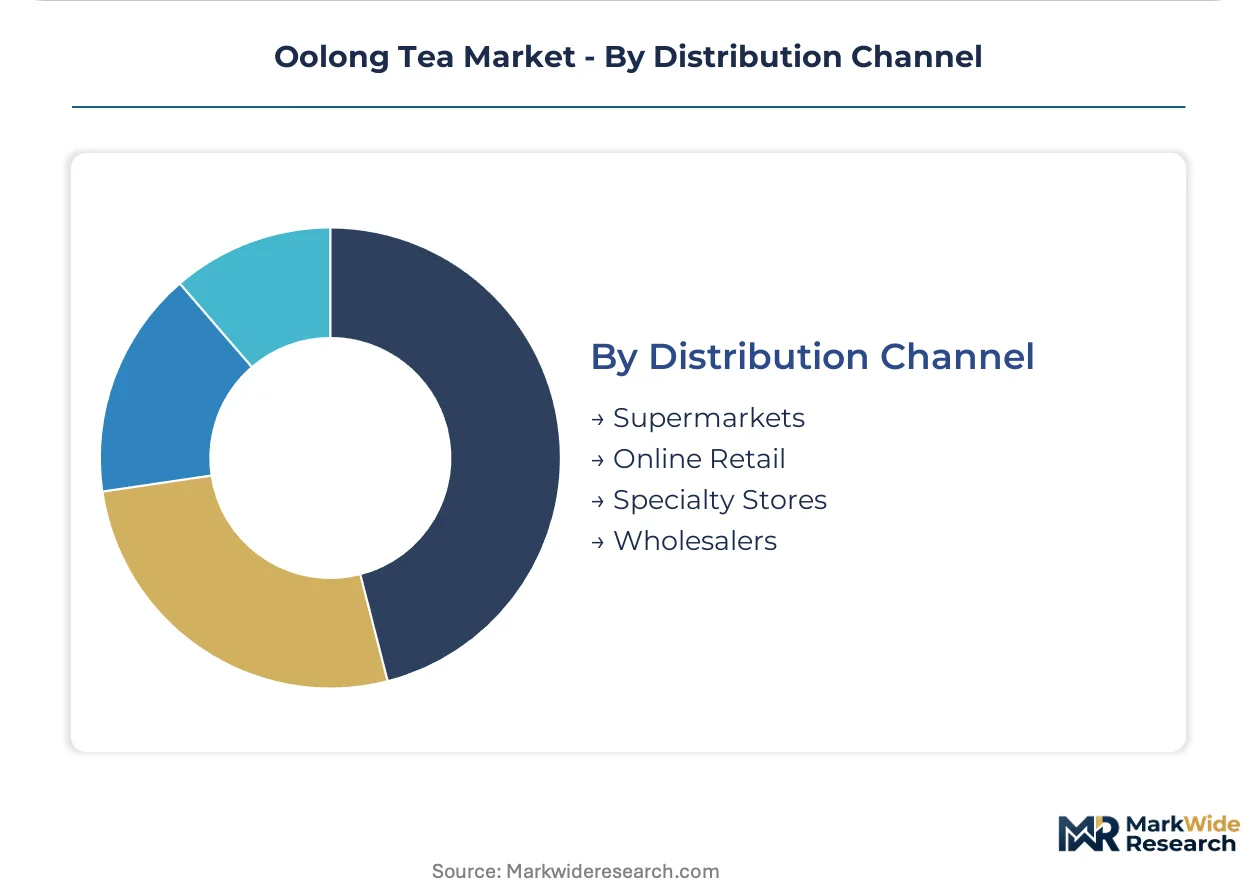
Distribution Channel:
Customer type and purchase frequency separate planned replenishment from impulse and experiential acquisition.
- Specialty Stores:Curated selection with staff-guided tasting and brewing education. Direct farm partnerships bypass import-distributor markups in United States and Australian urban markets.
- Online Retail:Subscription models and limited-release drops capture younger demographics. Blockchain origin verification mandated by China's SAMR enables premium positioning.
- Supermarkets:Mass-market tea bags and ready-to-drink placements compete on shelf velocity and promotional funding. Retailer private label programs compress branded margin.
- Wholesalers:Foodservice, hospitality, and private label manufacturing offtake in volume tiers. Contract roasting and blending services add value beyond commodity trading.
Specialty stores anchor premium revenue; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fujian province's Tieguanyin and Da Hong Pao production clusters anchor global oolong supply, with processing expertise concentrated in Anxi and Wuyi Mountain terroirs. Quality thresholds tighten across export destinations as regulators impose stricter residue limits and origin documentation requirements. Premium positioning depends on verified geographic indication compliance and sustainable cultivation certification.
China
Specialty beverage chains in Shanghai and Beijing drive domestic premium consumption, with single-origin Tieguanyin commanding retail premiums. SAMR enforces GB standards for pesticide residues and blockchain-based origin documentation that filter export eligibility for Fujian and Guangdong producers. Anxi county's hand-rolling workshops face succession pressures as younger workers migrate to urban manufacturing.
Japan
Convenience retail chains in Tokyo and Osaka expand ready-to-drink oolong placements, capturing commuter consumption occasions. METI and the Ministry of Agriculture, Forestry and Fisheries maintain positive list systems for agricultural chemicals that constrain Taiwanese and Chinese supplier flexibility. Shizuoka-based blenders source high-oxidation cultivars from Taiwanese processing facilities for polyphenol extraction applications.
United States
Specialty cafés in New York, Los Angeles, and Seattle unbundle traditional wholesale relationships for direct farm partnerships with named-origin storytelling. FDA import alerts and FSMA preventive controls govern market access, filtering non-compliant suppliers from Fujian export batches. Pacific Northwest roasting operations specify cultivar, harvest date, and processing method in procurement contracts.
Taiwan
Alishan and Nantou high-mountain terroirs supply floral-forward cultivars to Japanese and North American premium channels. Precision-controlled oxidation chambers with real-time monitoring achieve batch consistency previously requiring decades of artisan expertise. Taichung-area processing facilities scale energy-efficient upgrades aligned with regional carbon reduction targets.
Germany
EU Green Deal-aligned farm-level auditing opens premium positioning in Berlin and Hamburg retail environments for carbon-neutral certified lots. ECHA REACH compliance and packaging waste directives accelerate fiber-based innovation in tea bag and gift assortment formats. Hamburg wholesalers contract directly with Wuyi Mountain producers for limited-edition releases targeting specialty channels.
Oolong Tea Market Vendor Landscape
Direct farm partnerships dominate the current landscape as specialty channels bypass conventional import-distributor markups. The vendor base concentrates around vertically integrated garden-to-retail operators, curated direct-sourcing specialists, and certified organic supply relationship managers. Three archetypes define positioning: terroir-specific origin storytellers, convenience-ready formulation scale players, and sustainability-certified niche cultivators. Geographic expansion and carbon-neutral certification represent the dominant competitive moves for premium tier access.
Among garden-to-retail integrated operators, ITO EN Ltd. exemplifies captive supply chain control from Taiwanese cultivation through Japanese retail shelf placement. Within the direct-sourcing specialist tier, Harney and Sons Fine Teas occupies a position anchored on Wuyi Mountain cultivar relationships, while Rishi Tea and Botanicals represents the certified organic and Fair Trade supply archetype. These three players illustrate how origin verification depth and sustainability credentialing separate premium positioning from commodity competition.
| Leading Market Players |
|---|
| ITO EN Ltd. |
| East West Tea Company LLC |
| Harney and Sons Fine Teas |
| COFCO International |
| Adagio Teas |
| The Republic of Tea Inc. |
| Dilmah Ceylon Tea Co. Plc |
| Harada Tea Processing Co Ltd. |
| Rishi Tea and Botanicals |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between organic-certified Tieguanyin and conventional bulk oolong manifests in pricing spreads exceeding threefold, with supply chain configurations tracking this bifurcation through dedicated processing lines and segregated cold storage infrastructure. Premium tiers command origin-verified premiums under China's SAMR blockchain documentation mandates, while commodity lots face margin compression from wage inflation in Fujian's hand-rolling workshops.
Pricing Analysis
Input-cost pass-through from Fujian's labor-intensive hand-rolling and multiple charcoal roasting cycles concentrates pricing pressure in mid-tier Tieguanyin production. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-documented single-origin lots from blended regional grades and commodity auction material. Cost compression intensifies in standard tiers as wage inflation outpaces mechanization adoption. Economy buyers in foodservice and private label manufacturing exhibit highest price sensitivity, while specialty café procurement prioritizes cultivar specificity over per-kilogram rates.
Supply Chain Analysis
Hand-rolling labor supply rests on aging practitioner pools in Anxi and Phoenix Mountain, constraining quality replication as younger workers migrate to urban manufacturing. Geographic concentration centers on Fujian province's Tieguanyin belt, Taiwan's Alishan high-mountain terroirs, and Guangdong's Phoenix Mountain dancong clusters. Dependencies include seasonal jasmine and osmanthus for floral scenting, charcoal and electric roasting fuel sources, and blockchain compliance infrastructure for export certification. Single-source vulnerability to climate irregularity in Wuyi Mountain creates supply disruption risk. Distribution runs through specialty import channels in United States and Japanese convenience retail chains, with direct-to-consumer subscription platforms gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oolong tea market functions as a stable compounder, with functional beverage expansion and traceability-premium capture driving steady value growth across the projection horizon.
For Market Incumbents: Anchor defensive positioning through backward integration into certified organic cultivation in Fujian and Taiwan, securing three-year soil remediation timelines ahead of contract fulfillment demands. Deepen channel control via proprietary e-commerce subscription platforms that bypass wholesale margin compression. Counter emerging direct-sourcing specialists by investing in master roaster apprenticeship programs that preserve charcoal roasting expertise concentration. For New Entrants and Emerging Players: The mid-tier price-point gap between premium single-origin and economy blended oolong offers white-space entry for traceable regional grades with abbreviated origin stories. Target ready-to-drink formulations in North American convenience channels, where refrigerated distribution infrastructure remains underdeveloped relative to demand growth. Pursue carbon-neutral certification as the primary go-to-market angle for German and Dutch retail penetration under EU Green Deal alignment. For Investors and Strategic Acquirers: Consolidation pressure builds where organic conversion timelines outpace export contract fulfillment capacity, creating acquisition opportunities for certified garden-to-retail operators with compliant volume. Long-term viability favors vertically integrated specialists with captive Taiwanese or Fujian cultivation and Japanese or North American retail shelf placement. Watch for inflection where Japan's positive list system expands agricultural chemical restrictions, disqualifying conventional cultivation batches and reshaping supplier competitive sets.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Neutral Certification Program | EU Green Deal alignment opens premium positioning in German and Dutch retail environments. |
| Direct-to-Consumer Subscription Launch | Proprietary e-commerce platforms bypass wholesale margin compression in North American specialty channels. |
| Master Roaster Apprenticeship Investment | Charcoal roasting expertise preservation counters succession risk in Anxi and Phoenix Mountain processing clusters. |
| Blockchain Origin Verification Integration | SAMR-mandated harvest-to-package tracking preserves export eligibility for Tieguanyin and Da Hong Pao producers. |
| Ready-to-Drink Formulation Expansion | Convenience retail penetration in Japanese and North American markets captures commute consumption occasions. |
Methodological Framework
Coverage spans Fujian and Guangdong provinces in China, Taiwan's Alishan and Nantou regions, Japan's Shizuoka processing corridor, and North American specialty retail hubs, with primary inputs from each. The analysis combines structured interviews with tea estate managers, specialty café procurement directors, Japanese convenience chain buyers, and organic certification auditors with secondary validation from China customs records, Japanese Ministry of Agriculture trade statistics, and FDA import alert databases. Bottom-up volume modeling and top-down value triangulation cross-validate segment outputs.
Granularity-level modeling disaggregates oxidation tiers, packaging formats, and distribution channels across the projection horizon, with separate treatment of loose leaf, ready-to-drink, and nutraceutical ingredient applications. Segmentation dimensions include product type, form, packaging material, and channel strategy, with regional regulatory clusters layered as an overlay. CAGRs derive from trend extrapolation of functional beverage penetration rates, organic certification adoption curves, and direct-to-consumer channel share shifts. Forecast inputs incorporate China's dual carbon subsidy trajectories and Japan's positive list expansion schedules.
Caveats apply where climate irregularity in Wuyi Mountain, abrupt positive list revisions, or master roaster succession failures could materially shift the outlook. Forecasts reflect assumptions around organic conversion timeline adherence and blockchain infrastructure deployment pace. A small set of named triggers—drought severity in Fujian, Japanese agricultural chemical restriction expansion, and EU packaging waste directive enforcement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
US Ready to Drink Tea Market
Tea
South America Tea Market
Tea
Plant Based New Tea Drink Market
Tea
Tea Concentrate Market
Tea
Probiotic Tea Market
Tea
Pyramid Tea Bags Market
Tea
Mate Tea Market
Tea
APAC RTD Tea Market
Tea
High Protein Tea Market
Tea
Light-Fermented Tea Market
Tea
Tea Polyphenols Market
Tea
Green Tea Bag Market
Tea
US RTD Organic Tea Market
Tea
Middle East Ready to Drink Tea Market
Tea
Tea Pitchers Market
Tea
North America Ready-To-Drink Tea Market