
 Saudi Arabia Pharmaceutical Glass Packaging Market | 2026-2036
Saudi Arabia Pharmaceutical Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Pharmaceutical Glass Packaging Market Analytics
Preventive maintenance contracts for glass-forming equipment is recalibrating how packaging suppliers monetize relationships beyond unit sales. Gerresheimer AG leverages its technical service networks to lock in long-term pharmaceutical contracts. SGD Pharma S.A. anchors its regional position through specialized borosilicate vial production for temperature-sensitive formulations. Obeikan Glass Company competes on proximity, sustaining shorter lead times to domestic drug manufacturers.
Pharmaceutical glass packaging denotes container systems fabricated from borosilicate or soda-lime glass, engineered to meet hydrolytic resistance Class I or II standards and thermal shock thresholds exceeding 42°C for autoclave sterilization cycles. These containers protect drug stability from pH shift, oxygen ingress, and ultraviolet degradation across shelf lives spanning 24 to 60 months. Vials and sterile containers command the deepest margin pools, with demand for ready-to-use formats outpacing traditional bulk configurations. Ampoules face gradual displacement by prefillable syringes and blow-fill-seal alternatives, though break-seal ampoules retain niche demand for emergency injectables.
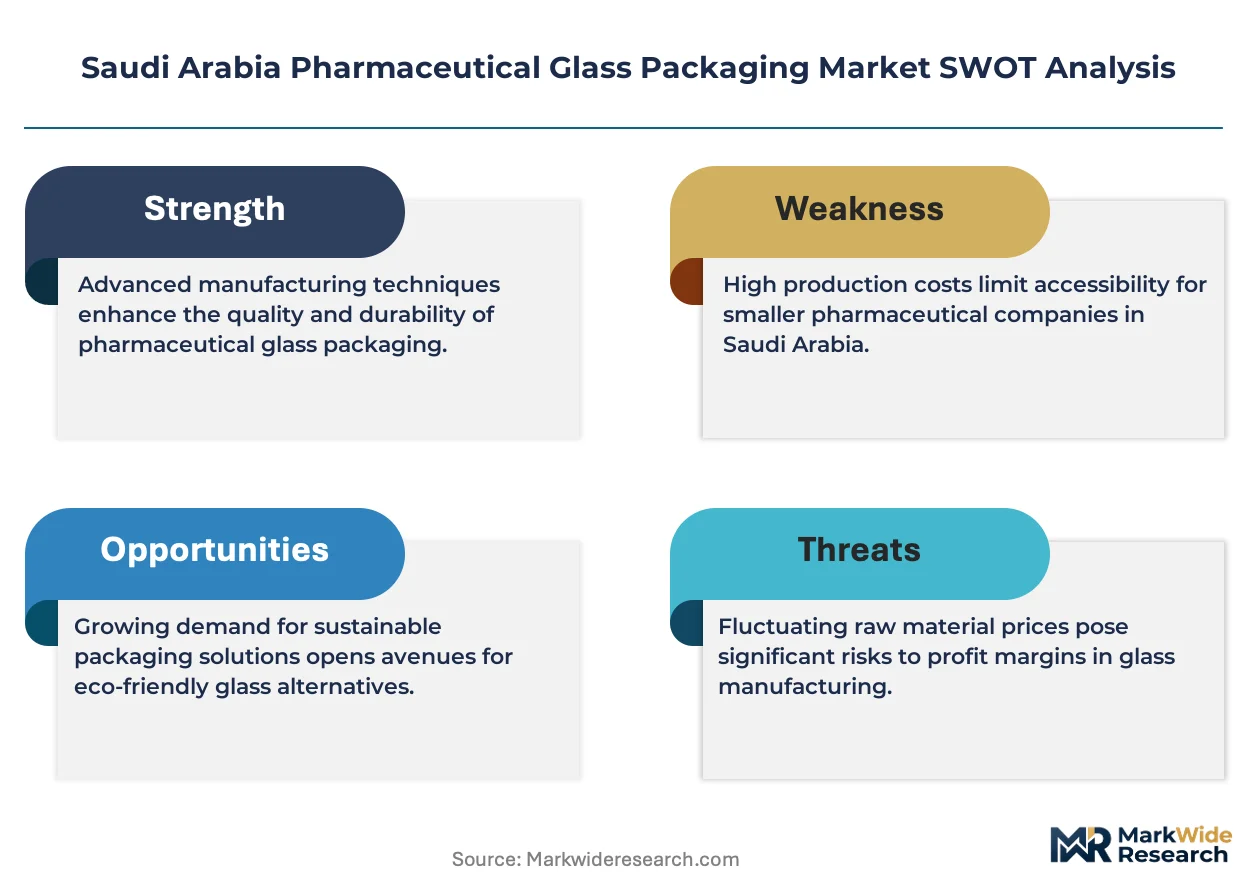
SFDA enforces Gulf Standardization Organization (GSO) conformity and traceability codes for all imported and locally produced pharmaceutical primary packaging. The Saudi Food and Drug Authority also mandates pharmacopeial compliance with USP <660> and EP 3.2.1 container glass testing protocols, effectively filtering out uncertified suppliers. Stakeholders must weigh backward integration into tubing conversion against reliance on European borosilicate feedstock as local mining and refining capacities for pharmaceutical-grade silica remain underdeveloped.
Market Dynamics
SFDA's serialization mandates are compressing supplier qualification timelines while simultaneously elevating technical compliance costs, forcing domestic pharmaceutical manufacturers to consolidate procurement relationships around vertically capable packaging partners.
Growth Catalysts
- Injectable Biologics Expansion:Temperature-sensitive monoclonal antibody formulations require borosilicate vials with hydrolytic resistance Class I certification, pulling specialized glass capacity into the Kingdom.
- SFDA Serialization Mandates:Traceability code requirements for all primary packaging are filtering out uncertified importers and accelerating contract migrations to GSO-conformant domestic suppliers.
- Riyadh Manufacturing Corridor Concentration:Clustering of pharmaceutical production around the capital creates density economies for just-in-time glass container delivery.
Market Restraints
- European Borosilicate Feedstock Dependency:Local mining and refining capacities for pharmaceutical-grade silica remain underdeveloped, exposing converters to euro-denominated input volatility and shipping disruptions.
- Autoclave Sterilization Throughput Bottlenecks:Thermal shock thresholds exceeding 42°C require specialized annealing equipment that few regional fabricators possess.
- Prefillable Syringe Substitution:Blow-fill-seal alternatives and ready-to-use syringe formats are eroding ampoule demand in chronic disease therapeutic categories.
Strategic Opportunities
- Jeddah Logistics Hub Expansion:Red Sea port infrastructure investments enable re-export positioning toward East African and Levantine pharmaceutical markets.
- Ready-to-Use Vial Formats:Pre-sterilized, pre-filled container systems command margin premiums and reduce fill-finish line contamination risk for biologics manufacturers.
- SFDA Local Content Incentives:Procurement preferences for Saudi-manufactured primary packaging create protected demand pools for domestic glass conversion investments.
Industry Challenges
- Pharmacopeial Certification Timelines:USP <660> and EP 3.2.1 container glass testing protocols require 18-24 month validation cycles that delay new supplier market entry.
- Glass-Forming Equipment Maintenance Skill Gaps:Specialized technicians for IS machine calibration and defect detection remain concentrated in European technical service networks.
- Backward Integration Capital Intensity:Tubing conversion capabilities require furnace investments that strain mid-scale packaging converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Pharmaceutical Glass Packaging Market |
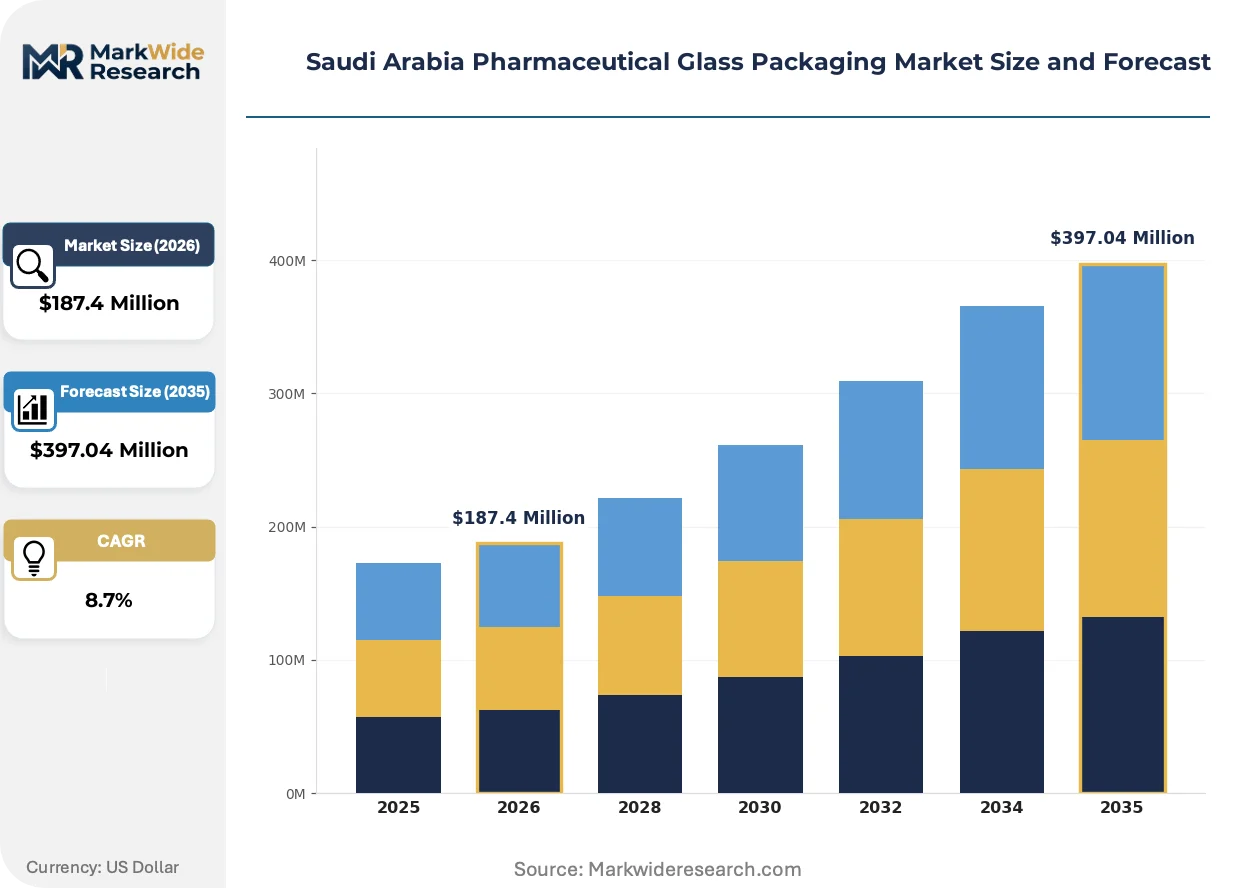
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Ampoules, Bottles, Sterile Containers End User: Pharmaceutical Companies, Contract Manufacturers, Hospitals, Laboratories Application: Injectables, Oral Medications, Diagnostics, Research Packaging Type: Single-use, Multi-use, Bulk Packaging, Custom Packaging |
| Companies Covered | Saudi Arabian Glass Company Ltd., Obeikan Glass Company, Zoujaj Glass, Schott AG, Gerresheimer AG, Ardagh Group S.A., SGD Pharma S.A., Corning Incorporated, Middle East Glass, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Pharmaceutical Glass Packaging Market Evolving Landscape
Pharmaceutical glass packaging in Saudi Arabia is undergoing functional transformation driven by biologics containment requirements, regulatory traceability mandates, and procurement consolidation around full-service technical partners.
Ready-to-use vial systems are integrating silicone coating technologies and pre-sterilized closure components to eliminate depyrogenation steps at fill-finish sites. Biologics manufacturers in Riyadh's manufacturing corridor are adopting these formats at accelerating rates to reduce contamination risk during aseptic processing. This integration is compressing demand for traditional bulk vial configurations and elevating technical service expectations toward container closure integrity guarantees.
SFDA enforcement of Gulf Standardization Organization conformity marks is tightening import documentation requirements for all pharmaceutical primary packaging entering the Kingdom. The regulation is redirecting procurement flows toward Saudi-based converters capable of real-time traceability code generation. Sterile vial and container segments face the steepest compliance ramps as serialization deadlines approach.
Maintenance contracts for glass-forming equipment are displacing transactional spare parts purchasing as the dominant commercial model. Pharmaceutical manufacturers in the Eastern Province are locking multi-year technical service agreements to secure uptime guarantees on high-speed filling lines. This behavioral shift is most visible among injectables producers running 24-hour autoclave sterilization cycles where unplanned downtime carries batch loss penalties.
Saudi Arabia Pharmaceutical Glass Packaging Market Segmentation
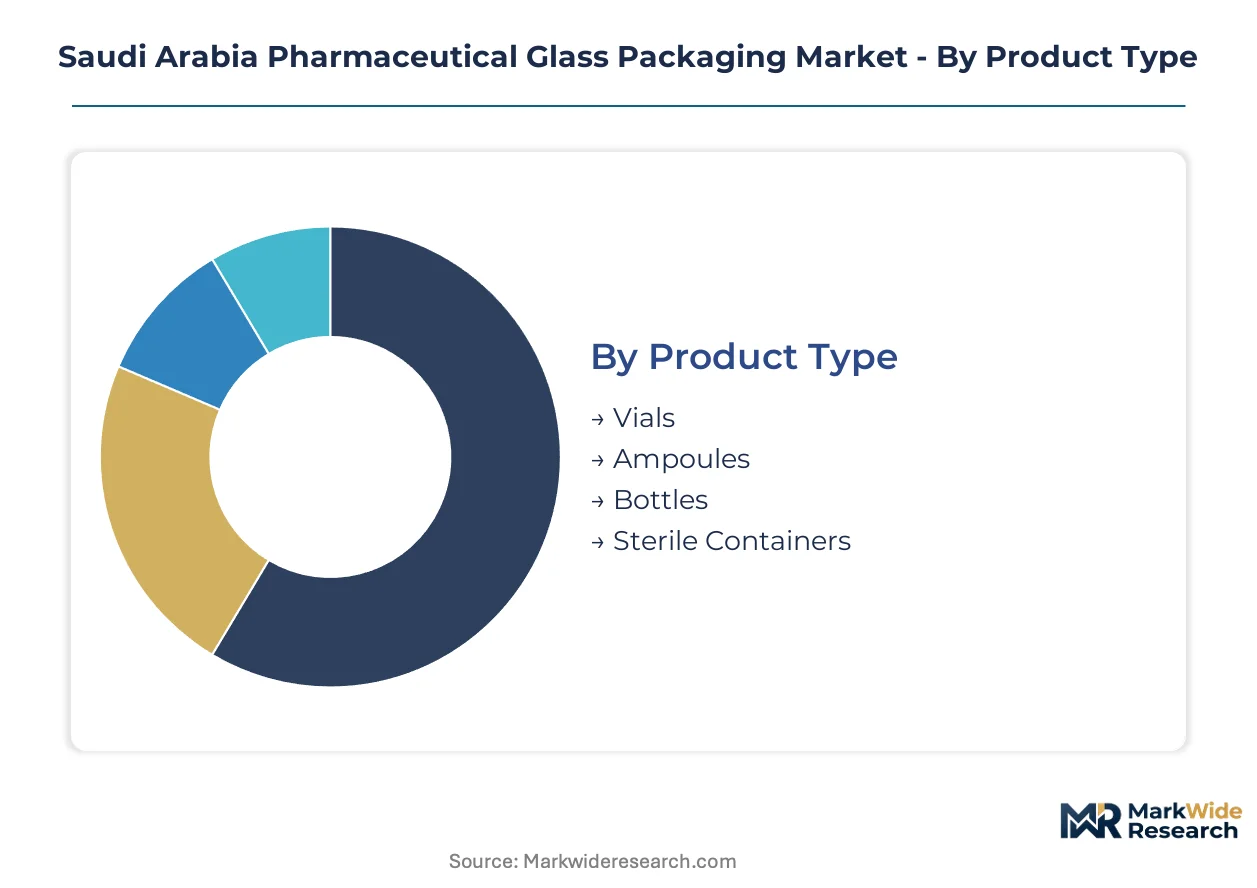
Glass packaging specifications diverge sharply across pharmaceutical applications in Saudi Arabia. SFDA's pharmacopeial mandates and biologics containment requirements create tiered compliance burdens that reshape procurement priorities by product format and end-use.
Product Type:
Borosilicate hydrolytic resistance and thermal shock tolerance separate premium pharmaceutical glass from commodity alternatives.
- Vials:Type I borosilicate construction with hydrolytic resistance Class I certification protects pH-sensitive biologics across 24-60 month shelf lives. Riyadh's manufacturing corridor concentrates demand for ready-to-use silicone-coated formats that eliminate depyrogenation steps.
- Sterile Containers:Pre-sterilized closure-integrated systems command margin premiums by reducing fill-finish contamination risk. Temperature-sensitive monoclonal antibody formulations in Jeddah's logistics hub drive adoption of these integrated formats.
- Ampoules:Break-seal glass retains niche demand for emergency injectables despite prefillable syringe displacement in chronic therapeutics.
- Bottles:Soda-lime and treated borosilicate configurations serve oral solid and liquid dosage forms with lower thermal shock requirements.
Vials lead on scale; sterile containers lead on momentum.
End User:
Procurement sophistication varies by manufacturing scale and regulatory exposure.
- Pharmaceutical Companies:Domestic drug manufacturers in Riyadh and the Eastern Province consolidate procurement around vertically capable packaging partners capable of real-time traceability code generation under SFDA mandates.
- Contract Manufacturers:Fill-finish service providers demand just-in-time delivery and container closure integrity guarantees to maintain 24-hour autoclave sterilization cycle uptime.
- Hospitals:Institutional buyers prioritize break-seal ampoules and single-use vials for emergency and surgical applications.
- Laboratories:Research and diagnostic facilities source smaller lot sizes with flexible specification tolerances.
Pharmaceutical companies anchor volume; contract manufacturers expand most quickly.
Application:
Drug stability requirements dictate glass specification intensity across therapeutic categories.
- Injectables:Parenteral formulations require Type I borosilicate with thermal shock thresholds exceeding 42°C for autoclave sterilization cycles. Biologics manufacturers in Saudi Arabia pull specialized capacity into the Kingdom.
- Oral Medications:Lower hydrolytic resistance requirements permit soda-lime glass for tablets, capsules, and liquid syrups.
- Diagnostics:Reagent containment demands ultraviolet degradation protection and precise dimensional tolerances for automated handling equipment.
- Research:Preclinical and clinical trial materials use flexible lot sizing with expedited qualification timelines.
Injectables dominate value capture; diagnostics climbs fastest.
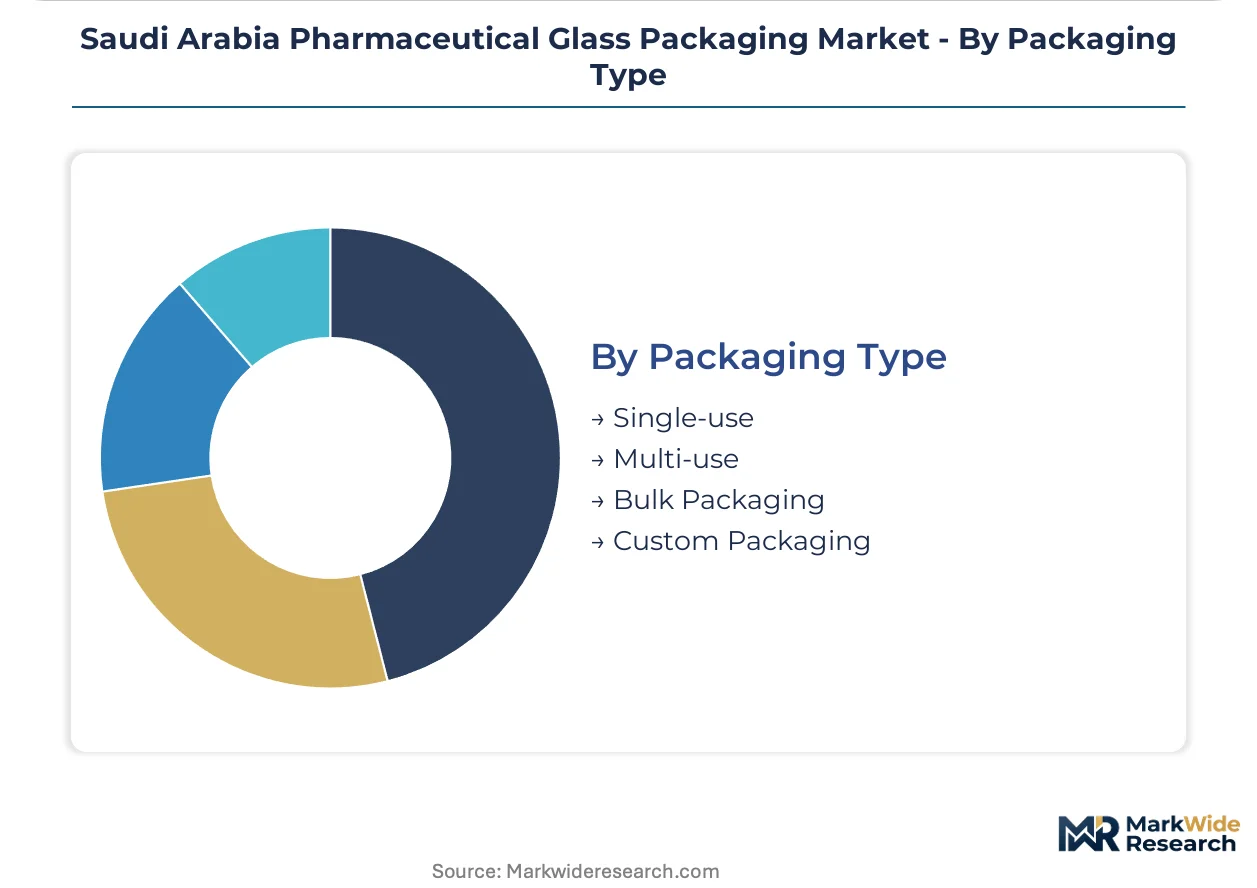
Packaging Type:
Usage model and contamination risk define procurement economics.
- Single-use:Pre-sterilized, pre-filled container systems eliminate aseptic processing steps. SFDA serialization mandates accelerate migration toward traceable unit-dose formats.
- Custom Packaging:Specialized dimensional and coating specifications serve proprietary drug-device combination products.
- Bulk Packaging:Traditional multi-dose configurations face compression as ready-to-use formats gain share in injectables.
- Multi-use:Reusable glass systems retain limited demand for compounding pharmacy and research applications.
Single-use commands premium positioning; custom packaging shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical glass packaging production migrates toward jurisdictions where SFDA-equivalent compliance costs remain lower than European benchmarks, creating arbitrage opportunities for converters operating under Gulf Standardization Organization alignment. Saudi Arabia captures inbound investment as regional drug manufacturers seek shorter qualification timelines and reduced euro-denominated feedstock exposure.
Riyadh
Domestic pharmaceutical manufacturing concentrates in the capital corridor, with SFDA's serialization mandates pulling traceable container demand toward locally qualified suppliers. The city's dense cluster of fill-finish operations generates just-in-time delivery requirements that favor proximity-based glass converters. Riyadh's pharmaceutical manufacturing corridor anchors the Kingdom's borosilicate vial consumption.
Eastern Province
Industrial-scale injectables producers operate 24-hour autoclave sterilization cycles that demand specialized annealing equipment uptime guarantees. Maintenance contracts for glass-forming equipment displace transactional purchasing as the dominant commercial model among Dammam-based manufacturers. The region's contract manufacturing expansion elevates technical service expectations toward container closure integrity guarantees.
Jeddah
Red Sea port infrastructure investments position the logistics hub for re-export toward East African and Levantine pharmaceutical markets. Temperature-sensitive monoclonal antibody formulations transit through Jeddah's cold chain facilities, pulling specialized borosilicate capacity into western Saudi Arabia. The city's customs modernization aligns with SFDA import documentation requirements for GSO-conformant primary packaging.
Western Region
Makkah and Madinah institutional buyers prioritize break-seal ampoules for emergency and surgical applications in hospital networks serving pilgrimage healthcare demand. Local procurement patterns favor single-use formats that reduce aseptic processing complexity in high-throughput medical settings. The region's seasonal demand spikes stress-test regional glass container inventory management systems.
Saudi Arabia Pharmaceutical Glass Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium borosilicate vial supply consolidating around European-origin multinationals while domestic converters capture commoditized soda-lime formats. The vendor base stratifies into three tiers: integrated tubing converters with captive furnace operations, toll processors dependent on imported feedstock, and regional distributors without fabrication capabilities. Two strategic archetypes dominate competitive positioning—technical service bundlers monetizing long-term maintenance relationships, and proximity specialists competing on lead time compression to domestic drug manufacturers. Capacity expansion and backward integration into tubing conversion represent the dominant competitive moves as converters seek insulation from euro-denominated input volatility.
Within the European-origin tier, Gerresheimer AG and SGD Pharma S.A. exemplify technical service bundlers leveraging specialized borosilicate production networks to anchor regional pharmaceutical contracts. Obeikan Glass Company occupies a position among proximity-based domestic fabricators competing on shorter lead times to Riyadh's manufacturing corridor. These three entities represent the strategic poles around which procurement consolidation is concentrating under SFDA's tightening qualification timelines.
| Leading Market Players |
|---|
| Saudi Arabian Glass Company Ltd. |
| Obeikan Glass Company |
| Zoujaj Glass |
| Schott AG |
| Gerresheimer AG |
| Ardagh Group S.A. |
| SGD Pharma S.A. |
| Corning Incorporated |
| Middle East Glass |
| Others |
Value Network & Pricing Analysis
European borosilicate tubing price indices cascade through Saudi pharmaceutical glass packaging tiers, compressing margins on commodity soda-lime formats while insulating premium Type I borosilicate vials from euro-denominated volatility through long-term offtake contracts. SFDA's GSO-conformant certification requirements stratify procurement budgets across hydrolytic resistance grades, with Riyadh-based drug manufacturers absorbing higher unit costs for traceable ready-to-use systems.
Pricing Analysis
Distributor markups on imported borosilicate feedstock widen spreads between European-origin premium vials and domestic toll-processed alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects hydrolytic resistance certification and thermal shock performance tiers. Cost compression in standard-grade vials is intensifying because contract manufacturers consolidate volumes around vertically capable partners. Generic drug producers in the Eastern Province exhibit highest price sensitivity; biologics specialists in Riyadh's manufacturing corridor accept premium positioning for container closure integrity guarantees.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale pharmaceutical demand in Riyadh's manufacturing corridor, while distributor networks serve smaller Eastern Province contract manufacturers. Supply concentrates in Germany, France, and India for pharmaceutical-grade borosilicate tubing; domestic Saudi converters draw from these sources for furnace feedstock. The supply chain rests on specialized annealing equipment, silicone coating chemistries, and pre-sterilized closure components. Single-source vulnerability in European borosilicate feedstock exposes converters to shipping disruptions and currency fluctuations. Distribution runs through Jeddah's Red Sea port infrastructure toward East African re-export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through backward integration into tubing conversion, capturing value currently flowing to European suppliers while SFDA local content incentives protect domestic production premiums.
For Market Incumbents: Anticipate prefillable syringe substitution pressure in ampoule segments by accelerating ready-to-use vial format investments and locking multi-year technical service contracts with Eastern Province injectables producers. Backward integration into captive borosilicate furnace operations insulates margin pools from euro-denominated feedstock volatility and secures qualification priority under SFDA's tightening serialization timelines. For New Entrants and Emerging Players: Mid-scale contract manufacturers in Dammam represent an underserved buyer archetype seeking just-in-time delivery with flexible lot sizing. White-space targets include specialized borosilicate production for temperature-sensitive monoclonal antibodies and maintenance-contract bundling for glass-forming equipment uptime guarantees. A go-to-market angle emphasizing proximity-based lead time compression against European-origin competitors unlocks initial procurement trials. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic converters possessing GSO-conformant certification and established SFDA qualification records. Long-term viability over a multi-year horizon favors acquisition targets with technical service networks and backward integration pathways into tubing conversion. The signal to watch is SFDA enforcement intensity on traceability code generation capabilities as a barrier to uncertified importers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tubing Conversion | Captive borosilicate furnace operations insulate converters from European feedstock price volatility and currency risk. |
| Ready-to-Use Vial Format Expansion | Pre-sterilized silicone-coated systems command margin premiums from Riyadh biologics manufacturers reducing contamination risk. |
| Technical Service Contract Bundling | Multi-year maintenance agreements lock in pharmaceutical relationships beyond transactional unit sales. |
| SFDA Certification Investment | GSO-conformant qualification creates protected demand pools under local content procurement preferences. |
| Jeddah Logistics Hub Positioning | Red Sea port infrastructure enables re-export arbitrage toward East African and Levantine pharmaceutical markets. |
Research Methodology
Direct dialogue with pharmaceutical manufacturing executives, SFDA regulatory affairs specialists, glass-forming equipment technical service directors, and procurement leads at Riyadh-based drug manufacturers grounded qualitative findings. Secondary validation drew from SFDA serialization mandate documentation, Gulf Standardization Organization conformity protocols, USP and EP pharmacopeial standards, and European borosilicate supplier trade disclosures. Bottom-up demand modeling across vial, ampoule, and sterile container formats triangulated against top-down pharmaceutical production capacity estimates.
Segment-level value outputs reflect discrete modeling across product type, end user sophistication tier, therapeutic application, and packaging usage format throughout the forecast period. CAGRs were derived from elasticity-adjusted demand projections incorporating biologics pipeline expansion rates and SFDA compliance timeline enforcement intensity. Industry-specific forecast inputs included monoclonal antibody formulation growth in Riyadh's manufacturing corridor and autoclave sterilization capacity expansion in the Eastern Province.
Inputs from primary stakeholder interviews and published regulatory guidance were available through the study window; gaps in real-time pharmaceutical production data introduce uncertainty bands around near-term volume estimates. Forecasts reflect assumptions regarding SFDA serialization enforcement consistency and European borosilicate supply continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Dosing Bottles Market
Glass Packaging
UAE Container Glass Market
Glass Packaging
Glass Bottles Market
Glass Packaging
Amber Glass Packaging Market
Glass Packaging
Europe Glass Bottles and Containers Market
Glass Packaging
Thailand Container Glass Market
Glass Packaging
Italy Container Glass Market
Glass Packaging
China Glass Container Packaging Market
Glass Packaging
Egypt Glass Packaging Market
Glass Packaging
Sweden Container Glass Market
Glass Packaging
Ethiopia Container Glass Market
Glass Packaging
Netherlands Container Glass Market
Glass Packaging
Europe Glass Packaging Market
Glass Packaging
Packaging Jars Market
Glass Packaging
Chile Container Glass Market
Glass Packaging
Retail Glass Packaging Market