
 Functional Food Ingredients Market | 2026-2036
Functional Food Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Food Ingredients Market Analysis
China's expanded fermentation capacity is reshaping global supply dynamics for probiotic strains and specialty proteins. Cargill, Incorporated leverages its integrated agricultural supply chain to secure raw material cost advantages across prebiotic fiber production. BASF SE anchors its position through advanced omega-3 fatty acid concentration technologies derived from algal sources. Kerry Group plc differentiates via customized ingredient systems that blend multiple functional actives for dairy and beverage applications.
Functional food ingredients comprise bioactive compounds, live microorganisms, and physiologically beneficial substances formulated into conventional foods to deliver targeted health effects beyond basic nutrition; these ingredients typically require minimum effective doses measured in colony-forming units for probiotics or grams per serving for prebiotic fibers, and they undergo stabilization processes including microencapsulation to preserve viability through manufacturing and shelf life. Probiotics command the largest revenue share due to entrenched consumer recognition and established clinical validation for digestive health claims, while microbial fermentation sources represent the fastest-expanding ingredient origin as precision biotechnology enables scalable production of compounds previously limited to extraction from fish or plants. Powder formulations dominate industrial procurement because of extended stability, easier dosing accuracy, and lower transportation costs compared to liquid alternatives.
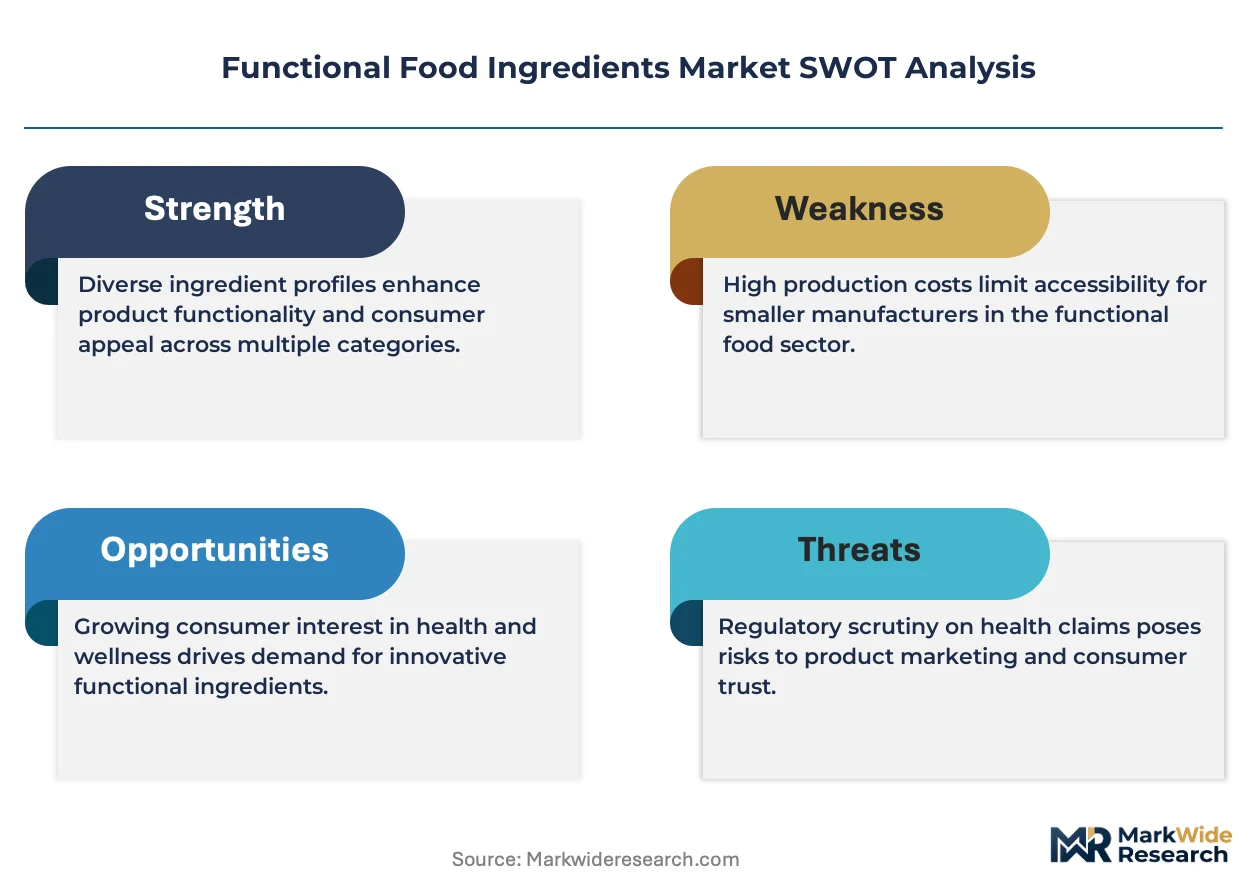
EFSA novel food assessments and EMA health claim evaluations determine which functional ingredients gain European market access, creating compliance bottlenecks that favor well-capitalized suppliers with dedicated regulatory affairs teams. The FDA GRAS self-affirmation pathway and FSMA preventive controls impose parallel requirements in the United States, where substantiation dossiers for structure-function claims demand rigorous scientific evidence. ISO 22000 and FSSC 22000 certifications increasingly function as baseline qualifiers for supplier qualification by multinational food manufacturers. Stakeholders must track evolving definitions of what constitutes a food versus a supplement across jurisdictions, as reclassification would trigger entirely different approval burdens and channel restrictions.
Market Dynamics
Precision fermentation platforms are compressing production timelines for omega-3 alternatives and specialty proteins, while EFSA novel food authorizations and FDA GRAS pathways create divergent compliance burdens that reshape supplier competitive positions across Atlantic markets.
Growth Catalysts
- EFSA Novel Food Pathway:Streamlined authorizations for prebiotic fibers in Germany accelerate product launches across dairy and beverage applications, reducing time-to-market for validated ingredients.
- Microbial Fermentation Scale-Up:Bioreactor optimization cuts strain cultivation cycles from weeks to days, enabling cost parity with fish-derived omega-3 sources and expanding addressable volume.
- ANVISA Functional Claim Registration:Brazil's simplified probiotic beverage approvals unlock South American demand clusters previously constrained by regulatory uncertainty.
Market Restraints
- Algal Oil Feedstock Volatility:Omega-3 concentration from algal sources faces yield inconsistency tied to photobioreactor climate control energy costs.
- Chinese Strain Supply Concentration:Probiotic culture banks in Shanghai and Tianjin control critical germplasm access, creating single-source vulnerability for European formulators.
- EMA Health Claim Substantiation:Clinical trial requirements for digestive health claims impose multi-year dossier development timelines that exclude mid-tier ingredient developers.
Strategic Opportunities
- Precision Fermentation Convergence:CRISPR-edited chassis strains combined with continuous bioprocessing enable de novo synthesis of bioactives previously limited to botanical extraction.
- Sports Nutrition White Space:Protein-fortified functional beverages in Mexico and Colombia remain underpenetrated relative to maturity in North American and Western European markets.
- Clean Label Channel Expansion:Direct-to-consumer ingredient kits bypass traditional foodservice distribution, capturing margin from home fermentation and DIY probiotic cultures.
Industry Challenges
- Microencapsulation Talent Scarcity:Formulation chemists with dual expertise in spray-drying optimization and strain viability preservation command premium compensation and limited availability.
- FSSC 22000 Certification Backlogs:Third-party audit capacity constraints delay supplier qualification timelines for multinational food manufacturers consolidating vendor bases.
- Legacy ERP Integration Friction:Batch record systems designed for commodity ingredients struggle to capture live-cell count traceability required for probiotic finished goods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Food Ingredients Market |
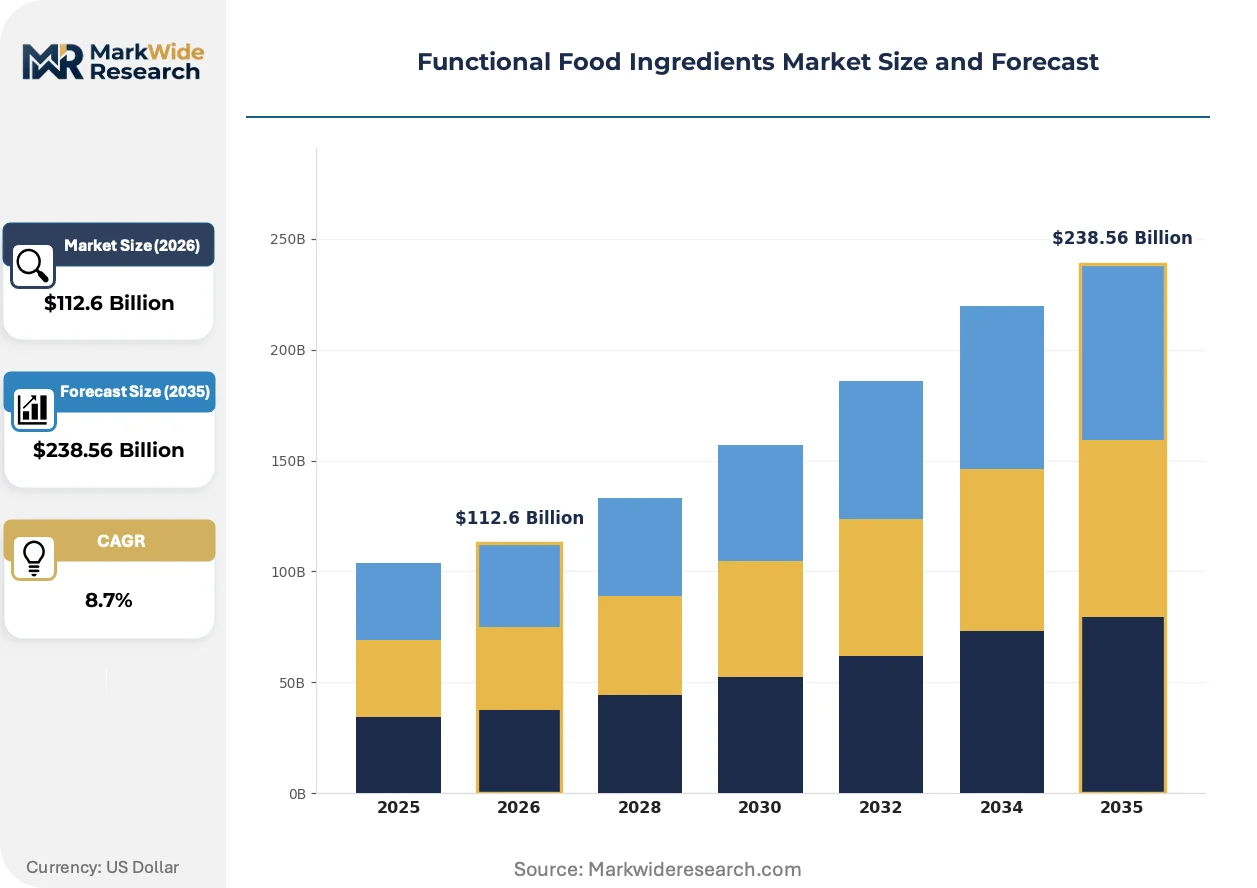
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $238.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prebiotics, Probiotics, Omega-3 Fatty Acids, Fiber Application: Dairy Products, Bakery, Beverages, Nutritional Supplements Ingredient Source: Plant-Based, Animal-Based, Microbial Fermentation, Synthetic Form: Powder, Liquid, Granulate, Capsules |
| Companies Covered | Cargill, Incorporated, BASF SE, Archer Daniels Midland Company, Kerry Group plc, Ingredion Incorporated, DSM-Firmenich AG, Arla Foods amba, Tate & Lyle PLC, Glanbia plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Food Ingredients Market Emerging Trajectories
Bioprocess control systems and regulatory data harmonization are compressing development cycles while procurement models shift toward outcome-based ingredient specifications rather than commodity-grade purchasing.
Smart bioreactor sensor arrays paired with machine learning feedback loops are digitizing fermentation parameter optimization. Dairy processors in the Netherlands and Denmark deploy these systems to maintain strain viability within 0.5% tolerance across 10,000-liter batches. Real-time metabolite monitoring is digitizing quality assurance workflows that previously required offline chromatography, compressing release timelines from days to hours.
REACH registration requirements for novel microbial metabolites are tightening substance volume thresholds across EU member states. Industrial enzyme producers face reclassification pressure as fermentation-derived bioactives trigger chemical safety dossier obligations previously exempt under food-grade exemptions. German and French formulators are responding by front-loading toxicology studies to secure five-year registration windows ahead of 2027 dossier deadlines.
Ingredient buyers now specify colony-forming unit stability at 24-month shelf life rather than accepting manufacturer certificates of analysis. This specification inversion forces prebiotic fiber suppliers to invest in accelerated aging protocols and modified atmosphere packaging. The shift is most visible in Nordic retail channels where private-label functional dairy contracts embed penalty clauses for viability shortfalls.
Functional Food Ingredients Market Segmentation
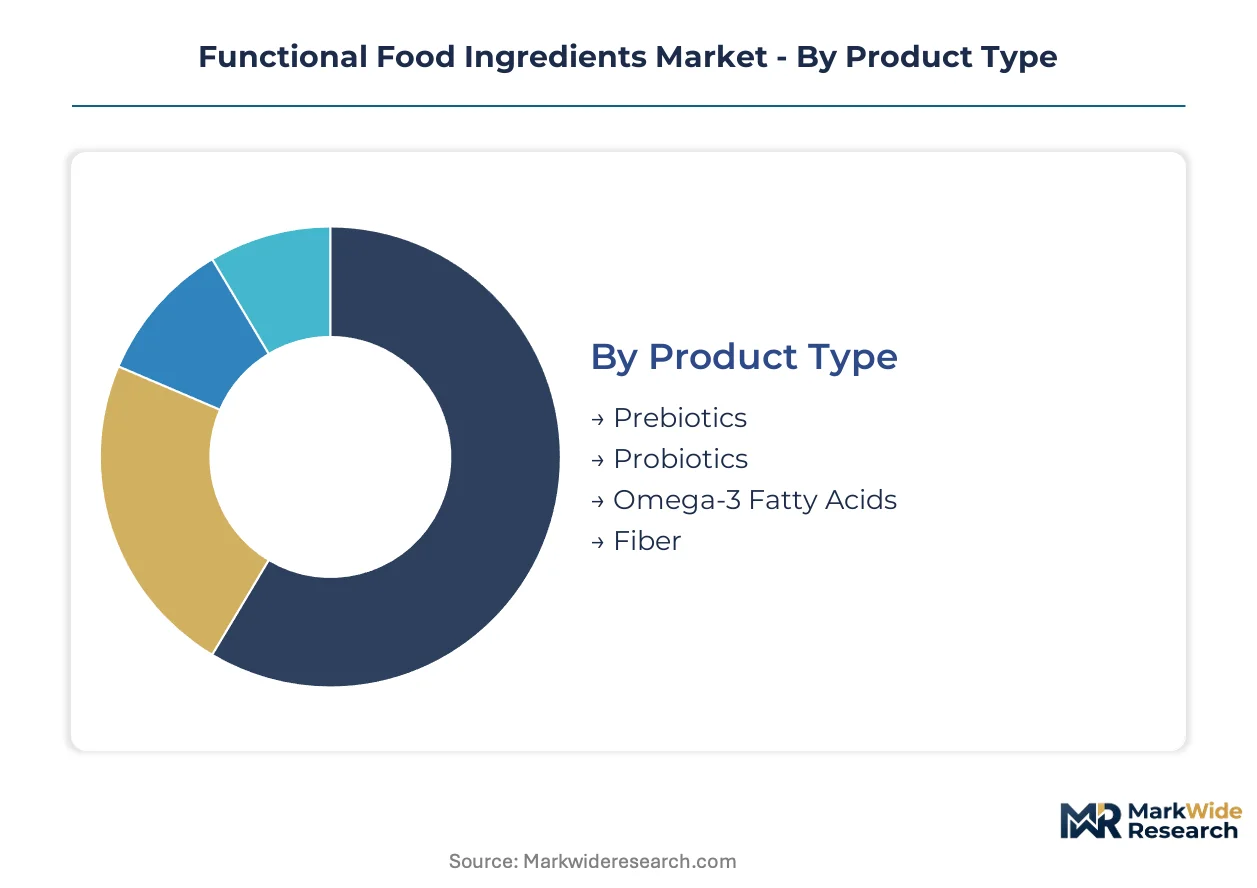
Segmentation in functional food ingredients determines formulation compatibility, regulatory pathways, and supply chain configuration. Technical specifications vary sharply across product categories, forcing procurement teams to align supplier qualification with end-use performance requirements.
Product Type:
After-sales technical support intensity runs highest for probiotic strains requiring viability monitoring and cold chain validation, while prebiotic fibers demand less intensive post-sale service.
- Prebiotics:Non-digestible oligosaccharides and resistant starches that selectively nourish beneficial gut microbiota. German dairy processors under EFSA novel food authorizations drive procurement volumes for inulin and fructooligosaccharide variants in yogurt applications.
- Probiotics:Live microbial cultures delivered in specified colony-forming units requiring stabilization through microencapsulation. ANVISA's streamlined Brazilian registrations for probiotic beverages are accelerating South American demand clusters for Lactobacillus and Bifidobacterium strains.
- Omega-3 Fatty Acids:EPA and DHA concentrates from algal or fish sources targeting cardiovascular and cognitive health positioning.
- Fiber:Soluble and insoluble fractions including beta-glucan and psyllium husk for digestive health claims.
By volume, probiotics lead. By growth pace, omega-3 alternatives from microbial fermentation are expanding most quickly.
Application:
Cost tier differentiation separates premium-positioned nutritional supplements from commodity-integrated dairy and bakery segments.
- Dairy Products:Fermented milk, yogurt, and cheese matrices requiring strain compatibility with acidic pH environments. Netherlands and Denmark dairy processors deploy smart bioreactor sensor arrays to maintain probiotic viability within tight tolerances across industrial-scale batches.
- Beverages:Shelf-stable and refrigerated drink formats demanding enhanced microencapsulation for aqueous stability. Brazil's ANVISA functional claim registration simplification is unlocking probiotic beverage launches previously stalled by regulatory uncertainty.
- Bakery:Heat-stable prebiotic fibers and resistant starches surviving oven temperatures for bread and snack integration.
- Nutritional Supplements:Concentrated delivery formats commanding premium pricing for clinical-grade substantiation dossiers.
By volume, dairy products lead. By margin expansion, nutritional supplements are gaining share fastest.
Ingredient Source:
Supply concentration varies sharply, with microbial fermentation platforms achieving scale parity fastest while plant-based extraction faces agricultural yield constraints.
- Microbial Fermentation:Precision biotechnology platforms using CRISPR-edited chassis strains for de novo bioactive synthesis. Bioreactor optimization has compressed cultivation cycles from weeks to days, enabling cost parity with fish-derived omega-3 sources.
- Plant-Based:Botanical extraction from chicory root, flaxseed, and algae requiring crop cultivation cycles and solvent processing. Chinese fermentation capacity expansion is reshaping global supply dynamics for specialty proteins and probiotic strains.
- Animal-Based:Fish oil concentrates and dairy-derived bioactives facing sustainability scrutiny and marine resource constraints.
- Synthetic:Chemically synthesized vitamins and amino acids with batch consistency advantages but clean-label positioning disadvantages.
By current volume, plant-based leads. By capacity expansion trajectory, microbial fermentation shows the steepest climb.
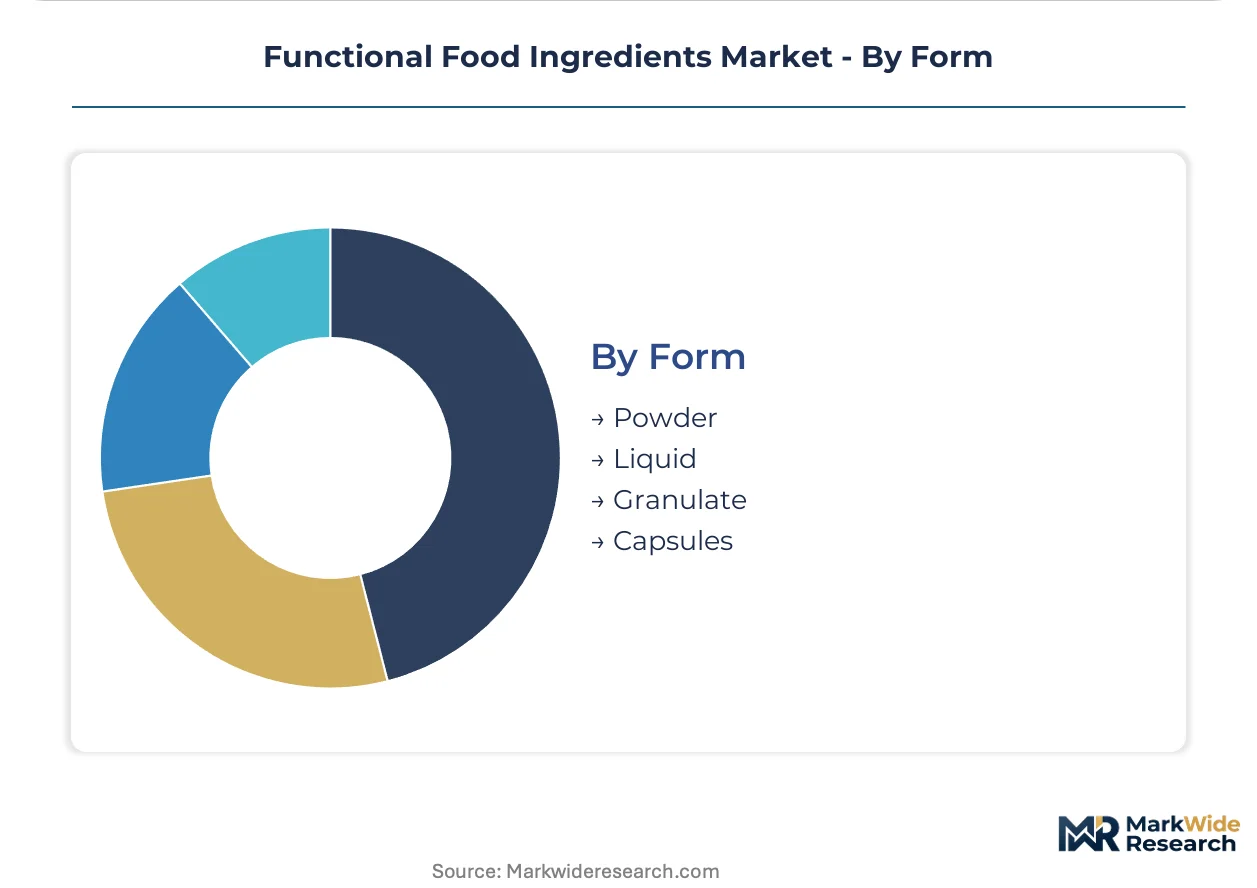
Form:
Customer type separates industrial powder procurement from direct-to-consumer capsule formats with divergent stability and dosing requirements.
- Powder:Extended stability, precise dosing accuracy, and lower transportation costs favor industrial procurement for dairy and beverage integration. Nordic retail channels now embed penalty clauses for 24-month shelf-life viability shortfalls.
- Liquid:Ready-to-use suspensions for beverage manufacturing with shorter stability windows and refrigerated distribution requirements.
- Granulate:Free-flowing particles for bakery and dry-mix applications with reduced dusting and improved handling characteristics.
- Capsules:Unit-dose delivery for nutritional supplements with modified-release coatings targeting intestinal delivery.
By procurement volume, powder leads. By channel expansion, capsules show the fastest growth in direct-to-consumer positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites European probiotic distribution, while Shanghai Yangshan Port's bioreactor feedstock terminals anchor Asia-Pacific fermentation capacity expansion.
Germany
Dairy processors in Bavaria and North Rhine-Westphalia drive prebiotic fiber procurement for yogurt applications. EFSA novel food authorizations streamline ingredient market entry, reducing regulatory lag for validated strains. Munich's biotech cluster concentrates precision fermentation R&D facilities serving pan-European formulators.
United States
Sports nutrition manufacturers in Utah and California propel demand for protein-fortified functional beverages. FDA GRAS self-affirmation pathways enable faster ingredient launches than European equivalents. Chicago's ingredient distribution hub consolidates procurement for Midwest dairy cooperatives.
Brazil
São Paulo and Minas Gerais beverage bottlers expand probiotic drink portfolios for health-conscious consumers. ANVISA's streamlined functional claim registrations cut approval timelines, unlocking previously stalled product launches. Campinas hosts South America's largest microbial culture production facility.
China
Tianjin and Shanghai fermentation complexes supply probiotic strains and specialty proteins to global formulators. SAMR's evolving food-supplement classification rules create compliance uncertainty for cross-border ingredient shipments. Hangzhou's biotech parks concentrate CRISPR-edited chassis strain development.
Netherlands
Dairy cooperatives in Friesland and Gelderland deploy smart bioreactor systems for industrial-scale probiotic viability control. REACH registration requirements for novel microbial metabolites tighten substance volume thresholds. Wageningen's food science cluster anchors European prebiotic fiber application research.
Functional Food Ingredients Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower technical scope. The supplier base organizes into three tiers: multinational agricultural conglomerates with captive raw material sourcing, mid-cap biotechnology firms with fermentation platform specialization, and regional ingredient distributors with formulation service capabilities. Dominant competitive moves include backward integration into strain development capabilities and strategic partnerships between fermentation technology providers and dairy processors.
Among diversified agricultural conglomerates, Cargill, Incorporated and Archer Daniels Midland Company exemplify platform integrators with integrated supply chain control over prebiotic fiber feedstocks. BASF SE occupies a position within the specialty chemicals tier, anchoring algal-derived omega-3 concentration technology. Kerry Group plc represents the formulation service archetype, blending multiple functional actives into customized ingredient systems for beverage and dairy applications.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| BASF SE |
| Archer Daniels Midland Company |
| Kerry Group plc |
| Ingredion Incorporated |
| DSM-Firmenich AG |
| Arla Foods amba |
| Tate & Lyle PLC |
| Glanbia plc |
| Others |
Supply Flow & Price Mechanics
Tianjin's fermentation complex capacity expansion is compressing spot prices for probiotic strains while concentrating bargaining power among buyers with multi-year offtake contracts. This supply-side scale-up feeds downstream into tiered pricing structures where volume commitments unlock preferential terms for dairy processors.
Pricing Analysis
Volume-discount tiering separates clinical-grade probiotic strains with EFSA novel food dossiers from commodity prebiotic fibers and unvalidated fermentation outputs. Price differentiation hinges on certification tier — ISO 22000 and FSSC 22000 qualifications command 15-20% premiums — and cold chain integrity guarantees. Cost compression in standard-grade prebiotic fibers is intensifying because Chinese fermentation scale-up has displaced European chicory root extraction. Contract manufacturers show highest price sensitivity; pharmaceutical-grade formulators least.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for probiotic culture banks. Manufacturing concentrates in China, Germany, and the Netherlands, with raw material flows drawing from algal biomass farms, corn-derived dextrose feedstocks, and specialized nitrogen sources. Single-source vulnerability persists for CRISPR-edited chassis strains developed in Hangzhou biotech parks. Distribution runs through Rotterdam's cold chain infrastructure for European dairy processors and Chicago's ingredient hub for North American beverage manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional food ingredients sit in early-cycle expansion as precision fermentation platforms displace extraction-dependent supply models and regulatory clarity unlocks previously stalled product categories.
For Market Incumbents: Harden regulatory affairs capabilities against EMA health claim substantiation timelines that now exclude mid-tier competitors without dedicated dossier teams. Deepen backward integration into strain development capabilities to reduce germplasm dependence on Shanghai and Tianjin culture banks. Lock in multi-year offtake agreements with Brazilian beverage bottlers before ANVISA registration simplification attracts new supplier entrants.
For New Entrants and Emerging Players: Establish a beachhead in sports nutrition white space across Mexico and Colombia where protein-fortified functional beverages remain underpenetrated relative to North American maturity. Target direct-to-consumer ingredient kits for home fermentation enthusiasts, bypassing traditional foodservice distribution margin capture. Lead with clean-label positioning and modified atmosphere packaging guarantees that address Nordic retail penalty clauses for viability shortfalls.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation platform specialists with CRISPR-edited chassis strain libraries and continuous bioprocessing capabilities. Long-term viability over a 5-10 year window rests on de novo synthesis expertise rather than botanical extraction relationships. Target acquisition archetype: mid-cap biotechnology firms with validated EFSA novel food authorizations and stranded capacity in precision fermentation infrastructure. The signal to watch is bioreactor utilization rates at Tianjin and Shanghai complexes as inflection indicator for global supply-demand balance.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Investment | Streamlined authorizations in Germany accelerate dairy and beverage product launches. |
| Precision Fermentation Scale-Up | CRISPR-edited chassis strains enable cost parity with fish-derived omega-3 sources. |
| Smart Bioreactor Sensor Deployment | Dutch and Danish dairy processors maintain probiotic viability within 0.5% tolerance across industrial batches. |
| Direct-to-Consumer Channel Expansion | Ingredient kits bypass foodservice distribution, capturing margin from DIY probiotic cultures. |
| Regulatory Affairs Team Buildout | Dedicated EMA and FDA expertise creates compliance moats against mid-tier competitors. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EFSA novel food authorization databases, ANVISA functional claim registries, and fermentation platform patent filings. Primary interviews engaged regulatory affairs directors at multinational ingredient suppliers, procurement leads at German and Dutch dairy cooperatives, and bioprocess engineers at precision fermentation facilities. Secondary validation drew from FDA GRAS notification logs, REACH registration submissions for microbial metabolites, and trade flow data through Rotterdam and Shanghai Yangshan ports. Bottom-up strain-level production estimates triangulate against top-down category demand projections.
Forecast inputs incorporate bioreactor capacity expansion timelines, EFSA and ANVISA regulatory pipeline velocities, and dairy processor procurement contract tenors across the analysis window. Segmentation dimensions include product type, application matrix, ingredient source technology, and geographic regulatory cluster. CAGRs derive from supply-demand balance modeling where precision fermentation cost curves intersect with extraction-based alternatives. Industry-specific inputs capture algal oil photobioreactor yield volatility and microencapsulation formulation chemist compensation inflation.
Stress conditions across Chinese strain supply concentration, EMA health claim approval delays, and algal biomass climate control energy costs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway efficiencies and bioreactor scale-up success rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Europe Botanical Extract Market
Functional Food & Ingredients
South America Prebiotic Ingredients Market
Functional Food & Ingredients
Mediterranean Cognitive-First Ingredient Systems Market
Functional Food & Ingredients
Poultry Probiotic Ingredients Market
Functional Food & Ingredients
Mediterranean Pre-Diabetes Ingredient Concepts Market
Functional Food & Ingredients
Low-Carb Low-Fat Meal Market
Functional Food & Ingredients
Healthy Fats Low Carb Market
Functional Food & Ingredients
South America Omega-3 PUFA Market
Functional Food & Ingredients
North America Omega-3 PUFA Market
Functional Food & Ingredients
Europe Prebiotic Ingredient Market
Functional Food & Ingredients
Prebiotic Ingredients Market
Functional Food & Ingredients
Africa Omega-3 PUFA Market
Functional Food & Ingredients
North America Pea Protein Ingredients Market
Functional Food & Ingredients
Europe Sterol Market
Functional Food & Ingredients
Global Whole Grain and High Fiber Food Market
Functional Food & Ingredients
Japan Soy Protein Market