
 Global Weaving Machinery Market | 2026-2036
Global Weaving Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Weaving Machinery Market Foresight
The EU Green Deal's textile sustainability requirements is repositioning capital expenditure toward energy-efficient weaving platforms. Dornier GmbH leverages its rapier loom specialization to anchor premium technical fabric lines in Germany. Picanol sustains R&D intensity across electronic jacquard controls, while Itema S.p.A. dominates air-jet loom sales into high-speed apparel operations.
Weaving machinery comprises mechanically or electronically controlled looms that interlace warp and weft yarns at speeds exceeding 2,000 picks per minute for industrial textile production. These systems execute shed formation, weft insertion, and beat-up through cam, dobby, or jacquard mechanisms to manufacture fabrics ranging from lightweight apparel cloth to heavy-duty industrial belting. Air-jet looms lead volume shipments for standardized apparel fabrics where speed economics override flexibility requirements. Electronic jacquard technology captures expanding margin pools in technical fabrics and automotive textiles as pattern complexity commands pricing premiums. Rapier looms retain structural importance in home textiles and upholstery where diverse yarn counts and delicate fibers demand gentle handling.
REACH chemical compliance in Europe, EPA emissions standards in the United States, and China's GB energy-efficiency mandates collectively elevate capital barriers for loom manufacturers seeking multi-regional market access. ECHA's restricted substance lists now extend to textile finishing chemicals, forcing upstream machinery suppliers to certify compatibility with water-based and low-VOC process chemistries. Stakeholders must monitor how divergent national efficiency standards reshape equipment specification requirements and aftermarket service obligations.
Market Dynamics
EU Green Deal textile sustainability mandates are forcing capital rotation from legacy mechanical looms toward electronically controlled energy-efficient platforms, compressing replacement cycles and redistributing vendor market power.
Growth Catalysts
- REACH chemical compliance extension:ECHA's restricted substance lists now cover textile finishing chemicals, compelling fabric producers to upgrade looms compatible with water-based and low-VOC process chemistries.
- Electric vehicle interior specifications:Automotive textile producers in Germany and Japan are expanding procurement of electronic jacquard systems to meet tighter pattern complexity and durability requirements for EV cabin fabrics.
- Vietnam fabric export corridor concentration:Weaving capacity expansion in Binh Duong and Dong Nai provinces is pulling air-jet and rapier loom shipments toward Southeast Asian manufacturing clusters.
Market Restraints
- Steel and electronic component cost volatility:Loom frames and servo motor inputs face commodity price swings that compress manufacturer margins and destabilize project quoting.
- Precision component supply concentration:High-tolerance shedding cams and electronic jacquard modules rely on specialized German and Japanese suppliers, creating single-source vulnerability.
- Regulatory fragmentation:Divergent efficiency certification requirements between EPA emissions standards, EU machinery directives, and China's GB energy mandates multiply compliance costs for multi-regional vendors.
Strategic Opportunities
- India technical textile expansion:PLI scheme incentives for geotextiles and medical fabrics are opening procurement windows for rapier and projectile loom suppliers in Gujarat and Tamil Nadu.
- Digital twin integration:Convergence of IoT sensors and predictive maintenance software enables outcome-based service contracts that capture recurring revenue from installed loom fleets.
- Remanufacturing and retrofit services:Secondary markets for electronic control upgrades on mechanical dobby looms offer margin capture without full replacement capex burden.
Industry Challenges
- Mechatronics technician scarcity:Servo drive calibration and electronic jacquard programming skills lag equipment complexity, extending commissioning timelines and service costs.
- Legacy system integration friction:Mill floors running 1990s-era mechanical looms face fiber path incompatibility and control protocol mismatches when adding digitally controlled units.
- Multi-jurisdiction certification timelines:CE marking, UL listing, and CCC approval sequences for new loom models stretch 14-22 months, delaying regional market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Weaving Machinery Market |
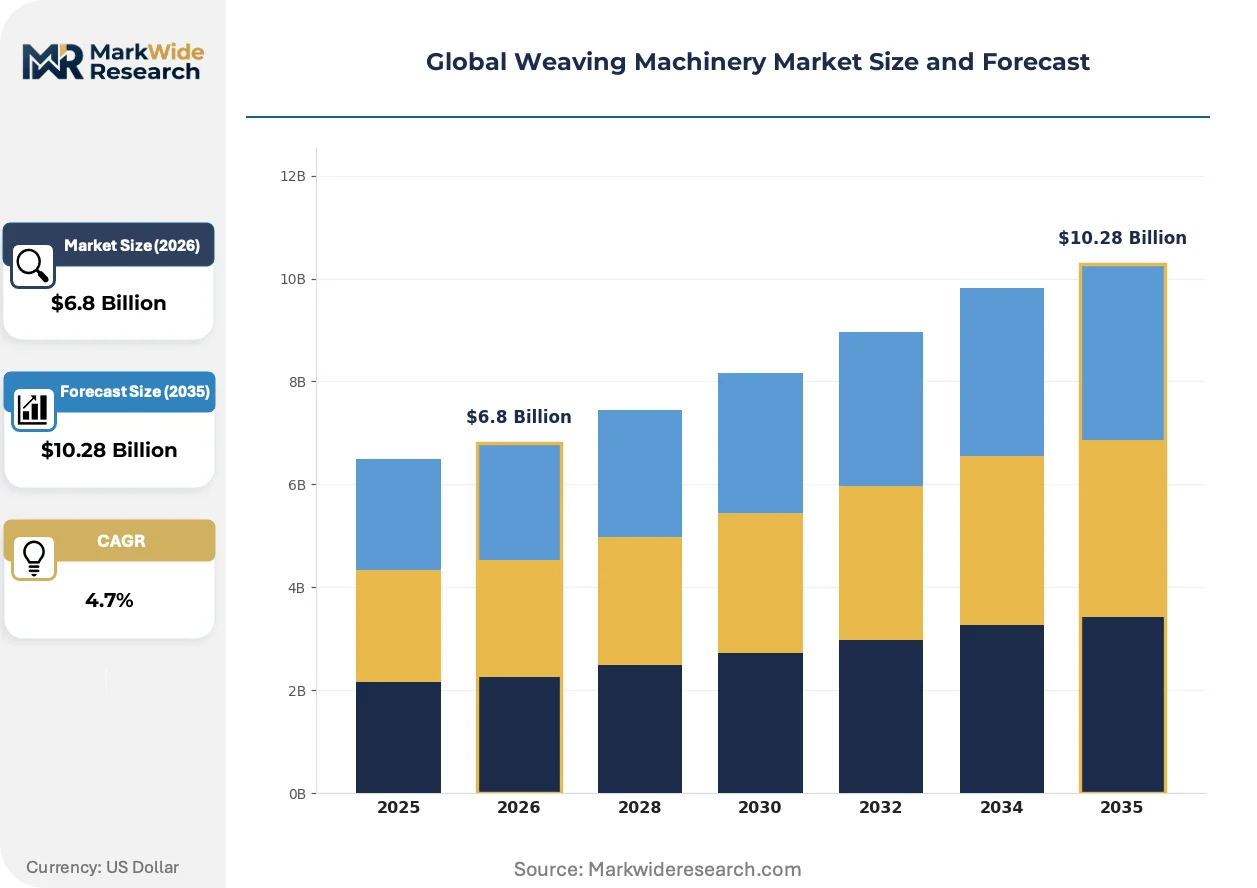
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
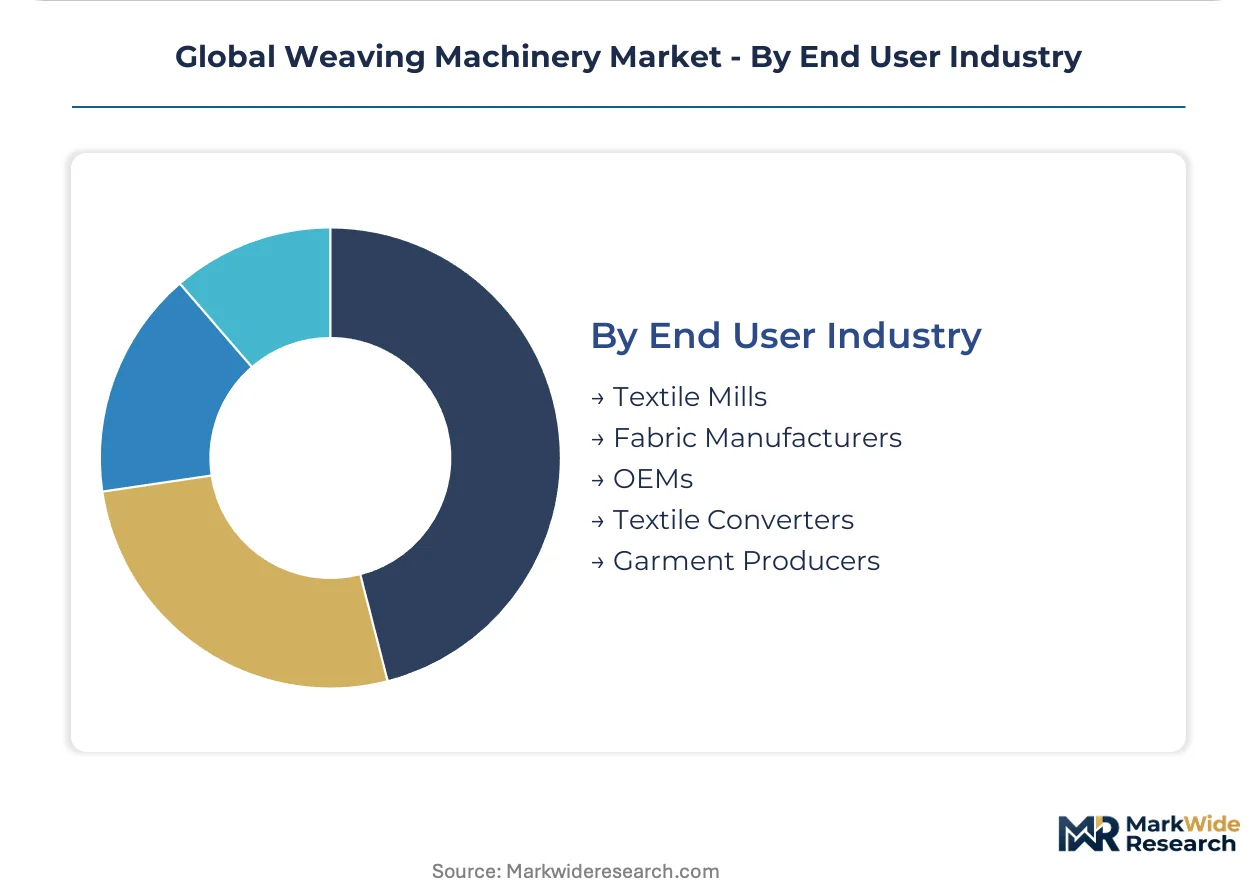
| Segmentation | Product Type: Rapier Looms, Air-Jet Looms, Water-Jet Looms, Projectile Looms, Circular Looms, Dobby Looms Technology: Electronic Jacquard, Mechanical Jacquard, Computerized Shedding, Drum Dobby, Release Dobby Application: Home Textiles, Technical Fabrics, Apparel Fabrics, Automotive Textiles, Industrial Textiles, Upholstery Textiles End User Industry: Textile Mills, Fabric Manufacturers, OEMs, Textile Converters, Garment Producers |
| Companies Covered | Dornier GmbH, Staubli Group, Picanol, Bonas, Rieter, Itema S.p.A., Tsudakoma Corp., SMIT Textile Machinery, Toyota Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Weaving Machinery Market Shifts & Advancements
Electronics and software are displacing mechanical control systems across loom architectures, while regulatory chemical restrictions and buyer consolidation reshape competitive requirements and procurement patterns.
Electronic jacquard shedding systems are consolidating control over pattern complexity in technical fabric production. Automotive seating suppliers and industrial belting manufacturers now specify 10,000+ hook capacities as baseline requirements. This capability concentration is consolidating margin pools around vendors with proprietary servo drive and harness motion algorithms, squeezing mechanical dobby specialists toward commodity apparel segments.
EPA emissions standards and EU machinery directives are tightening energy efficiency verification for textile equipment. Loom manufacturers must now submit third-party tested power consumption curves across operating speed ranges. Air-jet loom producers face the steepest compliance burden, as compressor energy draw dominates lifecycle operating costs and threatens market access in regulated jurisdictions.
Buyer concentration among vertically integrated fabric-to-garment groups is compressing equipment specification diversity. Large Vietnamese and Bangladeshi textile groups now mandate standardized control interfaces and remote diagnostics compatibility across multi-facility fleets. This procurement rationalization favors global loom vendors with established service networks over regional specialists lacking distributed technical support infrastructure.
Global Weaving Machinery Market Segmentation
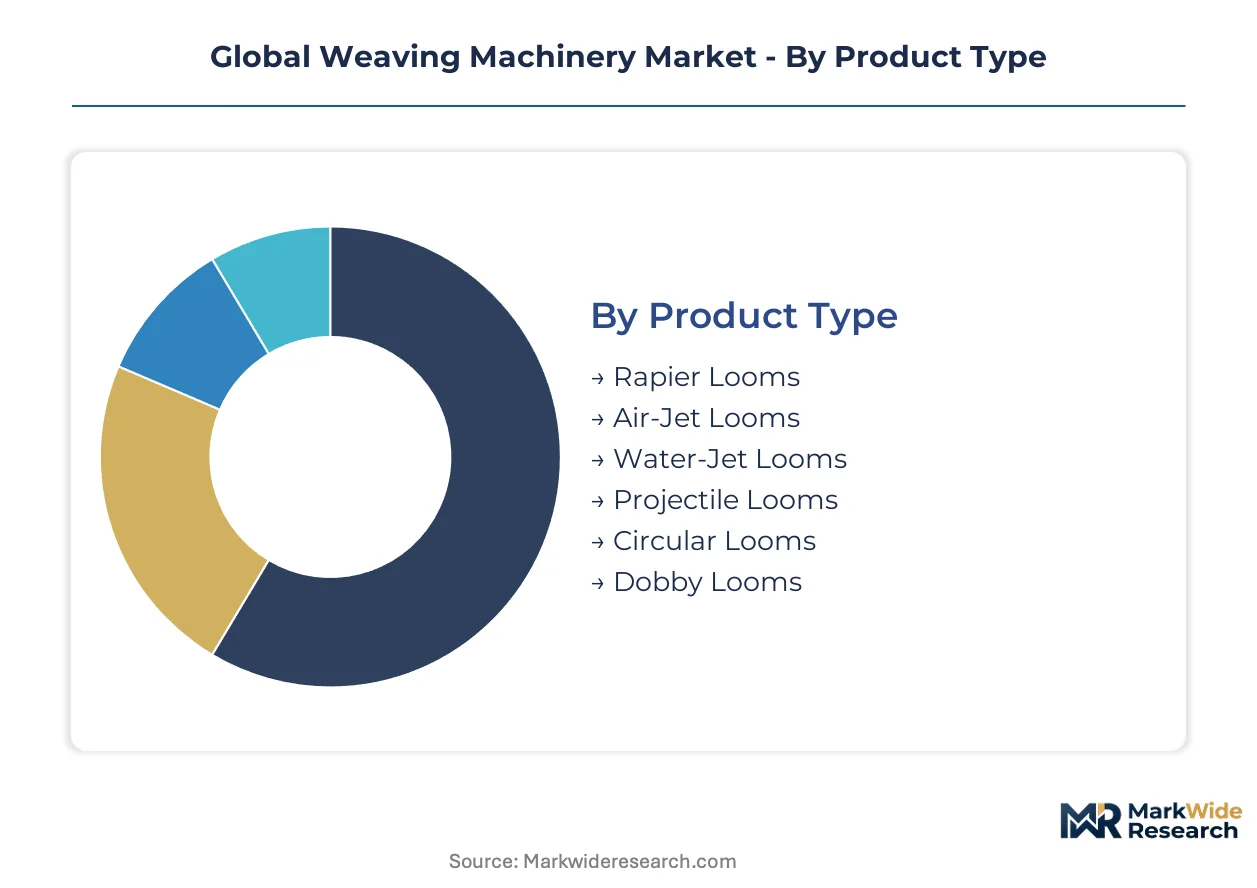
Weaving machinery segmentation reveals how capital allocation priorities diverge across loom architectures, control systems, and end-use specifications. Buyers select platforms based on speed economics, pattern complexity requirements, and fiber handling gentleness rather than universal performance metrics.
Product Type:
Buyers differentiate primarily by the trade-off between production velocity and material flexibility, with speed-focused apparel producers diverging sharply from technical fabric specialists.
- Air-Jet Looms:These machines deploy compressed air to propel weft yarns across the shed at rates exceeding 2,000 picks per minute. Vietnam's Binh Duong export corridor is pulling concentrated procurement of these systems as vertically integrated garment groups standardize on high-speed standardized fabric output.
- Rapier Looms:Mechanical grippers or flexible rapiers insert weft yarns with minimal tension, preserving delicate fiber integrity. German automotive seating suppliers and Italian upholstery manufacturers specify these platforms for technical fabrics requiring diverse yarn counts and gentle handling.
- Water-Jet Looms:High-pressure water streams propel weft insertion, limiting application to hydrophobic synthetic fibers. Japanese filament fabric producers dominate procurement for lightweight polyester apparel bases.
- Projectile Looms:Small metal projectiles carry weft across wide weaving widths, serving heavy-duty industrial belting and geotextile manufacturers in Gujarat's technical textile zones.
- Circular Looms:Continuous warp beams enable seamless tube formation for packaging and agricultural mesh applications. Chinese PP woven bag producers maintain the largest installed base.
- Dobby Looms:Mechanical or electronic cam systems control limited pattern repeat capabilities for mid-complexity home textiles. Turkish towel and bed linen manufacturers represent core demand.
Air-jet systems lead volumes today; rapier platforms are gaining share fastest in premium technical segments.
Technology:
Control system selection determines pattern resolution capabilities and energy consumption profiles, with electronic architectures commanding pricing premiums over mechanical alternatives.
- Electronic Jacquard:Individual warp thread control via electromagnetic actuators enables 10,000+ hook pattern complexity. Automotive textile producers in Germany and Japan mandate these systems for EV cabin fabric specifications requiring intricate designs and durability certification.
- Computerized Shedding:Software-driven harness motion optimizes beat-up timing and reduces mechanical wear. Bangladeshi fabric-to-garment groups prioritize these controls for multi-facility fleet standardization and remote diagnostics integration.
- Mechanical Jacquard:Punched card or barrel mechanisms control pattern selection, retaining cost advantage for traditional ethnic textile producers in India.
- Drum Dobby:Rotating drums with pegs or magnets select harness frames for geometric pattern repeats. Indonesian batik and ikat weaving cooperatives sustain niche demand.
- Release Dobby:Spring-return mechanisms enable rapid shedding motion for high-speed plain and twill constructions. Egyptian cotton sheeting mills favor these for volume efficiency.
Electronic jacquard dominates margin capture; computerized shedding is climbing the fastest as mills retrofit mechanical legacy assets.
Application:
End-use specifications dictate loom selection through required fabric weight ranges, pattern complexity thresholds, and regulatory compliance burdens.
- Technical Fabrics:Geotextiles, medical textiles, and industrial filtration media require precise porosity control and certification traceability. India's PLI scheme incentives are opening procurement windows for rapier and projectile loom suppliers in Tamil Nadu.
- Automotive Textiles:Seating fabrics, headliners, and airbag substrates must meet flammability and abrasion standards. Suppliers to BMW, Mercedes-Benz, and Toyota specify electronic jacquard systems with servo-driven harness motion.
- Home Textiles:Bedding, curtains, and table linens balance decorative patterning with production economics. Turkish and Portuguese manufacturers concentrate procurement of mid-tier dobby and mechanical jacquard platforms.
- Apparel Fabrics:Woven shirting, suiting, and denim prioritize speed and width consistency. Vietnam and Bangladesh drive air-jet loom demand for export-oriented garment integration.
- Industrial Textiles:Conveyor belting, hose reinforcement, and composite preforms require heavy-duty construction. German and US mining equipment suppliers source from specialized projectile loom producers.
- Upholstery Textiles:Furniture and marine seating demand abrasion resistance and colorfastness. Italian design houses and North Carolina contract furniture manufacturers specify rapier platforms for wool and synthetic blends.
Apparel fabrics lead volumes today; automotive textiles are expanding most quickly as EV interior specifications tighten.
End User Industry:
Customer scale and integration depth determine procurement sophistication, with vertically integrated groups imposing standardization requirements that reshape vendor competitive dynamics.
- Textile Mills:Large-scale integrated producers operate multi-hundred-loom facilities with centralized maintenance and programming capabilities. Vietnamese conglomerates like Vinatex and TAL Apparel mandate standardized control interfaces across air-jet and rapier fleets.
- Fabric Manufacturers:Specialized weavers serving branded apparel and industrial customers prioritize pattern flexibility over raw speed. Italian Como silk producers and Japanese synthetic specialists maintain diversified loom portfolios.
- OEMs:Automotive tier-one suppliers and industrial equipment manufacturers source certified fabrics with full material traceability. Lear Corporation and Adient specify electronic jacquard output for seating programs.
- Textile Converters:Commission weavers and toll processors require rapid style changeover capabilities. Surat's polyester hub and Keqiao's fabric market sustain demand for versatile dobby and small-batch jacquard systems.
- Garment Producers:Vertically integrated apparel groups adding captive weaving capacity prioritize speed and width standardization. Shein, Zara, and H&M supplier networks in Bangladesh and Ethiopia drive air-jet procurement.
Textile mills lead volumes today; OEMs are gaining share fastest as automotive and industrial certification requirements concentrate procurement among qualified suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Weaving machinery manufacturing traces its industrial lineage to 19th-century European textile engineering centers, with subsequent capacity dispersion toward Asian export manufacturing corridors reshaping regional demand patterns.
Germany
Automotive seating suppliers and technical fabric producers drive loom procurement toward electronic jacquard platforms. The EU Green Deal's machinery efficiency directives compel manufacturers to certify energy consumption curves across operating speeds. Stuttgart and Chemnitz industrial clusters host specialized servo drive and harness motion engineering for premium weaving systems.
China
GB energy-efficiency mandates and dual carbon goals accelerate replacement of mechanical looms with electronically controlled platforms. The Yangtze River Delta and Shandong Peninsula concentrate air-jet and water-jet loom production for synthetic fiber fabrics. MIIT textile industry guidelines prioritize intelligent manufacturing upgrades in weaving operations.
Vietnam
Vertically integrated garment groups in Binh Duong and Dong Nai provinces expand captive weaving capacity for export-oriented production. Government industrial zone incentives support machinery imports for fabric-to-garment integration. Ho Chi Minh City periphery clusters pull concentrated air-jet loom shipments from European and Japanese suppliers.
India
PLI scheme incentives for technical textiles open procurement windows for rapier and projectile loom suppliers. BIS certification requirements and state-level textile policies shape equipment specification standards. Gujarat's technical textile zones and Tamil Nadu's weaving belts drive regional demand concentration for industrial fabric production.
United States
EPA emissions standards elevate compliance burdens for air-jet loom compressor energy verification. Industrial belting and automotive textile producers specify electronic controls for pattern complexity and durability certification. North Carolina's contract furniture manufacturing and Georgia's technical textile corridors sustain regional equipment demand.
Global Weaving Machinery Market Competitive Landscape
Capital-heavy machinery fabricators compete with asset-light control system designers across differentiated competitive terrain. The vendor base organizes around three strategic archetypes: integrated loom manufacturers with proprietary electronic controls, specialized component suppliers licensing technology across multiple OEMs, and regional assemblers sourcing standardized subsystems. Consolidation pressures concentrate among electronic jacquard and servo drive specialists, while geographic expansion and strategic partnerships constitute the dominant competitive moves for market access.
Among European integrated manufacturers, Dornier GmbH, Picanol, and Itema S.p.A. occupy positions exemplifying the premium-tier archetype with established service networks across Asian manufacturing corridors. These entities represent the control system consolidation pattern, with proprietary algorithms and harness motion engineering anchoring competitive positioning in technical fabric segments. Staubli Group exemplifies the specialized component supplier archetype, licensing shedding and weaving preparation systems across multiple loom OEMs rather than competing in finished machinery assembly.
| Leading Market Players |
|---|
| Dornier GmbH |
| Staubli Group |
| Picanol |
| Bonas |
| Rieter |
| Itema S.p.A. |
| Tsudakoma Corp. |
| SMIT Textile Machinery |
| Toyota Industries |
| Others |
Supply & Pricing Matrix
Captive weaving capacity expansion among Vietnamese garment conglomerates anchors both supply positioning and pricing power across the machinery procurement landscape. These vertically integrated groups leverage standardized fleet specifications to compress vendor margins while securing preferential service terms from European and Japanese loom manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates electronic jacquard systems from computerized shedding platforms from mechanical dobby units. Price differentiation rests on certification grade—CE-marked energy-efficient platforms command substantial premiums over non-compliant alternatives. Cost compression in the economy tier is intensifying because Chinese manufacturers are flooding Southeast Asian markets with stripped-down air-jet configurations. Garment producers in Bangladesh exhibit the highest price sensitivity, while German automotive seating suppliers demonstrate minimal elasticity for certified technical fabric systems.
Supply Chain Analysis
Remanufacturing flows for electronic control modules and servo drive assemblies are creating secondary supply channels that compete with original equipment channels. Component manufacturing concentrates in Germany, Japan, and China, with high-tolerance shedding cams and jacquard modules drawing from specialized precision engineering clusters in Stuttgart and Nagoya. Steel frame fabrication and electronic component sourcing face single-source vulnerability for specialized harness motion systems. Distribution runs through manufacturer-direct sales teams for large mill contracts, while regional distributors handle smaller textile converter accounts across South and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal machinery efficiency mandates are systematically accelerating replacement cycles and redistributing procurement toward certified electronic platforms.
For Market Incumbents: Deploy predictive maintenance software integration to lock in recurring revenue from installed loom fleets. Dornier and Picanol must deepen backward integration into proprietary servo drive engineering to defend against Chinese control system encroachment. Certification investment in EPA emissions verification and BIS energy-efficiency marking represents the critical defensive lever against margin erosion in regulated jurisdictions.
For New Entrants and Emerging Players: Digital spare parts platforms offer a low-capital route to capture aftermarket service revenue from legacy mechanical loom installations. India's technical textile expansion under PLI scheme incentives represents the most penetrable white-space target for rapier and projectile loom specialists. A retrofit-focused go-to-market angle—selling electronic jacquard upgrades rather than full replacement systems—sidesteps the capital intensity barrier that protects incumbent positions.
For Investors and Strategic Acquirers: Roll-up economics work for electronic control system specialists because proprietary harness motion algorithms are consolidating margin pools as pattern complexity requirements escalate across automotive and technical fabric segments. The five-to-ten year viability window favors targets with established service networks in Vietnam and India over pure technology licensors lacking geographic presence. Monitor ECHA restricted substance list expansions as the inflection indicator for accelerated capital rotation toward water-based process chemistry-compatible platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Electronic Control Retrofit Services | Captures margin from mechanical loom installed base without full replacement capex burden. |
| Energy Efficiency Certification Investment | Secures EU Green Deal compliance and access to sustainability-linked procurement windows. |
| Predictive Maintenance Platform Launch | Enables outcome-based service contracts with Vietnamese and Bangladeshi mill operators. |
| Technical Textile Application Expansion | Opens PLI scheme procurement channels in Gujarat and Tamil Nadu industrial zones. |
| Regional Service Network Densification | Meets buyer concentration demands for standardized control interfaces across multi-facility fleets. |
Research Methodology
Direct dialogue with loom manufacturer product managers, textile mill maintenance directors, automotive tier-one supplier procurement leads, and aftermarket service heads grounded the qualitative assessment. Secondary validation drew from MIIT textile industry guidelines, ECHA restricted substance database updates, customs machinery import records, and SEC filings from listed textile equipment manufacturers. Bottom-up demand modeling across end-use segments and top-down supply capacity assessments were triangulated to constrain forecast variance.
Installed base projections and replacement cycle timing emerged from segment-level capital expenditure pattern analysis across the projection horizon. The modeling framework incorporated loom architecture type, control system technology tier, end-use application specification, and regional regulatory compliance cluster as primary segmentation dimensions. CAGRs were derived from historical machinery shipment correlations with fabric production capacity expansion and forward-looking policy incentive trajectories. Energy efficiency mandate stringency indices and electric vehicle interior specification evolution served as key industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for mechanical-to-electronic control migration would alter the outlook if legacy system retrofit economics improve unexpectedly. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and commodity input price stabilization. Practitioners should monitor ECHA substance restriction announcements, EPA compressor energy verification rulemaking, and Indian PLI scheme disbursement pacing for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Technical Textile Production Equipment Market
Textile Machinery and Equipment
Global Digital Textile Printing Machine Market
Textile Machinery and Equipment
Stringing Machines Market
Textile Machinery and Equipment
3D Knitting Machines Market
Textile Machinery and Equipment
Global Textile Machinery Market
Textile Machinery and Equipment
Plasma Surface Treatment Machine for Leather Market
Textile Machinery and Equipment
Multifunctional Clothes Folding Machine Market
Textile Machinery and Equipment
Gel Dryer Market
Textile Machinery and Equipment
Tarpaulin Market
Textile Machinery and Equipment
Dyeing Machine Market
Textile Machinery and Equipment
Global Custom T-Shirt Printing Market
Textile Machinery and Equipment
Compact Spinning Machine Market
Textile Machinery and Equipment
Textile Tester Market
Textile Machinery and Equipment
Disposable Garment Bags Market
Textile Machinery and Equipment
Fiber Spinning Equipment Market
Textile Machinery and Equipment
Global Rotary Clothes Dryer Market