
 North America Sanitary Napkin Market | 2026-2036
North America Sanitary Napkin Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sanitary Napkin Market Intelligence
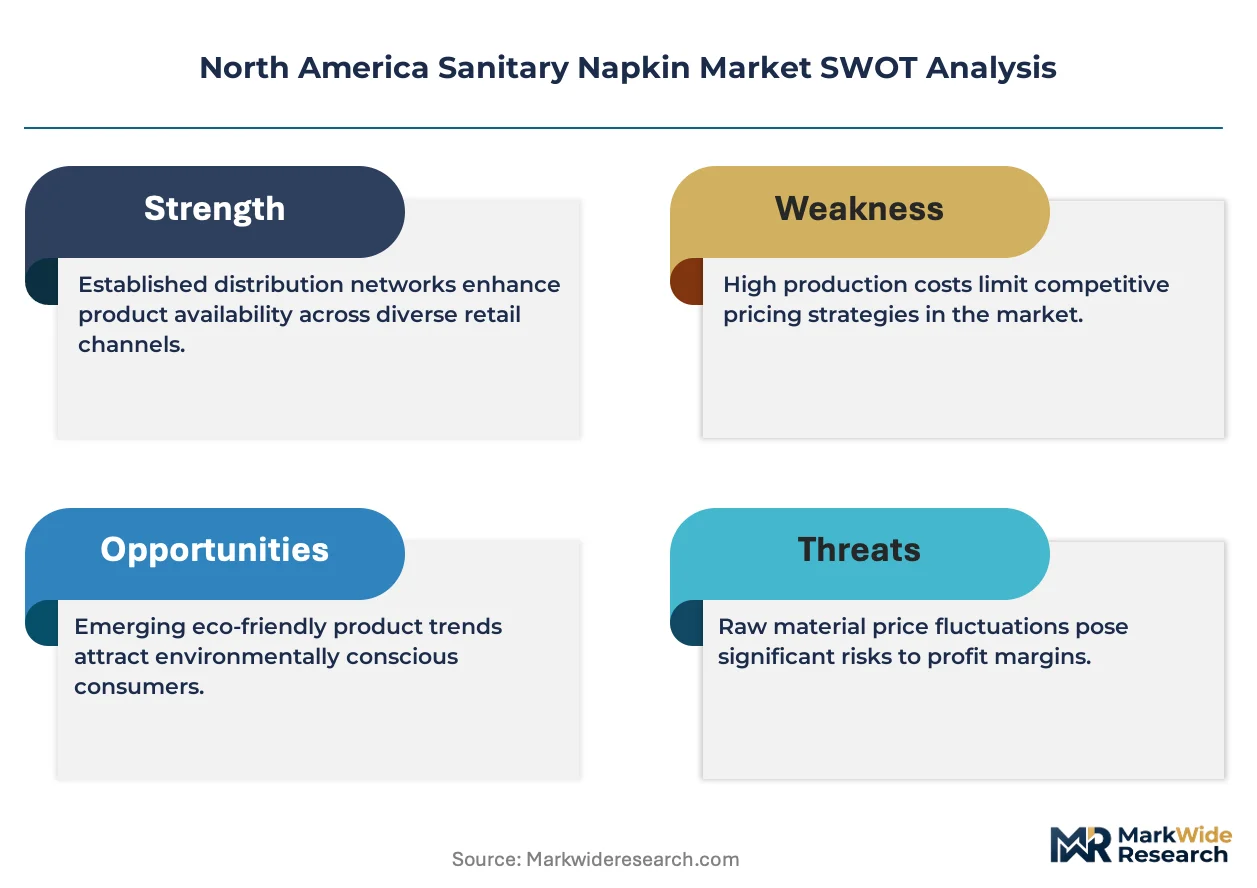
Plant-based absorbent core technology is tilting product formulation away from petroleum-derived superabsorbent polymers across North American manufacturing. Kimberly-Clark Corporation leverages its integrated pulp supply chain to control raw material costs. Procter & Gamble anchors its position through extensive clinical testing protocols that validate performance claims. Edgewell Personal Care specializes in natural-ingredient positioning to capture premium shelf space in specialty retail channels.
A sanitary napkin is a disposable absorbent pad worn during menstruation, typically constructed with a topsheet of nonwoven polypropylene or perforated film, an absorbent core of fluff pulp and superabsorbent polymer, and a polyethylene backsheet to prevent leakage. The product serves the essential function of managing menstrual flow with varying capacity levels calibrated to flow intensity and duration. Overnight variants command disproportionate margin pools due to higher unit pricing and lower price elasticity among consumers prioritizing sleep protection. Biodegradable materials represent the fastest-growing material category as state-level plastic reduction mandates intensify pressure on synthetic components. Online distribution channels are gaining structural share as subscription models reduce customer acquisition costs and improve inventory predictability for manufacturers.
The US FDA enforces absorbency labeling standards under its medical device framework, compelling manufacturers to substantiate performance claims through standardized testing protocols. Health Canada applies similar rigor through its medical device regulations, creating a harmonized compliance burden across the US-Canada trade corridor. Mexico's national health regulator maintains parallel sanitary standards that govern import clearance and domestic manufacturing licensing. Stakeholders must monitor evolving state-level chemical disclosure requirements in California and New York, as these jurisdictions increasingly mandate ingredient transparency that exceeds federal baselines.
Market Dynamics
Plant-based absorbent core technology is restructuring North American manufacturing economics by displacing petroleum-derived superabsorbent polymers. FDA absorbency labeling mandates and state-level chemical disclosure requirements in California and New York are simultaneously compressing formulation flexibility while opening premium positioning for transparent supply chains.
Growth Catalysts
- Teen menstrual health education:School-based curriculum expansion across the United States and Canada is creating first-time buyers earlier in the consumer lifecycle, extending brand relationship duration.
- California SB 54 plastic reduction mandates:State-level packaging regulations are accelerating biodegradable material R&D investment and rewarding early compliance with shelf placement advantages.
- Subscription commerce infrastructure:Direct-to-consumer replenishment models are lowering customer acquisition costs and improving demand forecasting accuracy for manufacturers.
Market Restraints
- Fluff pulp supply concentration:North American pulp production clusters in the US Southeast, creating geographic vulnerability to hurricane disruption and freight cost spikes.
- Superabsorbent polymer import dependency:Specialty SAP resin supply concentrates among Asian petrochemical producers, exposing margins to currency and tariff volatility.
- FDA 510(k) clearance timelines:Medical device classification for novel absorbent technologies extends product launch cycles by 18-24 months versus cosmetic-grade competitors.
Strategic Opportunities
- Mexico manufacturing expansion:Lower labor and energy costs in Guanajuato and Querétaro states offer export platforms serving US Southwest and Latin American markets.
- Reusable product hybridization:Menstrual cup and period underwear convergence with disposable pad technology creates dual-use product categories.
- Health Canada organic certification:Federal natural product standards provide premium positioning framework unmatched by US federal equivalents.
Industry Challenges
- Biodegradable certification backlog:Third-party compostability verification through BPI and TÜV Austria faces 12-16 month queues, delaying marketing claims.
- Legacy ERP integration:Subscription commerce and inventory management platforms require costly middleware development to connect with established manufacturing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sanitary Napkin Market |
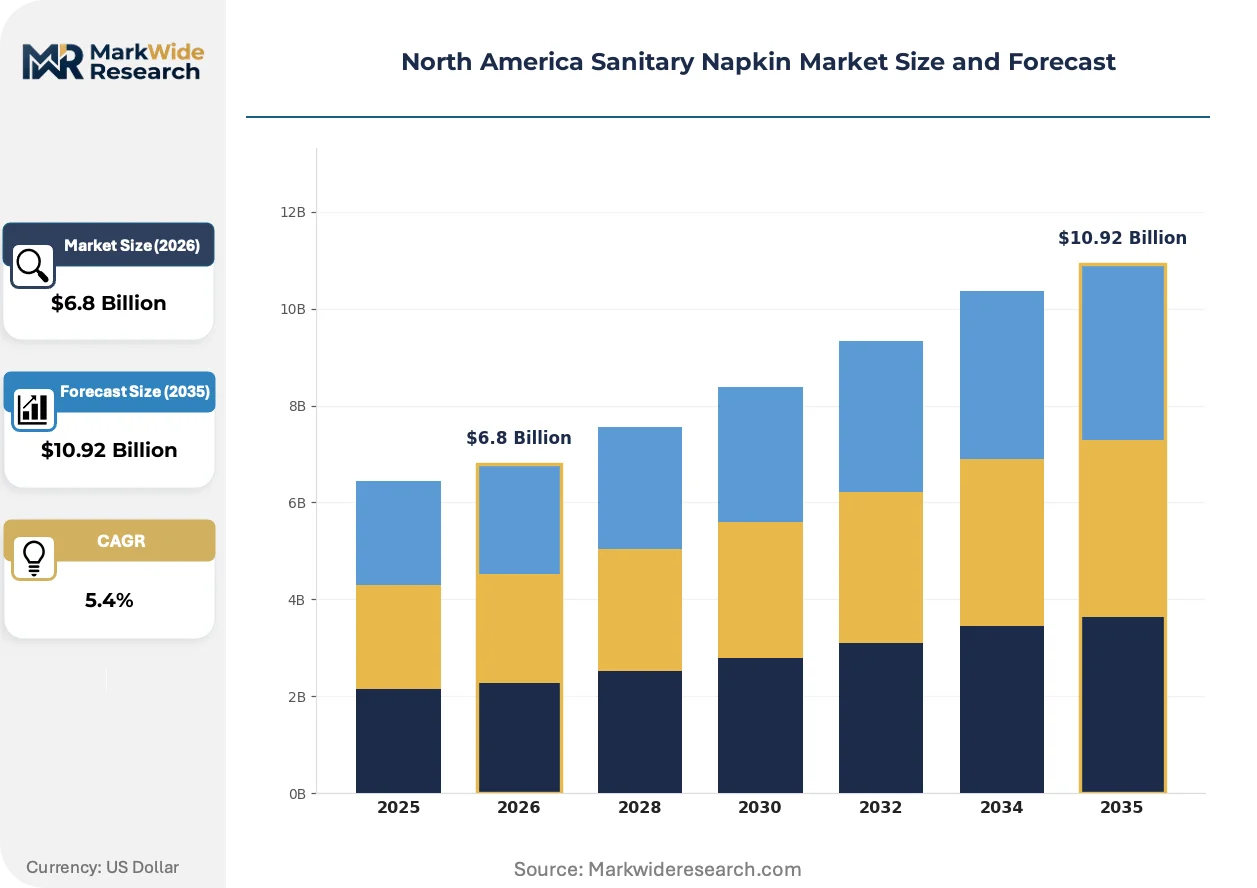
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Super, Overnight, Panty Liners Material: Cotton, Rayon, Biodegradable, Synthetic End User: Women, Teens, Healthcare Facilities, Retail Customers Distribution Channel: Online, Supermarkets, Pharmacies, Convenience Stores |
| Companies Covered | Essity AB, Edgewell Personal Care, Procter & Gamble, Ontex Group, Unicharm Corporation, Kimberly-Clark Corporation, Kao Corporation, The Honest Company, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sanitary Napkin Market Strategic Shifts & Innovations
Digital manufacturing and materials science are converging to compress product development cycles while regulatory transparency requirements reshape competitive positioning. Three forces are actively restructuring how sanitary napkins are formulated, certified, and distributed across North America.
Bio-based superabsorbent polymers derived from corn starch and cellulose are virtualizing the traditional petroleum-SAP supply chain. Kimberly-Clark and smaller specialty manufacturers are piloting these materials in overnight and heavy-flow variants where absorbency performance is most critical. The technology is virtualizing cost structures by enabling manufacturers to hedge against oil price volatility while meeting state plastic reduction mandates.
California's Safer Consumer Products regulations and New York's menstrual product ingredient disclosure law are forcing reformulation transparency that exceeds federal FDA baselines. Manufacturers must now submit full chemical inventories to state regulators and disclose fragrance components previously protected as trade secrets. Premium and natural-positioned brands are capturing shelf space by preemptively publishing ingredient lists, while mass-market players face compliance cost escalation.
Subscription-based replenishment is displacing traditional retail stocking patterns among urban millennial and Gen Z consumers. Amazon Subscribe & Save and direct brand websites are capturing volume that previously flowed through Walmart and Target supercenters. This channel rotation is most pronounced in coastal metropolitan corridors from Seattle to Boston, where delivery density supports same-day or next-day fulfillment economics.
North America Sanitary Napkin Market Segmentation
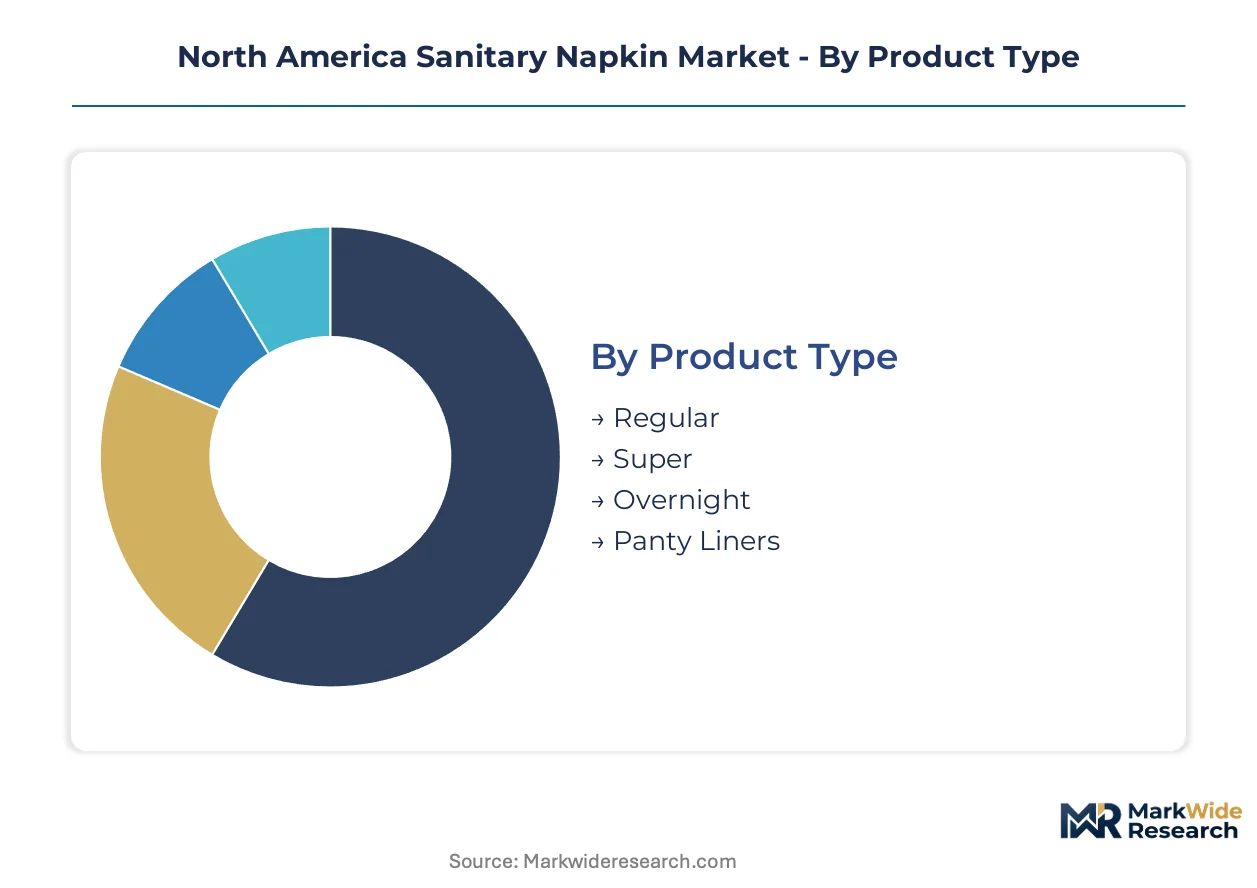
Sanitary napkin segmentation in North America tracks absorbency calibration, material provenance, and channel economics that together determine margin capture. Manufacturers align production capacity against these dimensions to optimize inventory turns and shelf placement.
Product Type:
Absorbency tiering separates usage occasions by flow intensity and duration requirements.
- Regular:Designed for light to moderate flow with standard fluff pulp cores and 240-280mm length specifications. Demand concentrates in suburban and rural markets across the US Midwest and Southeast where price sensitivity exceeds performance premium willingness.
- Super:Higher density absorbent cores accommodate moderate to heavy flow with extended length and widened rear coverage. The segment is rotating up the share rankings in urban corridors along the US East and West Coasts where consumers prioritize leakage protection during active daytime use.
- Overnight:Maximum absorbency variants with 320-360mm length and reinforced side barriers for extended wear. Overnight holds installed capacity due to disproportionate margin pools and lower price elasticity among consumers prioritizing sleep protection.
- Panty Liners:Ultra-thin daily protection products with minimal absorbent capacity for spotting and discharge management. These products capture volume in California and New York markets where daily freshness positioning resonates with professional demographics.
Overnight holds installed capacity. Super is rotating up the share rankings.
Material:
Raw material sourcing is tilting toward plant-based alternatives as state-level mandates compress synthetic component flexibility.
- Cotton:Natural fiber topsheets and absorbent cores derived from cultivated or organic cotton bolls. Demand concentrates in specialty retail channels across Canada where Health Canada organic certification provides premium positioning unmatched by US federal equivalents.
- Rayon:Regenerated cellulose fibers offering softness and fluid wicking properties at intermediate cost points. Rayon is rotating up the share rankings as manufacturers seek petroleum-free alternatives without absorbing full organic cotton price premiums.
- Biodegradable:Compostable materials including corn starch-derived superabsorbent polymers and plant-based backsheet films. These materials are climbing the fastest as California SB 54 plastic reduction mandates accelerate R&D investment and reward early compliance.
- Synthetic:Petroleum-derived polypropylene topsheets, polyethylene backsheets, and acrylic superabsorbent polymers. Synthetic maintains volume in Mexico's price-sensitive mass market where regulatory pressure lags US and Canadian timelines.
Biodegradable is climbing the fastest. Cotton holds installed capacity.
End User:
Customer lifecycle positioning determines brand relationship duration and lifetime value capture.
- Women:Adult consumers aged 18-54 representing the established core demographic with established brand preferences and multi-variant purchasing patterns. This segment anchors volume in metropolitan markets from Seattle to Boston.
- Teens:First-time menstruators aged 10-17 entering the category through school-based health education programs. Teens are expanding most quickly as menstrual health curriculum expansion across US and Canadian schools creates earlier brand relationship initiation.
- Healthcare Facilities:Hospitals, clinics, and long-term care institutions procuring institutional-grade products through group purchasing organizations. Demand concentrates in US urban medical corridors with centralized supply chain infrastructure.
- Retail Customers:Individual purchasers across all demographics buying through mass retail, specialty, and direct-to-consumer channels. This segment fragments across channel types with subscription models capturing structural share in coastal metropolitan corridors.
Women holds installed capacity. Teens is expanding most quickly.
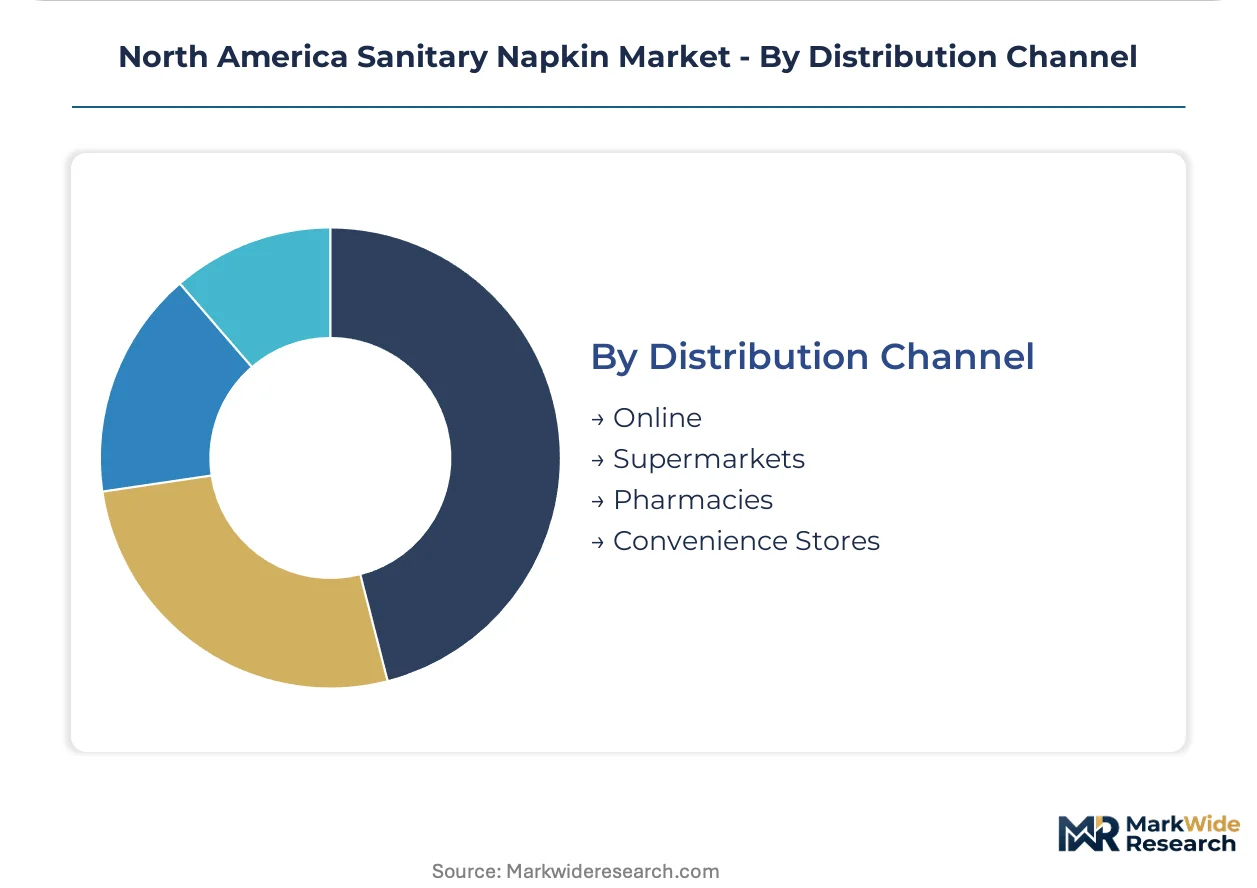
Distribution Channel:
Channel economics are restructuring as subscription commerce displaces traditional retail stocking patterns.
- Online:Direct-to-consumer brand websites and marketplace platforms offering subscription replenishment and discrete delivery. Amazon Subscribe & Save and dedicated brand sites are capturing volume that previously flowed through supercenters in dense urban markets.
- Supermarkets:Mass retail chains including Walmart, Target, and Kroger with broad SKU assortment and promotional pricing. Supermarkets hold installed capacity in suburban and exurban geographies where one-stop shopping convenience dominates.
- Pharmacies:Drugstore chains including CVS, Walgreens, and Rexall with health-and-wellness positioning and pharmacist recommendation access. These channels concentrate in US and Canadian markets with aging demographics seeking clinical validation.
- Convenience Stores:Small-format retailers offering limited assortment emergency purchase occasions at premium unit pricing. Demand localizes in transit corridors and 24-hour service zones across major metropolitan areas.
Supermarkets holds installed capacity. Online is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada exports fluff pulp and specialty fibers to US manufacturing clusters along the East Coast, while Mexico serves as a low-cost production platform for Southwest US distribution. This triangular trade flow concentrates regulatory compliance burdens in the United States while dispersing manufacturing economics across the continent.
United States
Urban corridors from Seattle to Boston drive premium absorbency demand among millennial and Gen Z consumers. The FDA enforces medical device classification for novel absorbent technologies, extending product launch timelines. Manufacturing concentrates in Wisconsin and Georgia, where Kimberly-Clark and Procter & Gamble operate integrated pulp-to-finished-goods facilities.
Canada
Health Canada organic certification creates premium positioning frameworks unmatched by US federal equivalents, attracting natural-ingredient brands. The country's national health regulator applies medical device rigor parallel to FDA standards, harmonizing compliance across the border. Pulp production clusters in British Columbia and Quebec supply raw material to US manufacturers.
Mexico
Price-sensitive mass market demand dominates as regulatory pressure lags US and Canadian timelines. Mexico's national health regulator maintains sanitary standards governing import clearance and domestic licensing. Manufacturing expansion accelerates in Guanajuato and Querétaro states, offering export platforms to the US Southwest and Latin America.
California
SB 54 plastic reduction mandates accelerate biodegradable material R&D investment and reward early compliance with shelf placement advantages. The state's Safer Consumer Products regulations force fragrance component disclosure previously protected as trade secrets. Los Angeles and San Francisco metropolitan areas concentrate subscription commerce adoption among professional demographics.
New York
Menstrual product ingredient disclosure law exceeds federal FDA baselines, requiring full chemical inventory submission to state regulators. New York Metro anchors demand for panty liners and daily freshness positioning among professional women. The Northeast Corridor distribution infrastructure supports rapid fulfillment to Boston and Philadelphia markets.
North America Sanitary Napkin Market Key Industry Players
Channel-controlling players compete with product-specialist players across a consolidated structure where scale advantages dominate mass retail placement. Three to four multinational corporations anchor volume through supermarket and pharmacy networks, while mid-tier specialists capture premium positioning in specialty and direct-to-consumer channels. Strategic archetypes separate into integrated pulp-to-retail manufacturers, natural-ingredient specialists, and subscription-native digital brands. Competitive moves concentrate on portfolio diversification into biodegradable materials and geographic expansion into Mexico manufacturing.
Among integrated manufacturers, Kimberly-Clark Corporation and Procter & Gamble exemplify scale-driven archetypes with captive pulp supply chains and extensive clinical testing protocols. Edgewell Personal Care occupies a specialist position, anchoring natural-ingredient premium positioning in specialty retail channels. These three entities represent distinct competitive vectors: upstream integration, performance validation, and ingredient transparency.
| Leading Market Players |
|---|
| Essity AB |
| Edgewell Personal Care |
| Procter & Gamble |
| Ontex Group |
| Unicharm Corporation |
| Kimberly-Clark Corporation |
| Kao Corporation |
| The Honest Company |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
US Southeast pulp production clusters anchor cost structures for absorbent core materials, concentrating margin capture among manufacturers with captive fluff pulp supply or long-term offtake agreements. Overnight and heavy-flow variants command premium positioning due to performance-critical absorbency requirements, while subscription commerce compresses customer acquisition costs and enables predictable demand forecasting.
Pricing Analysis
Petroleum-derived superabsorbent polymer pricing diverges sharply from emerging bio-based alternatives, creating a three-tier pricing structure across premium, standard, and economy levels. Certification-grade differentiation under FDA medical device tiers and California chemical disclosure compliance drives price spreads, with organic and biodegradable-positioned products capturing shelf premiums. Cost compression in mass-market synthetic tiers intensifies as Asian SAP resin imports face currency volatility. Retail customers in Mexico's price-sensitive mass market exhibit highest price sensitivity; professional demographics in coastal US metros show lowest elasticity for sleep-protection and transparency-positioned products.
Supply Chain Analysis
Extended payment terms from Kimberly-Clark and Procter & Gamble squeeze mid-tier suppliers, accelerating consolidation among specialty chemical providers. Raw material sourcing concentrates in the United States for fluff pulp, Canada for specialty fibers, and China, South Korea, and Japan for superabsorbent polymer resins. Hurricane disruption vulnerability in Georgia and Alabama pulp mills, combined with tariff exposure on Asian petrochemical imports, elevates supply risk. Distribution runs through Walmart and Target supercenters in suburban corridors, with Amazon Subscribe & Save and direct brand sites capturing structural share in dense metropolitan markets from Seattle to Boston.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription commerce infrastructure and state-level chemical disclosure mandates are converting sanitary napkins from transactional retail goods into platform-mediated recurring revenue streams, with interoperability between inventory management and direct-to-consumer fulfillment systems determining competitive survival.
For Market Incumbents: Build captive bio-based material supply chains to defend margin pools against petroleum price volatility and California SB 54 compliance costs. Secure Health Canada organic certification to capture premium positioning unmatched by US federal equivalents, while expanding Guanajuato manufacturing capacity to serve Southwest US and Latin American export demand. For New Entrants and Emerging Players: Establish a beachhead in teen-focused subscription offerings leveraging school-based menstrual health education expansion as customer acquisition channel. Target biodegradable material segments facing 12-16 month BPI certification backlogs with preemptive transparency positioning, deploying direct-to-consumer sampling to bypass entrenched retail slotting fees. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed natural-ingredient specialists holding Health Canada certification and coastal subscription customer bases. Five-to-ten year viability hinges on bio-based absorbent technology maturation and state plastic mandate expansion velocity. Watch FDA 510(k) clearance timelines for novel core technologies as inflection signal for incumbent R&D productivity.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Material Transition | California SB 54 compliance secures shelf placement advantages in mandated jurisdictions. |
| Subscription Commerce Infrastructure | Amazon Subscribe & Save integration reduces customer acquisition costs in dense metros. |
| Health Canada Organic Certification | Federal natural product standards enable premium pricing unmatched by US equivalents. |
| Mexico Manufacturing Expansion | Guanajuato and Querétaro facilities serve US Southwest and Latin American export markets. |
| Teen-Focused Product Development | School-based curriculum expansion creates earlier brand relationship initiation and lifetime value. |
Research Approach
The analysis maps biodegradable material adoption, subscription commerce penetration, and regulatory compliance tiers, each validated through procurement managers at Kimberly-Clark and Procter & Gamble, category buyers at Walmart and Target, supply chain directors at Edgewell Personal Care, and regulatory affairs leads navigating FDA and Health Canada medical device frameworks. Secondary validation drew from FDA 510(k) filings, Health Canada medical device licenses, California Department of Toxic Substances Control chemical inventory submissions, Nielsen retail audit data, and US Census trade statistics. Bottom-up demand modeling triangulated against top-down macroeconomic indicators.
Assumptions held fixed include current FDA medical device classification frameworks, California and New York chemical disclosure enforcement trajectories, and existing tariff structures on Asian petrochemical imports; variables included bio-based SAP technology maturation rates and subscription commerce adoption curves across metropolitan corridors. Segmentation dimensions modeled encompass absorbency tier, material provenance, end-user lifecycle stage, and channel economics. CAGRs derived from trend extrapolation against historical volume trajectories, with pulp pricing volatility and state plastic mandate expansion as primary forecast sensitivity inputs.
Stress conditions across hurricane disruption frequency in US Southeast pulp clusters, currency fluctuation in Asian SAP resin trade, and FDA clearance timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory stability and technology substitution rates. Macroeconomic recession, federal preemption of state chemical disclosure laws, or breakthrough bio-based absorbency performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
United States Sanitary Napkin Market
Medical and Hygiene Textiles
Compressed Towel Market
Medical and Hygiene Textiles
Examination Gloves Market
Medical and Hygiene Textiles
Textile Based Ph Controllers Market
Medical and Hygiene Textiles
Medical Non-Woven Disposables Market
Medical and Hygiene Textiles
Intestinal Wash Bags Market
Medical and Hygiene Textiles
Latin America Sanitary Napkin Market
Medical and Hygiene Textiles
Global Feminine Hygiene Wash Market
Medical and Hygiene Textiles
Antimicrobial Polyamide Textiles Market
Medical and Hygiene Textiles
Period Patch Market
Medical and Hygiene Textiles
Period Panties Market
Medical and Hygiene Textiles
Sleeping Masks Market
Medical and Hygiene Textiles
Global Diabetic Socks Market
Medical and Hygiene Textiles
Medical Textiles Market
Medical and Hygiene Textiles
Textile Implants Market
Medical and Hygiene Textiles
Global Antimicrobial Medical Textiles Market