
 Medical Fabrics Market | 2026-2036
Medical Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Fabrics Market Outlook
ISO 10993 biocompatibility certification is redrawing competitive boundaries in medical textiles, forcing smaller converters to outsource testing or exit higher-risk applications. Kimberly-Clark Corp. leverages its North American hygiene infrastructure to sustain hospital contract renewals across surgical drape portfolios. Freudenberg and Co. KG anchors European supply through in-house non-woven production, while Asahi Kasei Corp. differentiates via specialized spunbond-meltblown composites for barrier applications.
Medical fabrics are engineered textile structures—woven, non-woven, knitted, or coated—designed to meet specific barrier, absorbency, or biocompatibility parameters for patient contact applications, typically incorporating polyester, cotton, or polypropylene substrates with antimicrobial or fluid-resistant finishes. Non-woven fabrics dominate procedural volume due to disposability economics and sterilization compatibility, while coated fabrics command premium positioning in extended-wear wound dressings where moisture vapor transmission rates determine clinical outcomes. Woven cotton retains share in bandage substrates where fiber familiarity and absorbency specifications satisfy traditional procurement criteria.
FDA 510(k) pathways and EU MDR technical documentation requirements govern market access duration and testing expenditure, with ISO 13485 quality management systems now baseline for contract eligibility. The EPA regulates antimicrobial claims on treated fabrics, creating additional validation layers for suppliers seeking differentiated positioning. Stakeholders must monitor evolving biocompatibility testing protocols and regional quality system harmonization to align R&D timelines with procurement qualification cycles.
Market Dynamics
EU MDR clinical evidence requirements and FDA biocompatibility updates are compressing product development timelines while elevating capital barriers for market entry, fundamentally restructuring competitive boundaries around certification capability rather than manufacturing scale alone.
Growth Catalysts
- Surgical procedure volumes:Rising hospital admissions in Germany, the United States, and Japan sustain demand for sterilizable barrier fabrics in operating theaters.
- ISO 10993 certification mandates:Biocompatibility testing requirements are filtering out non-compliant suppliers and consolidating contract eligibility among certified manufacturers.
- Antimicrobial finishing chemistry:Silver-ion and copper-based treatments are expanding addressable applications in wound care and implantable textile scaffolds.
Market Restraints
- Polypropylene feedstock volatility:Crude oil price swings directly compress margins on spunbond-meltblown non-woven production.
- EU MDR technical documentation burden:Extended clinical evaluation timelines delay product launches by 18-36 months for novel fabric constructions.
- Reusable surgical textile substitution:Launderable woven alternatives in cost-constrained healthcare systems threaten single-use non-woven volumes.
Strategic Opportunities
- India's hospital infrastructure expansion:Government health insurance schemes are accelerating surgical capacity build-out in tier-2 and tier-3 cities.
- Smart wound dressing integration:Biosensor-embedded fabrics enabling real-time moisture and pH monitoring are opening premium positioning in chronic care.
- EPA antimicrobial claim pathways:Validated treated textile registrations are creating differentiated product tiers for infection control procurement.
Industry Challenges
- ISO 13485 quality management implementation:Smaller converters face capability gaps in documentation and audit readiness for hospital contract qualification.
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization study queues at accredited laboratories are extending R&D-to-commercialization cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Fabrics Market |
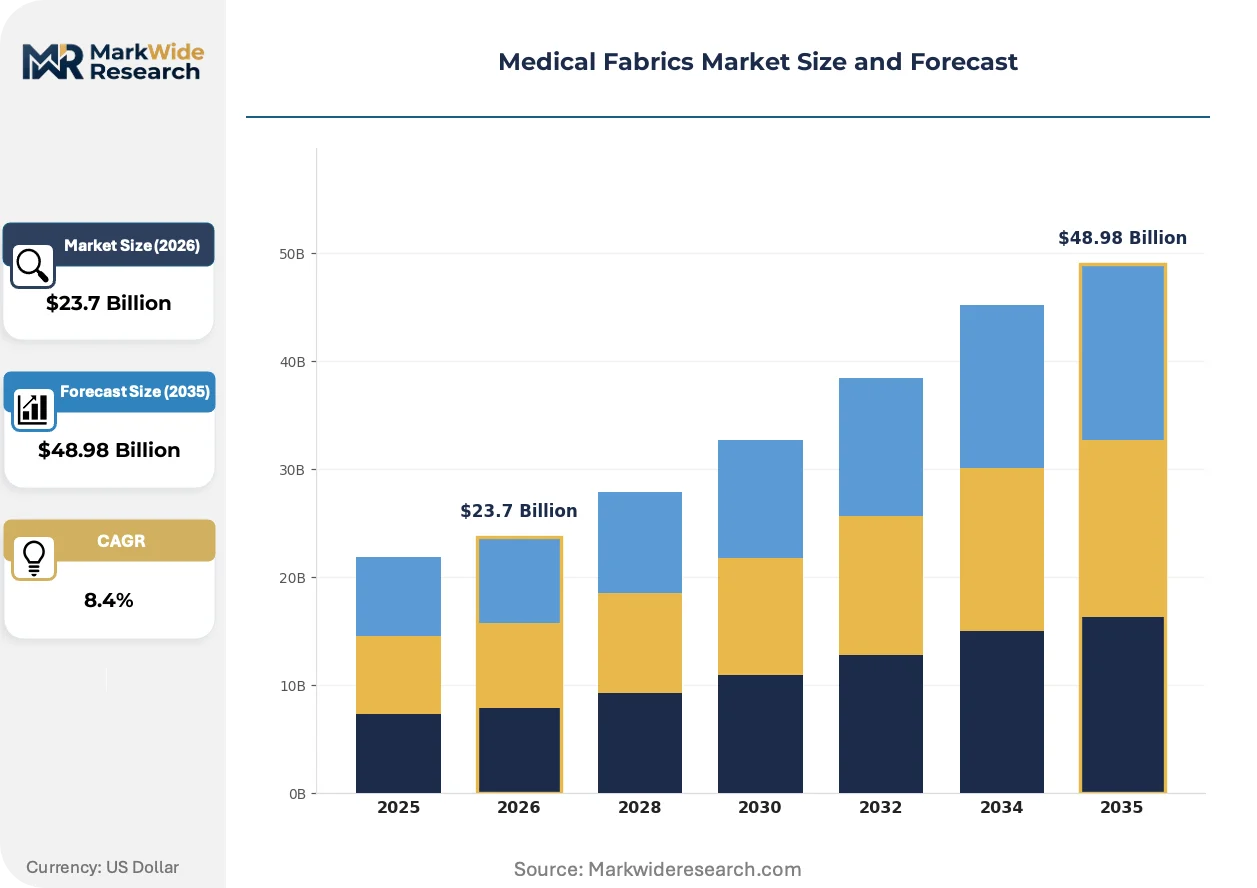
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabrics, Non-Woven Fabrics, Knitted Fabrics, Coated Fabrics Application: Surgical Drapes, Gowns, Bandages, Wound Dressings End User: Hospitals, Clinics, Nursing Homes, Rehabilitation Centers Material: Polyester, Cotton, Nylon, Spandex |
| Companies Covered | 3M Co., Berry Global Inc., Kimberly-Clark Corp., Freudenberg and Co. KG, DuPont de Nemours Inc., Ahlstrom Oyj, Asahi Kasei Corp., ATEX Technologies Inc., Cardinal Health Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Fabrics Market Strategic Shifts
Active material science advances and regulatory harmonization pressures are converging to redefine performance benchmarks across barrier, absorbency, and biocompatibility specifications in patient-contact textiles.
Spunbond-meltblown-spunbond (SMS) composite structures with tuned basis weights are displacing heavier woven alternatives in surgical drape applications. Hospital procurement committees in the United States and Germany are specifying these laminates for their balance of barrier efficiency and disposability economics. The shift is compressing demand for reusable woven cotton in procedural settings where sterilization logistics costs previously favored multi-use models.
REACH restrictions on persistent antimicrobial chemistries are forcing reformulation of silver-based treatments across European supply chains. Manufacturers are accelerating migration to quaternary ammonium compounds and chitosan derivatives to maintain EPA-registered claim validity for US export markets. Wound dressing producers with dual-region certification pipelines are absorbing disproportionate compliance costs relative to single-market competitors.
Consolidated purchasing through group purchasing organizations is compressing supplier negotiation cycles and unbundling technical service from fabric supply contracts. Large hospital networks in Japan and the United States are centralizing specification authority at regional procurement hubs. Smaller surgical centers are losing direct supplier relationships as distribution intermediaries capture value through inventory management and compliance documentation bundling.
Medical Fabrics Market Segmentation
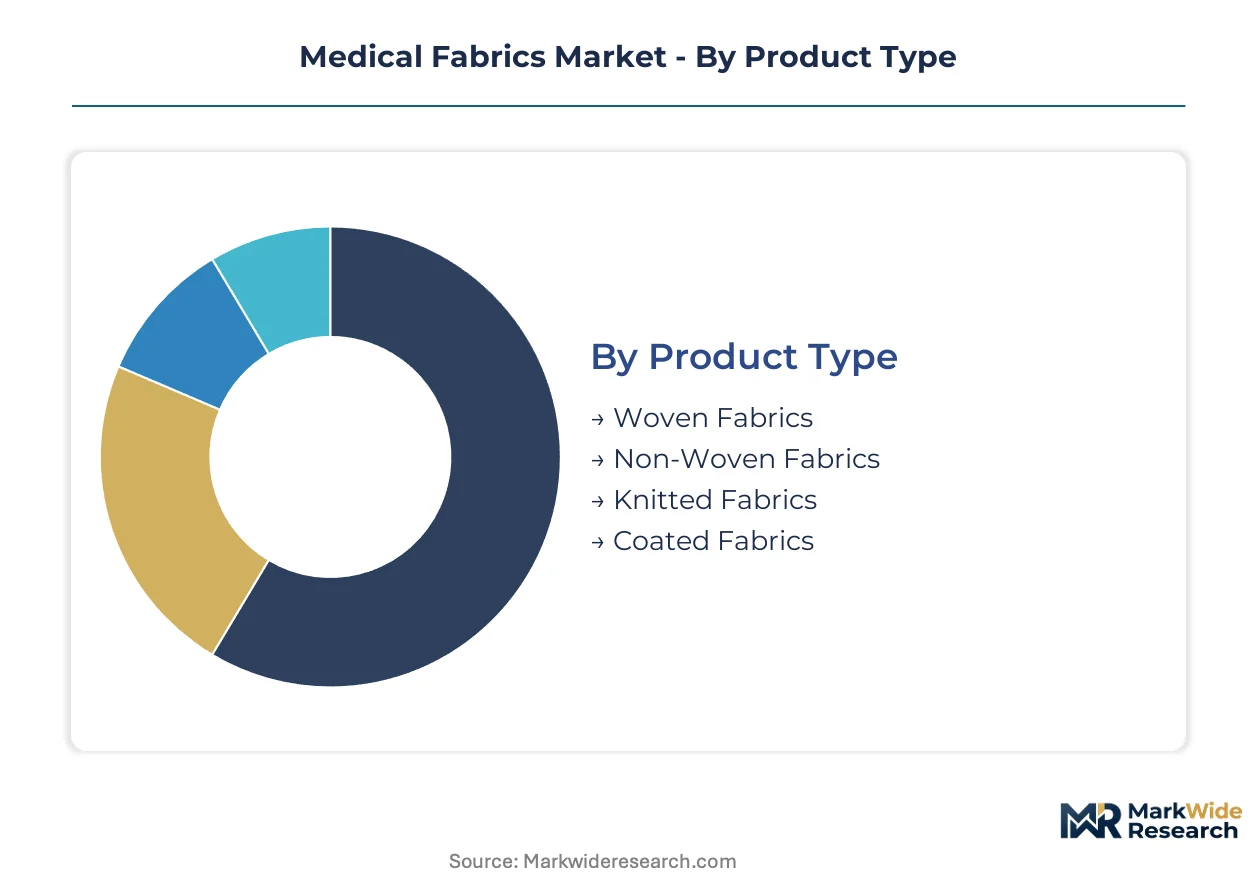
Segmentation in medical fabrics reveals how regulatory pathways, sterilization requirements, and procurement economics fragment demand across material classes and end-use settings. ISO 10993 biocompatibility tiers and FDA 510(k) clearance complexity create divergent margin structures that reshape supplier positioning.
Product Type:
FDA biocompatibility classifications and EU MDR technical documentation burdens stratify competitive entry across fabric construction methods.
- Non-Woven Fabrics:Spunbond-meltblown composites deliver calibrated barrier efficiency against liquid penetration for surgical drapes. Hospital procurement in the United States concentrates demand for single-use disposables that eliminate sterilization logistics. Spunbond-meltblown-spunbond laminates displace woven alternatives in operating theaters where infection control protocols tightened.
- Woven Fabrics:Cotton and polyester interlock structures provide mechanical durability for reusable surgical textiles. Launderable woven gowns retain procurement share in Germany's cost-constrained municipal hospital systems where lifecycle economics favor multi-use models over disposable volumes.
- Knitted Fabrics:Elastic warp-knit constructions enable compression bandages with graduated pressure profiles.
- Coated Fabrics:Polyurethane and silicone membrane laminates control moisture vapor transmission in extended-wear wound dressings.
Established volume favors non-woven fabrics; emerging adoption favors coated fabrics.
Application:
Procedure volume concentration and reimbursement tiers determine specification authority across clinical use cases.
- Surgical Drapes:SMS laminates with fluid-resistant zones isolate sterile fields during invasive procedures. Operating theater throughput in Japanese tertiary hospitals sustains demand for drapes with adhesive fenestration and instrument pouches.
- Wound Dressings:Hydrophilic foam and alginate composites manage exudate in chronic ulcer care. Silver-ion antimicrobial finishing expands addressable applications in diabetic foot clinics where infection risk elevates.
- Gowns:AAMI Level 3 and Level 4 barrier ratings govern isolation gown procurement for contact precaution protocols.
- Bandages:Woven cotton and elastic knit substrates satisfy traditional absorbency specifications in first-aid and post-operative wrapping.
Surgical drapes capture the highest procurement value concentration; wound dressings climb the fastest on chronic disease prevalence.
End User:
Centralized purchasing scale and compliance documentation requirements filter supplier eligibility across care settings.
- Hospitals:Group purchasing organization consolidation in the United States compresses supplier negotiation cycles for surgical drape and gown contracts. Regional procurement hubs unbundle technical service from fabric supply, favoring manufacturers with ISO 13485 quality systems and dedicated hospital contract teams.
- Clinics:Outpatient surgical centers in Germany specify lower-basis-weight non-wovens for minor procedure volumes where barrier requirements moderate.
- Nursing Homes:Pressure ulcer prevention protocols drive demand for low-friction positioning textiles and moisture-wicking underpads.
- Rehabilitation Centers:Compression therapy and orthotic bracing applications specify elastic knitted constructions with calibrated stretch recovery.
Hospital procurement dominates contract value; nursing home demand expands most quickly on aging population care intensity.
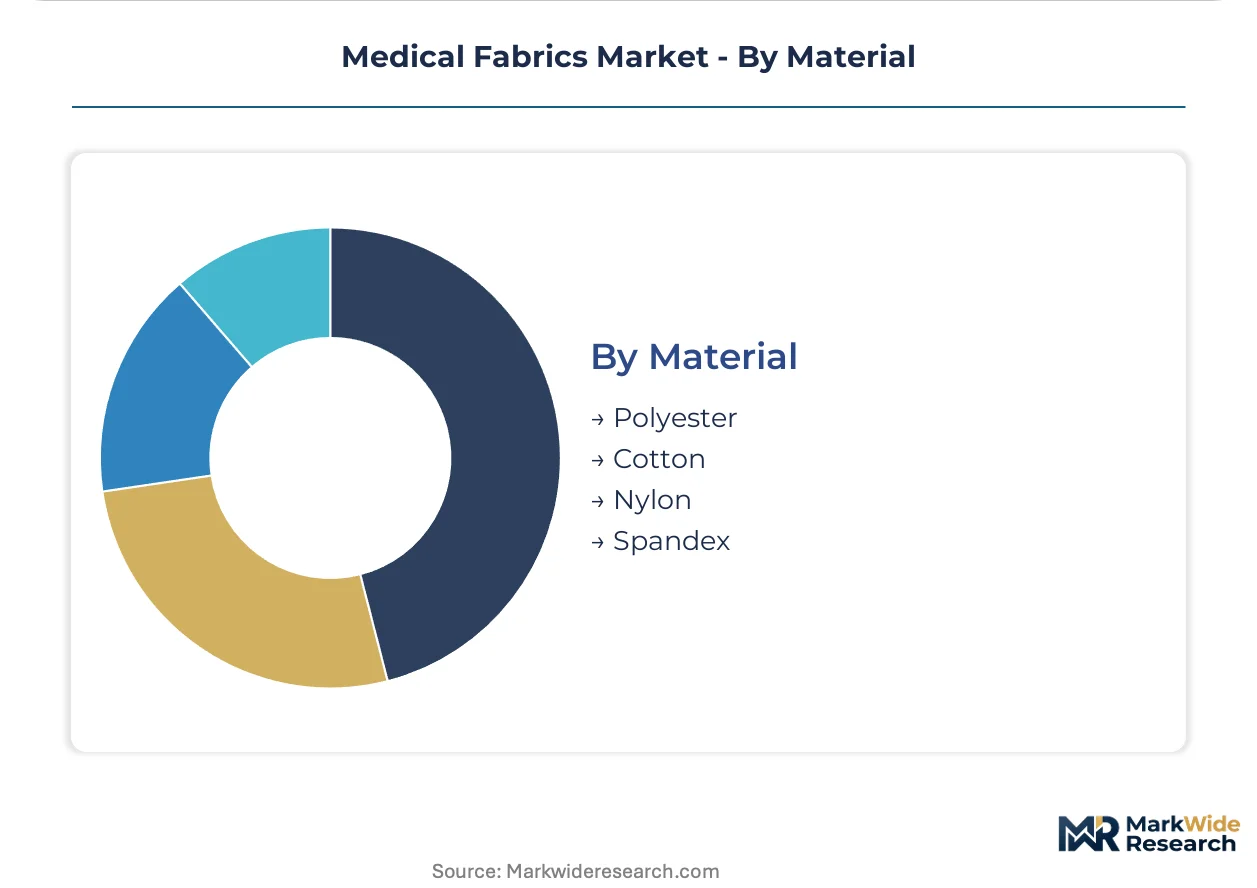
Material:
Feedstock cost volatility and biocompatibility certification compatibility shape material selection in product development pipelines.
- Polypropylene:Spunbond and meltblown non-woven production relies on polymer grades with narrow melt flow index ranges for fiber diameter control. Crude oil price swings directly compress margins on barrier fabric output.
- Cotton:Woven and non-woven cotton substrates satisfy EU REACH compliance for natural fiber claims in wound contact applications. Fiber familiarity in traditional bandage procurement resists full synthetic substitution.
- Polyester:PET spunbond offers dimensional stability in surgical drape laminates where sterilization compatibility matters.
- Spandex:Polyurethane elastic fiber enables compression garment graduated pressure profiles in lymphedema management.
Polypropylene holds the largest procedural volume base; polyester gains share fastest on sterilization durability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan concentrate demand for ISO 13485-certified suppliers, while India's surgical capacity expansion and China's polymer feedstock integration reshape supply-side geography.
United States
Group purchasing organizations centralize surgical drape and gown contracts at regional procurement hubs, compressing supplier negotiation cycles. FDA 510(k) clearance pathways and EPA antimicrobial claim registrations govern product qualification timelines. North Carolina and Tennessee host non-woven production clusters where spunbond-meltblown capacity serves hospital networks across the Southeast and Midwest.
Germany
Municipal hospital systems in Bavaria and North Rhine-Westphalia specify launderable woven textiles where lifecycle economics favor reusable models over disposables. EU MDR technical documentation requirements and REACH antimicrobial chemistry restrictions filter supplier eligibility. Freudenberg anchors European supply through in-house non-woven production headquartered in Weinheim.
Japan
Tertiary hospitals in Tokyo and Osaka sustain demand for SMS laminates with instrument pouches and adhesive fenestration. PMDA quality system requirements and METI industrial standards shape import qualification protocols. The Kansai region concentrates wound dressing manufacturing where silver-ion antimicrobial finishing expands diabetic foot clinic applications.
India
Government health insurance schemes accelerate surgical capacity build-out in tier-2 and tier-3 cities across Maharashtra and Gujarat. CDSCO medical device registration pathways and BIS textile standards create dual compliance layers for domestic and export markets. Tamil Nadu's medical textile cluster near Coimbatore supplies non-woven surgical drapes to Southeast Asian markets.
China
Polypropylene feedstock integration in Shandong and Jiangsu provinces supports spunbond-meltblown capacity serving domestic hospital procurement. NMPA medical device registration and GB standards biocompatibility testing requirements extend product launch timelines. The Yangtze River Delta concentrates coated fabric production for moisture-vapor-transmission wound dressings.
Medical Fabrics Market Competitive Environment
Player mix skews toward diversified hygiene conglomerates and specialized non-woven converters, with tiered competitive boundaries drawn around ISO 10993 certification capability rather than manufacturing scale alone. Market structure concentrates contract eligibility among manufacturers with dedicated hospital qualification teams and in-house biocompatibility testing infrastructure. Three archetypes dominate: integrated polymer-to-fabric producers, regional contract converters, and hygiene multinationals leveraging cross-category procurement relationships. Competitive moves center on backward integration into polymer feedstock and strategic partnerships with accredited testing laboratories.
Within the hygiene multinational tier, Kimberly-Clark Corp. and 3M Co. occupy positions anchored by North American hospital contract renewal infrastructure. Among specialized non-woven producers, Freudenberg and Co. KG exemplifies European supply consolidation through captive manufacturing, while Asahi Kasei Corp. represents Japanese differentiation via composite barrier technologies. These three companies illustrate how geographic origin and corporate structure correlate with divergent certification pipeline strategies.
| Leading Market Players |
|---|
| 3M Co. |
| Berry Global Inc. |
| Kimberly-Clark Corp. |
| Freudenberg and Co. KG |
| DuPont de Nemours Inc. |
| Ahlstrom Oyj |
| Asahi Kasei Corp. |
| ATEX Technologies Inc. |
| Cardinal Health Inc. |
| Others |
Value Chain & Pricing Dynamics
ISO 10993 biocompatibility certification gates both supplier qualification and price stratification in medical fabrics, creating parallel barriers where certified manufacturers command contract premiums while uncertified converters absorb disproportionate testing costs or exit higher-margin applications entirely.
Pricing Analysis
Cost-plus contracts with polypropylene feedstock indexation dominate hospital supply agreements for spunbond-meltblown non-wovens. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified suppliers with in-house testing from regional converters outsourcing biocompatibility validation. Pricing pressure stems from group purchasing organization consolidation unbundling technical service from fabric supply. Tier-2 surgical centers exhibit highest price sensitivity; Japanese tertiary hospitals with adhesive fenestration specifications show lowest.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for polypropylene resin shipments to non-woven converters in Germany and the United States. Supply concentrates in China, Germany, and the United States, with Shandong province hosting integrated spunbond-meltblown capacity and Weinheim anchoring European output. Raw material dependencies center on propylene monomer, silver-ion antimicrobial chemistries, and spunbond production equipment. Single-source vulnerability in accredited ISO 10993 testing laboratories extends R&D-to-commercialization cycles. Distribution runs through group purchasing organization regional hubs consolidating hospital procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical fabrics present a service-attach opportunity where compliance documentation and sterilization logistics contracts expand faster than commodity fabric supply, as hospital procurement committees unbundle technical service from material procurement.
For Market Incumbents: Shield contract renewal rates by embedding ISO 13485 quality system auditors directly within hospital supply chain teams, while accelerating backward integration into polypropylene feedstock to offset crude oil price volatility compressing spunbond-meltblown margins. For New Entrants and Emerging Players: FDA 510(k) third-party review fast-tracks offer accelerated pathways for barrier fabric entrants targeting India's tier-2 and tier-3 surgical capacity build-out under government health insurance schemes, with CDSCO dual-registration creating export qualification leverage. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified hygiene conglomerates where medical fabric divisions lack dedicated hospital contract teams and absorb disproportionate compliance costs relative to core consumer hygiene revenue pools; watch for biocompatibility testing laboratory acquisition activity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Testing Laboratory Acquisition | In-house biocompatibility infrastructure compresses R&D-to-commercialization cycles and secures contract eligibility. |
| Hospital System Partnership | Direct relationships with GPO regional hubs unbundle technical service from commodity fabric supply. |
| Backward Integration into Polypropylene Feedstock | Captive resin supply insulates spunbond-meltblown margins from crude oil price volatility. |
| Smart Wound Dressing Platform Development | Biosensor-embedded fabrics enable premium positioning in chronic care with real-time monitoring. |
| Dual-Region Certification Pipeline Investment | Parallel FDA and EU MDR pathways absorb disproportionate compliance costs relative to single-market competitors. |
Study Parameters
Two parallel data streams informed the analysis: structured interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and non-woven technical directors; and secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contracts, and polymer trade flow records. Bottom-up and top-down triangulation reconciled fabric volume estimates with surgical procedure throughput data.
Across the analysis window, forecasts modeled product type segmentation by construction method, application by clinical use case, end user by care setting, and material by polymer chemistry. CAGRs derived from regression analysis against surgical admission trends, sterilization protocol adoption curves, and antimicrobial finishing penetration rates. Propylene monomer price indices and ISO 10993 testing queue lengths served as key volatility inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained hospital infection control tightening and stable polypropylene feedstock availability; material deviation in regulatory harmonization timelines or crude oil price shocks would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Global Feminine Hygiene Wash Market
Medical and Hygiene Textiles
Textile Based Ph Controllers Market
Medical and Hygiene Textiles
Washable and Reusable Mask Market
Medical and Hygiene Textiles
Global Surgical Drapes and Gowns Market
Medical and Hygiene Textiles
Compressed Towel Market
Medical and Hygiene Textiles
GCC Sanitary Napkin Market
Medical and Hygiene Textiles
Feminine Wipes Market
Medical and Hygiene Textiles
Pant Type Adult Diaper Market
Medical and Hygiene Textiles
Europe Sanitary Napkin Market
Medical and Hygiene Textiles
Antibacterial Washcloth Market
Medical and Hygiene Textiles
Global Healthcare Fabrics Market
Medical and Hygiene Textiles
Antimicrobial Polyamide Textiles Market
Medical and Hygiene Textiles
Global Maternity Support Product Market
Medical and Hygiene Textiles
Global Diabetic Socks Market
Medical and Hygiene Textiles
Arm Pouches Market
Medical and Hygiene Textiles
Medical Non-Woven Disposables Market