
 Breast Pads Market | 2026-2036
Breast Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Breast Pads Market Intelligence
The capital-intensity divergence between automated spunlace production lines and manual assembly operations is redrawing competitive boundaries in breast pad manufacturing. Medela leverages its clinical-grade certification infrastructure to command premium placement in hospital discharge kits across North America and Europe. Lansinoh Laboratories anchors its position through proprietary absorbent polymer formulations that sustain higher fluid-lock thresholds than standard cellulose alternatives. Pigeon Corporation dominates Japanese pharmacy and maternity retail channels through integrated distribution controls that extend from factory floor to point-of-sale.
Breast pads are absorbent, skin-contact hygiene products engineered with superabsorbent polymer cores, breathable polyethylene backsheet laminates, and hypoallergenic top layers to capture lactation leakage and maintain epidermal integrity. Manufacturing employs thermal bonding or needle-punch nonwoven processes to achieve 80–200 gram-per-square-meter basis weights with moisture vapor transmission rates exceeding 2,000 grams per square meter per day. Disposable pads currently occupy the largest revenue pool due to convenience-driven purchasing among new mothers, while washable and organic cotton variants are expanding fastest as sustainability preferences reshape procurement in European and North American online retail channels. The form dimension shows contoured and adhesive designs capturing disproportionate margin share by addressing fit stability and garment compatibility concerns that flat configurations fail to resolve.
The US FDA regulates breast pads as Class I medical devices under 21 CFR 880.5440, requiring biocompatibility testing and quality system compliance that elevates barriers for unvalidated entrants. The EU MDR and REACH frameworks impose substance restrictions and clinical evaluation obligations that reshape formulation choices for European market access. India's CDSCO and BIS standards govern domestic manufacturing quality, while China's NMPA registration requirements control import pathways. Stakeholders must monitor evolving extended producer responsibility mandates and polymer disclosure rules that will determine which material platforms retain commercial viability across jurisdictions.
Market Dynamics
The EU's Single-Use Plastics Directive is forcing material platform migrations across absorbent hygiene manufacturing, compressing lead times for biodegradable polymer validation while expanding compliance costs for cellulose-dependent producers.
Growth Catalysts
- Postpartum Clinic Expansion:Maternity discharge kit standardization in Germany, Japan, and Brazil is pulling clinical-grade breast pads into institutional procurement channels with multi-year supply agreements.
- REACH Substance Restrictions:European chemical disclosure mandates are accelerating superabsorbent polymer reformulations toward bio-based alternatives that qualify for green public procurement preferences.
- Spunlace Automation:Thermal bonding line investments are compressing unit economics for 80-120 GSM breathable laminates, enabling price parity with conventional airlaid constructions in pharmacy retail.
Market Restraints
- Petrochemical Input Volatility:Polyethylene backsheet and SAP feedstock costs fluctuate with naphtha cracking margins, squeezing gross margins for non-integrated converters.
- East Asian Supply Concentration:Needle-punch nonwoven capacity clusters in Zhejiang and Jiangsu provinces, creating single-source vulnerability for European and North American brand owners.
- Biodegradation Performance Gap:PLA and PHA alternatives currently achieve 60-70% of conventional SAP fluid-lock capacity, limiting clinical acceptance in heavy-leakage segments.
Strategic Opportunities
- Tier-2 Indian Hospital Networks:Underpenetrated maternity wards in Pune, Hyderabad, and Ahmedabad present white-space expansion for disposable pad distributors with cold-chain logistics capabilities.
- Reusable Cotton Subscription Models:Direct-to-consumer channels are capturing sustainability-motivated buyers in Scandinavian and Benelux markets with wash-count guarantees and take-back programs.
- Extended Producer Responsibility Mandates:France's AGEC law and forthcoming German packaging regulations create compliance-service revenue streams for manufacturers offering end-of-life collection infrastructure.
Industry Challenges
- Biocompatibility Testing Bottlenecks:FDA 510(k) and EU MDR cytotoxicity validation timelines extend 14-22 months, delaying product line extensions for mid-tier manufacturers without established QSR infrastructure.
- Multi-Jurisdiction Polymer Disclosure:Divergent state-level chemical registries in the US, combined with SCIP database obligations in Europe, fragment formulation standardization and inflate regulatory affairs headcount.
- Legacy ERP Integration:Batch-level traceability requirements for medical device classification force costly MES upgrades for manual assembly operations seeking hospital supply chain entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast Pads Market |
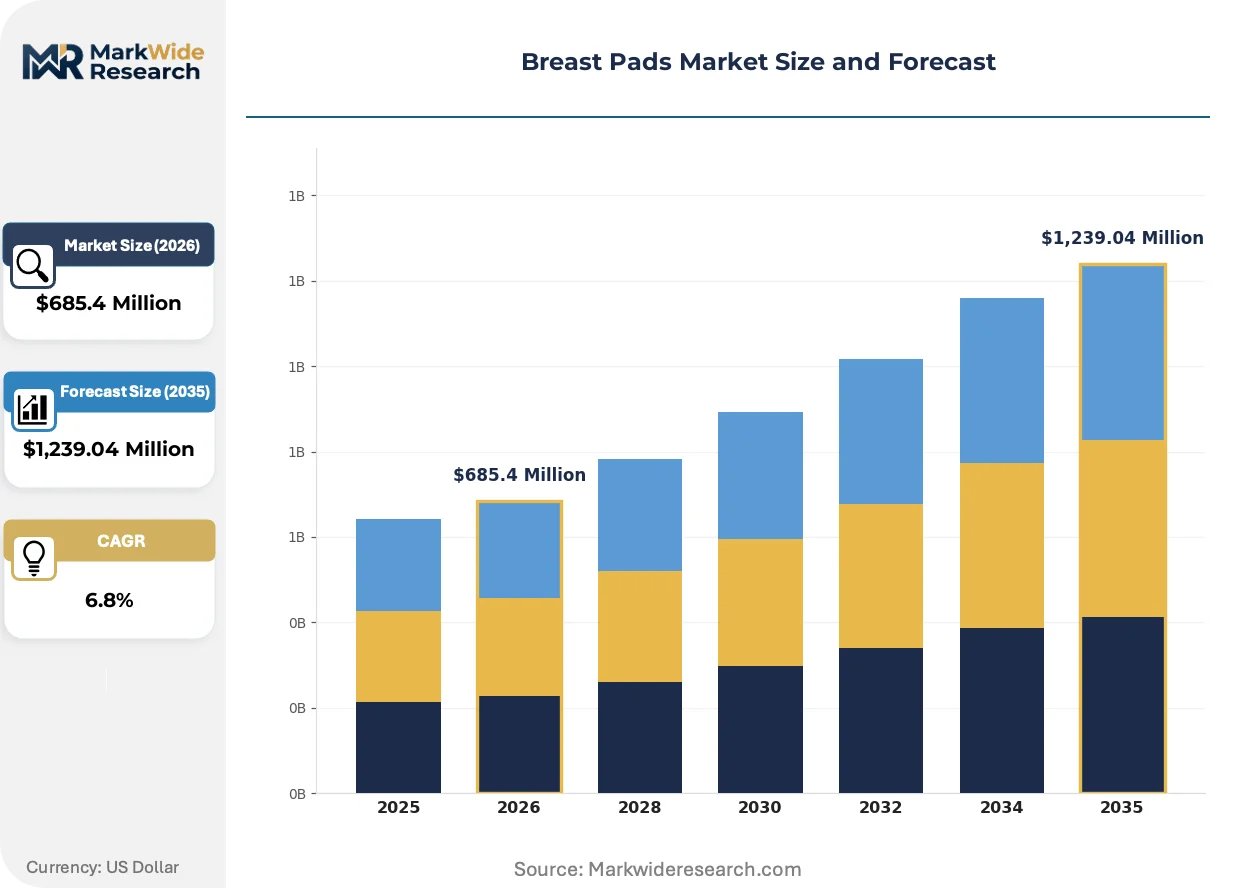
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Pads, Washable Pads, Organic Cotton Pads, Silicone Pads Form: Flat, Contoured, Adhesive, Non-Adhesive Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores Customer Type: Expectant Mothers, New Mothers, Caregivers, Health Enthusiasts |
| Companies Covered | Medela, Cardinal Health, Lansinoh Laboratories, Pigeon Corporation, Johnson & Johnson, Koninklijke Philips, Ameda, LilyPadz, Bamboobies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast Pads Market Strategic Shifts & Innovations
Material science advances and channel restructuring are compressing product lifecycles while elevating performance thresholds for epidermal safety and environmental compliance.
Plant-derived superabsorbent polymers derived from wheat straw and corn starch are bifurcating the raw material supply base. Premium maternity retailers in Germany and the Netherlands are specifying bio-based SAP cores for private-label lines. This material transition is compressing conventional petroleum-based polymer margins while creating certification premiums for validated sustainable sourcing.
REACH Annex XVII restrictions on microplastic release are reshaping formulation choices for European market access. Manufacturers must now demonstrate biodegradation rates exceeding 90% within 180 days for products claiming environmental compatibility. Disposable pad categories with conventional polyethylene backsheet laminates face reformulation pressure, while breathable film alternatives with moisture vapor transmission above 2,500 g/m²/day capture disproportionate shelf placement in French and German pharmacy chains.
Hospital procurement consolidation is compressing vendor panels and elevating clinical evidence requirements for discharge kit inclusion. Integrated health systems in the US and NHS Trusts in England are unbundling absorbent hygiene from broader maternity supply contracts, enabling direct manufacturer relationships that bypass traditional distribution intermediaries. This channel restructuring concentrates volume with suppliers holding ISO 13485 certification and documented dermatological safety profiles, most visible in California's Kaiser Permanente network and Greater Manchester maternity services.
Breast Pads Market Segmentation
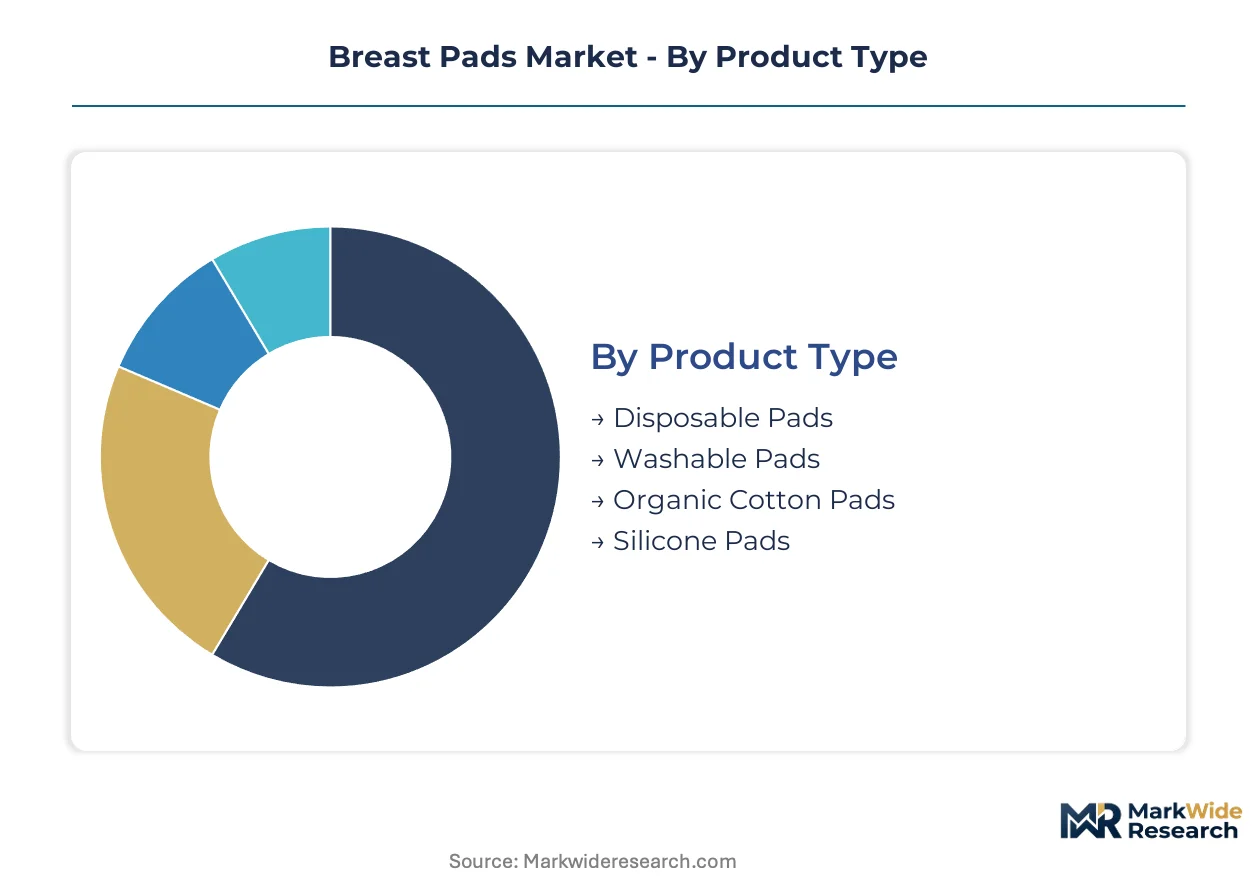
Segmentation in breast pads determines both manufacturing configuration and channel economics. Material platforms dictate regulatory pathway complexity, while form factors govern margin capture through fit differentiation.
Product Type:
Margin pools concentrate in premium absorbency tiers and sustainability-certified lines that command pharmacy placement premiums.
- Disposable Pads:Spunlace thermal-bonded laminates with superabsorbent polymer cores dominate hospital discharge kit procurement across Germany, Japan, and Brazil. Institutional standardization pulls volume through multi-year supply agreements with postpartum care networks.
- Washable Pads:Organic cotton terrycloth and bamboo fiber constructions with 150+ wash-cycle durability are expanding fastest in Scandinavian direct-to-consumer channels. Subscription models with take-back programs capture sustainability-motivated buyers in Benelux markets.
- Organic Cotton Pads:GOTS-certified unbleached cotton with natural latex waterproofing meets EU Green Deal procurement preferences.
- Silicone Pads:Medical-grade platinum-cured silicone with integrated collection chambers targets heavy-leakage clinical segments.
Disposable Pads holds installed capacity. Washable Pads is rotating up the share rankings.
Form:
Volume concentrates in contoured configurations that solve garment compatibility failures of legacy flat designs.
- Contoured:3D-molded nonwoven shells with anatomical curvature and elasticized edges achieve superior fit stability under structured nursing bras. German and French pharmacy chains specify contoured geometries for premium private-label placement.
- Adhesive:Medical-grade silicone adhesive strips with repositionable backing enable secure attachment to skin or fabric without bra dependency. This configuration captures disproportionate margin in summer-weight clothing segments where braless wear increases.
- Flat:Simple rectangular cellulose pads with polyethylene backing serve economy-tier supermarket distribution.
- Non-Adhesive:Slip-in designs relying on bra compression for retention dominate price-sensitive emerging market retail.
Contoured holds installed capacity. Adhesive is rotating up the share rankings.
Distribution Channel:
Customer acquisition costs diverge sharply between clinical procurement and direct-to-consumer fulfillment infrastructure.
- Pharmacies:B2B institutional sales through maternity discharge kit integration require ISO 13485 certification and documented dermatological safety profiles. Kaiser Permanente and NHS Greater Manchester unbundle absorbent hygiene from broader supply contracts, enabling direct manufacturer relationships.
- Online Retail:Subscription-based reusable pad models with wash-count guarantees capture sustainability-motivated buyers in Scandinavian markets. Platform algorithms favor products with biodegradable certification badges.
- Supermarkets:Mass-market disposable pads compete on shelf placement fees and promotional slotting.
- Specialty Stores:Premium maternity boutiques curate organic and silicone variants for high-leakage clinical segments.
Pharmacies holds installed capacity. Online Retail is rotating up the share rankings.
Customer Type:
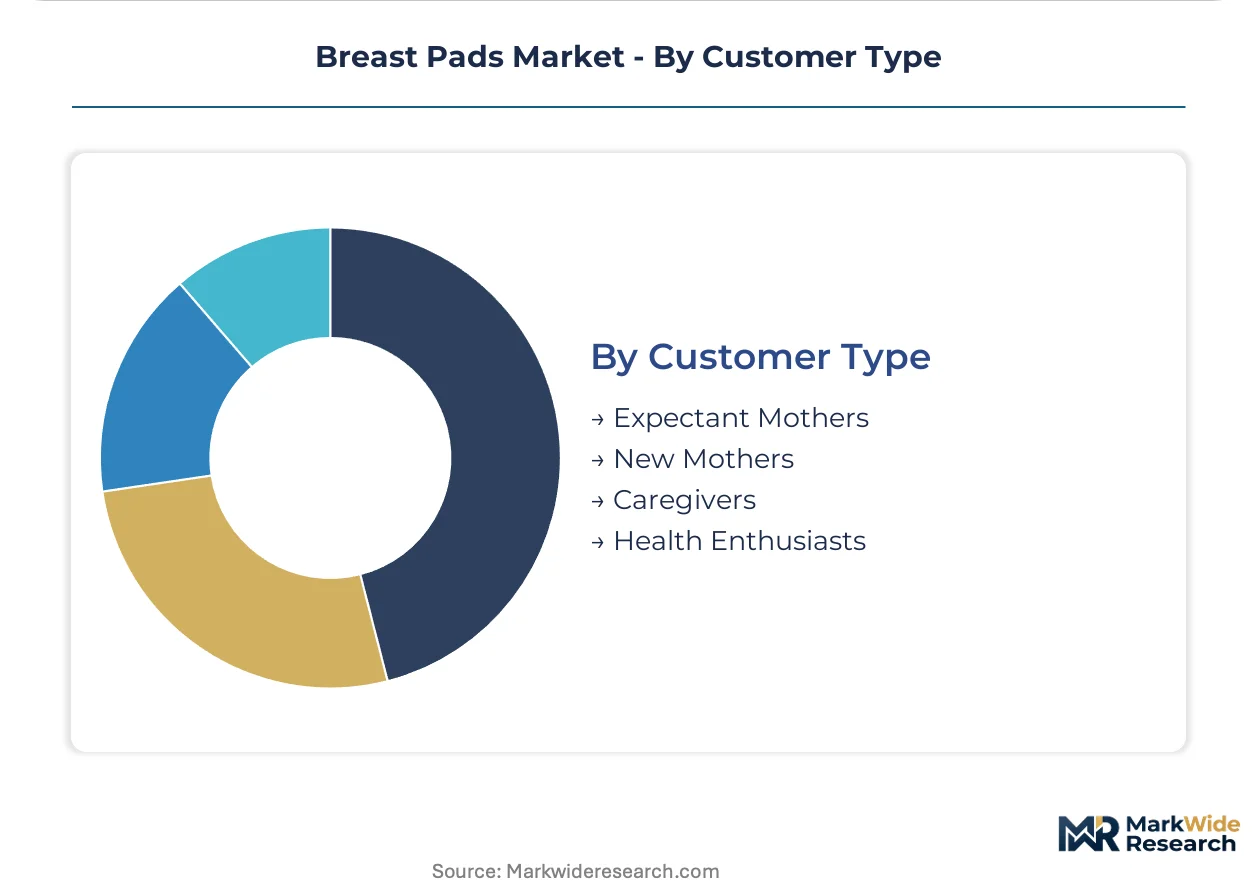
Purchase frequency and price elasticity vary dramatically across the postpartum timeline and caregiver involvement.
- New Mothers:Peak absorbency demand in weeks 2-6 postpartum drives 3-4 pad daily consumption rates. India's tier-1 maternity hospital networks in Pune, Hyderabad, and Ahmedabad present white-space expansion for cold-chain distributors.
- Expectant Mothers:Third-trimester colostrum leakage creates pre-birth category entry with trial-size disposable formats. Hospital pre-registration gift bags in Japan and Brazil standardize clinical-grade pad inclusion.
- Caregivers:Institutional purchasing for neonatal intensive care and lactation consulting practices values bulk packaging and hypoallergenic certification.
- Health Enthusiasts:Wellness-focused buyers seeking chemical-free alternatives drive organic cotton and bamboo fiber demand.
New Mothers holds installed capacity. Expectant Mothers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmacy chains command 35-40% pricing premiums over Brazilian retail channels for identical absorbent hygiene SKUs, reflecting divergent regulatory compliance burdens and procurement standardization levels. This asymmetry redistributes manufacturing investment toward EU-certified production lines while compressing margins in price-sensitive emerging markets.
United States
Hospital discharge kit standardization by Kaiser Permanente and other integrated health systems pulls clinical-grade breast pads into institutional procurement with multi-year supply agreements. FDA Class I medical device classification under 21 CFR 880.5440 mandates biocompatibility testing and quality system compliance that elevates barriers for unvalidated entrants. California's Kaiser Permanente network and Greater Manchester maternity services unbundle absorbent hygiene from broader supply contracts, enabling direct manufacturer relationships.
Germany
Postpartum care clinic expansion across Bavaria and North Rhine-Westphalia drives institutional procurement of absorbent hygiene products through standardized discharge protocols. EU MDR and REACH frameworks impose substance restrictions and clinical evaluation obligations that reshape formulation choices for European market access. Frankfurt and Munich pharmacy chains specify contoured geometries and bio-based SAP cores for premium private-label placement, compressing conventional petroleum-based polymer margins.
Japan
Pigeon Corporation's integrated distribution controls extend from factory floor to point-of-sale across Kanto and Kansai maternity retail channels. METI standards and PMDA registration requirements govern domestic manufacturing quality and import pathways. Tokyo and Osaka hospital pre-registration gift bags standardize clinical-grade pad inclusion, creating third-trimester category entry for expectant mothers.
India
Tier-1 maternity hospital networks in Pune, Hyderabad, and Ahmedabad present white-space expansion for disposable pad distributors with cold-chain logistics capabilities. CDSCO and BIS standards govern domestic manufacturing quality, while state-level procurement preferences favor local production. Maharashtra and Telangana urban pharmacy chains concentrate demand visibility for absorbent hygiene products.
Brazil
Postpartum care clinic expansion pulls clinical-grade breast pads into institutional procurement channels with multi-year supply agreements. ANVISA registration requirements control import pathways and elevate barriers for unvalidated entrants. São Paulo and Rio de Janeiro maternity discharge kit standardization drives volume concentration for hospital-grade absorbent hygiene products.
Breast Pads Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the breast pads market, with clinical-grade certification infrastructure separating premium positioning from commodity production. The vendor base organizes into three tiers: multinational hygiene conglomerates with medical device divisions, specialized maternal care brands with proprietary absorbent formulations, and regional converters serving price-sensitive retail channels. Strategic moves concentrate on M&A to capture ISO 13485-certified manufacturing assets and capacity expansion in spunlace thermal-bonding lines to achieve pharmacy retail price parity.
Within the clinical-certification tier, Medela leverages its established quality system infrastructure to anchor premium placement in North American and European hospital discharge kits. Lansinoh Laboratories exemplifies the specialized formulation archetype through proprietary absorbent polymer positioning. Pigeon Corporation represents integrated distribution control, extending factory-to-shelf coordination across Japanese pharmacy and maternity retail channels.
| Leading Market Players |
|---|
| Medela |
| Cardinal Health |
| Lansinoh Laboratories |
| Pigeon Corporation |
| Johnson & Johnson |
| Koninklijke Philips |
| Ameda |
| LilyPadz |
| Bamboobies |
| Others |
Cost & Logistics Intelligence
FDA Class I medical device classification under 21 CFR 880.5440 gates both supply qualification and price differentiation simultaneously, elevating ISO 13485-certified producers into premium hospital discharge kit procurement while relegating uncertified converters to supermarket price tiers. This regulatory threshold compresses margin pools at the economy end while sustaining 35-40% pharmacy premiums in Germany over Brazilian retail for identical SKUs.
Pricing Analysis
The customization-premium spread between clinical-grade contoured pads and flat economy configurations reaches substantial multiples in pharmacy channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and absorbency performance, with FDA-cleared spunlace laminates commanding institutional premiums. Cost compression in conventional cellulose pads is intensifying because petrochemical input volatility squeezes non-integrated converters. Supermarket buyers exhibit highest price sensitivity; hospital purchasing committees demonstrate lowest elasticity due to discharge kit standardization mandates.
Supply Chain Analysis
China anchors needle-punch nonwoven capacity across Zhejiang and Jiangsu provinces, feeding superabsorbent polymer cores and breathable polyethylene backsheet laminates to global brand owners. Manufacturing draws from petroleum-based SAP feedstocks, spunlace thermal-bonding equipment, and medical-grade adhesive formulations. Single-source vulnerability concentrates in East Asian needle-punch capacity, exposing European and North American distributors to logistics chokepoint risk. Distribution runs through integrated health system procurement offices, pharmacy chain category managers, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 13485 certification infrastructure represents the critical scarcity asset, separating hospital-grade suppliers from commodity converters and determining long-term positioning in institutional procurement channels.
For Market Incumbents: Fortify quality system infrastructure against emerging bio-based SAP specialists by accelerating backward integration into spunlace thermal-bonding capacity in EU-certified production lines. Deepen channel control through direct manufacturer relationships with Kaiser Permanente and NHS Trusts that are unbundling absorbent hygiene from broader maternity supply contracts. For New Entrants and Emerging Players: Lead with tier-2 Indian hospital networks in Pune, Hyderabad, and Ahmedabad where cold-chain logistics capabilities remain underdeveloped and procurement standardization is nascent. Capture white-space through GOTS-certified organic cotton subscription models with take-back programs targeting Scandinavian sustainability-motivated buyers. For Investors and Strategic Acquirers: EU MDR implementation reshapes the acquisition landscape toward ISO 13485-certified manufacturing assets with documented dermatological safety profiles. Long-term viability centers on suppliers capable of navigating REACH Annex XVII microplastic restrictions and biodegradable polymer validation timelines. Watch for extended producer responsibility mandate expansion beyond France's AGEC law into German packaging regulations as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Unlocks Kaiser Permanente and NHS Trust direct procurement relationships bypassing distribution intermediaries. |
| Backward Integration into Spunlace Capacity | Captures pharmacy retail price parity by compressing unit economics for 80-120 GSM breathable laminates. |
| Bio-Based SAP Core Development | Qualifies for EU Green Deal public procurement preferences as REACH substance restrictions tighten. |
| Reusable Pad Subscription Launch | Captures sustainability-motivated buyers in Benelux markets with wash-count guarantees and take-back infrastructure. |
| Tier-2 India Distribution Expansion | Establishes cold-chain logistics presence in underpenetrated Maharashtra and Telangana maternity wards. |
Research Approach
A standing panel of hospital purchasing committee members, pharmacy category managers, absorbent hygiene procurement leads, and lactation consulting practice administrators provided ongoing calibration across primary interview programs. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation, CDSCO registration databases, and hospital procurement contract disclosures. Bottom-up volume modeling triangulated against top-down spending pattern analysis across the projection horizon.
Consistency checks validated outputs against external benchmarks including customs trade data for spunlace nonwoven imports, GPO contract award announcements, and retail audit data from Nielsen and Circana. Segmentation dimensions spanned product type, form factor, distribution channel, and customer lifecycle stage, with CAGRs derived from regression analysis of historical volume trajectories and elasticity-adjusted price evolution. Industry-specific inputs incorporated SAP feedstock cost indices and certification timeline distributions.
Forecasts assume regulatory continuity in FDA 510(k), EU MDR, and CDSCO regimes; material policy shifts would require re-modeling. Specific risks include REACH Annex XVII expansion, extended producer responsibility mandate acceleration, and biodegradable polymer performance gap persistence in heavy-leakage clinical segments. Recalibration cycles align with material shifts in hospital procurement consolidation patterns and sustainability certification adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Global Diabetic Socks Market
Medical and Hygiene Textiles
GCC Sanitary Napkin Market
Medical and Hygiene Textiles
Medical Smart Textile Market
Medical and Hygiene Textiles
Sleeping Masks Market
Medical and Hygiene Textiles
Global Maternity Support Product Market
Medical and Hygiene Textiles
Medical Non-Woven Disposables Market
Medical and Hygiene Textiles
Sanitary Napkin Market
Medical and Hygiene Textiles
Global Antimicrobial Medical Textiles Market
Medical and Hygiene Textiles
Textile Implants Market
Medical and Hygiene Textiles
Global Healthcare Fabrics Market
Medical and Hygiene Textiles
Antibacterial Washcloth Market
Medical and Hygiene Textiles
Tissue Towel Market
Medical and Hygiene Textiles
United States Sanitary Napkin Market
Medical and Hygiene Textiles
Global Biomedical Textiles Market
Medical and Hygiene Textiles
Arm Pouches Market
Medical and Hygiene Textiles
Global Surgical Drapes and Gowns Market