
 Global Surgical Drapes and Gowns Market | 2026-2036
Global Surgical Drapes and Gowns Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Drapes and Gowns Market Outlook
Asset-light leasing models for sterile processing equipment are narrowing the capital barrier for mid-sized distributors entering the surgical drapes and gowns space. Cardinal Health leverages its nationwide logistics network to sustain hospital contract renewals. Medline Industries anchors private-label volume through direct sales teams embedded in integrated delivery networks. 3M differentiates via proprietary repellent technologies in its disposable gown portfolio.
Surgical drapes and gowns are sterile textile barriers engineered from spunbond-meltblown-spunbond (SMS) laminates or reinforced polypropylene, designed to maintain aseptic fields by resisting fluid penetration and bacterial transmission during invasive procedures. Disposable gowns dominate volume in ambulatory settings where turnover speed outweighs per-unit cost, while reusable cotton-polyester blends retain share in academic medical centers with captive sterilization infrastructure. SMS materials command premium positioning due to higher hydrostatic head ratings, whereas polypropylene variants compete on cost in high-throughput emergency care applications.
The FDA regulates liquid barrier classification under 21 CFR 878.4040, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements for reusable surgical textiles entering European markets. Health Canada and the Therapeutic Goods Administration (TGA) in Australia enforce parallel standards that manufacturers must navigate for multi-jurisdictional approval. Stakeholders should monitor how evolving sterilization validation protocols and single-use plastic restrictions reshape material selection and regional sourcing strategies.
Market Dynamics
Hospital purchasing consolidation in the United States is compressing distributor margins and forcing manufacturers to restructure contract terms around guaranteed volume tiers rather than spot pricing.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter documentation requirements for reusable surgical textiles are accelerating conversion toward single-use SMS products in European acute care settings.
- Ambulatory surgery center expansion:Outpatient procedural volume growth in the United States is driving procurement of rapid-turnover disposable drapes and gowns over reusable alternatives.
- Spunbond-meltblown-spunbond (SMS) material advances:Higher hydrostatic head ratings in tri-laminate fabrics are displacing basic polypropylene in fluid-intensive surgical applications.
Market Restraints
- Polypropylene feedstock volatility:Petrochemical input cost swings compress margin predictability for manufacturers of economy-grade surgical textiles.
- Captive sterilization infrastructure lock-in:Academic medical centers with sunk capital in reusable textile processing resist conversion to disposables despite superior barrier performance.
- Single-use plastic restriction momentum:Extended producer responsibility frameworks in France and Germany threaten volume economics for disposable surgical product lines.
Strategic Opportunities
- India's hospital infrastructure buildout:Greenfield medical facility construction under the country's PLI scheme creates first-mover positioning for SMS material suppliers.
- RFID-enabled inventory tracking convergence:Integration of embedded sensor textiles with hospital ERP systems enables outcome-based procurement contracts.
- Brazil's ANVISA streamlined registration:Regulatory harmonization with FDA 510(k) pathways accelerates market entry for mid-tier manufacturers.
Industry Challenges
- Sterilization validation specialist scarcity:Qualified personnel for gamma and ethylene oxide validation are concentrated among legacy medical device contractors, extending product launch timelines.
- Legacy ERP integration friction:Hospital supply chain systems built for commodity purchasing resist SKU-level tracking of barrier-classified surgical textiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Drapes and Gowns Market |
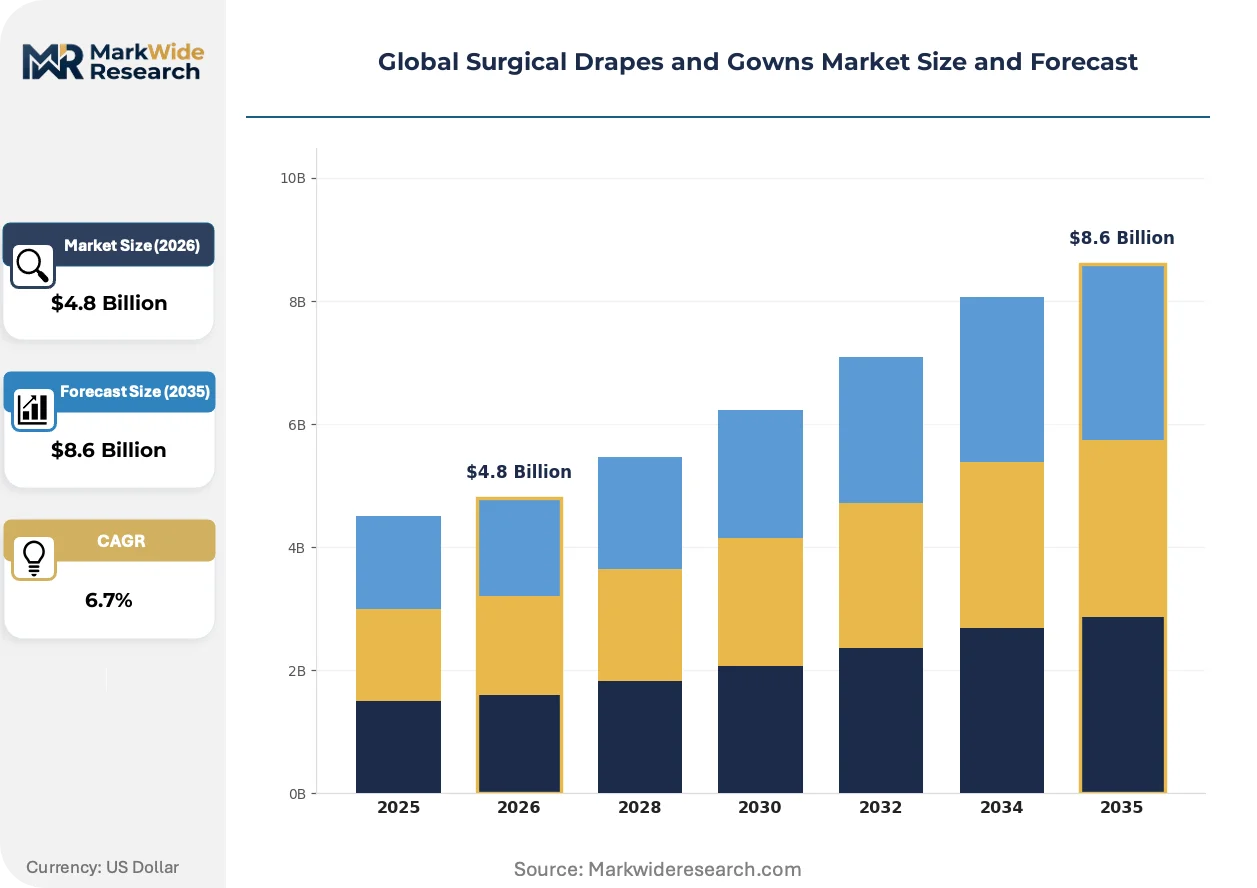
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Drapes, Disposable Drapes, Reusable Gowns, Disposable Gowns Material: Polypropylene, Cotton, Polyester, SMS End User: Hospitals, Ambulatory Surgery Centers, Clinics, Laboratories Application: Surgical Procedures, Emergency Care, Infection Control, Patient Protection |
| Companies Covered | Cardinal Health, Medline Industries, 3M, Mölnlycke Health Care AB, Owens & Minor, McKesson Corporation, B.D., Thermo Fisher Scientific, PAUL HARTMANN AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Drapes and Gowns Market Strategic Shifts
Material science advances and regulatory stringency are converging to reshape product specifications, while procurement centralization is restructuring how surgical barrier products reach end-users.
Smart textile integration with embedded RFID tags is digitizing inventory tracking across hospital supply chains. Integrated delivery networks in the United States are piloting real-time consumption monitoring to automate reorder triggers. This visibility layer is digitizing procurement workflows previously managed through manual par-level checks.
REACH restrictions on per- and polyfluoroalkyl substances (PFAS) are forcing reformulation of fluid-repellent finishes on surgical gowns. Manufacturers serving European markets are accelerating migration to silicone-based alternatives ahead of enforcement deadlines. SMS producers with EU MDR technical documentation are capturing share from suppliers dependent on legacy chemistries.
Consolidated purchasing through group purchasing organizations is compressing distributor roles in the United States. Direct manufacturer contracts with large health systems are displacing traditional two-step distribution for high-volume surgical drape SKUs. This channel compression is most visible in the Southeast and Midwest regions where hospital merger activity has concentrated buying power among three dominant systems.
Global Surgical Drapes and Gowns Market Segmentation
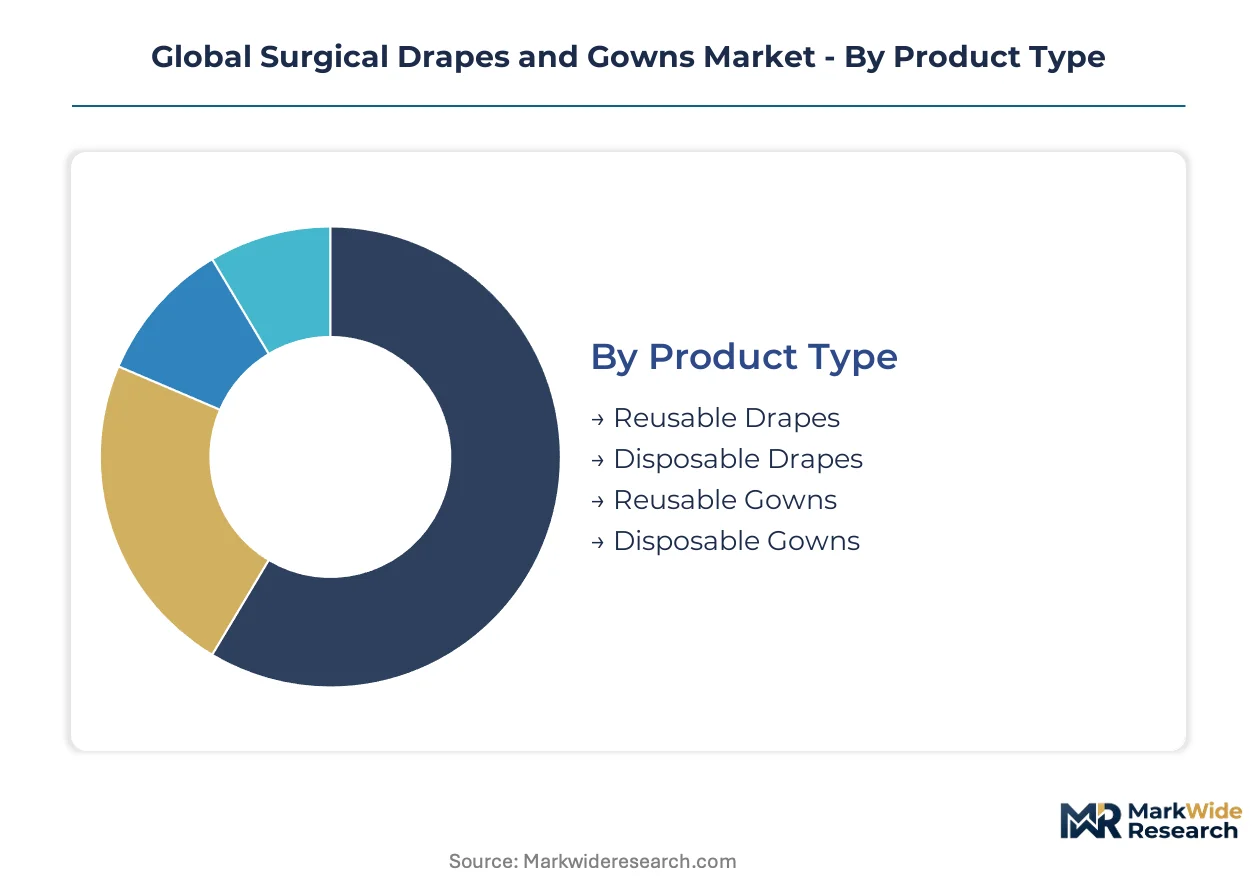
Surgical drapes and gowns segment across multiple dimensions that determine barrier performance, cost structure, and procurement channel. Material composition and sterility requirements create distinct supply chains for each category, while end-user scale dictates contract terms and inventory velocity.
Product Type:
Mature reusable formats coexist with rapidly scaling disposable alternatives as sterilization economics shift across healthcare settings.
- Reusable Drapes:Woven cotton-polyester blends processed through central sterile supply departments in academic medical centers. Demand concentrates in Germany and the United States where captive sterilization infrastructure amortizes fixed costs across high surgical throughput.
- Disposable Drapes:Nonwoven SMS or polypropylene barriers engineered for single-procedure use with integrated adhesive apertures. Ambulatory surgery centers in the United States and India's greenfield hospitals under the PLI scheme are driving procurement volume as turnover speed outweighs per-unit economics.
- Reusable Gowns:Reinforced woven textiles with fluid-resistant coatings validated for industrial laundering cycles. Retains share in European university hospitals with EMAS-certified sterilization facilities.
- Disposable Gowns:Tri-laminate SMS or spunbond polypropylene with taped seams meeting AAMI PB70 liquid barrier classifications. Fastest volume expansion in emergency departments and outpatient surgical suites where rapid donning protocols reduce turnover time.
Disposable gowns handle the majority of throughput; disposable drapes are the fastest mover on share.
Material:
Cost tiers separate commodity feedstocks from engineered laminates with differentiated barrier certification.
- Polypropylene:Spunbond nonwoven produced through continuous filament extrusion, competing on unit cost in high-throughput emergency care applications across Brazil and India. Margins compress when petrochemical feedstock prices spike.
- Cotton:Natural fiber woven textiles retaining niche demand in reusable gown applications where breathability and tactile comfort outweigh fluid barrier requirements. European REACH compliance adds processing cost for dye and finish chemistries.
- Polyester:Synthetic woven base for reusable drapes and gowns, blended with cotton for durability in industrial laundering. Demand clusters in Japan's acute care networks with METI-guided sterilization efficiency standards.
- SMS:Spunbond-meltblown-spunbond tri-laminate achieving hydrostatic head ratings above 50 cm for Level 3-4 barrier classification. FDA 510(k) submissions and EU MDR technical documentation requirements favor suppliers with validated SMS production lines.
SMS commands the premium tier; polypropylene dominates volume throughput in cost-sensitive procurement.
End User:
Customer scale determines contract structure, with consolidated health systems extracting volume-tier pricing unavailable to fragmented buyers.
- Hospitals:Integrated delivery networks and standalone acute care facilities with centralized materials management. United States hospital consolidation is compressing distributor margins and forcing direct manufacturer contracts.
- Ambulatory Surgery Centers:Outpatient procedural facilities with rapid turnover requirements and limited sterile processing infrastructure. Fastest-growing procurement channel for disposable SMS products in the United States and Germany.
- Clinics:Lower-acuity settings with intermittent surgical volume and par-level inventory management. Price sensitivity drives polypropylene preference over engineered laminates.
- Laboratories:Research and pathology settings requiring sterile barriers for necropsy and specimen handling. Niche volume with specialized chemical resistance requirements.
Hospitals anchor procurement volume; ambulatory surgery centers are expanding most quickly as outpatient migration accelerates.
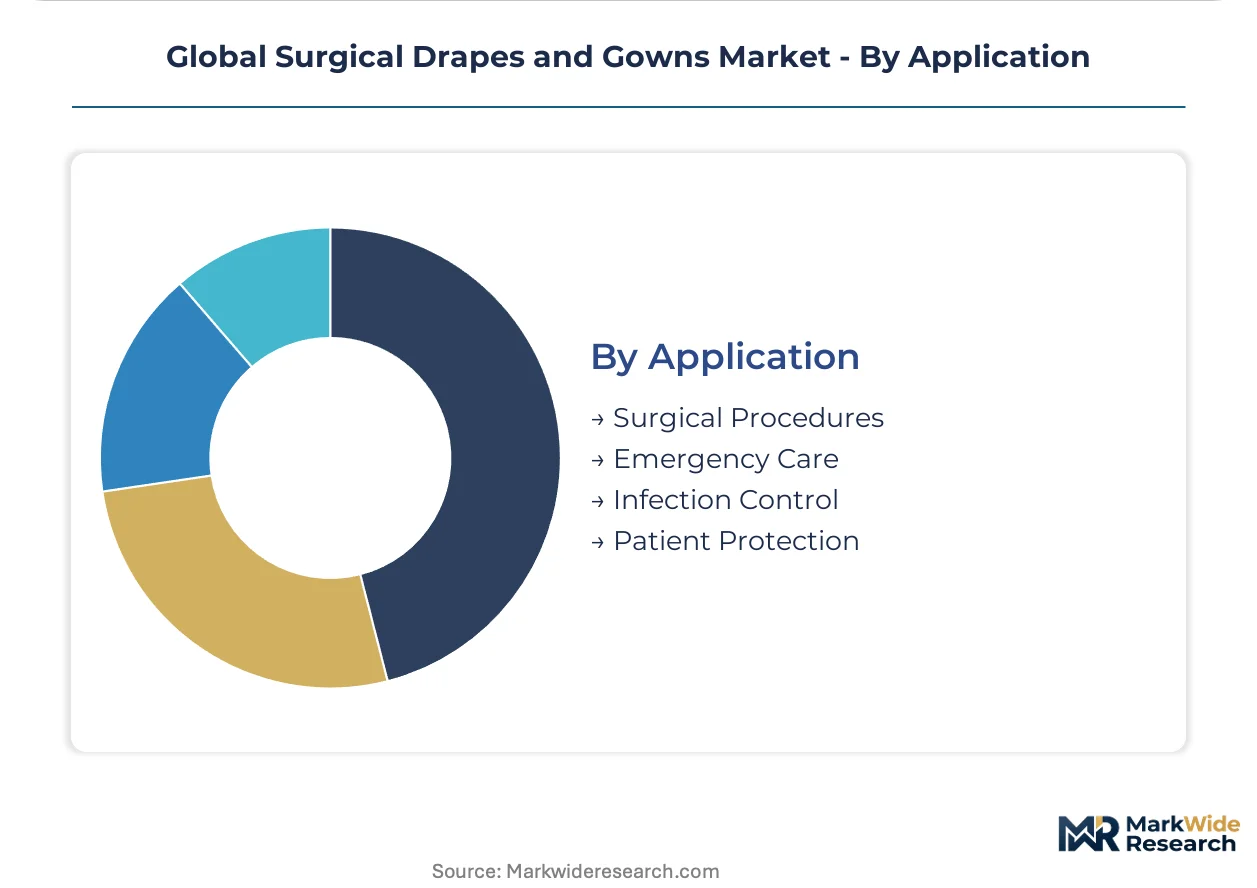
Application:
Procedure intensity and infection risk stratify barrier performance requirements across clinical settings.
- Surgical Procedures:Invasive interventions requiring validated sterile fields with liquid barrier protection against blood and irrigation fluid. AAMI Level 3-4 gowns dominate orthopaedic and cardiovascular suites in the United States and Japan.
- Emergency Care:Trauma and urgent intervention settings with unpredictable contamination exposure. Polypropylene drapes compete on cost where barrier classification requirements are less stringent.
- Infection Control:Isolation and outbreak response protocols requiring donning and doffing efficiency. Demand spikes correlate with seasonal respiratory surges and institutional preparedness mandates from the CDC and ECDC.
- Patient Protection:Non-sterile barriers for immunocompromised populations and reverse isolation. Lower technical specification permits commodity nonwoven supply.
Surgical procedures generate the highest revenue per unit; infection control applications show the steepest expansion trajectory during public health preparedness cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital purchasing consolidation concentrates procurement leverage among integrated delivery networks in the United States, while ambulatory surgery center expansion and greenfield hospital construction reshape demand geography across developed and emerging markets.
United States
Hospital merger activity in the Southeast and Midwest has concentrated buying power among three dominant health systems, forcing direct manufacturer contracts for high-volume SMS drape SKUs. FDA 510(k) liquid barrier classifications under 21 CFR 878.4040 govern product entry. Cardinal Health leverages its nationwide logistics network from distribution hubs in Ohio and Illinois to sustain contract renewals.
Germany
EMA-certified sterilization facilities in university hospitals sustain demand for reusable cotton-polyester gown formats despite EU MDR pressure on clinical documentation. Extended producer responsibility frameworks in France and Germany threaten disposable product economics. PAUL HARTMANN AG anchors supply relationships from its Heidenheim manufacturing base.
India
Greenfield medical facility construction under the PLI scheme creates first-mover positioning for SMS material suppliers serving outpatient surgical volume growth. CDSCO medical device registration requirements parallel FDA pathways for accelerated market entry. Gujarat and Maharashtra industrial corridors host emerging nonwoven conversion capacity.
Japan
METI-guided sterilization efficiency standards preserve reusable textile share in acute care networks with sunk capital in captive processing infrastructure. PMDA quality management system inspections favor established suppliers with validated production lines. The Kansai region around Osaka maintains concentration of woven surgical textile manufacturers.
Brazil
ANVISA streamlined registration harmonized with FDA 510(k) pathways accelerates market entry for mid-tier manufacturers of polypropylene emergency care drapes. Petrobras feedstock volatility compresses margin predictability for domestic converters. São Paulo state anchors distribution infrastructure for Latin American surgical supply flows.
Global Surgical Drapes and Gowns Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. Distributor-led consolidation in North America compresses margins for manufacturers without direct health system relationships. Three archetypes dominate: logistics-integrated distributors with nationwide warehousing, private-label specialists with embedded sales teams in integrated delivery networks, and technology-differentiated manufacturers with proprietary material formulations. Competitive moves center on guaranteed volume-tier contract restructuring and RFID-enabled inventory system integration.
Within the logistics-integrated tier, Cardinal Health and Owens & Minor occupy positions anchored by distribution infrastructure scale. Among product-specialist players, 3M exemplifies technology-differentiated positioning through proprietary repellent formulations. Medline Industries sits within the private-label archetype with direct sales force deployment. Mölnlycke Health Care AB represents European-based specialization in advanced barrier textiles.
| Leading Market Players |
|---|
| Cardinal Health |
| Medline Industries |
| 3M |
| Mölnlycke Health Care AB |
| Owens & Minor |
| McKesson Corporation |
| B.D. |
| Thermo Fisher Scientific |
| PAUL HARTMANN AG |
| Others |
Value Chain & Pricing Dynamics
Gujarat's industrial corridor expansion is adding SMS conversion capacity faster than downstream hospital procurement can absorb, compressing margin capture for mid-tier manufacturers serving price-sensitive ambulatory surgery centers. This supply abundance feeds directly into distributor negotiating leverage across India's greenfield hospital buildout.
Pricing Analysis
Cost-plus contracts indexed to polypropylene feedstock benchmarks dominate procurement agreements for high-volume disposable drape SKUs, with quarterly adjustments passing through petrochemical volatility to end-users. Price differentiation hinges on AAMI barrier certification tier and embedded RFID inventory tracking capability, with Level 4 SMS gowns commanding premium positioning over basic polypropylene emergency alternatives. Pricing pressure stems from hospital purchasing consolidation in the United States, where three dominant health systems extract guaranteed volume discounts unavailable to fragmented buyers. Ambulatory surgery centers exhibit highest price sensitivity due to limited sterile processing infrastructure and rapid turnover economics, while academic medical centers with captive sterilization show lowest sensitivity given sunk capital in reusable textile workflows.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for nonwoven raw material flows, with Section 301 duties on polypropylene spunbond forcing sourcing shifts toward Vietnam and Mexico. Manufacturing concentration clusters in China, the United States, and Germany, with tri-laminate SMS production anchored in FDA-inspected facilities and basic polypropylene conversion distributed across cost-optimized Asian hubs. Raw material dependencies rest on petrochemical feedstocks, meltblown polypropylene intermediates, and silicone-based fluid-repellent chemistries replacing legacy PFAS formulations. Distribution runs through Cardinal Health and Owens & Minor's nationwide logistics networks for hospital system direct contracts, with regional distributors serving ambulatory and clinic segments on spot pricing terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
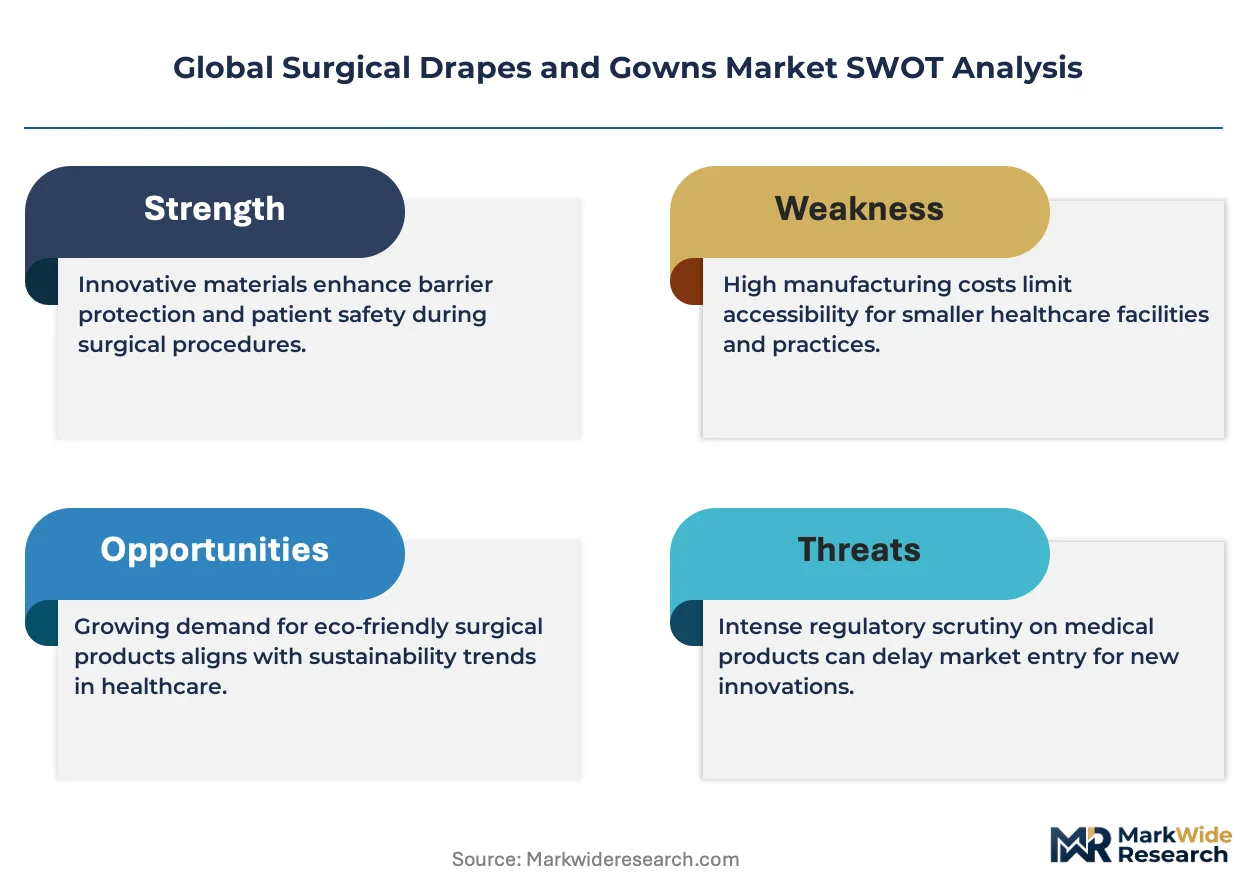
The surgical drapes and gowns market sits at an inflection where EU MDR clinical evidence mandates and REACH PFAS restrictions are simultaneously raising technical barriers and reformulation costs, creating asymmetric advantage for suppliers with validated documentation and advanced material science capabilities.
For Market Incumbents: Build regulatory documentation moats by accelerating EU MDR technical file completion for SMS product lines ahead of enforcement deadlines, while deepening backward integration into meltblown polypropylene production to insulate margins from petrochemical feedstock volatility. Cardinal Health and Medline Industries should leverage existing hospital system relationships to lock in multi-year direct contracts with RFID-enabled inventory tracking as a bundled value-add, defending against mid-tier manufacturers seeking share through price undercutting in the ambulatory surgery center channel.
For New Entrants and Emerging Players: Brazil's underpenetrated emergency care drape segment offers the most accessible white-space target, with ANVISA's harmonized FDA 510(k) registration pathway reducing time-to-market for polypropylene products against established multinational brands. India's PLI scheme hospital buildout presents secondary opportunity for SMS material suppliers willing to co-locate conversion capacity in Gujarat or Maharashtra industrial corridors. New entrants should pursue GPO-adjacent distributor partnerships rather than direct health system sales, avoiding the sunk cost of embedded sales team deployment that incumbent private-label specialists have already amortized.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because hospital purchasing centralization and regulatory documentation burdens are structurally advantaging scaled players with validated production lines and existing FDA 510(k) portfolios. Target acquisition archetypes include mid-tier SMS converters with EU MDR technical files in progress but constrained by working capital, and regional distributors with exclusive ambulatory surgery center relationships in underserved geographies. The signal to watch is group purchasing organization contract renewal timing, where incumbent pricing discipline versus share defense tradeoffs reveal competitive positioning durability.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Clinical evidence mandates under EU MDR are accelerating conversion from reusable to single-use SMS products in European acute care. |
| RFID-Enabled Inventory System Integration | Embedded sensor textiles with hospital ERP convergence enable outcome-based procurement contracts and automated reorder triggers. |
| Backward Integration into Meltblown Production | In-house polypropylene intermediate supply insulates margin predictability against petrochemical feedstock price volatility. |
| PFAS-Free Repellent Chemistry Migration | REACH restrictions on per- and polyfluoroalkyl substances force silicone-based formulation adoption ahead of enforcement deadlines. |
| Direct Health System Contract Restructuring | Guaranteed volume-tier terms displace spot pricing as hospital consolidation concentrates purchasing leverage among large systems. |
Study Parameters
Initial hypotheses were tested against primary input from hospital purchasing committee members, GPO contracts managers, biomedical engineers, and sterile processing department heads, then refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and customs trade data for polypropylene nonwoven imports. Bottom-up demand modeling across ambulatory surgery centers, acute care hospitals, and clinic settings was triangulated with top-down supply-side capacity assessments of SMS conversion lines.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product type, material grade tier, end-user scale, and application intensity, with CAGRs derived from procedure volume growth trajectories and materials substitution elasticities. Forecast inputs incorporated sterilization infrastructure capital stock depreciation schedules, regulatory transition timelines for reusable textile documentation, and outpatient surgical migration patterns by healthcare system type.
Practitioners should monitor EU MDR enforcement consistency, single-use plastic restriction expansion beyond France and Germany, and hospital merger approval velocity for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Medical Non-Woven Disposables Market
Medical and Hygiene Textiles
Medical Smart Textile Market
Medical and Hygiene Textiles
Absorbent Mats Market
Medical and Hygiene Textiles
Examination Gloves Market
Medical and Hygiene Textiles
Global Antimicrobial Medical Textiles Market
Medical and Hygiene Textiles
Antimicrobial Textiles Market
Medical and Hygiene Textiles
Latin America Sanitary Napkin Market
Medical and Hygiene Textiles
GCC Sanitary Napkin Market
Medical and Hygiene Textiles
Arm Pouches Market
Medical and Hygiene Textiles
Examination Gowns Market
Medical and Hygiene Textiles
Sleeping Masks Market
Medical and Hygiene Textiles
Washable and Reusable Mask Market
Medical and Hygiene Textiles
Intestinal Wash Bags Market
Medical and Hygiene Textiles
Foot Mask Market
Medical and Hygiene Textiles
Global Diabetic Socks Market
Medical and Hygiene Textiles
Period Panties Market