
 Antimicrobial Peptides Market | 2026-2036
Antimicrobial Peptides Market Size, Share, and Industry Trends Forecast 2026-2036
Antimicrobial Peptides Market Analysis
European fermentation capacity is expanding to meet peptide API demand. Novozymes leverages its industrial biotechnology platform to supply enzyme-enabled peptide synthesis. Eli Lilly and Company anchors North American production through specialized biologics infrastructure. Merck & Co., Inc. competes across contract development channels for late-stage peptide candidates.
Antimicrobial peptides are short amino acid sequences, typically 12–50 residues, that disrupt microbial membranes through electrostatic interactions with phospholipid bilayers; they serve as alternatives to conventional antibiotics in therapeutic and preservative applications. Natural peptides dominate current production volumes due to established extraction protocols from bacterial and mammalian sources, though synthetic peptides capture expanding margin pools in precision-targeted therapies. Injectable formulations lead the delivery mode landscape in hospital settings, while topical application segments grow fastest in dermatology and wound care protocols.
The FDA governs antimicrobial peptide IND submissions under its anti-infective guidance, while the EMA's MDR framework imposes stricter biocompatibility thresholds for peptide-device combinations. REACH and RoHS compliance in Europe further constrain solvent use in solid-phase peptide synthesis, pushing manufacturers toward greener chemistries. Stakeholders must monitor evolving pharmacovigilance requirements for novel peptide modalities and assess backward integration into fermentation or recombinant expression capacity.
Market Dynamics
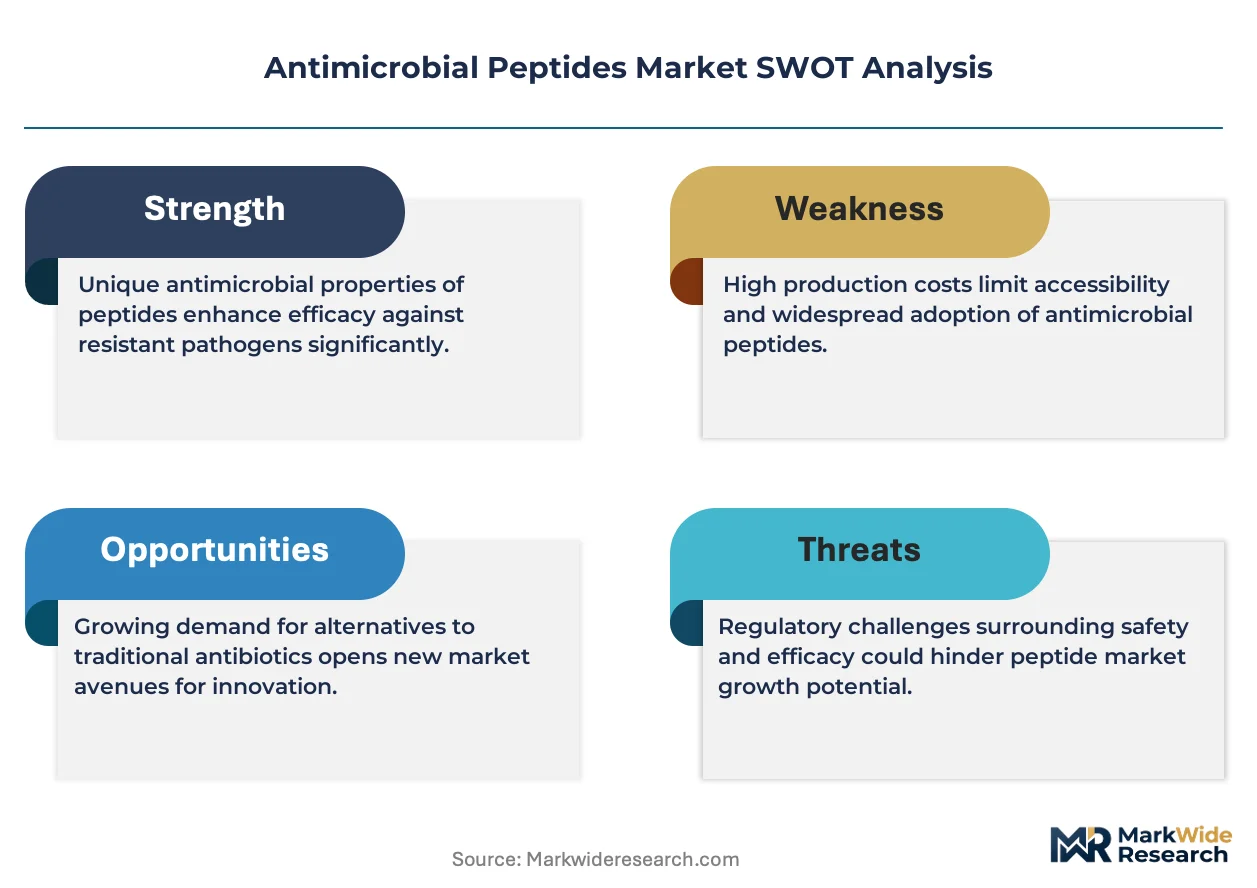
Antimicrobial peptide developers face escalating pressure from FDA and EMA pharmacovigilance mandates that compress clinical timelines while fermentation capacity constraints limit API scale-up for late-stage candidates.
Growth Catalysts
- EMA MDR Framework:Stricter biocompatibility thresholds for peptide-device combinations accelerate validation investments across wound care and implantable applications.
- Dermatology Protocols:Topical peptide formulations gain traction in hospital outpatient settings as alternatives to systemic antibiotics for localized infections.
- Enzymatic Synthesis:Industrial biotechnology platforms reduce solvent dependence in solid-phase peptide production, lowering environmental compliance costs under REACH.
Market Restraints
- Amino Acid Feedstock Volatility:Fermentation-grade amino acid supply concentrates among specialty chemical producers in Germany and Switzerland, exposing margins to input cost swings.
- Regulatory Friction:FDA anti-infective guidance requires expanded safety databases for novel peptide modalities, extending IND-to-approval timelines versus small-molecule benchmarks.
- Small-Molecule Substitution:Reformulated conventional antibiotics with improved PK profiles retain formulary preference in cost-sensitive hospital procurement.
Strategic Opportunities
- Chronic Wound Care:Diabetic foot ulcer protocols in the United States incorporate antimicrobial peptides as adjunctive therapy, opening reimbursement pathways.
- Green Chemistry Mandates:REACH solvent restrictions push contract manufacturers toward aqueous-phase synthesis, rewarding early adopters with preferred supplier status.
- Recombinant Expression Convergence:Yeast and bacterial expression systems merge with solid-phase finishing to enable complex disulfide-bridged peptides at commercial scale.
Industry Challenges
- Peptide Chemist Scarcity:Specialized expertise in large-scale peptide synthesis and analytical method development concentrates among legacy CMO workforces in Basel and Boston.
- cGMP Facility Certification:Dedicated peptide API suites require 18-24 month qualification timelines, delaying commercial launches for Phase III candidates.
- Legacy ERP Integration:Batch record systems designed for small-molecule workflows struggle with peptide-specific impurity profiling and forced degradation studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimicrobial Peptides Market |
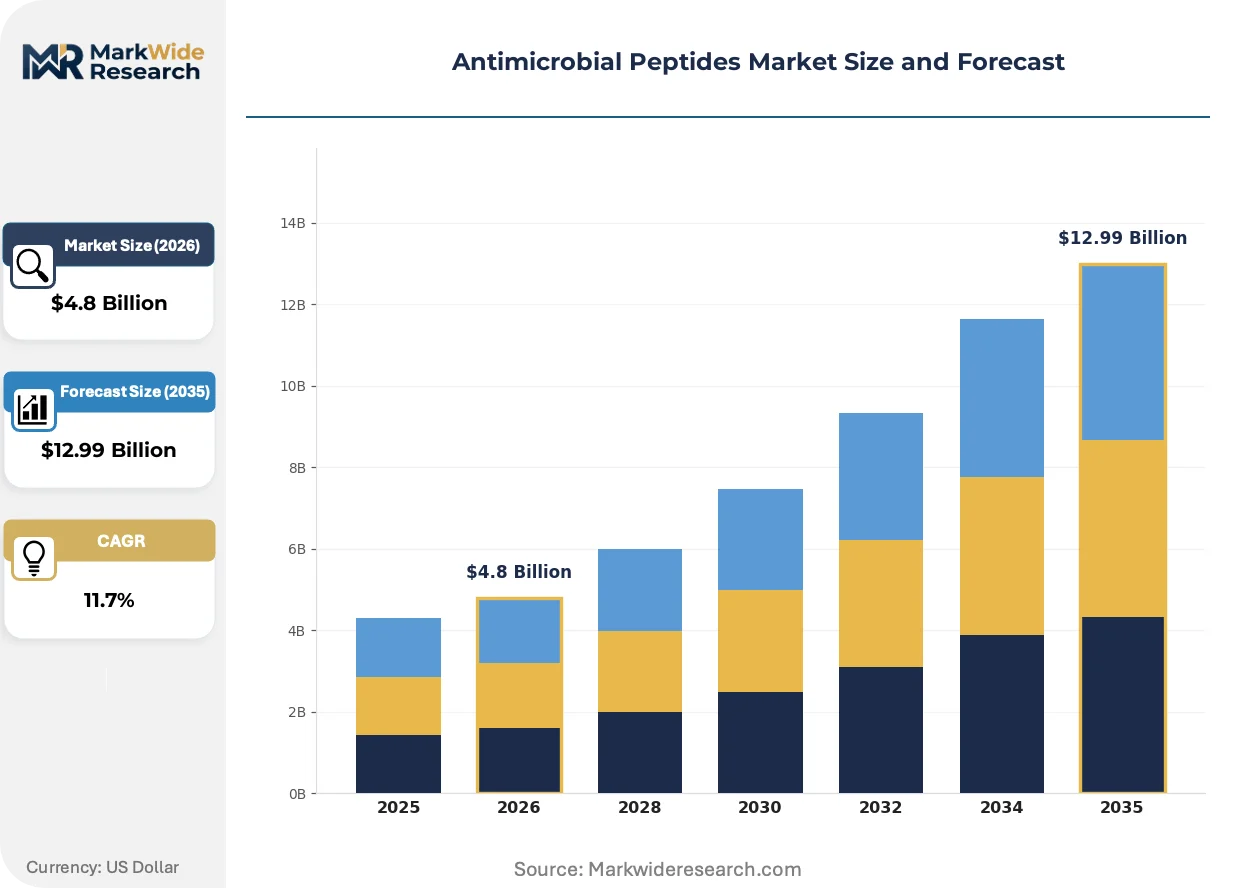
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Peptides, Synthetic Peptides, Modified Peptides, Hybrid Peptides Therapy Area: Infectious Diseases, Dermatology, Oral Care, Wound Care End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Manufacturing Organizations Delivery Mode: Topical Application, Oral Administration, Injectable Formulations, Intranasal Delivery |
| Companies Covered | Eli Lilly and Company, Novozymes, Pfizer Inc., Xellia Pharmaceuticals, Bachem, AbbVie Inc., AnaSpec, Phoenix Biotech, Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimicrobial Peptides Market Emerging Trajectories
Antimicrobial peptide manufacturing is bifurcating between precision synthetic routes for targeted therapeutics and scaled fermentation approaches for preservative applications, with regulatory chemistry controls tightening across both pathways.
Enzymatic peptide synthesis is expanding into commercial production as Novozymes and specialized suppliers deploy engineered proteases for regioselective ligation. Hospital-formulary buyers in Germany and the United States are qualifying enzyme-sourced peptides for high-volume parenteral applications. This technology is expanding into cost structures previously dominated by traditional solid-phase chemistry, compressing per-gram production costs for 20-30 residue sequences.
REACH and RoHS compliance frameworks in Europe now constrain N,N-dimethylformamide and acetonitrile use in peptide coupling steps. Manufacturers are reformulating activation chemistries around aqueous-compatible reagents or supercritical CO2 extraction. Solid-phase synthesis operations in the Netherlands and Denmark face the steepest reformulation timelines due to existing environmental permit dependencies.
Hospital procurement committees are consolidating antimicrobial peptide sourcing through sole-supplier agreements tied to formulary tier placement. Group purchasing organizations in the United States are displacing fragmented multi-vendor purchasing for topical and injectable peptide stocks. This concentration is most visible in academic medical centers, where infectious disease stewardship programs mandate preferred peptide alternatives for MRSA coverage.
Antimicrobial Peptides Market Segmentation
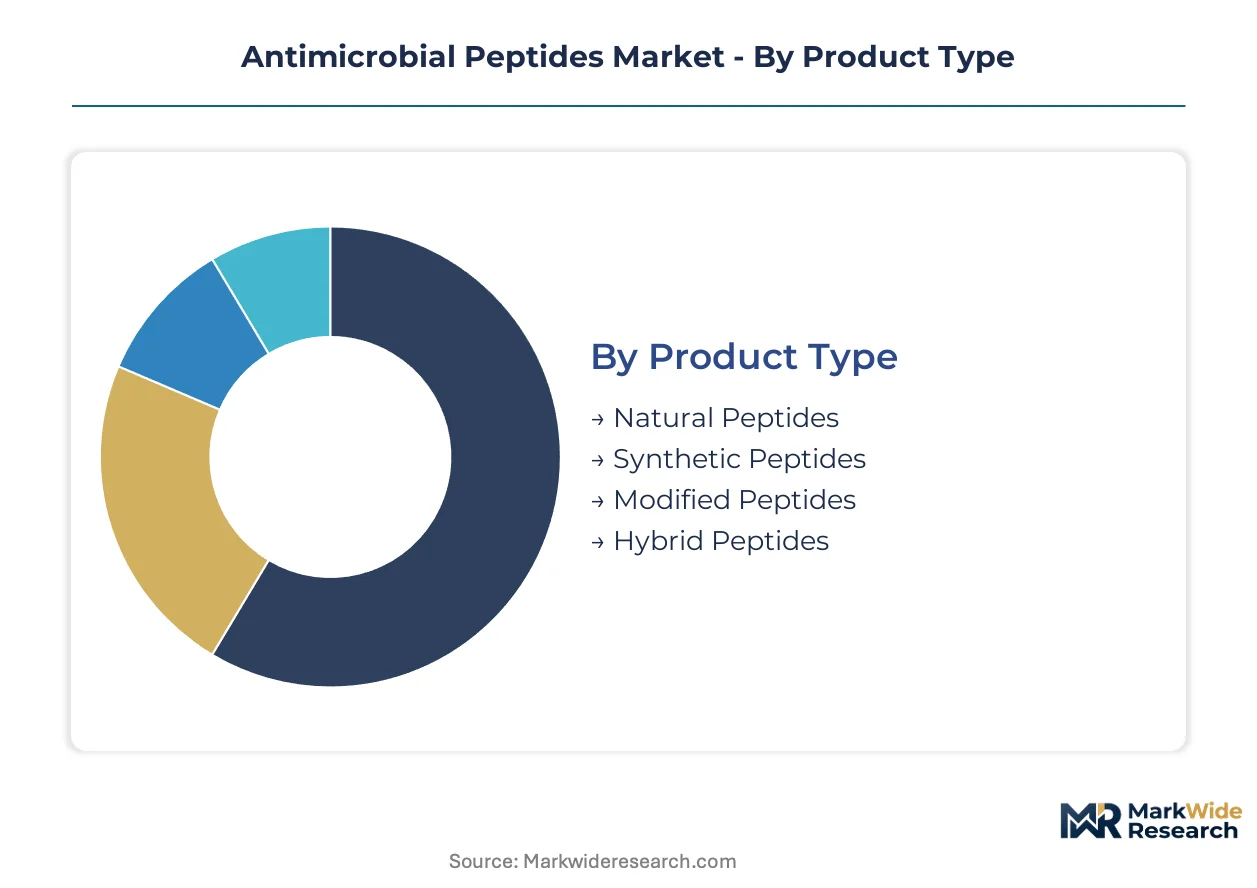
Antimicrobial peptide developers navigate divergent manufacturing economics across extraction-based and synthetic production routes. Segment boundaries increasingly blur as recombinant expression platforms merge with chemical finishing steps.
Product Type:
Fermentation capacity concentrates among specialized producers in Basel and Boston corridors, dictating competitive positioning across peptide sourcing strategies.
- Natural Peptides:Extracted from bacterial, fungal, or mammalian biomass through established downstream processing protocols. Hospital procurement committees in Germany and the United States prioritize these sequences for formulary placement in MRSA coverage protocols, though batch-to-batch variability constrains precision therapeutic applications.
- Synthetic Peptides:Assembled through solid-phase or solution-phase chemistry with exact sequence control and defined impurity profiles. Demand concentrates in late-stage clinical candidates where regulatory chemistry controls require validated synthetic routes; REACH solvent restrictions in the Netherlands and Denmark are accelerating aqueous-phase reformulation investments.
- Modified Peptides:Incorporate non-natural amino acids, lipid conjugation, or cyclization for enhanced proteolytic stability.
- Hybrid Peptides:Combine natural sequence motifs with synthetic modifications to balance potency against manufacturing scalability.
Natural peptides absorb the bulk of installed fermentation capacity; synthetic peptides are expanding most quickly as precision therapeutics advance through clinical pipelines.
Therapy Area:
Reimbursement pathways diverge sharply between acute hospital administration and outpatient self-pay categories, reshaping commercial prioritization across development portfolios.
- Infectious Diseases:Systemic peptide therapies targeting drug-resistant bacterial and fungal pathogens. FDA anti-infective guidance mandates expanded safety databases for novel modalities, compressing competitive timelines for developers with existing clinical datasets.
- Wound Care:Topical and implantable formulations for diabetic foot ulcers, surgical site infections, and chronic non-healing wounds. Medicare coverage determinations in the United States are opening reimbursement for adjunctive peptide therapy in academic medical center protocols.
- Dermatology:Prescription and cosmetic applications targeting acne, atopic dermatitis, and antimicrobial skin colonization.
- Oral Care:Preservative and therapeutic applications in mouthwash, toothpaste, and periodontal treatment formulations.
Infectious diseases commands the deepest clinical investment; wound care is gaining share fastest through hospital formulary expansion.
End User:
Customer concentration is accelerating as pharmaceutical majors internalize peptide capabilities while mid-tier developers rely increasingly on captive CMO relationships.
- Pharmaceutical Companies:Large-scale developers integrating peptide therapeutics into anti-infective portfolios through dedicated biologics infrastructure. Eli Lilly and Merck anchor North American production capacity for commercial-scale peptide API.
- Contract Manufacturing Organizations:Specialized peptide synthesis providers offering cGMP suites with 18-24 month qualification timelines. European fermentation capacity in Denmark and the Netherlands is expanding to meet late-stage candidate demand.
- Biotechnology Firms:Venture-backed developers advancing novel modalities through early-stage clinical validation.
- Research Institutions:Academic laboratories exploring mechanistic biology and structure-activity relationships in peptide-membrane interactions.
Pharmaceutical companies absorb the majority of high-volume peptide output; contract manufacturing organizations are scaling fastest to serve the clinical pipeline.
Delivery Mode:
Route selection determines regulatory pathway complexity and manufacturing investment intensity, with parenteral formats requiring the most specialized infrastructure.
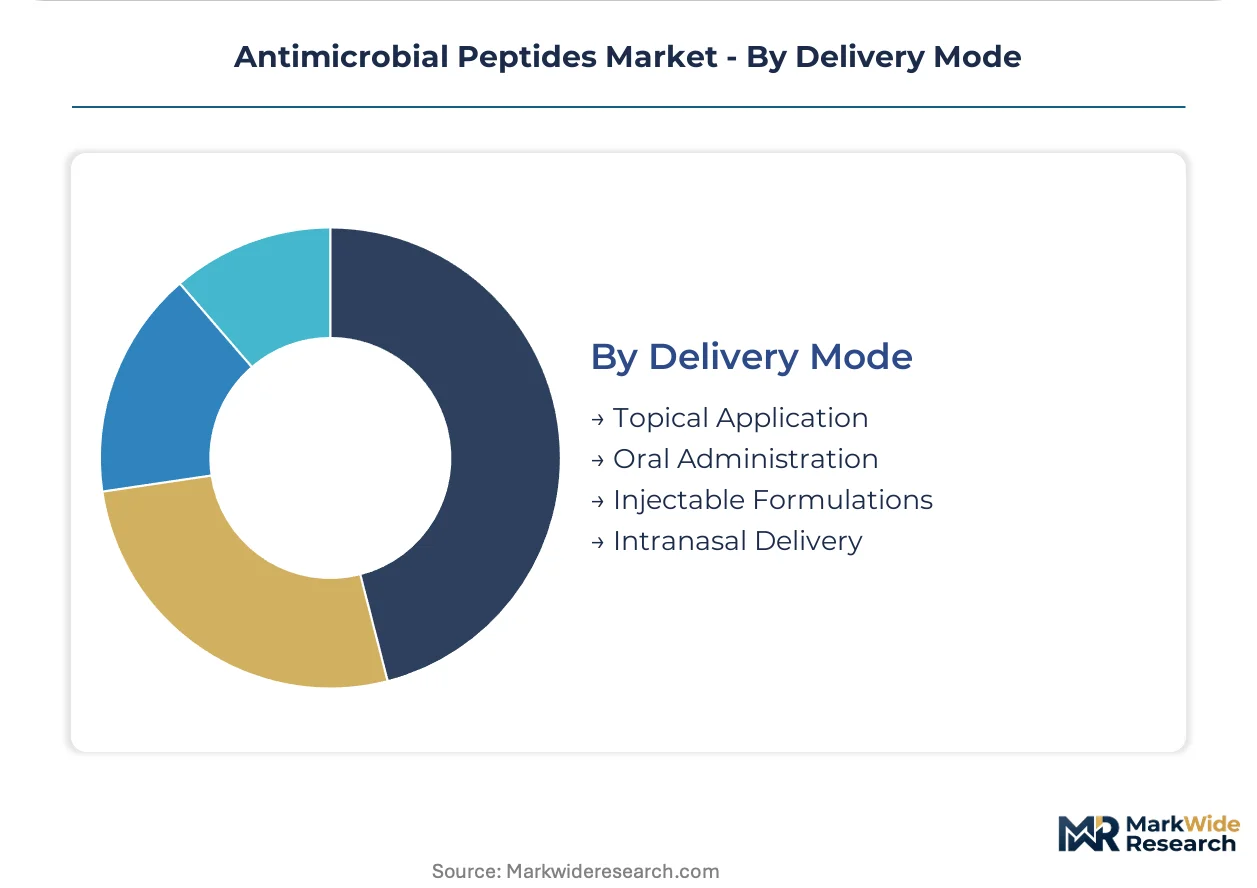
- Injectable Formulations:Parenteral delivery for systemic anti-infective therapy in hospitalized patients. cGMP fill-finish capacity constraints in the United States and Germany limit commercial scale-up for Phase III candidates.
- Topical Application:Cream, gel, and wound dressing formats for localized infection management. Dermatology protocols in German hospital outpatient settings are qualifying peptide alternatives to systemic antibiotics.
- Oral Administration:Tablet and capsule formulations challenged by gastric proteolysis; enteric coatings and cyclic peptide architectures dominate development focus.
- Intranasal Delivery:Mucosal administration for respiratory and CNS-targeted applications exploiting olfactory transport mechanisms.
Injectable formulations dominate current revenue; topical application is climbing the fastest as outpatient protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation-grade amino acid supply concentrates among specialty chemical producers in Germany and Switzerland, exposing margins to input cost swings across peptide manufacturing corridors.
United States
Academic medical centers in Boston and the Research Triangle drive clinical validation for wound care protocols. FDA anti-infective guidance mandates expanded safety databases for novel peptide modalities, compressing IND-to-approval timelines. Eli Lilly anchors North American production through specialized biologics infrastructure in Indianapolis.
Germany
Hospital procurement committees in Munich and Hamburg prioritize natural peptide sequences for MRSA coverage protocols. EMA MDR framework imposes stricter biocompatibility thresholds for peptide-device combinations. Basel-Baden-Württemberg corridor concentrates fermentation capacity among legacy CMO workforces.
Denmark
Novozymes leverages its industrial biotechnology platform from Copenhagen to supply enzyme-enabled peptide synthesis. REACH solvent restrictions push solid-phase operations toward aqueous-phase reformulation. Kalundborg industrial cluster faces steep environmental permit dependencies for existing synthesis infrastructure.
Switzerland
Bachem and specialized suppliers anchor contract development channels for late-stage peptide candidates. Swissmedic maintains alignment with EMA pharmacovigilance mandates while offering accelerated access pathways. Basel corridor concentrates peptide chemist expertise and cGMP facility certification capacity.
Netherlands
Rotterdam-Amsterdam logistics hub supports feedstock import for fermentation-grade amino acids. RoHS compliance frameworks constrain N,N-dimethylformamide use in peptide coupling steps. Delft biotech cluster advances aqueous-compatible activation chemistries for green chemistry mandates.
Antimicrobial Peptides Market Vendor Landscape
Global majors compete with regional champions across fermentation capacity and specialized synthesis expertise, producing a tiered structure where pharmaceutical conglomerates absorb high-volume output while mid-tier developers rely on captive CMO relationships. The vendor base stratifies between integrated biologics manufacturers, enzyme technology platforms, and pure-play peptide synthesis specialists. Two dominant competitive moves are reshaping positioning: backward integration into fermentation capacity by pharmaceutical majors, and geographic expansion of European CMOs into North American clinical trial supply.
Within the integrated pharmaceutical tier, Eli Lilly and Company and Merck & Co., Inc. occupy positions exemplifying captive biologics infrastructure for commercial-scale peptide API. Among enzyme technology platforms, Novozymes represents the industrial biotechnology archetype supplying regioselective ligation capacity. These three anchors demonstrate how competitive advantage concentrates at the intersection of fermentation scale and regulatory chemistry control.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Novozymes |
| Pfizer Inc. |
| Xellia Pharmaceuticals |
| Bachem |
| AbbVie Inc. |
| AnaSpec |
| Phoenix Biotech |
| Merck & Co., Inc. |
| Others |
Supply Flow & Price Mechanics
Enzymatic synthesis migration is compressing per-gram production costs for 20-30 residue sequences while simultaneously concentrating supplier power among industrial biotechnology platforms in Denmark and specialized CMO corridors in Basel. This technology shift rewards early adopters with preferred supplier status under REACH solvent restrictions, yet strands legacy solid-phase operations facing 18-24 month aqueous-phase reformulation timelines.
Pricing Analysis
Service bundling separates peptide API supply from analytical method development and regulatory dossier support, with cGMP certification and forced degradation studies typically unbundled for mid-tier developers. Three-tier pricing structure across premium, standard, and economy levels reflects fermentation scale, synthetic route complexity, and EMA MDR biocompatibility validation status. Pricing pressure stems from amino acid feedstock volatility concentrated among German and Swiss specialty chemical producers, compressing margins for natural peptide extraction operations. Hospital procurement committees in academic medical centers exhibit lowest price sensitivity due to infectious disease stewardship mandates, while outpatient dermatology protocols face highest sensitivity from self-pay patient segments.
Supply Chain Analysis
Single-source vulnerability sits with fermentation-grade amino acid supply anchored in Germany, Switzerland, and the Netherlands, where specialty chemical producers control critical input streams. Downstream peptide synthesis draws from solid-phase resins, protected amino acid derivatives, and enzyme catalysts engineered by Novozymes from Copenhagen. Tariff exposure on Chinese-sourced coupling reagents and acetonitrile alternatives amplifies cost uncertainty for aqueous-phase reformulation investments. Distribution runs through sole-supplier agreements tied to hospital formulary tier placement, with group purchasing organizations consolidating fragmented multi-vendor purchasing into concentrated sourcing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where REACH solvent restrictions and EMA MDR biocompatibility thresholds erect barrier-to-entry moats favoring players with captive fermentation capacity and validated green chemistry platforms.
For Market Incumbents: Anchor defensive positioning through backward integration into recombinant expression capacity in the Basel-Baden-Württemberg corridor, insulating against amino acid feedstock volatility while capturing preferred supplier status under REACH mandates. Consolidate analytical method development and regulatory dossier capabilities to displace mid-tier CMO competitors facing 18-24 month cGMP facility qualification delays. Prioritize enzyme-enabled synthesis investments to compress per-gram costs below traditional solid-phase benchmarks. For New Entrants and Emerging Players: Mid-tier biotechnology firms lacking captive manufacturing infrastructure represent an underserved buyer archetype seeking flexible contract development partnerships with accelerated timelines. White-space concentration appears in aqueous-phase peptide finishing for wound care device combinations facing EMA MDR reformulation deadlines. Enter through specialized CMO relationships offering integrated regulatory chemistry control and pharmacovigilance database support, bypassing capital-intensive fermentation buildout. For Investors and Strategic Acquirers: Re-rating potential sits with enzyme technology platforms possessing regioselective ligation capabilities given accelerating hospital formulary qualification for enzymatically synthesized parenteral peptides. Long-term viability favors targets with demonstrated REACH compliance and established relationships with German hospital procurement committees. Monitor FDA anti-infective guidance revisions as inflection signal for novel peptide modality approval timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Expands fermentation capacity in Kalundborg and Basel corridors to meet Phase III candidate demand. |
| Regulatory Approval Pathway | Accelerates EMA MDR biocompatibility validation for peptide-device combinations in wound care protocols. |
| Green Manufacturing Transition | Deploys aqueous-phase synthesis to secure preferred supplier status under REACH solvent restrictions. |
| Backward Integration | Captures amino acid feedstock supply through captive fermentation capacity in Germany and Switzerland. |
| Licensing Agreement | Accesses Novozymes enzyme platforms for regioselective ligation in commercial peptide production. |
Methodological Framework
Multi-period observation of FDA IND submission timelines, EMA MDR framework implementation, and hospital formulary placement patterns anchored the trend analysis, supplemented by interviews with peptide development executives, regulatory affairs leads, hospital procurement managers, and CMO technical directors. Secondary validation drew from FDA anti-infective guidance documents, EMA pharmacovigilance databases, REACH compliance filings, ClinicalTrials.gov peptide candidate tracking, and SEC 10-K disclosures from integrated pharmaceutical manufacturers. Bottom-up peptide API volume estimates triangulated against top-down therapeutic category spending analysis.
Input-output matrices modeled relationships between fermentation capacity utilization, amino acid feedstock pricing, and synthetic route adoption across product type, therapy area, end user, and delivery mode segmentation dimensions. CAGRs derived from regression analysis against clinical pipeline progression rates and regulatory approval velocity indicators. Forecast inputs incorporated enzyme synthesis technology penetration curves and hospital procurement consolidation trends.
Revisions become necessary when FDA anti-infective guidance mandates expand safety database requirements beyond current peptide modality benchmarks, or when REACH solvent restrictions accelerate faster than aqueous-phase reformulation capacity expansion. Deviation in German amino acid feedstock pricing or EMA MDR biocompatibility threshold enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Targeted Cancer Drugs Market
Medical Biotechnology
Global Mononucleosis Diagnostic Market
Medical Biotechnology
Europe Cell Culture Market
Medical Biotechnology
Cell and Tissue Preservation Market
Medical Biotechnology
Cyclin-Dependent Kinase Inhibitor Market
Medical Biotechnology
Global Small Interfering RNA (Sirna) Therapeutics Market
Medical Biotechnology
Mecobalamin Injection Market
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market
Medical Biotechnology
Insulin Management System Market
Medical Biotechnology
Mucormycosis Market
Medical Biotechnology
Botulism Illness Market
Medical Biotechnology
Asia-Pacific G-CSF/ PEG-G-CSF Market
Medical Biotechnology
Cancer Antigens Market
Medical Biotechnology
Alpha Mannosidosis Market
Medical Biotechnology
Thalassemia Market
Medical Biotechnology
Global Human Embryonic Stem Cells Market