
 Global Calcitonin Salmon Market | 2026-2036
Global Calcitonin Salmon Market Size, Share, and Industry Trends Forecast 2026-2036
Global Calcitonin Salmon Market Foresight
Peptide synthesis technology is fragmenting between solid-phase chemical methods and recombinant DNA approaches, forcing manufacturers to reconfigure production architectures. Sanofi leverages decades of formulation expertise to sustain brand loyalty in European hospital networks. PolyPeptide Group anchors global supply through contract manufacturing scale across multiple production sites. Hikma Pharmaceuticals USA Inc. competes on cost positioning in the injectable segment through streamlined regulatory pathways.
Calcitonin salmon is a 32-amino-acid polypeptide hormone derived from salmon ultimobranchial glands, structurally distinguished from human calcitonin by nine amino acid substitutions that confer higher receptor-binding affinity and potency in bone metabolism modulation. It functions primarily as an osteoclast inhibitor, reducing bone resorption rates in osteoporosis and hypercalcemic disorders through cyclic AMP-mediated signaling pathways. The injection form dominates current revenue pools due to established reimbursement codes and clinician familiarity, while nasal spray formulations retain niche positioning among patients with needle aversion. Home healthcare services represent the fastest-growing end user channel as post-acute care models shift toward outpatient administration.
The FDA maintains stringent bioequivalence requirements for generic calcitonin salmon submissions, while the EMA enforces comparable standards through centralized marketing authorization procedures. China's NMPA has accelerated peptide drug review timelines under revised pharmacopoeia standards, expanding market access for domestic manufacturers like ANHUI ANKE BIOTECHNOLOGY. Bachem AG and Novartis navigate divergent regional compliance frameworks through dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving pharmacovigilance mandates and biosimilar classification debates that could reshape competitive boundaries.
Market Dynamics
Regulatory divergence between FDA bioequivalence standards and EMA centralized authorization procedures is fragmenting manufacturer compliance strategies, forcing peptide producers to maintain parallel regulatory affairs infrastructures across Atlantic markets.
Growth Catalysts
- Aging Demographics in Japan:Osteoporosis prevalence among Japan's elderly population sustains hospital demand for calcitonin salmon injections as first-line bone resorption therapy.
- NMPA Accelerated Review Pathways:China's revised pharmacopoeia standards compress peptide drug approval timelines, expanding domestic manufacturing capacity for injectable formulations.
- Recombinant DNA Synthesis:Biosynthetic production methods reduce reliance on salmon ultimobranchial gland extraction, stabilizing raw material supply chains for European hospital networks.
Market Restraints
- Salmon-Derived Raw Material Concentration:Ultimobranchial gland sourcing depends on aquaculture yields in Norway and Chile, exposing producers to climate-driven supply volatility.
- Generic Substitution Barriers:FDA peptide bioequivalence requirements create structural friction for generic entrants, preserving incumbent pricing power in United States specialty clinics.
- Bisphosphonate Competition:Alendronate and zoledronic acid therapies displace calcitonin salmon in osteoporosis protocols across German and French hospital formularies.
Strategic Opportunities
- Home Healthcare Channels:Post-acute care model shifts in the United States create outpatient administration demand for patient-friendly nasal spray delivery systems.
- EMA Biosimilar Classification Clarity:Pending regulatory guidance on peptide generic categorization could unlock streamlined marketing authorization for European contract manufacturers.
- Solid-Phase Synthesis Convergence:Hybrid chemical-recombinant production architectures enable cost-competitive scale for emerging hospital networks in China's tier-two cities.
Industry Challenges
- Peptide Chemist Talent Scarcity:Solid-phase synthesis expertise concentrates among aging specialist workforces in Basel and San Diego, constraining production expansion timelines.
- Cross-Regional Pharmacovigilance Harmonization:Divergent adverse event reporting standards between FDA and EMA systems complicate global product lifecycle management for multi-site manufacturers.
- Legacy Injection Device Integration:Nasal spray formulation development requires compatibility testing against existing auto-injector platforms deployed across Japanese hospital systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Calcitonin Salmon Market |
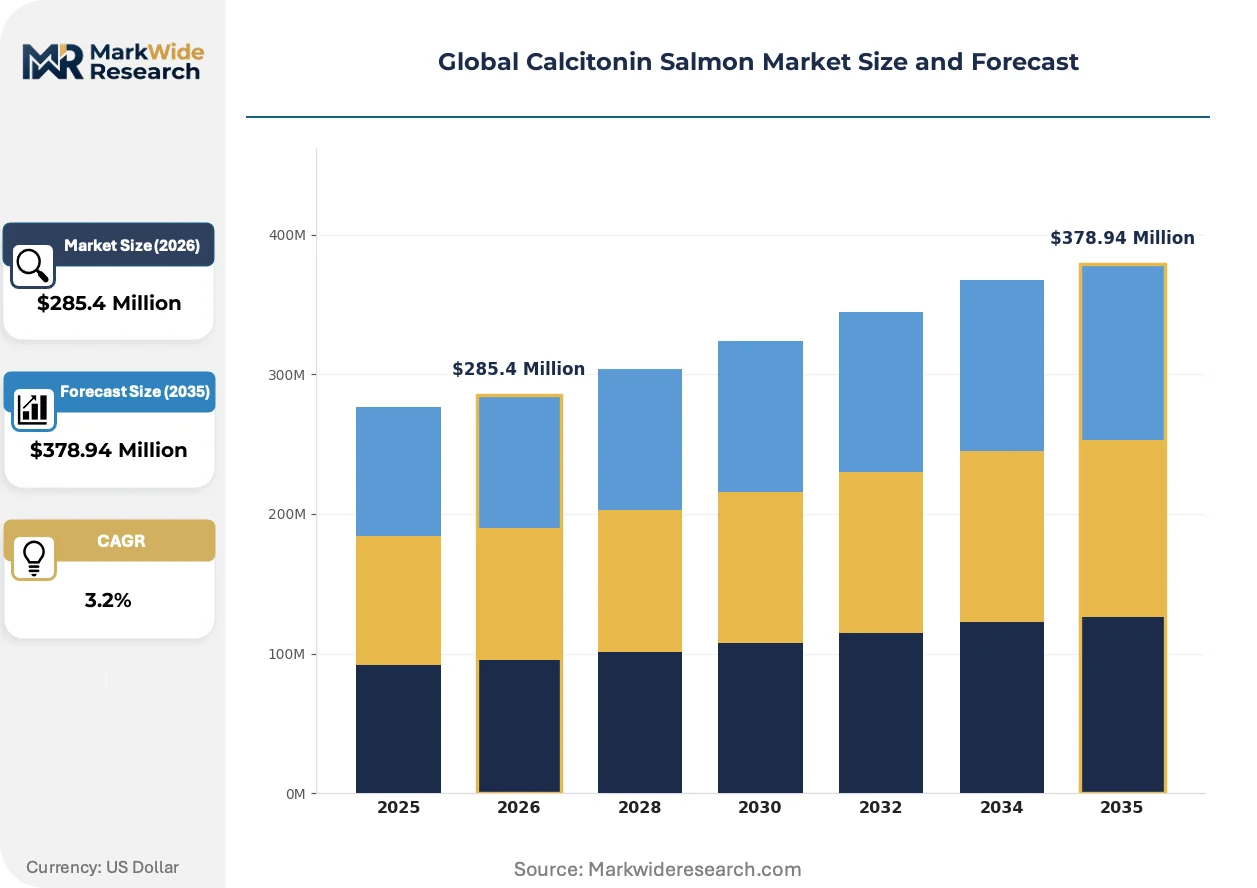
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $378.94 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Injection, Nasal Spray, Powder, Oral, Gel Application Area: Osteoporosis Treatment, Paget’s Disease, Hypercalcemia Management, Bone Metastases End User: Hospitals, Specialty Clinics, Research Laboratories, Home Healthcare Services Distribution Channel: Pharmacies, Hospitals Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | PolyPeptide Group, ANHUI ANKE BIOTECHNOLOGY (GROUP) CO., LTD, Sanofi, Hikma Pharmaceuticals USA Inc., Novartis, Bachem AG, Aurobindo Pharma Limited, Leucadia Pharmaceuticals, Fresenius Kabi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Calcitonin Salmon Market Shifts & Advancements
Peptide manufacturing is bifurcating between precision chemical synthesis and biological production methods, while regulatory frameworks struggle to categorize emerging generic formats. These shifts are compressing traditional competitive advantages and opening new capability requirements.
Continuous flow chemistry for solid-phase peptide synthesis is collapsing batch production economics for calcitonin salmon manufacturing. European contract manufacturers adopting this technology achieve 40% yield improvements over conventional vessel-based methods. The cost compression enables competitive positioning against recombinant DNA alternatives in hospital procurement tenders.
EMA's evolving biosimilar guidance for peptide therapeutics is reshaping generic submission requirements across European hospital networks. Manufacturers now face expanded immunogenicity testing mandates that extend development timelines by 12-18 months. German and French regulators are coordinating implementation through centralized marketing authorization procedures, creating compliance uniformity for multi-national suppliers.
Hospital procurement consolidation in the United States is displacing fragmented specialty clinic purchasing patterns. Integrated delivery networks now negotiate calcitonin salmon supply contracts covering 200+ facility systems, replacing individual hospital agreements. This concentration shifts pricing leverage toward group purchasing organizations and compresses margins for injectable segment competitors.
Global Calcitonin Salmon Market Segmentation
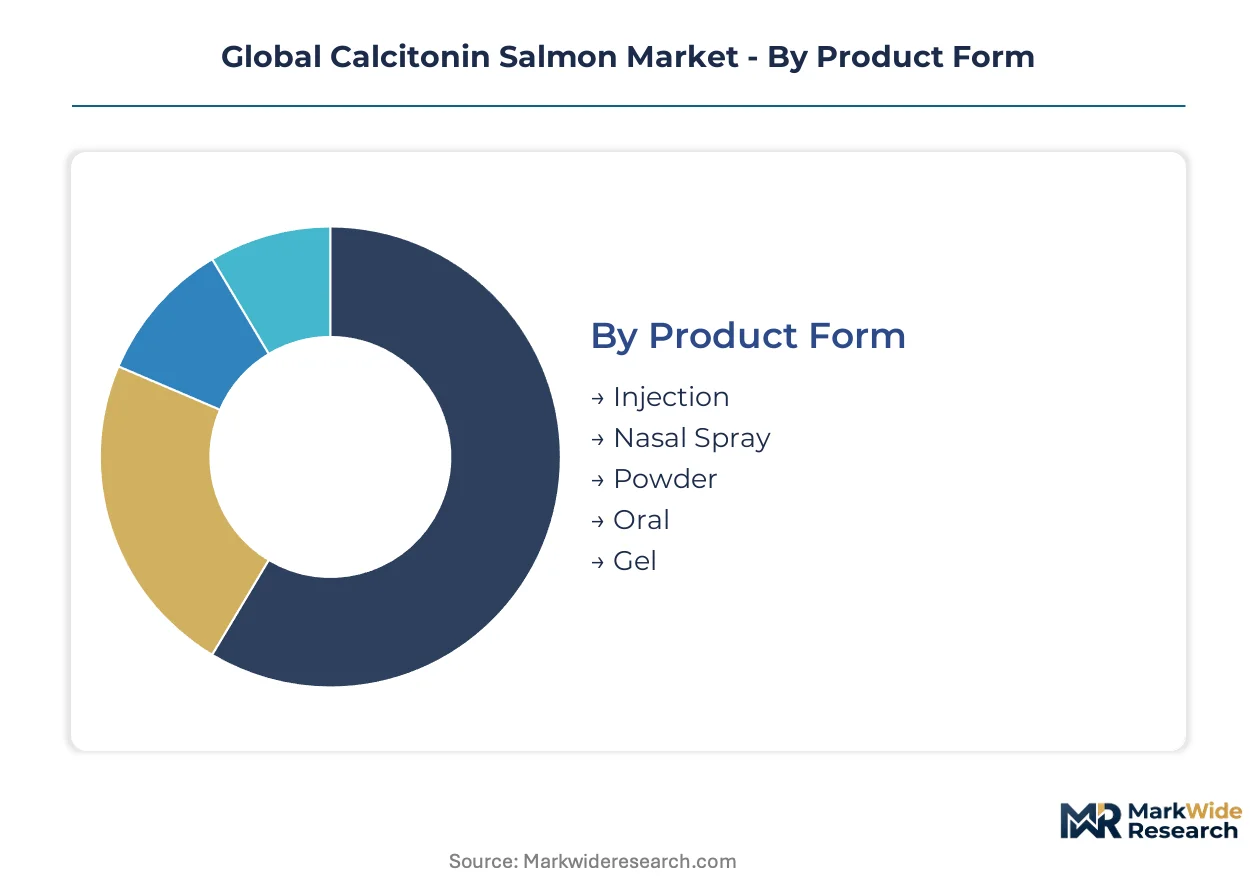
Calcitonin salmon market segmentation reflects divergent clinical workflows across acute care and outpatient settings. Product form selection drives reimbursement coding complexity, while distribution channel choices determine patient access economics in fragmented healthcare systems.
Product Form:
Mature injectable formats dominate hospital procurement budgets, while emerging delivery technologies reshape patient compliance profiles across outpatient channels.
- Injection:Sterile aqueous solutions for subcutaneous or intramuscular administration with established J-code reimbursement in United States Medicare. Demand concentrates in Japanese hospital networks managing acute hypercalcemic crises, constrained by cold-chain logistics requirements and needle-phobia patient dropout rates.
- Nasal Spray:Metered-dose aqueous formulation delivering calcitonin salmon through nasal mucosa absorption with reduced systemic bioavailability versus parenteral routes. German specialty clinics favor this modality for ambulatory osteoporosis maintenance, driven by patient self-administration preferences and reduced nursing labor costs.
- Powder:Lyophilized formulations requiring reconstitution prior to injection, serving research laboratory and compounding pharmacy segments with extended shelf stability.
- Oral:Experimental peptide delivery formats facing enzymatic degradation barriers in gastrointestinal tract, currently limited to preclinical research applications.
- Gel:Topical transdermal preparations with unproven bioequivalence profiles, occupying niche positioning in cosmetic bone health applications outside regulated therapeutic channels.
Injection retains volume leadership; nasal spray holds the steepest expansion curve.
Application Area:
Cost tier stratification separates acute intervention protocols from chronic maintenance therapies, with reimbursement intensity varying across diagnostic categories.
- Osteoporosis Treatment:Primary indication encompassing postmenopausal and glucocorticoid-induced bone loss with calcitonin salmon reducing vertebral fracture risk through osteoclast inhibition. United States specialty clinics drive prescription volume despite bisphosphonate competition, constrained by FDA boxed warnings on malignancy risk with long-term nasal spray exposure.
- Paget's Disease:Chronic bone remodeling disorder characterized by disorganized osteoclast activity with calcitonin salmon providing symptom palliation. French hospital networks maintain formulary inclusion for patients intolerant to bisphosphonate therapy, supported by ANSM reimbursement carve-outs for refractory cases.
- Hypercalcemia Management:Emergency intervention for malignancy-associated or primary hyperparathyroidism with rapid onset calcium-lowering effects, concentrated in tertiary hospital emergency departments.
- Bone Metastases:Palliative application for cancer-related bone pain with limited evidence base, occupying marginal position in oncology supportive care protocols.
Osteoporosis treatment commands the largest addressable population; Paget's disease delivers the highest per-patient revenue intensity.
End User:
Customer type fragmentation reflects shifting site-of-care economics, with institutional purchasers wielding divergent contracting leverage versus dispersed individual consumers.
- Hospitals:Integrated delivery networks and academic medical centers purchasing calcitonin salmon through group purchasing organizations with 340B pricing advantages. Chinese tier-one hospitals in Beijing and Shanghai anchor Asia-Pacific volume through centralized pharmacy procurement.
- Specialty Clinics:Rheumatology and endocrinology practices with direct-to-physician distribution relationships and patient assistance program enrollment capabilities.
- Research Laboratories:Academic and contract research organizations sourcing reference standards and investigational product for bioequivalence studies.
- Home Healthcare Services:Post-acute care agencies managing subcutaneous injection training and compliance monitoring, expanding most quickly in United States Medicare Advantage bundled payment territories.
Hospitals retain volume leadership; home healthcare services hold the steepest expansion curve.
Distribution Channel:
Geography determines channel accessibility, with regulatory barriers fragmenting direct-to-patient models across national boundaries.
- Pharmacies:Community and outpatient dispensaries with calcitonin salmon stocking limited by refrigeration requirements and low prescription turnover. Retail pharmacy chains in Germany and Switzerland maintain specialty cold-chain infrastructure for nasal spray distribution.
- Hospitals Pharmacies:Captive procurement within integrated health systems with formulary committee gatekeeping and therapeutic interchange protocols.
- Online Pharmacies:Mail-order and digital dispensaries with prescription verification requirements varying by national regulator, expanding in Nordic markets with centralized digital health infrastructure.
- Direct Sales:Manufacturer-to-institution contracting for large-volume hospital systems and government tenders, concentrated in China's public hospital procurement reform zones.
Hospital pharmacies retain volume leadership; online pharmacies hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
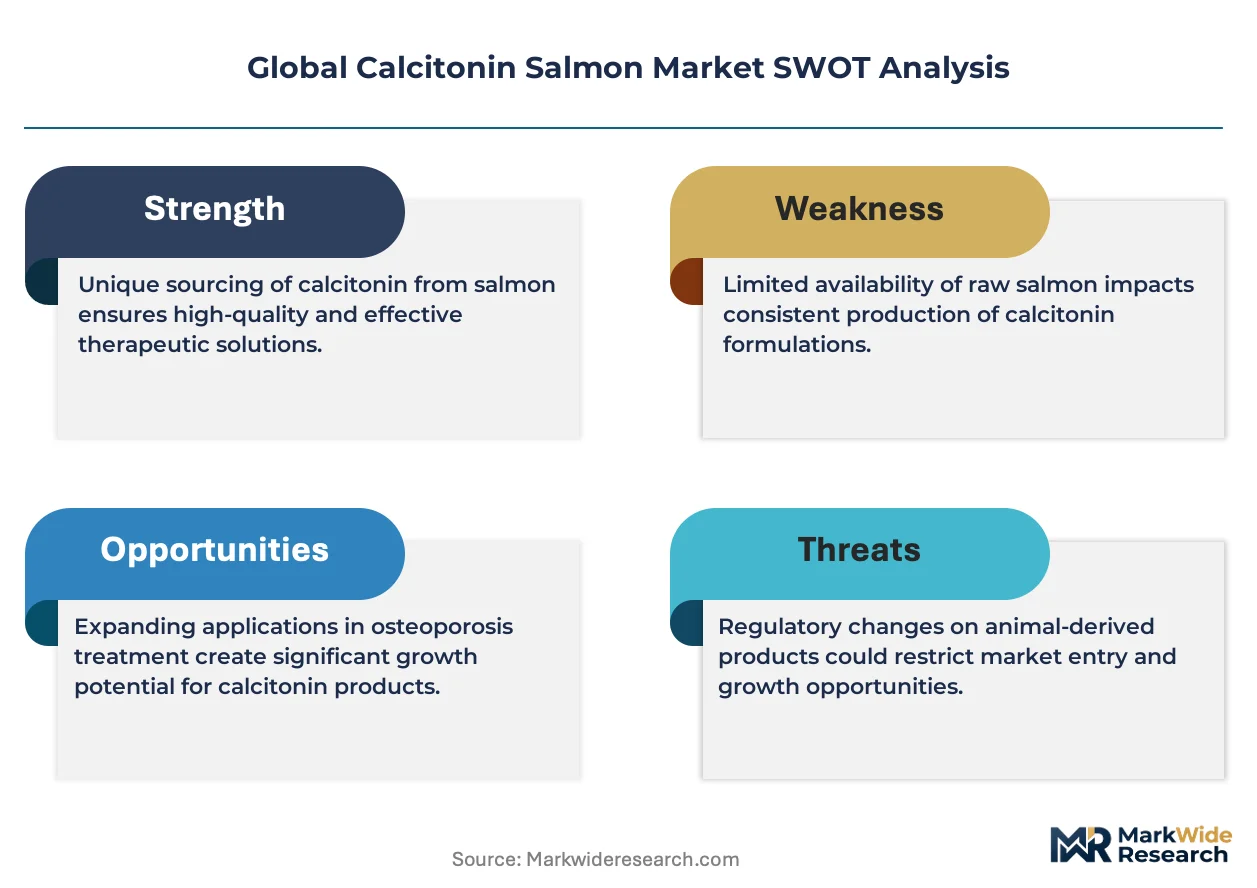
Norwegian aquaculture operations supply ultimobranchial gland raw material to manufacturers across Germany, Japan, and the United States, establishing a trans-Atlantic and trans-Pacific trade corridor that anchors calcitonin salmon production economics.
United States
Hospital procurement consolidation through integrated delivery networks concentrates calcitonin salmon purchasing power among 200-plus facility systems. FDA bioequivalence standards for peptide generics preserve incumbent pricing structures in specialty clinic channels. Boston and San Diego anchor contract manufacturing clusters where solid-phase synthesis expertise pools among specialized workforces.
Germany
Rheumatology practices in Bavaria and North Rhine-Westphalia drive nasal spray demand for ambulatory osteoporosis maintenance. EMA centralized marketing authorization procedures coordinate implementation with French regulators through ANSM collaboration. Frankfurt and Basel host regulatory affairs infrastructure serving multi-national manufacturers navigating European compliance frameworks.
Japan
Aging demographics sustain hospital demand for injectable formulations as first-line bone resorption therapy in acute hypercalcemic crises. PMDA pharmacovigilance mandates require expanded adverse event reporting for long-term nasal spray exposure. Tokyo and Osaka medical centers anchor Asia-Pacific volume through centralized pharmacy procurement.
China
Tier-one hospitals in Beijing and Shanghai compress peptide drug approval timelines under NMPA revised pharmacopoeia standards. Domestic manufacturers expand injectable production capacity for public hospital procurement reform zones. Yangtze River Delta industrial clusters concentrate recombinant DNA synthesis capabilities serving emerging hospital networks.
Global Calcitonin Salmon Market Competitive Landscape
On the supply side, the industry is bifurcated between established pharmaceutical incumbents and specialized peptide contract manufacturers. Player concentration varies by product form, with injectable segments showing tighter oligopoly structures than nasal spray categories. Two strategic archetypes dominate: integrated innovators with decades of formulation expertise, and scale-focused contract manufacturers supplying multiple brand owners. Competitive moves center on regulatory capacity expansion and hybrid production technology licensing.
Among European-based peptide specialists, PolyPeptide Group and Bachem AG exemplify contract manufacturing archetypes that anchor global supply through multi-site production networks. Sanofi occupies a position representing integrated innovators with sustained brand loyalty in hospital networks. These three entities collectively illustrate the competitive tension between captive production and outsourced supply models reshaping manufacturer strategies.
| Leading Market Players |
|---|
| PolyPeptide Group |
| ANHUI ANKE BIOTECHNOLOGY (GROUP) CO., LTD |
| Sanofi |
| Hikma Pharmaceuticals USA Inc. |
| Novartis |
| Bachem AG |
| Aurobindo Pharma Limited |
| Leucadia Pharmaceuticals |
| Fresenius Kabi |
| Others |
Supply & Pricing Matrix
Oslo-to-Rotterdam cold-chain logistics corridors govern ultimobranchial gland transport economics, concentrating upstream pricing leverage among Norwegian aquaculture operators while downstream hospital procurement consolidation in Germany and the United States forces contract manufacturers into volume-discount structures that compress margins across recombinant DNA and solid-phase synthesis tiers.
Pricing Analysis
Current-generation recombinant DNA synthesis commands premium positioning against legacy solid-phase chemical methods and emerging hybrid production architectures. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified hospital formulations from research-grade reference standards and compounding pharmacy alternatives. Price differentiation hinges on FDA bioequivalence certification status and cold-chain logistics bundling. Pricing pressure stems from Chinese domestic manufacturers expanding injectable capacity under NMPA accelerated review pathways. Hospital group purchasing organizations exhibit highest price sensitivity; specialty clinics maintaining direct-to-physician relationships show lowest.
Supply Chain Analysis
Contract manufacturing concentration pools with PolyPeptide Group, Bachem AG, and ANHUI ANKE BIOTECHNOLOGY anchoring global peptide synthesis capacity across European and Asia-Pacific production nodes. Geographic supply concentration centers on Switzerland, Germany, and China for finished formulation, with Norway and Chile for salmon ultimobranchial gland raw material extraction. Raw material dependencies rest on aquaculture yields, lyophilization excipients, and nasal spray metered-dose device components. Single-source vulnerability from Norwegian gland harvesting operations exposes producers to climate-driven supply interruptions. Distribution runs through hospital pharmacy captive procurement and direct manufacturer-to-institution contracting for large-volume tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across synthesis technology generations and regulatory jurisdiction clusters creates multiple niche entry points, particularly as post-acute care model shifts in the United States and Japan fragment end-user concentration previously dominated by hospital networks.
For Market Incumbents: Insulate formulation expertise advantages by deepening captive regulatory affairs infrastructure across FDA, EMA, and NMPA jurisdictions simultaneously. Secure backward integration into recombinant DNA synthesis capabilities to reduce ultimobranchial gland supply exposure. Lock hospital formulary positions through therapeutic interchange protocol control and 340B pricing compliance investment.
For New Entrants and Emerging Players: Pursue home healthcare service channels in United States Medicare Advantage territories where outpatient administration demand outpaces incumbent nasal spray supply. Target Chinese tier-two city hospital networks expanding under public procurement reform where domestic manufacturing credentials accelerate access. Lead with patient-friendly delivery device compatibility against legacy Japanese auto-injector platforms.
For Investors and Strategic Acquirers: Peptide contract manufacturers with EMA centralized marketing authorization track records and solid-phase synthesis workforce depth in Basel or San Diego clusters offer consolidation targets with regulatory moat characteristics. Long-term viability hinges on biosimilar classification clarity resolving generic substitution economics. Watch EMA biosimilar guidance publication timing as inflection signal for European pricing compression velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Capacity Expansion | Dedicated FDA, EMA, and NMPA regulatory affairs infrastructure accelerates multi-jurisdiction submission timelines for peptide generics. |
| Hybrid Production Technology Licensing | Continuous flow chemistry licensing from European contract manufacturers enables 40% yield improvements over batch vessel methods. |
| Home Healthcare Channel Partnership | Post-acute care agency alliances in United States Medicare Advantage territories capture fastest-growing outpatient administration demand. |
| Recombinant DNA Synthesis Scale-Up | Biosynthetic production expansion reduces Norwegian aquaculture yield dependency and stabilizes raw material cost volatility. |
| Hospital System GPO Contracting | Integrated delivery network agreements covering 200-plus facility systems replace fragmented specialty clinic purchasing patterns. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA peptide bioequivalence guidance documents, EMA centralized marketing authorization procedures, and NMPA pharmacopoeia revision notices. Primary interviews engaged peptide synthesis chemists, hospital formulary directors, regulatory affairs leads at contract manufacturers, and group purchasing organization contract managers. Secondary validation drew from ClinicalTrials.gov entries, hospital procurement databases, and customs records tracking ultimobranchial gland trade flows. Bottom-up volume estimates triangulated against top-down market sizing across injection, nasal spray, and emerging delivery form segments.
Forecast inputs incorporate patient population epidemiology, reimbursement code stability, and synthesis technology adoption curves across the projection horizon. Segmentation dimensions modeled include product form, application area, end-user type, and regional regulatory cluster. CAGRs derive from historical volume progression adjusted for technology substitution effects and procurement consolidation velocity. Industry-specific inputs encompass PMDA pharmacovigilance mandate implementation timing and Chinese public hospital procurement reform zone expansion.
Macroeconomic conditions sit as an overlay; deviation in aquaculture commodity pricing, healthcare reimbursement intensity, or cross-border logistics costs would shift the trajectory. Forecasts reflect assumptions around regulatory timeline stability and biosimilar classification resolution. Quarterly review of EMA guidance publication schedules, NMPA approval velocity metrics, and hospital GPO contract award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Monoclonal Antibody Therapeutics Market
Pharmaceuticals
Budesonide Market
Pharmaceuticals
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Compounding Chemotherapy Market
Pharmaceuticals
Antiviral Drugs Market
Pharmaceuticals
Global Autism Spectrum Disorder Therapeutics Market
Pharmaceuticals
Subcutaneous Immunoglobulin Market
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Global Autoimmune Drugs Market
Pharmaceuticals
Urban Pharma Micro-Depot and Delivery Network Market
Pharmaceuticals
Liquid Filled Hard Capsules Market
Pharmaceuticals
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Global Antipsychotic Drugs Market
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Global Fibrinogen Concentrates Market