
 Global Corticosteroids Market | 2026-2036
Global Corticosteroids Market Size, Share, and Industry Trends Forecast 2026-2036
Global Corticosteroids Market Foresight
Continuous manufacturing of corticosteroid APIs is tilting production economics toward integrated sites that combine fermentation, chemical synthesis, and finished-dose packaging under one roof. Pfizer leverages its North American manufacturing footprint to sustain supply security for hospital-grade injectable corticosteroids. Cipla anchors its competitive stance through backward integration into API production for respiratory formulations in India. Teva Pharmaceutical Industries competes aggressively in the oral generics segment across European reimbursement markets.
Corticosteroids comprise a class of steroid hormones synthesized from cholesterol derivatives, featuring a characteristic cyclopentanoperhydrophenanthrene ring structure with specific hydroxyl and ketone substitutions that determine glucocorticoid versus mineralocorticoid activity. These compounds modulate gene transcription through intracellular glucocorticoid receptors, producing anti-inflammatory and immunosuppressive effects exploited across rheumatology, pulmonology, dermatology, and ophthalmology. Among product types, dexamethasone retains dominant hospital share due to its potent anti-inflammatory profile and low mineralocorticoid activity, while inhaler formulations for asthma command premium pricing in outpatient settings. Injectable solutions represent the fastest-expanding formulation category as acute care protocols standardize perioperative and septic shock dosing regimens.
The FDA's Current Good Manufacturing Practice enforcement and the EMA's tightened impurity thresholds for nitrosamine contamination in chemically synthesized APIs are elevating compliance costs for generic manufacturers. India's CDSCO alignment with ICH Q3D guidelines on elemental impurities is forcing domestic API producers toward upgraded purification infrastructure. Stakeholders must monitor how biosimilar IL-6 and JAK inhibitors reshape corticosteroid positioning in rheumatoid arthritis and lupus treatment algorithms.
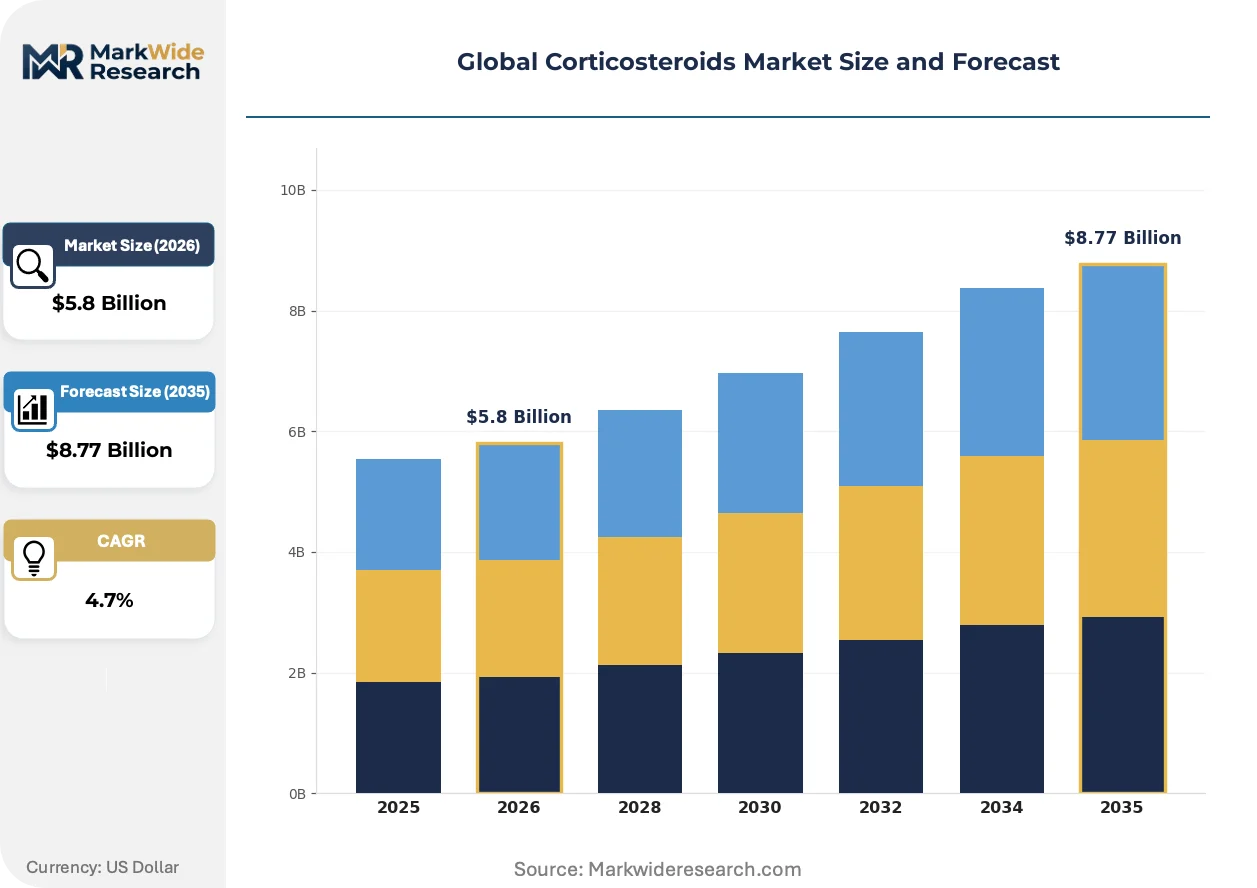
Market Dynamics
Continuous manufacturing is compressing batch-to-batch variability in corticosteroid API production, concentrating investment in integrated fermentation-to-finished-dose facilities that merge chemical synthesis with sterile fill-finish operations under unified quality systems.
Growth Catalysts
- FDA ANDA Pathway Streamlining:Accelerated review timelines for complex generic inhalers are pulling additional entrants into the respiratory corticosteroid segment.
- Perioperative Protocol Standardization:Hospital formularies are embedding injectable dexamethasone into enhanced recovery after surgery pathways across acute care networks.
- Hyderabad-Gujarat Manufacturing Corridors:API-to-finished-dose integration in these Indian clusters is shortening supply lead times for export markets.
Market Restraints
- Nitrosamine Impurity Scrutiny:EMA's tightened thresholds for chemically synthesized APIs are forcing costly purification retrofits and extended validation cycles.
- Cholesterol Derivative Feedstock Volatility:Sterol precursor supply concentrates among a limited base of fermentation-derived and plant-extracted sources, exposing margin pressure.
- IL-6 Inhibitor Biosimilar Entry:Rheumatology treatment algorithms are repositioning corticosteroids as bridging rather than maintenance therapy in autoimmune indications.
Strategic Opportunities
- Ophthalmic Sustained-Release Formulations:Intravitreal implants and depot injections for macular edema represent underpenetrated therapeutic positioning with premium pricing potential.
- CDSCO-ICH Q3D Alignment:India's elemental impurity guideline adoption is creating first-mover advantage for domestic API producers with upgraded ICP-MS capabilities.
- Continuous Processing Technology Convergence:Integration of real-time release testing with continuous crystallization is enabling smaller-footprint, higher-throughput manufacturing assets.
Industry Challenges
- Sterile Manufacturing Workforce Scarcity:Aseptic processing and isolator technology expertise gaps are extending qualification timelines for new injectable lines.
- Legacy Quality System Integration:Paper-based batch records and disparate ERP platforms are creating data integrity vulnerabilities during FDA pre-approval inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Corticosteroids Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocortisone, Prednisolone, Dexamethasone, Betamethasone, Triamcinolone, Methylprednisolone Therapy Area: Asthma, Rheumatoid Arthritis, Allergic Rhinitis, Psoriasis, Lupus, Inflammatory Bowel Disease Formulation: Topical Cream, Oral Tablets, Injectable Solutions, Nasal Spray, Ophthalmic Drops, Inhalers End User: Hospitals, Specialty Clinics, Diagnostic Laboratories, Outpatient Care Centers, Pharmacies |
| Companies Covered | Pfizer, Novartis, GlaxoSmithKline, Merck, AstraZeneca, Sanofi, Johnson & Johnson, Cipla, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Corticosteroids Market Shifts & Advancements
Manufacturing modality shifts and regulatory data integrity mandates are restructuring how corticosteroid producers validate processes, manage supply networks, and compete on quality documentation rather than unit cost alone.
Continuous direct compression for oral solid dosage forms is migrating from pilot-scale demonstration to commercial deployment among generic manufacturers seeking reduced hold times and real-time release capabilities. Mid-tier producers in India and Eastern Europe are retrofitting existing suites with PAT-enabled feed frames and roller compaction modules. This technology trajectory is compressing batch release cycles from weeks to days, enabling just-in-time inventory models for high-volume oral corticosteroid tablets.
REACH authorization requirements for residual solvent classification are compelling reformulation of corticosteroid synthesis pathways across European API supply chains. Manufacturers are substituting dichloromethane-dependent crystallization steps with alternative solvent systems or supercritical fluid extraction to maintain market access. The regulatory pressure falls most heavily on legacy multi-purpose facilities lacking dedicated containment infrastructure for high-potency compounds.
Hospital procurement consortia are consolidating corticosteroid purchasing through single-source tender frameworks that bundle injectable, oral, and inhaler formulations under multi-year agreements. Integrated delivery networks in the United States and Germany are displacing fragmented distributor relationships with direct manufacturer contracts tied to compliance dashboards and shortage risk mitigation clauses. This concentration pattern is most visible in tertiary academic medical centers standardizing perioperative and critical care formularies.
Global Corticosteroids Market Segmentation
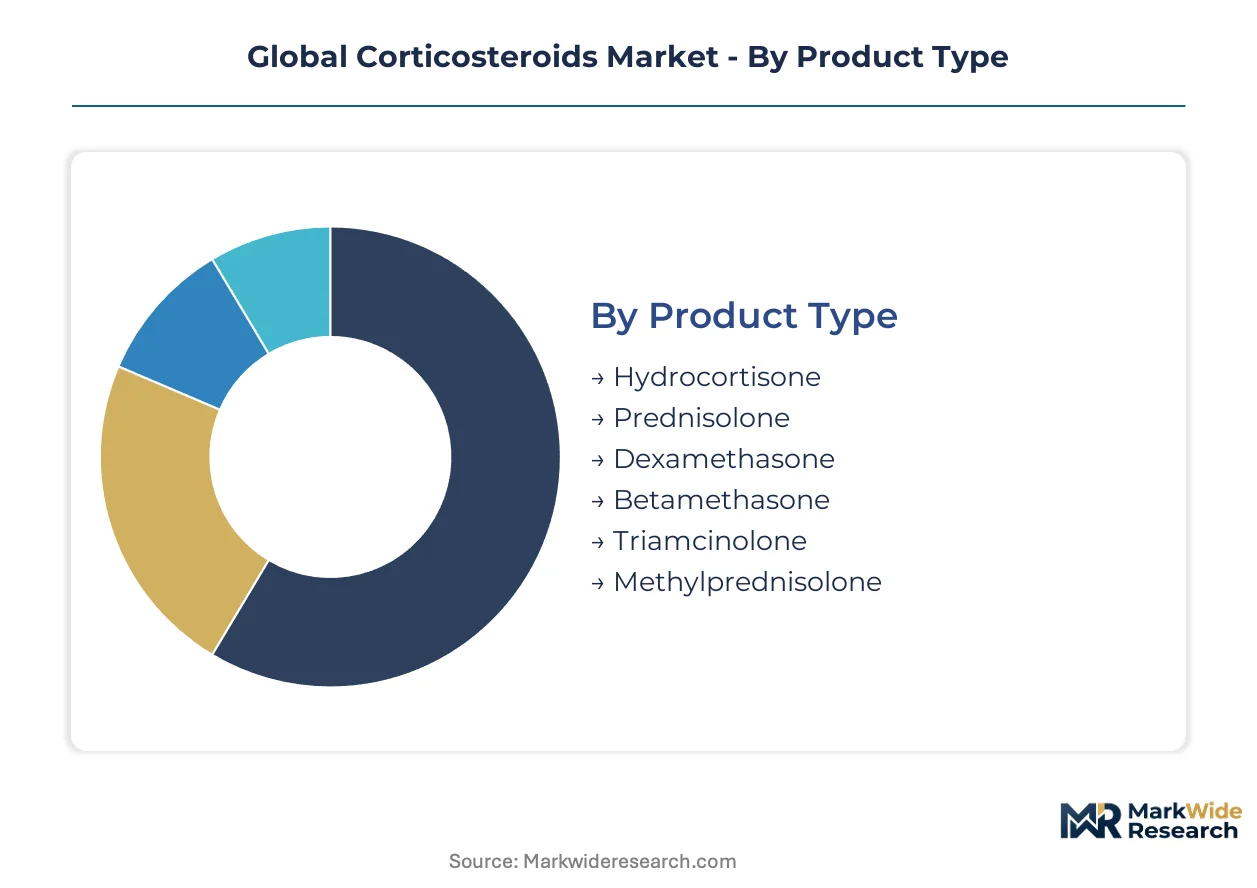
Corticosteroid segmentation reveals how formulation complexity and therapy specificity reshape service requirements across the value chain. Product chemistry, delivery mechanism, and care setting each impose distinct technical support, cold-chain, and training obligations on suppliers.
Product Type:
After-sales intensity escalates with molecular potency and formulation sophistication, as high-potency synthetic corticosteroids demand specialized handling protocols and stability monitoring throughout shelf life.
- Dexamethasone:Synthetic fluorinated corticosteroid with 25-30 times the glucocorticoid potency of hydrocortisone and negligible mineralocorticoid activity. Hospital procurement in the United States, Germany, and India is embedding this molecule into perioperative and septic shock protocols, driving demand for sterile injectable vials with extended stability data.
- Prednisolone:Active metabolite of prednisone with direct hepatic availability, formulated predominantly as oral tablets and ophthalmic suspensions. Rheumatology clinics across European reimbursement markets are standardizing this agent for maintenance therapy in autoimmune conditions, concentrating volume in specialty pharmacy distribution channels.
- Hydrocortisone:Natural cortisol substitute with balanced glucocorticoid-mineralocorticoid activity, essential for adrenal insufficiency replacement therapy.
- Betamethasone:Long-acting synthetic with high glucocorticoid selectivity, favored in prenatal maturation and dermatological depot applications.
- Triamcinolone:Intermediate-acting compound with reduced sodium-retaining effects, deployed in intra-articular and intravitreal sustained-release formulations.
- Methylprednisolone:Methylated derivative with enhanced anti-inflammatory potency, standard in high-dose pulse therapy for acute neurological and renal indications.
By volume, hydrocortisone leads due to chronic replacement therapy scale. By growth pace, dexamethasone is ahead on hospital protocol standardization.
Therapy Area:
Application-driven cost tiering separates acute episodic conditions from chronic maintenance diseases, with reimbursement intensity and treatment duration determining commercial attractiveness.
- Asthma:Chronic inflammatory airway disease requiring long-term controller therapy with inhaled corticosteroids as first-line maintenance. Pediatric and adult populations in outpatient settings across the United States and India are driving volume for combination inhaler devices with dose counters and adherence monitoring.
- Rheumatoid Arthritis:Systemic autoimmune joint disease where corticosteroids serve as bridging therapy during DMARD initiation. German and French rheumatology practices are repositioning these agents amid IL-6 inhibitor biosimilar entry, compressing maintenance dosing windows.
- Allergic Rhinitis:Seasonal and perennial nasal mucosa inflammation managed with intranasal corticosteroid sprays as preferred pharmacotherapy.
- Psoriasis:Chronic cutaneous inflammatory condition treated with topical, intralesional, and systemic corticosteroid regimens based on severity stratification.
- Lupus:Multisystem autoimmune disease requiring corticosteroid pulses for flares and low-dose maintenance for organ protection.
- Inflammatory Bowel Disease:Crohn's disease and ulcerative colitis management incorporating budesonide formulations for targeted ileocecal release.
Asthma generates the highest prescription volume. Rheumatoid arthritis is contracting fastest as biologic alternatives capture maintenance share.
Formulation:
Manufacturing margin stratification follows sterile processing complexity, with parenteral and inhalation forms commanding premium positioning over commodity oral solids.
- Injectable Solutions:Sterile aqueous or suspension formulations for intravenous, intramuscular, or intra-articular administration requiring aseptic fill-finish and endotoxin control. Hyderabad and Gujarat manufacturing corridors are expanding capacity for hospital-grade vials and prefilled syringes to supply export markets.
- Inhalers:Pressurized metered-dose and dry-powder devices delivering corticosteroid particles to lower airways with precise aerodynamic sizing. FDA streamlined ANDA pathways are accelerating complex generic entry for respiratory combinations in the United States.
- Topical Cream:Semisolid emulsions for dermatological application with permeation-enhancing vehicle systems.
- Oral Tablets:Immediate and modified-release solid dosage forms for systemic corticosteroid delivery.
- Nasal Spray:Aqueous or suspension formulations for localized allergic rhinitis treatment with pump-actuated dosing.
- Ophthalmic Drops:Sterile solutions and suspensions for anterior segment inflammation with preservative-free options for chronic use.
Oral tablets dominate unit volume. Injectable solutions are climbing fastest on acute care protocol embedding.
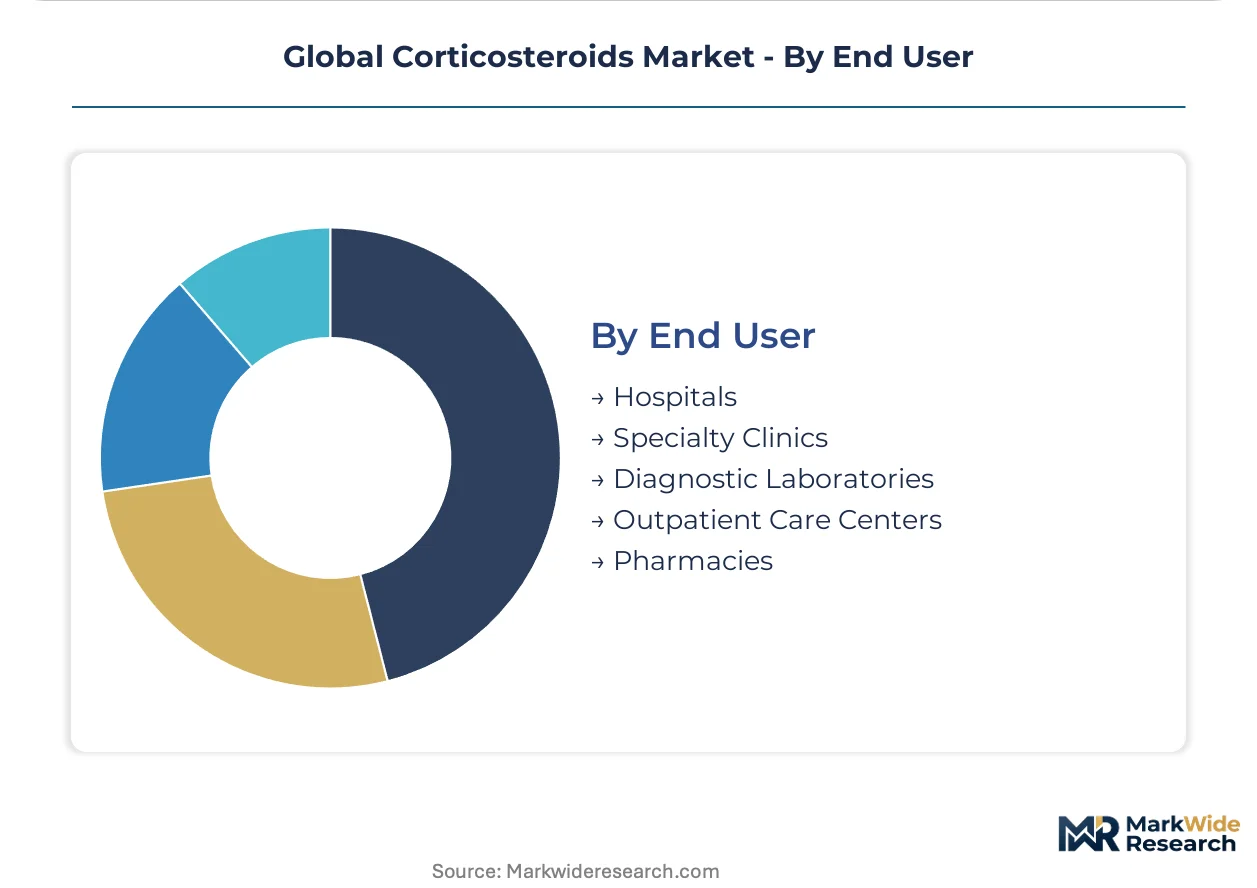
End User:
Customer-type concentration patterns reflect care setting reimbursement authority and formulary control leverage across integrated delivery networks.
- Hospitals:Acute care institutions with centralized pharmacy and therapeutics committees governing perioperative, critical care, and emergency department corticosteroid use. Tertiary academic medical centers in the United States and Germany are consolidating purchasing through single-source tender frameworks bundling multiple formulations.
- Specialty Clinics:Rheumatology, pulmonology, and dermatology practices with direct specialty pharmacy relationships and prior authorization expertise.
- Outpatient Care Centers:Ambulatory surgery and infusion facilities administering parenteral corticosteroids outside traditional hospital settings.
- Pharmacies:Retail and mail-order dispensers handling chronic oral and topical prescriptions with generic substitution protocols.
- Diagnostic Laboratories:Reference labs employing corticosteroids in stimulation testing and research applications.
Hospitals anchor procurement volume. Specialty clinics are gaining influence fastest on biologic co-prescribing complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian API-to-finished-dose corridors export dexamethasone injectables to hospital networks across the United States, Germany, and United Kingdom. European REACH solvent regulations and FDA sterility mandates are reshaping where fermentation-derived corticosteroid precursors undergo final chemical synthesis and fill-finish packaging.
United States
Hospital procurement consortia bundle perioperative dexamethasone into single-source tender frameworks for acute care networks. FDA streamlined ANDA pathways for complex generic inhalers are accelerating respiratory corticosteroid entry. Tertiary academic medical centers in Boston and Houston are consolidating formulary control through direct manufacturer contracts with shortage mitigation clauses.
Germany
Rheumatology practices reposition corticosteroids as bridging therapy amid IL-6 inhibitor biosimilar penetration in autoimmune maintenance protocols. EMA tightened nitrosamine thresholds for chemically synthesized APIs are forcing costly purification retrofits among legacy multi-purpose facilities. The Rhine-Ruhr pharmaceutical cluster is upgrading ICP-MS capabilities for elemental impurity testing under ICH Q3D alignment.
India
Injectable manufacturing corridors in Hyderabad and Gujarat are deepening API-to-finished-dose integration to shorten export lead times. CDSCO alignment with ICH Q3D guidelines on elemental impurities is driving domestic producers toward upgraded purification infrastructure. Ahmedabad-based fermentation facilities are expanding capacity for cholesterol-derived sterol precursors serving corticosteroid synthesis.
United Kingdom
NHS hospital pharmacy and therapeutics committees standardize perioperative corticosteroid protocols across integrated care systems. MHRA post-Brexit regulatory autonomy is maintaining EMA-equivalent impurity thresholds while streamlining national batch release procedures. The Cambridge-Oxford-London life sciences triangle hosts contract development organizations specializing in ophthalmic sustained-release formulation development.
Japan
PMDA quality system inspections emphasize data integrity for continuous manufacturing transitions in oral solid dosage production. Domestic inhaler device manufacturers are partnering with global corticosteroid API suppliers for combination product development. The Kansai region's Osaka-based pharmaceutical cluster maintains specialized capabilities in high-potency steroid handling and containment.
Global Corticosteroids Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation complexity tiers. The market structure concentrates around integrated multinationals with hospital contract leverage, mid-tier generic houses with API backward integration, and regional injectable specialists. Three archetypes dominate: North American supply-security anchors, Indian cost-integrated exporters, and European respiratory device innovators. Competitive moves center on sterile manufacturing capacity expansion and continuous processing technology licensing.
Among North American supply-security anchors, Pfizer occupies a position exemplifying hospital-grade injectable corticosteroid reliability. Indian cost-integrated exporters include Cipla, which represents backward-integrated API production for respiratory formulations. Teva Pharmaceutical Industries sits within the European complex generic tier, anchoring oral corticosteroid positioning across reimbursement markets. These three companies illustrate how geographic manufacturing footprint and regulatory compliance depth determine competitive viability under tightening FDA and EMA quality mandates.
| Leading Market Players |
|---|
| Pfizer |
| Novartis |
| GlaxoSmithKline |
| Merck |
| AstraZeneca |
| Sanofi |
| Johnson & Johnson |
| Cipla |
| Teva Pharmaceutical Industries |
| Others |
Supply & Pricing Matrix
Cholesterol derivative feedstock volatility compresses margin buffers across synthetic corticosteroid production, widening spreads between fermentation-integrated premium suppliers and spot-market dependent generic houses while accelerating geographic consolidation toward Indian API corridors.
Pricing Analysis
Continuous manufacturing technology adoption separates pricing tiers between legacy batch facilities and PAT-enabled integrated sites. Three-tier pricing structure across premium, standard, and economy levels reflects sterile certification grade, elemental impurity compliance depth, and volume scale commitments. Cost compression in economy-tier oral solids is intensifying because of Indian API export competition. Hospital procurement consortia exhibit lowest price sensitivity due to shortage risk mitigation priorities, while retail pharmacies face highest sensitivity from generic substitution mandates.
Supply Chain Analysis
Tariff exposure between United States and Chinese heparin precursor suppliers dominates supply chain risk planning for corticosteroid API producers. Fermentation-derived sterol production concentrates in India, China, and selected European facilities. Synthesis pathways draw from cholesterol derivatives, specialized solvents, and high-potency containment equipment. Single-source vulnerability persists in isolator technology and aseptic fill-finish engineering expertise. Distribution runs through hospital procurement consortia, specialty pharmacy networks, and integrated delivery network direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital formulary contracting represents a service-attach opportunity where compliance dashboarding and shortage risk mitigation clauses expand recurring revenue faster than commodity vial supply.
For Market Incumbents: Insulate sterile manufacturing margins through captive production of nitrosamine-compliant APIs in Hyderabad and Gujarat corridors. Prioritize EMA-aligned ICP-MS elemental impurity capabilities ahead of CDSCO enforcement waves. Lock multi-year tender frameworks with shortage penalty clauses before IL-6 inhibitor biosimilars compress rheumatology corticosteroid positioning. For New Entrants and Emerging Players: Build out ophthalmic sustained-release formulation capabilities in the Cambridge-Oxford-London triangle where intravitreal implant development expertise concentrates. Target CDSCO-ICH Q3D first-mover positioning among domestic Indian API producers with upgraded purification infrastructure. Pursue FDA streamlined ANDA pathways for complex generic inhalers through device-CMO partnerships. For Investors and Strategic Acquirers: The market sits at a compliance-investment phase that favors mid-tier specialists with backward-integrated API capacity and sterile fill-finish assets. Long-term viability hinges on continuous processing technology licensing positions and real-time release testing capabilities. Watch IL-6 and JAK inhibitor biosimilar penetration rates in rheumatology as corticosteroid maintenance share inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Scale-Up | PAT-enabled integration reduces batch release cycles from weeks to days for oral corticosteroid tablets. |
| API Backward Integration | Cipla's captive sterol fermentation in Ahmedabad insulates against cholesterol derivative feedstock volatility. |
| Regulatory Compliance Investment | EMA nitrosamine threshold alignment forces costly purification retrofits among legacy multi-purpose facilities. |
| Hospital System Partnership | Pfizer's direct contracts with Boston and Houston academic centers bundle perioperative dexamethasone across formulations. |
| Ophthalmic Formulation Development | Intravitreal implant capabilities in the UK life sciences triangle access premium macular edema positioning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA ANDA filings, EMA inspection reports, CDSCO regulatory circulars, and hospital procurement databases across the United States, Germany, India, and United Kingdom. Interviews with sterile manufacturing plant managers, hospital pharmacy and therapeutics committee directors, regulatory affairs leads at generic houses, and GPO contracts managers informed supply chain and pricing dynamics. Bottom-up volume modeling triangulates against top-down market sizing from trade flow analysis and API production capacity disclosures.
Forecast inputs span product type chemistry, formulation complexity tier, therapy area reimbursement intensity, and regional regulatory cluster stringency across the analysis window. Segmentation dimensions include molecular potency class, sterile processing requirement, acute versus chronic care setting, and hospital procurement consolidation level. CAGRs derive from protocol standardization trajectories, biosimilar displacement curves, and manufacturing technology adoption S-curves.
Practitioners should monitor IL-6 inhibitor biosimilar launch cadence, nitrosamine enforcement actions by EMA and FDA, and continuous manufacturing patent litigation for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Meperidine Drugs Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Systemic Antibiotics Market
Pharmaceuticals
Prothrombin Complex Concentrate (PCC) Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Risedronate Sodium Market
Pharmaceuticals
Structured Product Label Management Market
Pharmaceuticals
Global Desmopressin Market
Pharmaceuticals
Riociguat Tablets Market
Pharmaceuticals
Global Acyclovir Market
Pharmaceuticals
Cervical Cancer Drugs Market
Pharmaceuticals
Pharmacy Market
Pharmaceuticals
Global Thyroid Cancer Drugs Market
Pharmaceuticals
Global Pharmerging Market
Pharmaceuticals
Global Pharmaceutical Drug Delivery Market
Pharmaceuticals
Acetylspiramycin Market