
 Ultra-Secure Smartphone Market | 2026-2036
Ultra-Secure Smartphone Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra-Secure Smartphone Market Intelligence
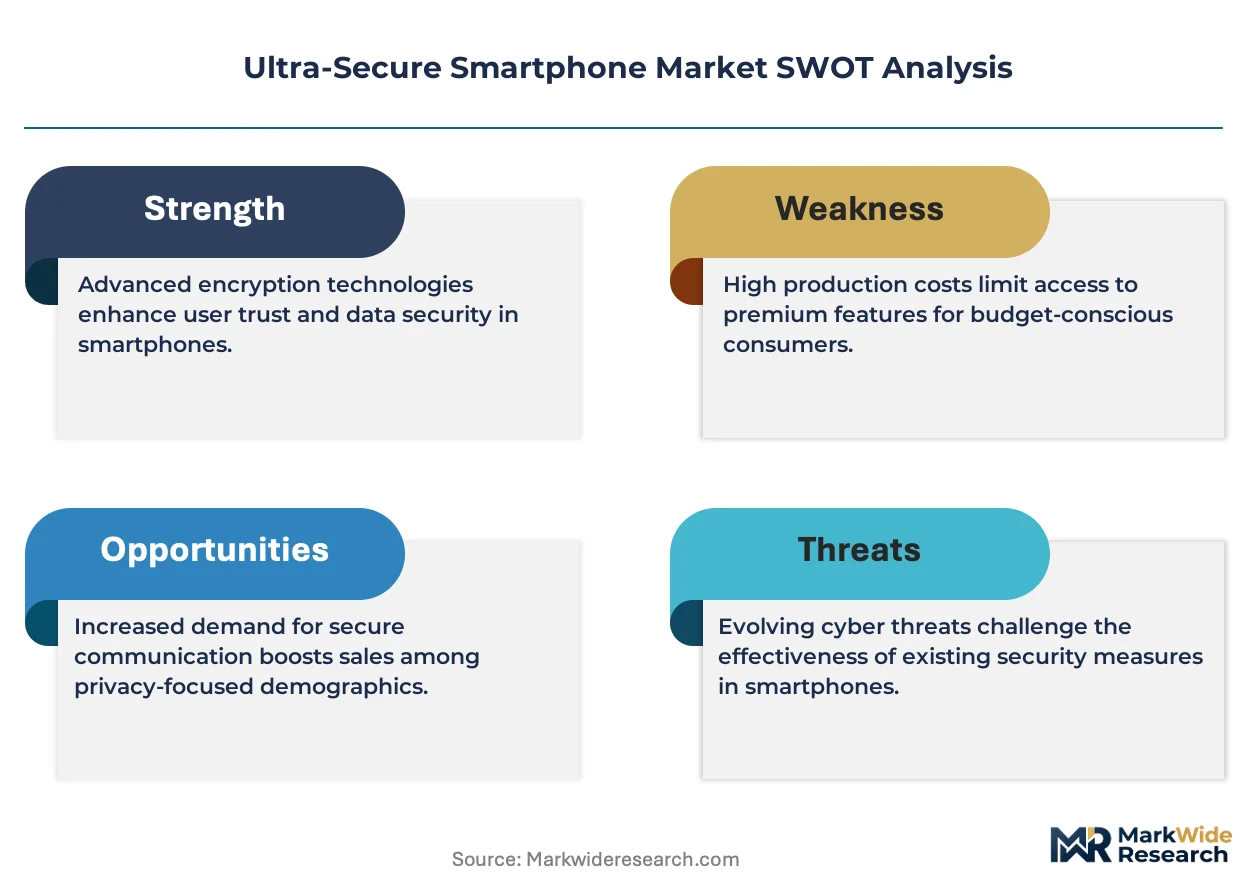
Hardware-based trusted execution environments is narrowing the attack surface for device-level compromise across the ultra-secure smartphone category. Apple sustains consumer-facing encryption leadership through its proprietary secure enclave architecture. BlackBerry Limited anchors enterprise and government channels with hardened Android distributions. Bittium specializes in NATO-aligned defense communications with Finnish manufacturing pedigree.
An ultra-secure smartphone integrates dedicated hardware security modules, tamper-resistant enclosures, and cryptographically verified boot chains to protect voice, data, and messaging against interception or forensic extraction. These devices typically incorporate discrete secure elements certified to Common Criteria EAL4+ or higher, with physical self-destruct mechanisms triggered by chassis breach detection. Military-grade phones command premium positioning due to extended certification cycles and sovereign procurement requirements, while secure enclave implementations see fastest growth as biometric authentication becomes mandatory for enterprise mobility programs. Business Devices concentrate margin pools through volume licensing and managed security service attachments.
The European Union's Cyber Resilience Act and CE marking requirements now mandate vulnerability disclosure timelines and automatic security update delivery for connected devices sold across member states. The United States National Security Agency publishes Commercial Solutions for Classified program criteria that gate federal smartphone procurement. Germany's Federal Office for Information Security evaluates and certifies devices through its technical guidelines. Stakeholders must track divergence between EU hardware certification mandates and US software supply chain attestation requirements as procurement specifications fragment across allied defense markets.
Market Dynamics
Post-quantum cryptography migration is compressing product development cycles across the ultra-secure smartphone supply chain, forcing hardware architects to redesign secure enclaves before NIST standards finalize.
Growth Catalysts
- EU Cyber Resilience Act:Hardware-level secure enclave mandates from Brussels are accelerating certification investments by device manufacturers seeking CE marking access.
- Defense procurement volumes:NATO-aligned intelligence agencies and defense contractors in Germany, Israel, and the United States are consolidating orders under sovereign communications infrastructure programs.
- Biometric authentication mandates:Enterprise mobility programs are requiring fingerprint and facial recognition modules, driving demand for discrete secure elements certified to Common Criteria EAL4+.
Market Restraints
- Extended certification cycles:Military-grade Common Criteria evaluations consume 18-36 months, freezing design iterations and inflating working capital requirements.
- Tamper-resistant enclosure costs:Physical self-destruct mechanisms and chassis breach detection systems add 40-60% to bill-of-materials versus standard smartphones.
- Finnish manufacturing concentration:NATO-aligned defense communications production clusters in Northern Europe, creating single-source vulnerability for hardened device assembly.
Strategic Opportunities
- Managed security service attachments:Business device segments are unbundling hardware from subscription-based threat monitoring and secure voice routing.
- Post-quantum algorithm integration:Lattice-based cryptography and hash-based signatures are converging with existing secure boot chains ahead of cryptanalytic threats.
- German BSI certification pipeline:The Federal Office for Information Security technical guidelines are opening procurement channels for non-military government users previously served by foreign vendors.
Industry Challenges
- Cryptographic engineering talent scarcity:Hardware security module design requires specialized firmware architects fluent in side-channel attack mitigation, with limited training pipelines outside defense contractors.
- Fragmented transatlantic standards:Divergence between EU hardware certification mandates and US software supply chain attestation requirements forces dual-track compliance investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra-Secure Smartphone Market |
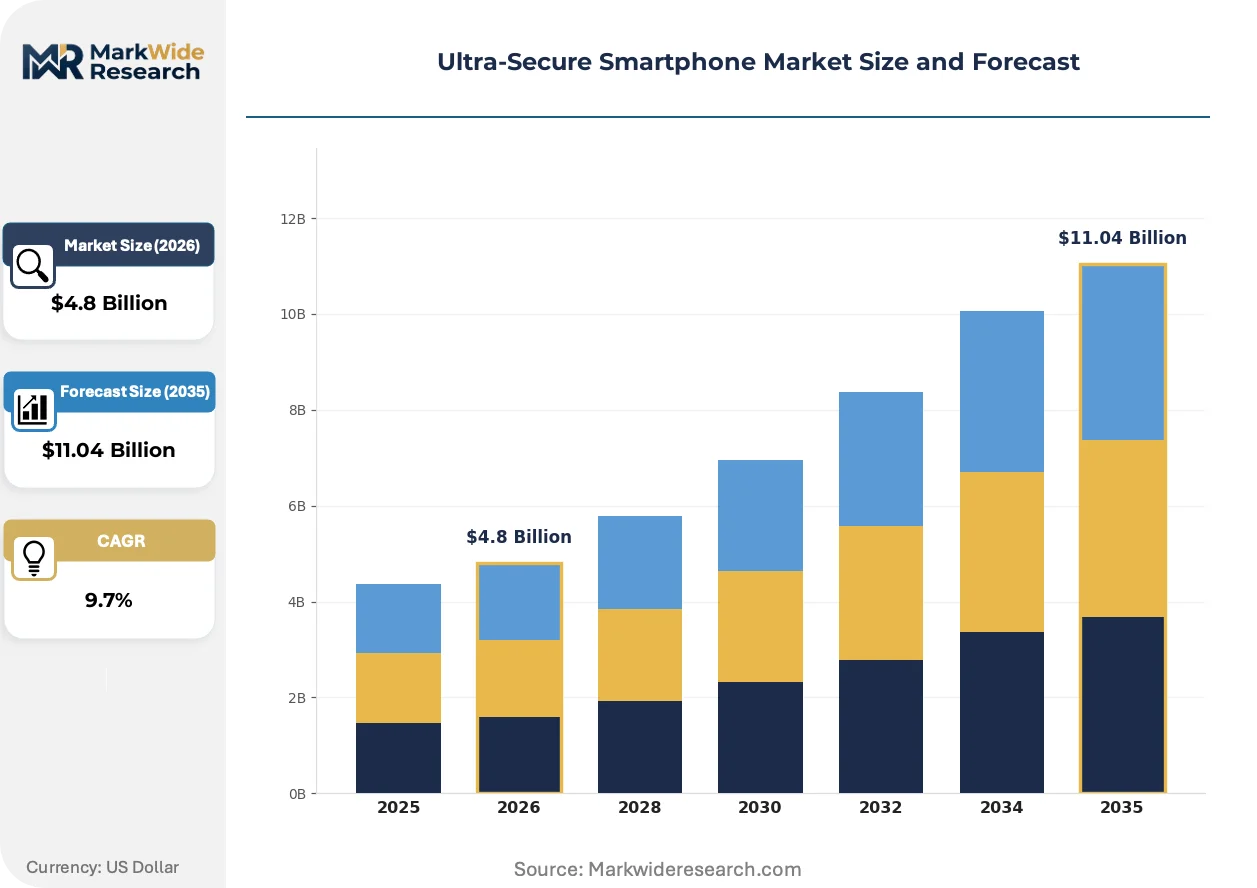
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Devices, Business Devices, Military-grade Phones, Health-focused Phones Security Features: Biometric Authentication, End-to-End Encryption, Remote Wipe, Secure Enclave End User: Government Agencies, Corporations, Healthcare Providers, Individual Consumers Distribution Channel: Online Retail, Brick-and-Mortar Stores, B2B Sales, Mobile Carriers |
| Companies Covered | Sirin Labs, Apple, Purism, Samsung, Google, Bittium, BlackBerry Limited, GSMK GmbH, Katim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra-Secure Smartphone Market Strategic Shifts & Innovations
Secure execution environments are undergoing architectural transformation as virtualization techniques displace discrete hardware modules, while regulatory pressure on vulnerability disclosure compresses product lifecycles.
Trusted execution environments are virtualizing secure enclave functions previously handled by dedicated hardware security modules. Enterprise mobility administrators are adopting these software-defined alternatives to reduce per-device provisioning costs. This shift is virtualizing the boundary between consumer-grade silicon and military-grade isolation, enabling faster patch cycles without hardware respins.
CE marking requirements under the EU Cyber Resilience Act now mandate automatic security update delivery and standardized vulnerability disclosure timelines. Device manufacturers must maintain update infrastructure for five years post-sale or forfeit market access. Enterprise and government channels face the steepest compliance costs, with many vendors restructuring firmware teams to meet the 24-hour critical patch window.
Outcome-based contracting is displacing perpetual licensing in defense and intelligence procurement. Agencies in Germany and Israel now specify operational availability metrics rather than device counts, forcing vendors to retain ownership of fielded hardware. This model concentrates margin risk with manufacturers while capturing lifecycle maintenance revenue previously lost to third-party integrators.
Ultra-Secure Smartphone Market Segmentation
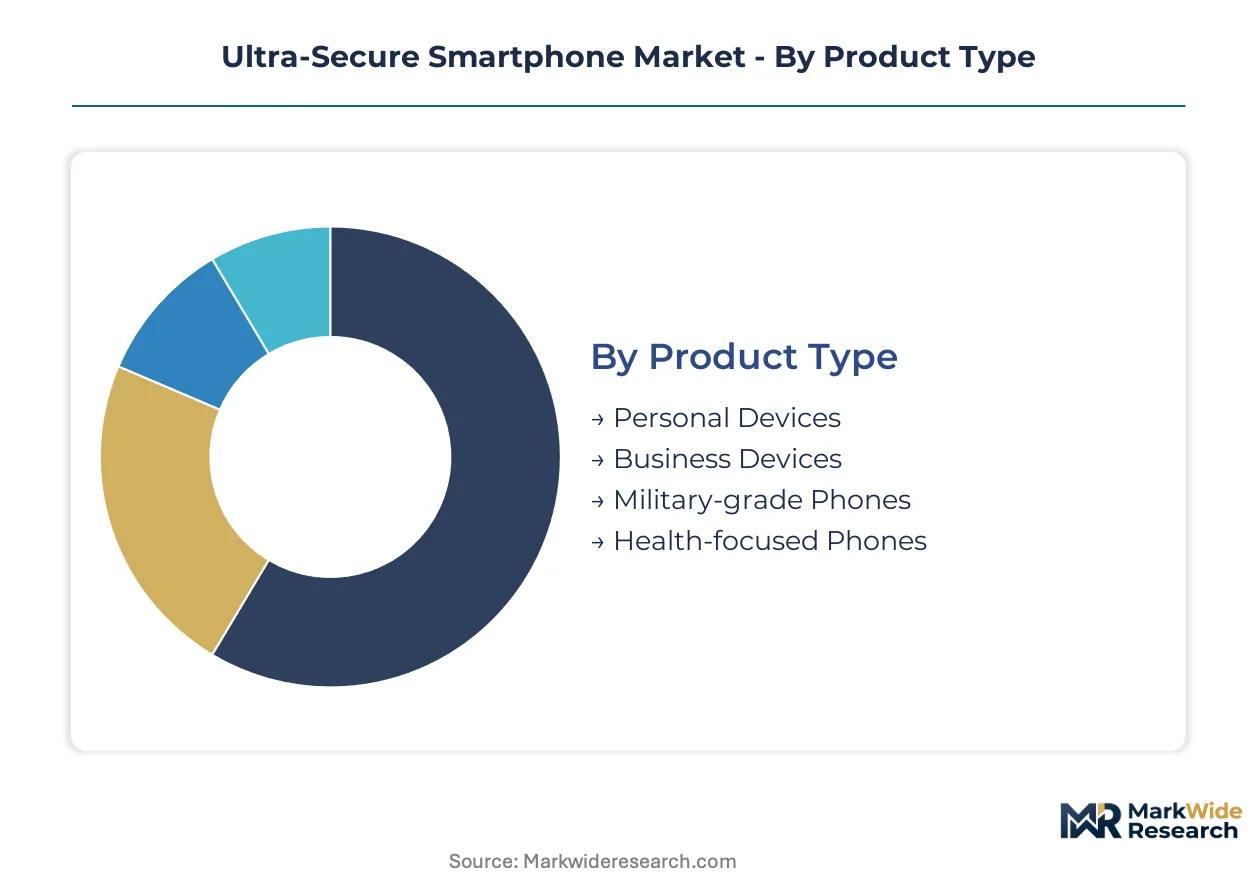
Ultra-secure smartphone procurement splits across sovereign defense programs, enterprise mobility mandates, and consumer privacy premiums. Each segment carries distinct certification burdens, update obligations, and margin structures that reshape vendor positioning.
Product Type:
Military-grade phones cycle through 18-36 month certification windows, while consumer-facing personal devices refresh annually. Business devices occupy the middle ground with 24-month enterprise refresh cycles.
- Military-grade Phones:These devices integrate discrete secure elements certified to Common Criteria EAL4+, physical self-destruct mechanisms, and tamper-resistant enclosures. NATO-aligned defense contractors in Germany and Israel drive procurement volumes through sovereign communications infrastructure programs.
- Business Devices:Hardened Android distributions with managed security service attachments dominate enterprise mobility programs. Corporations in the United States consolidate volume licensing under biometric authentication mandates that require fingerprint and facial recognition modules.
- Personal Devices:Consumer-facing encryption through proprietary secure enclave architecture serves privacy-conscious individual buyers.
- Health-focused Phones:HIPAA-compliant voice and data protection targets healthcare provider mobility requirements.
Military-grade phones dominate installed base value. Business devices are where expansion concentrates.
Security Features:
Cost tiering separates hardware-based implementations from software-defined alternatives, with premium positioning attached to discrete module architectures.
- Secure Enclave:Dedicated hardware security modules with cryptographically verified boot chains protect against forensic extraction. European Union Cyber Resilience Act mandates are accelerating certification investments by device manufacturers seeking CE marking access.
- Biometric Authentication:Fingerprint and facial recognition modules require discrete secure elements certified to Common Criteria EAL4+. Enterprise mobility programs across Germany and the United States now mandate these modules as baseline requirements.
- End-to-End Encryption:Voice and messaging protection through lattice-based cryptography is converging with existing secure boot chains ahead of post-quantum threats.
- Remote Wipe:Enterprise mobility administrators deploy software-defined alternatives to reduce per-device provisioning costs.
Secure enclave implementations command premium positioning. Biometric authentication modules are climbing the fastest.
End User:
Customer type determines procurement channel, with government agencies requiring outcome-based contracting while individual consumers transact through retail.
- Government Agencies:Outcome-based contracting specifies operational availability metrics rather than device counts. Germany's Federal Office for Information Security and Israel's defense procurement channels now retain vendor ownership of fielded hardware.
- Corporations:Volume licensing with managed security service attachments concentrates margin pools. United States enterprise mobility programs are consolidating orders under biometric authentication mandates.
- Healthcare Providers:HIPAA compliance requirements drive demand for health-focused phones with encrypted voice and data protection.
- Individual Consumers:Privacy premiums support consumer-facing encryption through proprietary secure enclave architecture.
Government agencies dominate contract value. Corporations are gaining share fastest.
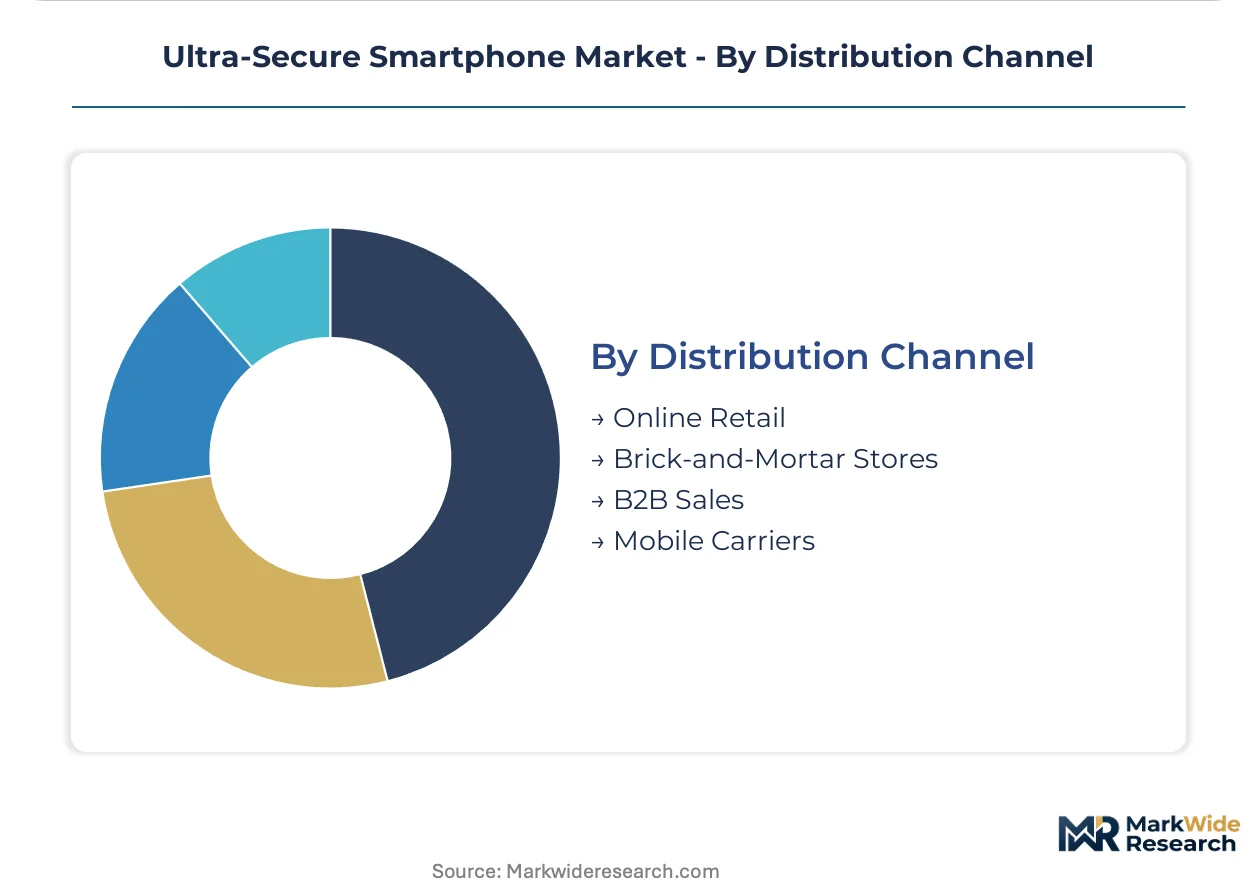
Distribution Channel:
Supply concentration in B2B sales reflects the technical complexity of enterprise and government procurement, while online retail serves simpler consumer transactions.
- B2B Sales:Direct vendor relationships with defense contractors and intelligence agencies handle extended certification cycles and sovereign procurement requirements. Finnish manufacturing clusters support NATO-aligned defense communications production.
- Mobile Carriers:Enterprise mobility programs bundle hardened devices with secure voice routing subscriptions. German and United States carriers are restructuring firmware teams to meet EU Cyber Resilience Act 24-hour critical patch windows.
- Online Retail:Consumer-facing encryption products reach privacy-conscious individual buyers through direct-to-consumer channels.
- Brick-and-Mortar Stores:Limited presence given the specialized technical consultation required for ultra-secure device selection.
B2B sales dominate revenue concentration. Mobile carrier channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finland exports hardened device assembly to NATO-aligned defense procurement channels across Germany, Israel, and the United States. Israeli secure communications technology flows into European and North American intelligence agency programs. German certification standards now govern CE marking access for vendors serving Brussels-mandated hardware security requirements.
United States
Defense contractors and intelligence agencies consolidate orders under sovereign communications infrastructure programs funded through federal procurement channels. The National Security Agency publishes Commercial Solutions for Classified program criteria that gate federal smartphone procurement. Silicon Valley secure enclave architects and Washington DC-area defense integrators collaborate on post-quantum cryptography migration timelines.
Germany
The Federal Office for Information Security evaluates devices through technical guidelines that open procurement channels for non-military government users. CE marking requirements under the EU Cyber Resilience Act mandate automatic security update delivery and standardized vulnerability disclosure timelines. Bavarian manufacturing clusters and Berlin-based certification laboratories anchor continental hardware security module production.
Israel
Defense procurement channels retain vendor ownership of fielded hardware through outcome-based contracting specifying operational availability metrics. The country's national cyber regulator aligns sovereign communications specifications with NATO interoperability standards. Tel Aviv metropolitan area hosts specialized cryptographic engineering talent pools serving both domestic and export defense contracts.
Finland
NATO-aligned defense communications production concentrates in Northern European manufacturing facilities with extended Common Criteria certification cycles. The country's national information security authority coordinates with Brussels on hardware-level secure enclave mandates. Oulu and Helsinki metropolitan areas host discrete secure element fabrication for military-grade phone assembly.
Ultra-Secure Smartphone Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. Defense contractors and intelligence agencies consolidate volumes under sovereign programs, while enterprise mobility administrators negotiate volume licensing with managed security attachments. Strategic archetypes include silicon-integrated platform owners, hardened Android distribution specialists, and NATO-certified defense communications fabricators. Competitive moves concentrate on post-quantum cryptography integration and dual-track compliance investments spanning EU hardware certification and US software supply chain attestation.
Among platform-integrated technology companies, Apple and Google occupy positions that exemplify consumer-facing encryption leadership through proprietary secure enclave architectures. Bittium represents the defense-specialist archetype with Finnish manufacturing pedigree serving NATO-aligned procurement channels. These anchors illustrate how vendor positioning splits between mass-market biometric authentication integration and military-grade Common Criteria EAL4+ certification cycles.
| Leading Market Players |
|---|
| Sirin Labs |
| Apple |
| Purism |
| Samsung |
| Bittium |
| BlackBerry Limited |
| GSMK GmbH |
| Katim |
| Others |
Cost & Logistics Intelligence
Finnish manufacturing clusters for NATO-aligned defense communications anchor upstream assembly capacity, concentrating margin capture with discrete secure element fabricators in Oulu and Helsinki while downstream pricing power accrues to vendors with BSI certification pipelines.
Pricing Analysis
Cost-plus contracts with NATO procurement channels index component costs to Common Criteria certification cycle durations. Three-tier pricing structure across military-grade, business device, and personal device levels separates EAL4+ certified hardware from managed security service bundles. Pricing pressure stems from extended 18-36 month certification windows freezing design iterations. Government agencies exhibit lowest price sensitivity due to sovereign communications infrastructure mandates, while individual consumers face the highest elasticity.
Supply Chain Analysis
Contract manufacturing for tamper-resistant enclosures concentrates with Finnish and German precision fabrication specialists serving defense procurement channels. Raw material dependencies include rare earth elements for secure element substrates, specialized alloys for chassis breach detection systems, and lattice-based cryptography chipsets. Single-source vulnerability runs through Northern European manufacturing clusters for NATO-aligned hardware. Distribution feeds from direct vendor relationships with defense contractors and intelligence agencies, bypassing traditional retail channels entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultra-secure smartphone penetration sits at early-cycle expansion as post-quantum cryptography migration forces hardware redesigns ahead of NIST standard finalization.
For Market Incumbents: Harden certification pipelines against German BSI technical guideline divergence from NSA Commercial Solutions for Classified criteria. Expand backward integration into discrete secure element fabrication to capture margin pools currently lost to Finnish semiconductor specialists. Lock enterprise mobility administrators into five-year managed security service attachments before EU Cyber Resilience Act update obligations commoditize hardware differentiation. For New Entrants and Emerging Players: Pursue white-space in health-focused HIPAA-compliant devices serving United States healthcare provider mobility requirements. Target German non-military government users previously served by foreign vendors through accelerated BSI certification investments. Lead with subscription-based threat monitoring rather than hardware margins to bypass capital-intensive Common Criteria cycles. For Investors and Strategic Acquirers: Capital is best deployed toward cryptographic engineering specialists with side-channel attack mitigation expertise and existing NATO procurement relationships. Long-term viability hinges on post-quantum algorithm integration capabilities ahead of cryptanalytic threats. Watch for NIST standard finalization as inflection signal triggering procurement refresh cycles across defense and intelligence channels.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography Integration | Lattice-based algorithm deployment ahead of NIST standard finalization secures procurement positioning. |
| Dual-Track Compliance Investment | Parallel EU hardware certification and US software attestation captures fragmented allied defense markets. |
| Managed Security Service Unbundling | Subscription-based threat monitoring concentrates recurring revenue from enterprise mobility programs. |
| Outcome-Based Contracting Adoption | Operational availability metrics shift lifecycle maintenance risk to manufacturers while retaining ownership. |
| Virtualized Secure Enclave Development | Software-defined alternatives to hardware modules enable faster patch cycles without respins. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across defense procurement officers, enterprise mobility administrators, cryptographic firmware architects, and secure element fabrication specialists. Primary fieldwork combined with secondary validation from NSA Commercial Solutions for Classified program criteria, German BSI technical guidelines, EU Cyber Resilience Act documentation, and NATO interoperability standards. Bottom-up device shipment modeling triangulated against top-down sovereign communications infrastructure budget allocations.
Calibration anchored volume projections to documented procurement cycles across German, Israeli, and United States defense channels. Segmentation dimensions spanned product type, security feature tier, end-user category, and distribution channel structure. CAGRs derived from regression analysis of historical certification cycle impacts on replacement rates and post-quantum migration timeline assumptions.
Sensitivities concentrate around NIST post-quantum standard finalization dates, EU-US regulatory divergence on hardware versus software attestation, and Finnish manufacturing cluster disruption risks. Quarterly review of NATO procurement budget appropriations and BSI certification pipeline throughput is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Data Loss Prevention Market
Security Software
Parental Control Software Market
Security Software
Cybersecurity Software Market
Security Software
Key Management Service Market
Security Software
Europe IP Video Intercom Device and Equipment Market
Security Software
Security Information and Event Management (SIEM) Market
Security Software
Anti-Money Laundering (AML) Software Solution Market
Security Software
Europe Lawful Interception Market
Security Software
Data Masking Technology Market
Security Software
Japan Mobile Biometrics Market
Security Software
VPN Software Market
Security Software
Global Error Monitoring Software Market
Security Software
Global Security Software in Telecom Market
Security Software
Software Defined Perimeter (SDP) Market
Security Software
Device Vulnerability Management Market
Security Software
Geofencing Market