
 Broadcast Censorship Solutions Market | 2026-2036
Broadcast Censorship Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Broadcast Censorship Solutions Market Outlook
ISO/IEC 27001 certification for information security management is rotating as a baseline qualification for vendors serving government and premium broadcaster contracts. Ericsson AB leverages its end-to-end broadcast infrastructure portfolio to bundle censorship modules with transmission equipment. Rohde & Schwarz anchors its position through deep specialization in monitoring hardware for regulatory compliance environments. Sony Corporation competes by extending its media technology ecosystem into cloud-native content verification workflows.
Broadcast censorship solutions encompass hardware and software systems that detect, flag, suppress, or delay audio-visual material based on regulatory, contractual, or editorial rules, operating at frame-accurate latency thresholds below 40 milliseconds for live transmission environments. These systems serve television networks, streaming platforms, and state broadcast authorities requiring real-time intervention before content reaches audiences. Automated filtering technology leads deployment volume due to scalability across high-channel-count operations, while cloud-based deployment models capture the fastest expansion as over-the-top platforms displace traditional linear distribution. Compliance monitoring applications command premium pricing because failure penalties from national regulators create acute buyer sensitivity to false-negative rates.
The Federal Communications Commission enforces decency standards that mandate delay mechanisms for live programming, while the EU AI Act imposes algorithmic transparency obligations on automated content classification systems deployed in member states. China's SAMR and NMPA coordinate content review protocols for streaming services operating under dual carbon goals that constrain data center expansion for censorship processing. Buyers must evaluate whether vendor architectures accommodate divergent jurisdictional rule sets without redundant infrastructure investments as cross-border content licensing proliferates.
Market Dynamics
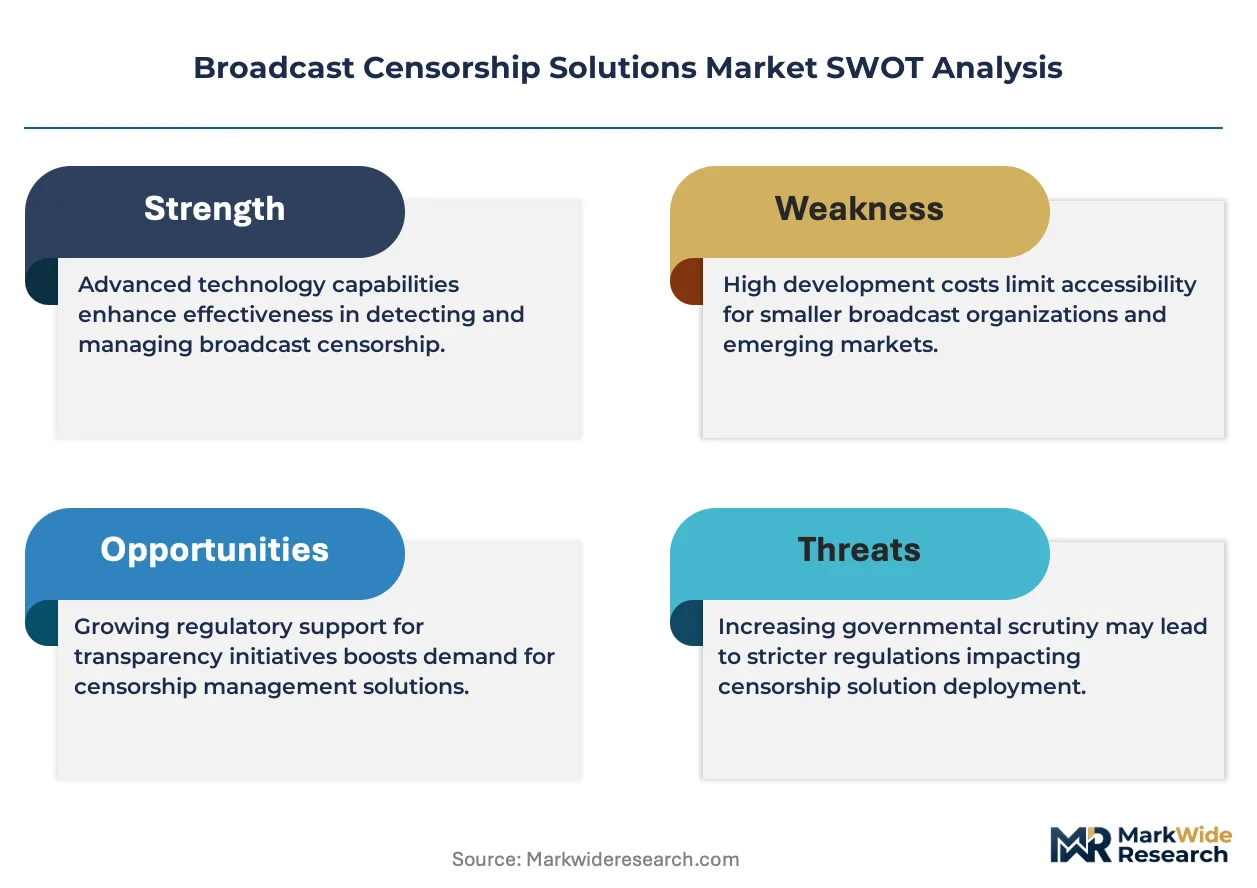
Real-time AI inference at sub-40ms latency is restructuring procurement priorities, as broadcasters and streaming platforms replace rule-based delay systems with neural classification pipelines that demand specialized GPU clusters and edge computing partnerships.
Growth Catalysts
- EU AI Act compliance mandates:Automated content classification systems deployed in member states face algorithmic transparency obligations, forcing platform upgrades to auditable machine learning architectures.
- Live sports streaming expansion:OTT broadcasters require frame-accurate intervention for unscripted content, driving hardware refreshes in professional sports production facilities.
- FCC decency enforcement:The commission's delay mechanism requirements for live programming sustain baseline demand across US television networks and affiliate stations.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in training-grade silicon creates procurement bottlenecks for vendors building real-time inference appliances.
- Jurisdictional rule fragmentation:Divergent content standards between China's SAMR protocols, EU AI Act requirements, and FCC guidelines force redundant engineering investments.
- Edge data center constraints:China's dual carbon goals limit expansion of censorship processing infrastructure for streaming services operating under NMPA oversight.
Strategic Opportunities
- Cloud-native verification workflows:Sony Corporation and specialized vendors are bundling content moderation APIs with existing media asset management platforms.
- India's TRAI streaming regulations:Pending content classification mandates for OTT platforms create first-mover advantages for ISO 27001-certified solution providers.
- Multimodal AI convergence:Synchronized audio-visual-language models enable single-pass classification that reduces hardware footprint versus legacy pipelined architectures.
Industry Challenges
- Frame-accurate latency engineering:Recruiting specialists who can optimize transformer-based models for sub-40ms inference remains exceptionally difficult.
- Legacy SDI infrastructure integration:Broadcasters with substantial sunk investment in serial digital interface workflows face complex migration paths to IP-based censorship pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Broadcast Censorship Solutions Market |
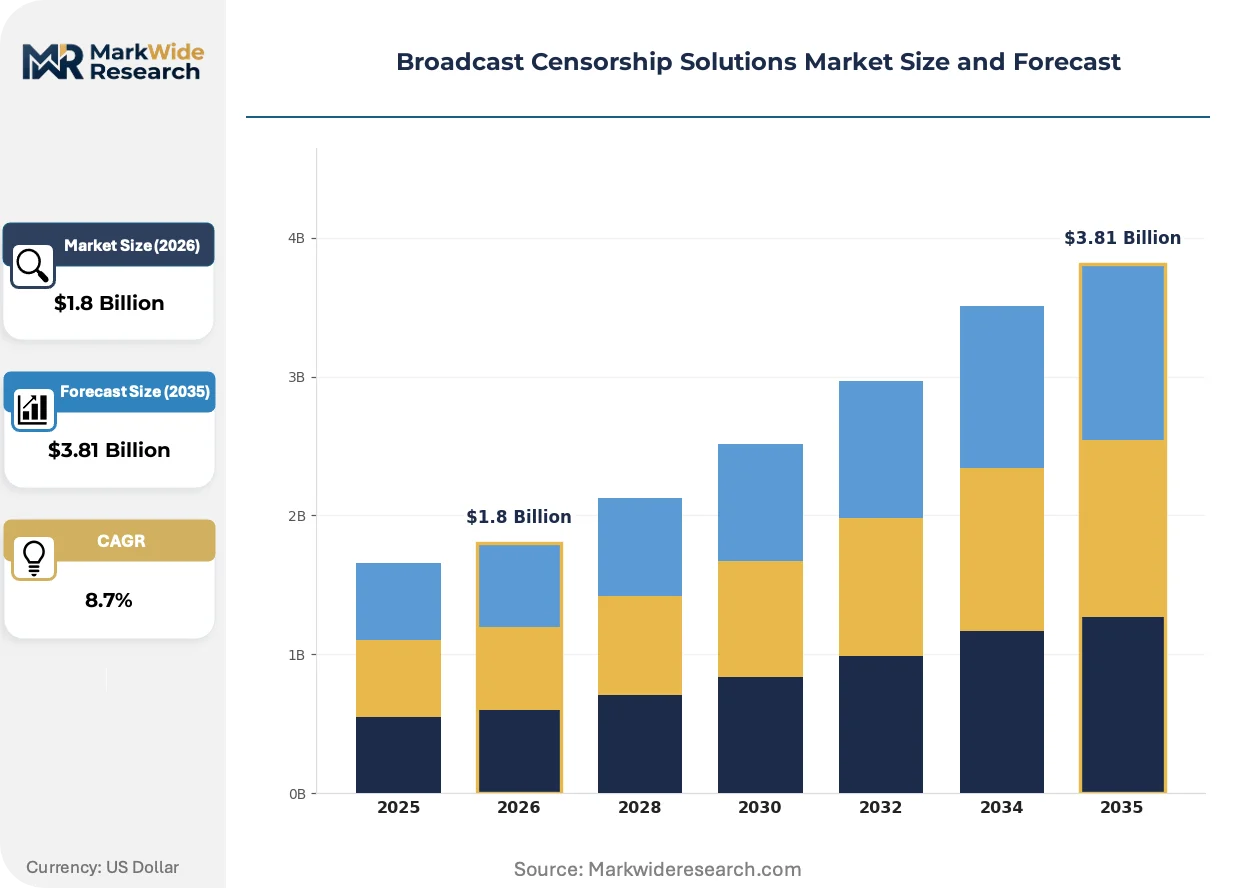
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Automated Filtering, Manual Review, Content Identification, Compliance Monitoring Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Service Content Category: News, Entertainment, Sports, Educational End User: Broadcasters, Streaming Services, Government Agencies, Content Producers |
| Companies Covered | Ericsson AB, Rohde & Schwarz, Sony Corporation, Huawei Technologies Co. Ltd., Grass Valley USA LLC, Harmonic Inc., Cisco Systems, EVS Broadcast Equipment SA, Media Excel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Broadcast Censorship Solutions Market Strategic Shifts
Neural content classification is compressing the vendor landscape, as specialized inference hardware and foundation-model fine-tuning capabilities separate tier-one platform providers from component suppliers.
Transformer-based multimodal models are displacing traditional computer vision pipelines in live broadcast environments. Tier-one streaming platforms in the United States and Western Europe are deploying these architectures for simultaneous audio, visual, and text classification. The shift is displacing established vendors who built market position on optimized CPU-based rule engines and fixed-function FPGA appliances.
The EU AI Act's algorithmic transparency obligations are mandating explainable classification outputs for automated content moderation systems. Vendors must now provide decision audit trails that satisfy national regulators in France, Germany, and Italy. European broadcast authorities and platform compliance teams are restructuring procurement specifications to prioritize vendors with certified model documentation workflows.
Buyers are unbundling hardware procurement from software licensing, favoring API-first content moderation services that integrate with existing cloud infrastructure. This pattern is most visible among mid-sized OTT platforms in India and Southeast Asia that lack capital for on-premise appliance deployment. Vendors with flexible consumption pricing are capturing share from traditional equipment-leasing incumbents.
Broadcast Censorship Solutions Market Segmentation
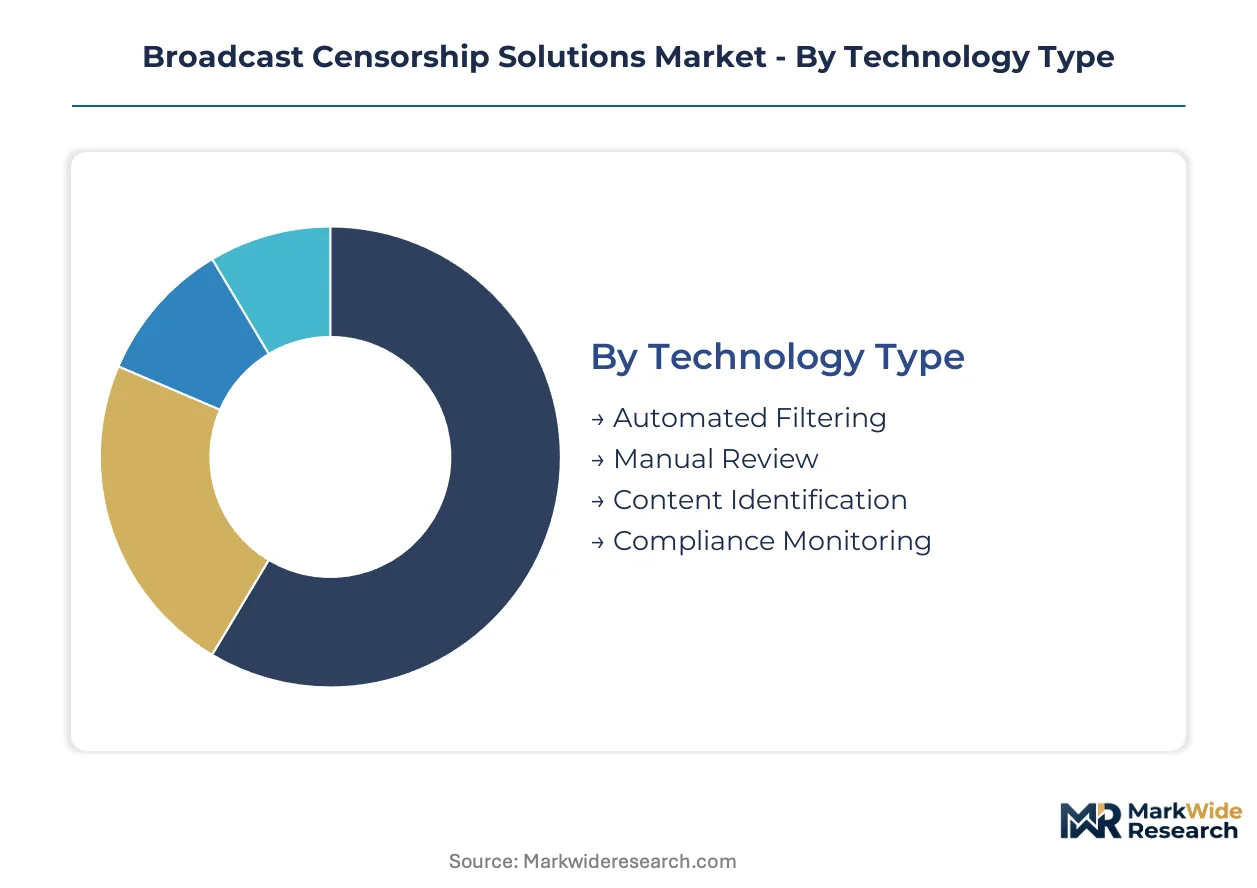
Broadcast censorship solutions serve divergent latency and compliance requirements across live transmission, on-demand streaming, and state-controlled broadcasting. Segmentation reveals how technology choices map to regulatory environments and infrastructure maturity. Procurement patterns split between legacy broadcasters defending sunk investments and streaming platforms building cloud-native stacks.
Technology Type:
Automated filtering and compliance monitoring dominate domestic procurement in the United States and Western Europe, while manual review retains substantial share in export markets with developing broadcast infrastructure.
- Automated Filtering:Neural classification pipelines process audio-visual streams at sub-40ms latency using GPU-accelerated inference. Demand concentrates among US streaming platforms facing FCC decency enforcement and EU platforms navigating AI Act transparency mandates.
- Compliance Monitoring:Frame-accurate logging and audit-trail generation systems command premium pricing due to penalty exposure from national regulators. European broadcast authorities in France, Germany, and Italy prioritize vendors with certified model documentation workflows.
- Manual Review:Human-in-the-loop intervention for nuanced editorial decisions. State broadcasters in India and Southeast Asia rely on hybrid staffing models during regulatory transition periods.
- Content Identification:Fingerprinting and watermark detection for rights management and repeat-offender tracking. Sports leagues and premium entertainment licensors drive specification requirements.
Automated filtering holds the largest share; momentum sits with compliance monitoring as EU AI Act enforcement tightens.
Deployment Model:
Cost tier separation is pronounced: on-premise appliances serve premium broadcasters with sub-50ms latency requirements, while cloud-based models capture mid-market OTT platforms prioritizing operational flexibility over capital expenditure control.
- Cloud-Based:API-first content moderation services integrate with existing media asset management platforms. Mid-sized OTT platforms in India and Southeast Asia favor consumption-based pricing over equipment leasing.
- On-Premise:Dedicated inference appliances for broadcast facilities with strict data sovereignty requirements. China's NMPA-licensed streaming services operate under dual carbon constraints limiting data center expansion.
- Hybrid:Split processing architectures route sensitive content through on-premise pipelines while leveraging cloud scale for archival review. European public service broadcasters adopt this model to satisfy GDPR localization rules.
- Managed Service:Outsourced compliance operations including 24/7 monitoring staffing and regulator liaison. Emerging market broadcasters without in-house AI engineering capacity contract specialized vendors.
On-premise deployments retain the revenue base; cloud-based models are expanding most quickly as OTT displacement of linear distribution accelerates.
Content Category:
Application intensity varies: live unscripted content demands real-time intervention infrastructure, while pre-produced material permits asynchronous review workflows with lower hardware specifications.
- Sports:Unscripted live production with unpredictable crowd behavior and participant conduct. Professional leagues in the United States and Western Europe drive hardware refresh cycles for frame-accurate delay systems.
- News:Rapid-turnaround current affairs with minimal production buffers. Broadcasters balancing editorial speed against defamation and incitement exposure in multiple jurisdictions.
- Entertainment:Scripted and variety programming with established pre-broadcast review windows. Streaming platforms apply automated classification at ingest rather than transmission stage.
- Educational:Curriculum-aligned content with age-appropriateness requirements. Public broadcasters and state distance-learning networks specify pedagogical suitability criteria beyond general decency standards.
Sports commands the highest per-channel infrastructure investment; news is gaining share fastest as 24-hour channel proliferation continues.
End User:
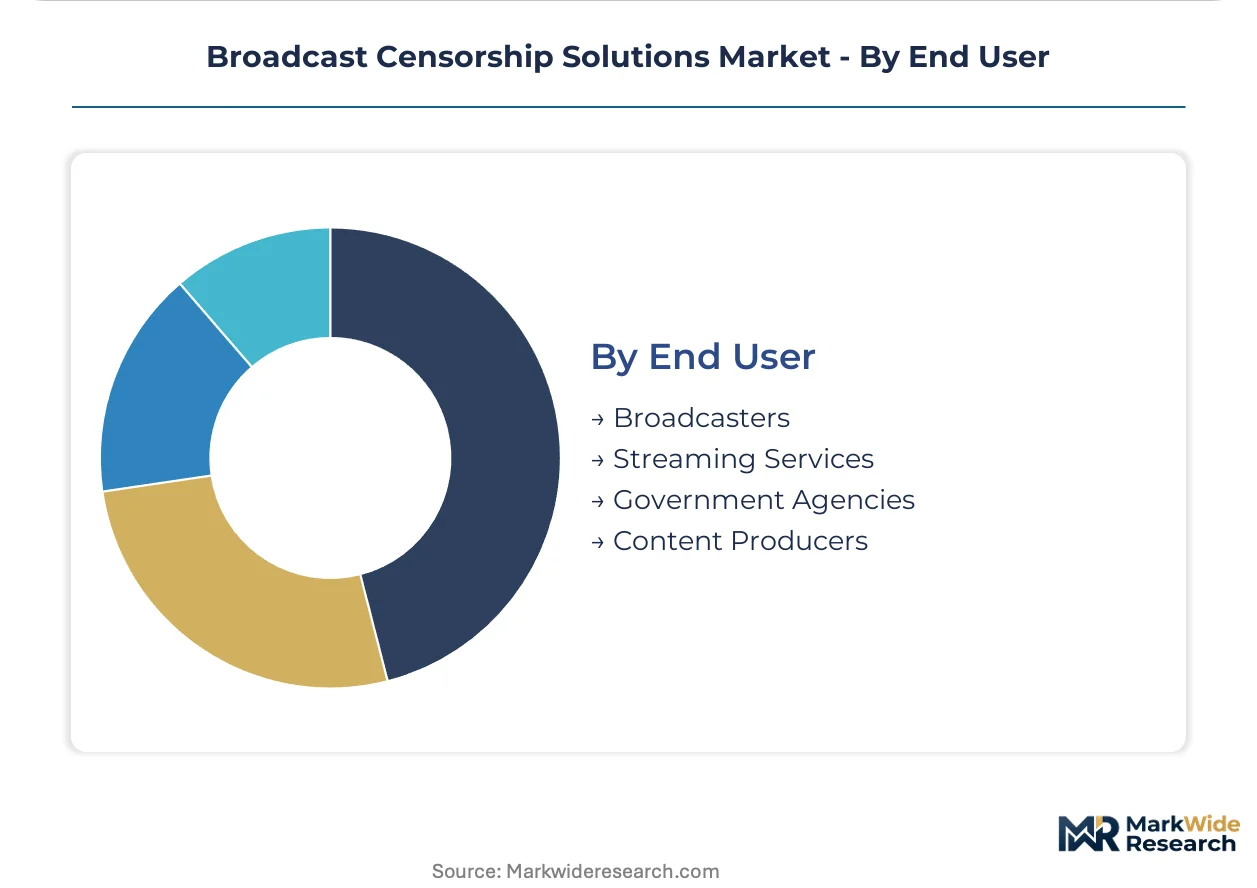
Customer type determines procurement authority and specification complexity: streaming platforms centralize purchasing at headquarters level, while government agencies impose certification requirements that filter vendor eligibility.
- Streaming Services:Over-the-top platforms with global content catalogs requiring multi-jurisdictional rule accommodation. Netflix, Amazon Prime Video, and regional competitors drive demand for cloud-native verification workflows.
- Broadcasters:Traditional television networks with hybrid SDI-IP infrastructure and affiliate station relationships. US networks maintain FCC-compliant delay mechanisms across owned-and-operated stations.
- Government Agencies:State broadcast authorities and regulatory bodies operating national monitoring centers. China's SAMR coordinates content review protocols with NMPA oversight of streaming licensing.
- Content Producers:Production companies and post-production facilities delivering compliance-ready masters to distributors. Independent studios in India anticipate TRAI classification mandates for OTT supply.
Streaming services represent the fastest-growing customer category; broadcasters retain the largest installed base of legacy equipment requiring refresh decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State broadcast authorities and streaming platforms concentrate procurement authority in jurisdictions with active regulatory enforcement. Buyers prioritize vendors capable of accommodating divergent rule sets without redundant infrastructure investments.
United States
The Federal Communications Commission enforces decency standards mandating delay mechanisms for live programming. Major television networks and affiliate stations sustain baseline demand for frame-accurate intervention systems. Los Angeles and New York production clusters drive specification requirements for professional sports and entertainment content.
Germany
The EU AI Act imposes algorithmic transparency obligations on automated content classification systems deployed in member states. National regulators in France, Germany, and Italy require certified model documentation workflows. Berlin and Munich broadcast technology centers prioritize explainable classification outputs for compliance audit trails.
China
The State Administration for Market Regulation coordinates content review protocols with National Medical Products Administration oversight of streaming licensing. Dual carbon goals constrain data center expansion for censorship processing infrastructure. Beijing and Shanghai streaming services operate under localized data sovereignty requirements limiting cloud-based deployment.
India
The Telecom Regulatory Authority of India is developing pending content classification mandates for over-the-top platforms. Mid-sized streaming services favor API-first content moderation services with consumption-based pricing. Mumbai and Bangalore production hubs anticipate first-mover advantages for ISO 27001-certified solution providers.
United Kingdom
Ofcom broadcast standards require real-time intervention capabilities for live transmission environments. Public service broadcasters adopt hybrid processing architectures to satisfy GDPR localization rules. London media technology clusters drive demand for cloud-native verification workflows integrating with existing asset management platforms.
Broadcast Censorship Solutions Market Competitive Environment
Player mix skews toward diversified technology conglomerates with end-to-end broadcast infrastructure portfolios. The vendor base separates into three strategic archetypes: transmission equipment bundlers, specialized monitoring hardware providers, and cloud-native workflow extenders. Competitive positioning depends on GPU-accelerated inference capabilities and edge computing partnerships. Market participants pursue strategic partnerships and portfolio diversification to accommodate divergent jurisdictional rule sets.
Within the diversified technology tier, Ericsson AB and Sony Corporation exemplify conglomerate strategies leveraging existing broadcast infrastructure relationships. Rohde & Schwarz occupies a specialist position in monitoring hardware for regulatory compliance environments. These three anchors represent distinct competitive vectors: bundled transmission systems, deep hardware specialization, and media technology ecosystem extension.
| Leading Market Players |
|---|
| Ericsson AB |
| Rohde & Schwarz |
| Sony Corporation |
| Huawei Technologies Co. Ltd. |
| Grass Valley USA LLC |
| Harmonic Inc. |
| Cisco Systems |
| EVS Broadcast Equipment SA |
| Media Excel |
| Others |
Value Chain & Pricing Dynamics
Forty-five to ninety days of GPU inventory lead time concentrates pricing power with NVIDIA's distribution network, compressing margins for appliance vendors while amplifying subscription-based software premiums. This inventory constraint reshapes procurement patterns as buyers pivot toward API-first consumption models that bypass hardware procurement cycles entirely.
Pricing Analysis
Cost-plus contracts with NVIDIA silicon indexation dominate hardware appliance procurement, while software tiers stratify across enterprise, professional, and standard levels based on ISO 27001 certification status and inference volume commitments. Price differentiation hinges on latency grade—sub-40ms premium tiers command substantial premiums over 100ms archival review tiers—and geographic deployment scope. Pricing pressure stems from cloud-native competitors offering consumption-based APIs that undercut capital-intensive appliance leasing. Mid-sized OTT platforms in India exhibit highest price sensitivity due to constrained procurement budgets, while European public service broadcasters show lowest sensitivity given penalty exposure from national regulators.
Supply Chain Analysis
Taiwan and South Korea anchor advanced GPU and high-bandwidth memory fabrication, while the United States concentrates specialized inference chip design and edge computing hardware assembly. The vendor ecosystem draws from Chinese metal chassis suppliers, German precision monitoring components, and Japanese optical transmission modules. Single-source vulnerability around NVIDIA's training-grade silicon creates acute procurement bottlenecks when allocation tightens. Distribution runs through systems integrators with broadcast infrastructure relationships, bypassing direct vendor engagement for tier-two and tier-three accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Broadcast censorship solutions function as a service-attach opportunity where recurring compliance monitoring and API consumption layers expand faster than hardware refresh cycles. Managed service revenues for 24/7 monitoring and regulator liaison outpace equipment leasing growth across all major geographies.
For Market Incumbents: Compound defensive positioning by embedding censorship modules deeper into end-to-end broadcast infrastructure bundles, mirroring Ericsson's transmission equipment strategy. Acquire specialized GPU inference optimization firms to secure transformer-based model latency advantages against cloud-native entrants. Prioritize ISO 27001 certification maintenance as table stakes for government and premium broadcaster contracts. Extend edge computing partnerships to reduce reliance on centralized data center expansion in carbon-constrained markets. For New Entrants and Emerging Players: Anchor in India's pending TRAI classification mandate implementation, where mid-sized OTT platforms lack in-house AI engineering capacity and favor consumption-based API pricing. Target hybrid deployment architectures for European public service broadcasters navigating GDPR localization requirements. Pursue white-label partnerships with existing media asset management platforms rather than competing for direct procurement relationships. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because automated content governance obligations will expand across jurisdictions regardless of macroeconomic cycles. Acquisition targets should display certified model documentation workflows and established regulator relationships in at least two major markets. Watch for EU AI Act enforcement actions against platforms lacking algorithmic transparency as the signal for accelerated vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| GPU Inference Optimization Acquisition | Secures sub-40ms latency capabilities for transformer-based classification pipelines against cloud-native competition. |
| ISO 27001 Certification Investment | Unlocks government and premium broadcaster procurement channels with mandatory security compliance requirements. |
| Edge Computing Partnership Expansion | Addresses China's dual carbon constraints while maintaining data sovereignty for NMPA-licensed streaming services. |
| API-First Platform Launch | Captures mid-market OTT demand in India and Southeast Asia favoring consumption-based pricing models. |
| Regulatory Documentation Workflow Development | Satisfies EU AI Act algorithmic transparency mandates for French, German, and Italian national regulators. |
Study Parameters
A spread of perspectives from broadcast technology procurement officers, streaming platform compliance directors, regulatory affairs leads at state broadcast authorities, and GPU supply chain specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FCC enforcement records, EU AI Act implementation guidance, SAMR content review protocols, and SEC filings from diversified technology conglomerates with broadcast infrastructure exposure. Bottom-up triangulation across deployment model, technology type, and end-user segments was cross-checked against top-down market sizing from capital expenditure disclosures at major streaming platforms.
Segmentation dimensions modeled include deployment architecture, latency requirement tier, content category application, and jurisdictional regulatory cluster across the analysis window. CAGRs were derived from trend extrapolation of streaming platform infrastructure investment patterns and linear broadcaster refresh cycles, calibrated against GPU supply availability constraints and carbon policy impacts on data center expansion. Forecast inputs incorporated TRAI mandate implementation timelines and EU AI Act enforcement phase transitions.
Decision-makers should treat outputs as directional under assumptions of sustained GPU supply concentration and continued regulatory fragmentation; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in national content classification mandate implementations and hyperscaler edge computing partnership announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Privileged Access Management (PAM) Solutions Market
Security Software
Data Leakage Prevention Product Market
Security Software
Device-Embedded Biometric Authentication Market
Security Software
Automotive Endpoint Authentication Market
Security Software
Global Visitor Management System Market
Security Software
Cloud File Security Software Market
Security Software
Bot Mitigation Market
Security Software
United States Lawful Interception Market
Security Software
Decentralized Identity Software Market
Security Software
Identity Verification Software Market
Security Software
DC and PKI Market
Security Software
Hardware Encryption Market
Security Software
Global Software-Defined Security Market
Security Software
Global Data Loss Prevention Software Market
Security Software
Global Secure Access Service Edge Market
Security Software
Secure Email Gateway Market