
 VPN Software Market | 2026-2036
VPN Software Market Size, Share, and Industry Trends Forecast 2026-2036
VPN Software Market Analytics
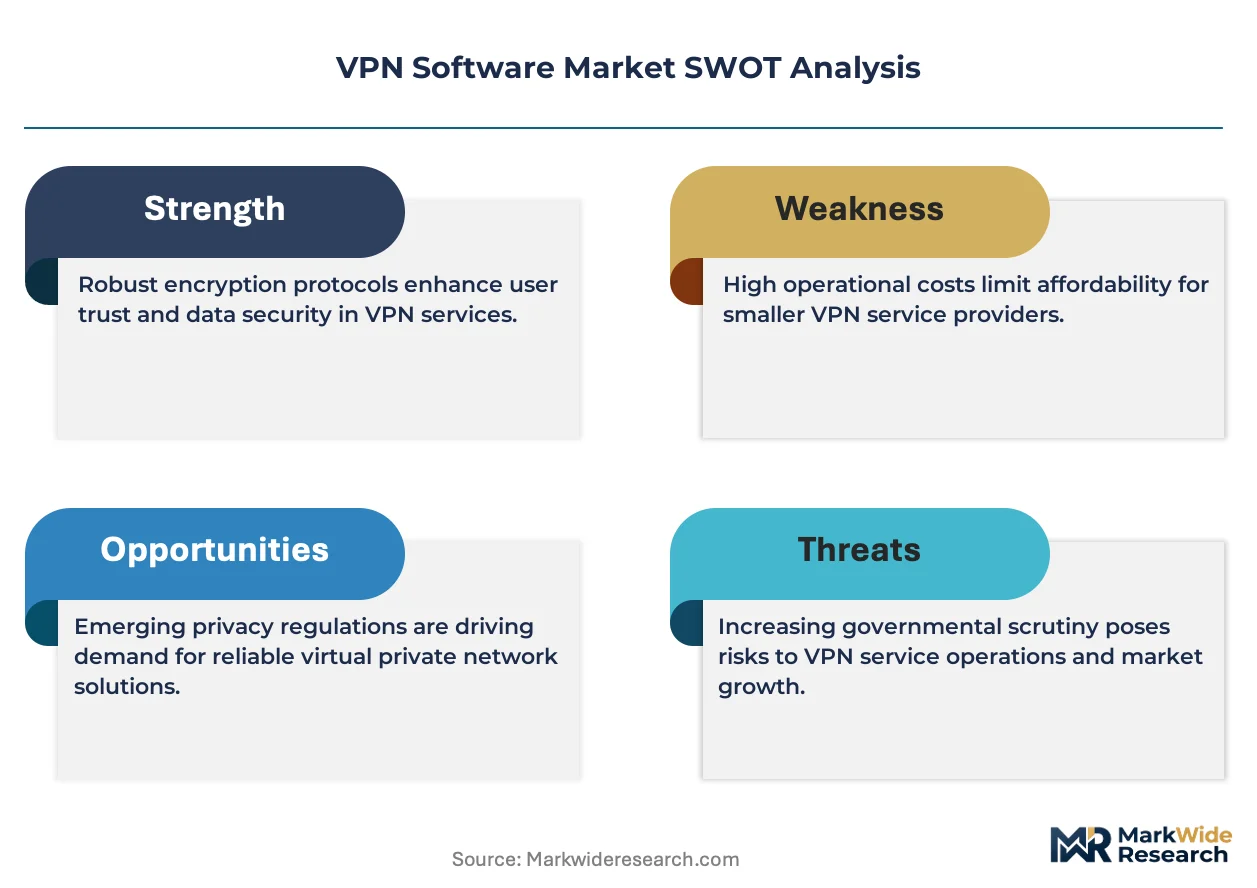
Enterprise cybersecurity talent scarcity is unwinding legacy perimeter-defense strategies and forcing organizations toward automated, software-defined VPN orchestration. NordVPN leverages consumer brand recognition to cross-sell business-tier solutions, while Cisco Systems, Inc. anchors enterprise trust through decades of router-to-endpoint integration. Palo Alto Networks, Inc. competes by embedding VPN functions within broader SASE platforms that unify networking with cloud-delivered security.
VPN software creates encrypted tunnels across public networks using protocols such as IPSec or SSL to authenticate endpoints and encapsulate data packets, ensuring confidentiality for remote users and branch offices accessing corporate resources. Cloud-based deployment leads among segments as enterprises abandon hardware appliances for elastic, API-driven connectivity that scales with distributed workforces. Subscription-based service models capture expanding margin pools by converting perpetual-license customers into recurring-revenue relationships, while managed services attract mid-market firms lacking in-house network engineering depth.
FCC net-neutrality rulings in the US, GDPR cross-border transfer rules in Europe, and China's MIIT cybersecurity reviews collectively shape where VPN providers must locate infrastructure, what logging policies they adopt, and which markets remain accessible. The EU AI Act's risk-classification system further complicates deployment for AI-dependent traffic-inspection tools bundled with enterprise VPN suites. Stakeholders must monitor regulatory divergence between data-sovereignty regimes and technical standards bodies to anticipate compliance costs that will determine competitive survival in fragmented national markets.
Market Dynamics
Zero-trust architecture mandates are dismantling perimeter-based security models and forcing enterprises to deploy encrypted tunneling at every network access point, fundamentally restructuring how organizations procure and manage connectivity infrastructure.
Growth Catalysts
- EU AI Act Risk Classification:The EU AI Act's high-risk system designations compel enterprises to route AI-dependent traffic through jurisdiction-specific VPN nodes with auditable logging, expanding demand for compliant infrastructure.
- Automotive Supplier Networks:German industrial conglomerates operate dense, multi-tier supplier ecosystems requiring secure remote access for thousands of external partners, driving volume deployment of cloud-based VPN orchestration.
- WireGuard Protocol Adoption:The lightweight, high-performance WireGuard protocol reduces computational overhead for mobile and IoT endpoints, accelerating replacement of legacy IPSec implementations in distributed workforces.
Market Restraints
- Certificate Authority Concentration:Trust root dependencies on a narrow set of commercial certificate authorities creates systemic vulnerability if any major provider experiences compromise or distrust event.
- Silicon Supply Bottlenecks:Specialized cryptographic processors and hardware security modules face allocation constraints from TSMC and Samsung foundry capacity, extending delivery timelines for appliance-integrated solutions.
- MIIT Cybersecurity Review Friction:China's Ministry of Industry and Information Technology mandatory security assessments for cross-border data flows impose operational delays and localization costs for multinational VPN deployments.
Strategic Opportunities
- India PLI Scheme Tailwinds:India's Production Linked Incentive scheme for electronics manufacturing attracts data center and cloud infrastructure investment, creating demand for sovereign VPN nodes serving domestic enterprises.
- Post-Quantum Cryptography Convergence:The intersection of NIST-standardized post-quantum algorithms with existing TLS stacks enables vendors to differentiate through future-proofed encryption offerings ahead of regulatory mandates.
- Managed Security Service Channels:Mid-market firms lacking in-house network engineering depth increasingly procure VPN functionality through MSSP bundles, opening recurring revenue streams beyond direct enterprise sales.
Industry Challenges
- Zero-Trust Architecture Skill Scarcity:Enterprise IT teams lack depth in software-defined perimeter design and continuous authentication implementation, slowing deployment velocity despite executive mandate.
- Legacy Router Integration Complexity:Decades-old Cisco and Juniper infrastructure in installed bases resists API-driven orchestration, forcing parallel overlay architectures that increase operational overhead.
- Cross-Border Data Transfer Certification Delays:EU GDPR adequacy determinations and Schrems II compliance requirements extend legal review cycles for multinational VPN configurations, freezing procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VPN Software Market |
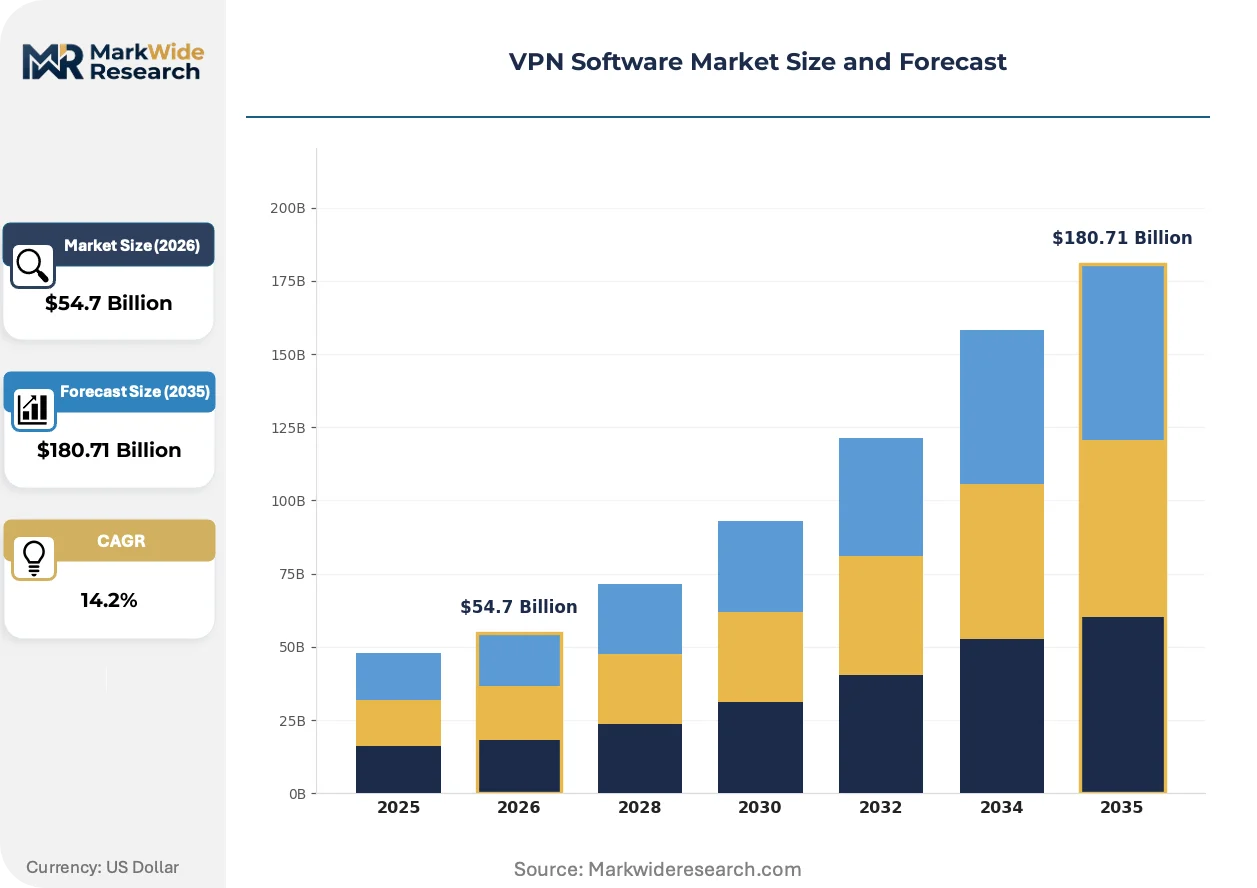
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $180.71 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Virtual Private Network Service Type: Managed Service, Self-Managed, Subscription-Based, Open Source End User: Large Enterprises, Small and Medium Businesses, Individual Users, Government Agencies Technology: IPSec, SSL, OpenVPN, L2TP |
| Companies Covered | NordVPN, ExpressVPN, CyberGhost, Surfshark, ProtonVPN, Private Internet Access, Cisco Systems, Inc., Palo Alto Networks, Inc., Fortinet, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VPN Software Market Evolving Landscape
SASE architecture consolidation is compressing standalone VPN markets as networking and security functions merge into unified cloud-delivered platforms, reshaping vendor competitive positioning and buyer evaluation criteria.
Software-defined WAN edge technology is decomposing traditional branch-router VPN termination by embedding encrypted tunneling directly into cloud-native security stacks. Financial services and healthcare enterprises with stringent compliance requirements are adopting these converged platforms fastest, typically replacing hardware refresh cycles with elastic subscription models. This decomposition is compressing margins for point-solution VPN vendors while expanding addressable wallet share for integrated platform providers.
The EU AI Act's extraterritorial risk-classification framework is forcing VPN providers to rearchitect traffic-inspection capabilities for AI model training data flows. High-risk AI system operators must now demonstrate auditable data lineage and encryption standards, creating compliance-driven upgrade cycles for enterprise VPN suites. German automotive and French healthcare verticals are responding earliest, demanding jurisdiction-specific node deployments with localized key management.
Consumption-based licensing models are displacing perpetual-seat agreements as hybrid work patterns render fixed user counts obsolete. Enterprise procurement teams now negotiate elastic tiers tied to concurrent session peaks rather than named employee bases, with this shift most visible among US technology and professional services firms with seasonal contractor scaling. Channel partners are adapting by unbundling implementation services from recurring license streams, capturing margin through migration consulting rather than resale markups.
VPN Software Market Segmentation
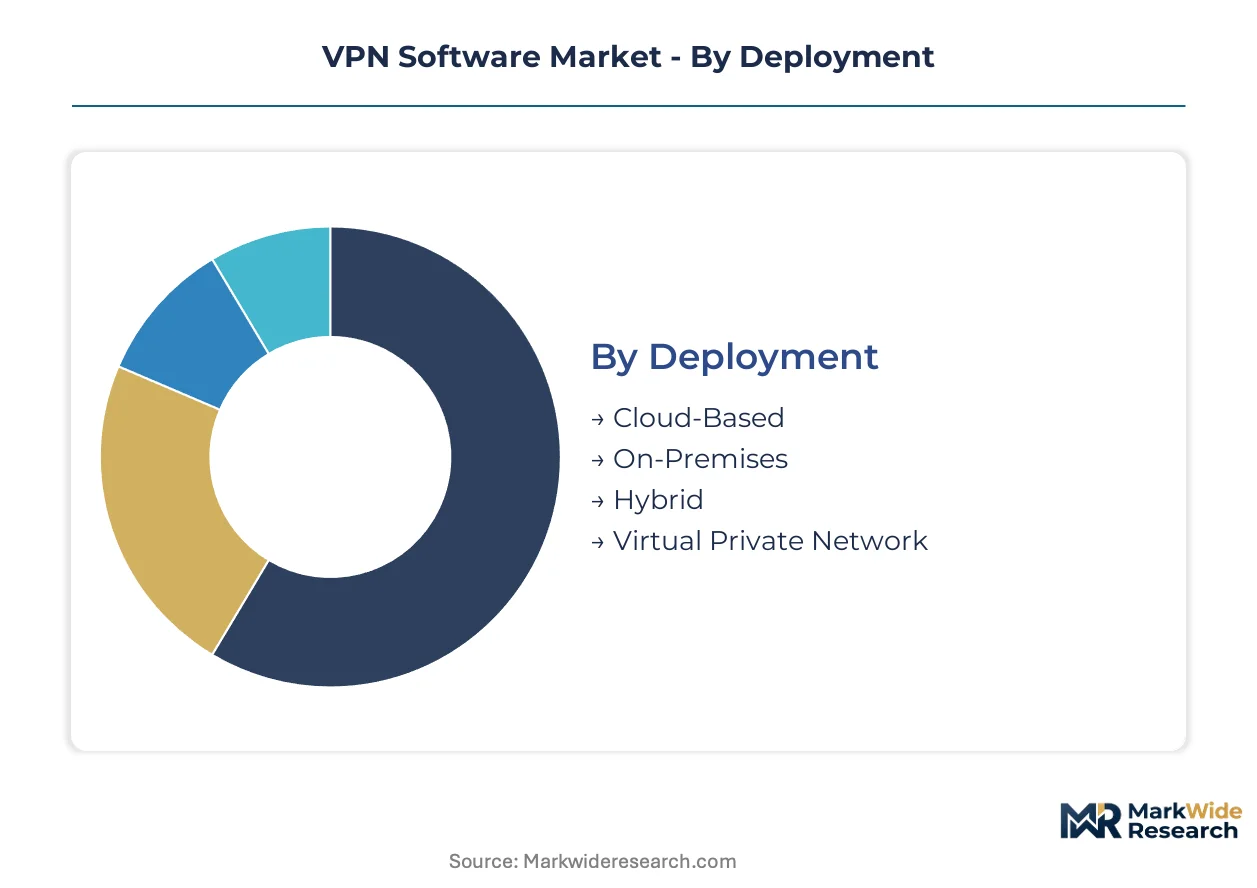
VPN software segmentation reveals how substitution pressures from converged security platforms reshape procurement patterns across deployment modes, service models, and end-user categories. Understanding these fault lines helps vendors anticipate where standalone solutions face displacement versus where specialized functionality commands premium positioning.
Deployment:
Cloud-based configurations confront the strongest substitution threat as SASE platforms absorb tunneling functions into broader networking stacks, while on-premises installations retain defensibility in regulated environments with data-sovereignty constraints.
- Cloud-Based:Elastic, API-driven infrastructure scales concurrent sessions dynamically without hardware refresh cycles. German automotive suppliers and US technology firms with seasonal contractor surges drive demand for usage-optimized provisioning.
- On-Premises:Dedicated appliance clusters maintain encrypted gateways within facility perimeters, preferred by French healthcare networks and government agencies under strict data-localization mandates.
- Hybrid:Split-tunnel architectures route sensitive traffic through on-premises nodes while general access flows via cloud relays, balancing compliance with operational flexibility.
- Virtual Private Network:Traditional dedicated-circuit implementations persist in legacy industrial control systems where protocol stability outweighs modernization costs.
Cloud-based deployment retains volume leadership; hybrid configurations hold the steepest expansion curve as enterprises phase out pure on-premises estates.
Service Type:
Margin structures diverge sharply between recurring-revenue models and one-time engagements, with self-managed options compressing service attach rates while managed services capture implementation complexity premiums.
- Managed Service:Third-party operators assume full lifecycle responsibility for tunnel provisioning, certificate rotation, and policy enforcement. Mid-market manufacturers in India and Brazil lacking network engineering depth drive adoption through MSSP channels.
- Subscription-Based:Per-seat or concurrent-session licensing converts perpetual-license customers into predictable revenue streams, with elastic tiers replacing fixed employee counts.
- Self-Managed:Enterprises with mature security operations centers license software directly and maintain internal orchestration, minimizing vendor dependency.
- Open Source:Community-maintained protocols like WireGuard and OpenVPN reduce licensing costs for technically sophisticated organizations with customization requirements.
Subscription-based models dominate revenue contribution; managed services are climbing fastest as skills scarcity pushes operational burden to external specialists.
End User:
Procurement authority and evaluation criteria fragment across organizational scale, with large enterprises demanding platform integration while individual users prioritize ease-of-installation over administrative depth.
- Large Enterprises:Multi-site deployments require centralized policy orchestration, SIEM integration, and zero-trust architecture compatibility. Financial services and healthcare verticals in the US and Germany lead upgrade cycles for post-quantum readiness.
- Small and Medium Businesses:Bundled security suites with simplified management consoles reduce operational overhead, with cloud-delivered solutions displacing hardware appliances.
- Individual Users:Consumer-grade applications emphasize streaming unblocking and privacy marketing, with cross-selling pathways into business tiers underutilized.
- Government Agencies:FIPS 140-2 certification and classified-network accreditation requirements restrict vendor eligibility to specialized suppliers with established security clearances.
Large enterprises command the deepest per-account value; small and medium businesses are expanding most quickly as digitization penetrates previously underserved segments.
Technology:
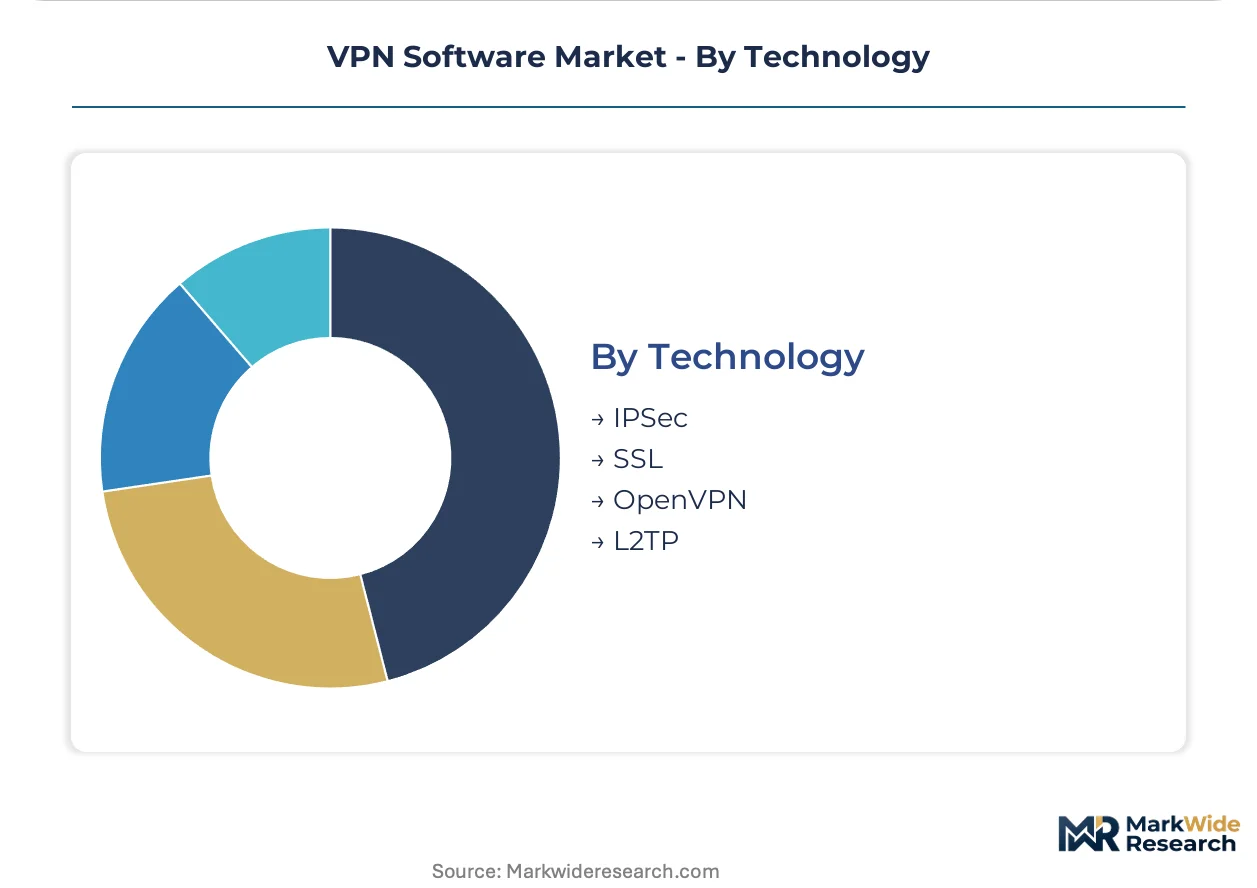
Protocol selection determines computational efficiency, interoperability breadth, and vulnerability surface, with newer lightweight implementations displacing legacy standards in mobile and IoT contexts.
- IPSec:Mature standard with broad router compatibility and established cryptographic libraries, though configuration complexity and connection latency disadvantage remote workforce scenarios.
- SSL:Browser-native transport layer security enables clientless access through standard HTTPS ports, simplifying deployment for contractor and partner access use cases.
- OpenVPN:Open-source implementation with cross-platform support and flexible authentication backends, favored by privacy-conscious organizations and technical users.
- L2TP:Layer-two tunneling paired with IPSec encryption persists in legacy Windows environments and telecommunications provider infrastructures.
IPSec maintains installed-base dominance; SSL and OpenVPN are gaining share fastest as browser-based and mobile-first architectures reshape access patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Federal Office for Information Security anchors European VPN demand through stringent baseline protection certification requirements. The country's automotive and industrial machinery clusters drive dense supplier network deployments.
United States
Financial services and healthcare enterprises in New York and California accelerate zero-trust migrations. FCC net-neutrality rulings shape infrastructure location decisions for domestic providers. The Washington DC metro corridor hosts government agencies requiring FIPS 140-2 accredited solutions for classified network access.
Germany
Automotive suppliers in Stuttgart and Munich operate multi-tier ecosystems requiring secure remote partner access. The EU AI Act's high-risk system designations compel auditable traffic routing through jurisdiction-specific nodes. Industrial conglomerates in the Ruhr region deploy cloud-based orchestration for thousands of external contractors.
China
Multinational manufacturers in Shanghai and Shenzhen face MIIT mandatory security assessments for cross-border data flows. The dual carbon goals drive energy-efficient protocol adoption in enterprise networks. Beijing's state-owned enterprises maintain strict data-localization compliance through sovereign gateway infrastructure.
India
Mid-market manufacturers in Maharashtra and Gujarat procure VPN functionality through MSSP channels lacking internal network engineering depth. The PLI scheme for electronics manufacturing attracts data center investment creating domestic node demand. Bangalore's technology services firms negotiate elastic subscription tiers for seasonal contractor scaling.
United Kingdom
Financial services firms in the City of London navigate Schrems II compliance requirements extending legal review cycles. GDPR adequacy determinations freeze procurement decisions for multinational configurations. Manchester and Birmingham healthcare networks prefer on-premises clusters under strict data-localization mandates.
VPN Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with enterprise platform providers commanding premium positioning against consumer-origin cross-sellers. The structure stratifies across three vertical layers: converged security platforms unifying networking with cloud-delivered functions, router-anchored incumbents leveraging decades of infrastructure integration, and privacy-marketing consumer brands attempting business-tier migration. Dominant competitive moves include embedding VPN functions within broader SASE architectures and converting perpetual-license customers into recurring-revenue relationships through elastic subscription models.
Within the consumer-origin tier, NordVPN and ExpressVPN exemplify brands leveraging privacy marketing recognition toward business solution expansion. Cisco Systems, Inc. occupies the enterprise infrastructure anchor position, while Palo Alto Networks, Inc. represents the converged platform archetype embedding tunneling within unified security stacks. These three patterns illustrate how competitive positioning fragments across origin stories and customer acquisition channels rather than technology differentiation alone.
| Leading Market Players |
|---|
| NordVPN |
| ExpressVPN |
| CyberGhost |
| Surfshark |
| ProtonVPN |
| Private Internet Access |
| Cisco Systems, Inc. |
| Palo Alto Networks, Inc. |
| Fortinet, Inc. |
| Others |
Value Network & Pricing Analysis
Capacity-reservation contracts with cloud infrastructure providers lock in both compute access and predictable unit economics for VPN software vendors serving enterprise clients. These arrangements tether pricing visibility to foundry allocation cycles and data center buildout timelines across key jurisdictions.
Pricing Analysis
Subscription-based SaaS tiers dominate enterprise procurement, with elastic concurrent-session licensing displacing fixed-seat agreements. Price differentiation rests on FIPS 140-2 certification grade and managed service attach rates. Cost compression in the mid-market segment intensifies as SASE platforms bundle tunneling functions at marginal cost. Small and medium businesses exhibit highest price sensitivity, while financial services and government agencies absorb premium tiers for compliance-grade features.
Supply Chain Analysis
Taiwan and South Korea anchor cryptographic processor fabrication, while the United States and Ireland concentrate data center infrastructure for cloud-based VPN delivery. The supply chain draws from specialized silicon foundries, hardware security module manufacturers, and hyperscale cloud operators. Single-source vulnerability in TSMC advanced node allocation threatens delivery timelines for appliance-integrated solutions. Distribution runs through direct enterprise sales, MSSP channels, and cloud marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Standalone VPN vendors face substitution pressure from converged SASE platforms that absorb tunneling into unified security stacks. Incumbents must navigate this threat through strategic repositioning.
For Market Incumbents: Fortify platform integration by embedding VPN functions within broader zero-trust architectures that SIEM vendors cannot easily replicate. Prioritize certification investment in FIPS 140-2 and EU AI Act compliance to maintain government and regulated-industry access. Vertical integration into managed service delivery captures margin pools that pure-software competitors cannot reach.
For New Entrants and Emerging Players: Differentiate on post-quantum cryptography readiness as NIST-standardized algorithms create upgrade cycles ahead of regulatory mandates. Target India's mid-market manufacturing segment through MSSP partnerships where network engineering skills scarcity blocks self-managed deployment. Lead with WireGuard protocol efficiency for mobile-first and IoT-heavy use cases that legacy IPSec vendors serve poorly.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native vendors with elastic subscription models and managed service attach rates above forty percent. Long-term viability over the next decade hinges on SASE platform integration depth rather than standalone tunneling technology. Monitor NIST post-quantum standardization timelines as the critical inflection signal for compliance-driven upgrade spending.
| Strategic Initiative | Industry Significance |
|---|---|
| SASE Platform Integration | Embedding VPN within unified security stacks defends against standalone displacement by Palo Alto Networks and Zscaler. |
| Post-Quantum Cryptography Launch | NIST-standardized algorithm deployment differentiates offerings ahead of German BSI and US NSA compliance mandates. |
| Managed Service Expansion | Third-party lifecycle management captures mid-market manufacturers in India and Brazil lacking internal network engineering depth. |
| EU AI Act Compliance Certification | Auditable logging and jurisdiction-specific node deployment unlocks German automotive and French healthcare procurement. |
| WireGuard Protocol Migration | Lightweight implementation reduces mobile and IoT computational overhead against legacy IPSec incumbents. |
Research Methodology
A spread of perspectives from enterprise CISOs, cloud infrastructure architects, MSSP operations directors, and regulatory compliance officers converged on the working assumptions. Primary interviews combined with secondary validation from SEC filings, hyperscaler capex disclosures, and EU regulatory databases. Bottom-up deployment estimates and top-down security spending analysis triangulated market sizing across the projection horizon.
Segmentation dimensions modeled include deployment mode, service type, organization size, vertical industry, and regional regulatory framework. CAGRs derived from historical growth rate analysis adjusted for technology substitution effects and compliance-driven upgrade cycles. Post-quantum cryptography readiness and zero-trust architecture adoption velocity served as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained enterprise cloud migration and stable regulatory enforcement would require recalibration. Forecasts reflect documented assumptions regarding SASE platform substitution rates and certificate authority trust stability. Recalibration cycles align with material shifts in NIST standardization timelines and EU AI Act implementation guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
SSL Inspection Solution Market
Security Software
ATM Security Market
Security Software
Security Testing Market
Security Software
Global Data Protection As a Service (Dpaas) Market
Security Software
Device-Embedded Biometric Authentication Market
Security Software
Identity-As-A-Service (Idaas) Market
Security Software
User Provisioning Software Market
Security Software
Global Network Encryption Market
Security Software
Global User Activity Monitoring Market
Security Software
Network Camera and Video Analytics Market
Security Software
Global Security Software in Telecom Market
Security Software
Employee Fraud Detection Market
Security Software
Vsaas Market
Security Software
Global Insider Threat Management ITM Software Market
Security Software
Global Email Verification Tools Market
Security Software
Mobile Antivirus Software Market