
 Glazing Machine Market | 2026-2036
Glazing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Glazing Machine Market Foresight
CE marking under the EU Construction Products Regulation is bifurcating the competitive landscape for glazing equipment sold into European markets. LiSEC Group leverages its vertical integration across insulating glass lines to sustain pricing power in automated sealing stations. Bottero S.p.A. anchors its position through deep specialization in cutting and grinding pre-processors that feed downstream glazing operations. Hegla GmbH & Co. KG differentiates via control over in-house logistics automation that links washing, coating, and assembly stages.
Glazing machines apply controlled layers of sealants, coatings, or adhesives onto glass substrates using precision dispensing, robotic handling, or CNC-guided applicator heads operating at tolerances below 0.1 mm to achieve thermal, optical, or structural performance. Automatic glazing systems dominate capital deployment among architectural glass fabricators seeking throughput above 1,000 units per shift. Robotic coating cells represent the fastest-expanding technology segment as solar panel manufacturers adopt curtain coating for anti-reflective layers on photovoltaic cover glass.
EMA machinery safety directives, EPA emissions standards for solvent-based coating operations, and REACH chemical restrictions on sealant formulations collectively elevate compliance costs for glazing machine builders and their customers. The EU F-Gas Regulation specifically pressures insulating glass producers to verify gas-fill accuracy, tightening specifications for automated spacer bar and sealing equipment. Stakeholders must monitor how regional carbon border adjustments reshape equipment sourcing decisions for glass fabricators serving export markets.
Market Dynamics
Automated sealing stations are compressing production cycles for insulating glass units as fabricators face tightening EU F-Gas Regulation verification requirements for gas-fill accuracy. Equipment buyers now prioritize throughput above 1,000 units per shift over incremental precision gains.
Growth Catalysts
- EU F-Gas Regulation:Mandates for gas-fill verification accuracy in insulating glass units are forcing fabricators to replace manual sealing with automated spacer bar and sealing equipment.
- Photovoltaic manufacturing:Solar panel producers are adopting curtain coating for anti-reflective layers on photovoltaic cover glass, expanding the addressable base for robotic coating cells.
- German window renovation rates:Elevated replacement demand for energy-efficient fenestration sustains capital deployment in automated glazing lines among architectural glass fabricators.
Market Restraints
- REACH chemical restrictions:Sealant formulation compliance costs are elevating total cost of ownership for glazing machine operators and constraining formulation flexibility.
- Specialized component supply:Precision dispensing heads and CNC-guided applicator systems concentrate among a limited supplier base in Germany and Italy.
- Silicone price volatility:Primary sealant material cost swings compress margin predictability for coating equipment operators running solvent-based processes.
Strategic Opportunities
- India's PLI scheme for solar:Domestic photovoltaic manufacturing incentives are creating first-mover advantage for glazing equipment vendors establishing local coating cell installations.
- Curtain coating-sputtering convergence:Hybrid deposition systems combining liquid curtain coating with thin-film sputtering enable multi-layer anti-reflective stack production in single-pass configurations.
- Service contract unbundling:Predictive maintenance subscriptions for robotic handling systems represent recurring revenue expansion beyond equipment sale margins.
Industry Challenges
- Multi-axis programming expertise:Robotic coating cell deployment requires scarce CNC-guided applicator calibration specialists, extending commissioning timelines.
- CE marking timeline compression:Evolving EU Construction Products Regulation requirements for insulating glass units are lengthening equipment certification cycles before market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glazing Machine Market |
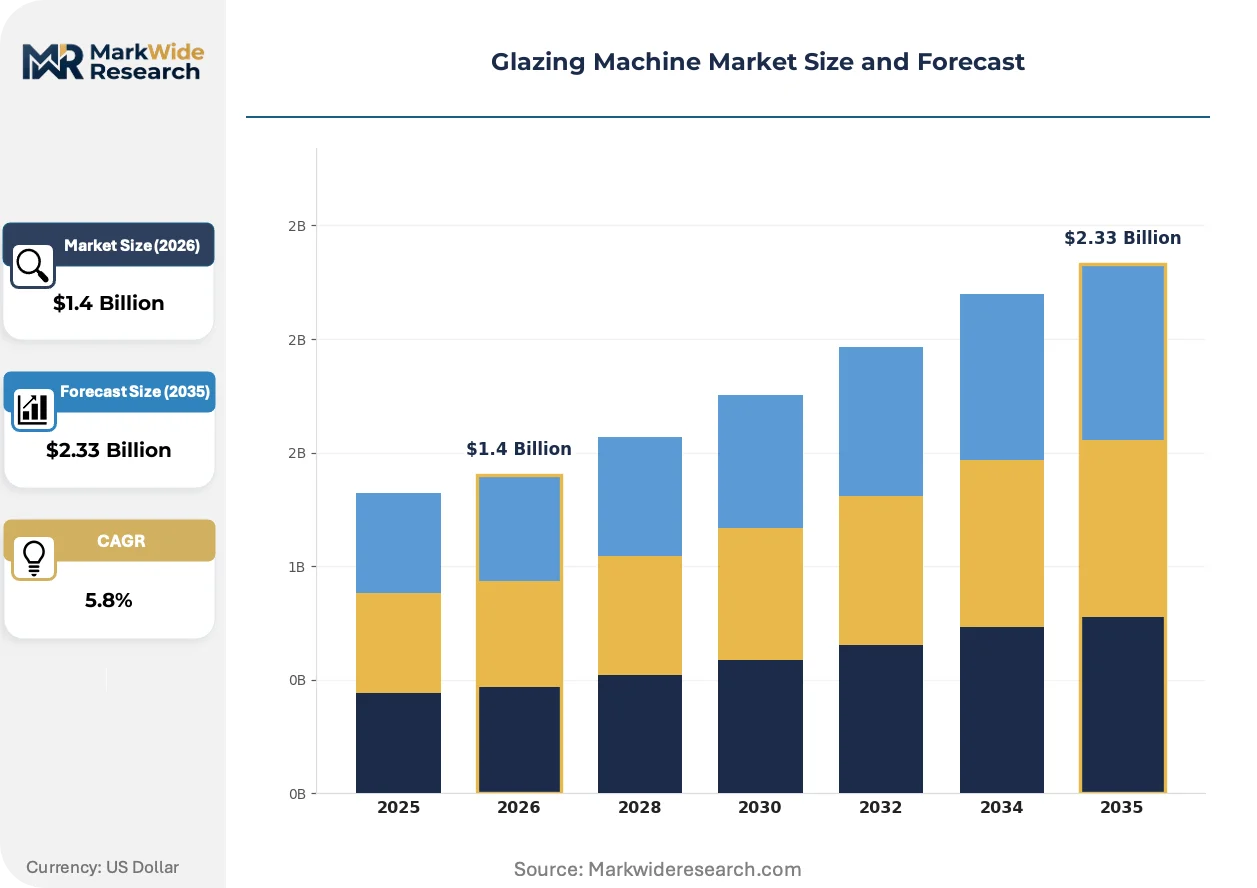
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, CNC, Robotic Technology: Screen Printing, Roll Coating, Curtain Coating, Dip Coating, Spray Coating Application: Automobile Components, Ceramics, Electronic Displays, Architectural Glass, Solar Panels End User: OEM Manufacturers, Aftermarket Providers, Glass Fabricators, Solar Equipment Producers, Electronics Assemblers |
| Companies Covered | LiSEC Group, Bottero S.p.A., Bystronic Glass, Hegla GmbH & Co. KG, Bosch Rexroth AG, Jinan Sinon CNC Machine Co., Ltd., Forel SPA, Thermoseal Group, CMS Glass Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glazing Machine Market Shifts & Advancements
Precision dispensing architectures are converging with machine vision feedback loops to enable real-time sealant bead geometry correction. Equipment vendors are repositioning around closed-loop process control as the primary competitive differentiator.
Electrostatic spray deposition for low-emissivity coatings is supplanting conventional sputtering lines in architectural glass fabrication. Mid-sized European window manufacturers are adopting electrostatic cells to reduce chamber downtime and gas consumption. The technology is compressing capital intensity thresholds for energy-efficient coating capacity.
EPA emissions standards for solvent-based coating operations are tightening volatile organic compound thresholds in US manufacturing zones. Architectural glass fabricators serving North American markets are accelerating waterborne sealant formulation transitions. Equipment suppliers are responding with modified dispensing head materials compatible with reduced-solvent chemistries.
Buyer concentration among national window renovation programs is compressing procurement cycles for automated glazing lines. Large German fabricators are consolidating supplier relationships toward single-source line integration contracts. This pattern is most visible in the Rhine-Ruhr industrial cluster where energy-efficiency mandates drive synchronized equipment refresh schedules.
Glazing Machine Market Segmentation
Segmentation in glazing equipment reveals how capital deployment priorities diverge across automation levels, coating technologies, and end-use specifications. Equipment vendors must align product architectures with distinct buyer workflows ranging from high-volume architectural glass lines to precision solar coating cells.
Product Type:
Automatic systems move through direct sales channels and systems integrators serving high-volume architectural glass fabricators, while manual and semi-automatic units distribute through regional machinery dealers targeting smaller window manufacturers.
- Automatic:These systems integrate washing, coating, sealing, and gas-filling stations into continuous lines operating above 1,000 units per shift. Demand concentrates among German architectural glass fabricators facing EU F-Gas Regulation compliance deadlines for insulating glass verification.
- Robotic:Articulated-arm applicators with CNC-guided heads achieve sub-0.1 mm tolerances for anti-reflective coating on photovoltaic cover glass. Solar panel manufacturers in India under the PLI scheme are driving the steepest expansion trajectory for robotic coating cell installations.
- Semi-Automatic:Batch-mode systems with operator-assisted loading serve mid-sized European window manufacturers upgrading from manual sealing.
- CNC:Computer-numerical control architectures enable programmable bead geometry for complex insulating glass spacer configurations.
- Manual:Hand-operated dispensing equipment persists in aftermarket repair operations and developing market small fabricators.
Automatic systems dominate installed base. Robotic configurations are where expansion concentrates.
Technology:
Cost tiers separate these technologies, with curtain coating and sputtering hybrids commanding premium positioning against commodity spray and dip alternatives.
- Curtain Coating:Gravity-fed liquid film deposition creates uniform anti-reflective layers on photovoltaic glass at throughput rates exceeding roll coating alternatives. Solar equipment producers in India and Germany are prioritizing curtain coating cells for anti-reflective stack production.
- Screen Printing:Mesh-based stencil deposition applies conductive silver pastes and ceramic frits for automotive and electronic display applications. Electronics assemblers in East Asia sustain demand for precision screen printing architectures.
- Roll Coating:Direct-transfer roller systems serve high-volume architectural glass low-emissivity coating with lower capital intensity than vacuum deposition.
- Spray Coating:Pneumatic atomization systems face EPA emissions standard pressures in US manufacturing zones, accelerating waterborne formulation transitions.
- Dip Coating:Immersion-based deposition persists in ceramic glazing and specialty optical applications requiring thick film builds.
Screen printing anchors legacy installed base. Curtain coating is gaining share fastest among new capacity additions.
Application:
Volume concentration varies sharply by application, with architectural glass consuming multi-station lines while solar and automotive applications drive single-purpose robotic cell demand.
- Architectural Glass:Insulating glass units, tempered facades, and low-emissivity windows require integrated washing, coating, and sealing sequences. German window renovation programs and Rhine-Ruhr industrial cluster equipment refresh cycles sustain capital deployment.
- Solar Panels:Photovoltaic cover glass demands anti-reflective and anti-soiling coatings to maximize energy yield. India's PLI scheme for domestic solar manufacturing is creating first-mover opportunities for coating equipment vendors establishing local installations.
- Automobile Components:Windshield and backlight glazing requires precision sealant application for structural bonding and acoustic dampening.
- Electronic Displays:Touch panel and cover glass coating demands sub-micron thickness control for optical clarity.
- Ceramics:Tile and sanitary ware glazing applies decorative and protective layers through adapted glass coating architectures.
Architectural glass commands the largest share of line-integrated system sales. Solar panel applications are where technology differentiation matters most.
End User:
Customer type determines procurement patterns, with OEM manufacturers pursuing single-source line integration contracts and aftermarket providers sourcing modular replacement equipment.
- Glass Fabricators:Architectural and automotive specialists purchase integrated glazing lines with automated sealing stations. Large German fabricators are consolidating supplier relationships toward single-source contracts spanning washing through gas-filling operations.
- Solar Equipment Producers:Photovoltaic module manufacturers adopt robotic coating cells for anti-reflective deposition on cover glass. India's domestic manufacturing incentives are accelerating local procurement of curtain coating systems.
- OEM Manufacturers:Original equipment manufacturers in automotive and electronics specify coating equipment for captive production lines.
- Electronics Assemblers:Display and touch panel producers require precision coating for cover glass and sensor substrates.
- Aftermarket Providers:Repair and replacement glazing operations source semi-automatic and manual equipment for lower-volume batch processing.
Glass fabricators represent the dominant customer category by system value. Solar equipment producers are where vendor margins expand most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation verification mandates are redirecting capital toward automated glazing lines in Germany, while India's PLI scheme for solar manufacturing is accelerating robotic coating cell procurement. Equipment vendors are establishing regional service hubs to support localized compliance requirements.
Germany
Window renovation rates in the Rhine-Ruhr industrial cluster sustain demand for integrated insulating glass lines. The EU F-Gas Regulation tightens gas-fill accuracy specifications, forcing fabricators toward automated spacer bar equipment. Stuttgart and Munich host concentrated equipment refresh cycles as energy-efficiency mandates compress procurement timelines.
United States
EPA emissions standards for solvent-based coating operations are accelerating waterborne sealant transitions in architectural glass fabrication. OSHA machinery safety directives elevate compliance costs for glazing line operators. The Southeast industrial corridor, particularly Georgia and the Carolinas, sees expanding automated sealing station deployment serving regional window manufacturers.
India
Domestic photovoltaic manufacturing incentives under the PLI scheme are creating first-mover opportunities for curtain coating cell installations. The Bureau of Indian Standards (BIS) certification requirements for insulating glass products are tightening equipment specifications. Gujarat and Tamil Nadu industrial zones concentrate new solar glass coating capacity as module producers localize supply chains.
China
Dual carbon goals under MIIT industrial policy are pressuring glass fabricators toward low-emissivity coating equipment upgrades. GB standards for energy-efficient building materials are tightening performance thresholds for insulating glass units. The Yangtze River Delta and Pearl River Delta clusters drive capital deployment in precision dispensing architectures for export-oriented architectural glass production.
Italy
Specialized cutting and grinding pre-processor demand feeds downstream glazing operations across Northern Italian glass fabrication networks. CE marking requirements under the EU Construction Products Regulation lengthen equipment certification cycles for insulating glass unit machinery. The Veneto and Lombardy industrial districts maintain concentrated supplier relationships with German sealing equipment vendors.
Glazing Machine Market Competitive Landscape
Listed leaders compete with private specialists across automation intensity, creating a tiered structure where scale-driven system integrators face off against focused component suppliers. The vendor base concentrates around German and Italian engineering clusters, with equipment architectures diverging between line-integrated solutions and modular cell configurations. Two dominant competitive moves define positioning: backward integration into precision dispensing component manufacturing, and strategic partnerships with solar panel producers for robotic coating cell deployment. Geographic proximity to glass fabrication clusters remains the decisive factor in service contract capture.
Within the line-integration tier, LiSEC Group and Hegla GmbH & Co. KG exemplify German-engineered system architectures, while Bottero S.p.A. anchors Italian specialization in pre-processing equipment that feeds downstream glazing operations. These three occupy positions spanning the value chain from cutting and grinding through automated sealing, representing distinct strategic postures on vertical scope versus focused component excellence. The competitive dynamic between them shapes procurement patterns among large architectural glass fabricators consolidating toward single-source supplier relationships.
| Leading Market Players |
|---|
| LiSEC Group |
| Bottero S.p.A. |
| Bystronic Glass |
| Hegla GmbH & Co. KG |
| Bosch Rexroth AG |
| Jinan Sinon CNC Machine Co., Ltd. |
| Forel SPA |
| Thermoseal Group |
| CMS Glass Machinery |
| Others |
Supply & Pricing Matrix
Waterborne sealant formulations replacing solvent-based chemistries under EPA emissions standards are simultaneously shifting procurement geography toward US Southeast fabricators and compressing margin structures for equipment vendors adapting dispensing head materials. This substitution dynamic concentrates pricing power with German and Italian component specialists while elevating total cost of ownership for operators running modified coating architectures.
Pricing Analysis
Certification level under EU CE marking and EPA emissions compliance creates the primary spread between premium automated sealing stations and standard semi-automatic configurations. Three-tier pricing structure across premium CE-marked lines, standard EPA-compliant systems, and economy manual units stratifies the installed base. Cost compression in standard-tier equipment is intensifying because REACH chemical restrictions elevate formulation compliance burdens. Mid-sized European window manufacturers exhibit highest price sensitivity, while large German fabricators consolidating toward single-source contracts demonstrate lowest sensitivity to unit pricing.
Supply Chain Analysis
Germany and Italy anchor precision dispensing head and CNC-guided applicator manufacturing for glazing machine builders worldwide. Component sourcing draws from specialized suppliers in Stuttgart, Munich, and Veneto industrial districts, with secondary feedstock reliance on silicone polymer producers in Belgium and the Netherlands. Single-source vulnerability concentrates in robotic coating cell calibration systems, where multi-axis programming expertise extends commissioning timelines. Distribution runs through direct sales channels for automatic line-integrated systems and regional machinery dealers for semi-automatic and manual equipment tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glazing machine market sits at a regulatory-inflection disruption where EU F-Gas verification mandates and India's PLI solar incentives are compressing procurement cycles and expanding addressable demand simultaneously.
For Market Incumbents: Secure backward integration into precision dispensing component manufacturing to defend margin position against REACH compliance cost escalations. Anchor capacity in the Rhine-Ruhr cluster to capture synchronized equipment refresh cycles driven by German window renovation programs. Certification investment in BIS compliance for Indian solar coating cells represents the priority defensive lever against emerging local competitors. For New Entrants and Emerging Players: Lead with robotic coating cell deployments targeting India's Gujarat and Tamil Nadu industrial zones under PLI scheme incentives, where first-mover advantage remains achievable. Curtain coating-sputtering hybrid architectures offer the most penetrable technology wedge for photovoltaic cover glass applications. A service-contract unbundling go-to-market approach generates recurring revenue streams that offset upfront equipment sale margin compression. For Investors and Strategic Acquirers: The market sits at an early-consolidation phase that favors specialized component suppliers with captive control over precision dispensing technologies. Long-term viability centers on vendors positioned at the convergence of architectural glass automation and solar coating cell expansion. The signal to watch is procurement pattern shifts among large German fabricators toward single-source line integration contracts as an indicator of vendor concentration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Dispensing | Captive control over CNC-guided applicator heads insulates LiSEC and Hegla from supply bottlenecks in German engineering clusters. |
| Curtain Coating-Sputtering Hybrid Development | Single-pass multi-layer deposition architectures capture solar panel manufacturers in India and Germany seeking yield optimization. |
| Regional Service Hub Establishment | Localized technical support in Gujarat and Tamil Nadu accelerates commissioning timelines for robotic coating cell installations. |
| Predictive Maintenance Subscription Launch | Recurring revenue expansion beyond equipment margins targets large fabricators with automated lines above 1,000 units per shift. |
| CE Marking Fast-Track Certification Investment | Compressed regulatory approval cycles address lengthening equipment certification timelines under evolving EU Construction Products Regulation. |
Research Methodology
Desk research of EU regulatory filings, EPA emissions standards documentation, and Indian PLI scheme notifications preceded structured interviews with architectural glass fabricator operations directors, solar equipment producer procurement leads, glazing machine vendor sales executives, and precision component supplier technical directors. Secondary validation incorporated customs trade data for glass fabrication machinery, SEC filings from listed equipment manufacturers, and BIS certification records for Indian insulating glass products. Bottom-up unit deployment estimates triangulated against top-down market sizing derived from regional window renovation program budgets and photovoltaic manufacturing capacity announcements.
Variance decomposition across product type, technology, application, and end-user dimensions structured the analytical framework over the projection horizon. Modeled segmentation captured automatic versus robotic system deployment, curtain coating versus screen printing technology adoption, architectural glass versus solar panel application splits, and glass fabricator versus solar equipment producer customer categories. CAGRs were derived from regression analysis of historical capital expenditure patterns against regulatory deadline schedules and manufacturing incentive program timelines. Industry-specific forecast inputs included EU F-Gas Regulation compliance cost trajectories and India's domestic content requirement phase-in schedules.
Forecasts assume regulatory continuity in EU F-Gas verification mandates, EPA emissions thresholds, and Indian PLI incentive structures; material policy shifts would require re-modeling. Specific risks that could revise projections encompass REACH chemical restriction expansions affecting sealant formulations, silicone price volatility disrupting coating operation economics, and multi-axis programming talent scarcity extending robotic cell commissioning timelines. Recalibration cycles align with material shifts in regulatory enforcement intensity and solar manufacturing localization policy announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Lid Applicator Machine Market
Packaging Machinery
Vertical Bagging Machine Market
Packaging Machinery
Corrugated Box Printer Slotter Machine Market
Packaging Machinery
Meal Tray Sealing Machines Market
Packaging Machinery
Combination Filler Machine Market
Packaging Machinery
Carton Folding and Gluing Machine Market
Packaging Machinery
Folding Gluing Machines Market
Packaging Machinery
Box Sealing Machines Market
Packaging Machinery
Precision Dispensing Machine Market
Packaging Machinery
Strapping Machine Market
Packaging Machinery
Induction Sealing Machine Market
Packaging Machinery
Flow Pack Machine Market
Packaging Machinery
Form-Fill-Seal Equipment Market
Packaging Machinery
Global Food and Beverage Packaging Machinery Market
Packaging Machinery
Palletizing Machines Market
Packaging Machinery
Paper Napkin Converting Lines Market