
 North America Cosmetic Packaging Market | 2026-2036
North America Cosmetic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cosmetic Packaging Market Analytics
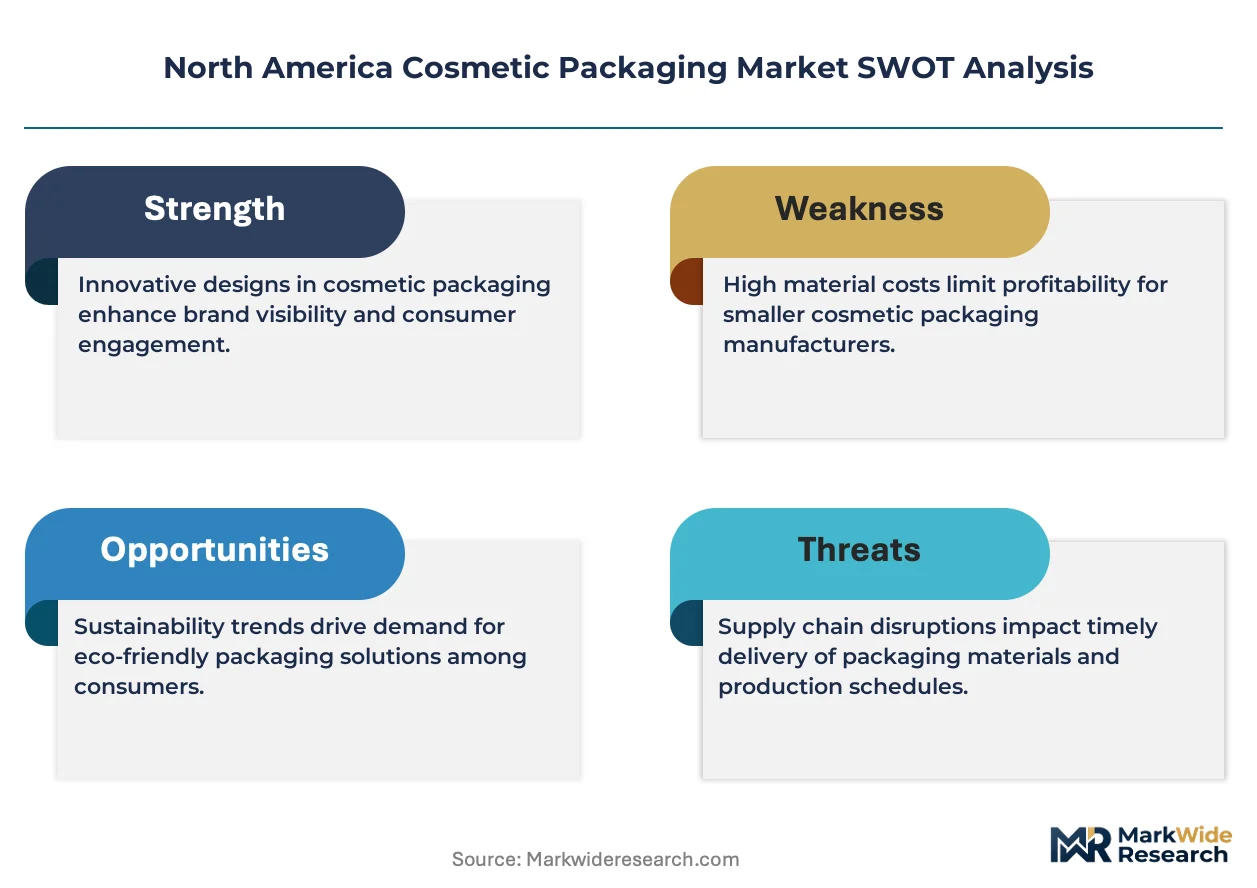
Indie beauty brands and direct-to-consumer labels are redrawing procurement priorities across North America cosmetic packaging. These buyers prioritize small-batch flexibility, recycled content verification, and rapid turnaround over volume scale. Amcor PLC leverages its North American film and rigid plastics footprint to serve mid-tier skincare clients with certified post-consumer resin streams. AptarGroup, Inc. dominates airless pump and precision dispensing technology for high-end serum and treatment formats. Silgan Holdings Inc. anchors metal and closure supply for heritage fragrance houses with stable, long-run contracts.
Cosmetic packaging encompasses primary and secondary containment systems engineered to protect formulation integrity, enable controlled dispensing, and communicate brand identity through substrate selection, decoration, and structural geometry. Materials range from borosilicate glass for fragrance and active skincare to multi-layer polyethylene tubes for haircare and travel-size formats, with barrier properties calibrated against oxygen transmission and UV degradation thresholds. Plastic bottles and tubes lead volume throughput across mass-market haircare and body care, while glass jars command premium positioning in skincare where tactile weight and chemical inertness justify higher unit costs. Pump and sprayer closure types are expanding fastest as serum, mist, and sunscreen formats displace traditional open-mouth jars across prestige and clinical beauty lines.
The US Food and Drug Administration governs cosmetic labeling and ingredient disclosure under the Federal Food, Drug, and Cosmetic Act, while state regulators in California enforce Proposition 65 warning requirements and emerging extended producer responsibility frameworks. Health Canada and the Canadian Food Inspection Agency administer parallel cosmetic notification and safety standards that shape cross-border product and packaging compliance. Stakeholders must monitor how fragmented state-level packaging EPR legislation converges with federal preemption debates, as this regulatory uncertainty will determine capital allocation between domestic molding capacity and nearshore supply restructuring.
Market Dynamics
Refillable and airless dispensing systems are forcing capital reallocation across North American cosmetic packaging as skincare brands pursue circularity targets and formulation stability requirements simultaneously.
Growth Catalysts
- California's Extended Producer Responsibility frameworks:State-level mandates for material traceability are accelerating investment in certified recycled resin streams and closed-loop collection infrastructure.
- Serum and treatment format expansion:Prestige skincare lines are converting from open-mouth jars to precision pump systems, creating sustained demand for high-barrier airless technologies.
- Northeast corridor innovation clusters:Geographic concentration of premium beauty headquarters in Boston-to-New York corridor is concentrating R&D partnerships and pilot-scale manufacturing capacity.
Market Restraints
- Post-consumer resin price volatility:Fluctuating availability of food-grade recycled polyethylene and polypropylene is compressing margin predictability for mid-tier converters.
- Domestic blow-molding capacity concentration:Limited qualified suppliers for pharmaceutical-grade barrier bottles in the US Midwest creates single-source vulnerability for clinical beauty launches.
- Multi-layer tube recycling incompatibility:Current mechanical recycling infrastructure cannot process EVOH-barrier laminates, constraining circularity claims for haircare and sunscreen tubes.
Strategic Opportunities
- Mexico nearshoring for US-bound volume:Emerging thermoforming and injection molding clusters in Querétaro and Guanajuato offer tariff-advantaged capacity for mass-market haircare brands.
- Mono-material pump innovation:Convergence of all-polypropylene spring mechanisms with polyethylene bottle bodies enables full-package recyclability without performance sacrifice.
- Direct-to-consumer sampling formats:Single-dose pod and ampoule systems are capturing trial-size demand previously served by multi-use minis, opening specialty equipment investment.
Industry Challenges
- Colorant and additive compliance timelines:FDA color certification and state-level Proposition 65 reformulation requirements are extending new packaging development cycles by 8-14 months.
- Decorative metallization skill scarcity:Vacuum deposition and hot-stamping technicians with cosmetic-grade quality experience command premium wages in New Jersey and California packaging corridors.
- Legacy ERP integration with traceability platforms:Batch-level resin provenance tracking required by emerging EPR laws conflicts with decades-old manufacturing execution systems at family-owned converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cosmetic Packaging Market |
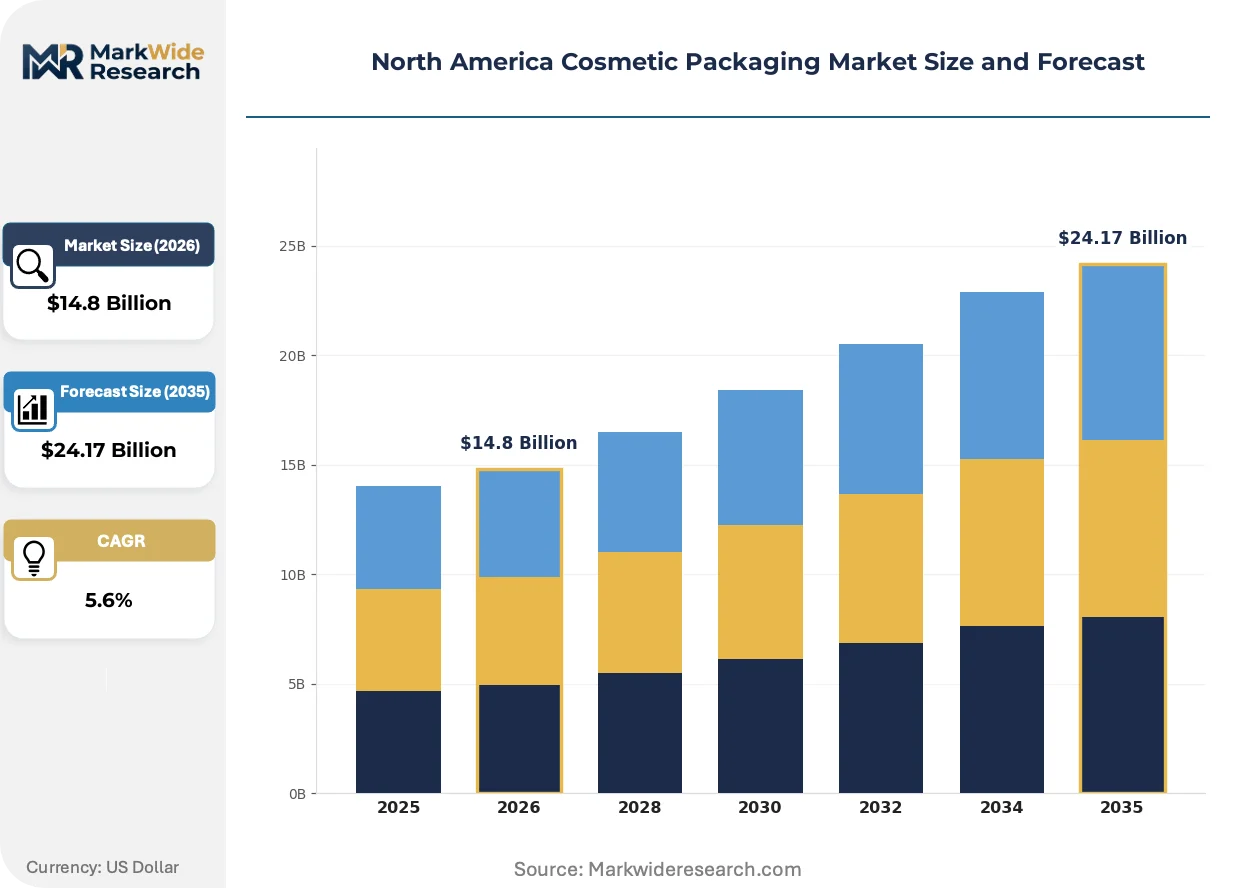
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Tubes, Sachets Material: Plastic, Glass, Metal, Paperboard Closure Type: Screw Caps, Flip-tops, Pumps, Sprayers End User: Makeup, Skincare, Haircare, Fragrance |
| Companies Covered | Silgan Holdings Inc., Graphic Packaging Holding Co, Albea Group, DS Smith plc, Amcor PLC, AptarGroup, Inc., HCP Packaging, Gerresheimer AG, Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cosmetic Packaging Market Evolving Landscape
Material science breakthroughs and regulatory precision are converging to redefine performance standards across primary and secondary cosmetic containment. Three developments are commanding disproportionate capital allocation.
Airless pump systems with piston-based product evacuation are displacing traditional dip-tube dispensers in active skincare and probiotic formulations. Prestige brands and dermatological lines are adopting these systems to prevent oxidation and microbial contamination. The technology is displacing glass jar formats that previously dominated premium anti-aging and vitamin C categories.
The US FDA is tightening enforcement of cosmetic ingredient labeling under modernized Federal Food, Drug, and Cosmetic Act authorities while California's Proposition 65 warning requirements expand to cover additional packaging migrants and residual monomers. This dual-track regulatory pressure is forcing reformulation of adhesives, inks, and barrier coatings. Fragrance houses with heritage glass-and-metal formats are experiencing the steepest compliance cost escalation.
Indie beauty brands are consolidating purchasing through specialized packaging distributors rather than direct mill relationships. These buyers prioritize small-batch flexibility and rapid prototyping over volume discounts, compressing traditional minimum order quantity structures. California and New York direct-to-consumer labels are driving this behavioral shift most visibly, with turnaround expectations of 4-6 weeks versus standard 12-16 week industry norms.
North America Cosmetic Packaging Market Segmentation
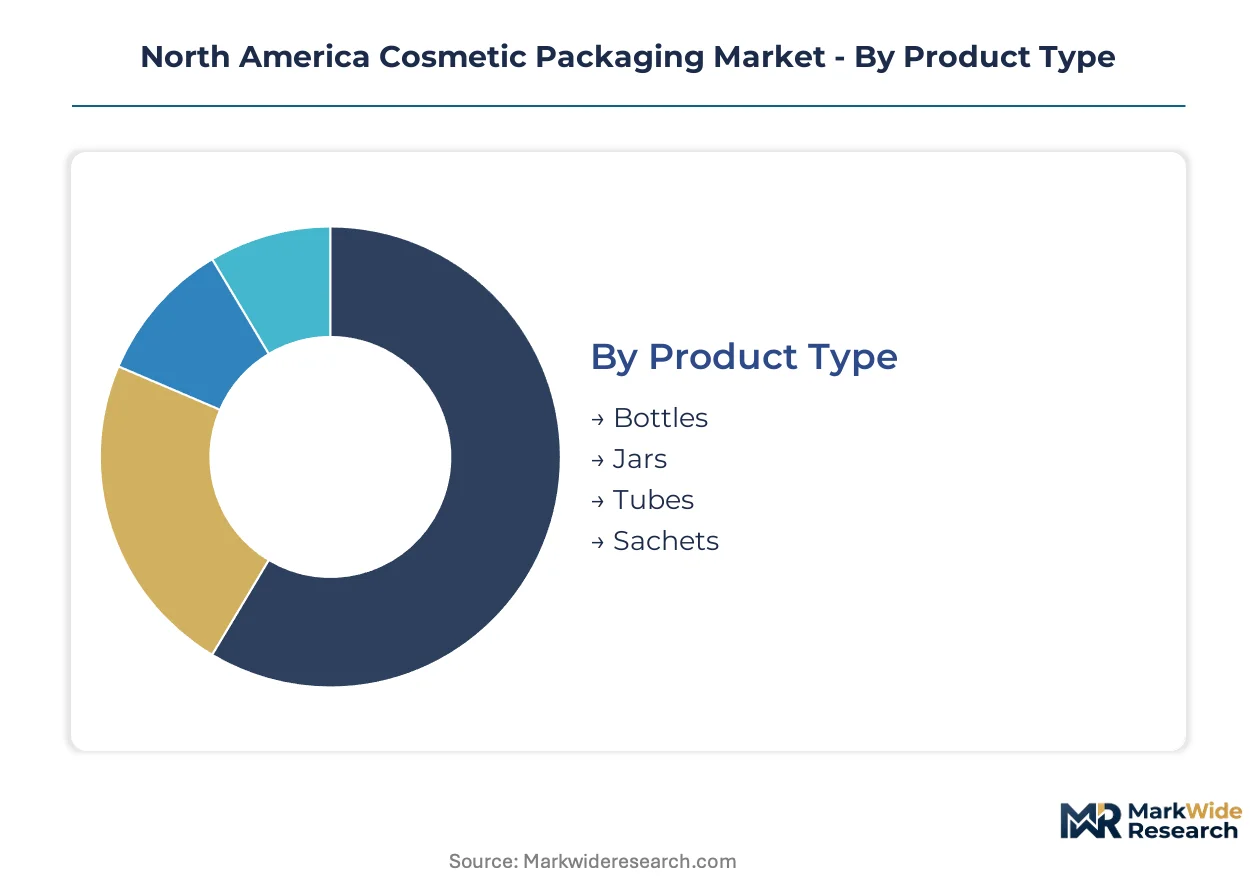
Packaging format decisions in North American cosmetics reflect tension between formulation protection requirements and circular economy mandates. Each segment category carries distinct substitution pressures as brands reformulate portfolios around refillable systems and mono-material recyclability.
Product Type:
Pump-dispensed formats are displacing open-mouth containers fastest across prestige skincare lines, forcing converters to reallocate blow-molding capacity toward airless-compatible geometries.
- Bottles:Polyethylene terephthalate and high-density polyethylene dominate mass-market haircare and body wash applications. California-based direct-to-consumer brands are driving demand for post-consumer resin certification and narrow-neck geometries compatible with trigger sprayers.
- Jars:Wide-mouth glass and thick-walled polypropylene structures serve solid balms and waterless formulations. Northeast corridor skincare headquarters are converting jar SKUs to refillable pod systems, compressing primary container volumes.
- Tubes:Multi-layer laminates with ethylene vinyl alcohol barriers protect retinol and sunscreen formulations. Mechanical recycling incompatibility constrains circularity claims for these formats.
- Sachets:Single-dose flexible pouches capture sampling and travel-size demand. Mono-material polyethylene variants are gaining preference over aluminum-laminate predecessors.
Bottles retain volume leadership across haircare and body care; pumps and sprayers hold the steepest expansion curve as serum formats displace traditional jars.
Material:
Cost tier stratification separates pharmaceutical-grade glass from commodity plastics, with recycled content premiums widening spreads between certified and virgin resin streams.
- Plastic:Polypropylene and polyethylene lead throughput across mass-market applications. FDA food-contact certification and California Proposition 65 compliance are extending qualification timelines for recycled resin integration.
- Glass:Borosilicate and soda-lime compositions command premium positioning in fragrance and active skincare. Tactile weight and chemical inertness justify unit cost premiums in dermatological lines.
- Metal:Aluminum bottles and tinplate aerosols serve heritage fragrance houses and dry shampoo formats. Domestic canmaking capacity concentrates in Midwest manufacturing corridors.
- Paperboard:Folding cartons and rigid boxes provide secondary containment and shelf presence. Moisture barrier coatings face reformulation pressure under evolving FDA labeling enforcement.
Plastic maintains absolute volume dominance; glass is climbing the fastest as premium skincare brands emphasize perceived formulation integrity.
Closure Type:
Precision dispensing mechanisms are capturing margin concentration previously held by commodity screw closures, with airless pump patents creating supplier stickiness.
- Screw Caps:Polypropylene continuous-thread designs serve standard bottles and jars. Thread standardization enables cross-supplier compatibility but limits differentiation.
- Flip-tops:Living-hinge polypropylene structures dominate shampoo and conditioner tubes. One-handed operation drives preference in shower-use contexts.
- Pumps:Piston-based airless systems prevent oxidation in vitamin C and retinol formulations. AptarGroup and Silgan Holdings anchor supply for prestige skincare clients.
- Sprayers:Fine-mist and foam actuators serve sunscreen, setting spray, and dry shampoo formats. Bag-on-valve systems are displacing traditional dip-tube designs.
Screw caps retain volume leadership across mass-market haircare; airless pumps are gaining share fastest as clinical beauty lines expand.
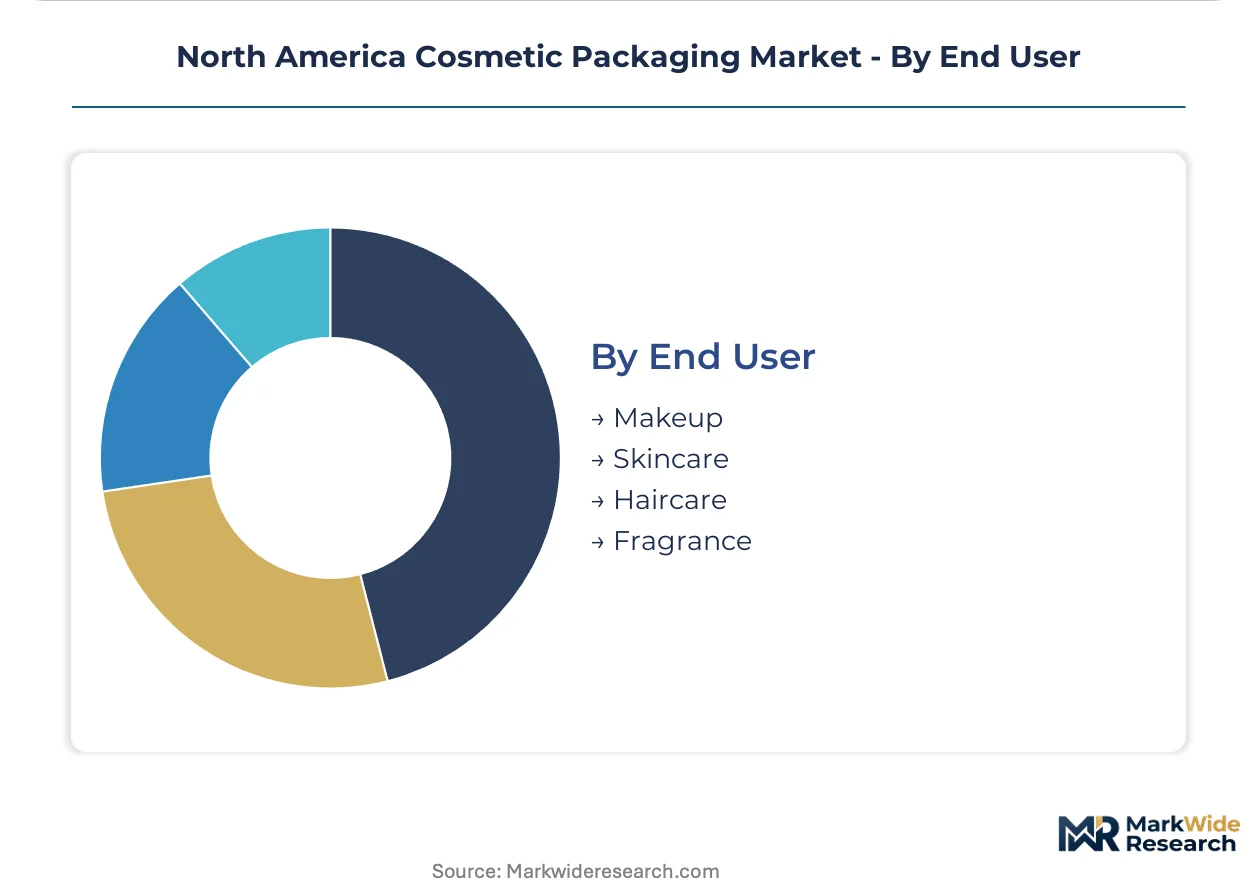
End User:
Customer type segmentation reveals divergent procurement patterns between heritage fragrance houses with stable long-run contracts and indie beauty labels demanding rapid prototyping flexibility.
- Makeup:Compact cases, cushion foundations, and lip bullet formats require precise mechanism tolerances. Airless pump integration is limited compared to skincare applications.
- Skincare:Serum, treatment, and probiotic formats drive airless pump and ampoule demand. California and Northeast corridor brands are consolidating purchasing through specialized distributors.
- Haircare:High-volume bottles and tubes dominate throughput. Extended producer responsibility frameworks are pressuring mono-material conversion for recycling compatibility.
- Fragrance:Heritage glass bottles with metal closures command stable, long-run supply relationships. Decorative metallization skill scarcity constrains capacity expansion.
Haircare retains volume leadership across North American throughput; skincare is expanding most quickly as treatment formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates along the US-Canada border corridor and Mexico's central highlands, where converter capacity clusters within trucking distance of major beauty brand headquarters. California's regulatory stringency and the Northeast's R&D density are redrawing procurement patterns across the continent.
United States
California's Proposition 65 enforcement and emerging extended producer responsibility laws are forcing reformulation of packaging migrants and adhesives. The FDA's modernized cosmetic labeling authorities under the Federal Food, Drug, and Cosmetic Act are extending qualification timelines for recycled resin integration. The Boston-to-New York corridor concentrates premium beauty headquarters and pilot-scale manufacturing partnerships.
Canada
Health Canada and the Canadian Food Inspection Agency administer parallel cosmetic notification standards that shape cross-border compliance strategies. Ontario's manufacturing base supplies folding cartons and rigid boxes for US-bound prestige brands. Toronto and Montreal anchor specialized distributors serving indie beauty labels with rapid-turnaround expectations.
Mexico
Nearshoring momentum is accelerating thermoforming and injection molding investment in Querétaro and Guanajuato for tariff-advantaged US supply. The country's national environmental regulator is developing packaging waste frameworks that anticipate convergence with California's material traceability requirements. Mexico City Metro hosts regional headquarters for multinational converters targeting North American volume.
North America Cosmetic Packaging Market Competitive Landscape
Concentration sits with diversified packaging conglomerates and specialized dispensing technology providers. The market exhibits tiered structure, with global converters holding long-run fragrance contracts while mid-tier players capture indie beauty flexibility demands. Three archetypes dominate: integrated rigid plastics specialists, precision pump and closure engineers, and metal-and-glass heritage suppliers. Competitive moves center on certified recycled resin stream development and airless technology patent licensing.
Among North American converters, Silgan Holdings Inc., AptarGroup, Inc., and Amcor PLC exemplify distinct strategic positions. Silgan anchors metal and closure supply for established fragrance houses through stable contract structures. AptarGroup occupies the precision dispensing tier with airless pump technologies for clinical skincare formats. Amcor leverages film and rigid plastics scale to serve mid-tier clients with post-consumer resin certification capabilities.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| Graphic Packaging Holding Co |
| Albea Group |
| DS Smith plc |
| Amcor PLC |
| AptarGroup, Inc. |
| HCP Packaging |
| Gerresheimer AG |
| Berry Global Inc. |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between heritage fragrance houses and Midwest metal closure suppliers lock in multi-year price visibility while insulating converters from post-consumer resin volatility. These contract structures concentrate purchasing power among established buyers and compress spot-market flexibility for mid-tier skincare labels.
Pricing Analysis
Volume-discount tiering separates heritage fragrance contracts from indie beauty spot purchases, with the former commanding 40-60% lower unit costs at 10M+ annual volumes. Price differentiation hinges on FDA food-contact certification tier and California Proposition 65 compliance status, not substrate alone. Cost compression in post-consumer polyethylene streams is intensifying because food-grade recycled resin availability fluctuates with municipal collection economics. Mass-market haircare brands exhibit highest price sensitivity, while prestige skincare houses absorb premiums for airless pump integration.
Supply Chain Analysis
Inventory lead-times for airless pump mechanisms now stretch 14-20 weeks as AptarGroup and Silgan Holdings manage precision component backlogs. Geographic supply concentration centers on the US Midwest for metal closures, New Jersey for decorative metallization, and Querétaro for tariff-advantaged thermoforming. Raw material dependencies include borosilicate glass from domestic specialty melt houses, pharmaceutical-grade polyethylene from Gulf Coast crackers, and EVOH barrier resins sourced from Japanese petrochemical complexes. Single-source vulnerability for clinical-grade barrier bottles in the US Midwest creates supply chain risk. Distribution runs through specialized packaging distributors serving indie beauty labels with 4-6 week turnaround expectations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended producer responsibility mandates and airless pump patent concentration are accelerating competitive disruption across North American cosmetic packaging. These regulatory and technological inflections favor converters with certified recycled resin streams and precision dispensing capabilities.
For Market Incumbents: Consolidate backward integration into post-consumer resin washing and pelletizing to secure California EPR-compliant supply chains. Acquire decorative metallization technicians in New Jersey and California corridors to defend against skill scarcity threatening heritage fragrance contract renewals. For New Entrants and Emerging Players: Anchor in mono-material pump engineering for haircare and body care segments where mechanical recycling compatibility commands EPR compliance premiums. Target direct-to-consumer sampling formats—single-dose pods and ampoules—where equipment specialization barriers deter incumbent reallocation. For Investors and Strategic Acquirers: Family-owned converters with legacy ERP systems and batch-level traceability capabilities represent prime acquisition targets as EPR mandates force technology refresh cycles. Watch for FDA enforcement patterns on cosmetic ingredient labeling as the signal indicating compliance cost escalation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Resin Certification Investment | California's EPR frameworks reward converters with verified recycled content streams. |
| Airless Pump Patent Licensing | AptarGroup's precision dispensing IP creates supplier stickiness in clinical skincare. |
| Nearshore Capacity Expansion | Querétaro thermoforming clusters offer tariff advantages for US-bound mass-market volume. |
| Mono-Material Format Conversion | All-polypropylene pump mechanisms enable full-package recyclability without performance sacrifice. |
| Specialized Distributor Partnership | Indie beauty procurement consolidation favors agile intermediaries over direct mill relationships. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with packaging procurement directors, sustainability officers at beauty brands, converter operations managers, and specialized distributor principals; and secondary validation through FDA cosmetic labeling enforcement records, California Proposition 65 regulatory filings, Health Canada notification databases, and customs trade data on resin and packaging machinery imports. Bottom-up capacity assessments at individual converter facilities were triangulated against top-down beauty brand procurement surveys.
Across the analysis window, forecasts were constructed using product type, material substrate, closure mechanism, and end-use application segmentation dimensions. CAGRs were derived from elasticity modeling of serum format penetration rates and EPR compliance cost pass-through assumptions. Industry-specific inputs included airless pump adoption curves in prestige skincare and post-consumer resin price volatility indices.
Decision-makers should treat outputs as directional under assumptions of stable FDA enforcement intensity and California EPR implementation timelines; material deviation in regulatory stringency would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Hair Care Packaging Market
Cosmetic Packaging
Single Portion Cosmetic Packaging Market
Cosmetic Packaging
Asia Pacific Personal Care Packaging Market
Cosmetic Packaging
Fragrance Packaging Market
Cosmetic Packaging
Beauty Supplements Packaging Market
Cosmetic Packaging
Cosmetic Tubes Market
Cosmetic Packaging
Global Cosmetic Packaging Market
Cosmetic Packaging
Europe Personal Care Packaging Market
Cosmetic Packaging
Cosmetic Vials Market
Cosmetic Packaging
Plastic Cosmetic Packaging Market
Cosmetic Packaging
Cream Jars Market
Cosmetic Packaging
Global Perfume Packaging Market
Cosmetic Packaging
Anti-Counterfeit Cosmetic Packaging Market
Cosmetic Packaging
India Personal Care Packaging Market
Cosmetic Packaging
Beauty and Personal Care Packaging Market
Cosmetic Packaging
US Personal Care Packaging Market