
 US Personal Care Packaging Market | 2026-2036
US Personal Care Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
US Personal Care Packaging Market Analytics
California's SB 54 extended producer responsibility law is shifting how brands specify primary packaging materials across the US personal care sector. Amcor plc leverages its recycled-content film platforms to anchor supply relationships with clean beauty formulators. Berry Global Group, Inc. competes through in-house production of post-consumer resin bottles for mass haircare lines. AptarGroup Inc. differentiates via airless pump technology leadership in premium skincare dispensing systems.
US personal care packaging encompasses primary and secondary containment systems engineered from plastics, glass, metal, or paper substrates to protect, dispense, and merchandise cosmetic and hygiene formulations with shelf-life stability and consumer ergonomics. Blow-molded bottles and extruded tubes dominate unit volume across haircare and skincare applications, though flexible pouches gain ground in travel-size and refill segments where e-commerce fulfillment efficiency matters. Glass jars retain margin concentration in prestige fragrance and facial treatment categories where perceived quality justifies higher material cost and shipping weight.
FDA cosmetic labeling requirements, combined with emerging state-level packaging extended producer responsibility frameworks and Federal Trade Commission green marketing guidance, collectively raise compliance thresholds for material claims and recyclability assertions. The FTC's Green Guides specifically constrain how brands communicate biodegradable or compostable attributes on personal care packaging, forcing reformulation of consumer-facing sustainability messaging. Stakeholders must monitor how fragmented state legislation outpaces federal harmonization and whether preemptive national standards emerge to simplify multi-jurisdictional compliance.
Market Dynamics
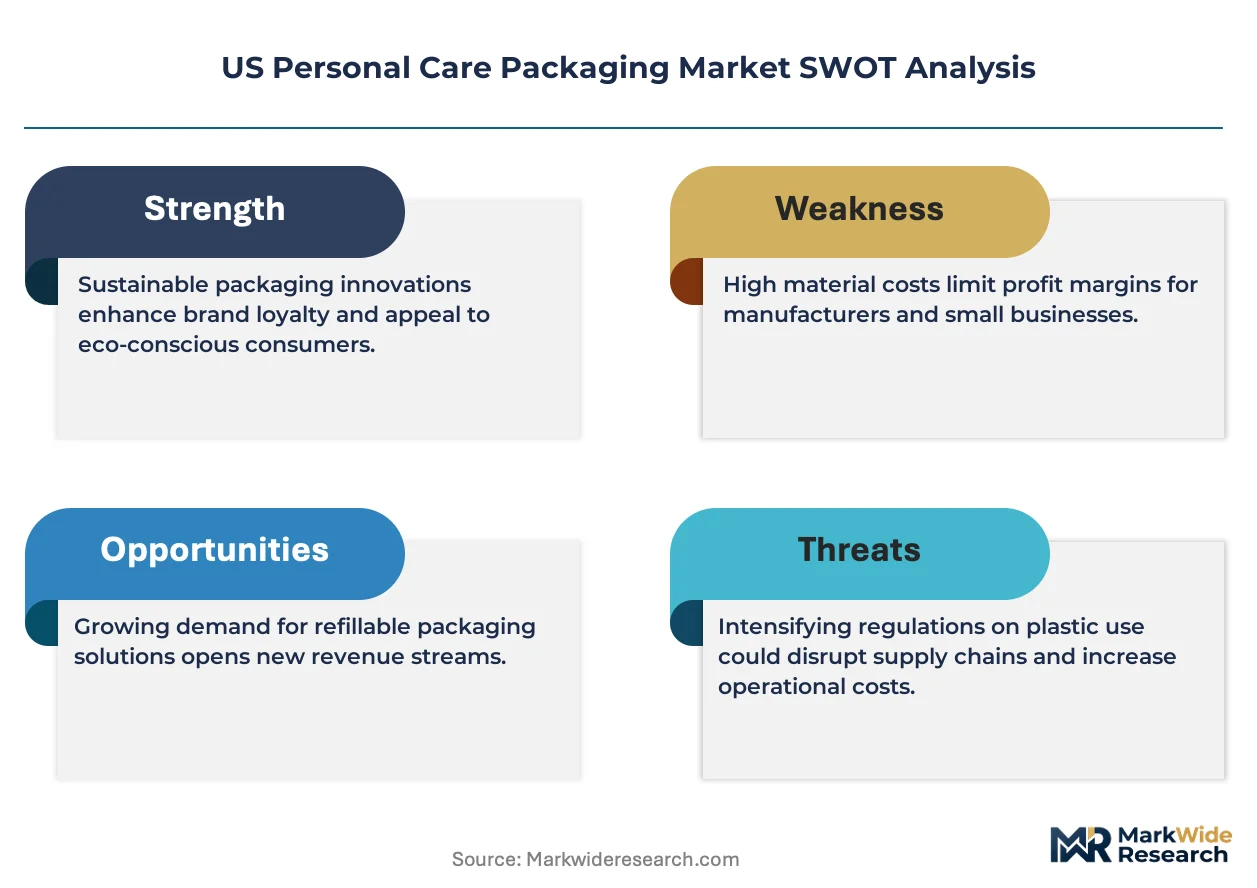
California's SB 54 extended producer responsibility framework is forcing material specification changes across US personal care supply chains, compressing design cycles and reallocating R&D budgets toward recyclability engineering.
Growth Catalysts
- State EPR mandates:California SB 54 and pending New York packaging laws compel brands to redesign primary containers for circular material flows, creating specification pull for post-consumer resin suppliers.
- Clean beauty formulators:Premium skincare brands in the Northeast corridor now require recycled-content films and airless dispensing systems as baseline procurement criteria.
- Mono-material flexible pouches:Travel-size and refill segments are accelerating adoption of all-polyethylene structures that satisfy e-commerce fulfillment efficiency and curbside recyclability simultaneously.
Market Restraints
- Post-consumer resin supply concentration:Domestic PCR availability remains tight relative to brand commitments, creating allocation risk for mass haircare lines dependent on rPET bottles.
- Glass weight penalty:Prestige fragrance and facial treatment categories face freight cost inflation that erodes margin concentration on jarred SKUs.
- FTC Green Guides enforcement:The commission's constraints on biodegradable and compostable claims force reformulation of sustainability messaging, extending legal review cycles.
Strategic Opportunities
- Refill infrastructure buildout:Retailers in California and the Northeast are piloting in-store dispensing systems that shift unit economics toward concentrate-and-reuse models.
- Airless pump technology convergence:Integration of mechanical dispensing with connected packaging (QR-enabled traceability) opens premium skincare positioning.
- Federal preemption possibility:Fragmented state legislation may yield to harmonized national standards, simplifying multi-jurisdictional compliance for national brand portfolios.
Industry Challenges
- Recyclability certification timelines:How2Recycle label approvals and APR design recognition processes lag product development cycles, delaying launch windows.
- Legacy blow-molding asset base:Converting incumbent bottle production lines to handle high-PCR feedstocks requires capital retrofit without guaranteed offtake commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Personal Care Packaging Market |
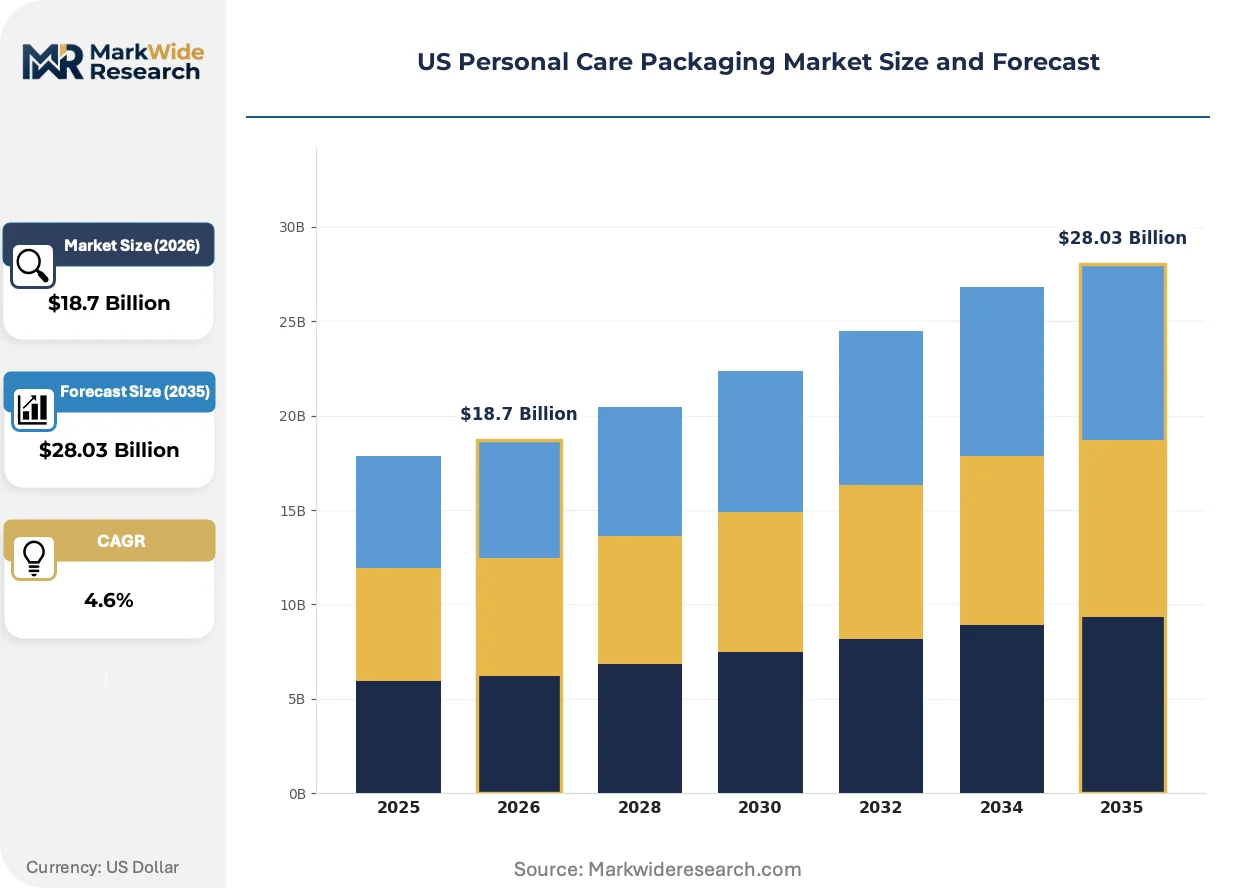
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Material: Plastic, Glass, Metal, Paper Packaging Type: Bottles, Tubes, Jars, Pouches End User: Consumers, Retailers, Wholesalers, E-commerce |
| Companies Covered | Amcor plc, Berry Global Group, Inc., Silgan Holdings Inc., Albea Services SA, Sonoco Products Company, WestRock Company, HCP Packaging Co. Ltd, AptarGroup Inc., Mondi Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Personal Care Packaging Market Evolving Landscape
Material science advances and regulatory pressure are converging to redefine acceptable packaging performance standards across the US personal care sector, with sustainability metrics now embedded in procurement scorecards alongside cost and aesthetics.
Mono-material polyethylene flexible pouches are decentralizing supply chain control away from rigid bottle converters by enabling brands to source film structures from a broader base of extrusion specialists. Mass haircare and body wash marketers are accelerating specification shifts toward these formats for e-commerce-dominant SKUs. The structural consequence is compression of converter margins in blow-molded HDPE as volume migrates to pouch filling operations.
FTC Green Guides revisions are constraining how personal care brands communicate end-of-life attributes on primary packaging, forcing legal and marketing functions to collaborate earlier in design development. The industrial consequence is extended concept-to-shelf timelines as claims substantiation requirements tighten. Premium skincare and clean beauty segments are responding by pivoting toward third-party certifications from How2Recycle and APR that transfer liability risk.
Direct-to-consumer subscription models are fragmenting traditional retail procurement power by enabling emerging brands to bypass shelf-space gatekeepers and test packaging innovations with lower volume commitments. Refill and concentrate formats are displacing single-use bottles in these channels, particularly among millennial and Gen-Z cohorts. This behavioral shift concentrates in California and urban Northeast markets where sustainability premiums command least price elasticity.
US Personal Care Packaging Market Segmentation
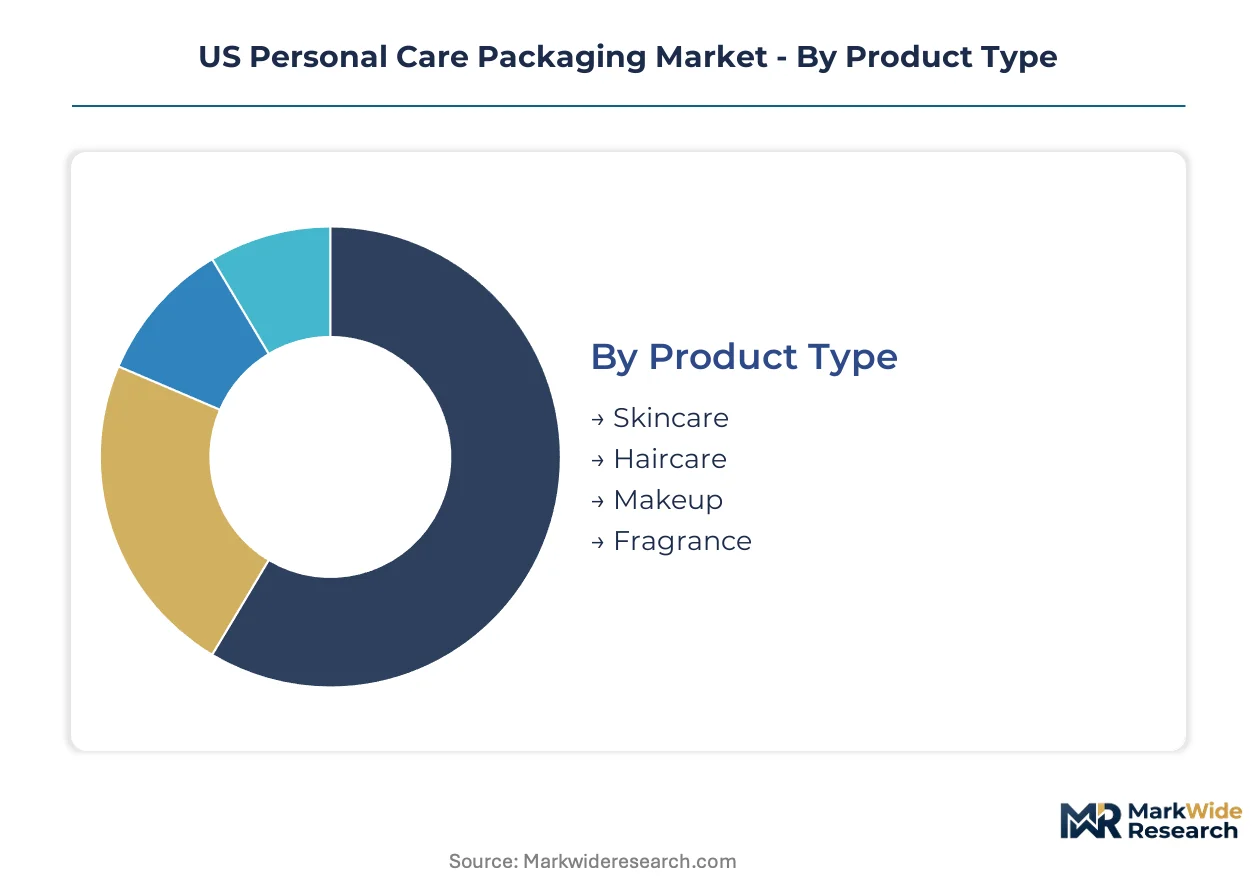
Personal care packaging procurement varies sharply across product chemistry, material compliance requirements, and fulfillment channel specifications. Understanding how these dimensions intersect reveals where specification power concentrates and where margin pressure builds.
Product Type:
Skincare buyers prioritize airless dispensing and premium material finishes; haircare purchasers emphasize volume efficiency and shelf impact economics.
- Skincare:Facial treatments and serums demand multi-layer barrier films and precision pump systems that preserve active ingredient stability. Clean beauty formulators in California and the Northeast corridor now mandate recycled-content substrates as baseline procurement criteria, compressing converter margins for conventional virgin plastic suppliers.
- Haircare:Shampoo and conditioner bottles dominate unit volume through blow-molded HDPE formats optimized for high-speed filling lines. Mass-market lines face acute post-consumer resin allocation risk as brand sustainability commitments outstrip domestic rPET and rHDPE supply availability.
- Makeup:Compact cases and component-heavy kits require intricate multi-material assemblies with tight dimensional tolerances.
- Fragrance:Prestige positioning sustains glass bottle demand despite freight weight penalties and e-commerce shipping cost inflation.
Volume sits with haircare; growth tilts toward skincare.
Material:
Specification choices here trace directly to California SB 54 compliance timelines and FTC Green Guides substantiation requirements.
- Plastic:Polyethylene and polypropylene structures command unit volume across bottles, tubes, and flexible pouches. Mono-material PE pouch formats are gaining specification share in travel-size and refill segments where e-commerce fulfillment efficiency intersects with curbside recyclability demands.
- Glass:Jars and bottles retain margin concentration in prestige fragrance and facial treatment categories. Weight-driven freight cost inflation now erodes profitability on glass-dependent SKUs, pushing some brands toward lightweighted designs or hybrid material solutions.
- Metal:Aerosol cans and tinplate containers serve specific dispensing and barrier requirements.
- Paper:Folding cartons and rigid boxes function primarily in secondary packaging and gift set configurations.
Plastic holds volume dominance; paper is climbing fastest on sustainability positioning.
Packaging Type:
Format selection increasingly reflects channel-specific fulfillment economics rather than shelf presence alone.
- Bottles:Blow-molded containers remain the default for liquid formulations across haircare and body wash. Incumbent converter asset bases face retrofit pressure to handle high-PCR feedstocks without guaranteed long-term offtake commitments from mass-market brands.
- Tubes:Extruded and laminate structures serve viscous creams and lotions with controlled dispensing precision. Mono-material polyethylene tube formats are displacing multi-layer laminates as brands prioritize recyclability certification from How2Recycle and APR.
- Jars:Wide-mouth containers facilitate finger-dip application for balms and masks.
- Pouches:Flexible formats are decentralizing supply chain control by enabling brands to source from extrusion specialists rather than rigid bottle converters.
Bottles anchor volume; pouches show steepest expansion trajectory on refill and concentrate model adoption.
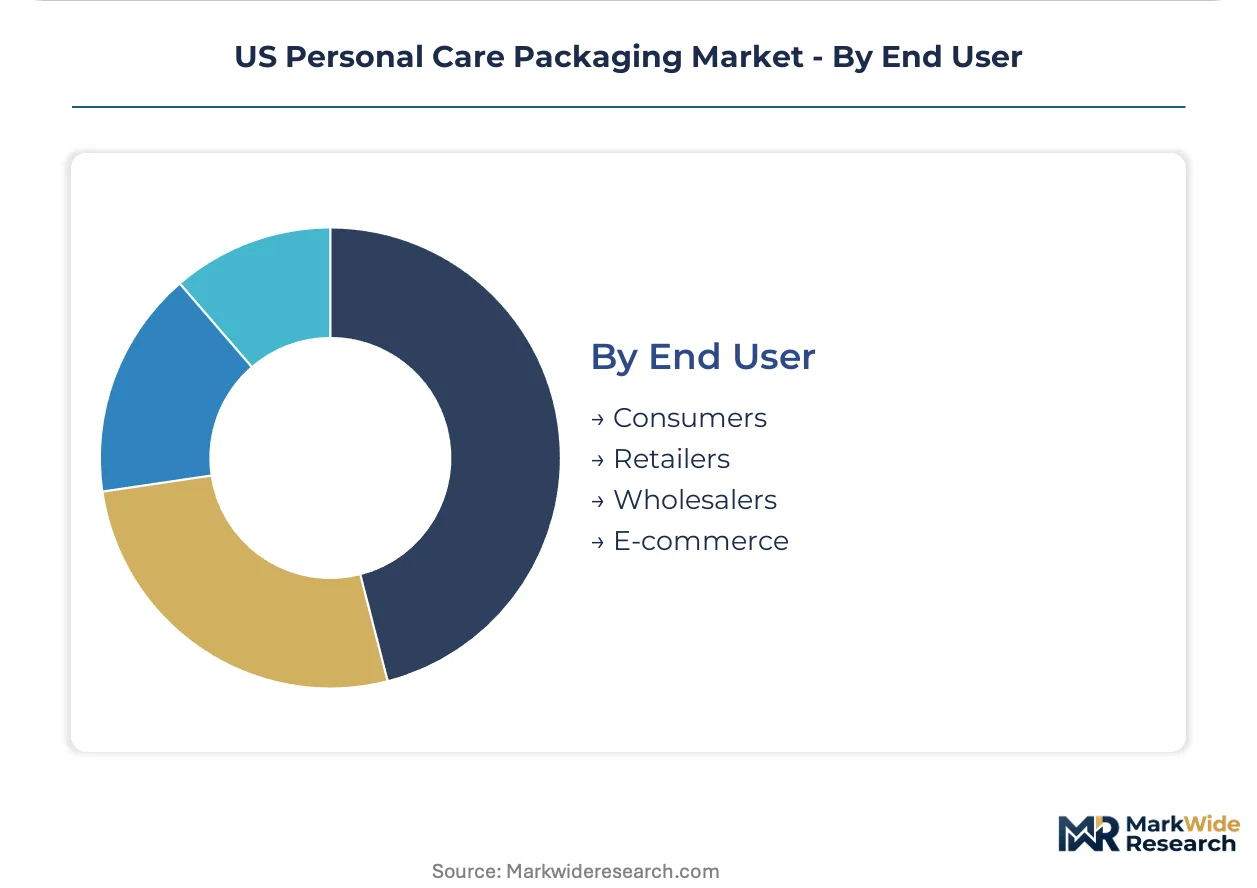
End User:
Channel power fragmentation is reshaping minimum order quantities and innovation risk allocation across the supplier base.
- Consumers:Direct-to-consumer subscription channels enable emerging brands to test packaging innovations with lower volume commitments than traditional retail gatekeepers require. Refill and concentrate formats concentrate in millennial and Gen-Z cohorts, particularly in California and urban Northeast markets.
- Retailers:Mass merchandisers and specialty beauty chains wield specification influence through private label programs and shelf-space allocation. California and Northeast retailers are piloting in-store dispensing infrastructure that shifts unit economics toward concentrate-and-reuse models.
- Wholesalers:Distribution intermediaries aggregate demand across fragmented regional beauty supply markets.
- E-commerce:Pure-play digital channels prioritize dimensional weight optimization and damage resistance over shelf aesthetics, favoring pouch and tube formats over glass jars.
Retailers command volume; e-commerce is gaining share fastest on fulfillment efficiency requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors the US personal care packaging ecosystem, hosting the nation's densest concentration of blow-molding converters and flexible film extruders serving West Coast clean beauty formulators. The metropolitan corridor channels Pacific Rim resin imports through Long Beach port infrastructure while sustaining direct supplier relationships with California's SB 54 compliance advisory ecosystem.
California
Los Angeles and Orange County house the majority of domestic flexible pouch extrusion capacity serving e-commerce-dominant personal care brands. The state's SB 54 extended producer responsibility law mandates 25% post-consumer resin thresholds by 2025, forcing converters to reengineer blow-molded bottle specifications. San Francisco Bay Area clean beauty headquarters drive specification pull for mono-material polyethylene structures and airless dispensing systems.
Northeast Corridor
New York Metro and Greater Boston concentrate premium skincare brand headquarters demanding recycled-content films and precision pump technologies. Pending New York packaging legislation mirrors California's EPR framework, creating dual-compliance pressure for national brand portfolios. New Jersey's chemical processing corridor supplies specialty barrier resins for facial treatment packaging requiring active ingredient stability.
Texas
Houston and the Gulf Coast petrochemical complex anchor domestic polyethylene and polypropylene resin production feeding personal care packaging converters nationwide. The region's resin manufacturing concentration positions Texas-based converters to negotiate favorable feedstock contracts for high-volume haircare bottle production. Dallas-Fort Worth distribution hubs optimize freight economics for mass-market personal care brands serving central US retail networks.
Midwest
Chicago and Detroit industrial corridors sustain legacy blow-molding operations serving mass haircare and body wash brands with HDPE bottle capacity. The region's automotive supplier base provides transferable precision molding expertise for cosmetic compact and component assemblies. Ohio River Valley resin distribution terminals enable cost-competitive material sourcing for regional contract packaging operations.
Southeast
Atlanta and Charlotte emerge as alternative distribution nodes reducing freight exposure for brands serving Florida and Gulf Coast retail markets. The region's lower operating costs attract secondary packaging and fulfillment operations from Northeast and West Coast headquarters. South Carolina's growing film extrusion base targets mono-material pouch demand from direct-to-consumer personal care startups.
US Personal Care Packaging Market Competitive Landscape
The competitive structure tilts toward diversified packaging conglomerates with integrated resin sourcing and multi-format production capabilities. Three to five multinational suppliers command disproportionate specification influence through long-term supply agreements with mass-market personal care brands. The vendor base segments into rigid container specialists, flexible film converters, and dispensing system engineers. Capacity expansion and strategic partnerships dominate competitive moves as participants seek PCR supply security and geographic coverage.
Among diversified packaging conglomerates, Amcor plc and Berry Global Group, Inc. exemplify scale-driven archetypes with integrated post-consumer resin platforms. AptarGroup Inc. occupies a position within the precision dispensing tier, anchoring airless pump technology supply relationships with premium skincare formulators. These three entities represent distinct competitive vectors: resin-integrated volume production, flexible format innovation, and high-value dispensing engineering.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Group, Inc. |
| Silgan Holdings Inc. |
| Albea Services SA |
| Sonoco Products Company |
| WestRock Company |
| HCP Packaging Co. Ltd |
| AptarGroup Inc. |
| Mondi Group |
| Others |
Value Network & Pricing Analysis
Precision blow-molding technicians in the Los Angeles basin command wage premiums that propagate through converter pricing tiers, widening spreads between mass-market haircare bottle contracts and premium skincare dispensing system quotes.
Pricing Analysis
Value-based pricing anchored to shelf-life extension outcomes dominates premium skincare dispensing contracts, where airless pump performance metrics justify per-unit premiums over commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels separates certified PCR-content specifications from virgin resin baselines. Cost compression in mass haircare blow-molded bottles is intensifying because domestic rPET and rHDPE allocation shortages force brands toward spot resin markets. Mass-market retailers exhibit highest price sensitivity, while clean beauty formulators in California and the Northeast corridor accept sustainability premiums with minimal elasticity.
Supply Chain Analysis
Reverse-logistics flows for post-consumer bottle collection and flake processing concentrate in California, Texas, and the Southeast, where mechanical recycling infrastructure feeds regional converter networks. The US personal care packaging supply chain draws from Gulf Coast polyethylene production, Pacific Rim specialty resin imports, and domestic mechanical recycling output. Single-source vulnerability concentrates in California flexible film extrusion capacity serving e-commerce pouch demand. Distribution runs through Los Angeles and Dallas-Fort Worth hubs for West Coast and central US retail networks respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-consumer resin supply scarcity props pricing power for converters with secured feedstock contracts, creating durable margin advantages for integrated players.
For Market Incumbents: Deploy captive PCR sourcing agreements to lock in resin allocation ahead of California SB 54 compliance deadlines. Incumbents should retrofit legacy blow-molding lines for high-recycle-content processing to defend against flexible pouch substitution in travel-size segments. Threat from mono-material pouch converters demands accelerated airless pump technology integration to maintain premium positioning. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription channels targeting millennial and Gen-Z cohorts in California and urban Northeast markets with refill and concentrate formats. White-space concentrates in in-store dispensing infrastructure partnerships with California and Northeast retailers piloting reuse models. Go-to-market angle should emphasize third-party recyclability certifications from How2Recycle and APR to transfer liability risk. For Investors and Strategic Acquirers: Re-rating potential sits with flexible film extruders with mono-material PE pouch capabilities given e-commerce fulfillment efficiency requirements. Long-term viability favors converters with backward integration into post-consumer resin sourcing or upstream control over specialty barrier resin supply. Signal to watch is Federal preemption of fragmented state EPR legislation simplifying national brand compliance.| Strategic Initiative | Industry Significance |
|---|---|
| PCR Supply Security Investment | Captive post-consumer resin sourcing locks in California SB 54 compliance feedstock for blow-molded bottle converters. |
| Airless Pump Technology Integration | Mechanical dispensing convergence with connected packaging opens premium skincare positioning for precision engineers. |
| Mono-Material Pouch Capacity Expansion | All-polyethylene structures satisfy e-commerce fulfillment and curbside recyclability for travel-size segments. |
| In-Store Refill Infrastructure Partnership | California and Northeast retailer pilot programs shift unit economics toward concentrate-and-reuse models. |
| Third-Party Certification Investment | How2Recycle and APR design recognition transfers FTC Green Guides liability risk for sustainability claims. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with packaging converters, brand sustainability directors, retail procurement managers, and resin supply specialists. Secondary sources included FDA cosmetic labeling guidance, California SB 54 implementation documents, FTC Green Guides revisions, APR design recognition databases, and How2Recycle label approval records. Bottom-up capacity assessments triangulated against top-down brand procurement survey data.
Segmentation granularity modeled product type, material substrate, packaging format, and end-user channel at the state-cluster level across the analysis window. CAGRs derived from shipment volume trajectories and value-per-unit trends indexed to resin price movements and compliance cost pass-through assumptions. Forecast inputs incorporated California EPR mandate phase-in schedules and FTC enforcement pattern probabilities.
PCR supply disruption, Federal preemption timing, and FTC Green Guides enforcement intensity are the dominant revision risks. Forecasts reflect assumptions about resin availability and regulatory implementation pacing. Practitioners should monitor post-consumer resin spot market volatility and state legislative divergence for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Beauty Supplements Packaging Market
Cosmetic Packaging
Plastic Cosmetic Packaging Market
Cosmetic Packaging
Single Portion Cosmetic Packaging Market
Cosmetic Packaging
Beauty and Personal Care Packaging Market
Cosmetic Packaging
Cosmetic Spray Bottles Market
Cosmetic Packaging
Injection Moulding Cosmetic Packaging Market
Cosmetic Packaging
Fragrance Packaging Market
Cosmetic Packaging
Europe Personal Care Packaging Market
Cosmetic Packaging
Middle East and Africa Personal Care Packaging Market
Cosmetic Packaging
Cosmetic Bottles Packaging Market
Cosmetic Packaging
Make-Up Products Packaging Market
Cosmetic Packaging
Latin America Personal Care Packaging Market
Cosmetic Packaging
Europe Plastic Cosmetic Packaging Market
Cosmetic Packaging
Asia Pacific Personal Care Packaging Market
Cosmetic Packaging
Latin America Cosmetic Packaging Market
Cosmetic Packaging
Lotion Tubes Market