
 Hair Care Packaging Market | 2026-2036
Hair Care Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Care Packaging Market Foresight
European rigid plastics capacity is hardening as converters retool for circular material streams. Amcor PLC leverages its integrated film-to-bottle platform across multiple hair care accounts. Berry Global Group sustains North American dominance through blow-molded HDPE lines optimized for salon-format volumes. Gerresheimer AG anchors premium glass demand from prestige fragrance and hair oil brands in Western Europe.
Hair care packaging encompasses primary and secondary containers engineered to protect formulations from oxidation, UV degradation, and microbial contamination while enabling precise dosing; typical specifications include barrier coextrusion layers of EVOH or PA6 ranging from 2-5 mils, with headspace nitrogen flushing for oxygen-sensitive actives. Tubes lead unit volume across mass-market shampoo and conditioner segments, though pouches represent the fastest-expanding format as refill systems penetrate e-commerce subscription channels. Glass bottles command the densest margin pools in prestige hair oil and scalp treatment segments where tactile weight signals formulation quality.
The EU Green Deal and ECHA REACH frameworks mandate recycled content thresholds and restrict certain phthalate plasticizers in flexible packaging, compelling converters to validate post-consumer rPET streams for cosmetic-grade applications. FDA cosmetic packaging regulations in the United States require material migration testing for substances contacting topical formulations, adding qualification cycles for novel biopolymer candidates. Stakeholders must monitor evolving extended producer responsibility fee structures across jurisdictions to anticipate cost pass-through dynamics.
Market Dynamics
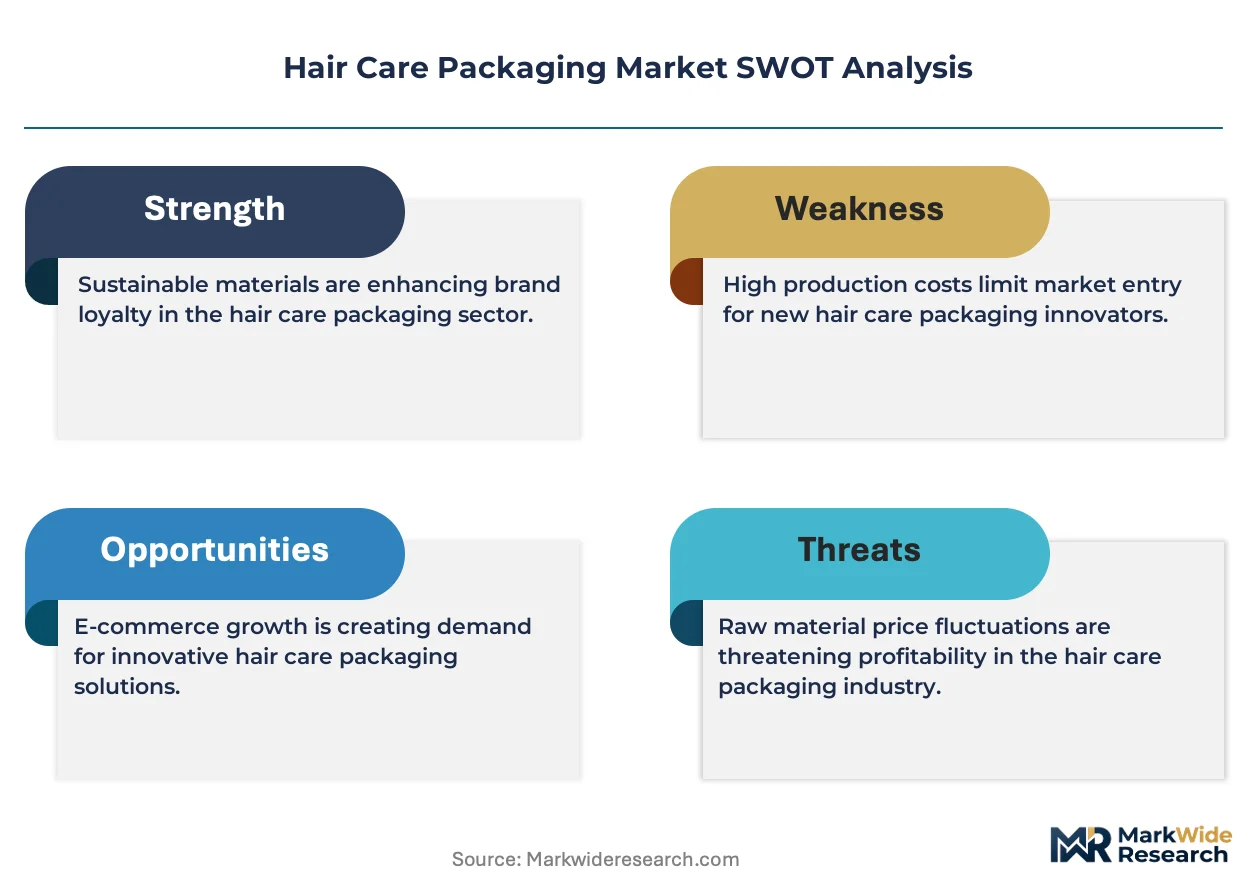
The EU Green Deal and ECHA REACH restrictions on single-use plastics are forcing converters to retool extrusion lines for post-consumer recycled streams, compressing qualification timelines for cosmetic-grade rPET while premium brands accelerate biodegradable material trials.
Growth Catalysts
- Regulatory Mandates:The EU Green Deal establishes recycled content thresholds for cosmetic packaging, compelling brands to specify post-consumer rPET in procurement contracts.
- Material Innovation:Barrier coextrusion with EVOH layers is extending shelf life for oxygen-sensitive hair actives, opening premium positioning for tube formats previously limited to mass segments.
- E-Commerce Penetration:Refill pouch systems are capturing subscription channel volume as direct-to-consumer brands eliminate secondary boxing.
Market Restraints
- rPET Supply Concentration:Cosmetic-grade post-consumer resin availability clusters around German and French recycling infrastructure, creating geographic bottlenecks for converters elsewhere.
- Migration Testing Burden:FDA cosmetic packaging regulations require 12-18 month validation cycles for novel biopolymers, delaying commercialization of PHA and PLA alternatives.
- Glass Weight Penalty:Prestige hair oil brands face rising freight costs from tactile glass formats, eroding margin pools as e-commerce share expands.
Strategic Opportunities
- Underpenetrated Markets:Indian hair care brands lack domestic biodegradable packaging capacity, creating import substitution potential for European converters with BIS certification.
- Regulatory Tailwinds:Extended producer responsibility fee structures in France and Italy reward lightweight pouch formats, incentivizing format switching from rigid bottles.
- Technology Convergence:Nitrogen flushing systems combined with mono-material barrier films are enabling aluminum-free preservation for clean-label hair treatments.
Industry Challenges
- Compounding Expertise Scarcity:Formulators with EVOH-PP adhesion chemistry experience command premium wages, constraining converter expansion timelines.
- Legacy Equipment Stranding:Blow-molded HDPE lines require $2-4 million retrofit investments to process 30%+ recycled content without optical defects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Care Packaging Market |
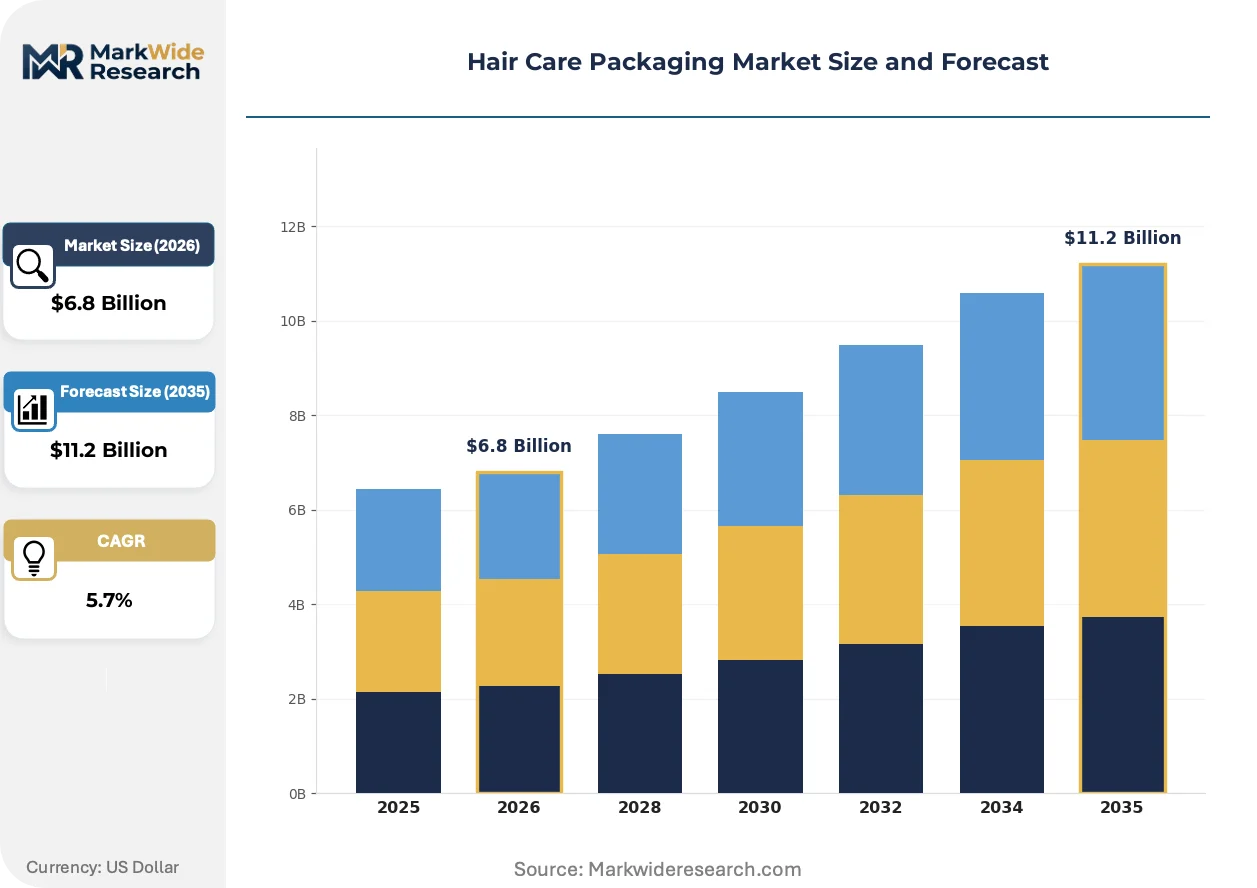
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Tubes, Bottles, Jars, Pouches Material: Plastic, Glass, Aluminum, Biodegradable Closure Type: Pumps, Sprayers, Caps, Flip-tops End User: Retail, Salon, E-commerce, Institutions |
| Companies Covered | Amcor PLC, Berry Global Group, Gerresheimer AG, Silgan Holdings, AptarGroup, HCP Packaging, Albea S.A., DS Smith, Quadpack Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Care Packaging Market Shifts & Advancements
Refill infrastructure and mono-material design are collapsing traditional primary-secondary packaging hierarchies, while digital printing enables batch-level customization for influencer-collaboration launches.
Barrier mono-material tubes with EVOH coextrusion are decentralizing premium hair care packaging away from glass-dependent prestige formats. Indie scalp treatment brands in Germany and the Netherlands specify these tubes for their lightweight shipping profiles and squeezable dosing precision. The shift is compressing glass converter order books while expanding flexible film capacity around Düsseldorf.
ECHA REACH restrictions on phthalate plasticizers in flexible packaging are eliminating certain PVC formulations from hair mask sachets and conditioner pouches. Converters must validate TPE or bio-based alternatives through 18-month migration testing protocols. Salon-format professional brands face the steepest compliance costs given their reliance on high-clarity flexible formats.
Subscription-based refill systems are fragmenting procurement authority away from retail buyers toward direct-to-consumer operations teams. Hair care brands in Sweden and Denmark now specify pouch-to-bottle refill ratios in vendor scorecards, displacing traditional unit-volume contracts. This pattern concentrates demand among converters with ISO 15378 pharmaceutical-grade cleanroom capabilities for bulk pouch filling.
Hair Care Packaging Market Segmentation
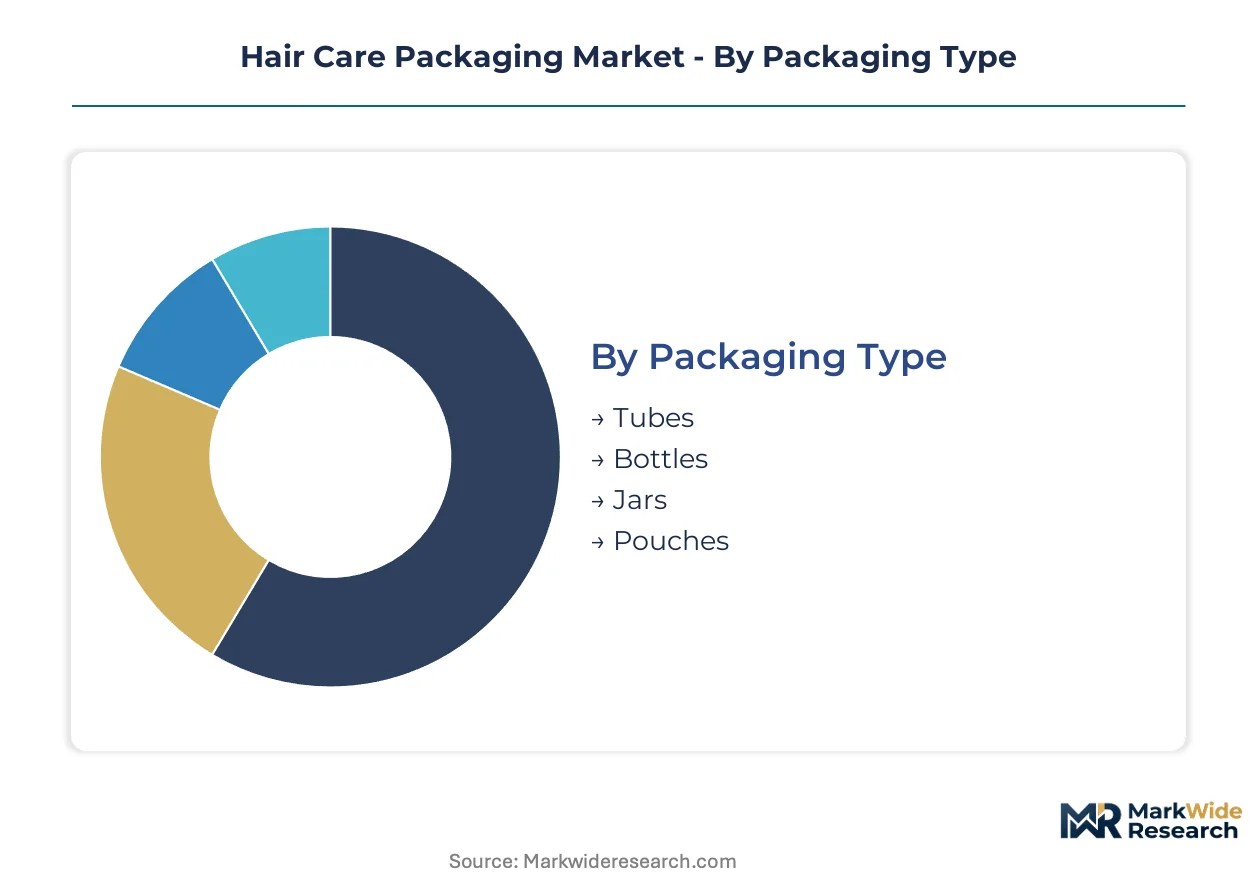
Hair care packaging procurement decisions hinge on format-function alignment across viscosity ranges, dispensing precision needs, and shelf-preservation requirements. Brand managers weight material specifications against channel-specific logistics constraints and regulatory compliance burdens.
Packaging Type:
Upgrade cycles accelerate as brands replace rigid formats with flexible alternatives to reduce shipping cube and EPR fees.
- Tubes:Barrier coextrusion with EVOH layers protects oxygen-sensitive actives in scalp treatments and hair masks. Demand clusters in Germany around Düsseldorf converters serving mass-market shampoo and conditioner brands facing EU Green Deal compliance deadlines.
- Pouches:Refill systems for subscription channels eliminate secondary boxing while reducing freight weight. Swedish and Danish direct-to-consumer brands specify pouch-to-bottle refill ratios in vendor scorecards, displacing traditional unit-volume contracts.
- Bottles:Blow-molded HDPE dominates salon-format professional volumes with pump-dispensing precision for back-bar applications.
- Jars:Wide-mouth formats accommodate thick hair masks and styling pomades where finger-access application prevails.
Volume placements concentrate in tubes; the faster expansion belongs to pouches.
Material:
Cost tiers separate premium positioning from mass-market compliance-driven substitutions.
- Plastic:Post-consumer rPET streams command qualification priority as EU recycled content mandates tighten. German and French recycling infrastructure concentrates cosmetic-grade resin availability, creating geographic bottlenecks for converters elsewhere.
- Biodegradable:PHA and PLA alternatives face 12-18 month FDA migration testing cycles that delay commercialization timelines. Indian hair care brands lack domestic capacity, creating import substitution potential for European converters with BIS certification.
- Glass:Tactile weight signals formulation quality in prestige hair oil segments though freight costs erode margin pools as e-commerce share expands.
- Aluminum:Lightweight barrier properties suit dry shampoo aerosols and powder-format scalp treatments.
Plastic retains dominant volume share; biodegradable materials are climbing the fastest as regulatory deadlines approach.
Closure Type:
Application specificity drives precision requirements across viscosity and dosage control needs.
- Pumps:Metered dispensing dominates conditioner and leave-in treatment formats where controlled dosage reduces waste. Salon professional brands specify locking mechanisms for back-bar theft prevention.
- Sprayers:Fine-mist atomization serves dry shampoo and heat-protectant applications requiring even distribution.
- Caps:Screw-top formats persist in travel-size and sample formats where cost minimization overrides dispensing convenience.
- Flip-tops:One-handed operation suits shower-environment shampoo and body wash combinations in mass retail.
Pumps anchor professional and premium retail positioning; sprayers gain share fastest in styling product proliferation.
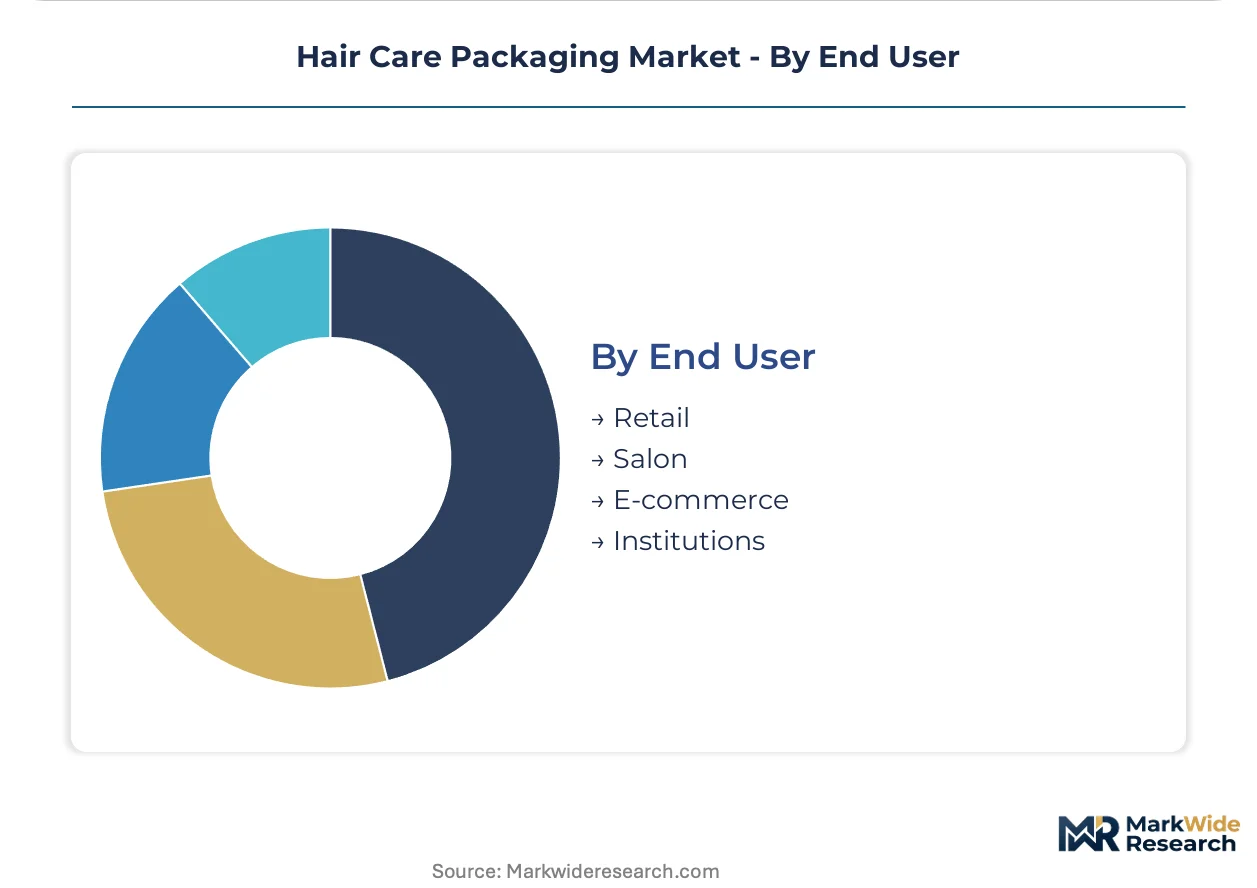
End User:
Customer type determines order scale, customization requirements, and regulatory documentation burdens.
- E-commerce:Direct-to-consumer operations fragment procurement authority away from retail buyers toward subscription logistics teams. Brands specify ISO 15378 pharmaceutical-grade cleanroom capabilities for bulk pouch filling.
- Retail:Mass-market chains demand shelf-ready secondary packaging and regional language labeling compliance across multiple jurisdictions.
- Salon:Professional back-bar formats prioritize liter-plus volumes with pump dispensers and locking mechanisms for inventory control.
- Institutions:Hospitality and healthcare procurement emphasizes cost minimization and bulk refill compatibility over brand differentiation.
Retail maintains the largest absolute volume; e-commerce shows the steepest expansion trajectory as subscription models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Post-consumer rPET feedstock availability clusters around German and French recycling infrastructure, concentrating converter capacity in Western Europe while Asian demand outpaces domestic supply.
Germany
Barrier tube demand from mass-market shampoo brands drives converter activity around Düsseldorf and Hamburg. ECHA REACH restrictions on phthalate plasticizers compel PVC-to-TPE transitions in flexible formats. The Düsseldorf packaging cluster serves continental European beauty brands with EVOH coextrusion capabilities.
France
Extended producer responsibility fee structures reward lightweight pouch formats for direct-to-consumer hair care subscriptions. ANSM cosmetic packaging guidelines align with EU Green Deal recycled content mandates. Paris-based brand headquarters source refill systems from converters in the Hauts-de-France industrial corridor.
United States
Salon-format professional volumes sustain blow-molded HDPE demand with pump-dispensing precision for back-bar applications. FDA cosmetic packaging regulations impose 12-18 month migration testing cycles for novel biopolymers. New Jersey and Ohio converters dominate North American supply for mass-market conditioner bottles.
India
Domestic hair care brands lack indigenous biodegradable packaging capacity, creating import dependency for PHA and PLA alternatives. BIS certification requirements for cosmetic-grade materials filter European converter participation. Maharashtra-based formulators rely on imported barrier films for scalp treatment tubes.
Sweden
Subscription-based refill systems fragment procurement authority toward direct-to-consumer operations teams. The country's national environmental agency enforces strict extended producer responsibility frameworks for packaging waste. Stockholm-based brands specify pouch-to-bottle refill ratios in vendor scorecards, displacing traditional unit-volume contracts.
Hair Care Packaging Market Competitive Landscape
Global majors compete with regional champions across material qualification capabilities and regulatory compliance expertise. The vendor base stratifies into integrated film-to-bottle platforms, rigid plastic specialists, and premium glass fabricators. Three archetypes dominate: converters with backward integration into resin compounding, specialists in pharmaceutical-grade cleanroom filling, and diversified packaging conglomerates with cross-sector material science. Capacity expansion and strategic partnerships represent the primary competitive vectors as brands consolidate supplier bases.
Among diversified packaging conglomerates, Amcor PLC and Berry Global Group exemplify scale-driven positioning across multiple hair care accounts, while Gerresheimer AG occupies a specialized tier serving prestige fragrance and hair oil segments. These three entities represent contrasting strategic postures: integrated film-to-bottle platforms, North American blow-molded volume leadership, and Western European glass prestige anchoring respectively.
| Leading Market Players |
|---|
| Amcor PLC |
| Berry Global Group |
| Gerresheimer AG |
| Silgan Holdings |
| AptarGroup |
| HCP Packaging |
| Albea S.A. |
| DS Smith |
| Quadpack Industries |
| Others |
Supply & Pricing Matrix
Premium-mass bifurcation separates cosmetic-grade rPET formulations from commodity blow-molded HDPE, with the former commanding qualification premiums around German recycling clusters while the latter faces cost compression from legacy equipment retrofit requirements. This tier divergence manifests in procurement contracts through extended producer responsibility fee pass-throughs and migration testing burden allocations.
Pricing Analysis
Warranty-bundled validation services separate premium converters from commodity suppliers, with German and French providers including 18-month FDA migration testing support in long-term contracts. Three-tier pricing structure across premium, standard, and economy levels reflects EVOH barrier layer complexity, ISO 15378 certification status, and refill-system integration depth. Pricing pressure stems from rPET feedstock scarcity around Düsseldorf and Hamburg clusters. Mass-market retail buyers exhibit highest price sensitivity; prestige hair oil brands tolerate freight cost premiums for tactile glass formats.
Supply Chain Analysis
Compounding chemist shortages around Düsseldorf and Hamburg constrain converter expansion timelines, with EVOH-PP adhesion specialists commanding wage premiums that ripple through tube production costs. Supply concentrates in Germany, France, and the United States for cosmetic-grade resin and barrier film extrusion. Raw material dependencies include post-consumer rPET flakes, EVOH barrier resins, and nitrogen flushing equipment. Single-source vulnerability clusters around German recycling infrastructure for cosmetic-grade feedstock. Distribution runs through brand-direct contracts for refill systems and retail procurement networks for mass-market formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hair care packaging market reads as a cost-of-compliance story where EU Green Deal recycled content mandates erect barrier-to-entry moats for converters with validated rPET streams and established ECHA REACH documentation systems.
For Market Incumbents: Hedge against biopolymer disruption by securing pharmaceutical-grade cleanroom certifications for pouch filling ahead of subscription channel consolidation. Lock in long-term rPET supply contracts around German and French recycling infrastructure before feedstock allocation tightens. Prioritize backward integration into barrier film compounding to capture margin pools from EVOH coextrusion demand.
For New Entrants and Emerging Players: EU Green Deal compliance deadlines in Germany open a window for niche converters specializing in mono-material barrier tubes with aluminum-free nitrogen flushing. Target Indian hair care brands lacking domestic biodegradable packaging capacity, leveraging BIS certification as market entry credential. Pursue direct-to-consumer refill system partnerships with Swedish and Danish subscription brands seeking ISO 15378-qualified pouch suppliers.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap converters possessing integrated film-to-bottle platforms given EPR fee structures rewarding lightweight format transitions. Long-term viability favors specialists with captive resin qualification capabilities and established brand-direct relationships. Monitor ECHA REACH restriction expansion timelines as inflection indicators for PVC-to-TPE transition demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Film Compounding Integration | Captures EVOH coextrusion premiums from German scalp treatment brands. |
| Pharmaceutical-Grade Cleanroom Certification | Unlocks ISO 15378 subscription pouch contracts with Swedish direct-to-consumer brands. |
| Post-Consumer rPET Stream Validation | Secures EU Green Deal compliance positioning ahead of recycled content mandate deadlines. |
| Mono-Material Tube Platform Development | Displaces glass-dependent prestige formats through lightweight aluminum-free preservation. |
| Indian Market BIS Certification | Enables import substitution for PHA and PLA alternatives in biodegradable packaging. |
Research Methodology
Independent corroboration across packaging converter executives, brand sustainability officers, and regulatory compliance consultants underwrites the qualitative findings in this study. Primary interviews with procurement leads at mass-market retailers, salon-format professional distributors, and direct-to-consumer operations teams informed format demand patterns. Secondary validation drew from ECHA REACH substance restriction databases, EU Green Deal implementation directives, FDA cosmetic packaging guidance documents, and extended producer responsibility fee schedules across France, Italy, and Sweden. Bottom-up unit volume estimates triangulated against top-down material consumption figures from European recycling infrastructure reports.
Rate-of-change decomposition across packaging type, material composition, closure mechanism, and end-user channel anchored the analytical framework. Segmentation modeling incorporated format-function alignment across viscosity ranges, dispensing precision requirements, and shelf-preservation specifications. CAGRs derived from logistic diffusion curves fitted to regulatory mandate implementation timelines and e-commerce penetration trajectories. Industry-specific forecast inputs included EVOH barrier layer adoption rates and nitrogen flushing system deployment in clean-label hair treatments.
The model assumes a particular technology adoption path; alternative pathways for PHA and PLA biopolymer commercialization would alter the outlook for biodegradable material penetration timelines. Forecasts reflect documented assumptions around EU Green Deal enforcement consistency and rPET feedstock availability expansion. Material deviation in ECHA REACH restriction scope or FDA migration testing protocol revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Make-Up Products Packaging Market
Cosmetic Packaging
Nail Polish Packaging Market
Cosmetic Packaging
Middle East and Africa Cosmetic Packaging Market
Cosmetic Packaging
Anti-Counterfeit Pharmaceuticals and Cosmetics Packaging Market
Cosmetic Packaging
Asia Pacific Personal Care Packaging Market
Cosmetic Packaging
Glass Cosmetic Bottle Market
Cosmetic Packaging
Crimp Neck Serum Bottles Market
Cosmetic Packaging
Skin Care Packaging Market
Cosmetic Packaging
Metal Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic Spray Bottles Market
Cosmetic Packaging
Cosmetic and Toiletry Containers Market
Cosmetic Packaging
Global Eye Cosmetic Packaging Market
Cosmetic Packaging
Latin America Cosmetic Packaging Market
Cosmetic Packaging
US Personal Care Packaging Market
Cosmetic Packaging
Eyeliner and Kajal Sculpting Pencil Packaging Market
Cosmetic Packaging
Middle East and Africa Personal Care Packaging Market