
 Fragrance Packaging Market | 2026-2036
Fragrance Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Fragrance Packaging Market Analysis
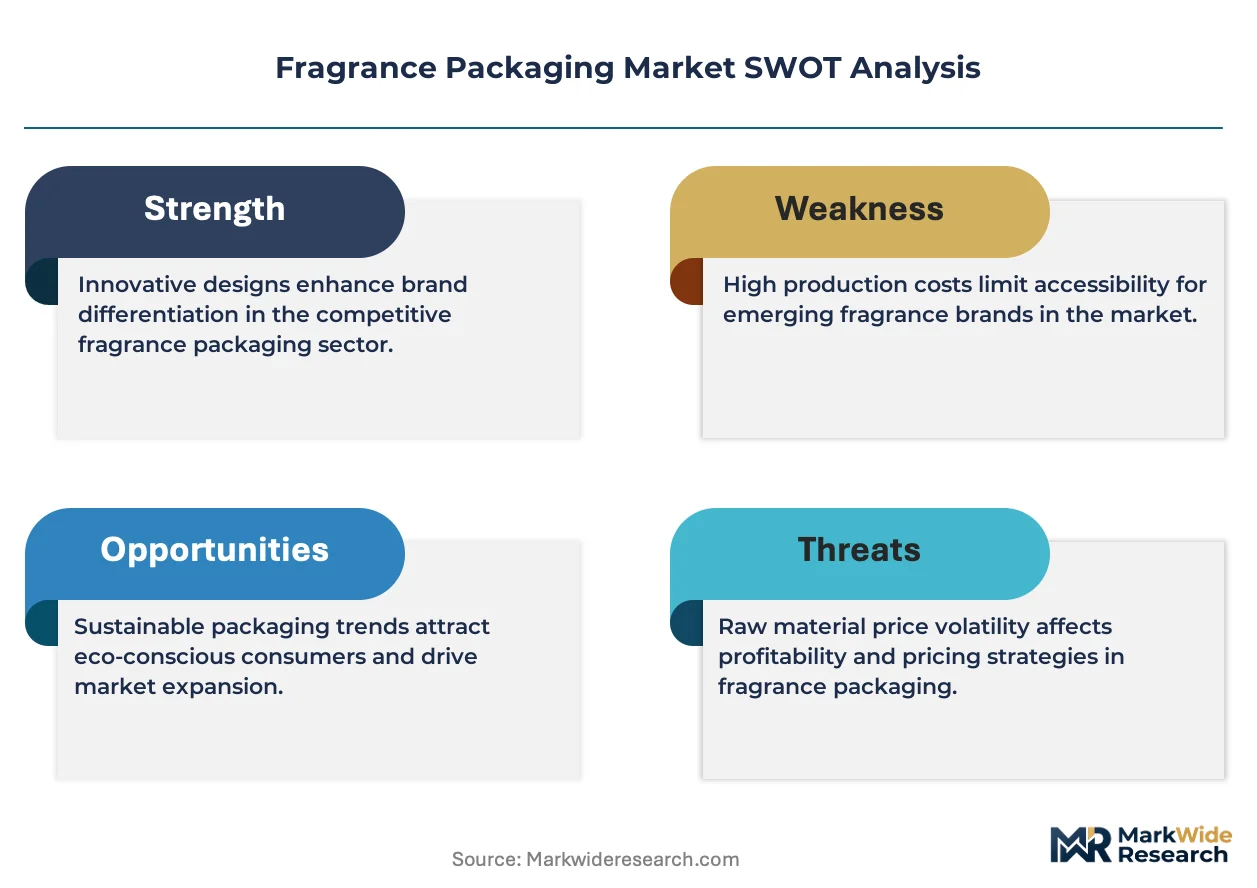
Buyer concentration among luxury fragrance houses is pivoting toward a fragmented landscape as direct-to-consumer indie brands and niche perfumeries multiply their packaging procurement. Gerresheimer AG leverages its blown-glass expertise to dominate premium bottle contracts for European maisons. Saverglass anchors artisanal positioning through its Burgundy manufacturing heritage and limited-run capabilities. Albéa competes across pump and closure systems while sustaining dual supply lines for mass-market and prestige fragrance accounts.
Fragrance packaging encompasses primary containers, dispensing closures, and secondary wrapping engineered to preserve volatile aromatic compounds, prevent oxidation, and communicate brand identity through tactile and visual design. Glass bottles remain the dominant substrate, with borosilicate and soda-lime formulations selected for chemical inertness and clarity in high-end applications. Bottles command the largest value share within product type segmentation, though vials accelerate in travel-retail and sample distribution channels. Eco-friendly design types attract capital allocation as refillable formats and post-consumer recycled content reshape material specifications across glass and paperboard segments.
The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility and recycled content minimums that force reformulation of glass feedstocks and plastic closure compositions. REACH restrictions on certain phthalates and heavy metals in decorative coatings constrain surface treatment options for metal and glass decorators. FDA oversight of cosmetic packaging materials in the United States requires migration testing for substances contacting fragrance oils. Stakeholders must monitor evolving extended producer responsibility schemes and material traceability requirements to secure formulation flexibility and market access across competing regulatory jurisdictions.
Market Dynamics
Refillable fragrance packaging programs are compressing primary packaging replacement cycles while forcing converters to reengineer glass durability specifications and closure thread geometries for repeated use.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates accelerate investment in post-consumer recycled glass feedstocks and mono-material pump assemblies across European manufacturing facilities.
- Travel-retail channel expansion:Airport duty-free operators are doubling fragrance SKU counts, driving vial and miniature bottle procurement from specialized glass converters.
- Borosilicate glass thermal stability:Premium perfume houses specify chemically inert substrates for high-concentration oil compatibility, displacing soda-lime alternatives in prestige lines.
Market Restraints
- Energy cost volatility:Natural gas prices govern furnace operating economics for glass bottle manufacturers, compressing margin structures during supply shocks.
- Decorative coating restrictions:REACH limitations on heavy metal pigments constrain surface treatment options for metalized caps and silk-screened bottle designs.
- Aluminum substitution in closures:Lightweight metal dispensing systems compete with traditional glass stoppers in mass-market fragrance applications.
Strategic Opportunities
- Direct-to-consumer indie brands:Niche perfumeries bypass traditional retail markup structures, creating packaging procurement accounts with specialized low-MOQ converters.
- Personalization tooling investments:Digital printing and laser engraving technologies enable single-run customization for limited-edition fragrance releases.
- Secondary packaging reduction:Regulatory pressure on paperboard waste drives demand for protective yet minimal outer wrapping systems.
Industry Challenges
- Glass color-matching precision:Batch-to-batch consistency in tinted borosilicate production requires skilled furnace operators in short supply across European manufacturing clusters.
- Migration testing protocols:FDA substance contact regulations for fragrance oils extend certification timelines for new closure elastomer formulations entering the United States market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fragrance Packaging Market |
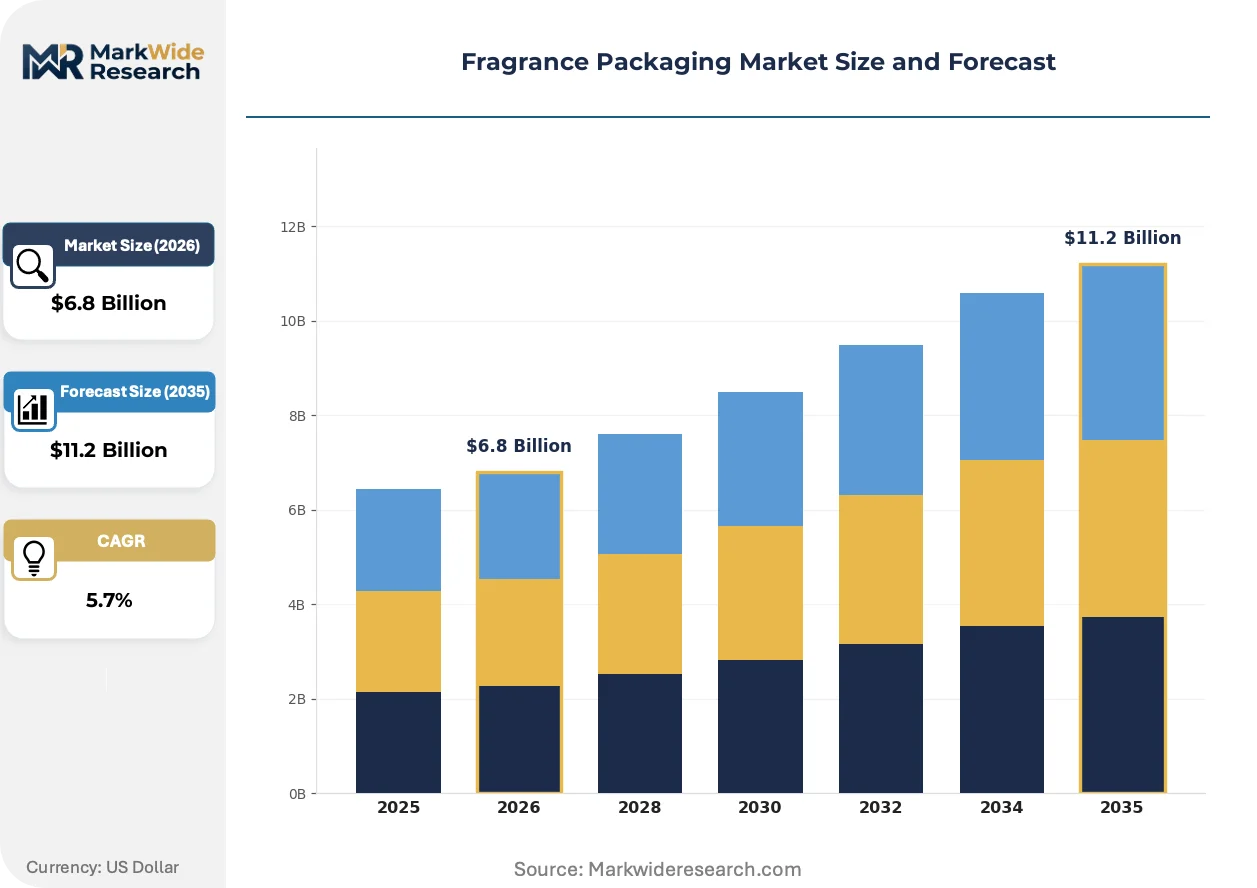
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Vials, Jars, Sprays Material: Glass, Plastic, Metal, Paperboard Closure Type: Screw Caps, Pumps, Roll-ons, Mist Sprayers Design Type: Luxury, Eco-friendly, Custom, Standard |
| Companies Covered | Gerresheimer AG, Saverglass, Verescence France SASU, Albéa, Quadpack Ltd., AptarGroup, EXAL Corporation, Piramal Glass Ltd., Coverpla S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fragrance Packaging Market Emerging Trajectories
Digital manufacturing workflows and circular material specifications are converging to redefine how fragrance houses specify, prototype, and validate packaging systems across compressed development timelines.
Embedded NFC chips and QR-linked authentication layers are rewriting how premium brands combat counterfeiting and capture post-purchase consumer engagement. European maisons deploy these identifiers in limited editions first, with mass-market adoption following as unit economics improve. The technology is rewriting competitive differentiation from physical ornamentation toward digital-verified provenance.
REACH restrictions on phthalate plasticizers in pump elastomers are forcing reformulation of fragrance dispensing mechanisms across European supply chains. Manufacturers substitute bio-based thermoplastic elastomers or silicone alternatives, validating compatibility with volatile aromatic compounds through extended aging protocols. Prestige fragrance accounts absorb qualification costs first; mass-market suppliers lag by eighteen to twenty-four months.
Subscription-based fragrance replenishment services are fragmenting traditional retail procurement patterns. Direct-to-consumer operators specify standardized bottle geometries compatible with automated fulfillment infrastructure, displacing bespoke shapes historically favored by department store buyers. This behavioral shift concentrates most visibly in United States metropolitan markets where delivery density supports economic viability.
Fragrance Packaging Market Segmentation
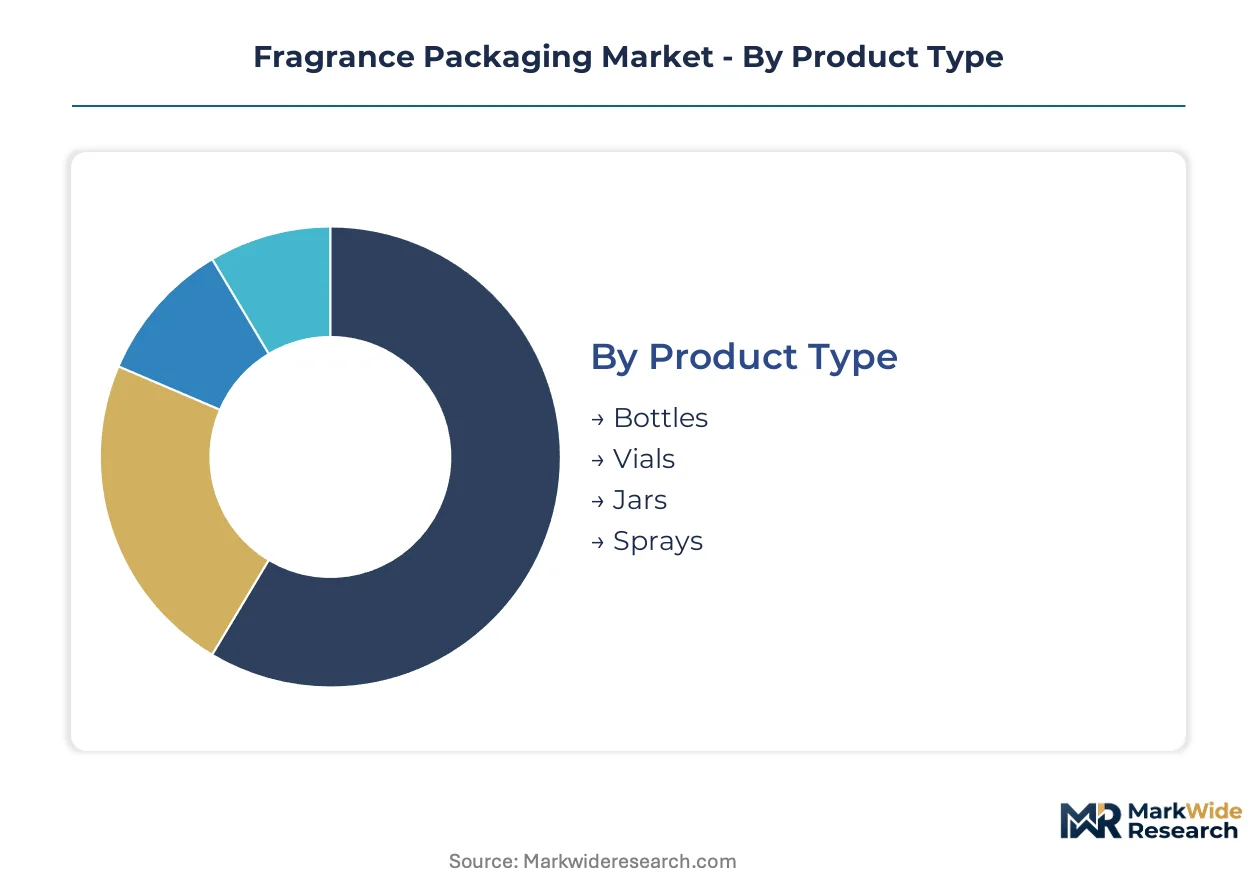
Segmentation in fragrance packaging reveals how capital deployment, regulatory exposure, and brand positioning intersect across substrate choices and dispensing formats. Converters allocate furnace capacity and tooling investments based on which segments command premium pricing and repeat procurement cycles.
Product Type:
Blown-glass bottle manufacturing demands the heaviest capital commitment, with furnace infrastructure and mold fabrication consuming the majority of converter balance sheets across European manufacturing clusters.
- Bottles:Borosilicate and soda-lime glass formulations dominate prestige fragrance lines for chemical inertness and optical clarity. Heritage maisons in France and Italy anchor demand through multi-year supply agreements with specialized converters.
- Vials:Miniature formats serve travel-retail sampling and subscription service distribution, with airport duty-free operators in Germany and the United Kingdom doubling procurement volumes for fragrance discovery programs.
- Jars:Solid perfume and balm applications utilize thick-walled glass or acrylic substrates for finger-access dispensing.
- Sprays:Integrated pump-bottle systems combine primary container and dispensing mechanism in single-SKU procurement.
Bottles absorb the bulk of installed capacity; vials are expanding most quickly.
Material:
Feedstock selection determines regulatory compliance burden, with glass commanding the highest furnace energy costs and plastic facing the steepest REACH reformulation requirements.
- Glass:Post-consumer recycled content mandates under the EU Packaging and Packaging Waste Regulation force reformulation of soda-lime feedstocks. French and Italian converters invest in cullet processing infrastructure to meet minimum recycled thresholds.
- Plastic:Pump housings and closure systems rely on bio-based thermoplastic elastomers substituting for phthalate-restricted formulations. REACH compliance extends qualification timelines for new resin grades entering European supply chains.
- Metal:Aluminum caps and decorative collars provide lightweight alternatives to glass stoppers in mass-market applications.
- Paperboard:Secondary wrapping and rigid box construction face pressure to reduce grammage while maintaining structural protection during distribution.
Glass commands the deepest capital investment; plastic faces the steepest substitution pressure.
Closure Type:
Thread geometry and elastomer compatibility specifications vary sharply between single-use prestige formats and refillable systems engineered for repeated actuation cycles.
- Screw Caps:Machined aluminum or zamac alloy constructions dominate prestige fragrance presentations, with Italian metal decorators specializing in high-luster surface finishes.
- Pumps:Crimp-on assemblies with silicone or thermoplastic elastomer seals serve fine fragrance dispensing. REACH restrictions on phthalate plasticizers force reformulation across German and French pump manufacturers.
- Roll-ons:Ball-and-housing systems concentrate in deodorant and body spray applications with lower fragrance oil concentrations.
- Mist Sprayers:Trigger-style mechanisms appear in home fragrance and room spray categories outside traditional personal perfume markets.
Pumps capture the largest procurement volumes; screw caps retain the strongest pricing power.
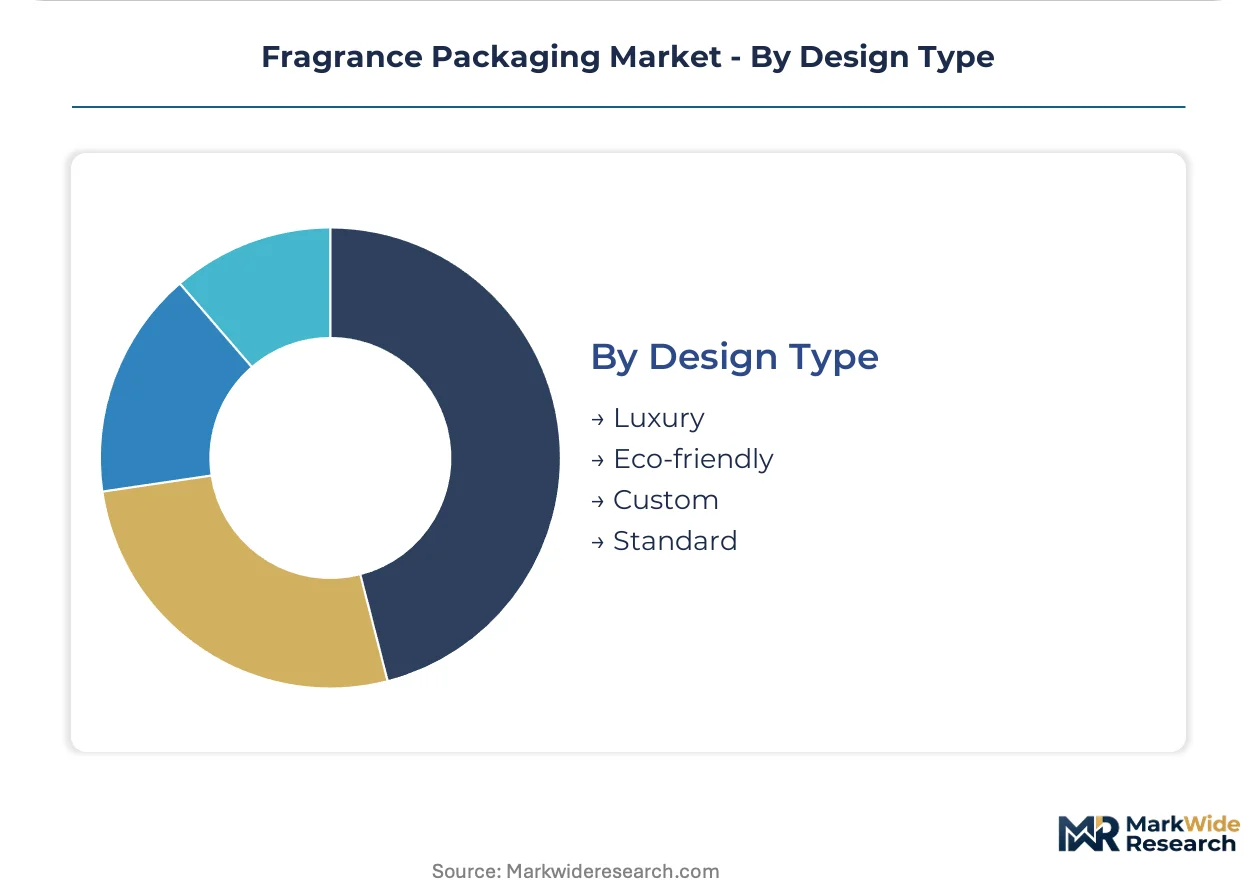
Design Type:
Brand positioning tiers separate tooling amortization strategies, with luxury formats justifying bespoke mold investments and eco-friendly specifications driving standardization for circular material flows.
- Luxury:Bespoke bottle shapes, hand-finished surface treatments, and precious metal accents require dedicated mold fabrication and skilled artisan labor concentrated in Burgundy and Murano manufacturing clusters.
- Eco-friendly:Refillable formats and mono-material constructions simplify end-of-life sorting. EU extended producer responsibility schemes incentivize design for disassembly across French and German brand portfolios.
- Custom:Limited-edition collaborations and seasonal releases utilize digital printing and laser engraving for short-run personalization without dedicated mold costs.
- Standard:Catalog shapes and off-the-shelf closures minimize lead times for indie brands and private-label fragrance operators.
Luxury designs command the highest per-unit margins; eco-friendly specifications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France, Italy, and Germany concentrate heritage fragrance manufacturing and anchor procurement decisions for premium glass converters. Supply chain investments follow these demand centers.
France
Heritage maisons in Paris and Grasse drive borosilicate bottle specifications for high-concentration perfume oils. REACH restrictions on heavy metal pigments constrain decorative surface treatments from Burgundy metal decorators. Verescence France SASU operates furnace capacity in the Pocé-sur-Cisse cluster to serve LVMH and Kering fragrance portfolios.
Italy
Murano glass artisans and Lombard pump manufacturers supply limited-run prestige formats for niche perfumeries. ECHA phthalate restrictions force reformulation of thermoplastic elastomer seals across Venetian converter facilities. Coverpla S.A. anchors artisanal metal cap production in Milan's packaging corridor.
Germany
Travel-retail expansion at Frankfurt and Munich airports accelerates vial procurement for fragrance discovery programs. EU Packaging and Packaging Waste Regulation cullet mandates drive investment in post-consumer recycled glass feedstocks at Gerresheimer AG's Essen manufacturing complex.
United States
Subscription-based replenishment services in New York and Los Angeles metropolitan areas standardize bottle geometries for automated fulfillment. FDA migration testing protocols extend certification timelines for new closure elastomers entering the market. Quadpack Ltd. serves indie brand accounts from its North American distribution hub.
United Kingdom
London-based direct-to-consumer fragrance startups fragment traditional retail procurement with low-MOQ converter relationships. Extended producer responsibility schemes under UK packaging regulations pressure secondary packaging reduction. Albéa maintains pump assembly operations to serve mass-market and prestige accounts across British retail channels.
Fragrance Packaging Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue refillable format specialization and digital personalization services. The supplier base stratifies across blown-glass heritage houses, pump system integrators, and aluminum closure specialists. Three archetypes dominate: furnace-scale glass converters with multi-decade maison relationships, agile low-MOQ specialists serving indie brands, and cross-material integrators offering bottle-closure-secondary systems. Competitive moves concentrate on capacity expansion in recycled cullet processing and strategic partnerships for mono-material pump development.
Among European furnace-scale operators, Gerresheimer AG and Verescence France SASU exemplify the heritage glass converter archetype with deep relationships in French and German luxury fragrance houses. Saverglass occupies a position within the artisanal tier, leveraging Burgundy manufacturing heritage for limited-run prestige formats. Albéa represents the cross-material integrator model, spanning pump assemblies and closure systems across both mass-market and prestige account segments.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Saverglass |
| Verescence France SASU |
| Albéa |
| Quadpack Ltd. |
| AptarGroup |
| EXAL Corporation |
| Piramal Glass Ltd. |
| Coverpla S.A. |
| Others |
Supply Flow & Price Mechanics
Family-owned furnace operators in Burgundy and Murano anchor premium glass supply, translating multi-generational artisan networks into pricing discipline that resists commoditization despite energy cost volatility. Their concentrated ownership structures limit capacity expansion responsiveness, tightening supply availability for bespoke borosilicate formats and sustaining margin premiums across heritage fragrance accounts.
Pricing Analysis
Volume procurement concentrates in standardized soda-lime bottles where German and French converters compete on furnace throughput, while margin capture clusters in limited-run borosilicate specifications for Parisian and Grasse maisons. Price differentiation hinges on batch consistency certification and hand-finishing labor intensity. Cost compression in mass-market tiers intensifies as aluminum closure substitution erodes glass stopper demand. Indie fragrance houses exhibit highest price sensitivity, deferring to off-the-shelf catalog shapes; luxury maisons absorb premium tooling amortization with minimal negotiation leverage exercised.
Supply Chain Analysis
Reverse-logistics infrastructure for refillable fragrance programs remains underdeveloped, with only Gerresheimer and Verescence piloting dedicated cullet recovery networks for repeated-use bottle formats. Primary supply concentrates in France, Italy, and Germany where furnace clusters draw from Belgian soda ash and Spanish silica sand feedstocks. Single-source vulnerability concentrates in skilled furnace operator availability across European manufacturing clusters. Distribution runs through heritage maison direct procurement for prestige tiers, while mass-market channels utilize packaging distributors serving private-label operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation erects a compliance moat that favors incumbent converters with installed cullet processing infrastructure, marginalizing aspirant entrants lacking capital for extended producer responsibility scheme participation.
For Market Incumbents: Lock in multi-year borosilicate supply agreements with Grasse and Parisian heritage maisons before REACH reformulation deadlines accelerate qualification costs. Backward integration into Spanish silica sand sourcing mitigates energy-driven margin compression. Defensive priority rests on securing limited-run artisan capacity in Murano against niche perfumery demand fragmentation. For New Entrants and Emerging Players: Begin with low-MOQ digital personalization services for London and New York direct-to-consumer fragrance startups, bypassing furnace-scale capital requirements. Subscription service bottle standardization represents the most penetrable procurement segment. Go-to-market leverage centers on rapid prototyping partnerships with Burgundy converters possessing idle artisan labor capacity. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap pump manufacturers in Lombardy facing REACH elastomer reformulation cost overruns, with consolidation value emerging from combined closure-bottle system capabilities. Long-term viability favors converters with demonstrated EU regulatory compliance infrastructure. Monitor ECHA phthalate restriction enforcement intensity as inflection signal for thermoplastic elastomer substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Recycled Glass Feedstock Investment | Verescence and Gerresheimer furnace retrofits satisfy EU cullet mandates ahead of enforcement deadlines. |
| Mono-Material Pump Assembly Development | Albéa and AptarGroup R&D targets disassembly-compatible dispensing systems for circular material flows. |
| Digital Personalization Tooling Deployment | Laser engraving and single-run printing capabilities capture limited-edition fragrance release demand. |
| Direct-to-Consumer Channel Integration | Quadpack distribution partnerships bypass traditional retail markup structures for indie brand accounts. |
| Artisan Capacity Preservation Partnerships | Saverglass Burgundy heritage positioning secures scarce skilled furnace operator labor pools. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with fragrance house procurement directors, glass converter plant managers, pump system R&D leads, and EU regulatory affairs specialists. ECHA restriction updates, French packaging federation sustainability reports, and Italian glass industry export statistics supplied validation benchmarks. Bottom-up SKU-level procurement analysis triangulated against top-down furnace capacity estimates across European manufacturing clusters.
Data-stream reconciliation across shipment volumes, furnace operating rates, and maison portfolio expansion plans shaped the analytical framework. Segmentation modeling incorporated product type, material substrate, closure mechanism, and design tier dimensions across the projection horizon. CAGRs derived from installed capacity utilization trends and regulatory compliance cost trajectory assumptions. Forecast inputs included REACH plasticizer substitution timelines and travel-retail channel recovery patterns.
Energy price volatility, ECHA enforcement intensity shifts, and refillable program consumer adoption rates are the dominant revision risks. Forecasts reflect documented assumptions regarding regulatory implementation schedules and furnace fuel cost baselines. Practitioners should monitor natural gas futures, ECHA substance restriction consultation outcomes, and airport duty-free operator SKU expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Europe Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic Tubes Market
Cosmetic Packaging
Latin America Personal Care Packaging Market
Cosmetic Packaging
Hair Care Packaging Market
Cosmetic Packaging
Lotion Tubes Market
Cosmetic Packaging
Eyeliner and Kajal Sculpting Pencil Packaging Market
Cosmetic Packaging
Single Portion Cosmetic Packaging Market
Cosmetic Packaging
Make-Up Products Packaging Market
Cosmetic Packaging
China Personal Care Packaging Market
Cosmetic Packaging
Nail Polish Packaging Market
Cosmetic Packaging
Injection Moulding Cosmetic Packaging Market
Cosmetic Packaging
Lip Care Packaging Market
Cosmetic Packaging
Plastic Cosmetic Packaging Market
Cosmetic Packaging
Middle East and Africa Personal Care Packaging Market
Cosmetic Packaging
Global Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic Bottles Packaging Market