
 Polymer Bearing Market | 2026-2036
Polymer Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Bearing Market Intelligence
The polymer bearing market is recalibrating around a widening performance gap between aerospace-certified grades and standard industrial commodities. Schaeffler Technologies AG & Co. KG leverages its integrated materials science division to control PTFE compound formulations from resin to finished component. Igus Inc. sustains dominance in maintenance-free sliding bearings through its engineered plastics laboratory in Cologne.
Polymer bearings are self-lubricating tribological components manufactured from thermoplastic or thermosetting polymers—typically PTFE, nylon, or ultra-high-molecular-weight polyethylene—often reinforced with glass fiber or carbon fiber to achieve load capacities exceeding 50 MPa while operating without external lubrication in corrosive or hygienic environments. Sliding bearings lead volume demand in conveyor and packaging machinery where dry-running tolerance eliminates grease contamination, while composite bearings capture expanding margin pools in medical imaging equipment requiring radiolucency and magnetic resonance compatibility. Ball bearings remain the most mature category, with polyethylene-based variants finding replacement demand in chemical processing pumps.
REACH restrictions on perfluorinated substances and FDA 21 CFR food-contact material approvals shape polymer selection and compound development timelines across European and North American supply chains. Germany's KBA and Japan's METI enforce distinct automotive durability standards that fragment qualification protocols for tier-one suppliers. Stakeholders must monitor evolving PFAS regulatory thresholds and pre-qualify alternative polymer formulations before existing compound families face supply discontinuation.
Market Dynamics
REACH restrictions on perfluorinated substances are forcing polymer bearing manufacturers to requalify entire compound families before 2025 supply discontinuation deadlines, compressing R&D timelines while fragmenting qualification protocols across automotive and medical supply chains.
Growth Catalysts
- Food-contact compliance mandates:FDA 21 CFR approvals for polymer compounds are eliminating metal bearing alternatives in dairy processing equipment across Wisconsin and California dairy clusters.
- Maintenance-free tribology:Self-lubricating PTFE formulations are capturing replacement demand in chemical processing pumps where external grease contamination risks trigger unplanned shutdowns.
- Germany precision engineering concentration:KBA automotive durability standards are driving premium-grade polymer bearing adoption in Stuttgart and Munich OEM supply chains.
Market Restraints
- PFAS resin supply concentration:European PTFE compound feedstock relies on concentrated fluoropolymer resin production in Germany and Italy, creating single-source vulnerability.
- Load capacity ceiling:Standard thermoplastic formulations face displacement by ceramic hybrid bearings in wind turbine main shaft applications exceeding 80 MPa dynamic loads.
- REACH compliance cost inflation:ECHA substance of very high concern listings are extending polymer qualification timelines from 18 to 36 months for aerospace-certified grades.
Strategic Opportunities
- India pharmaceutical machinery:CDSCO medical device regulations are creating first-mover advantage for radiolucent polymer bearings in Mumbai and Hyderabad imaging equipment manufacturing.
- Carbon fiber reinforcement convergence:Composite bearing architectures combining UHMWPE matrices with carbon fiber are opening surgical robotics applications requiring MRI compatibility.
- Direct OEM technical sales:Bypassing distributor networks through application engineering teams is capturing margin in Japanese automotive tier-one procurement.
Industry Challenges
- Tribology simulation expertise scarcity:Finite element modeling of polymer wear rates requires specialized material science PhDs concentrated in Cologne and Boston research clusters.
- Multi-standard certification complexity:Simultaneous FDA, EMA, and ISO 13485 qualification for medical-grade bearings extends time-to-revenue by 14-22 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Bearing Market |
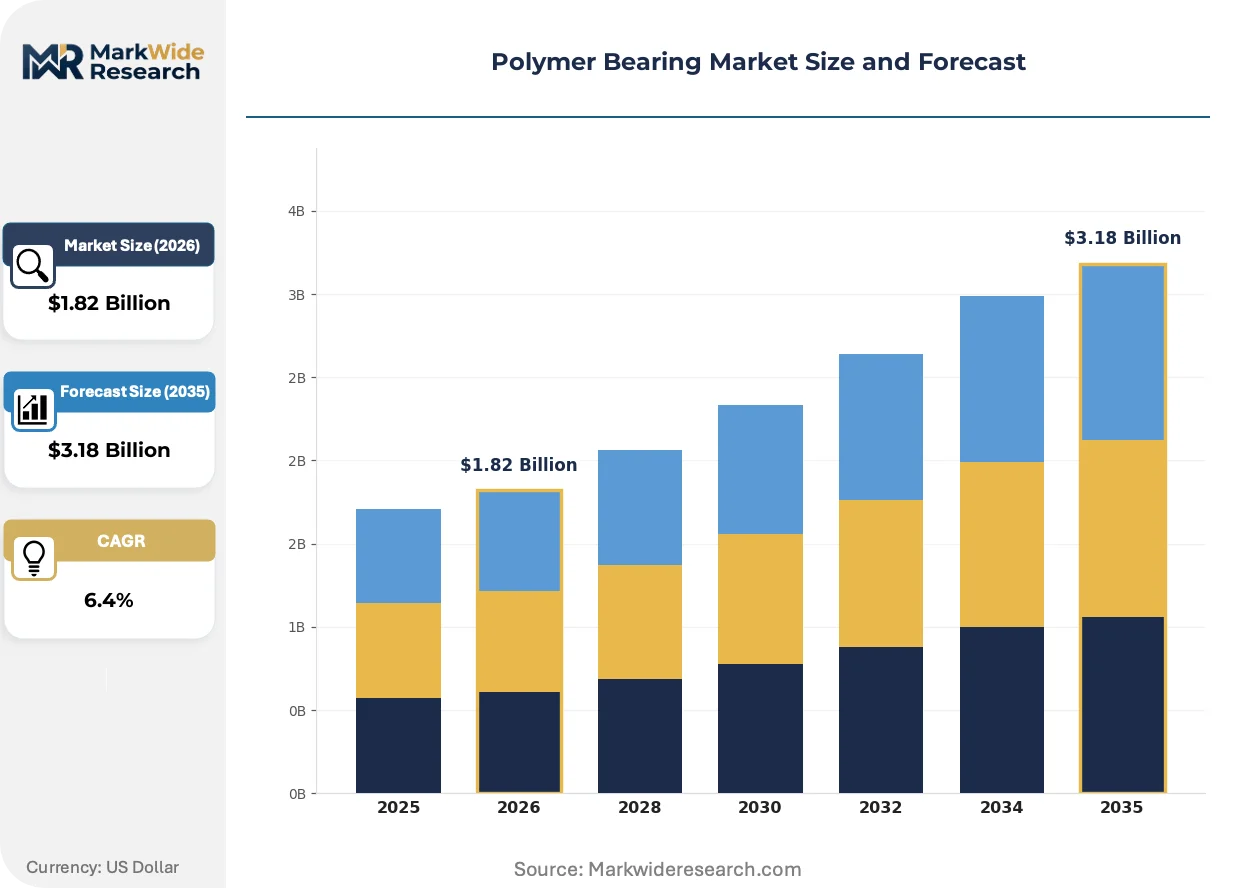
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearings, Roller Bearings, Sliding Bearings, Composite Bearings Material: Polyethylene, Nylon, Polypropylene, PTFE End Use Industry: Aerospace, Automotive, Food Processing, Medical Demand Type: Original Equipment Manufacturer, Replacement, Custom Solutions, Others |
| Companies Covered | Schaeffler Technologies AG & Co. KG, NTN Corporation, Igus Inc., Saint-Gobain, Oiles Corporation, SKF, NSK Ltd., MinebeaMitsumi Inc., The Timken Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Bearing Market Strategic Shifts & Innovations
Material science advances are collapsing the performance gap between polymer and metal bearings in high-load rotating applications, while regulatory pressure on fluorinated compounds accelerates alternative formulation development.
PEEK-based composite bearings with carbon fiber reinforcement are overtaking traditional PTFE-lined metal shells in aerospace landing gear actuators. Boeing and Airbus tier-one suppliers in Wichita and Toulouse are qualifying these formulations for 50,000-cycle maintenance intervals. This overtaking is compressing the addressable market for bronze-backed PTFE bearings in defense applications.
ECHA's 2023 PFAS restriction proposal is forcing compounders to accelerate bio-based polyamide development for European food machinery. Manufacturers in Bologna and Lyon are pre-qualifying glass-reinforced PA66 formulations to maintain EU market access. Medical imaging OEMs in Germany face the steepest reformulation timelines due to existing FDA 510(k) dependencies.
Consolidated procurement through technical buying centers is displacing regional distributor relationships in North American automotive supply chains. Tier-one suppliers in Detroit and Spartanburg now mandate direct application engineering support for polymer bearing selection. This concentration is most visible in electric vehicle powertrain programs where thermal management requirements exceed standard catalog specifications.
Polymer Bearing Market Segmentation
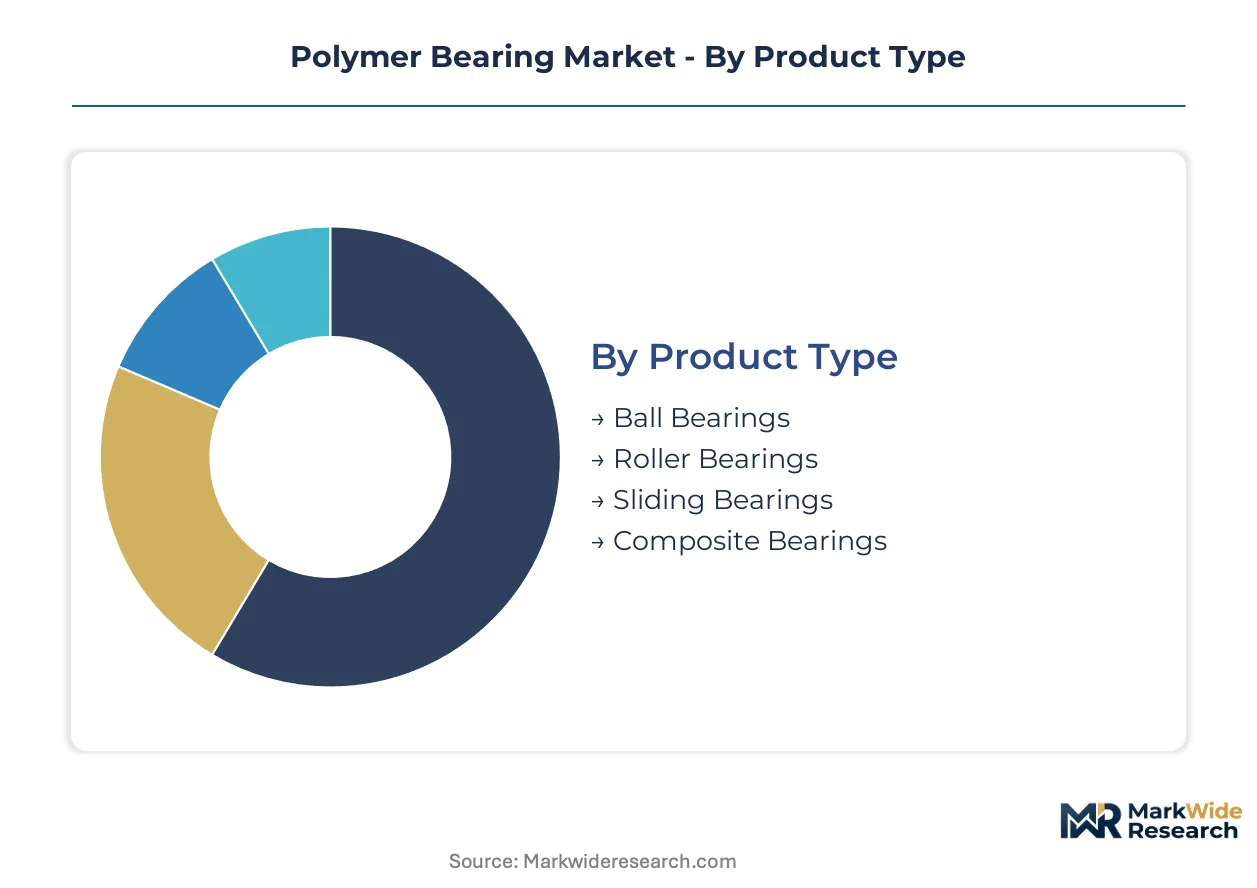
Segmentation in polymer bearings reveals how material science capabilities align with divergent buyer priorities across load-bearing, regulatory, and lifecycle requirements. Technical buyers select formulations based on tribological performance ceilings, while procurement teams weigh qualification timelines against total cost of ownership in regulated end-uses.
Product Type:
Load tolerance and motion type separate buyers—rotating applications demand rolling elements, while oscillating or linear motion favors sliding architectures.
- Sliding Bearings:Self-lubricating PTFE or UHMWPE sleeves operate dry in conveyor and packaging machinery across Wisconsin dairy clusters, eliminating grease contamination risks that trigger FDA inspection failures. Demand concentrates in food processing OEMs specifying maintenance-free tribology for washdown environments.
- Composite Bearings:Reinforced polymer matrices with carbon fiber or glass fiber achieve radiolucency and MRI compatibility for medical imaging equipment in German manufacturing clusters, where PEEK formulations replace metal in surgical robotics. METI durability standards in Japanese automotive tier-one procurement are accelerating carbon-epoxy hybrid adoption for weight-critical assemblies.
- Ball Bearings:Polyethylene-based variants serve chemical processing pumps with corrosion resistance exceeding bronze alternatives.
- Roller Bearings:Cylindrical polymer designs handle higher radial loads in material handling equipment.
Sliding bearings lead volumes today; composite bearings are gaining share fastest.
Material:
Regulatory exposure and thermal ceiling determine formulation selection, with fluorinated compounds facing supply discontinuation pressure.
- PTFE:Perfluoropolymer resin delivers the lowest coefficient of friction among engineered plastics, sustaining dominance in aerospace actuators and chemical pumps where REACH restrictions on PFAS are forcing compounders to secure alternative feedstock before supply cliffs. KBA automotive specifications in Stuttgart OEM networks still mandate PTFE for precision tolerance retention across temperature cycles.
- Nylon:Glass-reinforced PA66 formulations from Bologna compounders are capturing food machinery share as ECHA restrictions accelerate bio-based polyamide development, with Lyon manufacturers pre-qualifying grades to maintain EU market access despite reformulation timelines extending qualification windows.
- Polyethylene:UHMWPE variants serve low-load, high-wear applications in material handling.
- Polypropylene:Cost-positioned formulations dominate consumer appliance and light industrial uses.
PTFE maintains installed base dominance; nylon is expanding most quickly.
End Use Industry:
Certification burden and performance premium separate buyers—medical and aerospace demand traceable qualification chains, while automotive prioritizes volume scale.
- Medical:CDSCO regulations in Mumbai and Hyderabad imaging equipment manufacturing are creating first-mover advantage for radiolucent bearings, with FDA 510(k) dependencies in German OEMs extending reformulation timelines for PFAS-free alternatives. Carbon fiber-reinforced PEEK bearings enable MRI-compatible surgical robotics requiring magnetic resonance compatibility.
- Food Processing:FDA 21 CFR approvals for polymer compounds are eliminating metal alternatives in dairy processing equipment, with Wisconsin and California clusters specifying self-lubricating formulations to prevent lubrication contamination in pasteurization lines.
- Aerospace:Boeing and Airbus tier-one suppliers in Wichita and Toulouse qualify PEEK composites for 50,000-cycle maintenance intervals.
- Automotive:KBA durability standards and METI specifications fragment qualification protocols for tier-one suppliers.
Food processing leads volumes today; medical is climbing the fastest.
Demand Type:
Specification control and margin capture separate buyers—OEMs demand application engineering integration, while replacement markets prioritize interchangeability.
- Original Equipment Manufacturer:Direct technical sales with application engineering teams capture margin in Japanese automotive tier-one procurement, where Detroit and Spartanburg electric vehicle powertrain programs mandate thermal management specifications exceeding standard catalog offerings. Consolidated buying centers are displacing distributor relationships.
- Replacement:Aftermarket demand concentrates in chemical processing and food machinery where bearing failure triggers unplanned shutdown costs exceeding component price multiples.
- Custom Solutions:Patient-specific medical devices and aerospace actuators require compound formulation from resin to finished component.
- Others:Maintenance contract bundles and spare part kits serve fragmented industrial installed bases.
OEM demand leads volumes today; custom solutions show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Materials science PhDs concentrate in Cologne and Boston research clusters, anchoring polymer formulation expertise. Stuttgart and Munich precision engineering networks drive premium-grade specification demand. Japanese tribology specialists in Nagoya and Osaka sustain distinct qualification protocols.
Germany
KBA automotive durability standards mandate PTFE tolerance retention across temperature cycles for Stuttgart OEM networks. ECHA PFAS restriction proposals compress reformulation timelines for compounders in Cologne and Leverkusen. Bavarian medical imaging OEMs face extended FDA 510(k) dependencies when switching to PFAS-free alternatives.
United States
FDA 21 CFR approvals eliminate metal bearing alternatives in Wisconsin and California dairy processing clusters. EPA scrutiny of fluorinated substances accelerates bio-based polyamide qualification in industrial Midwest markets. Wichita aerospace tier-one suppliers qualify PEEK composites for Boeing and Airbus landing gear actuators.
Japan
METI durability specifications fragment automotive qualification protocols for Nagoya and Osaka tier-one suppliers. JIS standards govern precision tolerance requirements in Chubu manufacturing belts. Tokyo-based procurement teams mandate direct application engineering support for electric vehicle powertrain programs.
India
CDSCO medical device regulations create first-mover positioning for Mumbai and Hyderabad imaging equipment manufacturers. BIS standards for industrial components lag behind FDA and EMA benchmarks, extending import dependency for aerospace-certified grades. Gujarat pharmaceutical machinery clusters specify radiolucent bearings for export compliance.
Italy
Glass-reinforced PA66 formulations from Bologna compounders capture food machinery share as ECHA restrictions accelerate. Lyon manufacturers pre-qualify bio-based polyamides to maintain EU market access despite extended qualification windows. Emilia-Romagna packaging machinery OEMs specify self-lubricating sleeves for washdown environments.
Polymer Bearing Market Key Industry Players
Top-tier vendors anchor integrated materials science capabilities, while mid-scale compounders compete on regional qualification speed. The vendor base stratifies across resin-to-component integrators, specialized tribology laboratories, and catalog-scale distributors. Three archetypes dominate: captive resin formulators controlling PTFE compounds from feedstock to finished bearing; application engineering specialists embedding directly into OEM technical buying centers; and maintenance-free sliding bearing providers leveraging Cologne-based R&D density. Competitive moves concentrate on backward integration into fluoropolymer resin supply and direct technical sales bypassing distributor networks.
Among Germany-based integrated manufacturers, Schaeffler Technologies AG & Co. KG exemplifies the captive formulation archetype, while Igus Inc. represents the maintenance-free sliding bearing specialist model. Japanese precision bearing manufacturers including NTN Corporation and NSK Ltd. occupy positions shaped by METI durability standards and consolidated automotive procurement. Saint-Gobain anchors the European composite materials tier with ceramics-to-polymers portfolio breadth.
| Leading Market Players |
|---|
| Schaeffler Technologies AG & Co. KG |
| NTN Corporation |
| Igus Inc. |
| Saint-Gobain |
| Oiles Corporation |
| SKF |
| NSK Ltd. |
| MinebeaMitsumi Inc. |
| The Timken Company |
| Others |
Cost & Logistics Intelligence
Fluoropolymer resin feedstock flows from concentrated German and Italian production sites through compounders to finished bearing tiers, with REACH-driven reformulation costs compressing margins at standard-grade levels while aerospace-certified formulations retain pricing power.
Pricing Analysis
Application engineering support bundles separate premium polymer bearing tiers from catalog-scale offerings. Three-tier pricing structure across aerospace-certified, automotive-grade, and standard industrial levels reflects qualification burden and resin formulation complexity. Pricing pressure stems from ECHA PFAS restriction timelines accelerating R&D cost absorption. Replacement buyers in chemical processing show lowest price sensitivity due to unplanned shutdown costs, while consumer appliance OEMs drive hardest volume negotiations.
Supply Chain Analysis
PTFE resin supply rests on fluoropolymer production concentrated in Germany, Italy, and Japan, with carbon fiber reinforcement drawing from aerospace-certified fiber suppliers in the United States and Japan. Raw material dependencies span perfluorinated feedstock, glass fiber, and bio-based polyamide alternatives under development. Single-source vulnerability in European fluoropolymer resin creates qualification timeline risk for compounders facing supply discontinuation deadlines. Distribution runs through technical buying centers in Stuttgart, Detroit, and Nagoya that mandate direct OEM engineering engagement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with food processing and medical imaging buyers shifting procurement toward FDA-validated, maintenance-free formulations that command specification premiums.
For Market Incumbents: Lock in resin-to-component integration by securing captive fluoropolymer feedstock before REACH supply cliffs, and embed application engineering teams directly into Stuttgart and Nagoya OEM technical buying centers to defend against ceramic hybrid bearing substitution in high-load rotating applications. Prioritize certification investment for PFAS-free compound families to maintain aerospace and medical qualification pipelines. For New Entrants and Emerging Players: Direct technical sales channels offer the lowest-friction entry path, bypassing consolidated distributor relationships to capture margin in Indian pharmaceutical machinery clusters where CDSCO regulations create first-mover positioning for radiolucent bearings. Target Mumbai and Hyderabad imaging equipment manufacturers with MRI-compatible PEEK formulations, and leverage carbon fiber reinforcement expertise from adjacent composites industries to qualify surgical robotics applications. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-standard certification complexity extends time-to-revenue for mid-scale compounders lacking integrated materials science divisions. Long-term viability favors vendors controlling formulation from resin through finished component, with acquisition value concentrating on Cologne and Boston tribology laboratories possessing finite element modeling capabilities. Watch ECHA PFAS restriction implementation timelines as the critical inflection signal for alternative compound family adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin | Captive PTFE feedstock secures supply continuity ahead of REACH-mandated discontinuation deadlines in European markets. |
| Direct OEM Technical Sales Expansion | Application engineering teams in Stuttgart and Nagoya bypass distributor networks to capture margin in consolidated procurement. |
| Bio-Based Polyamide Qualification | Pre-qualified PA66 formulations from Bologna compounders maintain EU food machinery access despite ECHA restriction timelines. |
| Carbon Fiber Reinforcement Scale-Up | PEEK composite architectures enable MRI-compatible surgical robotics penetration in German medical imaging clusters. |
| Multi-Standard Certification Investment | Simultaneous FDA, EMA, and ISO 13485 qualification compresses time-to-revenue for medical-grade bearing portfolios. |
Research Approach
Coverage spans Germany, the United States, Japan, India, and Italy, with primary inputs from each market combining interviews with polymer compound R&D directors, OEM procurement managers in automotive and medical device manufacturing, food processing equipment engineers, and aftermarket service heads with secondary validation from ECHA regulatory filings, FDA 510(k) databases, KBA and METI automotive standards, and customs trade data. Bottom-up demand modeling triangulates against top-down macroeconomic indicators.
Granularity-level modeling operates at the intersection of material formulation, product architecture, and end-use certification tier. Segmentation dimensions include polymer type, reinforcement method, load capacity specification, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, OEM specification adoption curves, and qualification timeline compression effects. Forecast inputs incorporate REACH compliance cost trajectories and PFAS alternative compound development rates across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for bio-based polyamide and ceramic hybrid bearing substitution would alter the outlook. Forecasts reflect assumptions regarding regulatory implementation timelines, resin supply continuity, and OEM specification stickiness. Supply discontinuation risk, qualification timeline extension, and substitution technology maturation warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Global Industrial Chain Market
Industrial Materials
Global Thermally Modified Wood Market
Industrial Materials
Global Friction Materials Market
Industrial Materials
Crimped Wire Brushes Market
Industrial Materials
Elastomeric Couplings Market
Industrial Materials
Powder Funnels Market
Industrial Materials
Industrial Pails and Drums Market
Industrial Materials
Global Graphite Electrodes Market
Industrial Materials
Briquetting Press Market
Industrial Materials
Heat Shrink Tubing and Sleeves Market
Industrial Materials
Extruders Market
Industrial Materials
Bamboo Products Market
Industrial Materials
Plastics in Electrical and Electronics Market
Industrial Materials
Tension Spring Market
Industrial Materials
Global High Pressure Seals Market
Industrial Materials
Cork Material Market