
 Industrial Continuous Furnaces Market | 2026-2036
Industrial Continuous Furnaces Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Continuous Furnaces Market Insights
Asset-light leasing and project finance models is fragmenting the competitive landscape for industrial continuous furnaces, enabling mid-sized foundries and ceramics plants to access high-capacity thermal processing lines without full capital ownership. Andritz AG leverages its integrated metallurgy division to sustain long-term service contracts across European steel mills. SECO/WARWICK Group anchors its position through specialized vacuum and atmosphere furnace systems for aerospace-grade heat treatment. Ipsen International competes on modular furnace architectures that reduce installation downtime for automotive OEM clients.
Industrial continuous furnaces are enclosed thermal processing systems designed to heat, sinter, melt, or treat materials on a moving conveyor or pusher mechanism, typically operating at temperatures from 300°C to over 1,700°C depending on the process and refractory lining composition. These systems serve primary industrial purposes including continuous annealing of steel strip, ceramic tile firing, glass tempering, and powder metallurgy sintering, where throughput consistency and thermal uniformity directly determine yield quality. Belt conveyor and tunnel furnace configurations command the largest installed base due to their compatibility with high-volume ceramics and metal processing lines, while pusher furnace systems capture premium margin pools in precision metallurgical applications requiring controlled atmosphere processing. Electric resistance heating technology leads current order books in regions with stringent carbon intensity rules, though gas-fired systems retain cost advantages in markets with lower natural gas tariffs.
EPA emissions standards for hazardous air pollutants from metal finishing operations, EMA carbon border adjustments affecting imported heat-treated components, and ISO 13577 safety standards for industrial thermoprocessing equipment collectively shape furnace design requirements and procurement specifications across major manufacturing economies. Foundries in the United States and European Union now face combined regulatory pressure to retrofit or replace gas-fired installations with electric or hybrid heating systems to maintain operating permits. Stakeholders must monitor evolving carbon accounting methodologies and their impact on total cost of ownership calculations before committing to long-dated furnace investments.
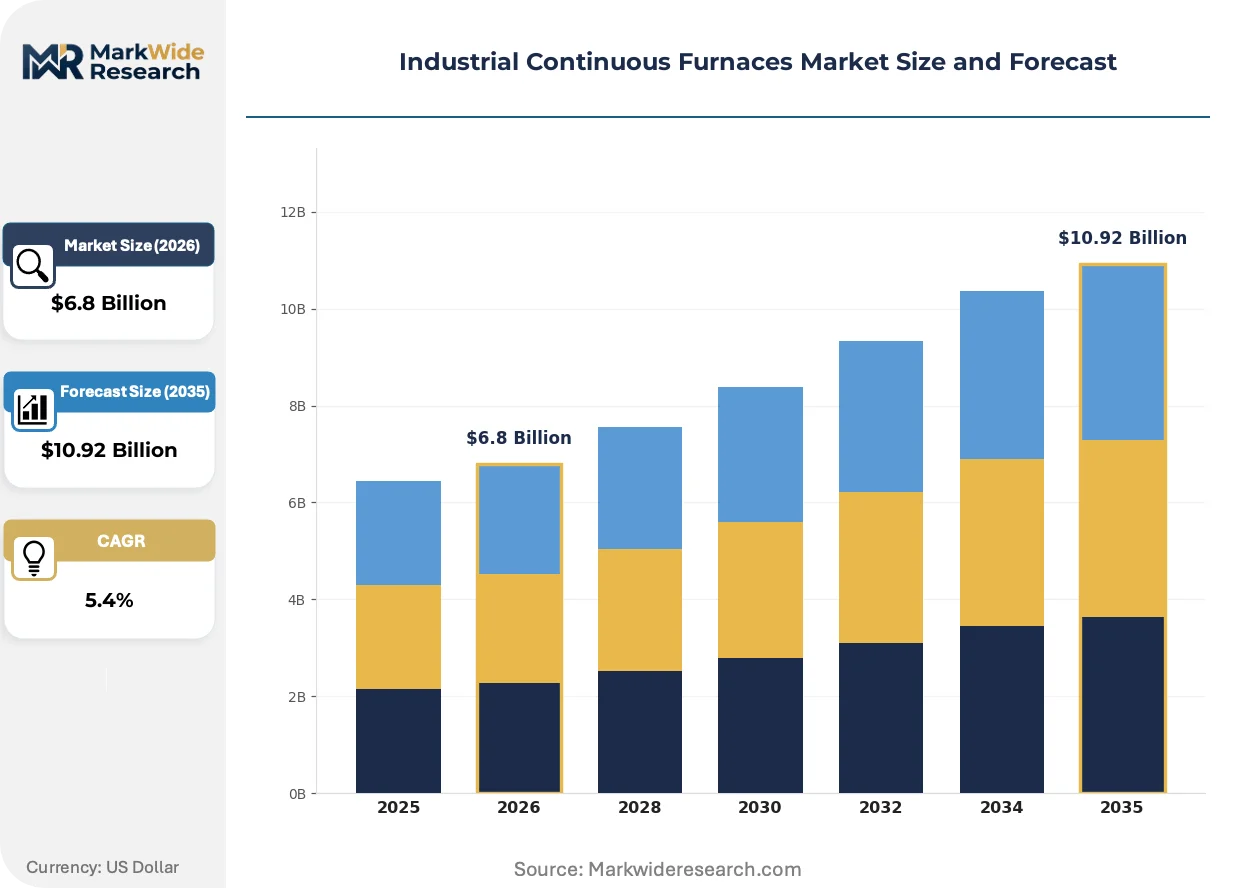
Market Dynamics
Electric resistance heating systems are displacing gas-fired furnaces across OECD manufacturing bases as carbon border adjustments and emissions trading schemes rewrite total cost of ownership calculations for long-dated thermal processing assets.
Growth Catalysts
- EMA Carbon Border Adjustment Mechanism:European importers of heat-treated metal components now face embedded emissions charges, pushing domestic manufacturers toward electric furnace retrofits to preserve contract competitiveness.
- Powder metallurgy sintering demand:Automotive transmission and electric drivetrain producers are expanding continuous belt furnace capacity for precision sintered components.
- China:Dual carbon policy enforcement is accelerating replacement of coal-fired tunnel kilns in ceramics clusters across Guangdong and Zhejiang provinces.
Market Restraints
- Refractory material cost volatility:Magnesia and alumina price swings from South African and Chinese supply concentration compress furnace builder margins.
- Technical limitation in ultra-high temperature:Electric resistance elements above 1,600°C exhibit shorter service intervals than gas-fired alternatives in tungsten carbide sintering applications.
- REACH compliance friction:Ceramic fiber insulation classifications under EU chemical regulations extend qualification timelines for European furnace deployments.
Strategic Opportunities
- India:PLI scheme incentives for specialty steel and automotive components are creating first-mover openings for atmosphere furnace system providers.
- Hydrogen-ready burner retrofits:Hybrid furnace architectures capable of fuel switching between natural gas and hydrogen are capturing early specification wins in German steel service centers.
- Service contract unbundling:Predictive maintenance subscriptions using thermal imaging diagnostics are opening recurring revenue streams independent of equipment sales cycles.
Industry Challenges
- Refractory installation skill scarcity:Specialized bricklaying and monolithic lining crews for high-temperature furnace construction face generational workforce gaps in the United States and Germany.
- ISO 13577 certification timelines:Third-party safety validation for custom atmosphere furnace designs extends project delivery by four to seven months.
- Legacy SCADA integration:Brownfield continuous furnace lines require protocol bridging to connect proprietary control systems with modern MES platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Continuous Furnaces Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Furnace Type: Batch, Rotary, Tunnel, Pusher, Belt Conveyor, Pit Heating Technology: Electric Resistance, Gas-Fired, Induction, Infrared, Microwave, Solar Application Sector: Metal Processing, Ceramics Production, Glass Manufacturing, Chemical Synthesis, Metallurgical Processing, Electronics Fabrication End User Industry: Foundries, Energy Providers, Aircraft Component Producers, Construction Material Plants, Semiconductor Manufacturers, Automotive OEMs |
| Companies Covered | Andritz AG, SECO/WARWICK Group, Ipsen International, Ebner Furnaces, Carbolite Gero, Nutec Bickley, Gasbarre Products, International Thermal Systems, Surface Combustion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Continuous Furnaces Market Trends and Innovations
Process control digitization and alternative heating modalities are converging to redefine furnace performance benchmarks, compressing thermal uniformity tolerances while expanding the addressable process window for advanced materials.
Induction-assisted resistance heating is hybridizing conventional furnace architectures by embedding modular induction coils at critical thermal zones, enabling automotive heat treaters to achieve faster ramp rates in gear hardening lines without full equipment replacement.
EPA Maximum Achievable Control Technology standards for hazardous air pollutants from metal finishing operations are mandating regenerative thermal oxidizer integration on new atmosphere furnace installations, compelling foundries in Michigan and Ohio to redesign exhaust handling configurations before permit approval.
Asset-light leasing structures are displacing traditional capital purchase models for mid-volume ceramics producers, with German equipment financiers now underwriting tunnel furnace deployments against throughput-based revenue shares rather than balance sheet collateral.
Industrial Continuous Furnaces Market Segmentation
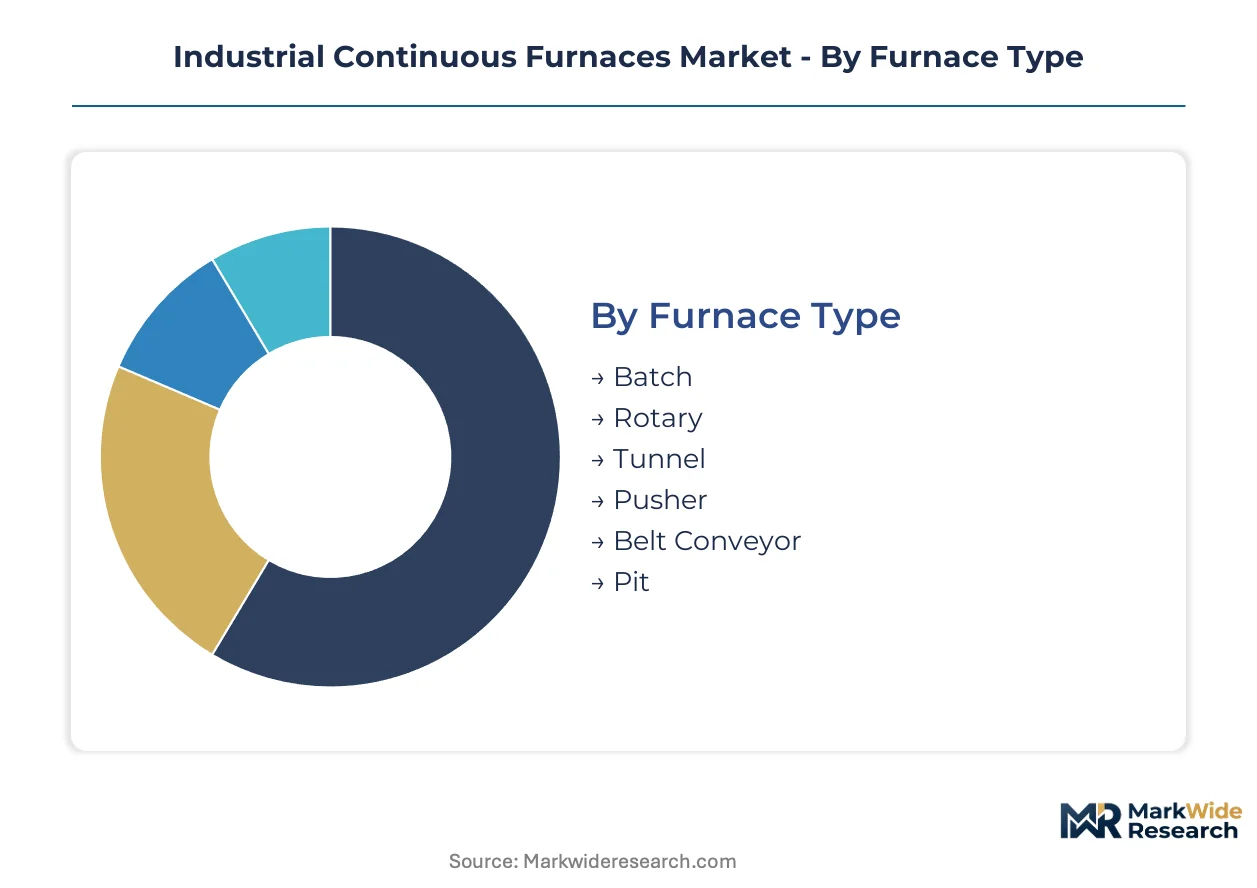
Industrial continuous furnace procurement cycles vary dramatically by configuration complexity and thermal duty. Equipment replacement timelines stretch from seven years for standardized belt systems to twenty-five years for custom atmosphere furnaces, fragmenting vendor revenue predictability across installed base vintages.
Furnace Type:
Cycle times for furnace replacement and retrofit diverge sharply across mechanical configurations, with continuous-motion designs turning over faster than static-chamber systems due to wear on conveying mechanisms and refractory linings.
- Belt Conveyor:Continuous steel mesh or cast link belts transport materials through heated zones, enabling high-throughput ceramics firing and powder metallurgy sintering. Demand concentrates in Guangdong ceramics clusters and Midwestern automotive heat-treat operations where EPA emissions deadlines accelerate replacement schedules.
- Tunnel:Enclosed linear chambers with pusher or roller conveyance handle large-volume brick, tile, and sanitary ware production. Chinese manufacturers under dual carbon policy enforcement are retiring coal-fired tunnel kilns for electric retrofits at the fastest clip globally.
- Pusher:Refractory alloy trays advance materials through controlled atmosphere zones for precision metallurgical processing. Aerospace component producers in Germany and the United States specify these systems for superalloy heat treatment requiring tight temperature uniformity.
- Rotary:Cylindrical drums rotate materials through heated zones for continuous calcination and drying operations.
- Batch:Intermittent loading chambers serve low-volume specialty processing where continuous flow economics fail.
- Pit:Vertical shaft furnaces handle large forging ingots and heavy castings requiring uniform through-thickness heating.
Belt conveyor systems anchor the volume base while tunnel configurations gain share at the steepest rate under carbon policy enforcement.
Heating Technology:
Capital cost tiers separate mature combustion technologies from emerging electric and electromagnetic alternatives, with fuel switching economics rewriting procurement specifications across OECD manufacturing bases.
- Electric Resistance:Nickel-chromium or silicon carbide elements deliver precise temperature control up to 1,600°C with zero direct emissions. European steel service centers facing EMA carbon border adjustments are specifying electric retrofits to preserve contract competitiveness against imported heat-treated components.
- Gas-Fired:Direct and indirect combustion burners retain cost advantages in markets with suppressed natural gas tariffs, though regenerative thermal oxidizer integration adds capital burden under EPA Maximum Achievable Control Technology standards.
- Induction:Electromagnetic field heating enables rapid selective surface hardening without bulk workpiece heating. Automotive transmission producers are embedding induction coils at critical thermal zones to accelerate gear hardening cycle times.
- Infrared:Radiant heating elements target surface treatments and drying applications with rapid response characteristics.
- Microwave:Dielectric heating penetrates materials volumetrically for specialized ceramic and polymer processing.
- Solar:Concentrated thermal energy systems serve experimental high-temperature applications in sun-belt manufacturing geographies.
Gas-fired technology still dominates installed capacity while electric resistance systems are climbing the fastest under emissions trading scheme pressure.
Application Sector:
Process temperature requirements and atmosphere control stringency segment furnace specifications, with high-purity applications commanding premium pricing over commodity thermal processing.
- Metal Processing:Continuous annealing, normalizing, and stress relieving of steel strip and bar stock. Demand clusters in German automotive supply chains and Indian specialty steel mills benefiting from PLI scheme incentives.
- Metallurgical Processing:Sintering, brazing, and heat treatment of powder metal and precision components. Electric drivetrain producers are expanding belt furnace capacity for soft magnetic composite stator cores.
- Ceramics Production:Firing of structural clay, refractory, and advanced ceramic products. Chinese provincial environmental inspectors are forcing kiln replacements in Zhejiang and Fujian manufacturing corridors.
- Glass Manufacturing:Tempering, annealing, and coating of flat and container glass products.
- Chemical Synthesis:Continuous calcination and thermal decomposition of inorganic compounds.
- Electronics Fabrication:Controlled atmosphere processing of semiconductor substrates and passive components.
Metal processing anchors the volume base while metallurgical processing gains share at the steepest rate under powder metallurgy sintering demand expansion.
End User Industry:
Customer scale and technical sophistication fragment procurement patterns, with integrated OEMs demanding modular architectures and mid-tier foundries gravitating toward service-inclusive leasing structures.
- Automotive OEMs:Transmission, engine, and chassis component heat treatment at production scale. Michigan and Ohio-based manufacturers are redesigning exhaust handling configurations to secure EPA permits for new atmosphere furnace installations.
- Foundries:Ferrous and non-ferrous casting heat treatment and stress relieving. Asset-light leasing structures are displacing capital purchases for mid-volume operations unable to carry long-dated furnace assets on balance sheets.
- Aircraft Component Producers:Superalloy and titanium heat treatment for airframe and engine applications. Tighter emissions thresholds under EPA and EMA rules are scaling purchases of tunnel and pusher furnace lines.
- Semiconductor Manufacturers:Wafer diffusion and thin-film thermal processing requiring ultra-high purity atmospheres.
- Construction Material Plants:Cement, lime, and gypsum calcination in continuous rotary and vertical shaft configurations.
- Energy Providers:Catalyst regeneration and solid oxide fuel cell manufacturing.
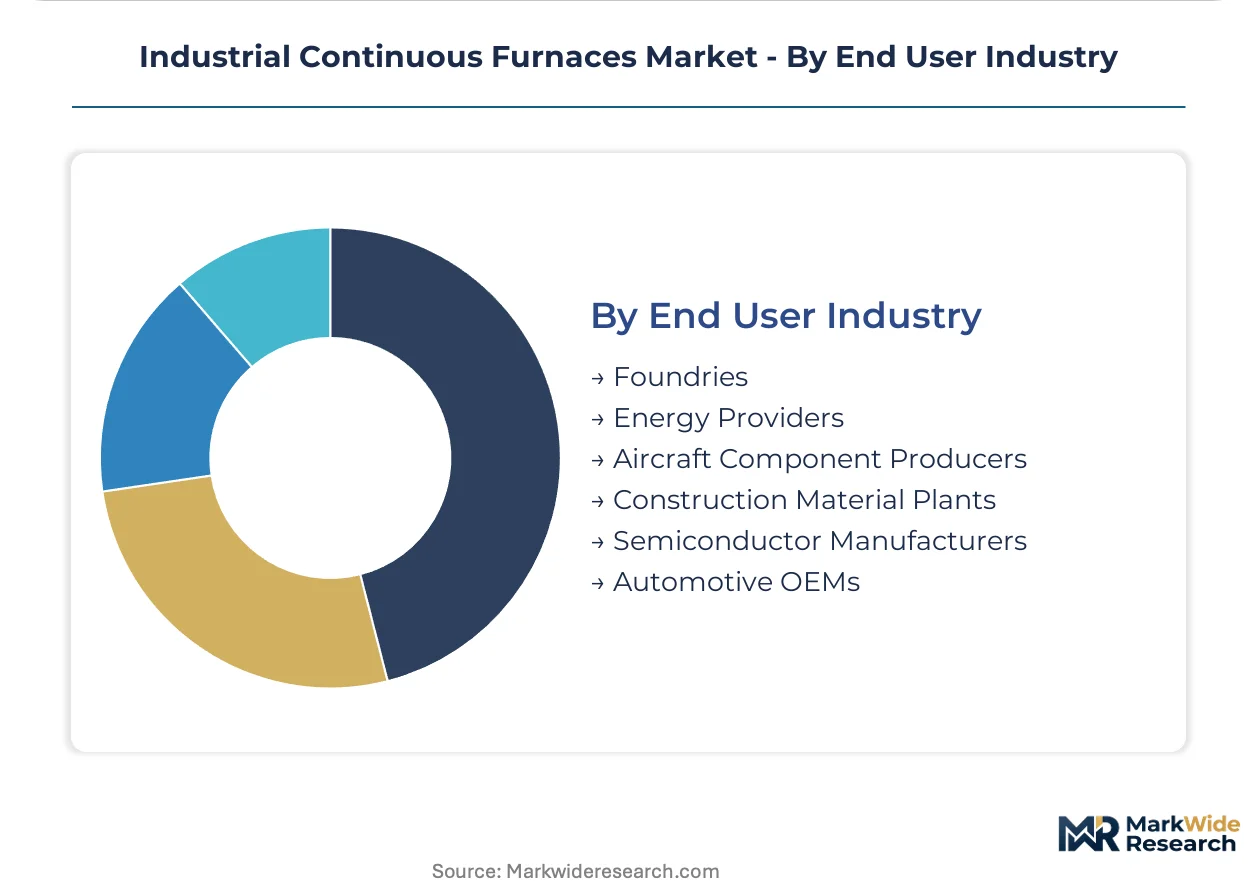
Foundries anchor the volume base while aircraft component producers gain share at the steepest rate under commercial aerospace production recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German furnace builders command 15-20% price premiums over Chinese suppliers for equivalent thermal capacity, while Guangdong ceramics manufacturers absorb that spread through faster delivery cycles and localized service networks. This asymmetry shapes procurement patterns across OECD and emerging manufacturing bases.
United States
Automotive heat-treaters in Michigan and Ohio are retrofitting atmosphere furnace exhaust systems to secure EPA Maximum Achievable Control Technology permits before 2026 deadlines. The Inflation Reduction Act's industrial emissions credits accelerate electric resistance furnace conversions at steel service centers. Cleveland-Cliffs and Nucor operations in Indiana and Alabama anchor the largest capacity replacement cycle.
China
Provincial environmental inspectors in Zhejiang and Guangdong are forcing coal-fired tunnel kiln retirements under dual carbon policy enforcement. MIIT efficiency standards for metallurgical equipment disqualify gas-fired systems from new project approvals in Yangtze River Delta manufacturing corridors. Foshan ceramics clusters are completing the fastest electric retrofit deployment globally.
Germany
Steel service centers in North Rhine-Westphalia are specifying hydrogen-ready burner architectures to preserve optionality under EU Green Deal industrial decarbonization timelines. EMA carbon border adjustment charges on imported heat-treated components push domestic manufacturers toward electric furnace specifications. Ruhr Valley heat-treatment operations anchor premium pusher furnace demand.
India
PLI scheme incentives for specialty steel and automotive components are creating first-mover openings for atmosphere furnace system providers in Maharashtra and Gujarat. BIS energy efficiency labeling for industrial heating equipment tightens procurement specifications at state-owned metal processing facilities. Pune and Chennai automotive supply chains are expanding continuous belt furnace capacity.
Japan
Powder metallurgy sintering operations in Aichi Prefecture are upgrading belt furnace lines for electric drivetrain component production under METI automotive electrification targets. JIS standards for industrial thermoprocessing equipment safety extend qualification timelines for custom atmosphere furnace deployments. Nagoya-area precision component manufacturers anchor demand for high-uniformity thermal systems.
Industrial Continuous Furnaces Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in refractory linings, heating elements, and atmosphere control subsystems. The vendor base organizes into three tiers: full-line furnace builders with integrated metallurgy divisions, specialized atmosphere and vacuum system providers, and regional fabricators serving commodity heat-treatment markets. Consolidation pressure concentrates at the mid-tier where scale disadvantages collide with rising certification costs. Dominant competitive moves include predictive maintenance service unbundling and hydrogen-ready architecture pre-positioning.
Among European-integrated industrial groups, Andritz AG and SECO/WARWICK Group exemplify contrasting archetypes—one leveraging diversified metallurgy platforms for long-term service capture, the other anchoring position through specialized vacuum and atmosphere configurations. Ipsen International occupies a position within the modular architecture tier, reducing installation downtime for automotive OEM procurement cycles. These three represent the competitive positioning spectrum: diversified platform, specialized system, and modular solution providers.
| Leading Market Players |
|---|
| Andritz AG |
| SECO/WARWICK Group |
| Ipsen International |
| Ebner Furnaces |
| Carbolite Gero |
| Nutec Bickley |
| Gasbarre Products |
| International Thermal Systems |
| Surface Combustion |
| Others |
Pricing and Supply Chain Analysis
Magnesia and alumina price volatility from South African and Chinese supply concentration compresses furnace builder margins while simultaneously widening pricing tier spreads between premium European systems and commodity Asian alternatives. This raw material chokepoint forces buyers into longer qualification cycles for refractory sourcing, reshaping procurement patterns across OECD manufacturing bases.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates ISO 13577-certified European systems from non-certified regional fabricators, with customization level and after-sales service bundling as secondary tiering factors. Cost compression in the economy tier is intensifying because Chinese manufacturers absorb refractory cost swings through localized supply networks. Mid-tier foundries exhibit the highest price sensitivity, while aerospace component producers prioritize certification compliance over unit economics.
Supply Chain Analysis
Export-control restrictions on high-purity alumina crucibles and silicon carbide heating elements limit technology flows from Germany and Japan to certain manufacturing corridors. Supply concentrates in China for refractory linings, South Africa for magnesia, and Germany for precision atmosphere control subsystems. Raw material dependencies rest on alumina, magnesia, and nickel-chromium alloys. Single-source vulnerability in South African magnesia exports creates structural exposure. Distribution runs through direct OEM sales for large furnace systems and regional distributor networks for aftermarket components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial continuous furnaces market sits in a cyclical recovery phase driven by EPA and EMA emissions compliance deadlines forcing replacement investment. Capital deployment now favors vendors with electric-ready architectures and service contract capabilities.
For Market Incumbents: Insulate installed base revenue by embedding predictive maintenance subscriptions using thermal imaging diagnostics, reducing customer switching incentives. Deepen backward integration into refractory lining production to capture margin pools currently leaking to South African and Chinese suppliers. Prioritize hydrogen-ready burner architecture certification to preempt EU Green Deal industrial decarbonization timelines.
For New Entrants and Emerging Players: Mid-market foundries in India and Southeast Asia represent the most penetrable entry point, as PLI scheme incentives and capacity expansion create first-mover openings without entrenched incumbent relationships. Atmosphere furnace retrofits for automotive heat-treaters facing EPA Maximum Achievable Control Technology deadlines offer a second white-space target. A leasing-based go-to-market model, underwriting deployments against throughput-based revenue shares, bypasses capital purchase barriers.
For Investors and Strategic Acquirers: The market sits at a replacement-cycle acceleration phase that favors specialized atmosphere system providers with aerospace certification pedigree. Long-term viability over a five-to-ten year window hinges on electric furnace specification share and hydrogen-ready architecture positioning. Watch for inflection in EMA carbon border adjustment enforcement intensity as the signal for accelerated electric retrofit demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Architecture Development | Preserves optionality under EU Green Deal industrial decarbonization timelines for German steel service centers. |
| Predictive Maintenance Service Unbundling | Opens recurring revenue streams independent of equipment sales cycles through thermal imaging diagnostics. |
| Backward Integration into Refractory Production | Captures margin pools currently compressed by South African and Chinese magnesia price volatility. |
| Electric Resistance Furnace Retrofit Programs | Secures EPA and EMA compliance contracts from Michigan and Ohio automotive heat-treaters. |
| Regional Manufacturing Footprint Expansion | Reduces delivery cycle advantages held by Guangdong ceramics equipment suppliers in Asian markets. |
Research Methodology
Desk research of trade association filings, customs and refractory import data, and EPA emissions compliance databases preceded structured interviews with plant engineers at automotive heat-treat operations, procurement leads at aerospace component manufacturers, aftermarket service heads at European furnace builders, and refractory supply specialists. Primary intelligence from furnace specification committees and installation contractors combined with secondary validation from SEC filings of integrated metallurgy groups and MIIT equipment efficiency standards. Bottom-up unit economics and top-down sector spend estimates were triangulated to anchor market sizing.
Assumptions held fixed include current EPA Maximum Achievable Control Technology enforcement intensity, EMA carbon border adjustment coverage scope, and MIIT metallurgical equipment efficiency standard thresholds. The analytical framework modeled furnace type, heating technology, application sector, and end-user industry dimensions across the projection horizon. CAGRs were derived from replacement cycle timing, capacity expansion pipelines, and regulatory deadline clustering. Forecast inputs incorporated powder metallurgy sintering demand trajectories from electric drivetrain producers and dual carbon policy enforcement intensity in Chinese ceramics clusters.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, natural gas-to-electricity price spreads, or refractory commodity indices would shift the trajectory. Material shifts in EPA enforcement timelines, EMA carbon border adjustment scope expansion, or breakthrough induction heating cost curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Injection Mold Hot Runners Market
Industrial Materials
High Purity Quartz Market
Industrial Materials
Polyurethane Insulation Board Market
Industrial Materials
Magnetic Separator Market
Industrial Materials
United States Engineering Plastics Market
Industrial Materials
Global Graphite Electrode Rod Market
Industrial Materials
Battery Separator Materials Market
Industrial Materials
Powder Processing Service Market
Industrial Materials
Industrial Wax Market
Industrial Materials
Argon Knife Market
Industrial Materials
Solid Surface Materials Market
Industrial Materials
Bamboo Products Market
Industrial Materials
Global Polycarbonate Sheets Market
Industrial Materials
Shock Mat Market
Industrial Materials
Metal Stamping Market
Industrial Materials
Encapsulated Gaskets/Seals Market