
 Ancillary Packaging Equipment Market | 2026-2036
Ancillary Packaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Ancillary Packaging Equipment Market Analytics
Software-defined maintenance contracts is broadening what packaging OEMs actually sell, shifting revenue from hardware shipments to uptime guarantees and remote diagnostics. Krones AG leverages its global service footprint to lock in multi-year aftermarket agreements. ProMach anchors its North American position through specialized integration capabilities across diverse end-user plants.
Ancillary packaging equipment encompasses the supporting machinery—labeling systems, filling stations, sealing units, and wrapping lines—that automate secondary and tertiary packaging operations downstream of primary forming equipment. These systems typically handle throughput rates from 50 to 1,200 units per minute depending on configuration, with servo-driven motion control replacing mechanical camshafts for format flexibility. Filling machines command the deepest margin pools due to precision dosing requirements in pharmaceutical and chemical applications, while robotics-based handling systems represent the fastest-expanding technology segment as labor costs escalate across European and Asian manufacturing hubs. Sealing machines remain the most mature product category, with incremental innovation focused on hermetic integrity verification rather than speed gains.
FDA cGMP guidelines and EU MDR traceability mandates compel pharmaceutical packagers to validate every ancillary line component for data integrity and cleanability. REACH chemical restrictions and ECHA substance evaluations further constrain sealant and lubricant specifications in European-installed equipment. Stakeholders must weigh total cost of ownership against regulatory compliance burdens when selecting between automatic and semi-automatic technology tiers.
Market Dynamics
Software-defined maintenance contracts are consolidating vendor-customer relationships around uptime guarantees rather than discrete hardware transactions, compressing traditional capital expenditure cycles into recurring operational commitments across pharmaceutical and food processing installations.
Growth Catalysts
- EU MDR serialization mandates:Pharmaceutical packagers in Germany and France must deploy automated labeling and verification systems to comply with track-and-trace requirements, forcing line retrofits and greenfield investments.
- Servo-driven motion control:Format flexibility demands from contract packagers are displacing mechanical camshafts with programmable servo architectures, reducing changeover downtime from hours to minutes.
- Labor cost escalation:Japanese and South Korean manufacturing hubs are accelerating robotics integration for palletizing and case packing to offset shrinking operator availability and rising wage floors.
Market Restraints
- Stainless steel and specialty alloy volatility:Filling machine fabricators face margin compression from nickel and molybdenum price swings, complicating long-term contract pricing.
- Precision dosing component concentration:High-accuracy pump and valve suppliers cluster in southern Germany and northern Italy, creating single-source vulnerability for pharmaceutical OEMs.
- Hermetic integrity verification limits:Current non-destructive testing protocols for sealing machines cannot reliably detect microleaks below 10 microns in high-speed rotary configurations.
Strategic Opportunities
- India pharmaceutical contract manufacturing:CDSCO compliance deadlines and PLI scheme incentives are driving demand for validated ancillary lines in Hyderabad and Ahmedabad clusters.
- Wet-wipe and personal care pouching:Single-serve format popularity in Southeast Asian retail is opening dedicated filling-sealing equipment categories distinct from traditional food packaging.
- Digital twin integration:Convergence of IoT sensor networks with predictive maintenance platforms enables remote diagnostics contracts that lock in decade-long service revenue streams.
Industry Challenges
- Mechatronics technician scarcity:Servo programming and vision system calibration require hybrid mechanical-electrical competencies that vocational pipelines in Italy and Spain cannot currently supply at scale.
- FAT/SAT timeline compression:Pharmaceutical buyers demand factory acceptance testing and site acceptance testing completion within 12-week windows that strain validation documentation workflows.
- Legacy PLC integration friction:Brownfield sites running Siemens S7-300 or Allen-Bradley ControlLogix architectures face protocol translation costs when connecting modern IIoT-enabled ancillary modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ancillary Packaging Equipment Market |
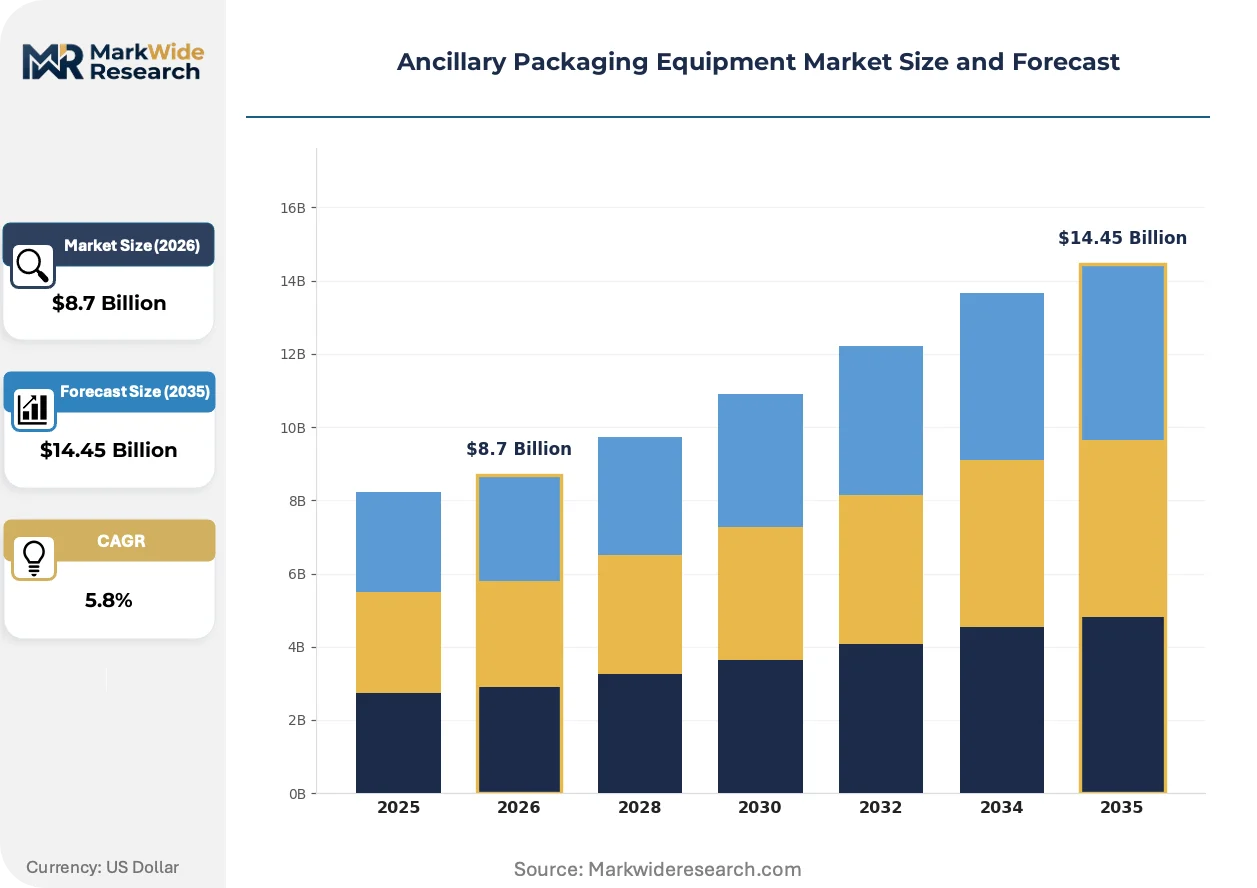
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Labeling Machines, Filling Machines, Sealing Machines, Wrapping Machines End User: Food & Beverage, Pharmaceuticals, Personal Care, Chemicals Size: Small Scale, Medium Scale, Large Scale, Industrial Scale Technology: Automatic, Semi-Automatic, Manual, Robotics |
| Companies Covered | Krones AG, ProMach, Syntegon Technology, MULTIVAC, Sidel, Coesia Group, Barry-Wehmiller, Ishida, IMA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ancillary Packaging Equipment Market Evolving Landscape
Active pharmaceutical ingredient containment and cold-chain biologics handling are redefining cleanroom-compatible machinery specifications, while artificial intelligence is compressing commissioning timelines through automated parameter optimization.
Collaborative robotics for end-of-line palletizing is consolidating material handling workflows previously split between fixed gantry systems and manual labor pools. Contract packagers in the Netherlands and Belgium are deploying UR20 and FANUC CRX units at throughput rates matching conventional solutions. This consolidation is collapsing the historical boundary between secondary packaging automation and tertiary logistics preparation.
REACH Article 33 substance disclosure requirements are forcing sealant and lubricant reformulations across European-installed equipment. ECHA evaluations of per- and polyfluoroalkyl substances are eliminating incumbent PTFE-based coatings from food-contact applications. Pharmaceutical OEMs in Switzerland and Denmark are responding with ceramic-coated alternatives validated for cGMP environments.
After-sales service unbundling is fragmenting traditional maintenance contracts into discrete remote monitoring, spare parts subscription, and on-demand technician dispatch tiers. Food and beverage processors in Brazil and Mexico are selecting modular service menus over comprehensive agreements. This pattern is most pronounced among mid-cap dairy and meatpacking operations seeking to match support spend to seasonal production curves.
Ancillary Packaging Equipment Market Segmentation
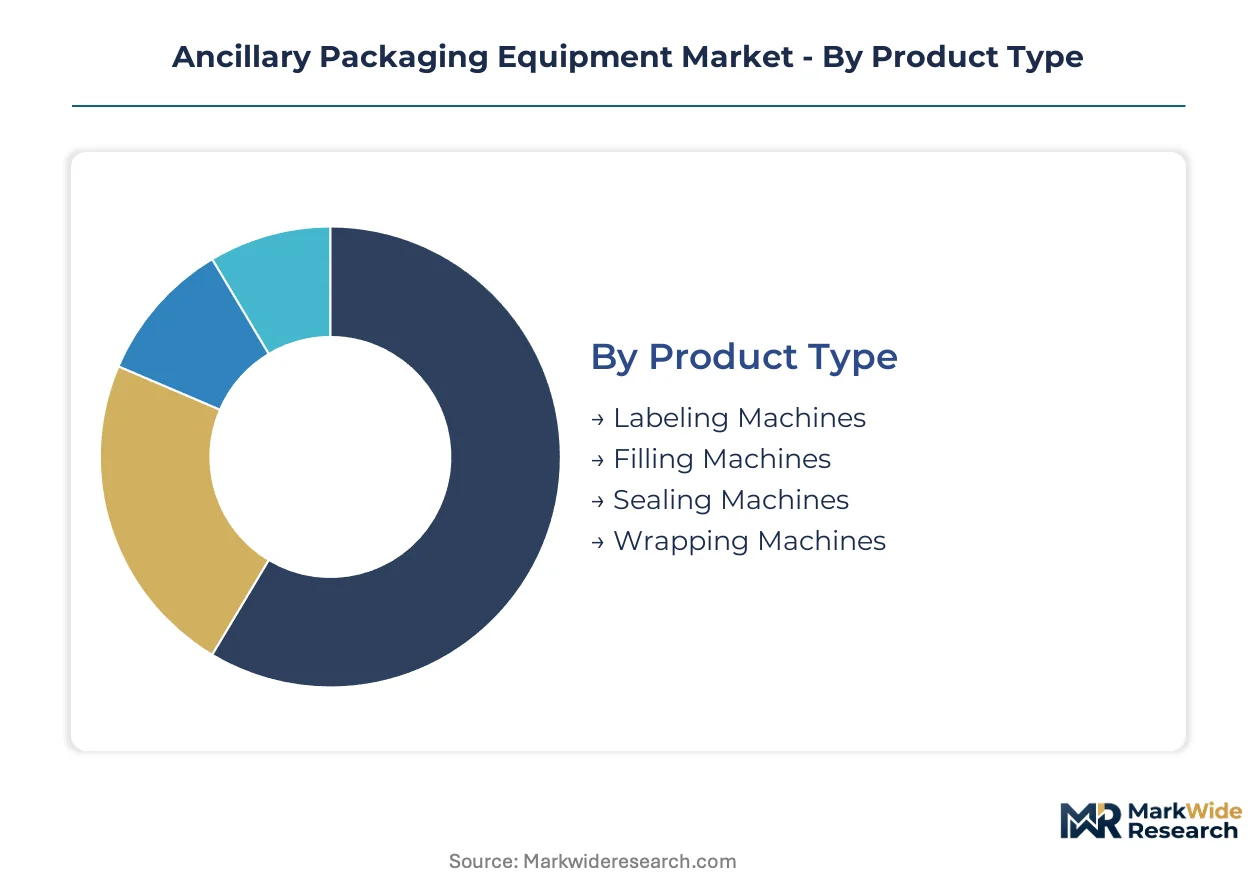
Ancillary packaging equipment spans heterogeneous performance tiers and compliance regimes. Equipment buyers segment procurement by throughput requirements, validation complexity, and labor substitution economics rather than hardware specifications alone.
Product Type:
Servo-driven architectures differentiate equipment categories by precision tolerances and changeover flexibility.
- Filling Machines:Positive-displacement and peristaltic pump configurations achieve dosing accuracy within ±0.5% for liquid pharmaceuticals and aggressive chemical formulations. Demand clusters in German pharmaceutical corridors where FDA and EU MDR validation requirements favor gravimetric feedback systems over volumetric alternatives.
- Labeling Machines:Pressure-sensitive and sleeve-application systems integrate serialization modules for track-and-trace compliance. Pharmaceutical packagers in France and Belgium prioritize vision-verified print quality for EU MDR mandates, while food processors emphasize throughput over verification depth.
- Sealing Machines:Impulse and continuous-band heat sealers dominate pouch and tray applications. Hermetic integrity testing remains limited to destructive sampling in most installations.
- Wrapping Machines:Stretch and shrink configurations handle tertiary collation for pallet stabilization. Food distribution centers in Spain and Italy specify film tension control for irregular produce geometries.
Mature deployment sits with sealing machines. Newer deployment is concentrated in filling machines.
End User:
Regulatory stringency and batch traceability requirements reshape equipment specifications across verticals.
- Pharmaceuticals:cGMP-validated stainless-steel construction with CIP/SIP compatibility defines procurement criteria. Serialization-ready labeling and verification systems command premium positioning as FDA track-and-trace deadlines and EU MDR mandates force line retrofits.
- Food & Beverage:High-throughput rotary fillers and wraparound case packers dominate dairy and beverage installations. REACH-compliant lubricant specifications constrain European equipment selection, particularly for incidental food-contact components.
- Personal Care:Wet-wipe pouching and single-serve sachet formats drive dedicated filling-sealing configurations distinct from traditional food packaging lines.
- Chemicals:Corrosion-resistant pump materials and explosion-proof electrical enclosures address aggressive formulations and solvent handling requirements.
Deployment maturity concentrates in food and beverage. Steepest expansion trajectory appears in pharmaceuticals.
Size:
Capital intensity and batch flexibility determine scale-tier selection for contract packagers versus captive operations.
- Large Scale:Integrated lines exceeding 600 units per minute serve multinational pharmaceutical and beverage manufacturers with dedicated facilities. German and Swiss installations emphasize redundant servo axes to minimize single-point failure exposure.
- Industrial Scale:Continuous-motion architectures for 24/7 operation integrate palletizing and warehouse management system connectivity.
- Medium Scale:Intermittent-motion equipment with 15-30 minute changeover windows targets regional contract packagers serving multiple SKUs.
- Small Scale:Benchtop fillers and semi-automatic sealers address pilot production and specialty chemical batches where validation documentation exceeds equipment cost.
Established volume sits with large scale. Emerging demand clusters in medium scale.
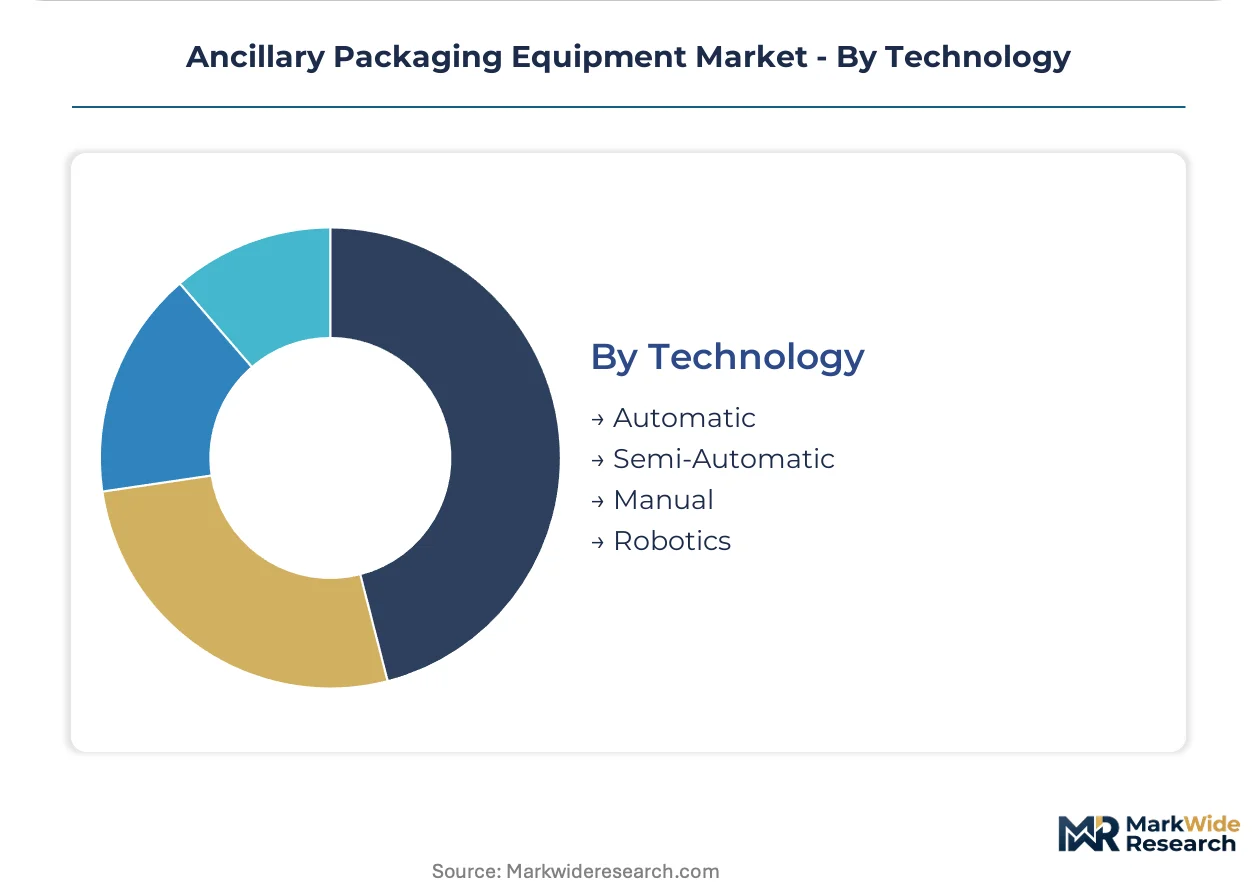
Technology:
Motion control architecture and operator substitution economics differentiate automation tiers.
- Robotics:Collaborative palletizing units from Universal Robots and FANUC consolidate end-of-line handling previously split between fixed gantries and manual labor. Dutch and Belgian contract packagers deploy these at throughput rates matching conventional solutions.
- Automatic:Servo-driven format changeover reduces downtime from hours to minutes, enabling pharmaceutical contract manufacturers to accommodate shorter production runs.
- Semi-Automatic:Operator-fed configurations persist in specialty chemical and personal care batches where SKU variety exceeds automation payback thresholds.
- Manual:Limited to prototype validation and regulatory sample preparation in pharmaceutical quality laboratories.
Conventional dominance rests with automatic systems. Fastest technology climb occurs in robotics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures more ancillary packaging equipment than it consumes, exporting servo-driven filling systems to pharmaceutical corridors worldwide. The United States and China absorb the largest import volumes, though each builds distinct regulatory specifications into procurement criteria.
Germany
Stuttgart and Hamburg host dense supplier ecosystems anchored by Krones AG and Syntegon Technology. EU MDR serialization mandates force domestic pharmaceutical packagers to retrofit labeling and verification lines. Baden-Württemberg fabricators specialize in stainless-steel filling machines validated for FDA and EMA submissions.
United States
FDA track-and-trace rules and cGMP guidelines compel pharmaceutical manufacturers to validate every line component for data integrity. Wisconsin and Ohio dairy processors drive demand for high-throughput rotary fillers with clean-in-place compatibility. Midwest contract packagers prioritize format flexibility to accommodate shorter production runs.
China
NMPA serialization requirements and dual carbon goals reshape equipment specifications for domestic pharmaceutical and beverage producers. Yangtze River Delta clusters in Shanghai and Suzhou concentrate wet-wipe pouching machine fabrication for Southeast Asian export. Local OEMs compete on cost while foreign joint ventures capture premium validation-intensive segments.
India
CDSCO compliance deadlines and PLI scheme incentives accelerate validated ancillary line deployment in Hyderabad and Ahmedabad pharmaceutical clusters. Contract manufacturers retrofit existing facilities to meet EU and US export standards. Domestic fabricators in Gujarat struggle to match German precision dosing tolerances for injectable formulations.
Japan
METI automation subsidies and shrinking operator availability push pharmaceutical and food manufacturers toward robotics-based palletizing. Osaka and Nagoya machinery builders integrate FANUC collaborative units into end-of-line configurations. PMDA validation protocols favor equipment with documented servo programming traceability.
Ancillary Packaging Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the ancillary packaging equipment landscape. German and Swiss fabricators maintain captive foundry relationships for specialty stainless-steel components, while Asian assemblers source standardized motion control modules from third-party suppliers. Three archetypes dominate: integrated line builders offering turnkey validation support, specialized component suppliers focusing on precision dosing or sealing subsystems, and regional integrators bundling third-party hardware with localized service networks. Competitive moves concentrate on multi-year aftermarket contracts and digital twin integration capabilities.
Among German-based integrated builders, Krones AG and Syntegon Technology exemplify the validation-centric archetype serving pharmaceutical and beverage multinationals. ProMach anchors the North American specialist tier through acquisition-driven portfolio breadth. These three occupy positions where hardware shipments increasingly bundle into uptime-guarantee contracts spanning decade-long service horizons.
| Leading Market Players |
|---|
| Krones AG |
| ProMach |
| Syntegon Technology |
| MULTIVAC |
| Sidel |
| Coesia Group |
| Barry-Wehmiller |
| Ishida |
| IMA Group |
| Others |
Value Network & Pricing Analysis
Pharmaceutical OEM procurement teams concentrate purchasing power among three integrated line builders, locking in decade-long service contracts that bundle hardware shipments with uptime guarantees and remote diagnostics subscriptions.
Pricing Analysis
Margin tightening in precision dosing equipment traces to nickel and molybdenum price volatility, compressing fabricator margins on stainless-steel filling machines. Three-tier pricing structure across premium, standard, and economy levels differentiates by validation documentation depth and servo axis redundancy. Cost-down pressure on mid-scale contract packagers accelerates because REACH-compliant lubricant reformulations add certification overhead. Food and beverage processors in Brazil and Mexico show highest price sensitivity, selecting unbundled service menus over comprehensive agreements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale pharmaceutical and beverage manufacturer demand, while regional integrators bundle third-party hardware with localized service networks for mid-cap operations. Component fabrication concentrates in Germany, Italy, and Switzerland, with Baden-Württemberg fabricators specializing in FDA-validated stainless-steel construction. Supply chains draw from specialty alloy foundries, servo motor suppliers, and precision pump manufacturers. Single-source vulnerability in high-accuracy pump and valve suppliers creates structural risk for pharmaceutical OEMs dependent on southern German and northern Italian clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Servo-driven motion control architectures are displacing mechanical camshafts across pharmaceutical and food processing lines, compressing capital expenditure cycles into recurring operational commitments.
For Market Incumbents: Extend multi-year aftermarket agreements into predictive maintenance platforms using IoT sensor networks, locking in service revenue against emerging digital-native competitors. Deepen backward integration into specialty stainless-steel foundries to offset alloy price volatility and secure margin control. Prioritize ceramic-coated component development ahead of ECHA per- and polyfluoroalkyl substance restrictions eliminating PTFE-based coatings.
For New Entrants and Emerging Players: System integrators in India and Southeast Asia represent the most penetrable channel partner type, retrofitting legacy lines for CDSCO and NMPA compliance without competing head-to-head with German validation-centric builders. Target wet-wipe pouching and single-serve sachet formats in Southeast Asian retail, where dedicated equipment categories remain distinct from entrenched food packaging suppliers. Lead with modular service menus matched to seasonal production curves.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale regional integrators with captive service networks in Brazil, Mexico, and India, where pharmaceutical contract manufacturing expansion outpaces local fabrication capability. Long-term viability hinges on digital twin integration competence and mechatronics technician training pipelines. Watch for inflection where FDA and EU MDR serialization mandate deadlines force accelerated line retrofit spending.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Maintenance Contract Expansion | Krones AG leverages global service footprint to convert hardware shipments into decade-long uptime guarantees. |
| Ceramic-Coated Component Development | Swiss and Danish pharmaceutical OEMs validate alternatives ahead of ECHA PTFE elimination timelines. |
| Collaborative Robotics Integration | Dutch and Belgian contract packagers deploy UR20 and FANUC CRX units at conventional throughput rates. |
| Digital Twin Platform Deployment | IoT sensor convergence enables remote diagnostics contracts locking in recurring service revenue streams. |
| Regional Service Network Buildout | ProMach anchors North American position through acquisition-driven integration capabilities across diverse plants. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across plant engineers, OEM procurement teams, aftermarket service heads, and mechatronics technicians. FDA 483 observations, EMA inspection reports, EU MDR technical documentation, and machinery import-export databases provided validation-intensive segment calibration. Bottom-up equipment shipment tallies and top-down pharmaceutical capital expenditure surveys underwent triangulation.
Segment-level volume and value estimates were reconciled against production capacity announcements and regulatory deadline impacts across the analysis window. Modeling incorporated product type, end-use vertical, scale tier, and motion control architecture dimensions. CAGRs derived from equipment replacement cycles, serialization mandate compliance spending, and robotics adoption curves in Japanese and South Korean manufacturing hubs.
Caveats apply where nickel and molybdenum price volatility, mechatronics technician scarcity, or REACH substance evaluation accelerations could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Global Reverse Vending Machine Market
Packaging Equipment
Heat Sealing Equipment Market
Packaging Equipment
Bag Re-Sealer Market
Packaging Equipment
Flatbed Die Cutters Market
Packaging Equipment
Depalletizers Market
Packaging Equipment
Corrugated Equipment Market
Packaging Equipment
Laser Coding Equipment Market
Packaging Equipment
Strapping and Banding Equipment Market
Packaging Equipment
Semi-Automatic and Manual Filling Equipment Market
Packaging Equipment
Nitrogen Filling Systems Market
Packaging Equipment
Bagging Equipment Market
Packaging Equipment
Shrink Sleeve Labeling Equipment Market
Packaging Equipment
Thermal Impulse Sealers Market
Packaging Equipment
Hydrapulper Market
Packaging Equipment
Filling Equipment Market
Packaging Equipment
PET Preform Machine Market