
 Strapping and Banding Equipment Market | 2026-2036
Strapping and Banding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Strapping and Banding Equipment Market Analytics
Multi-source procurement for strapping consumables is realigning toward captive supply arrangements as resin volatility persists. Dynaric leverages in-house extrusion capabilities to stabilize polyester strap margins. Samuel Packaging Systems anchors North American distribution through regional service depots. Signode Industrial Group competes on steel stranding integration with automated arch systems.
Strapping and banding equipment comprises machinery and hand tools that tension, seal, and cut flexible material around unitized loads, typically operating at banding forces from 50 to 2,000 pounds depending on package density. The equipment serves to secure palletized goods for transit handling and warehouse stacking. Automatic tools command the dominant share of capital expenditure as labor costs climb across logistics hubs. Polyester material adoption is outpacing polypropylene in heavy-gauge applications where elongation recovery and UV resistance determine load integrity. Steel strapping retains defensive margin pools in primary metals and construction end uses where cut resistance overrides weight considerations.
OSHA workplace safety standards govern operator guarding and tensioning mechanism interlocks on US-sold equipment, while EU machinery directives enforce CE conformity for automated arch strappers entering European logistics networks. ISO 9001 quality management certification shapes supplier qualification protocols for multinational consumer goods buyers. Stakeholders must monitor evolving extended producer responsibility frameworks for plastic strap recycling mandates.
Market Dynamics
Automated banding systems are compressing equipment replacement cycles as e-commerce fulfillment centers prioritize throughput velocity over capital preservation. The shift from semi-automatic to fully automated arch strappers is restructuring vendor relationships and service revenue models.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for high-global-warming-potential refrigerants in temperature-controlled logistics are accelerating equipment upgrades to electric-drive banding systems that eliminate pneumatic dependencies.
- Polyester strap elongation recovery:Heavy-gauge polyester adoption in automotive parts packaging is displacing steel in export-bound palletized loads where UV exposure and moisture resistance determine transit integrity.
- Germany's industrial packaging corridor:Machinery and automotive exporters in Baden-Württemberg and Bavaria are driving precision strapping specifications that pull high-tension automatic equipment demand.
Market Restraints
- Resin cost volatility:Fluctuations in petrochemical feedstock prices for polyester and polypropylene strap production are compressing margins for equipment vendors without captive extrusion capabilities.
- Steel stranding supply concentration:Primary metals and construction end uses remain locked into steel strapping where cut resistance requirements override weight reduction incentives, limiting polymer penetration.
- CE conformity timeline:EU machinery safety directives impose extended certification periods for automated arch strappers entering European logistics networks, delaying market entry for non-established suppliers.
Strategic Opportunities
- Extended producer responsibility frameworks:Emerging plastic strap recycling mandates in multiple jurisdictions are creating service revenue streams for equipment vendors that integrate closed-loop material recovery.
- Food and beverage cold chain:Temperature-stable banding applications in refrigerated distribution represent underpenetrated demand as grocers automate case-ready meat and produce packaging.
- ISO 9001 qualification protocols:Multinational consumer goods buyers are consolidating supplier bases around certified equipment vendors, favoring integrated service providers over component specialists.
Industry Challenges
- Interlock programming expertise:OSHA workplace safety standards for operator guarding and tensioning mechanism interlocks require specialized automation engineering talent that concentrates at established OEMs.
- Legacy system integration:Warehouse management system connectivity for automated strappers demands middleware development that extends deployment timelines and strains implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strapping and Banding Equipment Market |
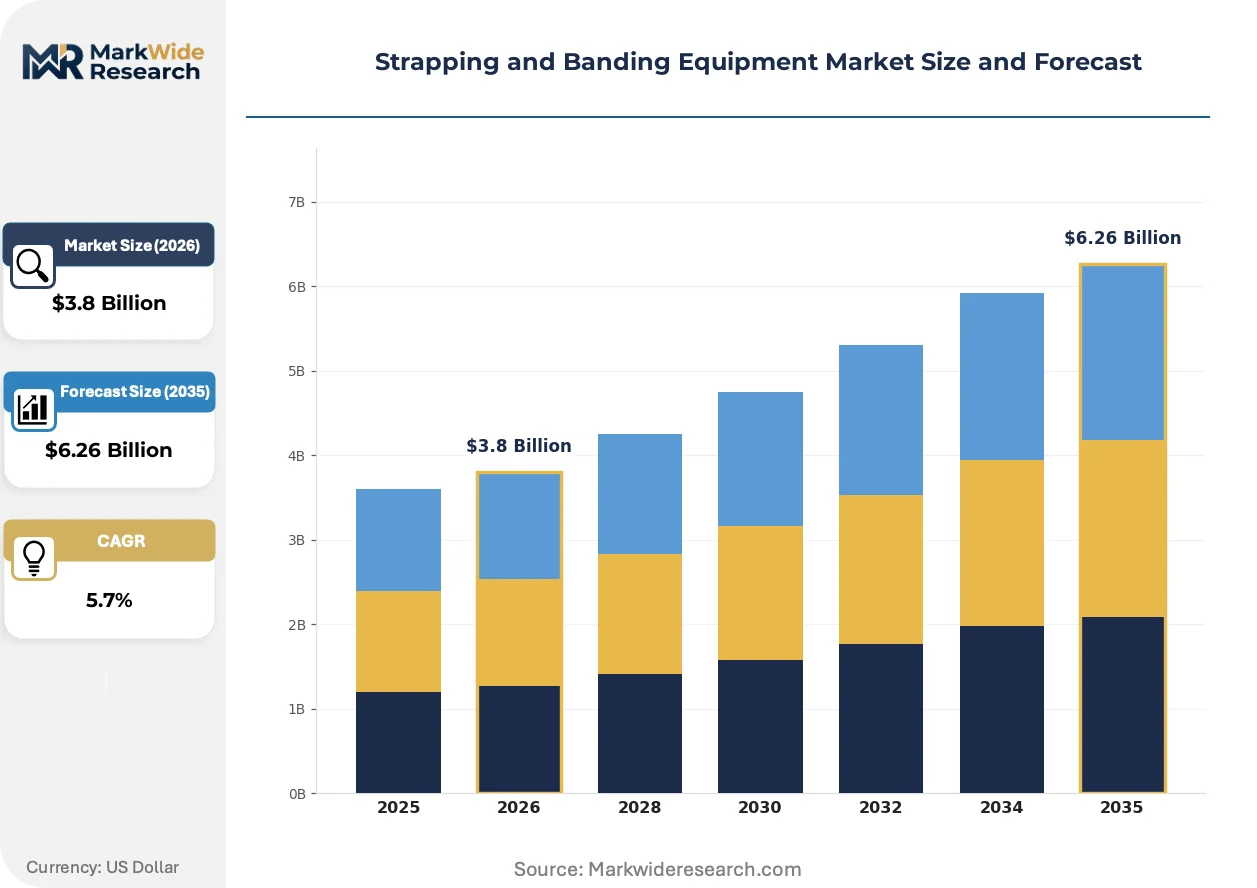
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Tools, Automatic Tools, Semi-Automatic Tools, Accessories Material: Polypropylene, Polyester, Steel, Composite End User: Manufacturing, Retail, Logistics, Construction Application: Packaging, Bundling, Unitizing, Palletizing |
| Companies Covered | Cyklop, Samuel Packaging Systems, Signode Industrial Group, StraPack, Dynaric, Fromm Packaging, Polychem, Teufelberger, Mosca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strapping and Banding Equipment Market Evolving Landscape
Equipment intelligence and material science advances are redrawing competitive boundaries between machinery OEMs and consumables suppliers. The convergence of automation and sustainability mandates is forcing architectural decisions that will determine vendor relevance.
Sensor-integrated strapping heads are decentralizing maintenance scheduling from calendar-based to condition-based protocols. Third-party logistics operators in high-velocity fulfillment centers are adopting vibration-monitoring and tension-feedback systems that predict component failure before throughput interruption. This architecture is compressing service contract structures and shifting vendor revenue toward uptime guarantees.
REACH substance restrictions and EU F-Gas phase-down schedules are accelerating electric-drive adoption in arch strappers previously dependent on pneumatic actuation. Equipment manufacturers are redesigning tensioning mechanisms around servo motors to eliminate compressed air infrastructure. Food and beverage cold chain operators face the steepest compliance timelines as refrigerated facilities retrofit for refrigerant regulations.
Buyer consolidation around integrated service contracts is displacing transactional equipment procurement. Large e-commerce fulfillment networks are unbundling capital expenditure from consumables supply, favoring vendors that guarantee strap availability alongside machine performance. This pattern concentrates procurement leverage in the hands of national account managers at integrated packaging distributors.
Strapping and Banding Equipment Market Segmentation
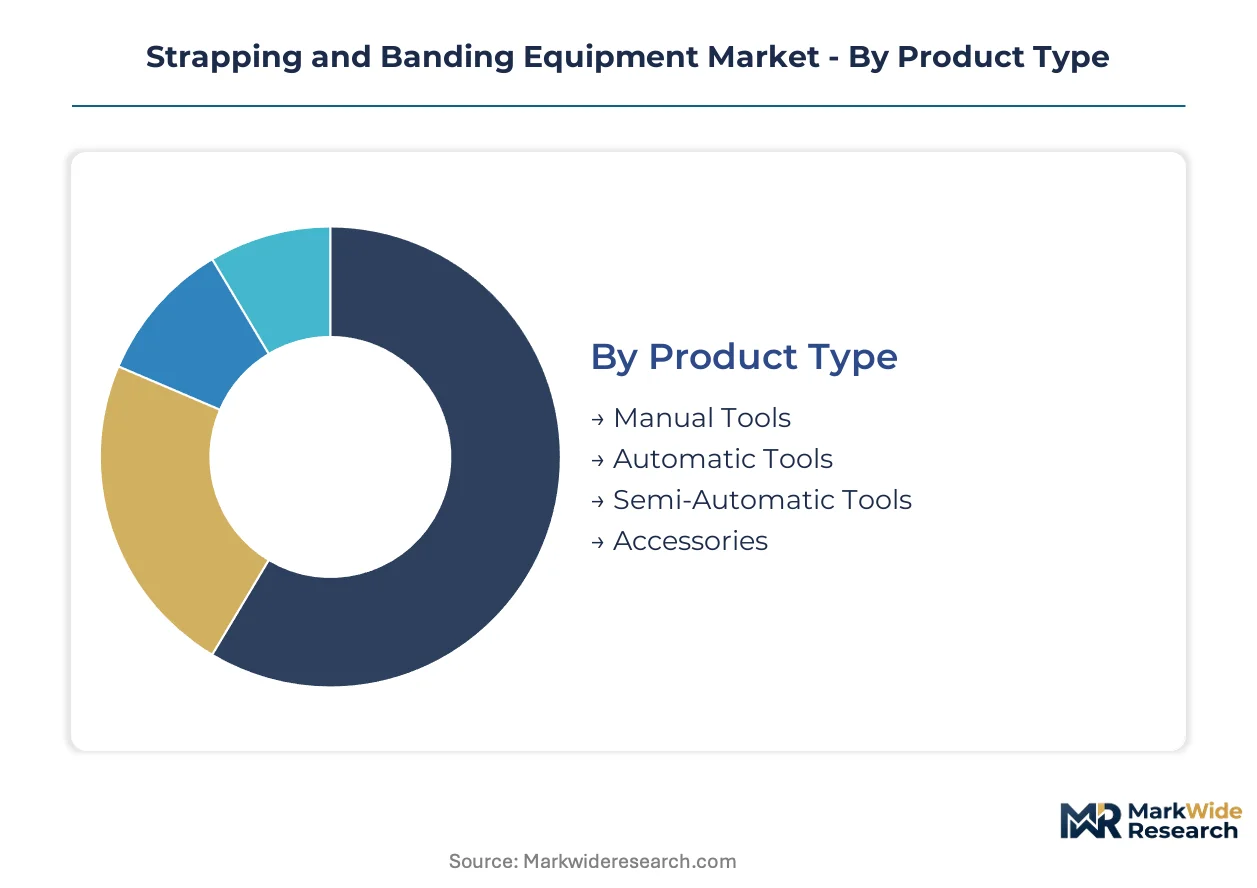
Equipment selection in strapping and banding depends on throughput requirements, load specifications, and labor cost structures. Segment boundaries are blurring as automation penetrates mid-volume operations previously served by manual tools.
Product Type:
Capital intensity varies sharply across this category, with automatic arch systems requiring tenfold higher upfront investment than manual alternatives.
- Automatic Tools:These arch strappers and inline banding systems deploy servo-driven tensioning heads operating at 60+ cycles per minute. Fulfillment centers in Germany's automotive corridor specify these for palletized exports where throughput velocity determines facility economics. CE conformity timelines and pneumatic-to-electric retrofits are extending procurement cycles for EU-bound installations.
- Manual Tools:Hand-held tensioners and sealers dominate low-volume operations where product mix variability resists automation. Small-batch metal fabricators and regional distributors in Bavaria retain these for job-shop flexibility despite climbing labor rates.
- Semi-Automatic Tools:Floor-mounted units requiring operator-fed strap bridge the gap between manual and fully automated systems. Mid-tier 3PL warehouses deploy these for seasonal volume spikes.
- Accessories:Replacement heads, feed wheels, and sealing dies sustain equipment lifecycle economics. OEMs bundle these into service contracts to lock consumables attachment.
Most installed capacity flows through Manual Tools. Expansion is steepest in Automatic Tools.
Material:
Feedstock exposure and resin volatility differentiate margin stability across material tiers.
- Polyester:Heavy-gauge PET strap delivers superior elongation recovery and UV resistance for export-bound palletized loads. Automotive parts suppliers in Baden-Württemberg specify polyester for ocean freight where moisture and temperature cycling threaten load integrity. REACH substance restrictions are accelerating recycled-content formulations.
- Steel:High-tensile metal stranding retains defensive positioning in primary metals and construction where cut resistance overrides weight considerations. German steel mills and building material distributors specify these for abrasive load surfaces.
- Polypropylene:Lightweight resin strap serves high-volume, low-tension applications in consumer goods bundling. Cost sensitivity here exposes margins to petrochemical feedstock swings.
- Composite:Hybrid fiber-reinforced straps merge polymer flexibility with tensile strength approaching steel. Cold chain operators test these for temperature-stable performance in refrigerated distribution.
Polypropylene holds the largest installed base. Polyester is climbing the fastest.
End User:
Procurement authority and service contract structures diverge sharply by customer scale and vertical.
- Manufacturing:OEMs and component suppliers integrate strapping into production line termini with WMS-connected automated systems. German machinery exporters specify precision-tension equipment for just-in-time delivery networks.
- Logistics:Third-party operators prioritize uptime guarantees and national service coverage over capital cost. E-commerce fulfillment centers drive demand for sensor-integrated predictive maintenance architectures.
- Retail:Distribution centers serving store networks balance throughput against SKU proliferation complexity. Semi-automatic tools persist where product dimensions vary unpredictably.
- Construction:Building material suppliers and steel service centers favor steel strapping for structural load security and site durability requirements.
Manufacturing commands the deepest equipment penetration. Logistics shows the steepest expansion trajectory.
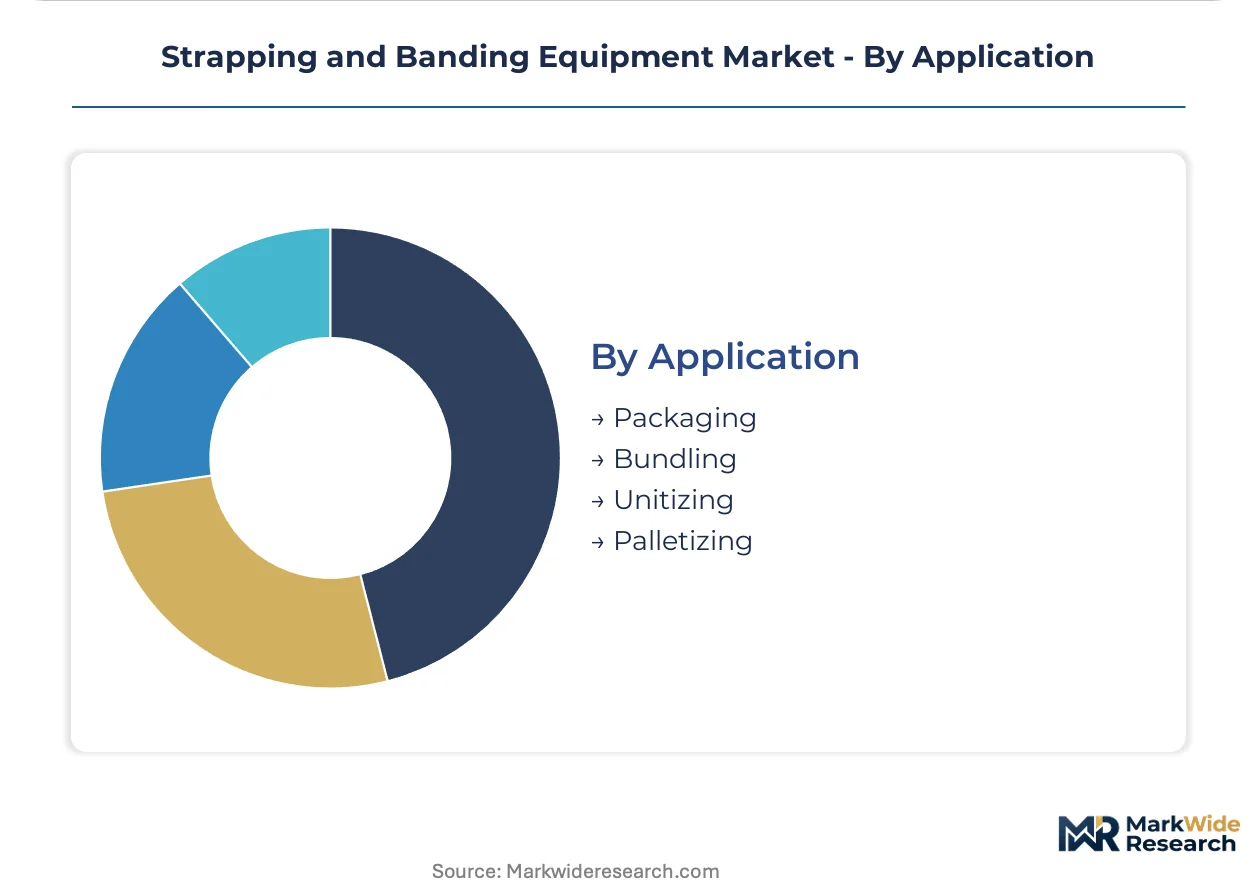
Application:
Functional requirements determine tension specifications, cycle speeds, and integration complexity.
- Palletizing:Unit load securing at 500-2,000 pound banding forces dominates capital deployment. Automated arch strappers here integrate with conveyor systems and robotic layer forming in high-volume fulfillment centers.
- Packaging:Case sealing and carton closing applications operate at lower tension thresholds with higher cycle frequency. Food and beverage cold chain automation is pulling electric-drive adoption for refrigerant compliance.
- Bundling:Multi-unit aggregation of pipes, lumber, or printed materials requires specialized feed mechanisms for irregular dimensions.
- Unitizing:Load consolidation for intermediate handling steps bridges warehousing and transport modes.
Palletizing absorbs the majority of system-level investment. Packaging is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between jurisdictions are redirecting equipment sourcing decisions, with manufacturers migrating assembly toward regions offering streamlined machinery certification pathways while maintaining sales presence in regulated markets.
Germany
Automotive and machinery exporters in Baden-Württemberg and Bavaria drive precision strapping specifications for export-bound palletized loads. CE marking requirements under EU machinery directives enforce extended conformity assessment periods for automated arch systems. Stuttgart's industrial packaging corridor concentrates demand for high-tension electric-drive equipment serving just-in-time delivery networks.
United States
E-commerce fulfillment centers across the Midwest and Southeast prioritize throughput velocity, compressing replacement cycles for automated banding systems. OSHA workplace safety standards govern operator guarding and tensioning mechanism interlocks on domestically sold equipment. Chicago's logistics hub anchors national distribution for integrated packaging distributors bundling equipment with consumables supply.
China
Domestic e-commerce logistics expansion and export manufacturing sustain equipment demand across coastal provinces. GB standards and MIIT machinery regulations shape certification requirements for automated systems entering industrial applications. The Yangtze River Delta manufacturing belt concentrates mid-tier equipment fabrication serving both domestic consumption and Southeast Asian export markets.
Japan
Automotive parts suppliers and precision electronics manufacturers specify high-reliability strapping systems for export logistics. METI industrial standards and JIS certification protocols influence equipment procurement by multinational buyers. The Nagoya industrial corridor in Chubu region anchors demand for sensor-integrated predictive maintenance architectures.
India
Third-party logistics operators and consumer goods distributors adopt semi-automatic tools bridging manual and fully automated systems. BIS machinery safety standards and state-level factory licensing shape equipment import and domestic manufacturing decisions. Maharashtra's Pune-Nashik industrial belt concentrates emerging demand from automotive component suppliers and food processing exporters.
Strapping and Banding Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor-integrated predictive maintenance architectures and electric-drive retrofit packages. The vendor base stratifies between integrated packaging distributors bundling equipment with captive consumables supply, and component specialists focused on replacement heads and sealing mechanisms. Three archetypes dominate: multinational industrial packaging conglomerates with regional service depot networks; mid-cap equipment fabricators with in-house extrusion capabilities; and automation-technology licensors supplying control systems to third-party assemblers. Competitive moves concentrate on national account consolidation and extended producer responsibility service contracts that lock consumables attachment.
Among European-headquartered industrial packaging groups, Cyklop and Mosca exemplify integrated service providers bundling equipment deployment with strap supply agreements. Dynaric represents North American fabricators leveraging in-house extrusion capabilities to stabilize polyester strap margins against resin volatility. Samuel Packaging Systems anchors regional distribution density through service depot networks, while Signode Industrial Group occupies a position at the steel-polymer integration frontier serving primary metals and construction end uses.
| Leading Market Players |
|---|
| Cyklop |
| Samuel Packaging Systems |
| Signode Industrial Group |
| StraPack |
| Dynaric |
| Fromm Packaging |
| Polychem |
| Teufelberger |
| Mosca |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up packaging specialists have consolidated regional service depot networks across North America and Europe, compressing distributor margins while extending captive consumables contracts that lock polyester strap supply to equipment placements. This ownership pattern tightens pricing discipline through bundled national account structures, where procurement leverage concentrates in the hands of integrated packaging distributors.
Pricing Analysis
Distributor margin layers stratify across premium, standard, and economy tiers based on ISO 9001 certification status and after-sales service bundling. CE-marked automatic arch systems command premium positioning against uncertified alternatives in EU-bound sales. Pricing pressure stems from resin cost volatility in polyester feedstocks, squeezing margins for vendors lacking in-house extrusion capabilities. Small-batch metal fabricators exhibit highest price sensitivity, while automotive OEM procurement teams prioritize uptime guarantees over capital cost.
Supply Chain Analysis
CE conformity timelines and OSHA workplace safety certifications gate market entry for automated arch strappers, concentrating qualified supply in Germany, the United States, and Japan. Equipment fabrication draws from servo motor assemblies, precision tensioning heads, and steel stranding feedstock. Single-source vulnerability concentrates in pneumatic-to-electric drive component supply as REACH substance restrictions accelerate retrofit demand. Distribution runs through integrated packaging distributors bundling equipment with captive strap supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strapping and banding equipment has shifted to a late-cycle quality story as e-commerce fulfillment centers prioritize precision-tension specifications and predictive maintenance architectures over lowest-capital-cost procurement.
For Market Incumbents: Deploy captive extrusion capabilities to stabilize polyester strap margins against petrochemical feedstock swings. Consolidate national account relationships around extended producer responsibility service contracts that bundle equipment performance with closed-loop material recovery. Defend against emerging electric-drive retrofit specialists by accelerating servo motor tensioning head development ahead of EU F-Gas phase-down deadlines. For New Entrants and Emerging Players: Mid-tier 3PL warehouses in India's Pune-Nashik industrial belt represent an underserved buyer archetype seeking semi-automatic tools bridging manual and fully automated systems. Target food and beverage cold chain operators facing steep refrigerant compliance timelines with temperature-stable composite strap solutions. Pursue channel partnerships with regional packaging distributors lacking in-house equipment service capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap equipment fabricators with backward integration into strap extrusion but limited geographic service coverage. Long-term viability hinges on consolidation plays that stitch together regional depot networks into national account-capable platforms. Watch for inflection when multinational consumer goods buyers consolidate supplier bases around ISO 9001-certified integrated service providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyester Extrusion | Cyklop and Dynaric stabilize margins against resin volatility through captive strap production. |
| Electric-Drive Retrofit Package Development | Equipment vendors eliminate pneumatic dependencies to meet EU F-Gas refrigerant phase-down mandates. |
| Predictive Maintenance Architecture Deployment | StraPack and Mosca adopt vibration-monitoring systems that shift revenue toward uptime guarantees. |
| Extended Producer Responsibility Service Contract | Signode Industrial Group bundles closed-loop material recovery with equipment performance guarantees. |
| National Account Manager Consolidation | Samuel Packaging Systems anchors procurement leverage through integrated equipment-consumables bundling. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with plant engineers, OEM procurement teams, aftermarket service heads, and distribution channel partners. Secondary validation draws from customs and trade data, SEC 10-K filings, machinery safety directive documentation, and industrial packaging association reports. Bottom-up equipment shipment tallies triangulate against top-down resin consumption estimates and end-use industry capacity expansion announcements.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions model equipment type, material grade, end-use vertical, and regional regulatory cluster. CAGRs derive from equipment replacement cycle compression in e-commerce logistics, polyester penetration rates in automotive export packaging, and electric-drive adoption curves tied to F-Gas compliance timelines. Industry-specific inputs include fulfillment center automation capex disclosures and REACH substance restriction implementation schedules.
Inputs from plant engineers and distribution channel partners were available through the study window; gaps in real-time resin price transmission data introduce uncertainty bands around margin forecasts. Forecasts reflect documented assumptions regarding replacement cycle acceleration and regulatory compliance deadlines. A model refresh is warranted upon material change in EU machinery directive enforcement timelines or extended producer responsibility mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Loose Fill Packaging Systems Market
Packaging Equipment
Loading Spout Market
Packaging Equipment
Blow Molding Tools Market
Packaging Equipment
Stretch Wrappers Market
Packaging Equipment
Filling Equipment Market
Packaging Equipment
Packaging Racks Market
Packaging Equipment
Strapping Devices Market
Packaging Equipment
Plastic Waste Sorting Equipment Market
Packaging Equipment
Auger Filler Market
Packaging Equipment
Global Pack Conveyors Market
Packaging Equipment
Tray Loader Market
Packaging Equipment
Can Seamers Market
Packaging Equipment
Shrink Wrap Equipment Market
Packaging Equipment
Heat Sealing Equipment Market
Packaging Equipment
Sack Tip Stations Market
Packaging Equipment
Diaper Packaging Machines Market