
 Depalletizers Market | 2026-2036
Depalletizers Market Size, Share, and Industry Trends Forecast 2026-2036
Depalletizers Market Outlook
Carbon fiber-reinforced polymers are broadening structural component options for high-speed depalletizer frames, reducing weight while maintaining load ratings. ABB Ltd. leverages its robotics portfolio to anchor positions in integrated packaging lines. KUKA AG competes through servo-pneumatic control systems that improve cycle precision. FANUC Corporation sustains manufacturing scale advantages across its global automation foundries.
Depalletizers are material handling machines engineered to remove individual cases, bottles, or containers from stacked pallets at rates exceeding 60 cycles per minute, employing vacuum heads, mechanical grippers, or electromechanical arms depending on load geometry. Their primary purpose centers on upstream decoupling in distribution centers and production facilities, feeding sortation, inspection, or repackaging stations. Robotic depalletizer configurations command premium positioning due to flexibility in handling mixed-SKU pallets without mechanical changeover. Food and beverage end users represent the most mature installation base, though pharmaceutical-grade stainless steel builds with washdown certification are capturing expanding margin pools.
OSHA machine guarding standards in the United States and the EU Machinery Directive govern interlock systems and collaborative robot speed limits, directly shaping control architecture and sensor integration requirements. ISO 10218 further defines robot safety parameters that manufacturers must embed to achieve CE marking and North American compliance. Stakeholders must weigh electromechanical technology migration against legacy pneumatic infrastructure when planning facility retrofits.
Market Dynamics
Carbon fiber-reinforced polymers are compressing frame weights while preserving load ratings, forcing incumbent steel fabricators to retool or cede high-speed segments to composite specialists. Beverage bottlers now specify cycle rates above 60 per minute as baseline procurement criteria.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for interlock systems and collaborative robot speed limits are accelerating sensor integration investments across European packaging OEMs.
- Pharmaceutical washdown certification:FDA-validated stainless steel builds with IP69K ratings are opening margin pools in aseptic filling operations previously served by general-purpose equipment.
- German packaging cluster density:Concentrated OEM ecosystems around Stuttgart and Munich enable localized sourcing, reducing lead times for electromechanical subassemblies.
Market Restraints
- Pneumatic infrastructure lock-in:Legacy compressed air systems at beverage plants create switching costs that slow electromechanical arm adoption despite superior precision.
- Specialized technician scarcity:Servo-pneumatic control calibration requires skills concentrated in German and Swiss automation engineering programs, constraining deployment velocity elsewhere.
- Steel price volatility:Structural frame material costs fluctuate with scrap metal markets, compressing margins for builders without backward integration into metal forming.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO-mandated serialization requirements are driving demand for washdown-certified depalletizers in sterile injectables packaging.
- Collaborative robot speed limit relaxation:Pending ISO/TS 15066 amendments may permit higher-speed human-robot collaboration, expanding cobot depalletizer addressable markets.
- Retrofit channel development:Third-party integrators are capturing value by upgrading legacy pneumatic cells with electromechanical end-effectors without full line replacement.
Industry Challenges
- Safety certification timeline compression:CE marking and OSHA compliance documentation now require 14-18 months, delaying revenue recognition for new platform launches.
- Mixed-SKU software complexity:Vision-guided robotic systems demand algorithm training across thousands of container geometries, straining OEM application engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Depalletizers Market |
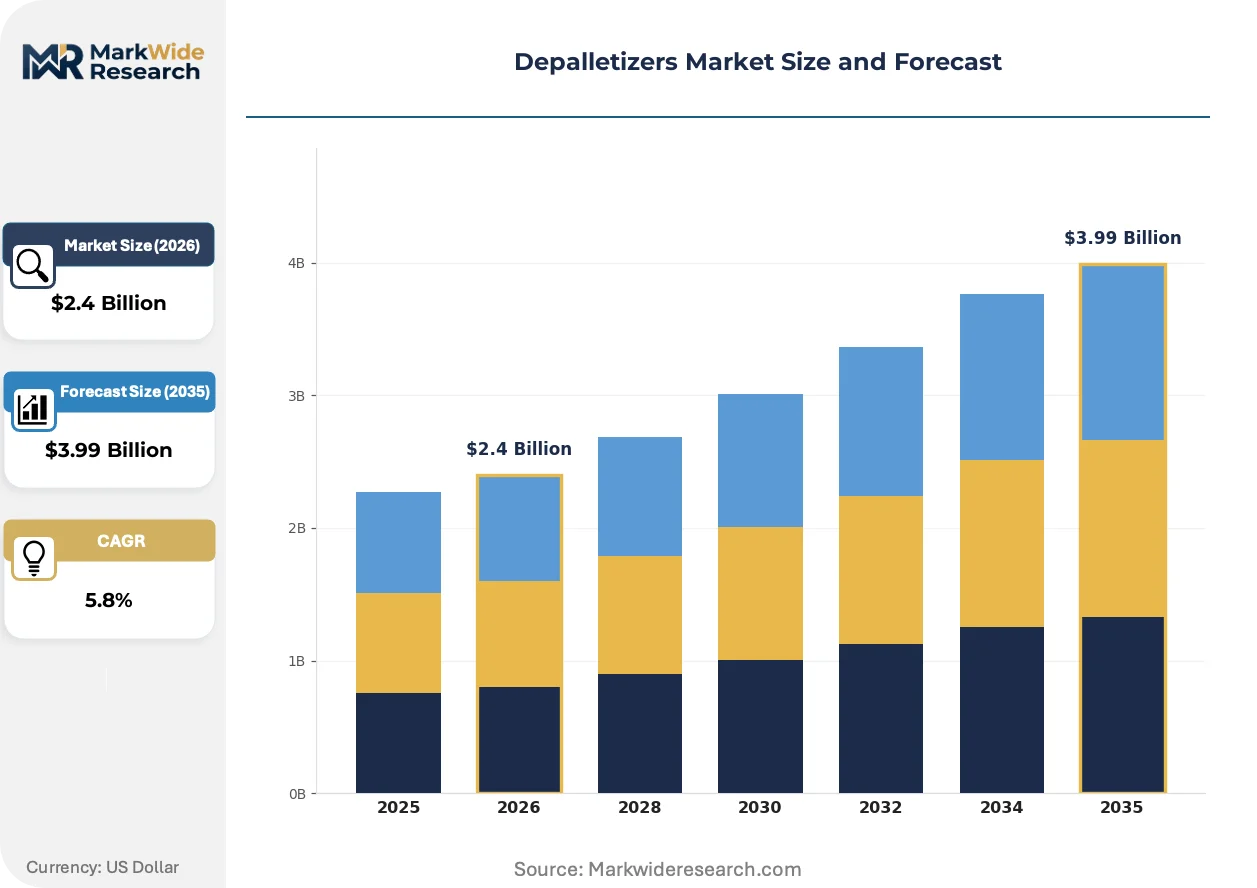
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Robotic End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Logistics Installation: Standalone, Integrated, Mobile, Fixed Technology: Vacuum, Mechanical, Servo-Pneumatic, Electromechanical |
| Companies Covered | ABB Ltd., FANUC Corporation, KUKA AG, Honeywell Intelligrated, Krones AG, BEUMER Group, Yaskawa Electric Corporation, Daifuku Co., Ltd., Fives Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Depalletizers Market Strategic Shifts
Electromechanical actuation architectures are displacing legacy pneumatic systems across high-throughput installations, compressing maintenance intervals while expanding programmable flexibility for mixed-load handling.
Carbon fiber-reinforced polymer frame construction is rewriting structural design paradigms for high-speed depalletizers. Beverage bottlers in Germany and the Netherlands are specifying composite frames for lines above 80 cycles per minute. The technology is rewriting competitive positioning by enabling lighter gantries that reduce servo motor sizing requirements without sacrificing payload capacity.
REACH substance restrictions on lubricants and hydraulic fluids are compelling seal material substitutions in European-built equipment. Manufacturers must reformulate greases to eliminate SVHC-classified compounds or risk market exclusion. Pharmaceutical-grade stainless steel builds face the steepest reformulation costs due to FDA-validated material traceability requirements.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-sized contract packagers. Third-party logistics providers in the Benelux region now prefer per-pallet handling fees with bundled maintenance over asset ownership. Food and beverage co-packers show the fastest adoption velocity, driven by balance sheet optimization priorities and uncertain volume forecasts.
Depalletizers Market Segmentation
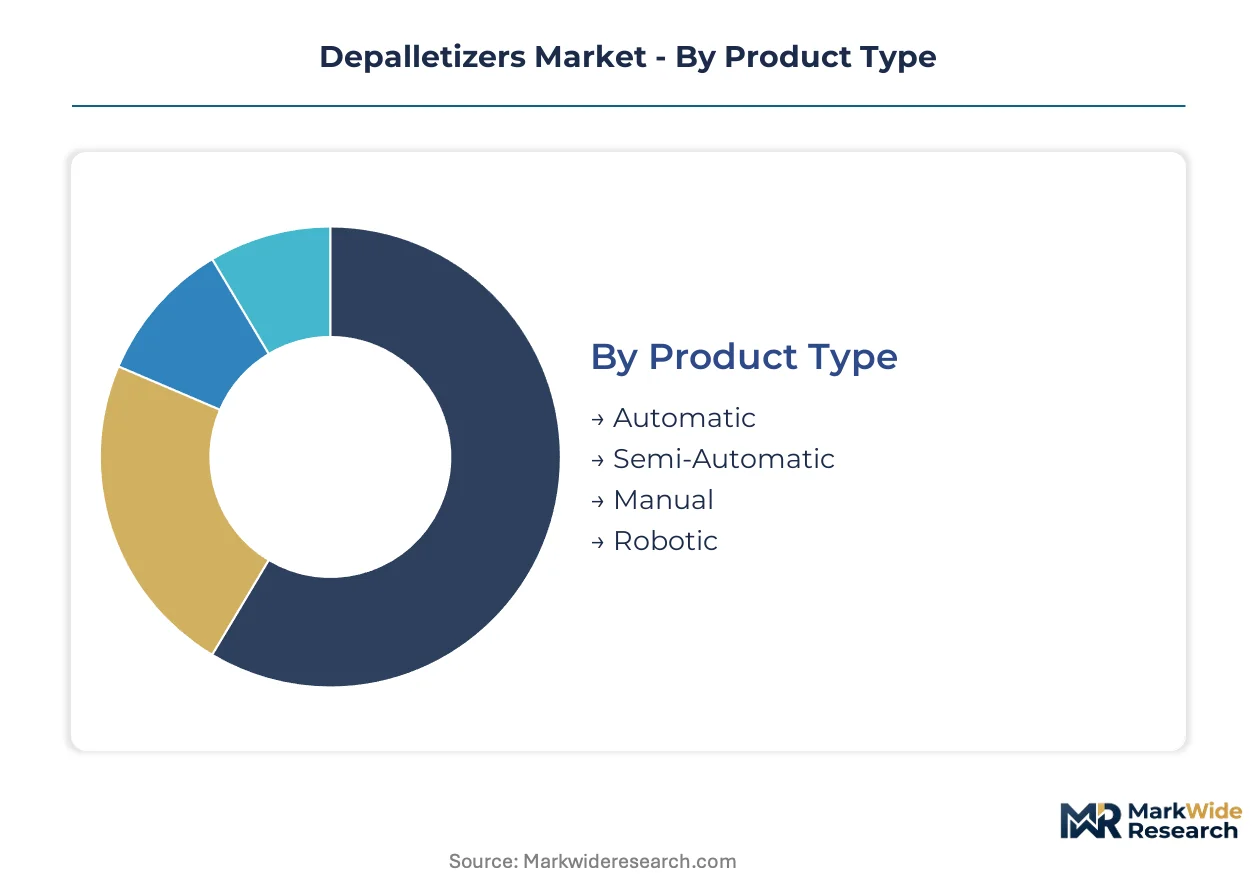
Depalletizer procurement patterns diverge sharply across operational scale and regulatory exposure. Capital deployment intensity varies by installation permanence, end-use compliance burden, and automation sophistication required for throughput targets.
Product Type:
Automatic configurations demand the highest upfront capital outlay, driven by multi-axis servo systems and integrated vision guidance. Robotic variants follow closely, requiring articulated arm platforms with collaborative safety enclosures.
- Automatic:These systems deploy continuous-motion conveyors with programmable logic controllers managing vacuum or mechanical end-effectors at rates exceeding 80 cycles per minute. Beverage bottlers in Germany and the Netherlands specify automatic platforms for lines above 60 pallets per hour, pressured by throughput guarantees in co-packing contracts.
- Robotic:Six-axis articulated arms with force-torque sensors handle mixed-SKU pallets without mechanical changeover. Pharmaceutical manufacturers in Switzerland and Belgium prioritize robotic flexibility for serialized batch runs with frequent format changes.
- Semi-Automatic:Operator-assisted platforms bridge manual feeding with automated discharge, common in mid-sized French dairy operations.
- Manual:Lever-operated or hand-pushed units serve microbreweries and artisanal food producers with volumes below 5 pallets daily.
Most installed capacity flows through Automatic systems. Expansion is steepest in Robotic configurations.
End User:
Regulatory stringency creates tiered margin structures, with aseptic pharmaceutical applications commanding premium pricing over general-purpose food handling.
- Food & Beverage:Carbonated soft drink and brewery applications dominate volume, with washdown-rated stainless steel builds standard. German beverage OEM clusters source locally to compress lead times for high-speed lines.
- Pharmaceuticals:FDA and EMA-validated equipment with full material traceability and isolator integration serves sterile injectables and biologics packaging. Swiss and Irish pharmaceutical manufacturing hubs drive specification intensity for electromechanical systems with IP69K ratings.
- Consumer Goods:Personal care and home product lines balance speed with gentle handling for dented-prone containers.
- Logistics:Third-party distribution centers prioritize mixed-load flexibility over cycle rate, favoring robotic configurations with adaptive gripping.
Food & Beverage holds the largest installed base. Pharmaceuticals is expanding most quickly.
Installation:
Physical permanence dictates foundation requirements and relocation economics, with mobile platforms enabling asset-light operating models.
- Integrated:Hardwired into upstream palletizing and downstream sortation conveyors, these systems require civil engineering coordination and extended commissioning timelines. Benelux contract packagers favor integrated lines for dedicated high-volume programs.
- Standalone:Self-contained units with independent controls allow rapid deployment and future relocation. Italian mid-sized wineries prefer standalone configurations for seasonal production peaks.
- Fixed:Anchored concrete foundations support the heaviest payloads in steel and glass container handling.
- Mobile:Castor-mounted or rail-guided systems enable line reconfiguration without structural modification, gaining traction among UK co-packers with volatile SKU portfolios.
Integrated systems carry the highest average project value. Mobile installations are gaining share fastest among logistics operators.
Technology:
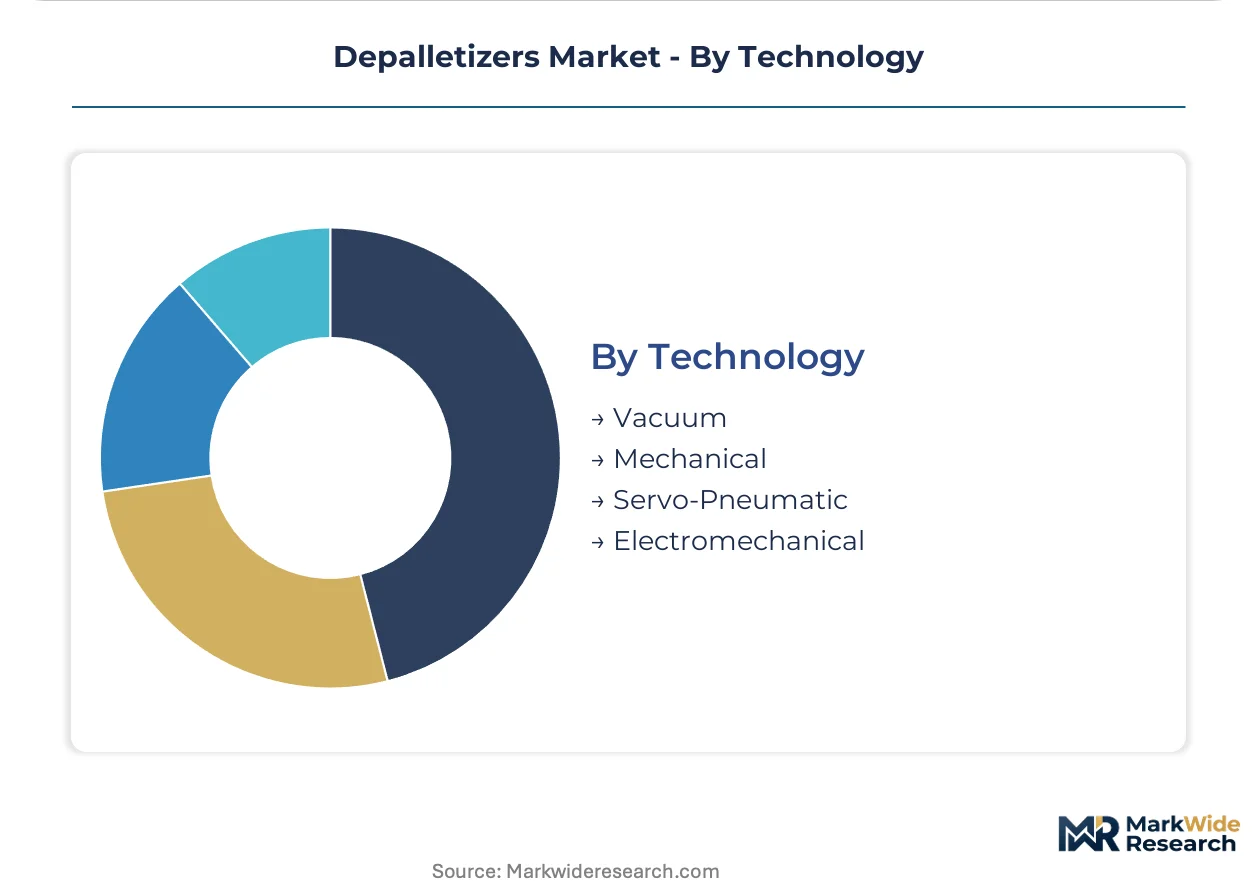
Actuation architecture determines precision, maintenance burden, and compatibility with legacy compressed air infrastructure.
- Electromechanical:Servo motors with ball screw or linear drive transmissions deliver positional accuracy within 0.1 millimeters. German automotive parts suppliers specify electromechanical systems for delicate component handling where pneumatic vibration risks damage.
- Servo-Pneumatic:Hybrid architectures combine pneumatic power with electronic valve control for cost-sensitive precision applications. Austrian packaging machinery OEMs specialize in servo-pneumatic integration for mid-speed beverage lines.
- Vacuum:Suction cup arrays handle uniform case geometries with minimal contact force, prevalent in corrugated container operations.
- Mechanical:Cam-driven grippers and pushers serve low-complexity, high-volume applications with minimal programmable flexibility.
Mechanical technology retains the largest legacy footprint. Electromechanical systems are climbing the fastest as precision requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German packaging machinery clusters around Stuttgart and Munich anchor equipment demand for high-speed beverage lines. Regulatory mandates across multiple jurisdictions are accelerating sensor integration and safety certification investments. Localized sourcing advantages concentrate procurement decisions near OEM ecosystems.
Germany
Beverage bottlers in Bavaria and Baden-Württemberg specify automatic depalletizers exceeding 80 cycles per minute for co-packing contracts. The EU Machinery Directive's CE marking requirements for interlock systems and collaborative robot speed limits compress deployment timelines. Stuttgart's concentrated OEM ecosystem enables same-day sourcing of electromechanical subassemblies.
United States
Pharmaceutical manufacturers in New Jersey and Massachusetts prioritize FDA-validated stainless steel builds with IP69K ratings for sterile injectables. OSHA machine guarding standards govern interlock architecture and sensor placement in robotic installations. Chicago-area distribution centers favor mixed-load robotic configurations for volatile SKU portfolios.
Switzerland
Swissmedic-regulated biologics packaging operations in Basel demand full material traceability and isolator integration. REACH substance restrictions on lubricants compel seal material substitutions in electromechanical actuation systems. The Basel-Land industrial corridor specializes in pharmaceutical-grade equipment with washdown certification.
India
CDSCO-mandated serialization requirements drive sterile injectables packaging investments in Maharashtra and Gujarat. The country's national pharmaceutical regulator enforces track-and-trace standards that necessitate vision-guided robotic handling. Hyderabad's vaccine manufacturing hub sources washdown-certified depalletizers for aseptic filling lines.
Netherlands
Benelux contract packagers prefer equipment-as-a-service contracts with per-pallet handling fees over capital purchases. ECHA-administered REACH compliance shapes lubricant formulations in European-built equipment. Rotterdam's third-party logistics cluster deploys mobile depalletizer configurations for seasonal volume fluctuations.
Depalletizers Market Competitive Environment
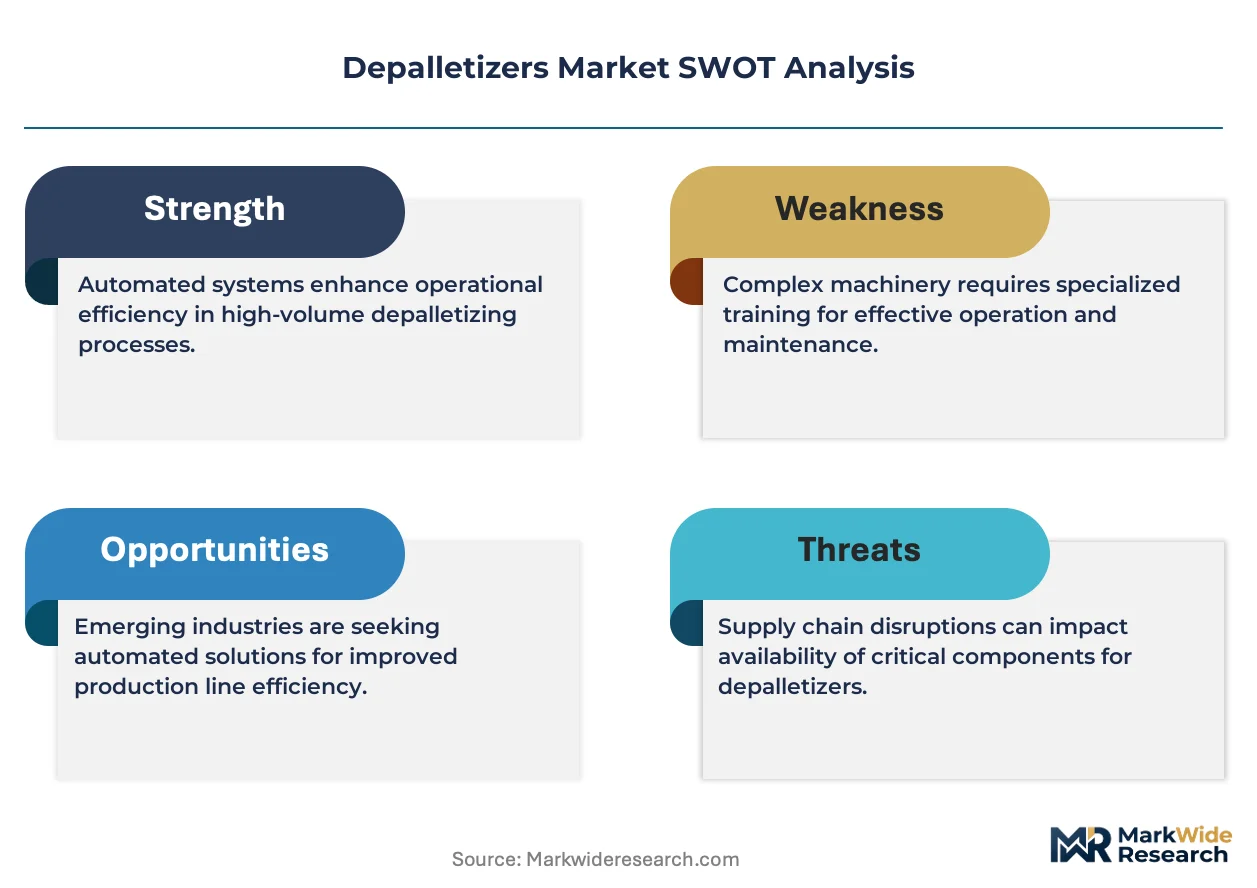
Portfolio diversification dominates the current landscape as incumbent automation suppliers extend into integrated packaging lines. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with robotics portfolios, specialized packaging machinery OEMs with regional density, and material handling integrators with logistics expertise. M&A activity and technology licensing agreements represent the primary competitive vectors as players seek electromechanical capabilities and software competencies.
Among diversified automation conglomerates, ABB Ltd., FANUC Corporation, and KUKA AG exemplify scale-driven positioning. ABB's Swiss-Swedish structure and FANUC's Japanese corporate form represent geographic anchoring strategies. KUKA's German AG structure situates it within the Stuttgart machinery cluster. These entities occupy positions as reference points for integrated line architectures, with their robotics portfolios serving as entry vectors into packaging automation procurement decisions.
| Leading Market Players |
|---|
| ABB Ltd. |
| FANUC Corporation |
| KUKA AG |
| Honeywell Intelligrated |
| Krones AG |
| BEUMER Group |
| Yaskawa Electric Corporation |
| Daifuku Co., Ltd. |
| Fives Group |
| Others |
Value Chain & Pricing Dynamics
Beverage bottlers in Germany and the Netherlands demanding cycle rates above 80 per minute are forcing frame fabricators toward carbon fiber-reinforced polymers, compressing margins for steel-dependent builders while opening premium tiers for composite specialists with backward integration into polymer sourcing.
Pricing Analysis
Input-cost pass-through from carbon fiber and servo motor components is stratifying pricing across three performance tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical builds from general-purpose food-grade systems and entry-level pneumatic units. Cost compression in economy-tier pneumatic depalletizers is intensifying because scrap steel volatility erodes fabricator margins. Contract packagers in the Benelux region show highest price sensitivity, preferring per-pallet service fees over capital deployment, while Swiss pharmaceutical manufacturers accept substantial premiums for IP69K-rated stainless steel with full material traceability.
Supply Chain Analysis
Freight cost escalation for electromechanical subassemblies is amplifying the advantage of Stuttgart and Munich machinery clusters, where same-day component sourcing eliminates air freight dependency. Manufacturing concentrates in Germany, Switzerland, and Austria, with electromechanical actuation systems drawing from Japanese servo motor suppliers and Italian precision gearbox specialists. Single-source vulnerability in force-torque sensor supply creates bottleneck risk for robotic configurations. Distribution runs through OEM-direct channels for integrated lines and third-party integrators for retrofit deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon fiber frame adoption and electromechanical actuation migration are expanding addressable margin pools, with equipment-as-a-service contracting capturing value from balance-sheet-constrained buyers.
For Market Incumbents: Hedge against pneumatic infrastructure lock-in by acquiring servo-pneumatic calibration capabilities concentrated in German and Swiss engineering programs. Deepen backward integration into carbon fiber frame production to defend margin position against composite specialists entering from aerospace supply chains. Prioritize CE marking documentation investments to compress 14-18 month certification timelines. For New Entrants and Emerging Players: The price-point gap between pharmaceutical-grade IP69K builds and general-purpose food-grade systems creates white-space opportunity in mid-tier washdown-certified equipment for dairy and brewery applications. Target Italian and Spanish mid-sized wineries with standalone mobile configurations for seasonal production peaks. Pursue third-party logistics partnerships in Rotterdam and Antwerp with retrofit-focused electromechanical end-effector upgrades. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized packaging machinery OEMs possessing regional density around Stuttgart and Munich combined with software competencies for mixed-SKU vision guidance. Long-term viability hinges on electromechanical technology migration completion and collaborative robot speed limit relaxation under pending ISO/TS 15066 amendments. Watch for CDSCO serialization mandate enforcement in Maharashtra and Gujarat as inflection indicator for Indian pharmaceutical equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Frame Integration | Reduces servo motor sizing requirements for lines exceeding 80 cycles per minute. |
| Servo-Pneumatic Capability Acquisition | Captures precision calibration skills concentrated in German automation engineering programs. |
| Equipment-as-a-Service Launch | Aligns with Benelux contract packager preference for per-pallet handling fees over ownership. |
| IP69K Certification Investment | Opens FDA-validated margin pools in Swiss and Irish sterile injectables packaging. |
| Retrofit Channel Partnership | Enables value capture from legacy pneumatic cell upgrades without full line replacement. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from packaging machinery OEM procurement directors, beverage plant maintenance engineers, pharmaceutical manufacturing heads, and third-party logistics operators in Rotterdam and Antwerp. Secondary validation drew from EU Machinery Directive compliance filings, ECHA REACH substance restriction updates, FDA equipment validation guidelines, and customs trade data for electromechanical component flows. Bottom-up installation tracking across German beverage bottlers and Swiss pharmaceutical manufacturers triangulated against top-down market sizing from automation supplier revenue disclosures.
Segment-weighting applied product type, end user regulatory tier, installation permanence, and actuation technology as core dimensions across the projection horizon. Automatic, robotic, semi-automatic, and manual configurations each carried distinct cycle rate and capital intensity assumptions. Food and beverage, pharmaceutical, consumer goods, and logistics end uses were modeled with divergent compliance burden and washdown certification requirements. CAGRs derived from historical installation velocity in German packaging clusters and projected electromechanical substitution rates against legacy pneumatic infrastructure.
The model assumes a particular technology adoption path; alternative pathways for electromechanical actuation would alter the outlook if pneumatic infrastructure lock-in persists longer than modeled. Forecasts reflect assumptions about ISO/TS 15066 amendment timing and REACH substance restriction enforcement that could compress or extend certification timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Beverage Packaging Equipment Market
Packaging Equipment
PET Preform Machine Market
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Shrink Wrapper Market
Packaging Equipment
Hydrapulper Market
Packaging Equipment
France Foam Pumps Market
Packaging Equipment
Hand Sealers Market
Packaging Equipment
Dispensing Sprayers Market
Packaging Equipment
Inflatable Void Fill System Market
Packaging Equipment
Rotary Band Heat Sealer Market
Packaging Equipment
Rotary Tray Sealers Market
Packaging Equipment
Auger Filler Market
Packaging Equipment
Die-Cutter Market
Packaging Equipment
Laser Coding Equipment Market
Packaging Equipment
Airless Pumps Market
Packaging Equipment
Hang Tag Applicators Market