
 Packaging Automation Market | 2026-2036
Packaging Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Automation Market Intelligence
Pharmaceutical packaging is recalibrating the end-use mix as serialization mandates tighten traceability requirements across supply chains. Siemens AG anchors European demand through its PLC control ecosystems integrated with servo motor arrays. Rockwell Automation leverages its FactoryTalk platform to dominate North American pharmaceutical line retrofits. ABB Ltd. competes in Asia-Pacific through compact robotic arms designed for cleanroom-compliant vial handling.
Packaging automation encompasses electromechanical systems that execute filling, sealing, labeling, and palletizing operations with cycle precision measured in milliseconds and repeatability tolerances below 0.1 millimeter. These systems eliminate manual intervention in high-throughput environments where contamination control and lot tracking are mandatory. Robotic arms command the largest installed base among product types, though palletizing robots capture expanding share in e-commerce fulfillment. Machine vision technology leads growth within the technology dimension as defect detection thresholds tighten across food and pharmaceutical applications. Contract manufacturers represent the fastest-growing end user category as brands outsource capital-intensive line upgrades to specialized operators.
FDA Title 21 CFR Part 11 and EU MDR frame validation protocols for pharmaceutical packaging lines, while EPA emissions standards constrain pneumatic system designs in US manufacturing plants. The EU Green Deal's packaging waste reduction targets are forcing retrofit cycles across European food processing facilities. Stakeholders must weigh total cost of ownership against regulatory compliance horizons when selecting between pneumatic and servo-electric actuation architectures.
Market Dynamics
Machine vision systems are compressing defect detection thresholds below 0.1 millimeter across food and pharmaceutical lines, forcing incumbent vendors to recalibrate servo-electric architectures or cede share to AI-native entrants.
Growth Catalysts
- EU Green Deal packaging waste directives:German food processors are accelerating robotic palletizing retrofits to meet 2030 reduction targets. This mandates line-level automation upgrades across dairy and meatpacking facilities.
- Serialization mandates:FDA Title 21 CFR Part 11 and EU MDR are tightening traceability requirements for pharmaceutical packaging. Contract manufacturers must deploy track-and-trace systems to maintain commercial access.
- Yangtze River Delta concentration:China's contract manufacturers are retrofitting aging lines with AI-guided inspection systems to serve export pharmaceutical demand. Regional clusters drive equipment refresh cycles.
Market Restraints
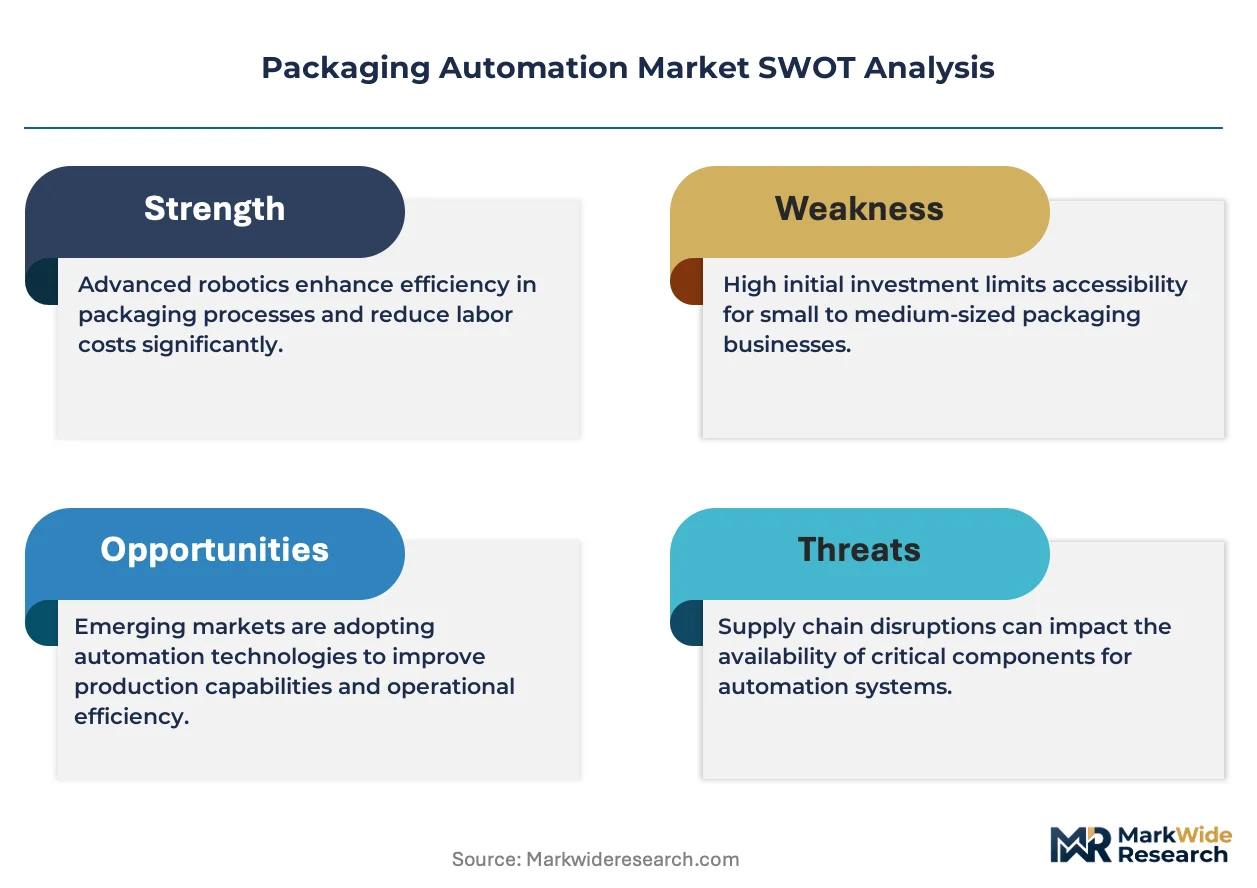
- Semiconductor supply concentration:Servo motor controllers depend on specialized chipsets from concentrated East Asian foundries. Lead times for motion control components extend equipment delivery windows.
- Pneumatic-to-electric transition costs:EPA emissions standards constrain compressed air system designs in US plants. Retrofitting pneumatic actuators to servo-electric architectures demands full line revalidation.
- Cleanroom compliance complexity:ISO 14644-1 particulate standards for pharmaceutical robotics require stainless steel construction and sealed bearing assemblies. Material specifications inflate unit costs versus standard industrial variants.
Strategic Opportunities
- Secondary packaging automation:E-commerce fulfillment centers in the US and Germany are deploying compact palletizing cells for mixed-SKU cartons. This application remains underpenetrated versus primary packaging.
- AI-actuation convergence:Machine vision platforms are integrating with predictive maintenance algorithms to reduce unplanned downtime. Early deployments in Japanese pharmaceutical lines demonstrate 15-20% throughput gains.
- India PLI scheme tailwinds:Production-linked incentives for domestic pharmaceutical manufacturing are driving greenfield automation investments. Contract packagers qualify for capital expenditure subsidies.
Industry Challenges
- Mechatronics skill scarcity:Servo tuning and vision system calibration require cross-trained technicians. German and US manufacturers report 6-9 month hiring timelines for qualified field service engineers.
- Legacy PLC integration friction:Brownfield pharmaceutical lines run on proprietary Siemens or Rockwell control ecosystems. Third-party robotics vendors face protocol translation barriers and extended commissioning cycles.
- Validation documentation burdens:FDA and EMA require Installation Qualification, Operational Qualification, and Performance Qualification protocols for each line modification. Documentation timelines extend project delivery by 4-8 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Automation Market |
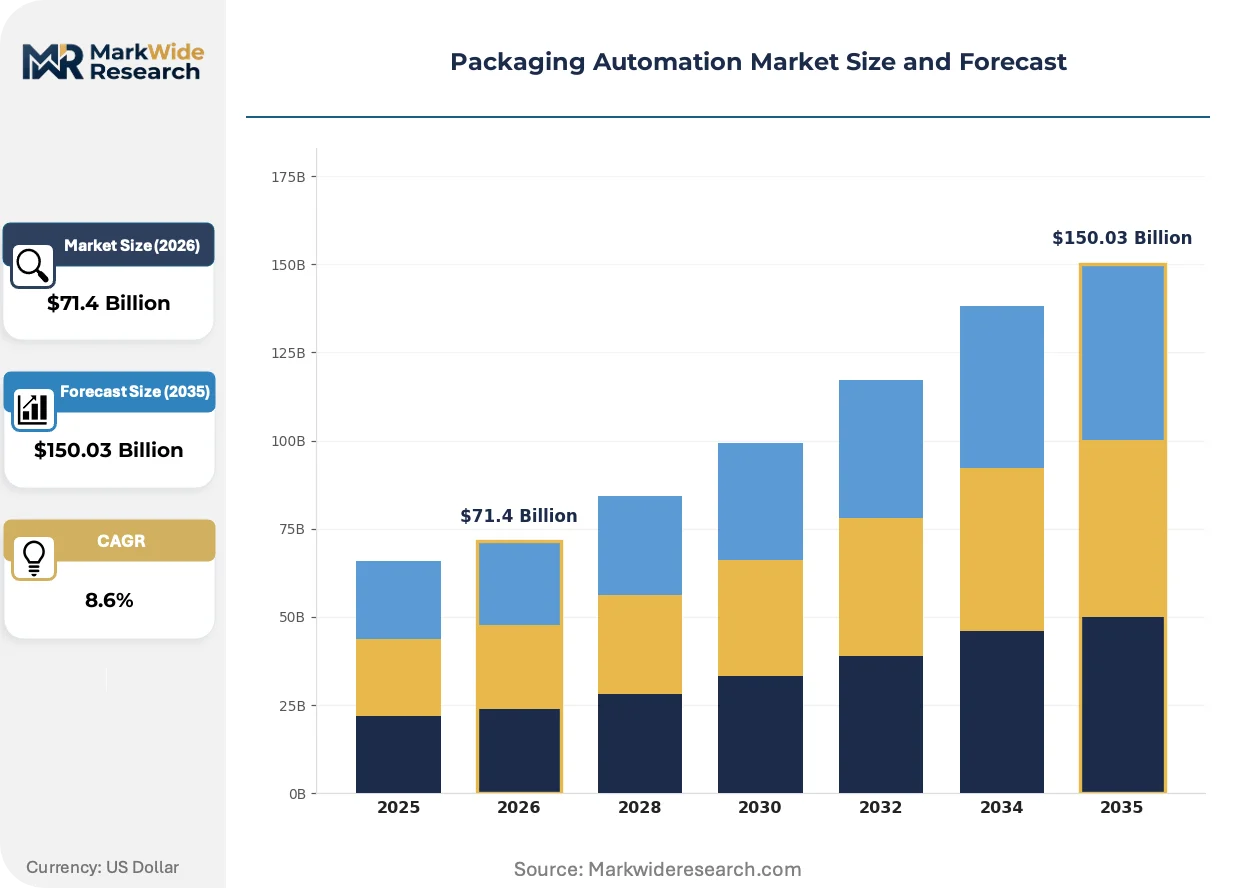
| Market Size in 2026 | $71.4 Billion |
| Market Size in 2035 | $150.03 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Arms, Conveyor Systems, Labeling Machines, Wrapping Equipment, Palletizing Robots Technology: Machine Vision, PLC Control, Servo Motors, Pneumatic Systems, Artificial Intelligence, Human-Machine Interface Application: Food Processing, Pharmaceutical Packaging, Electronics Assembly, Personal Care, Household Chemicals End User: Manufacturing Plants, Distribution Centers, Packaging Services, Contract Manufacturers |
| Companies Covered | Rockwell Automation, Mitsubishi Electric Corporation, Siemens AG, ABB Ltd., BEUMER Group GmbH & Co., Schneider Electric SE, Emerson Electric Co., Swisslog Holding AG, Tetra Pak International S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Automation Market Strategic Shifts & Innovations
Packaging automation is pivoting from fixed-speed mechanical systems to adaptive, software-defined architectures that reconfigure in real-time for batch size and format changes.
Collaborative robotic arms with force-torque sensing are integrating into cleanroom pharmaceutical lines for vial handling and secondary packaging tasks. Mid-sized contract manufacturers in Switzerland and Germany are adopting these systems to reduce changeover downtime between product runs. The technology is integrating vision-guided pick-and-place with automated tool changers, collapsing the economic viability threshold for lot sizes below 10,000 units.
EU MDR serialization requirements are mandating aggregation of unit-level codes into case and pallet hierarchies. Pharmaceutical packagers must deploy camera-based verification stations at every packaging hierarchy level. European lines are responding by embedding machine vision directly into cartoning and case-packing stations rather than bolting on standalone inspection units.
Equipment-as-a-service contracting is displacing outright purchase for mid-capacity food processors. German dairy cooperatives and US craft beverage producers are leasing palletizing cells with bundled maintenance and software updates. This model concentrates most visibly in regions with high capital cost sensitivity and volatile production volumes, including Nordic food processing and North American specialty coffee roasting.
Packaging Automation Market Segmentation
Packaging automation purchasing decisions hinge on capital intensity thresholds, regulatory compliance burdens, and throughput requirements that vary sharply across product configurations and end-use environments. Equipment specification determines total cost of ownership trajectories and retrofit feasibility for brownfield facilities.
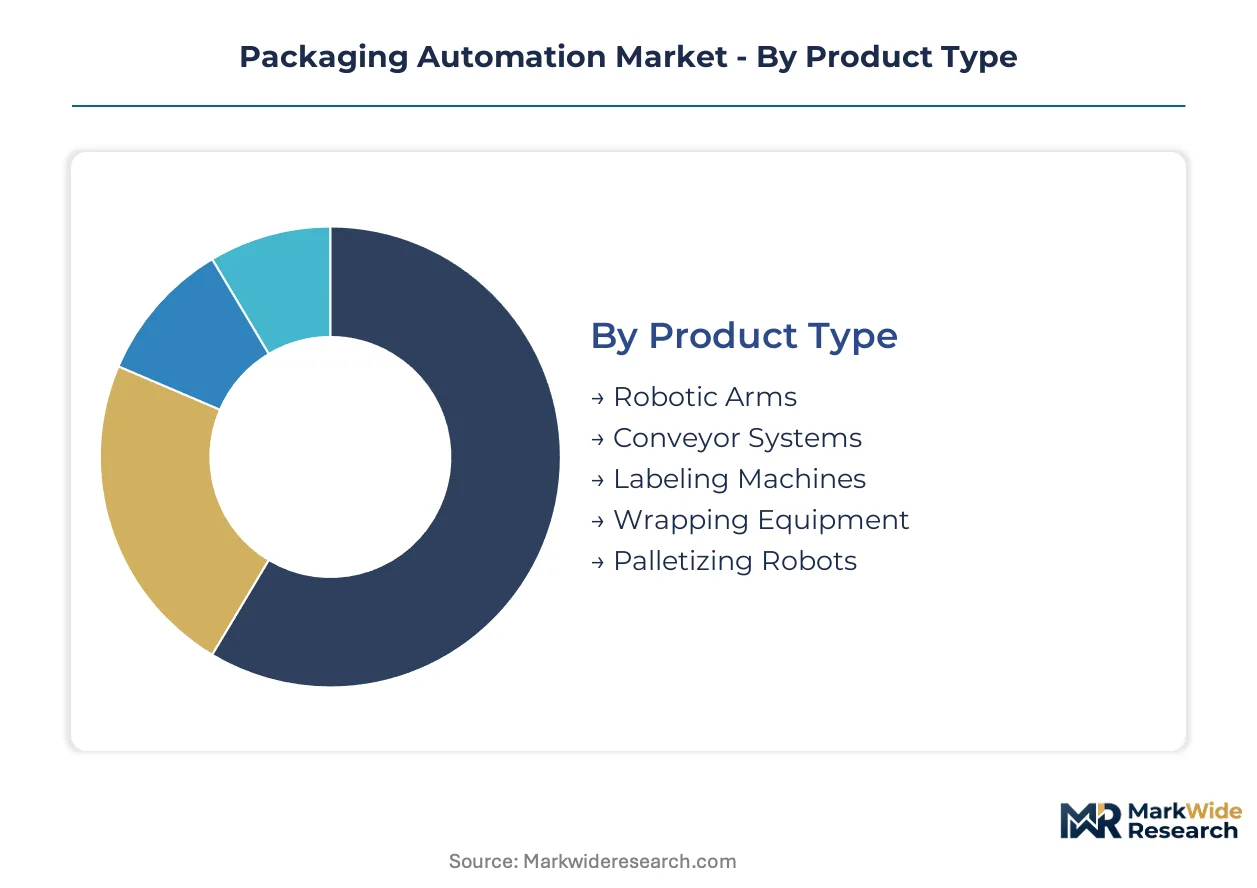
Product Type:
Capital intensity escalates sharply with degrees of freedom and precision requirements, with multi-axis robotic systems commanding multiples of fixed-path mechanical alternatives.
- Robotic Arms:Six-axis articulated systems execute pick-and-place operations with sub-millimeter repeatability for vial handling in pharmaceutical cleanrooms. German dairy processors deploy these for cheese portioning to meet EU Green Deal waste reduction targets while maintaining throughput.
- Palletizing Robots:Cartesian and articulated configurations stack mixed-SKU cartons in e-commerce fulfillment centers. Yangtze River Delta contract manufacturers are retrofitting aging lines with compact cells to serve export pharmaceutical demand from regional clusters.
- Conveyor Systems:Belt and roller configurations form the backbone of line integration, with servo-driven accumulation zones enabling format flexibility.
- Labeling Machines:Pressure-sensitive and sleeve applicators handle serialization mandates at line speeds exceeding 400 units per minute.
- Wrapping Equipment:Stretch and shrink systems secure pallet loads for distribution, with film tension control reducing material consumption.
Most installed capacity flows through Conveyor Systems. Expansion is steepest in Palletizing Robots.
Technology:
Technology selection determines reconfiguration speed, energy consumption, and compliance documentation burden for validation protocols.
- Machine Vision:Camera arrays with AI-guided defect detection compress inspection thresholds below 0.1 millimeter across food and pharmaceutical applications. Japanese pharmaceutical lines integrating predictive maintenance algorithms report throughput gains from reduced unplanned downtime.
- Servo Motors:Brushless permanent magnet motors with encoder feedback enable precise motion profiles for format changeovers. Lead times for specialized motion control chipsets from East Asian foundries currently extend equipment delivery windows.
- PLC Control:Programmable logic controllers from Siemens and Rockwell ecosystems anchor European and North American line architectures respectively.
- Pneumatic Systems:Compressed air actuators face EPA emissions constraints in US manufacturing plants, forcing transition cost calculations.
- Artificial Intelligence:Predictive algorithms optimize maintenance scheduling and quality threshold calibration in high-mix environments.
- Human-Machine Interface:Touchscreen panels with recipe management reduce changeover time for mid-sized contract manufacturers.
Technology deployment concentrates in PLC Control ecosystems. Machine Vision is climbing the fastest as inspection mandates tighten.
Application:
Application context dictates cleanroom classification, traceability depth, and changeover frequency requirements that shape equipment specification.
- Pharmaceutical Packaging:Vial filling, cartoning, and aggregation stations must comply with FDA Title 21 CFR Part 11 and EU MDR serialization mandates. Track-and-trace system deployment is mandatory for contract manufacturers to maintain commercial access.
- Food Processing:Dairy and meatpacking facilities across Germany are accelerating robotic retrofits to meet EU Green Deal packaging waste reduction targets.
- Electronics Assembly:ESD-controlled environments handle sensitive components with vision-guided placement accuracy.
- Personal Care:High-speed tube filling and cartoning lines serve volatile SKU proliferation in cosmetics.
- Household Chemicals:Corrosion-resistant construction and containment features address aggressive formulations.
Food Processing holds the largest installed base. Pharmaceutical Packaging is gaining share fastest on regulatory compulsion.
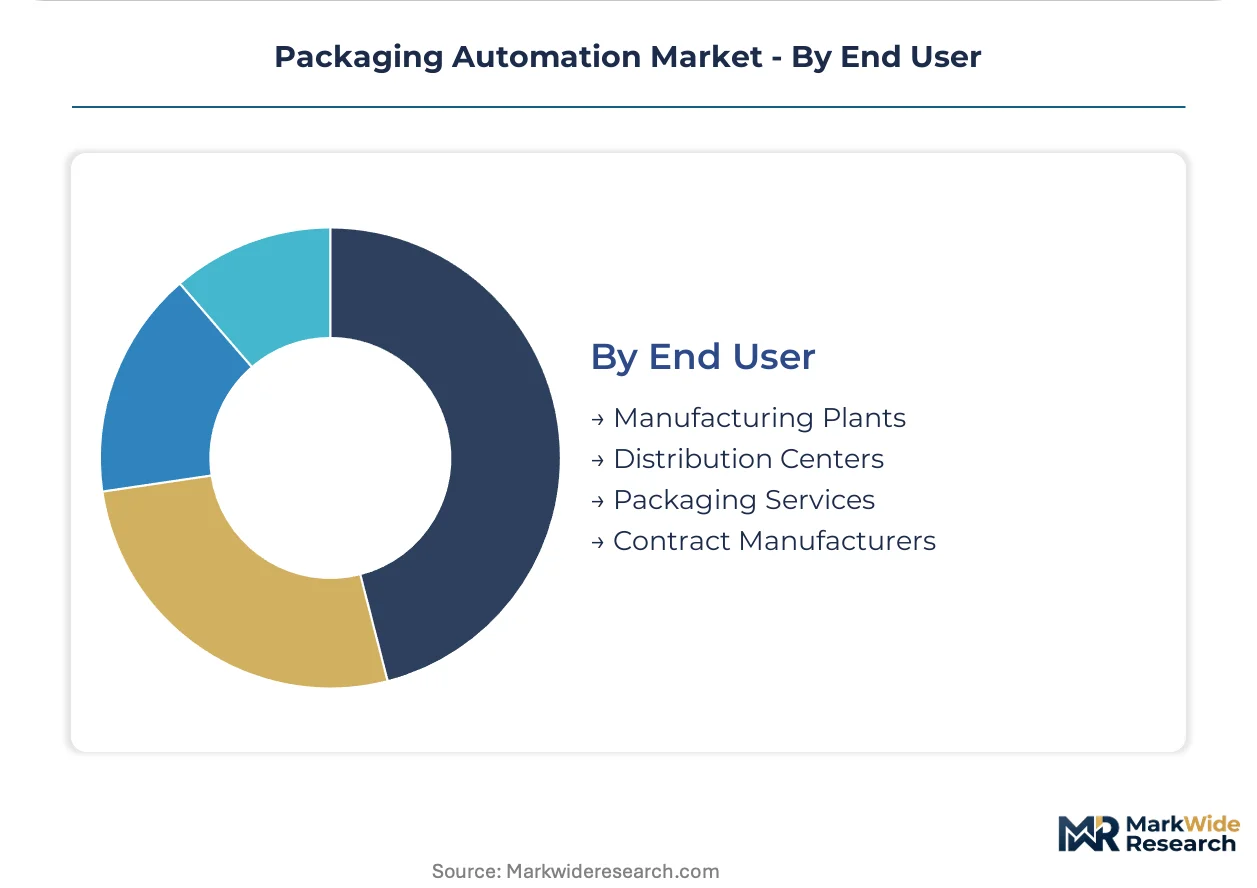
End User:
End user category determines capital access, technical staffing depth, and outsourcing propensity that shape procurement modality.
- Contract Manufacturers:Third-party packagers qualify for India's PLI scheme capital expenditure subsidies while absorbing validation documentation burdens for pharmaceutical clients. Equipment-as-a-service contracting is displacing outright purchase among mid-capacity operators with volatile production volumes.
- Manufacturing Plants:Captive packaging lines at brand owners face 6-9 month hiring timelines for mechatronics technicians capable of servo tuning and vision calibration.
- Distribution Centers:E-commerce fulfillment operations deploy compact palletizing cells for mixed-SKU carton handling.
- Packaging Services:Specialized operators bundle line upgrades with maintenance and software update subscriptions.
Manufacturing Plants account for the dominant share of installed equipment. Contract Manufacturers are expanding most quickly as brands outsource capital-intensive upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration toward jurisdictions with harmonized compliance standards is compressing cost-of-compliance gaps between mature and emerging manufacturing bases. Contract manufacturers in lower-cost clusters are absorbing validation documentation burdens to capture pharmaceutical outsourcing flows from Western markets.
Germany
Dairy and meatpacking facilities are accelerating robotic palletizing retrofits to meet EU Green Deal packaging waste reduction targets by 2030. The country's Federal Ministry for the Environment enforces strict emissions standards that constrain pneumatic system designs in food processing plants. Industrial automation clusters in Bavaria and Baden-Württemberg host concentrated servo motor and PLC control system production.
United States
Pharmaceutical contract manufacturers face FDA Title 21 CFR Part 11 validation protocols that extend equipment commissioning timelines by 4-8 months. The EPA constrains compressed air system emissions in manufacturing plants, forcing cost calculations for pneumatic-to-electric actuator transitions. E-commerce fulfillment centers in the Midwest and Southeast are deploying compact palletizing cells for mixed-SKU carton handling.
China
Contract manufacturers in the Yangtze River Delta are retrofitting aging lines with AI-guided machine vision systems to serve export pharmaceutical demand. The National Medical Products Administration enforces serialization mandates that align with EU MDR traceability requirements. Regional clusters around Shanghai and Suzhou drive concentrated equipment refresh cycles for track-and-trace system deployment.
India
Domestic pharmaceutical packagers qualify for Production-Linked Incentive scheme capital expenditure subsidies that offset greenfield automation investments. The Central Drugs Standard Control Organization mandates traceability systems for contract manufacturers seeking export commercial access. Maharashtra and Gujarat host expanding contract packaging capacity with bundled validation documentation services.
Switzerland
Mid-sized contract manufacturers are adopting collaborative robotic arms with force-torque sensing to reduce changeover downtime between pharmaceutical product runs. Swissmedic enforces cleanroom compliance standards that require stainless steel construction and sealed bearing assemblies. Industrial zones around Basel and Zurich concentrate precision automation system integration for vial handling applications.
Packaging Automation Market Key Industry Players
Technology licensing dominates the current landscape as established control ecosystem vendors open proprietary protocols to third-party robotics suppliers. The vendor base fragments across three tiers: integrated automation conglomerates with captive PLC platforms, specialized robotic arm fabricators, and emerging AI-native vision system entrants. Two strategic archetypes have crystallized: full-stack system integrators bundling hardware, software, and validation services; and component specialists supplying servo motors, machine vision cameras, or collaborative arms to downstream integrators. M&A activity and geographic expansion represent the dominant competitive moves as mid-cap players seek scale to absorb rising compliance documentation costs.
Among German-based industrial conglomerates, Siemens AG and BEUMER Group GmbH & Co. exemplify the full-stack integration archetype, anchoring European demand through embedded control ecosystems. ABB Ltd. occupies a position spanning both industrial robotics and motion control, representing the cross-border specialist model with concentrated Asia-Pacific presence. Rockwell Automation sits within the North American premium tier, leveraging established pharmaceutical industry relationships to dominate line retrofit cycles.
| Leading Market Players |
|---|
| Rockwell Automation |
| Mitsubishi Electric Corporation |
| Siemens AG |
| ABB Ltd. |
| BEUMER Group GmbH & Co. |
| Schneider Electric SE |
| Emerson Electric Co. |
| Swisslog Holding AG |
| Tetra Pak International S.A. |
| Others |
Cost & Logistics Intelligence
EU Green Deal packaging waste reduction mandates are forcing German food processors and pharmaceutical contract manufacturers to specify servo-electric actuation architectures over legacy pneumatic systems, compelling suppliers to absorb stainless steel construction costs and extend validation documentation services to maintain contract eligibility.
Pricing Analysis
Distributor margins for packaging automation equipment compress as direct OEM relationships expand, particularly for high-volume contract manufacturers in China's Yangtze River Delta. Three-tier pricing structure across premium cleanroom-compliant systems, standard industrial variants, and economy palletizing cells reflects ISO 14644-1 certification levels and after-sales bundling intensity. Cost compression in economy-tier conveyor systems intensifies due to commodity stainless steel price volatility and compressed air-to-electric retrofit demand. Contract manufacturers exhibit highest price sensitivity, while pharmaceutical brand owners prioritize validation throughput over unit economics.
Supply Chain Analysis
Mechatronics technician scarcity in Germany and the United States extends commissioning timelines and inflates field service premiums for servo tuning and vision calibration. Component fabrication concentrates in China, Germany, and Japan, with specialized motion control chipsets drawing from concentrated East Asian foundry capacity. Supply chain vulnerability centers on semiconductor lead time volatility for encoder feedback systems and sealed bearing assemblies. Distribution runs through system integrators bundling hardware, software, and FDA/EU MDR validation protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Packaging automation has transitioned into a late-cycle quality story as EU MDR serialization mandates and FDA Title 21 CFR Part 11 validation requirements elevate specification premiums above raw throughput metrics.
For Market Incumbents: Anchor control ecosystem dominance through backward integration into servo motor arrays and predictive maintenance software stacks. Siemens and Rockwell should extend proprietary PLC protocol licensing to third-party robotics vendors to capture retrofit cycles, while absorbing validation documentation costs to defend against AI-native vision system entrants eroding defect detection margins. For New Entrants and Emerging Players: Begin with secondary packaging automation for e-commerce fulfillment centers in the US Midwest and Germany, where mixed-SKU palletizing cells remain underpenetrated versus primary packaging lines. Target equipment-as-a-service contracting models for mid-capacity food processors with volatile production volumes, leveraging bundled maintenance subscriptions to bypass capital expenditure approval barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native machine vision specialists possessing predictive maintenance algorithms already deployed in Japanese pharmaceutical lines. Five-to-ten year viability favors component specialists with cleanroom-compliant hardware certifications and embedded software stacks over pure-play mechanical fabricators. Watch for inflection when EU Green Deal enforcement timelines accelerate German dairy and meatpacking retrofit procurement waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motors | Captive supply of motion control components reduces lead time exposure to East Asian foundry concentration. |
| AI-Vision Platform Integration | Predictive maintenance algorithms embedded in Japanese pharmaceutical lines demonstrate measurable throughput recovery. |
| Equipment-as-a-Service Launch | Subscription bundling penetrates capital-constrained German dairy cooperatives and US craft beverage producers. |
| Cleanroom Certification Investment | ISO 14644-1 compliance unlocks pharmaceutical vial handling contracts with Swissmedic-regulated manufacturers. |
| Regional System Integrator Acquisition | Local validation documentation expertise compresses FDA and EMA commissioning timelines for brownfield retrofits. |
Research Approach
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, regulatory filing analysis, and customs trade data — were reconciled against secondary validation from SEC disclosures and industry association reports. Conversations captured maintenance director priorities for unplanned downtime reduction and aftermarket service head perspectives on mechatronics skill gaps. Bottom-up equipment shipment tallies were cross-referenced against top-down pharmaceutical and food processing capital expenditure patterns.
Historical shipment trajectories were weighed against panel input from automation vendor sales executives and contract manufacturer operations directors across the projection horizon. Segmentation modeling spanned product type, technology layer, application environment, and end-user procurement modality. CAGRs were derived from equipment refresh cycle analysis and regulatory compliance deadline clustering. Forecast inputs incorporated EU Green Deal enforcement timelines and India's PLI scheme subsidy qualification thresholds.
Several conditions sit outside the modeled scope, including abrupt semiconductor trade restrictions, pandemic-scale logistics disruptions, and retroactive FDA validation requirement changes. Forecasts reflect assumptions about regulatory enforcement consistency and foundry capacity expansion trajectories. Material deviation in EU MDR implementation timelines or East Asian chip supply normalization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Automation
Automatic Powder Filling Machines Market
Packaging Automation
Fully Automatic Round Bottle Labeling Machine Market
Packaging Automation
Europe Packaging Automation Market
Packaging Automation
Packaging Automation Solutions Market
Packaging Automation
Automatic Die Cutting Machines Market
Packaging Automation
Automatic Strapping Machines Market
Packaging Automation
Robotic Packaging Machines Market
Packaging Automation
Automatic Labeling Machine Market
Packaging Automation
APAC Packaging Automation Market
Packaging Automation
Pre-Assembled Packaging Market
Packaging Automation
Middle East and Africa Packaging Automation Market
Packaging Automation
Automatic Glue Machine Market
Packaging Automation
North America Contract Packaging Market
Packaging Automation
Automated Tray Fill and Seal Machines Market
Packaging Automation
Automated Label Inspection Machines Market
Packaging Automation
Global Packaging Robot Market