
 Filling Equipment Market | 2026-2036
Filling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Filling Equipment Market Intelligence
Asset-light leasing models for high-speed rotary fillers is narrowing the capital barrier for mid-tier beverage bottlers in emerging markets. Krones AG leverages its integrated line engineering capability to sustain premium positioning across aseptic and carbonated applications. GEA Group anchors pharmaceutical-grade filling through isolator technology and cGMP compliance infrastructure. Accutek Packaging Equipment Companies Inc competes on configurable semi-automatic systems for regional craft producers.
Filling equipment encompasses machinery engineered to meter, dispense, and seal precise product volumes into primary packaging, with accuracy tolerances typically ranging from ±0.5% to ±2% depending on viscosity and regulatory class. These systems serve the essential industrial function of converting bulk processed goods into standardized, shelf-stable consumer units at throughputs from 10 to 120,000 units per hour. Pump fillers dominate viscous pharmaceutical and cosmetic applications where shear-sensitive formulations require positive-displacement metering. Automatic technology lines command the largest installed base but semi-automatic equipment captures replacement demand from small-batch chemical and specialty food processors. Bottle packaging maintains structural precedence across carbonated and still beverages, though pouch filling accelerates in condiments and ready-to-drink nutritionals.
FDA cGMP guidelines and EU MDR frame pharmaceutical filling validation requirements, while EPA and OSHA standards govern chemical handling and operator exposure limits in industrial installations. BIS certification requirements in India and China's NMPA Good Manufacturing Practice directives further segment market access for imported equipment. Stakeholders must weigh regulatory divergence against platform standardization when configuring regional production footprints.
Market Dynamics
Pharmaceutical serialization mandates and aseptic isolator upgrades are compressing replacement cycles for legacy rotary fillers across high-volume production facilities.
Growth Catalysts
- EU MDR compliance deadlines:Medical device manufacturers in Germany and France are retrofitting filling lines with isolator technology to meet sterility assurance level requirements.
- Shear-sensitive biologics:Peristaltic pump systems capture share from piston fillers in monoclonal antibody packaging where protein integrity demands gentle product handling.
- India:Domestic machinery output under PLI scheme incentives is displacing imported equipment for regional food processors serving export markets.
Market Restraints
- Stainless steel price volatility:Grade 316L sheet metal accounts for 35-45% of filler chassis cost, exposing fabricators to nickel and molybdenum commodity swings.
- Precision component sourcing:Servo motors and load cells concentrate in Japanese and German supply bases, creating lead time vulnerability for non-integrated builders.
- Validation burden:FDA cGMP process validation protocols extend commissioning timelines by 8-14 months for pharmaceutical installations.
Strategic Opportunities
- Cell and gene therapy:Small-batch aseptic filling for personalized medicines creates demand for modular isolator systems with rapid changeover capability.
- Brazil ANVISA alignment:Harmonization with FDA standards is opening import pathways for US and EU-validated equipment previously excluded by local content rules.
- Machine vision + AI:Real-time fill-level inspection converging with predictive maintenance algorithms reduces giveaway and unplanned downtime in carbonated beverage lines.
Industry Challenges
- Commissioning engineer scarcity:Qualified technicians for isolator qualification and media fill validation command 40% salary premiums, constraining deployment velocity.
- Retrofit integration:Legacy SCADA architectures in 1990s-era dairy plants resist seamless connection to modern track-and-trace databases without middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filling Equipment Market |
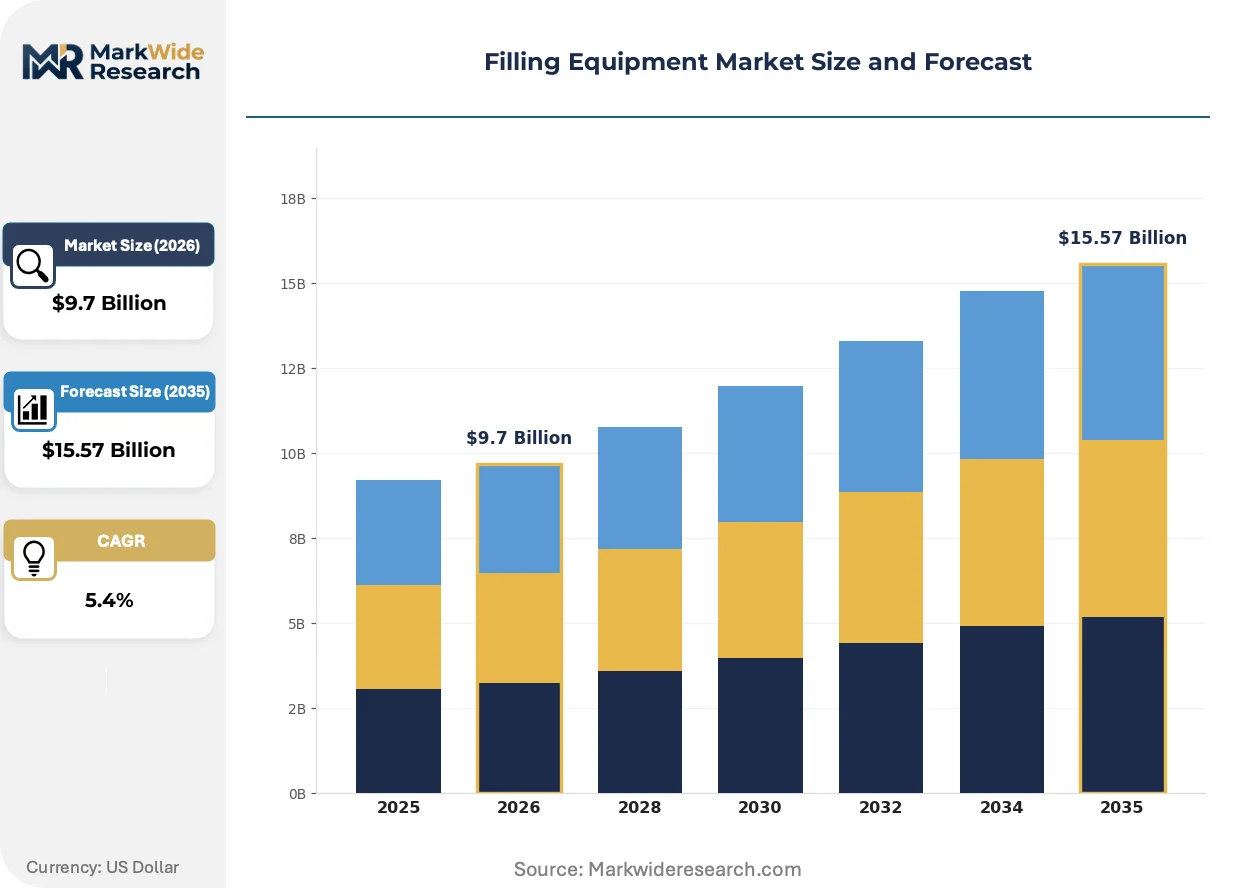
| Market Size in 2026 | $9.7 Billion |
| Market Size in 2035 | $15.57 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piston Fillers, Gravity Fillers, Pump Fillers, Auger Fillers End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Technology: Automatic, Semi-Automatic, Manual, Continuous Packaging Type: Bottles, Pouches, Cans, Jars |
| Companies Covered | Krones AG, KHS GmbH, GEA Group AG, Sidel Group, Barry-Wehmiller Companies Inc, Robert Bosch GmbH, Accutek Packaging Equipment Companies Inc, JBT Corporation, Coesia Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filling Equipment Market Strategic Shifts & Innovations
Digital thread integration from recipe management to electronic batch records is collapsing the traditional separation between process equipment and quality systems.
Single-use fluid path assemblies are digitizing changeover protocols in multi-product biopharma facilities. Contract manufacturers adopt disposable pump manifolds and bag assemblies to eliminate CIP/SIP cycles between campaigns. This architecture compresses batch turnaround from hours to minutes while reducing cross-contamination risk profiles.
EU F-Gas Regulation phase-down schedules are accelerating adoption of magnetic levitation bearings in high-speed rotary fillers. Compressor-dependent vacuum systems face refrigerant containment audits; mag-lev blowers eliminate lubricants and seals. Carbonated beverage bottlers in Italy and Spain retrofit lines ahead of 2030 service ban deadlines.
Regional craft distilleries and kombucha producers are consolidating procurement through equipment cooperatives and shared-service manufacturing networks. These buying pools negotiate volume discounts on semi-automatic piston fillers and counter-pressure bottling lines. The model is most developed in Colorado, Oregon, and British Columbia where beverage manufacturing clusters share technical staff and spare parts inventories.
Filling Equipment Market Segmentation
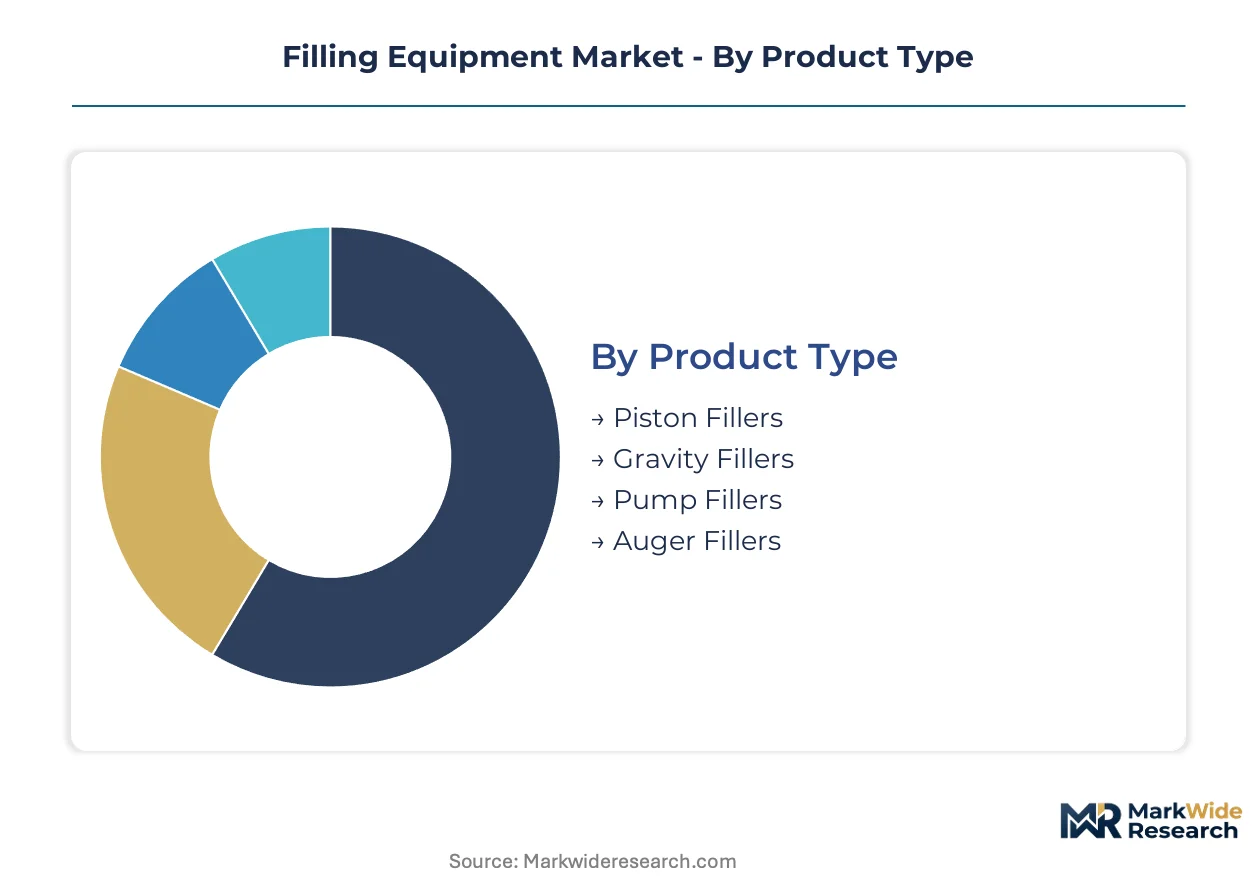
Segmentation in filling equipment reveals distinct engineering requirements and procurement patterns across viscosity ranges, regulatory classes, and throughput demands. Each dimension shapes capital allocation priorities and vendor selection criteria for end-users.
Product Type:
Cost tier stratification separates precision metering technologies from gravity-dependent systems with minimal component complexity.
- Piston Fillers:Positive-displacement cylinders deliver ±0.5% volumetric accuracy for viscous sauces and pharmaceutical suspensions. Food processors in India deploy these for ketchup and mayonnaise under FSSAI hygiene mandates.
- Pump Fillers:Peristaltic and gear pump architectures handle shear-sensitive biologics where protein denaturation risks exclude piston mechanisms. German pharmaceutical isolator lines specify peristaltic manifolds for monoclonal antibody filling.
- Gravity Fillers:Open-nozzle systems exploit hydrostatic pressure for thin liquids at lowest capital cost. Regional water bottlers in Brazil favor these for still beverages under ANVISA simplified validation pathways.
- Auger Fillers:Screw-feed mechanisms meter dry powders and granular products with controlled bulk density compensation. Cosmetic talc and protein powder packagers specify these for dust-containment compliance.
Pump fillers command the established base in pharmaceutical-grade applications. The steepest expansion runs through piston fillers displacing manual operations in emerging market food processing.
End User:
Application-specific validation burdens and changeover frequency requirements create divergent equipment specifications across sectors.
- Food & Beverage:High-throughput rotary systems with CIP/SIP integration dominate carbonated and still beverage bottling. Italian and Spanish producers retrofit lines ahead of EU F-Gas Regulation compressor phase-down deadlines.
- Pharmaceuticals:Aseptic isolator technology with media fill validation protocols governs injectable and ophthalmic filling. FDA cGMP and EU MDR sterility assurance level requirements compress replacement cycles for legacy equipment.
- Cosmetics:Semi-automatic piston and peristaltic systems serve small-batch premium skincare with frequent flavor and fragrance changeovers. Contract manufacturers prioritize rapid tooling swap capabilities.
- Chemicals:Corrosion-resistant 316L stainless steel construction with EPA-compliant vapor recovery systems addresses solvent and agrochemical filling. OSHA exposure limit compliance drives enclosed filling station specifications.
Food and beverage applications command the established installed base. The steepest expansion trajectory belongs to pharmaceutical isolator upgrades driven by serialization mandates and biologics volume growth.
Technology:
Customer type and batch scale determine automation level selection, from manual benchtop units to continuous motion rotary systems.
- Automatic:Servo-driven rotary fillers with machine vision inspection achieve 120,000 units per hour in carbonated beverage bottling. Krones and GEA integrated lines dominate this tier with line engineering bundling.
- Semi-Automatic:Operator-fed systems with pneumatic indexing serve craft distilleries and regional kombucha producers in Colorado and Oregon equipment cooperatives.
- Manual:Hand-operated piston and gravity units address micro-batch chemical and specialty food prototyping with minimal validation overhead.
- Continuous:Linear motion architectures eliminate indexing dwell time for high-viscosity pharmaceutical creams and ointments.
Automatic technology commands the established base in high-volume beverage and pharmaceutical installations. The steepest expansion runs through semi-automatic systems capturing replacement demand from small-batch chemical and specialty food processors.
Packaging Type:
Geometry and material constraints dictate filler nozzle configuration, handling mechanism, and sealing integration requirements.
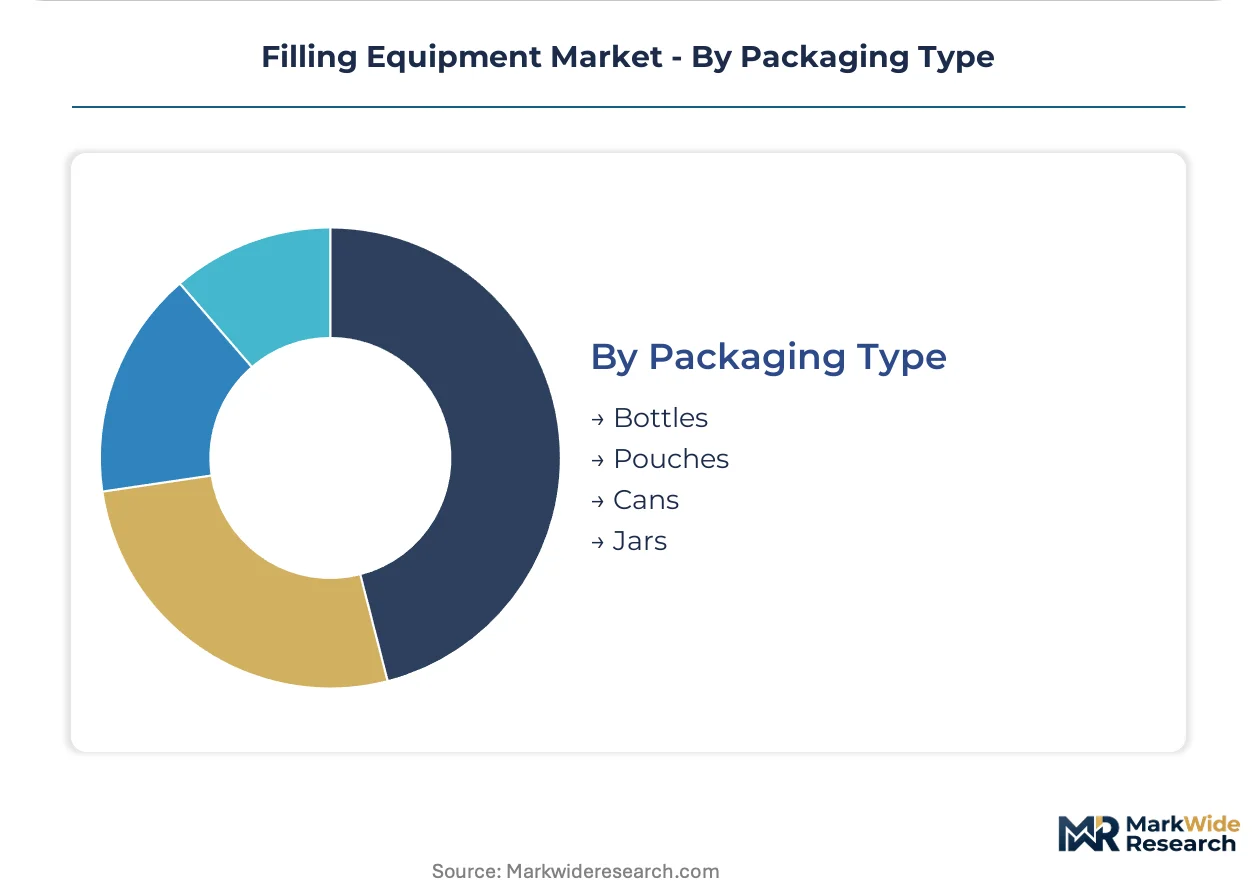
- Bottles:Glass and PET container handling with neck-centered transfer systems maintains structural precedence across carbonated and still beverages. Crown cork and screw cap torque integration completes the line.
- Pouches:Spouted and flat flexible format filling accelerates in condiments, baby food, and ready-to-drink nutritionals. Form-fill-seal integration reduces secondary packaging steps.
- Cans:Aluminum beverage can handling with counter-pressure filling preserves CO₂ saturation in beer and soft drinks. End-seaming integration follows fill station.
- Jars:Wide-mouth glass and plastic container filling serves viscous products including sauces, preserves, and cosmetic creams. Vacuum deaeration options address foam control.
Bottle packaging commands the established base across carbonated and still beverage categories. The steepest expansion runs through pouch filling as condiment and nutritional brands convert from rigid to flexible formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme incentives for domestic machinery manufacturing are redirecting procurement patterns across South Asian food processing clusters. German pharmaceutical isolator investments and Brazilian ANVISA regulatory alignment are compressing equipment replacement timelines in their respective markets.
Germany
Medical device manufacturers in Baden-Württemberg and Bavaria are retrofitting legacy rotary fillers with isolator technology to meet EU MDR sterility assurance level requirements. The country's national pharmaceutical regulator enforces accelerated validation protocols for aseptic filling lines. Stuttgart's industrial machinery corridor hosts concentrated engineering activity around peristaltic pump integration for monoclonal antibody packaging.
India
Domestic packaging machinery output under PLI scheme incentives is displacing imported equipment for regional food processors serving Middle Eastern and African export markets. BIS certification requirements for imported filling systems create procurement friction that favors local fabricators. Maharashtra's Pune-Ahmednagar belt concentrates semi-automatic piston filler manufacturing for ketchup and mayonnaise applications under FSSAI hygiene mandates.
United States
Cell and gene therapy contract manufacturers in Greater Boston and the San Francisco Bay Area are procuring modular isolator systems with rapid changeover capability for small-batch personalized medicines. FDA cGMP process validation protocols extend commissioning timelines for pharmaceutical installations. Colorado's Front Range beverage manufacturing cooperatives share technical staff and spare parts inventories for semi-automatic craft distillery equipment.
Brazil
ANVISA harmonization with FDA standards is opening import pathways for US and EU-validated equipment previously excluded by local content rules. Regional water bottlers favor gravity fillers for still beverages under simplified validation pathways. São Paulo state's industrial corridor concentrates retrofit activity as carbonated beverage producers prepare for compressor phase-down deadlines.
Italy
Carbonated beverage bottlers in Emilia-Romagna and Lombardy are retrofitting high-speed rotary filler lines ahead of EU F-Gas Regulation 2030 service ban deadlines. The regulation's phase-down schedules accelerate magnetic levitation bearing adoption to eliminate refrigerant-dependent vacuum systems. Parma's food machinery cluster drives form-fill-seal integration for condiment pouch filling applications.
Filling Equipment Market Key Industry Players
On the supply side, the industry is bifurcated between integrated line engineering conglomerates and specialized component fabricators. Tier-one vendors bundle filler, labeler, and inspection systems into turnkey installations. Tier-two regional builders compete on configurable semi-automatic platforms for craft producers. Strategic moves concentrate on isolator technology partnerships for pharmaceutical validation and shared-service manufacturing networks for beverage cooperatives.
Within the integrated engineering tier, Krones AG and GEA Group AG occupy positions defined by line-bundling capability and pharmaceutical-grade compliance infrastructure respectively. KHS GmbH represents the German machinery export archetype serving carbonated beverage bottlers across Southern European and Latin American markets. Accutek Packaging Equipment Companies Inc exemplifies the North American mid-tier specialist competing on rapid configuration for regional craft producers.
| Leading Market Players |
|---|
| Krones AG |
| KHS GmbH |
| GEA Group AG |
| Sidel Group |
| Barry-Wehmiller Companies Inc |
| Robert Bosch GmbH |
| Accutek Packaging Equipment Companies Inc |
| JBT Corporation |
| Coesia Group |
| Others |
Cost & Logistics Intelligence
Japanese and German servo motor suppliers anchor precision component availability, concentrating pricing power with integrated line engineering conglomerates while regional fabricators absorb stainless steel commodity volatility through chassis cost exposure.
Pricing Analysis
Certification level (FDA-grade/cGMP-validated vs. standard CE/ISO) creates the primary spread between pharmaceutical isolator systems and beverage-grade rotary fillers. Three-tier pricing structure across premium, standard, and economy levels segments by validation burden and after-sales service bundling. Cost compression in mid-tier semi-automatic equipment is intensifying because Indian domestic fabricators displace imports under PLI scheme incentives. Regional craft distilleries and beverage cooperatives exhibit highest price sensitivity; pharmaceutical contract manufacturers demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Contract manufacturing capacity for pharmaceutical-grade isolator assemblies concentrates with German and Swiss precision engineering specialists. Component sourcing draws from Japan for servo motors, Germany for load cells, and China for standardized pneumatic assemblies. Stainless steel Grade 316L sheet metal feeds from Indian and Chinese rolling mills, creating tariff exposure for European fabricators. Distribution runs through direct OEM sales for integrated line projects and regional distributor networks for semi-automatic replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell and gene therapy commercialization represents an early-cycle expansion story as personalized medicine manufacturing scales beyond clinical trial volumes into commercial production.
For Market Incumbents: Harden isolator technology partnerships with pharmaceutical validation specialists to defend against modular system entrants targeting small-batch biologics. Deepen backward integration into servo motor and precision metering component supply to reduce lead time vulnerability from Japanese and German suppliers. Expand captive service engineering capacity to capture commissioning engineer salary premiums constraining deployment velocity. For New Entrants and Emerging Players: Build out configurable semi-automatic platforms for India's regional food processors serving Middle Eastern and African export markets under BIS certification advantages. Target Brazil's ANVISA-harmonized import pathway for US and EU-validated equipment previously excluded by local content rules. Pursue equipment cooperative membership models pioneered in Colorado and Oregon beverage manufacturing clusters. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed pharmaceutical isolator specialists holding FDA cGMP validation libraries. Long-term viability hinges on biologics volume growth and serialization mandate compliance across the analysis window. Monitor cell and gene therapy contract manufacturer capital expenditure announcements as inflection indicators for modular isolator demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Partnership | GEA Group and Krones AG leverage integrated validation libraries to capture pharmaceutical-grade replacement cycles. |
| Domestic Manufacturing Scale-Up | Indian fabricators under PLI scheme incentives displace German and Italian imports for regional food processing. |
| Magnetic Levitation Bearing Retrofit | Italian and Spanish bottlers eliminate refrigerant-dependent vacuum systems ahead of EU F-Gas Regulation deadlines. |
| Single-Use Fluid Path Assembly | Contract manufacturers adopt disposable pump manifolds to compress biopharma batch turnaround from hours to minutes. |
| Equipment Cooperative Formation | Colorado and Oregon craft distilleries share technical staff and spare parts inventories for semi-automatic piston fillers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 483 inspection observations, EU MDR technical documentation filings, and customs trade data for packaging machinery imports. Plant engineers at beverage bottlers, pharmaceutical manufacturing heads, and aftermarket service directors provided operational perspective on replacement cycle timing and validation burden. SEC 10-K filings from Krones AG and GEA Group AG furnished capital allocation patterns. Bottom-up unit economics triangulated against top-down market sizing from machinery production statistics.
Forecast inputs span product type segmentation across piston, pump, gravity, and auger filler architectures; technology tiers from manual through continuous motion systems; and packaging format evolution from rigid bottles to flexible pouches. End-user demand modeling incorporates pharmaceutical serialization mandates, EU F-Gas Regulation phase-down schedules, and India PLI scheme incentive structures. CAGRs derive from installed base turnover analysis and penetration rate projections across the analysis window.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese precision component suppliers or accelerated ANVISA regulatory harmonization would shift outcomes. Quarterly review of pharmaceutical contract manufacturer capital expenditure announcements and stainless steel commodity price indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
High Resolution Dispensing Systems and Equipment Market
Packaging Equipment
Thermal Impulse Sealers Market
Packaging Equipment
Packing Belt Market
Packaging Equipment
Global Cap Applicators Market
Packaging Equipment
Label Converting Equipment Market
Packaging Equipment
Diaper Packaging Machines Market
Packaging Equipment
Sack Tip Stations Market
Packaging Equipment
Clip Applicator Market
Packaging Equipment
Coding and Marking Equipment Market
Packaging Equipment
Burnisher Market
Packaging Equipment
Global Dispensing Systems Market
Packaging Equipment
Corrugated Equipment Market
Packaging Equipment
Loose Fill Packaging Systems Market
Packaging Equipment
Volumetric Filing Lines Market
Packaging Equipment
Loading Spout Market
Packaging Equipment
Vacuum Sealers Market