
 Bag Re-Sealer Market | 2026-2036
Bag Re-Sealer Market Size, Share, and Industry Trends Forecast 2026-2036
Bag Re-Sealer Market Outlook
Food service vertical demand is realigning toward commercial-grade vacuum preservation systems as restaurants and catering operators prioritize inventory longevity. FoodSaver leverages its brand strength in North American retail channels to sustain household penetration. Weston Brands LLC anchors the hunting and outdoor preservation segment with specialized chamber sealers. Hamilton Beach Brands competes through broad kitchen-appliance distribution that extends re-sealer visibility alongside core small appliances.
A bag re-sealer is a thermal or pressure-activated device that fuses polymer film layers—typically polyethylene, polypropylene, or laminated multi-layer structures—through controlled heat application ranging from 120°C to 200°C, creating an airtight barrier to extend shelf life and prevent contamination. Electric tabletop units dominate the product type mix due to consistent seal integrity and throughput suited to small commercial kitchens, while battery-powered handheld variants represent the fastest-growing form factor for field use and constrained-space environments. Impulse sealing technology leads the technology landscape for energy efficiency, though ultrasonic sealing commands premium positioning in pharmaceutical and medical-grade applications where hermetic integrity is non-negotiable.
The US Food and Drug Administration governs indirect food-contact materials under 21 CFR 177, compelling manufacturers to validate seal-bar coatings and heating-element substrates for migration compliance. The EU F-Gas Regulation constrains refrigerant-dependent vacuum-chamber designs, redirecting R&D toward mechanical vacuum pumps and ambient sealing methods. California's SB 54 mandates 65% plastic packaging recycling by 2032, pressuring re-sealer makers to certify compatibility with emerging mono-material films. Stakeholders must monitor how polymer-recycling infrastructure investments reshape film availability and seal-parameter requirements across their served verticals.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are forcing re-sealer manufacturers to redesign thermal sealing profiles for mono-material compatibility, while food service operators simultaneously demand higher throughput from compact footprint equipment.
Growth Catalysts
- California SB 54 compliance deadlines:The state's 65% plastic packaging recycling mandate by 2032 accelerates demand for re-sealers certified to handle emerging recyclable mono-material films without seal-bar contamination.
- Commercial kitchen equipment procurement:Germany's food service sector is expanding vacuum-seal programs to reduce inventory spoilage, driving institutional-grade tabletop unit adoption across catering and hospitality verticals.
- Impulse sealing energy efficiency:Thermal cycling improvements in ceramic-coated seal bars cut power consumption by eliminating continuous heating, making electric units viable for off-grid field operations.
Market Restraints
- Copper and aluminum price volatility:Heating-element substrates and seal-bar castings face input cost swings that compress margin structures for mid-tier equipment manufacturers.
- EU F-Gas Regulation constraints:Refrigerant-dependent vacuum-chamber designs face phase-out timelines, forcing costly R&D pivots toward mechanical pump architectures.
- Adhesive tape substitution:Low-cost pressure-sensitive closures compete for non-hermetic applications in price-sensitive consumer segments, capping household penetration rates.
Strategic Opportunities
- India commercial cold chain expansion:The country's PLI scheme for food processing infrastructure creates first-mover positioning for vacuum preservation systems in emerging institutional kitchens.
- Ultrasonic-pharmaceutical convergence:Hermetic sealing requirements for medical-grade barrier packaging open premium positioning beyond food applications.
- Battery-powered handheld form factors:Field use cases in hunting, fishing, and remote meal preparation remain underpenetrated relative to tabletop saturation.
Industry Challenges
- Polymer film certification timelines:FDA 21 CFR 177 migration testing for new seal-bar coatings extends product development cycles by 8-14 months.
- Legacy kitchen equipment integration:Re-sealer connectivity with existing commercial appliance networks requires proprietary interface development that fragments R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bag Re-Sealer Market |
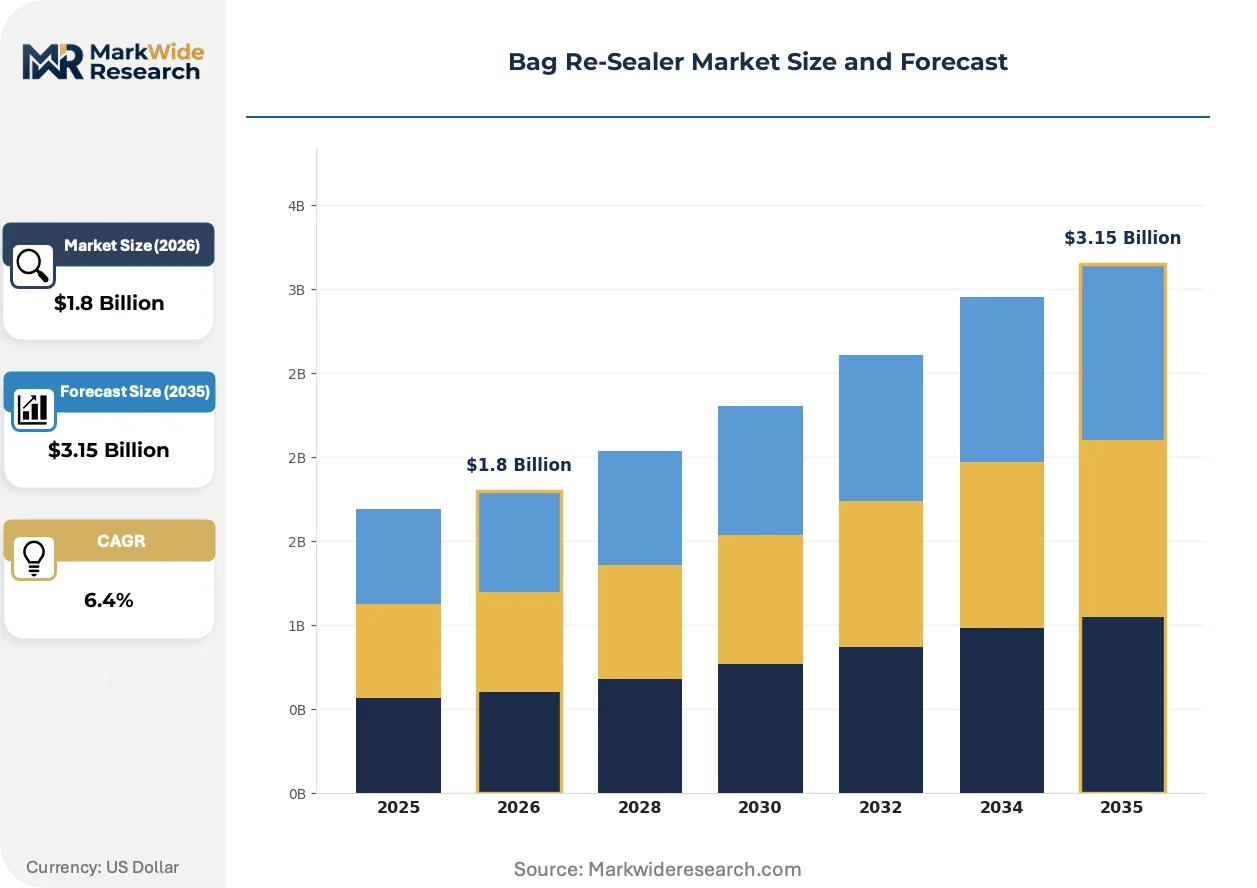
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Battery-Powered, Heat Sealer End User: Food Industry, Retail, Household, Pharmacy Form: Handheld, Tabletop, Portable, Industrial Technology: Impulse Sealing, Constant Heat, Ultrasonic, Induction |
| Companies Covered | Hamilton Beach Brands, Seal-a-Meal, FoodSaver, AVACRAFT, Crenova, iTouchless Housewares & Products, Inc., Ziploc, Bartelli, Weston Brands LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bag Re-Sealer Market Strategic Shifts
Thermal sealing architectures and regulatory compliance frameworks are converging to reshape equipment specifications, with material science advances and procurement pattern shifts creating divergent paths for premium and mass-market positioning.
Ultrasonic sealing is rewriting the hermetic integrity benchmark for pharmaceutical and medical-grade applications. Specialty packaging converters in Switzerland and Germany are adopting piezoelectric weld systems to eliminate thermal degradation of sensitive barrier films. This precision is compressing the performance gap between industrial chamber sealers and compact tabletop units in high-value verticals.
EU F-Gas Regulation phase-down schedules are redirecting vacuum-chamber R&D toward dry mechanical pump technologies. Equipment manufacturers must validate alternative evacuation methods that maintain seal integrity without hydrofluorocarbon refrigerants. German commercial kitchen suppliers are piloting ambient-pressure sealing protocols that bypass vacuum stages entirely for moisture-sensitive foods.
Food service procurement patterns are consolidating around bundled small-appliance contracts. Re-sealer visibility now depends on placement within broad kitchen equipment portfolios rather than standalone merchandising. This channel compression is most visible in North American restaurant supply distribution, where tabletop units compete for shelf space alongside immersion circulators and precision cookers.
Bag Re-Sealer Market Segmentation
Equipment replacement cycles in commercial kitchens and household pantries differ sharply, with institutional buyers prioritizing throughput durability while consumers weigh portability against seal reliability. Segment boundaries blur where battery-powered units achieve tabletop-grade performance or where ultrasonic precision migrates from pharmaceutical cleanrooms to high-end food service.
Product Type:
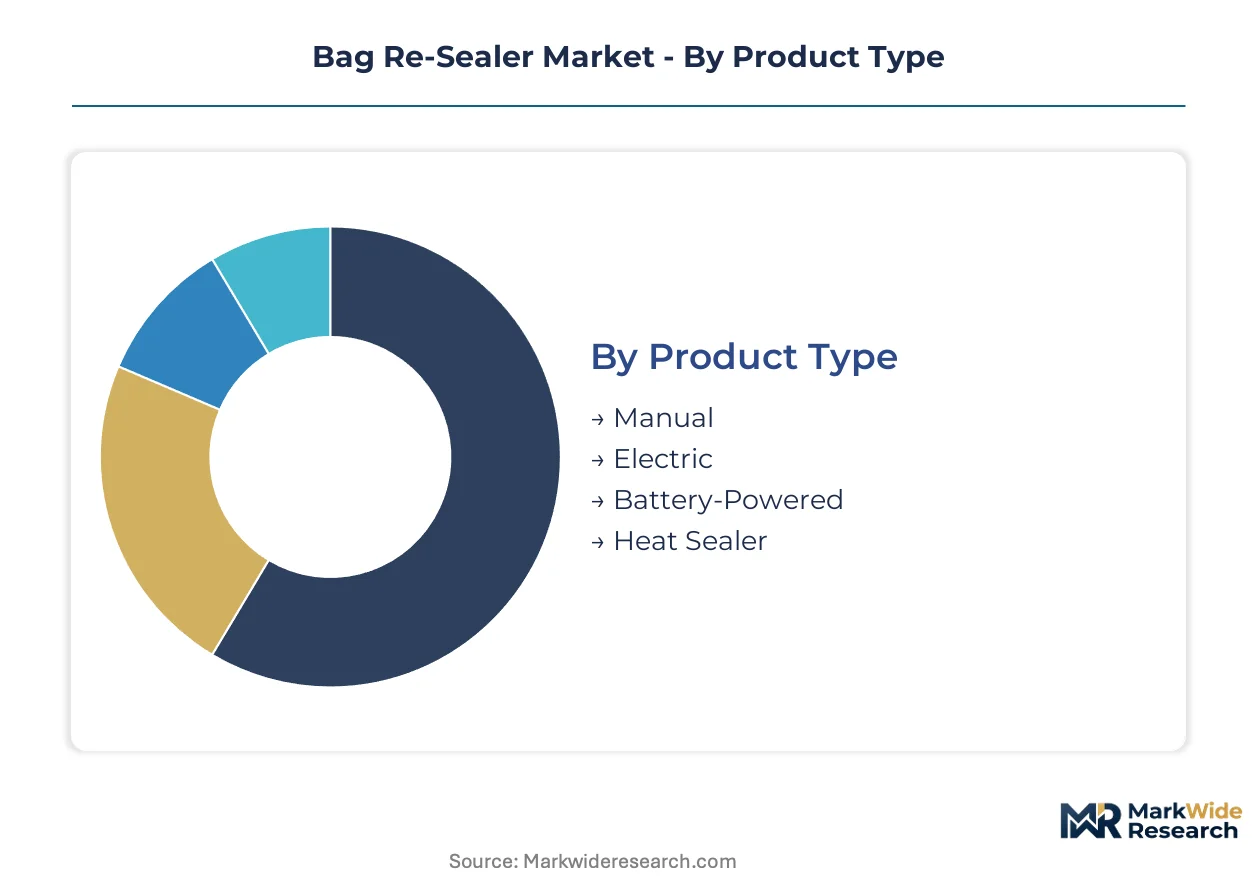
Upgrade decisions hinge on seal consistency requirements and power infrastructure availability, with electric models displacing manual units in professional settings while battery variants capture field-use expansion.
- Electric:Ceramic-coated seal bars deliver 120°C to 200°C thermal profiles with ±2°C stability across continuous duty cycles. Germany's commercial kitchen equipment sector specifies these for vacuum-seal programs targeting inventory spoilage reduction in catering operations.
- Battery-Powered:Lithium-ion cell configurations sustain 150+ seals per charge at reduced wattage, enabling deployment in hunting camps, fishing vessels, and remote meal preparation nodes lacking grid access.
- Manual:Pressure-activated clamp mechanisms without electrical components serve price-sensitive household segments and emergency preparedness kits where power independence outweighs throughput needs.
- Heat Sealer:Dedicated constant-temperature architectures for high-volume polypropylene film processing in light industrial packaging lines and centralized food commissaries.
Electric units sit at the top of the volume ranking, with battery-powered variants climbing the fastest as field-use applications multiply.
End User:
Procurement authority and volume scale separate institutional buyers from dispersed consumer demand, with compliance requirements fragmenting specifications across verticals.
- Food Industry:HACCP-aligned stainless-steel housings and IP65 washdown ratings dominate commercial kitchen specifications. California SB 54 mandates are accelerating certification for mono-material film compatibility in restaurant chain central kitchens.
- Household:Countertop footprint constraints and brand recognition drive purchasing, with North American retail channel placement determining visibility alongside immersion circulators and precision cookers.
- Retail:In-store demonstration requirements and impulse-purchase price points shape merchandising, with bundled small-appliance contracts compressing standalone positioning.
- Pharmacy:FDA 21 CFR 177 migration compliance and hermetic integrity validation for barrier packaging distinguish medical-grade specifications from food-service equivalents.
Food industry procurement commands the highest unit volumes, while pharmacy applications generate the steepest margin premiums.
Form:
Spatial constraints and mobility requirements dictate form factor selection, with footprint-to-throughput ratios determining commercial viability.
- Tabletop:Fixed-position electric units with 12-inch seal bars anchor small commercial kitchen workflows, offering institutional-grade throughput without chamber-sealer capital expenditure.
- Handheld:Grip-activated thermal jaws suit spot-sealing applications in field dressing, campsite meal prep, and constrained domestic storage environments.
- Portable:Collapsible or battery-integrated designs bridge stationary and mobile use cases, targeting food truck operators and catering fleets with intermittent power access.
- Industrial:Conveyor-fed continuous band sealers and vacuum-chamber systems for centralized processing facilities with dedicated maintenance protocols.
Tabletop configurations dominate installed base, with handheld form factors gaining share fastest through outdoor recreation market penetration.
Technology:
Energy efficiency mandates and seal integrity standards are concentrating R&D investment toward architectures that eliminate continuous thermal load or thermal degradation entirely.
- Impulse Sealing:Ceramic-element thermal cycling applies heat only during seal compression, cutting power consumption versus constant-temperature alternatives. EU energy efficiency directives favor this architecture for commercial equipment certification.
- Ultrasonic:Piezoelectric vibration welding at 20-40 kHz fuses polymer layers without bulk heating, preserving sensitive barrier film properties for pharmaceutical and medical-grade applications in Swiss and German converter facilities.
- Constant Heat:Maintained seal-bar temperature suits high-speed continuous operations in centralized food packaging lines where thermal mass stability outweighs energy penalty.
- Induction:Electromagnetic heating of metallic seal-layer components enables rapid thermal response in specialized laminated film structures.
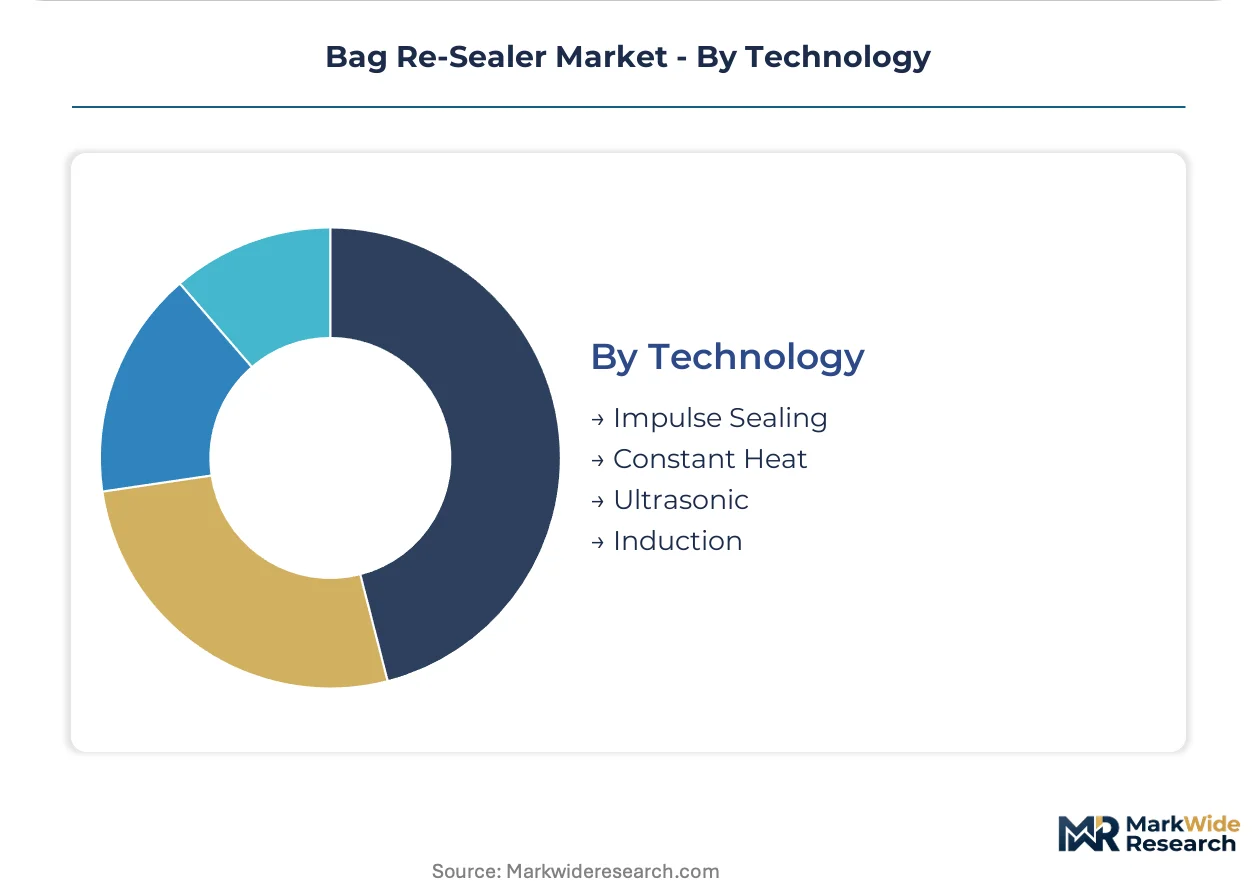
Impulse sealing holds the largest technology share, with ultrasonic systems expanding most quickly through pharmaceutical packaging adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as producers migrate toward jurisdictions with lower compliance costs for thermal-sealing equipment. The EU F-Gas Regulation and California SB 54 create divergent cost structures that favor localized production strategies over centralized supply.
United States
California SB 54 mandates 65% plastic packaging recycling by 2032, forcing re-sealer manufacturers to certify mono-material film compatibility. FDA 21 CFR 177 governs indirect food-contact materials for seal-bar coatings. The Pacific Northwest hosts testing facilities validating migration compliance for emerging polymer formulations.
Germany
Commercial kitchen equipment procurement is expanding vacuum-seal programs to cut inventory spoilage across catering operations. The EU F-Gas Regulation constrains refrigerant-dependent vacuum-chamber designs, redirecting R&D toward mechanical pump architectures. Bavaria's industrial equipment cluster pilots ambient-pressure sealing protocols for moisture-sensitive foods.
China
Domestic food processing infrastructure investment is creating demand for institutional-grade tabletop units in centralized commissaries. The country's national standards body certifies thermal cycling stability for ceramic-coated seal bars. The Yangtze River Delta concentrates contract manufacturing for export-oriented handheld battery-powered variants.
Switzerland
Specialty packaging converters adopt piezoelectric weld systems for pharmaceutical barrier films requiring hermetic integrity. Swissmedic regulates medical-grade sealing equipment validation for sterile packaging applications. The Basel region hosts precision engineering firms supplying ultrasonic transducer assemblies to European equipment makers.
India
The PLI scheme for food processing infrastructure creates first-mover positioning for vacuum preservation systems in emerging institutional kitchens. FSSAI alignment with international food-contact material standards accelerates import substitution for commercial-grade sealers. Maharashtra's cold chain expansion drives tabletop unit adoption in Mumbai-Pune catering corridors.
Bag Re-Sealer Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with household retail channels consolidating around recognizable names while commercial procurement favors technical specification over brand equity. The vendor base arranges into three tiers: multinational kitchen-appliance conglomerates with broad distribution reach, dedicated sealing-equipment specialists with vertical feature sets, and regional fabricators serving price-sensitive institutional buyers. Strategic moves concentrate on portfolio diversification into adjacent preservation technologies and geographic expansion through distributor partnerships in emerging cold-chain markets.
Among North American branded specialists, FoodSaver and Hamilton Beach Brands occupy positions anchored in retail channel visibility, while Weston Brands LLC exemplifies the outdoor-recreation specialization archetype. These three represent distinct competitive vectors: mass-market household penetration, broad kitchen-appliance bundling, and hunting-field preservation niche dominance.
| Leading Market Players |
|---|
| Hamilton Beach Brands |
| Seal-a-Meal |
| FoodSaver |
| AVACRAFT |
| Crenova |
| iTouchless Housewares & Products, Inc. |
| Ziploc |
| Bartelli |
| Weston Brands LLC |
| Others |
Value Chain & Pricing Dynamics
London Metal Exchange copper price volatility cascades through heating-element substrate costs, compressing margin structures for mid-tier equipment manufacturers while premium ceramic-coated seal-bar suppliers in Germany and Japan maintain pricing power through technical differentiation.
Pricing Analysis
Distributor markups of 35-50% separate factory-gate equipment from end-user pricing in commercial kitchen channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by seal-bar coating certification and duty-cycle durability. Cost compression in battery-powered handheld tiers intensifies as lithium-ion cell prices soften and Chinese contract manufacturers scale output. Household retail buyers exhibit highest price sensitivity, while pharmacy-grade procurement prioritizes FDA 21 CFR 177 compliance over unit cost.
Supply Chain Analysis
Returns and refurbishment flows remain minimal given equipment longevity, though German commercial kitchen operators increasingly demand seal-bar replacement programs to extend asset life. Component sourcing concentrates in China for battery-powered variants, Germany for ceramic heating elements, and Switzerland for ultrasonic transducer assemblies. Seal-bar coatings draw from specialized polymer suppliers in Japan and the United States. Single-source vulnerability in piezoelectric ceramics creates exposure for ultrasonic equipment makers. Distribution runs through restaurant supply houses in North America and specialized kitchen equipment distributors in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation compliance costs in Germany run 40% below equivalent vacuum-pump R&D investments required in California, creating geographic arbitrage for manufacturers willing to relocate pilot production to Bavaria.
For Market Incumbents: Cement market position by acquiring ceramic seal-bar coating specialists in Japan to secure supply-chain control over heating-element substrates. Invest in FDA 21 CFR 177 pre-certification for emerging mono-material films before California SB 54 enforcement tightens. Battery-powered handheld entrants from Chinese contract manufacturers pose the most acute substitution threat to tabletop dominance. For New Entrants and Emerging Players: Direct-to-consumer video commerce offers the lowest customer-acquisition cost path for battery-powered handheld units targeting hunting and outdoor recreation segments. India's PLI scheme for food processing infrastructure represents the most penetrable geography for institutional-grade tabletop equipment. Bundle vacuum preservation systems with cold-chain infrastructure tenders to bypass established distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier manufacturers lack vertical integration into seal-bar coating supply. Five-to-ten-year viability favors specialists with pharmaceutical-grade ultrasonic capabilities or dominant share in India's emerging institutional kitchen sector. Monitor EU Packaging and Packaging Waste Regulation amendment timelines as the critical inflection signal for mono-material film certification requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal-Bar Coatings | Captures margin from Japanese polymer suppliers while securing FDA migration compliance timelines. |
| Battery-Powered Handheld Launch | Opens hunting and fishing verticals where Weston Brands LLC currently dominates with chamber sealers. |
| Pharmaceutical Ultrasonic Certification | Accesses Swissmedic-regulated sterile packaging demand with hermetic integrity premiums. |
| India PLI Scheme Partnership | Positions tabletop units in Maharashtra cold-chain expansion ahead of FSSAI import substitution. |
| Ambient-Pressure Sealing R&D | Bypasses EU F-Gas Regulation constraints through Bavaria-piloted mechanical pump alternatives. |
Study Parameters
Bottom-up commercial kitchen equipment procurement modeling reconciled against top-down contract manufacturing output tracking forms the analytical core. Primary interviews with restaurant chain procurement directors, food service equipment distributors, ceramic seal-bar coating suppliers, and pharmaceutical packaging converters informed demand-side assumptions. Secondary validation drew from FDA 21 CFR 177 migration testing databases, EU F-Gas Regulation implementation notices, California SB 54 compliance filings, and India's PLI scheme beneficiary disclosures.
Input-output matrices mapped electric, battery-powered, and ultrasonic technology adoption against end-user segments across the projection horizon. Segmentation dimensions modeled include product type, form factor, technology architecture, end-use vertical, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and procurement pattern elasticity. Forecast inputs incorporated polymer film availability timelines and seal-parameter recalibration requirements for mono-material compatibility.
The model assumes a particular technology adoption path; alternative pathways for ultrasonic sealing in food applications would alter the outlook if piezoelectric cost curves steepen. Forecasts reflect assumptions about EU regulatory harmonization and polymer-recycling infrastructure buildout. Practitioners should monitor EU Packaging and Packaging Waste Regulation amendment drafts and India FSSAI food-contact material standard alignment for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Die-Cutter Market
Packaging Equipment
Labeling Equipment Market
Packaging Equipment
Volumetric Filing Lines Market
Packaging Equipment
Packaging Equipment Market
Packaging Equipment
Vacuum Sealers Market
Packaging Equipment
Tray Loader Market
Packaging Equipment
Packer Market
Packaging Equipment
Packaging Tensioner Market
Packaging Equipment
Powder Dispenser Market
Packaging Equipment
Rotary Band Heat Sealer Market
Packaging Equipment
Linear Net Weighing Machines Market
Packaging Equipment
Burnisher Market
Packaging Equipment
Strapping Equipment Market
Packaging Equipment
Plastic Hopper Loader Market
Packaging Equipment
Global Dispensing Systems Market
Packaging Equipment
Dispensing Booth Market