
 Nitrogen Filling Systems Market | 2026-2036
Nitrogen Filling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Nitrogen Filling Systems Market Foresight
China's industrial belt is reshaping competitive dynamics in nitrogen filling equipment. Hale Hamilton leverages its cryogenic expertise to anchor European aerospace contracts. Maximator GmbH sustains dominance in high-pressure stationary systems through in-house valve production. Hydraulics International, Inc. competes on portable military-grade fillers for field maintenance operations.
Nitrogen filling systems are pressure-controlled apparatus designed to inject high-purity nitrogen gas into sealed containers, tires, or process chambers, typically operating between 150–300 bar for industrial applications and 99.5–99.999% purity thresholds depending on end-use requirements. Their primary purpose is to displace oxygen and moisture, thereby preventing oxidation, extending shelf life, or maintaining inert process environments. Stationary systems generate the largest revenue pool due to capital intensity and integration with continuous production lines, while portable fillers represent the fastest-expanding segment as mobile service models penetrate automotive aftermarket channels. Membrane separation technology commands widening adoption in food packaging applications where moderate purity suffices and energy efficiency governs total cost of ownership.
EU F-Gas Regulation and REACH compliance frameworks tighten material specifications for sealing components and refrigerant-adjacent nitrogen circuits, compelling manufacturers to redesign gasket and valve chemistries. FDA 21 CFR Part 177 indirect food additive rules in the United States govern nitrogen contact surfaces for packaging applications, creating divergent certification requirements across Atlantic supply chains. China's SAMR enforces GB standards for pressure equipment safety that foreign entrants must satisfy through local testing partnerships. Stakeholders must monitor how fragmented purity standards across jurisdictions reshape equipment configuration costs and aftermarket service architectures.
Market Dynamics
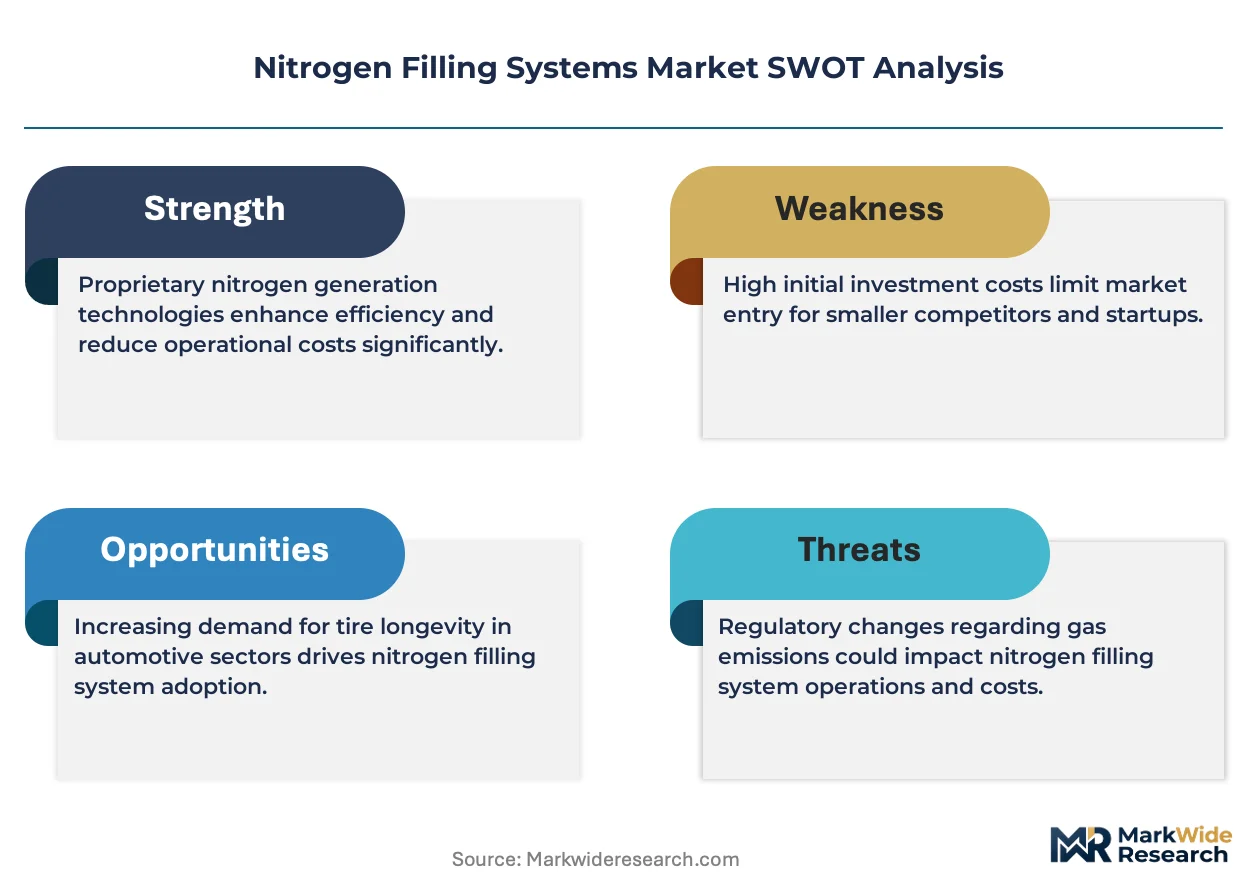
Membrane separation technology is compressing the addressable market for pressure swing adsorption systems in mid-scale nitrogen generation, forcing incumbent equipment suppliers to reconfigure their product architectures around energy efficiency metrics rather than purity benchmarks alone.
Growth Catalysts
- EU Packaging Waste Directives:Germany's food and beverage packaging lines are expanding nitrogen flushing capacity to comply with extended producer responsibility frameworks, creating equipment replacement cycles across Central European processing facilities.
- Electronics Manufacturing Concentration:Shenzhen's semiconductor and display fabrication corridor is absorbing high-purity nitrogen filling systems for cleanroom environments, with cluster effects pulling specialized service providers into Guangdong province.
- Membrane Technology Maturation:Hollow-fiber membrane modules now deliver 99.5% purity at 40% lower energy consumption than PSA alternatives, making nitrogen generation economically viable for regional bakeries and craft breweries previously dependent on liquid bulk delivery.
Market Restraints
- Specialized Alloy Input Costs:316L stainless steel and Inconel valve bodies face price volatility tied to nickel extraction constraints in Indonesian and Philippine mining jurisdictions, compressing margins on high-pressure stationary systems.
- Certification Timeline Friction:China's SAMR pressure equipment safety approvals require 14-18 month local testing partnerships for foreign entrants, creating asymmetric market access against domestic manufacturers with pre-certified platforms.
- Liquid Nitrogen Bulk Substitution:Regional gas distributors are expanding cryogenic tanker fleets for customers below 500 Nm³/h consumption thresholds, eroding the economic case for on-site generation in smaller food packaging operations.
Strategic Opportunities
- Automotive Aftermarket Mobility:Tire service chains in Brazil and Mexico are adopting portable nitrogen fillers as differentiation tools against compressed-air competitors, with mobile service vans converting fixed-cost equipment into revenue-generating assets.
- Aerospace MRO Convergence:Integration of nitrogen filling with hydraulic system testing creates bundled service contracts at heavy maintenance facilities, particularly where FAA and EASA dual certification requirements apply.
- India PLI Scheme Alignment:Electronics manufacturing incentives under India's production-linked incentive framework are attracting semiconductor packaging investments that require 99.999% purity nitrogen for wire bonding and encapsulation processes.
Industry Challenges
- Cryogenic System Integration Complexity:Field engineers with simultaneous expertise in membrane separation physics and PLC-controlled pressure regulation remain scarce, elongating commissioning timelines for hybrid generation-filling installations.
- Legacy Pneumatic Architecture Retrofit Costs:Food plants running 1980s-era compressed air infrastructure face 30-40% equipment replacement penalties to achieve nitrogen-compatible piping and sealing specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitrogen Filling Systems Market |
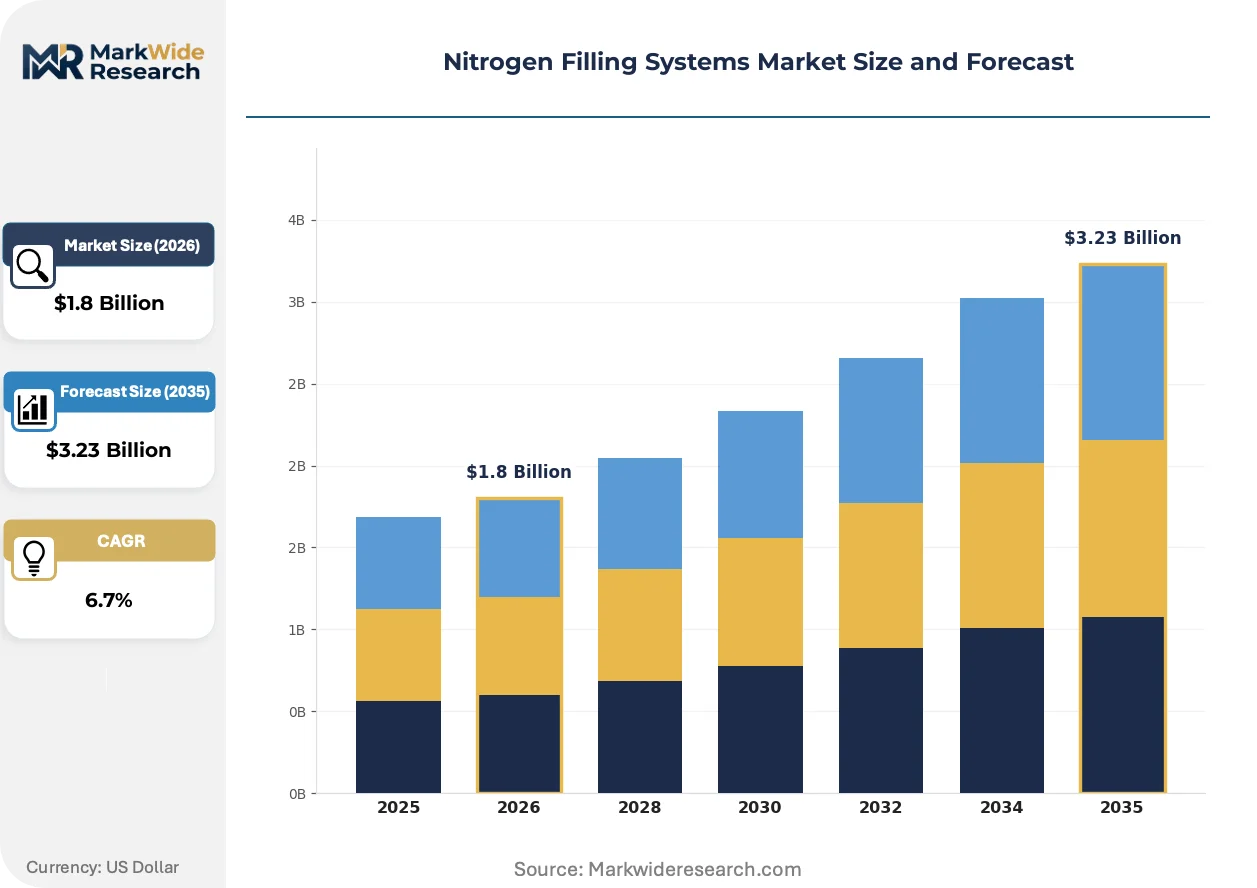
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Fillers, Stationary Systems, Industrial Units, Maintenance Kits Application: Food & Beverage Packaging, Tires Filling, Electronics Manufacturing, Medical Devices End User: Automotive, Aerospace, Manufacturing, Hospitality Technology: Membrane Separation, Cryogenic Distillation, PSA, Others |
| Companies Covered | Hale Hamilton, Maximator GmbH, Hydrotechnik UK Ltd., HYDAC company group, Hydraulics International, Inc., Accudyne Industries, Semmco Limited, South-Tek Systems, Levapack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitrogen Filling Systems Market Shifts & Advancements
Equipment architectures are converging around modular, containerized formats that decouple generation capacity from filling station deployment, enabling nitrogen-as-a-service business models to penetrate capital-constrained buyer segments.
Membrane separation technology is migrating from food packaging applications into electronics-grade nitrogen generation, with hollow-fiber module manufacturers achieving 99.9% purity through staged cascade configurations. Semiconductor fabs in South Korea and Taiwan are piloting these systems for non-critical process steps, reserving energy-intensive cryogenic distillation for lithography and implantation zones. This migration from PSA to membrane methods is compressing the premium pricing power historically enjoyed by cryogenic equipment suppliers in the 99.5-99.99% purity band.
REACH compliance frameworks are forcing gasket and valve chemistry redesigns across European nitrogen filling system supply chains, with ECHA restrictions on perfluorinated compounds eliminating legacy PTFE sealing solutions. Manufacturers are qualifying hydrogenated nitrile butadiene rubber and thermoplastic elastomer alternatives through accelerated aging protocols. German pressure equipment fabricators report 8-12 month material requalification cycles, with F-Gas Regulation adjacency creating additional refrigerant-circuit documentation burdens for nitrogen systems with integrated cooling functions.
After-sales service contracts are unbundling from equipment sales as independent service providers acquire nitrogen generation expertise, with automotive tire chains in the United States contracting directly with regional gas distributors for maintenance and membrane replacement. This disintermediation compresses OEM aftermarket revenue pools while expanding addressable market penetration through lower total cost of ownership propositions. The Southwest US sunbelt exhibits the most advanced unbundling, where mobile nitrogen service vans operate on pure opex models without capital equipment ownership.
Nitrogen Filling Systems Market Segmentation
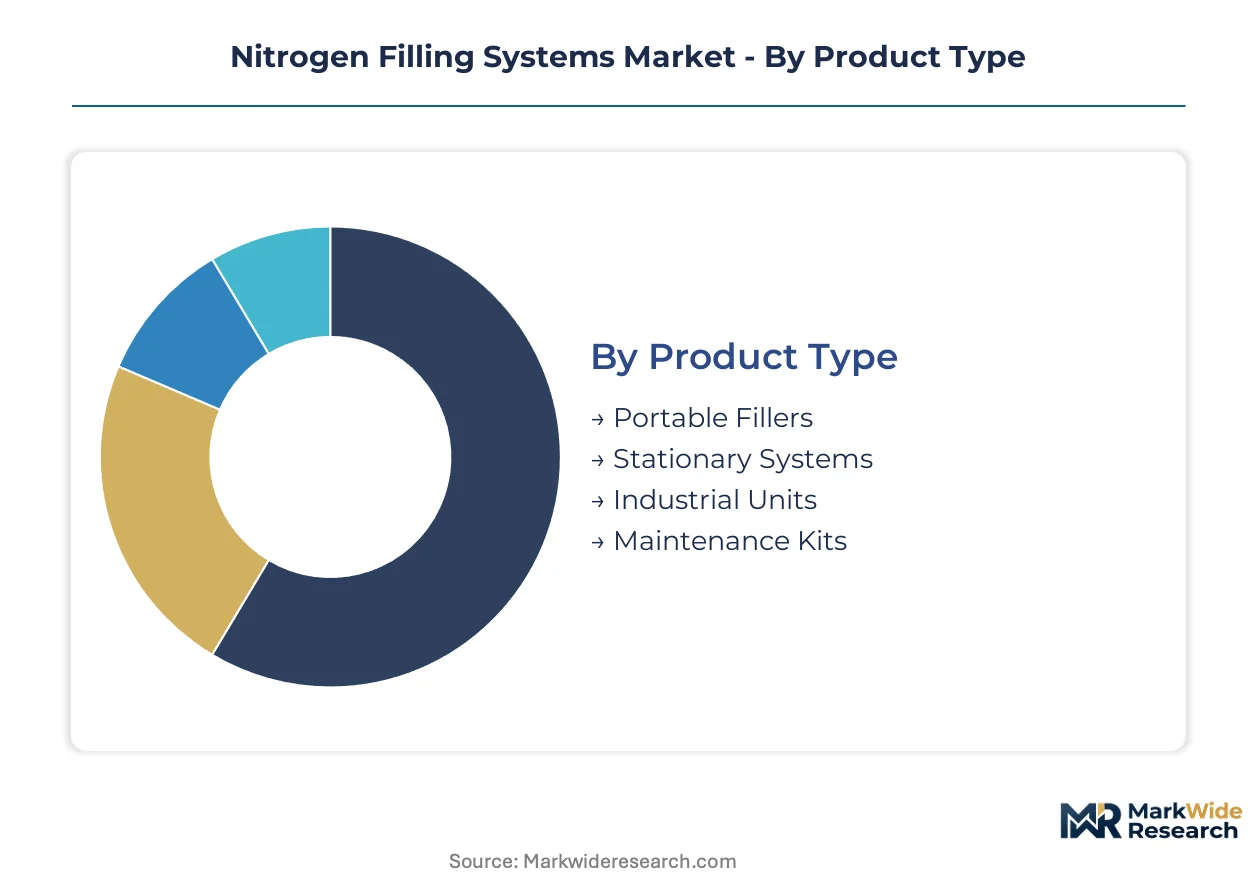
Segmentation in nitrogen filling systems reveals how purity thresholds and pressure specifications fragment equipment architectures across incompatible end-use requirements. Buyers optimize around total cost of ownership curves that diverge sharply between bulk gas substitution and precision process control applications.
Product Type:
Mature stationary platforms anchor capital-intensive continuous production, while emerging portable formats unlock mobile service economics previously inaccessible to smaller operators.
- Stationary Systems:Fixed-installation units integrate with continuous production lines at 150–300 bar operating pressure, generating the largest revenue pool due to capital intensity. German food packaging facilities are replacing legacy compressed air infrastructure with these systems to meet EU packaging waste directives.
- Portable Fillers:Mobile units mounted on service vans operate at reduced pressure ranges for tire inflation and field maintenance. Tire service chains in Brazil and Mexico are converting fixed-cost equipment into revenue-generating assets through mobile deployment models.
- Industrial Units:High-capacity modular systems designed for centralized nitrogen generation serving multiple filling stations.
- Maintenance Kits:Aftermarket component bundles for membrane replacement and valve servicing.
Stationary systems handle the majority of throughput; portable fillers are gaining share fastest through automotive aftermarket penetration.
Application:
Cost tier differentiation separates bulk displacement applications from ultra-high-purity process control, with mid-range segments experiencing the most technology disruption.
- Food & Beverage Packaging:Nitrogen flushing displaces oxygen to extend shelf life, with membrane separation achieving 99.5% purity at 40% lower energy consumption than PSA alternatives. Regional bakeries and craft breweries previously dependent on liquid bulk delivery are now adopting on-site generation.
- Electronics Manufacturing:Cleanroom environments in Shenzhen's semiconductor corridor demand 99.999% purity for wire bonding and encapsulation processes, pulling specialized service providers into Guangdong province.
- Tires Filling:Pressure maintenance applications requiring moderate purity where nitrogen density advantages justify premium pricing over compressed air.
- Medical Devices:Sterile packaging and pharmaceutical manufacturing with FDA 21 CFR Part 177 compliance requirements for nitrogen contact surfaces.
Food and beverage packaging commands the largest installed base; electronics manufacturing exhibits the steepest expansion trajectory as semiconductor fabrication concentrates in East Asian clusters.
End User:
Customer type segmentation tracks how procurement authority concentrates in integrated manufacturing groups versus distributed service networks.
- Manufacturing:Encompasses food processing, electronics fabrication, and pharmaceutical production with continuous nitrogen demand profiles.
- Automotive:Tire service chains and original equipment manufacturers deploying nitrogen for pressure stability and oxidation prevention.
- Aerospace:Heavy maintenance facilities requiring dual FAA and EASA certification for hydraulic system testing bundled with nitrogen filling services.
- Hospitality:Wine preservation and beverage dispensing applications with intermittent usage patterns favoring portable or small-scale stationary units.
Manufacturing absorbs the highest volume throughput; automotive channels are expanding most quickly through aftermarket mobility services.
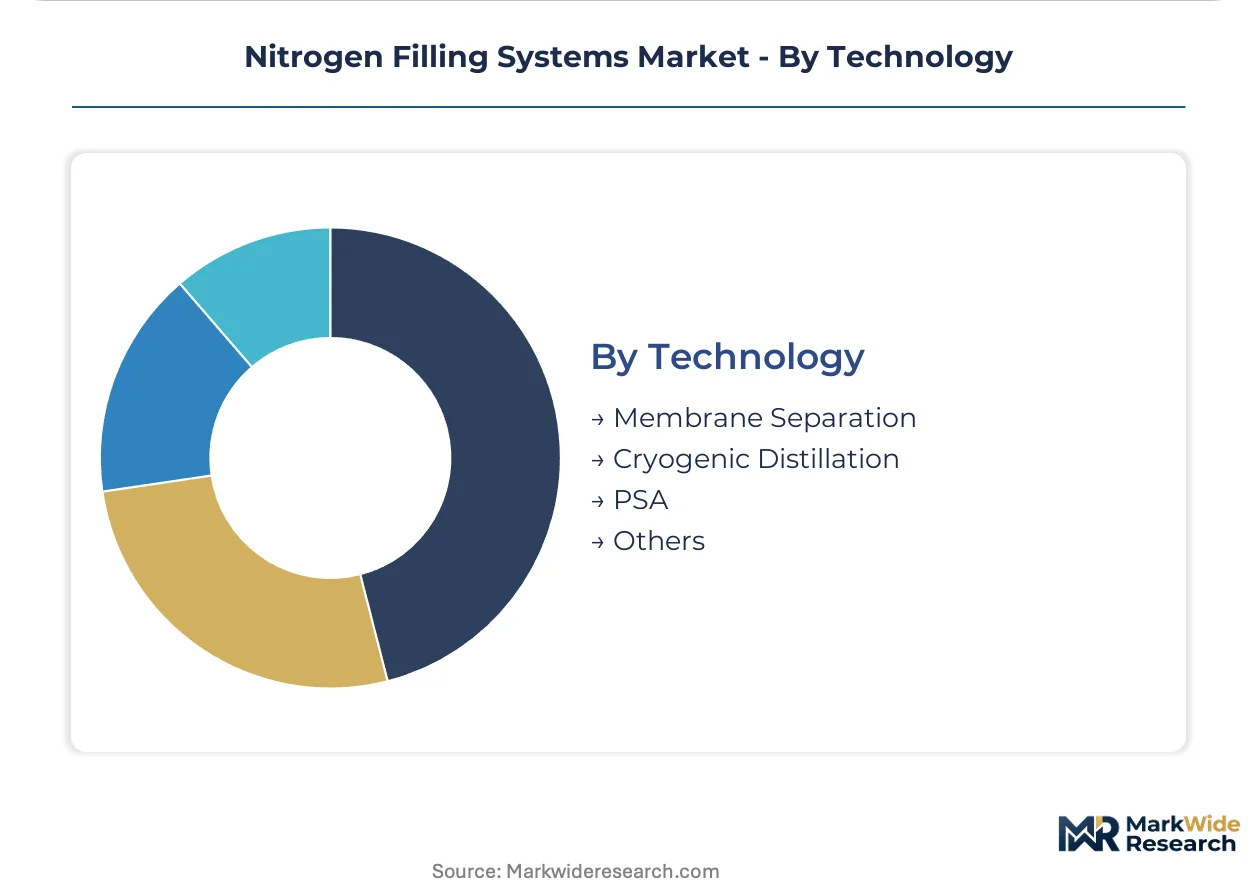
Technology:
Supply concentration in membrane module production is compressing margins for PSA incumbents and eroding cryogenic premium pricing in mid-purity bands.
- Membrane Separation:Hollow-fiber modules deliver 99.5% purity with superior energy efficiency, now migrating into electronics-grade applications through staged cascade configurations achieving 99.9% purity. South Korean and Taiwanese semiconductor fabs are piloting these systems for non-critical process steps.
- PSA:Pressure swing adsorption retains dominance in ultra-high-purity requirements above 99.99% where membrane cascades prove uneconomical.
- Cryogenic Distillation:Energy-intensive liquefaction and fractional distillation reserved for lithography and ion implantation zones requiring maximum purity.
- Others:Emerging electrochemical and adsorption technologies at pilot scale.
Membrane separation captures the fastest-growing share as energy efficiency governs total cost of ownership; cryogenic distillation retains premium positioning at the purity extreme.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's nitrogen logistics capacity, while China's coastal manufacturing belt leverages Shenzhen port infrastructure for high-purity gas equipment imports.
Germany
Food packaging lines along the Rhine corridor are retrofitting nitrogen flushing capacity to meet EU packaging waste directives. The F-Gas Regulation tightens material specifications for sealing components, compelling gasket chemistry redesigns. Bavarian processing facilities in the Munich-Stuttgart axis are absorbing membrane separation systems for regional bakery and brewery applications.
China
Shenzhen's semiconductor fabrication cluster is pulling specialized nitrogen service providers into Guangdong province for cleanroom environments. SAMR pressure equipment safety approvals require 14-18 month local testing partnerships for foreign entrants, creating asymmetric access. The Pearl River Delta electronics corridor now accounts for the steepest expansion trajectory in high-purity nitrogen demand.
United States
FDA 21 CFR Part 177 indirect food additive rules govern nitrogen contact surfaces for packaging applications, creating certification requirements divergent from European frameworks. The Southwest sunbelt exhibits advanced service unbundling, where mobile nitrogen vans operate on pure opex models. Tire service chains in Texas and Arizona are converting fixed-cost equipment into revenue-generating assets.
India
Electronics manufacturing incentives under the PLI scheme are attracting semiconductor packaging investments requiring 99.999% purity nitrogen for wire bonding. Karnataka and Tamil Nadu fabrication zones are emerging as demand centers. The country's national pharmaceutical regulator enforces material compatibility standards for medical device nitrogen applications.
South Korea
Semiconductor fabs in the Seoul Capital Area are piloting membrane separation systems for non-critical process steps, reserving cryogenic distillation for lithography zones. The national standards body coordinates with METI-aligned specifications for pressure equipment safety. Busan-Ulsan industrial complexes are integrating nitrogen generation with petrochemical process control systems.
Nitrogen Filling Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in valve and membrane module supply. The vendor base organizes around three strategic archetypes: cryogenic equipment fabricators with aerospace heritage, high-pressure stationary specialists with in-house valve production, and portable military-grade suppliers for field operations. Consolidation pressure is concentrating among membrane module manufacturers, while M&A activity targets regional service networks and technology licensing agreements for energy-efficient separation methods.
Among UK-based fabricators, Hale Hamilton and Hydrotechnik UK Ltd. occupy positions anchored in cryogenic expertise and pressure control heritage. Maximator GmbH represents the German GmbH-structured tier with high-pressure stationary system concentration. Hydraulics International, Inc. sits within the US-incorporated portable equipment segment. These three exemplify how geographic origin and corporate structure align with distinct technology archetypes across the nitrogen filling value chain.
| Leading Market Players |
|---|
| Hale Hamilton |
| Maximator GmbH |
| Hydrotechnik UK Ltd. |
| HYDAC company group |
| Hydraulics International, Inc. |
| Accudyne Industries |
| Semmco Limited |
| South-Tek Systems |
| Levapack |
| Others |
Supply & Pricing Matrix
Nickel extraction constraints in Indonesian and Philippine mining jurisdictions compress margins on high-pressure stationary systems while simultaneously widening pricing spreads between membrane-based and PSA-equipped product tiers. This commodity volatility forces buyers to weigh total cost of ownership against capital expenditure thresholds, reshaping procurement patterns across food packaging and electronics manufacturing segments.
Pricing Analysis
Volume-discount tiering structures dominate nitrogen filling system transactions, with three-tier pricing separating aerospace-grade certified units from standard industrial platforms and economy membrane configurations. Price differentiation hinges on purity certification thresholds and after-sales service bundling, with 99.999% cryogenic systems commanding substantial premiums over 99.5% membrane alternatives. Cost compression in mid-scale PSA equipment is intensifying because hollow-fiber membrane modules now deliver comparable purity at 40% lower energy consumption. Regional bakeries and craft breweries exhibit the highest price sensitivity, while semiconductor fabs in Shenzhen demonstrate minimal elasticity given process-critical purity requirements.
Supply Chain Analysis
Extended payment terms from German valve fabricators and supply-chain finance facilities from Chinese membrane module producers are restructuring working capital requirements for system integrators. Component sourcing draws from Germany for precision pressure vessels, Japan for hollow-fiber membrane substrates, and China for PLC control systems. Raw material dependencies include 316L stainless steel, Inconel alloys, and hydrogenated nitrile butadiene rubber gasket materials. Single-source vulnerability concentrates in specialized membrane module production, where two Asian suppliers control cascade-configuration intellectual property. Distribution runs through regional gas equipment distributors with certified service capabilities, particularly for FDA and EASA compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane-PSA interoperability standards and nitrogen-as-a-service platform economics are converging to create winner-take-most dynamics, with equipment architectures decoupling generation capacity from filling station deployment.
For Market Incumbents: Entrench membrane separation expertise through backward integration into hollow-fiber module production, securing supply continuity against Asian supplier concentration. Acquire regional service networks in India's PLI-aligned semiconductor corridors to capture aftermarket revenue pools disintermediated by independent providers. Prioritize ECHA-compliant gasket chemistry requalification to maintain European aerospace and food packaging access against REACH enforcement timelines. For New Entrants and Emerging Players: Mobile nitrogen service vans in Brazil and Mexico represent the most penetrable entry point, converting fixed-cost equipment into revenue-generating assets through pure opex models. Mid-scale craft breweries and regional bakeries previously dependent on liquid bulk delivery offer white-space expansion for containerized membrane systems with 99.5% purity output. Partner with automotive tire chains for maintenance and membrane replacement contracts, bypassing OEM sales channel establishment costs. For Investors and Strategic Acquirers: China's SAMR pressure equipment safety approval timelines reshapes the acquisition landscape, favoring targets with pre-certified platforms over foreign entrants facing 14-18 month local testing partnerships. Long-term viability centers on membrane technology licensing agreements and energy-efficient separation method patents rather than pure hardware fabrication. Watch for hollow-fiber cascade configuration breakthroughs achieving 99.9% purity as the signal for electronics-grade market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Module Backward Integration | Captive supply of hollow-fiber components insulates against Asian supplier concentration and nickel price volatility. |
| Nitrogen-as-a-Service Platform Launch | Containerized generation-filling decoupling enables opex-based penetration of capital-constrained regional bakeries and craft breweries. |
| EASA-FAA Dual Certification Investment | Bundled hydraulic testing and nitrogen filling contracts at heavy maintenance facilities command premium pricing power. |
| Regional Service Network Acquisition | Independent maintenance providers with SAMR pre-certification accelerate market access in China's Pearl River Delta corridor. |
| REACH-Compliant Gasket Chemistry R&D | Hydrogenated nitrile butadiene rubber alternatives secure European aerospace and food packaging market continuity. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SAMR pressure equipment filings, ECHA REACH substance restrictions, and semiconductor fab capital expenditure disclosures. Primary interviews engaged plant engineers at German food packaging facilities, procurement leads at Shenzhen electronics manufacturers, aftermarket service heads at US tire chains, and technical R&D directors at membrane module producers. Secondary validation incorporated customs data on 316L stainless steel and Inconel alloy trade flows, SEC filings from industrial gas distributors, and GB standards documentation from Chinese standardization bodies. Bottom-up equipment shipment analysis triangulated against top-down nitrogen generation capacity installations across the analysis window.
Forecast inputs include purity tier migration rates from PSA to membrane separation, energy efficiency benchmarks for hollow-fiber cascade configurations, and regional regulatory approval timelines for pressure equipment safety. Segmentation dimensions span stationary versus portable product architectures, food packaging versus electronics manufacturing applications, and membrane versus PSA versus cryogenic technology categories. CAGRs derive from installed base replacement cycles, greenfield capacity additions in India's PLI-aligned semiconductor zones, and aftermarket service contract unbundling trends in the Southwest US sunbelt.
Macroeconomic conditions sit as an overlay; deviation in nickel alloy prices, EU carbon border adjustment implementation, or China-Taiwan semiconductor trade flows would shift the trajectory. Forecasts reflect documented assumptions regarding membrane technology maturation rates and SAMR approval timeline stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Can Seamers Market
Packaging Equipment
Bagging Equipment Market
Packaging Equipment
Basket Granulator Extruder Market
Packaging Equipment
Hot Fill Packaging Market
Packaging Equipment
Bag Re-Sealer Market
Packaging Equipment
Coding and Marking Systems Market
Packaging Equipment
Multihead Weighers Market
Packaging Equipment
Loading Spout Market
Packaging Equipment
Flexible End-Load Cartoner Market
Packaging Equipment
Global Cap Applicators Market
Packaging Equipment
Shrink Wrapper Market
Packaging Equipment
Container Washing System Market
Packaging Equipment
Aerosol Dispensing Systems Market
Packaging Equipment
Bottle-Capping Equipment Market
Packaging Equipment
Shrink Wrap Sealers Market
Packaging Equipment
Packing Belt Market