
 Global Reverse Vending Machine Market | 2026-2036
Global Reverse Vending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Reverse Vending Machine Market Outlook
Aftermarket service revenue is reconfiguring margin distribution across the Global Reverse Vending Machine Market. TOMRA System ASA leverages its Nordic installed base to sustain recurring maintenance contracts. ENVIPCO anchors North American municipal contracts through long-term service agreements. Sielaff GmbH competes on component refurbishment capabilities across European retail networks.
Reverse vending machines are automated collection systems that identify, sort, and compact recyclable containers using barcode scanning, weight sensors, and material recognition algorithms, returning deposits or vouchers to consumers. Advanced Smart Machines dominate capital allocation as retailers prioritize cloud-integrated units with real-time fill monitoring. Sensor-Based Detection leads technology adoption by reducing contamination rates in high-volume supermarket installations.
The EU Green Deal and REACH framework mandate extended producer responsibility across member states, forcing retailers to install certified collection infrastructure. EPA guidelines and state-level bottle bill statutes in the US shape product specifications for deposit redemption accuracy. Stakeholders must monitor regulatory divergence between EU packaging mandates and fragmented North American state policies to calibrate regional deployment strategies.
Market Dynamics
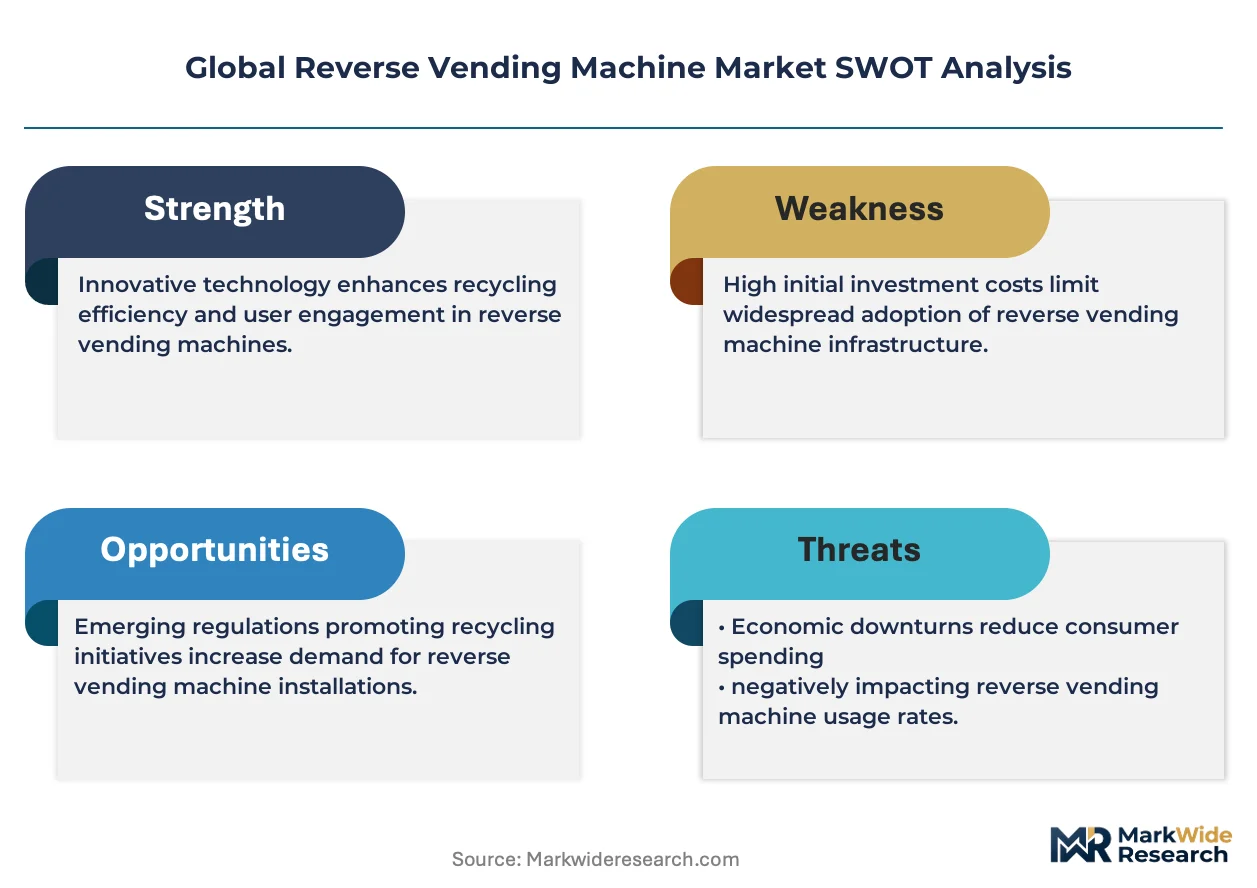
Extended producer responsibility mandates across the European Union are forcing retailers to deploy certified collection infrastructure at scale, compressing deployment timelines and reshaping competitive positioning around compliance capability rather than hardware cost alone.
Growth Catalysts
- EU Green Deal packaging mandates:Retail chains in Germany face binding collection targets that require certified reverse vending infrastructure, accelerating replacement of manual sorting systems.
- Sensor-based detection systems:Supermarket operators are prioritizing units with material recognition algorithms that reduce contamination rates below 2% in high-volume installations.
- Norway's deposit-return system:The country's decades-old extended producer responsibility framework sustains the world's highest per-capita reverse vending machine density, creating reference architecture for adjacent markets.
Market Restraints
- Stainless steel and electronic component costs:Input price volatility for industrial-grade sensors and compacting mechanisms compresses hardware margins for mid-tier equipment suppliers.
- Technical limitation in multi-material recognition:Current near-infrared systems struggle with opaque PET and multilayer cartons, forcing manual intervention that degrades throughput economics.
- Fragmented North American state policies:The absence of federal bottle legislation in the United States creates compliance complexity, with only ten states maintaining deposit-return statutes.
Strategic Opportunities
- India's emerging waste management framework:The country's Plastic Waste Management Rules are mandating extended producer responsibility for brand owners, creating first-mover advantage for equipment suppliers establishing local assembly.
- Cloud-integrated predictive maintenance:Convergence of IoT telemetry and machine learning enables remote diagnostics that reduce field service costs by 30% for fleet operators.
- Convenience store channel expansion:Small-format urban retail in Japan and South Korea represents underpenetrated deployment terrain as deposit systems expand beyond supermarkets.
Industry Challenges
- Embedded systems engineering talent scarcity:Firmware development for real-time image recognition and mechanical synchronization lags hardware production capacity across European and North American vendor bases.
- Certification timeline compression:EU type-approval for new detection algorithms under the Packaging and Packaging Waste Regulation requires 12-18 month validation cycles that delay product launches.
- Legacy POS integration complexity:Retailers operating heterogeneous checkout architectures face middleware development costs that erode project ROI on retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Reverse Vending Machine Market |
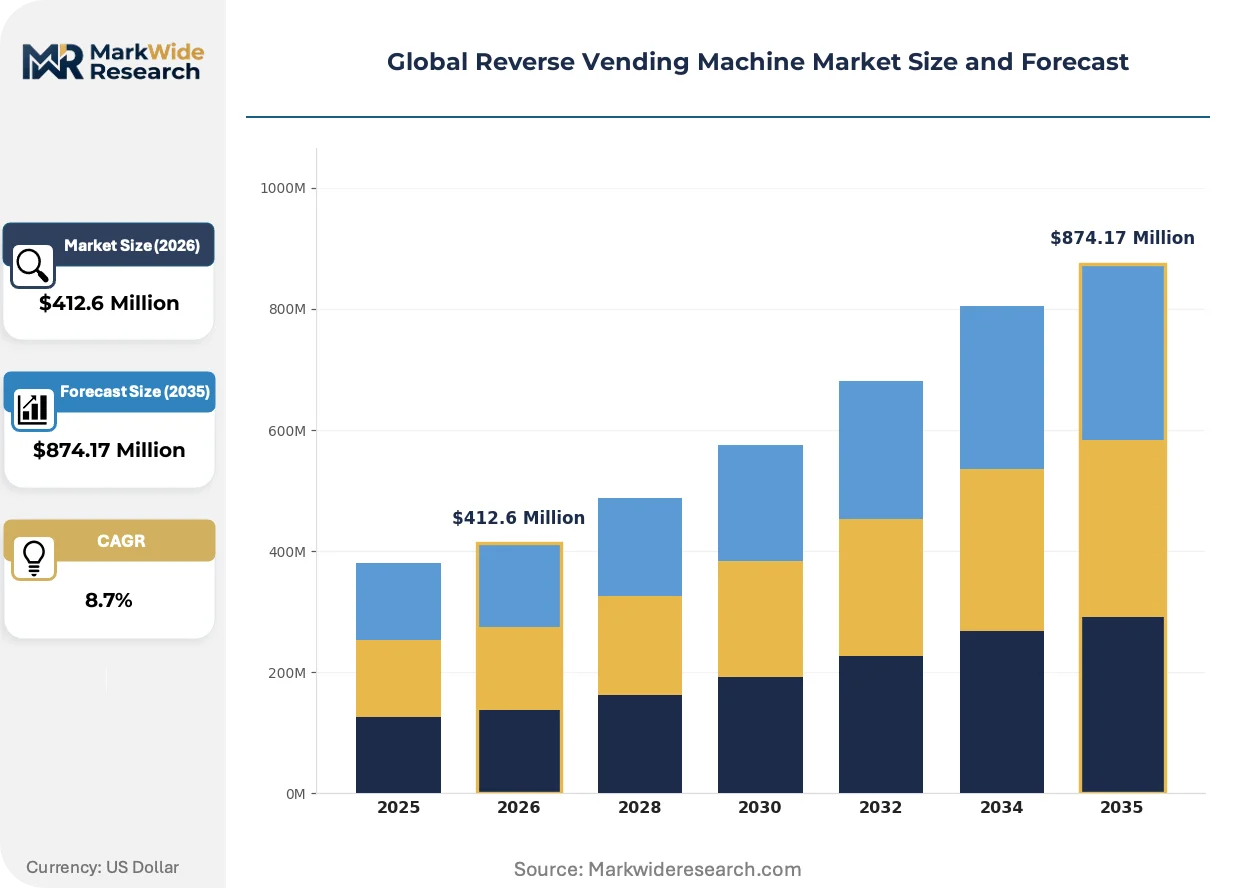
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Machines, Advanced Smart Machines, Mobile Reverse Vending, Compact Units End User: Retail Chains, Supermarkets, Educational Institutions, Municipalities Technology: Automated Collection, Sensor-Based Detection, Cloud Integration, Mobile App Connectivity Installation Type: Indoor Installation, Outdoor Installation, Semi-Permanent, Portable Solutions |
| Companies Covered | Veolia, Sielaff GmbH, TOMRA System ASA, Kansmacker Mfg, ACO Recycling, ENVIPCO, Diebold Nixdorf, AKE Environmental, RVM Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Reverse Vending Machine Market Strategic Shifts
Machine vision and artificial intelligence are fundamentally altering how containers are identified, sorted, and processed, shifting competitive advantage from mechanical engineering to software-defined recognition systems and data-driven fleet optimization.
Near-infrared spectroscopy combined with 3D depth cameras is migrating from premium supermarket installations to mid-tier convenience store deployments as sensor costs decline 40% over three generations. German retail chains are now specifying these units as baseline requirements for new store builds. The technology is migrating from high-throughput flagship locations to distributed urban networks, compressing the addressable market for legacy barcode-only machines.
The EU Green Deal's Packaging and Packaging Waste Regulation mandates 90% collection rates for plastic bottles by 2029, forcing retailers to prioritize equipment with real-time fill monitoring and cloud-based compliance reporting. This industrial consequence accelerates replacement cycles for machines lacking telemetry capabilities. Supermarket operators in France and Italy are responding by bundling hardware procurement with decade-long service contracts that guarantee uptime and regulatory documentation.
Buying committees at major retail chains are consolidating vendor relationships from multi-supplier configurations to single-source fleet agreements that bundle equipment, maintenance, and data analytics. This pattern displaces the traditional transactional hardware sale with subscription-based outcome contracts. The shift is most visible in Nordic markets where TOMRA's installed base creates switching costs that competitors struggle to overcome.
Global Reverse Vending Machine Market Segmentation
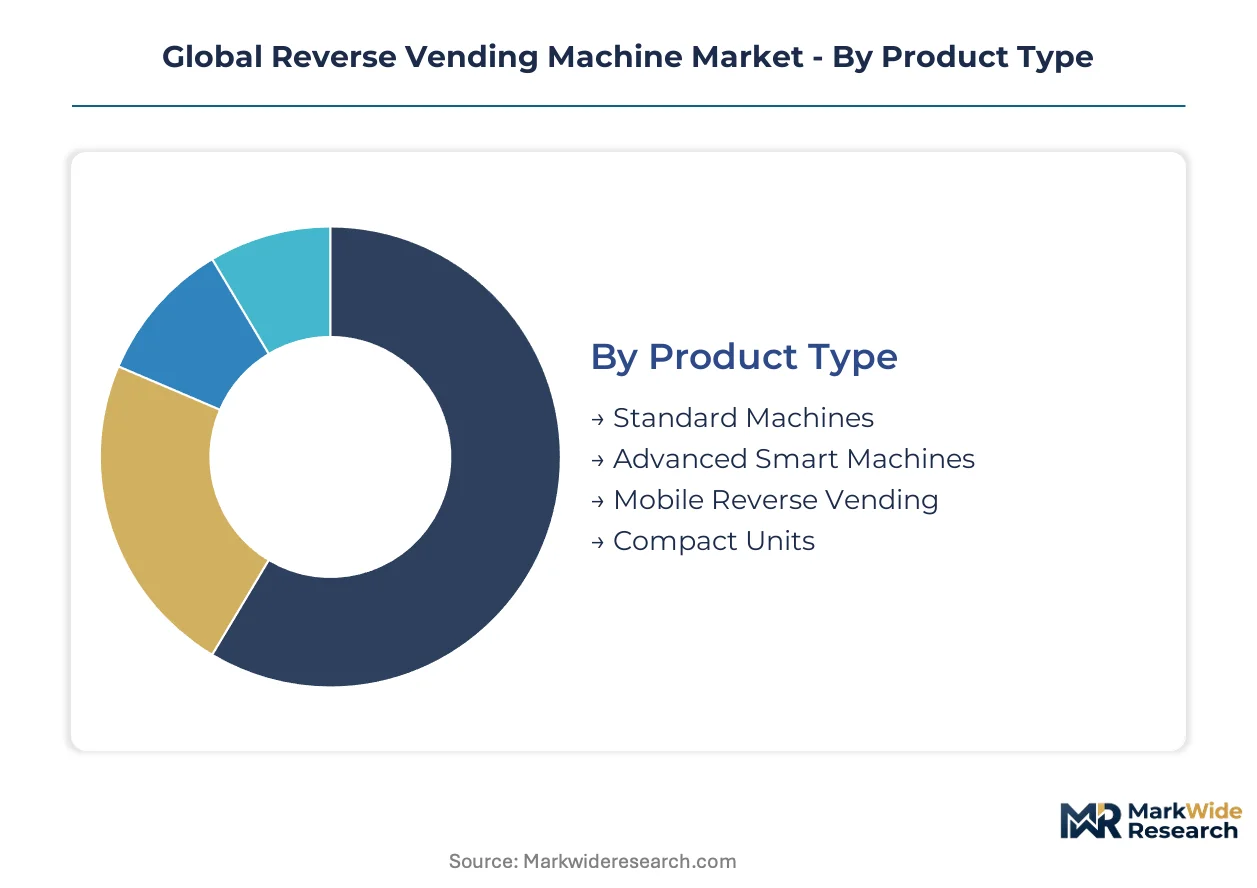
Segmentation in reverse vending machines reveals how capital allocation splits between compliance-driven hardware and software-enabled service models. Equipment specifications diverge sharply across retail formats and regulatory environments.
Product Type:
Cost tier determines procurement patterns as retailers balance upfront capital against operational efficiency and regulatory certification requirements.
- Advanced Smart Machines:These units integrate near-infrared spectroscopy, 3D depth cameras, and cloud telemetry for real-time fill monitoring. German retail chains specify these as baseline for new store builds under EU Green Deal mandates. The steepest expansion runs through this tier as compliance deadlines compress replacement cycles.
- Standard Machines:Barcode scanning and weight-based detection systems serve cost-sensitive deployments in secondary retail locations. Municipalities in deposit-return states with older infrastructure prioritize these units for budget-constrained retrofits.
- Mobile Reverse Vending:Trailer-mounted units enable temporary collection at festivals, construction sites, and seasonal retail locations. Norway's deposit system operators deploy these for rural coverage expansion.
- Compact Units:Space-constrained convenience stores in Japan and South Korea adopt countertop or wall-mounted configurations with reduced throughput capacity.
Advanced Smart Machines command the established base. The steepest expansion runs through Mobile Reverse Vending.
End User:
Application context shapes specification requirements as throughput demands and integration complexity vary across facility types.
- Retail Chains:National operators require fleet-standardized equipment with centralized compliance reporting and unified service contracts. France's supermarket consolidation drives multi-hundred-unit procurement events.
- Supermarkets:High-volume locations demand 60+ container per minute throughput with sub-2% contamination rates. Sensor-based detection systems anchor these specifications.
- Educational Institutions:Universities in California and New York deploy units as sustainability infrastructure with student engagement dashboards. Lower duty cycles permit refurbished equipment.
- Municipalities:City governments in Michigan and Oregon operate redemption centers serving non-retail collection points. These installations prioritize durability over recognition sophistication.
Retail Chains command the established base. The steepest expansion runs through Educational Institutions.
Technology:
Maturity curves separate proven mechanical systems from emerging digital layers that enable predictive maintenance and compliance automation.
- Sensor-Based Detection:Near-infrared spectroscopy combined with machine vision algorithms identifies material composition regardless of barcode condition. This technology is displacing legacy scanning in EU-certified installations.
- Cloud Integration:Telemetry-enabled units transmit fill levels, error codes, and transaction logs to centralized fleet management platforms. Operators in Norway leverage this capability for dynamic route optimization of collection logistics.
- Automated Collection:Mechanical compaction and sorting systems remain the foundational layer across all product tiers. Stainless steel construction and brushless motors define reliability benchmarks.
- Mobile App Connectivity:Consumer-facing interfaces enable digital deposit redemption and loyalty program integration. South Korean convenience stores pilot these features for demographic targeting.
Automated Collection commands the established base. Cloud Integration is climbing the fastest.
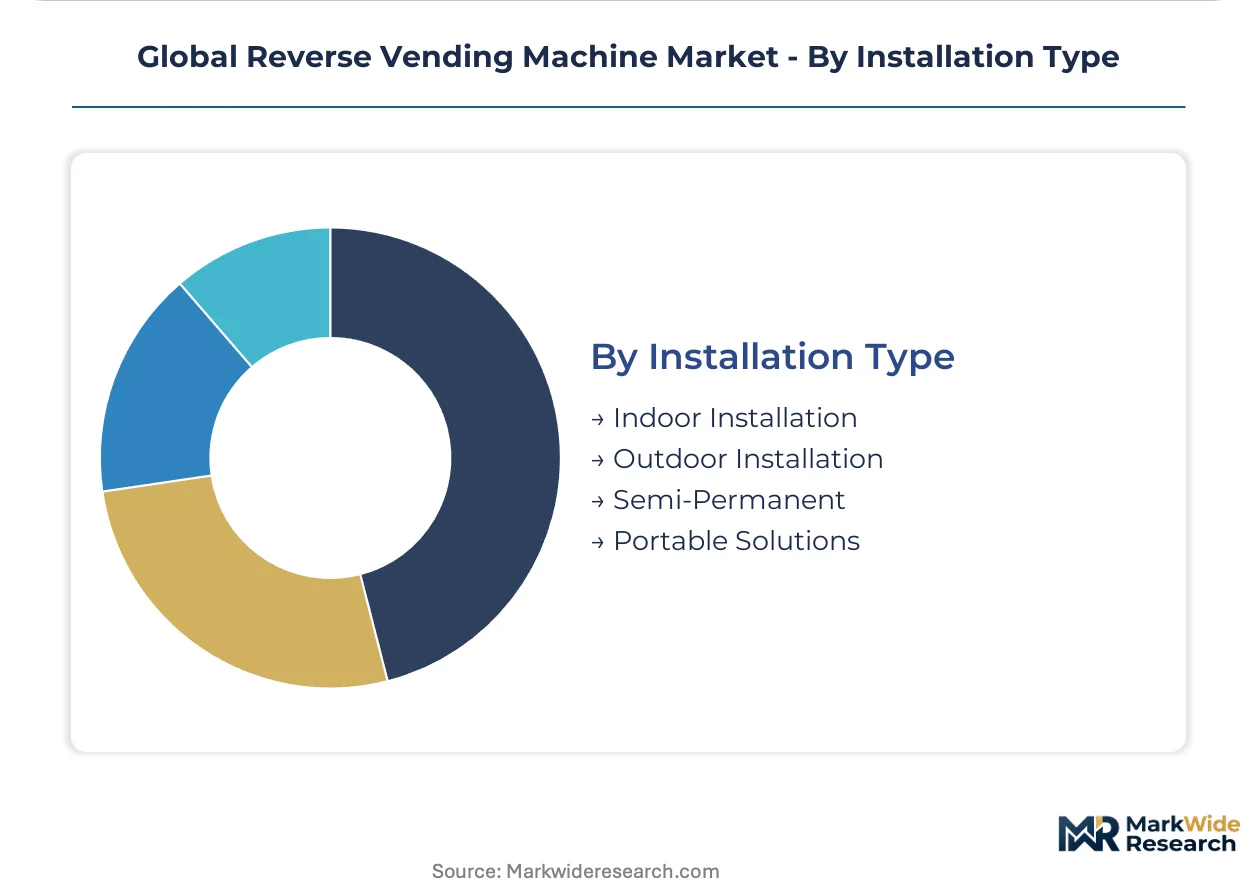
Installation Type:
Volume and permanence expectations dictate enclosure specifications, power requirements, and anchoring systems.
- Indoor Installation:Climate-controlled environments permit lighter enclosure materials and standard electrical connections. German supermarkets favor these configurations for customer-facing placement near checkout zones.
- Outdoor Installation:Weatherproofing to IP65 standards, heating elements, and vandal-resistant housings serve Nordic petrol stations and North American strip mall locations.
- Semi-Permanent:Modular foundations allow seasonal relocation for retail parking lot programs and agricultural collection events. These units balance durability with transportability.
- Portable Solutions:Battery-powered or solar-capable units support disaster response and remote community access programs in rural Canada and Alaska.
Indoor Installation commands the established base. Outdoor Installation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany demonstrate the lowest price elasticity as EU Green Deal compliance deadlines override capital constraints, while municipal purchasers in the United States exhibit acute sensitivity to upfront equipment costs amid fragmented state-level policy support.
Germany
Retail chains face binding collection targets under the EU Green Deal packaging mandates, forcing accelerated replacement of manual sorting infrastructure. The Packaging and Packaging Waste Regulation requires certified reverse vending infrastructure at all major retail locations. Berlin and Hamburg anchor the densest deployment clusters as supermarket operators consolidate vendor relationships under decade-long service contracts.
Norway
The world's highest per-capita reverse vending machine density sustains demand through decades-old extended producer responsibility frameworks. TOMRA System ASA anchors compliance infrastructure across the national deposit-return system. Oslo and Bergen retail networks operate as reference architecture for adjacent Nordic markets evaluating similar policy frameworks.
United States
Municipal redemption centers in Michigan and Oregon prioritize durability over recognition sophistication as only ten states maintain deposit-return statutes. EPA guidelines and state-level bottle bill statutes shape product specifications for deposit redemption accuracy. California and New York universities deploy units as sustainability infrastructure with student engagement dashboards.
Japan
Small-format urban retail in Tokyo and Osaka represents underpenetrated deployment terrain as deposit systems expand beyond supermarkets. METI guidelines on resource circulation influence equipment specifications for convenience store channels. The Kanto region pilots consumer-facing mobile app connectivity for digital deposit redemption and demographic targeting.
India
Brand owners face mandated extended producer responsibility under the Plastic Waste Management Rules, creating first-mover advantage for equipment suppliers establishing local assembly. BIS certification requirements for imported electronics shape procurement timelines. Maharashtra and Gujarat industrial corridors concentrate pilot deployments as municipal corporations test collection logistics.
Global Reverse Vending Machine Market Competitive Environment
Integrated solution providers and component specialists split the market along the hardware-service boundary. The vendor base concentrates around Nordic engineering heritage and North American municipal contracting capability. Three archetypes dominate: full-stack platform operators with captive service networks, precision mechanics fabricators with refurbishment expertise, and regional assembly specialists with cost-optimized configurations. Geographic expansion through local assembly partnerships and technology licensing for sensor integration represent the dominant competitive moves.
Among Nordic-anchored platform operators, TOMRA System ASA and ENVIPCO occupy positions that exemplify contrasting geographic specialization—one leveraging installed base density for recurring maintenance contracts, the other anchoring North American municipal relationships through long-term service agreements. Sielaff GmbH represents the European precision mechanics archetype with component refurbishment capabilities across retail networks. These three entities illustrate how competitive advantage migrates from hardware production toward compliance documentation and uptime guarantees.
| Leading Market Players |
|---|
| Veolia |
| Sielaff GmbH |
| TOMRA System ASA |
| Kansmacker Mfg |
| ACO Recycling |
| ENVIPCO |
| Diebold Nixdorf |
| AKE Environmental |
| RVM Systems |
| Others |
Value Chain & Pricing Dynamics
The Hamburg-Rotterdam container corridor shapes cost dynamics across the Global Reverse Vending Machine Market, concentrating supply leverage with Nordic precision mechanics fabricators while forcing German retail chains to absorb freight premiums that widen price differentiation between cloud-integrated and legacy barcode-only tiers.
Pricing Analysis
Aftermarket service revenue tiers anchor lifetime value calculations as equipment suppliers compete through decade-long maintenance contracts rather than hardware margins alone. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under EU Green Deal mandates and volume scale of fleet procurement events. Cost compression in mid-tier sensor modules is intensifying because near-infrared component costs declined across three generations. Municipal redemption centers in Michigan exhibit acute price sensitivity, while Berlin supermarket operators demonstrate minimal elasticity as compliance deadlines override capital constraints.
Supply Chain Analysis
Export-control regimes restricting dual-use machine vision technology limit flows of 3D depth camera modules from certain jurisdictions, constraining sensor sourcing options for EU-certified installations. Manufacturing concentrates in Germany, Norway, and Japan, drawing from stainless steel feedstock, brushless motor assemblies, and industrial-grade optical sensors. Single-source vulnerability runs through compacting mechanism fabricators in Central Europe. Distribution runs through captive service networks anchored by TOMRA and ENVIPCO rather than third-party logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against deposit-return system alternatives including curbside collection bins and manual redemption centers that threaten machine-based infrastructure economics.
For Market Incumbents: Insulate installed base density through backward integration into sensor module refurbishment capabilities, locking in recurring maintenance contracts that create switching costs against emerging cloud-native competitors. Prioritize certification investment under EU Packaging and Packaging Waste Regulation timelines to compress rival product launch windows. For New Entrants and Emerging Players: Establish a beachhead in India's municipal corporation pilot programs as Plastic Waste Management Rules enforcement creates first-mover terrain before TOMRA scales local assembly. Target educational institutions in California and New York with student-engagement dashboard features as a differentiated go-to-market angle against legacy municipal contractors. For Investors and Strategic Acquirers: Component refurbishment specialists with European retail network relationships represent the most attractive acquisition archetype, capturing recurring revenue streams without hardware production capital intensity. Monitor BIS certification timeline compression in India as the inflection signal for regional supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Telemetry Integration | Enables real-time compliance reporting under EU Green Deal Packaging and Packaging Waste Regulation mandates. |
| Local Assembly Partnerships | Bypasses BIS certification delays in India while establishing service network proximity to Maharashtra industrial corridors. |
| Sensor Cost Reduction Programs | Near-infrared component declines accelerate migration of 3D depth camera systems to mid-tier convenience store deployments. |
| Decade-Long Service Contracts | Transforms transactional hardware sales into subscription-based outcome agreements with French supermarket consolidation. |
| Predictive Maintenance Platforms | Converges IoT telemetry with machine learning to reduce field service costs for Norwegian fleet operators. |
Study Parameters
A standing panel of supermarket operations directors, municipal redemption center managers, OEM procurement leads, and aftermarket service heads provided ongoing calibration across primary interview rounds, cross-checked against EU regulatory filings, EPA state-level bottle bill statutes, customs trade data, and SEC equipment supplier disclosures. Bottom-up unit deployment tracking triangulated with top-down market sizing derived from retail chain capex announcements and extended producer responsibility compliance timelines.
Scenario-bracketing framed analytical outputs across the analysis window, modeling volume and value trajectories by product tier, end-user category, technology maturity curve, and installation permanence type. CAGRs emerged from regression analysis against deposit-return system penetration rates and sensor cost decline curves, with regulatory deadline compression serving as the primary demand-pull input alongside fleet replacement cycle data.
Macroeconomic conditions sit as an overlay; deviation in stainless steel input costs and freight rates on the Hamburg-Rotterdam corridor would shift the trajectory. Forecasts reflect assumptions around EU Green Deal enforcement consistency and state-level US bottle bill expansion. Material shifts in India's Plastic Waste Management Rules implementation pace or EU type-approval timeline compression would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Packaging Racks Market
Packaging Equipment
Can Seamers Market
Packaging Equipment
Powder Dispenser Market
Packaging Equipment
Retail Press Dispenser Pump Market
Packaging Equipment
Label Converting Equipment Market
Packaging Equipment
Volumetric Filing Lines Market
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Flatbed Die Cutters Market
Packaging Equipment
Semi-Automatic and Manual Filling Equipment Market
Packaging Equipment
Corrugated Equipment Market
Packaging Equipment
Strap Dispenser Market
Packaging Equipment
Table Top Band Sealer Market
Packaging Equipment
Global 2-Shot Injection Molding Market
Packaging Equipment
Global Shrink Sleeve Applicator Market
Packaging Equipment
Dispensing Sprayers Market
Packaging Equipment
Refrigerated Display Cases Market