
 Spray Fluxer Market | 2026-2036
Spray Fluxer Market Size, Share, and Industry Trends Forecast 2026-2036
Spray Fluxer Market Analytics
Asset-light leasing models for precision coating equipment is reconfiguring competitive entry barriers in the spray fluxer sector. Sono-Tek leverages ultrasonic atomization expertise to anchor its position in high-mix electronics assembly. Kurtz Ersa sustains German engineering credibility through in-house production of selective soldering and fluxing systems. Nordson Corporation dominates fluid dispensing technology and extends that control into integrated spray fluxer architectures for automotive tier-one suppliers.
A spray fluxer is an industrial coating device that atomizes liquid flux—typically alcohol-based, water-based, or rosin-activated formulations—onto printed circuit boards or metal surfaces prior to soldering, with nozzle pressures ranging from 15 to 60 psi and droplet sizes controlled between 10 and 50 microns to ensure uniform wetting without bridging. Its primary purpose is to reduce surface oxide, promote solder alloy flow, and minimize defect rates in high-density interconnect assemblies. Water-based flux formulations now lead volume shipments as OEMs phase out volatile organic compound carriers, while solvent-based chemistries retain margin concentration in aerospace component applications where MIL-STD-202G compliance demands aggressive oxide removal. Electronics assembly absorbs the dominant share of unit demand, though automotive manufacturing represents the fastest-growing application as electric vehicle inverter boards multiply layer counts and thermal management requirements.
The EPA enforces National Emission Standards for Hazardous Air Pollutants on electronics manufacturing solvents, while REACH restricts rosin acid derivatives in European flux imports, and China's MEE implements GB standards on industrial volatile organic compound discharge limits. These frameworks compel formulation houses to recertify product lines and push contract manufacturers toward closed-loop spray recovery systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned R&D spending on incompatible chemistries.
Market Dynamics
Water-based flux chemistry conversion is compressing equipment replacement cycles as contract manufacturers face dual pressure from EPA NESHAP enforcement and REACH substance restrictions on rosin derivatives.
Growth Catalysts
- Electric vehicle inverter board proliferation:Automotive OEMs in Germany and China are scaling multi-layer PCB production, forcing tier-one suppliers to upgrade spray fluxer throughput capacity for thermal management substrates.
- REACH Article 33 compliance deadlines:European electronics assemblers are retiring solvent-based flux systems ahead of 2027 substance restriction phases, redirecting capital toward closed-loop water-based spray architectures.
- Ultrasonic atomization maturation:Precision electronics manufacturers in South Korea are adopting nozzle technologies that achieve sub-20-micron droplet consistency, reducing bridging defects in 01005 component placements.
Market Restraints
- Isopropanol price volatility:Residual solvent-based flux formulations remain exposed to petrochemical feedstock swings, compressing margin stability for aerospace-grade product lines.
- Nozzle supplier concentration in southern Germany:Precision atomization component sourcing clusters around Stuttgart-area machining networks, creating geographic vulnerability for Asian equipment assemblers.
- Water-based flux drying energy intensity:Infrared cure requirements add 15-25% cycle time versus alcohol carriers, limiting adoption in high-velocity consumer electronics lines.
Strategic Opportunities
- India electronics manufacturing clusters:PLI scheme incentives for semiconductor packaging are attracting greenfield PCB assembly investments in Gujarat and Tamil Nadu, creating first-mover equipment positioning windows.
- Asset-light leasing models:Precision coating equipment lessors are penetrating mid-tier contract manufacturers previously priced out of automated fluxing, converting CapEx to OpEx for Shenzhen and Penang facilities.
- ISO 14001-driven supplier mandates:Automotive tier-one certification requirements are filtering down to second-tier flux applicators, advantaging vendors with verified volatile organic compound recovery systems.
Industry Challenges
- Process engineer scarcity:Expertise in spray pattern optimization for high-density interconnect substrates concentrates among aging technicians in Japanese and German equipment service networks.
- Legacy conveyor integration:Retrofitting ultrasonic spray heads into 1990s-era wave soldering lines demands mechanical customization that extends commissioning timelines by 8-12 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spray Fluxer Market |
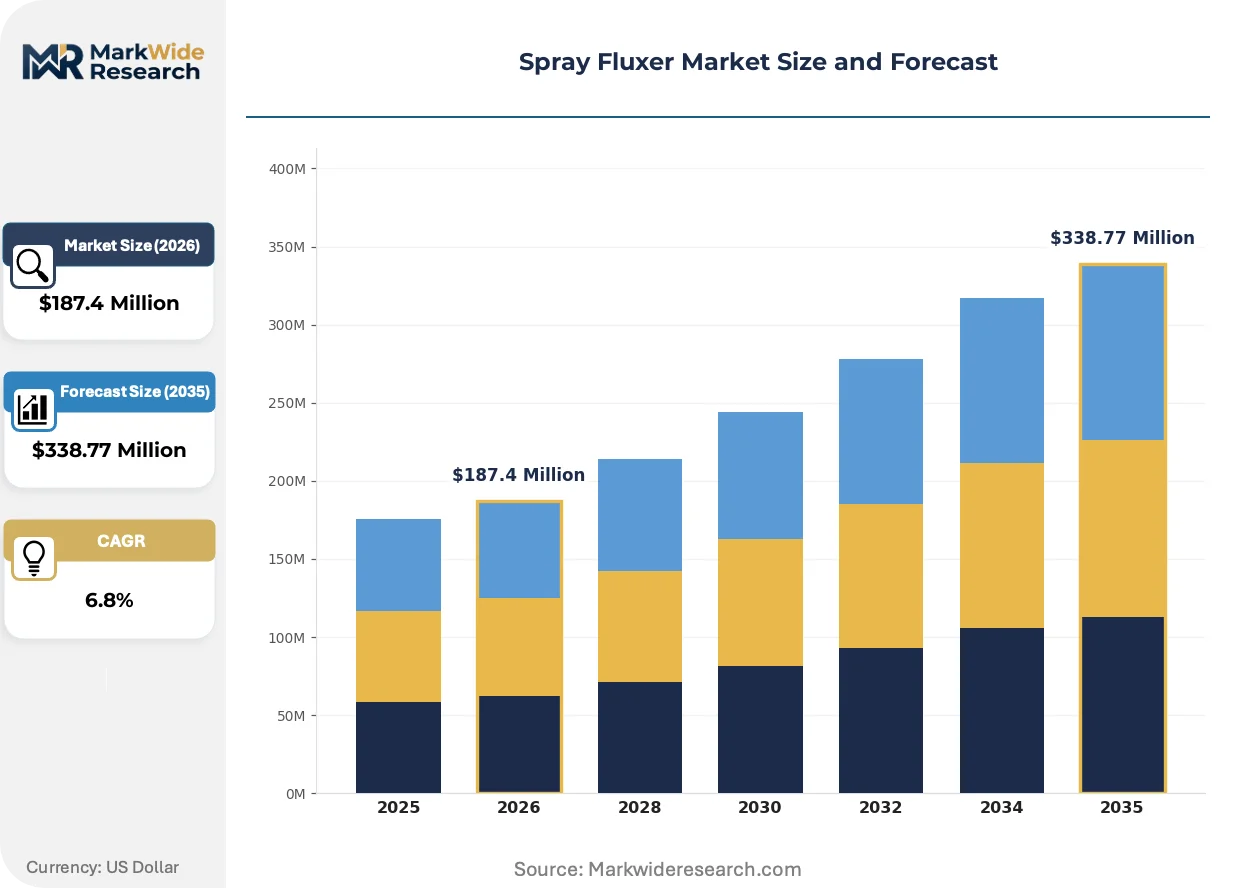
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Rosin-Based, Other Application: Electronics Assembly, Automotive Manufacturing, Metal Fabrication, Aerospace Components End User: OEMs, Contract Manufacturers, Repair Services, Maintenance Providers Packaging Type: Aerosol Can, Drum, Bulk Container, Others |
| Companies Covered | Nordson Corporation, SENJU METAL INDUSTRY, Kurtz Ersa, Sono-Tek, Tamura, TMPL Machines, KOKI, National Solbot, Henkel AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spray Fluxer Market Evolving Landscape
Atomization control systems are converging with inline inspection feedback, enabling real-time flux deposition adjustment that reduces over-application waste and rework rates in high-mix assembly environments.
Ultrasonic spray technology is hybridizing precision coating and selective fluxing functions into single-platform architectures. Automotive PCB manufacturers in Stuttgart and Wolfsburg are piloting these dual-mode systems for electric powertrain control modules. The convergence is compressing floor space requirements and consolidating supplier relationships for tier-one electronics assemblers.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is tightening solvent recovery documentation requirements for US-based contract manufacturers. Electronics assemblers in Texas and California are deploying closed-loop spray fluxer configurations with carbon adsorption units to maintain operating permits. Aerospace component suppliers remain the most exposed segment due to MIL-STD-202G compliance demands that resist water-based formulation substitution.
Buyer consolidation among top-five electronics manufacturing services providers is concentrating procurement leverage and compressing equipment refresh cycles. Tier-two assemblers in Malaysia and Vietnam are responding through cooperative purchasing consortia that aggregate volume for standardized spray fluxer configurations. The shift is most visible in consumer electronics where annual model turnover demands rapid line reconfiguration capability.
Spray Fluxer Market Segmentation
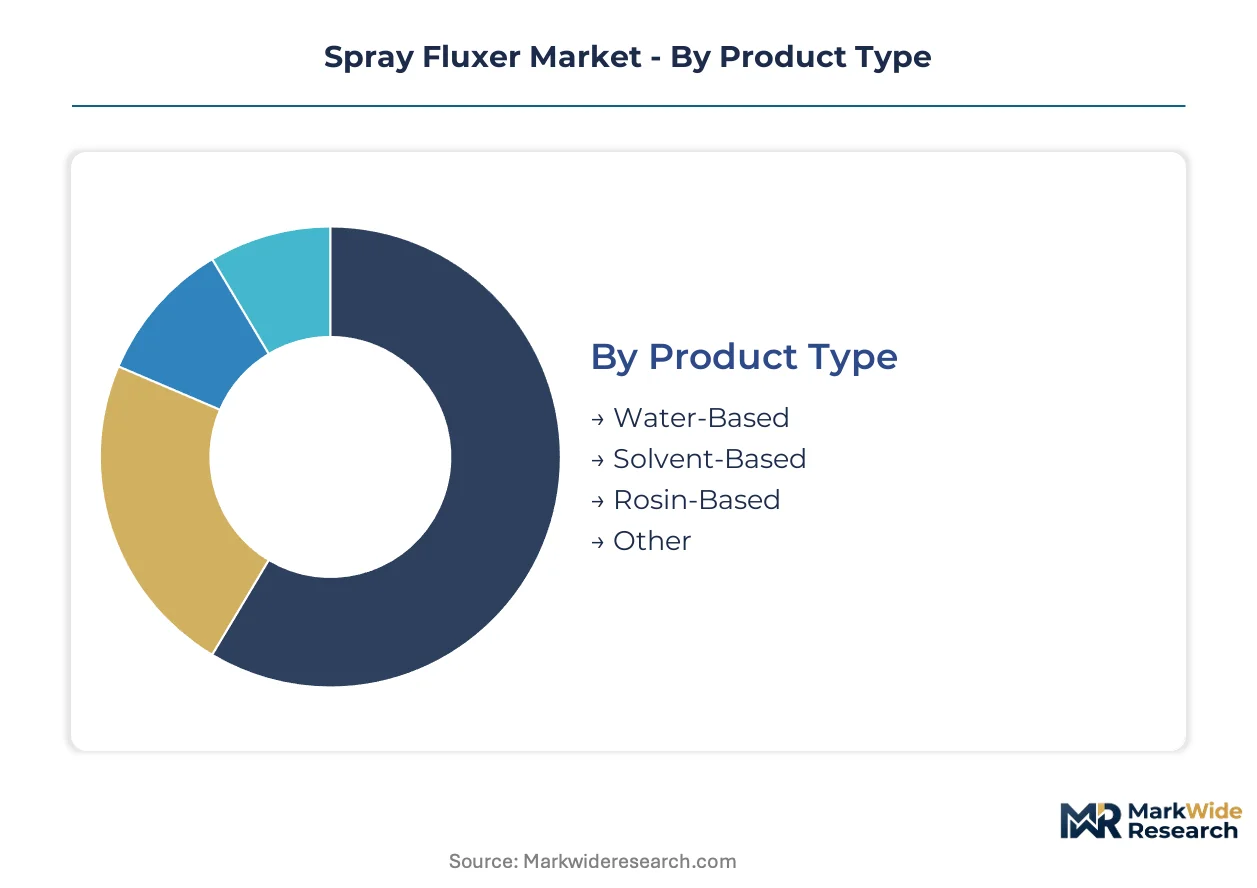
Spray fluxer segmentation reveals distinct replacement rhythms across chemistry types, with water-based formulations driving equipment turnover while solvent-based systems linger in legacy aerospace installations. Understanding these velocity differentials helps suppliers align inventory and service networks to actual demand pulses rather than aggregated forecasts.
Product Type:
Cycle times vary dramatically by carrier chemistry, with water-based systems refreshing every 3-5 years under EPA NESHAP pressure while rosin-based equipment persists 8-12 years in unregulated maintenance shops.
- Water-Based:Formulations suspend activator chemistry in deionized water carriers, eliminating volatile organic compound emissions at point of application. Tier-one automotive suppliers in Germany and China are standardizing on these systems to meet REACH Article 33 and MEE discharge limits, accepting 15-25% longer infrared cure cycles as the compliance cost.
- Solvent-Based:Alcohol or glycol-ether carriers deliver aggressive oxide removal through rapid evaporation kinetics. Demand concentrates in US aerospace component facilities where MIL-STD-202G compliance mandates resist water-based substitution despite EPA enforcement tightening in Texas and California.
- Rosin-Based:Natural pine-derived fluxes with halide activators persist in legacy wave soldering lines. Repair services in Southeast Asia maintain stocked inventories for 1990s-era equipment.
- Other:Synthetic low-residue and no-clean formulations serve specialty high-frequency RF assemblies. South Korean telecommunications equipment OEMs specify these for 5G base station production.
Water-Based anchors the volume base while Solvent-Based retains margin concentration in aerospace applications.
Application:
End-use economics separate high-velocity consumer electronics lines from capital-intensive automotive powertrain investments, with each segment demanding incompatible flux deposition specifications.
- Electronics Assembly:High-mix contract manufacturing absorbs the dominant equipment deployment, with Shenzhen and Penang facilities running 24-hour cycles on ultrasonic atomization platforms. Consumer electronics model turnover compresses line reconfiguration windows to 6-8 weeks.
- Automotive Manufacturing:Electric vehicle inverter boards multiply layer counts and thermal substrate complexity. Stuttgart and Wolfsburg OEMs are piloting dual-mode selective fluxing systems that consolidate precision coating and spray functions.
- Metal Fabrication:Galvanized steel pretreatment for HVAC ducting and architectural panels employs bulk spray fluxers with 40-60 psi nozzle pressures. US Midwest fabricators favor drum-fed systems for continuous coil processing.
- Aerospace Components:Defense and satellite electronics demand rosin-activated formulations with documented lot traceability. Suppliers face dual pressure from MIL-STD compliance and emerging EPA solvent recovery documentation requirements.
Electronics Assembly commands the installed base while Automotive Manufacturing climbs fastest on EV powertrain electrification.
End User:
Procurement sophistication separates multinational OEMs with ISO 14001-mandated supplier audits from fragmented maintenance providers purchasing through distributor channels.
- OEMs:Automotive and telecommunications equipment manufacturers specify closed-loop spray recovery systems with carbon adsorption units. Their procurement leverage concentrates volume with 3-4 approved equipment vendors.
- Contract Manufacturers:Foxconn, Jabil, and Flex operate global equipment standardization programs that compress regional supplier margins. Their cooperative purchasing consortia in Malaysia and Vietnam aggregate mid-tier assembler demand.
- Repair Services:Independent PCB rework shops purchase aerosol can flux for manual touch-up operations. Price sensitivity drives private-label sourcing through Shenzhen distributors.
- Maintenance Providers:Industrial facility contractors service legacy wave soldering lines with replacement nozzle assemblies. Their demand concentrates in southern Germany machining networks around Stuttgart.
Contract Manufacturers drive standardization while OEMs push specification upgrades fastest.
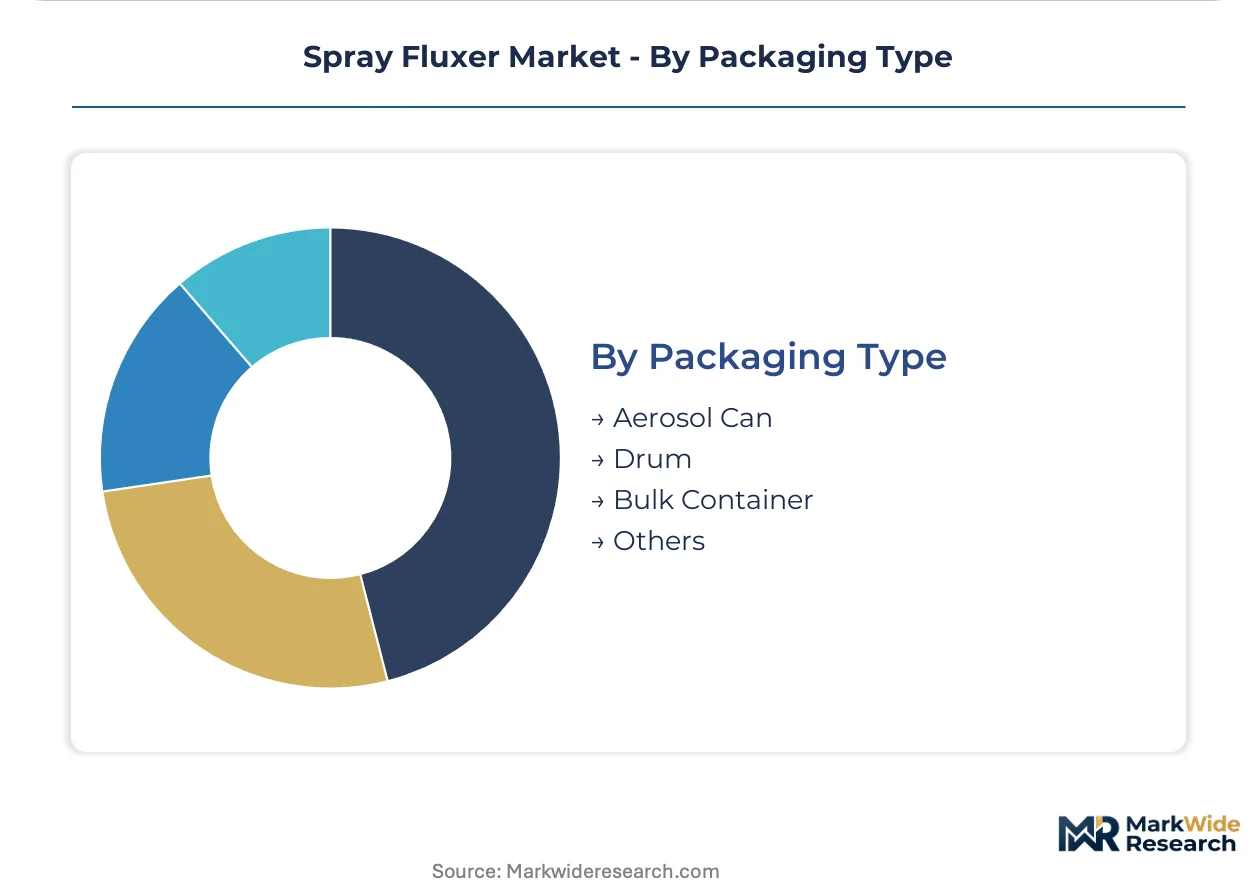
Packaging Type:
Container economics mirror customer scale, with bulk systems serving continuous production and aerosol formats penetrating intermittent maintenance demand.
- Aerosol Can:Pressurized dispensers serve field repair technicians and prototype labs requiring portability. South Korean electronics R&D facilities standardize on 400ml canisters for benchtop soldering stations.
- Drum:55-gallon steel containers supply mid-volume contract manufacturers with weekly flux consumption. German automotive tier-one suppliers specify UN-certified drums with integrated pump systems.
- Bulk Container:IBC totes and tanker deliveries feed high-velocity surface mount technology lines in China and Vietnam. Closed-loop returnable container programs reduce per-liter logistics costs.
- Others:Cartridge systems for automated selective fluxing heads and sample vials for process qualification labs complete the packaging matrix.
Drum and Bulk Container formats dominate commercial volume while Aerosol Can maintains penetration in repair channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net flux formulation trade flows from Germany, China, and South Korea toward electronics assembly clusters in Vietnam and Mexico, while equipment exports concentrate in German and US precision engineering corridors. Import dependency for atomization components creates vulnerability for Southeast Asian contract manufacturers sourcing from Stuttgart-area machining networks.
China
Electric vehicle inverter board production in Shenzhen and Suzhou drives multi-layer PCB fluxing equipment demand. The MEE enforces GB standards on industrial volatile organic compound discharge limits, accelerating water-based formulation conversion. Guangdong province electronics manufacturing clusters are deploying closed-loop spray recovery systems to maintain operating permits under tightening environmental audits.
Germany
Automotive tier-one suppliers in Stuttgart and Wolfsburg are piloting dual-mode selective fluxing systems for powertrain control modules. REACH Article 33 compliance deadlines through 2027 are forcing retirement of solvent-based flux architectures. Baden-Württemberg precision machining networks supply concentrated nozzle component manufacturing, creating geographic lock-in for European equipment assemblers.
United States
Aerospace component facilities in Texas and California face dual pressure from MIL-STD-202G compliance demands and EPA NESHAP enforcement on solvent recovery documentation. The EPA's National Emission Standards for Hazardous Air Pollutants are tightening carbon adsorption unit requirements. Electronics contract manufacturers in the Southwest are retrofitting closed-loop configurations to maintain operating permits.
South Korea
Telecommunications equipment OEMs specify synthetic low-residue formulations for 5G base station production in Gyeonggi-do and Incheon. The MFDS maintains chemical substance notification requirements for imported flux activators. Seoul Capital Area precision electronics manufacturers are adopting ultrasonic atomization platforms achieving sub-20-micron droplet consistency for 01005 component placements.
India
PLI scheme incentives for semiconductor packaging are attracting greenfield PCB assembly investments in Gujarat and Tamil Nadu. The BIS implements phased conformity assessment for electronics manufacturing chemicals. Electronics manufacturing clusters in Sriperumbudur and Sanand are creating first-mover equipment positioning windows for spray fluxer vendors establishing service networks.
Spray Fluxer Market Competitive Landscape
On the supply side, the industry is consolidating around fluid handling specialists with captive atomization technology and precision coating equipment lessors penetrating mid-tier contract manufacturers. Strategic archetypes separate ultrasonic atomization technology owners, selective soldering system integrators, and bulk chemical formulation houses. Competitive moves concentrate on geographic expansion into India electronics manufacturing clusters and asset-light leasing model deployment across Southeast Asian facilities.
Among established equipment specialists, Sono-Tek occupies a position exemplifying ultrasonic atomization expertise, while Kurtz Ersa represents German engineering credibility through in-house production capabilities. Nordson Corporation anchors the fluid dispensing technology tier, extending control into integrated spray fluxer architectures. These three entities sit within distinct competitive vectors—precision coating innovation, European manufacturing heritage, and fluid management scale—rather than direct overlapping rivalry.
| Leading Market Players |
|---|
| Nordson Corporation |
| SENJU METAL INDUSTRY |
| Kurtz Ersa |
| Sono-Tek |
| Tamura |
| TMPL Machines |
| KOKI |
| National Solbot |
| Henkel AG & Co. KGaA |
| Others |
Value Network & Pricing Analysis
Tariff exposure between German precision machining networks and Asian equipment assemblers determines both pricing tier spreads and supply chain shape, compressing margin buffers for mid-tier contract manufacturers while concentrating premium pricing power with Stuttgart-area nozzle suppliers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on REACH certification tier and ultrasonic atomization precision grade, with automotive tier-one suppliers accepting 20-30% premiums for closed-loop recovery systems. Cost compression in the economy tier is intensifying because Shenzhen-based contract manufacturers are aggregating demand through cooperative purchasing consortia. Repair services in Southeast Asia exhibit the highest price sensitivity, while German automotive OEMs demonstrate the lowest due to ISO 14001-mandated supplier audits.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for electronics manufacturing equipment. Component manufacturing draws from Germany, South Korea, and Japan, with precision atomization nozzles feeding from Baden-Württemberg machining networks. Single-source vulnerability concentrates in Stuttgart-area suppliers for sub-20-micron ultrasonic components. Distribution runs through regional equipment lessors and direct OEM procurement channels, with bulk flux formulations moving via IBC totes to high-velocity surface mount technology lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spray fluxer demand sits in early-cycle expansion as electric vehicle inverter board proliferation forces tier-one automotive suppliers to upgrade throughput capacity for multi-layer PCB production.
For Market Incumbents: Entrench market position through backward integration into captive nozzle manufacturing and capacity addition in Gujarat electronics manufacturing clusters. Water-based formulation conversion timelines compress replacement cycles, threatening solvent-based product line margins. Certification investment in REACH Article 33 compliance documentation provides defensive moats against emerging Asian equipment vendors. For New Entrants and Emerging Players: Build out service networks in Tamil Nadu and Sanand industrial corridors before established vendors lock in automotive tier-one relationships. India's PLI scheme for semiconductor packaging offers the most penetrable geography for greenfield equipment positioning. Asset-light leasing models convert CapEx to OpEx for Penang and Vietnam contract manufacturers previously priced out of automated fluxing. For Investors and Strategic Acquirers: EPA NESHAP enforcement milestones through 2027 reshape the acquisition landscape toward closed-loop spray recovery system specialists. Long-term viability over a 5-10 year window favors vendors with verified volatile organic compound recovery architectures and ultrasonic atomization IP. The signal to monitor is automotive OEM dual-mode selective fluxing pilot programs in Stuttgart and Wolfsburg.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nozzle Manufacturing | Captive supply of precision atomization components insulates margin pressure from Stuttgart supplier concentration. |
| Water-Based Formulation Certification | REACH Article 33 compliance opens procurement channels with German automotive tier-one suppliers. |
| Asset-Light Leasing Model Deployment | OpEx conversion penetrates mid-tier contract manufacturers in Penang and Vietnam facilities. |
| India Service Network Expansion | First-mover positioning in Gujarat and Tamil Nadu captures PLI-scheme-driven greenfield investments. |
| Closed-Loop Recovery System Integration | Carbon adsorption unit bundling maintains EPA NESHAP operating permits for Texas and California assemblers. |
Research Methodology
A spread of perspectives from electronics manufacturing services procurement directors, automotive tier-one supplier quality engineers, precision coating equipment R&D heads, and flux formulation technical directors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, customs and trade data, EPA enforcement documentation, and REACH substance restriction registers. Bottom-up equipment shipment analysis and top-down electronics assembly capacity modeling provided triangulation across the analysis window.
Demand-supply balance framing anchored the quantitative approach, with segmentation across carrier chemistry type, end-use application, and regional regulatory cluster modeled throughout the forecast period. CAGRs were derived from replacement cycle velocity differentials between water-based and solvent-based systems, layered against electric vehicle production ramp assumptions and contract manufacturer capital expenditure surveys. Industry-specific inputs included ultrasonic atomization adoption curves and REACH compliance deadline phasing.
Stress conditions across isopropanol price volatility, nozzle supplier geographic concentration, and water-based flux drying energy intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and automotive electrification penetration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
EV Adhesives Market
Adhesives & Sealants
Global Bioadhesive Market
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
Global Construction Adhesives and Sealants Market
Adhesives & Sealants
Polyurethane Adhesives and Sealants Market
Adhesives & Sealants
North America Sealants Market
Adhesives & Sealants
Central Reinforced Tape Market
Adhesives & Sealants
Asia-Pacific EVA Adhesives Market
Adhesives & Sealants
Europe Adhesives and Sealants Market
Adhesives & Sealants
Indonesia Adhesives and Sealants Market
Adhesives & Sealants
Indonesia Sealants Market
Adhesives & Sealants
Temporary Bonding Adhesives Market
Adhesives & Sealants
Polyurethane (PU) Adhesives in Electronics Market
Adhesives & Sealants
Paper-Backing Abrasive Adhesive Discs Market
Adhesives & Sealants
Middle East and Africa Bone Glue Market