
 Data Processing Unit Market | 2026-2036
Data Processing Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Data Processing Unit Market Outlook
ISO 26262 functional safety certification is rotating the competitive field for automotive-grade DPUs, filtering out suppliers lacking ASIL-D qualification pipelines. NVIDIA leverages its CUDA software ecosystem to dominate data-center training workloads. Broadcom sustains silicon design leadership through in-house production of custom ASICs for hyperscalers. Kalray specializes in embedded acceleration for edge-automotive applications, occupying a defensible niche against general-purpose rivals.
A data processing unit is a programmable semiconductor subsystem that offloads infrastructure tasks—networking, storage virtualization, security encryption—from host CPUs, typically integrating ARM or RISC-V cores with dedicated hardware accelerators at 7nm or 5nm process nodes. Its primary purpose is to reclaim server CPU cycles for revenue-generating compute while reducing data-center power consumption per workload. FPGA-based DPUs currently lead in programmable infrastructure deployments where protocol flexibility matters, while ASIC implementations capture margin pools in high-volume cloud contracts with fixed-function optimization. Edge Computing applications represent the fastest-growing technology segment as latency-sensitive AI inference pushes processing toward distributed nodes.
The US FCC governs electromagnetic emissions for DPU-equipped networking gear, while China's MIIT enforces GB standards on domestic data-center equipment efficiency and cybersecurity. The EU AI Act imposes risk-classification requirements on DPUs deployed in high-stakes automated decision systems, shaping European procurement specifications. Stakeholders must monitor how export control frameworks from the US Bureau of Industry and Security and China's SAMR licensing rules reshape supply chain access for advanced node fabrication.
Market Dynamics
Hyperscaler AI infrastructure buildouts are compressing DPU procurement cycles while fragmenting supplier qualification pathways across cloud, enterprise, and edge verticals.
Growth Catalysts
- Cloud AI Workload Expansion:Hyperscalers are deploying DPUs to reclaim CPU cycles from networking and storage virtualization overhead. This infrastructure offload demand concentrates in United States data-center clusters.
- China's GB 40879 Energy Efficiency Mandate:MIIT enforcement of data-center power usage effectiveness thresholds is forcing domestic operators to adopt hardware-level acceleration. DPUs reduce per-workload consumption to meet compliance.
- Automotive Functional Safety Requirements:ISO 26262 ASIL-D certification is becoming a procurement gate for autonomous vehicle programs. This regulatory filter creates qualified supplier scarcity in automotive-grade silicon.
Market Restraints
- Advanced Node Fabrication Concentration:Taiwan-based foundry capacity for 5nm and below processes limits supply elasticity. Geopolitical friction over Taiwan Strait access amplifies allocation risk.
- CUDA Software Ecosystem Lock-in:Proprietary programming models create switching costs that retard alternative DPU architecture penetration in training workloads.
- High NRE for Custom ASICs:Non-recurring engineering costs for hyperscaler-specific silicon designs exceed viable thresholds for mid-scale cloud operators.
Strategic Opportunities
- India Data-Center Buildout:PLI scheme incentives for semiconductor assembly and testing are attracting DPU packaging investments. Domestic cloud demand from BFSI and telecom verticals remains underpenetrated.
- Edge-AI Inference Convergence:Integration of DPUs with 5G base stations and industrial IoT gateways enables sub-10ms latency processing. This architecture merges networking acceleration with localized AI compute.
- EU AI Act Risk Classification:High-stakes automated decision systems face mandatory explainability and audit requirements. DPUs with embedded telemetry and deterministic execution gain preference in European procurement.
Industry Challenges
- Hardware-Software Co-Design Talent Scarcity:DPU optimization requires rare expertise spanning silicon architecture, kernel-level programming, and workload-specific acceleration. This skill concentration limits vendor scaling velocity.
- Multi-Generation Certification Timelines:Automotive and aerospace qualification cycles span 24-36 months. Product roadmaps must freeze features early, constraining competitive responsiveness to protocol evolution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Processing Unit Market |
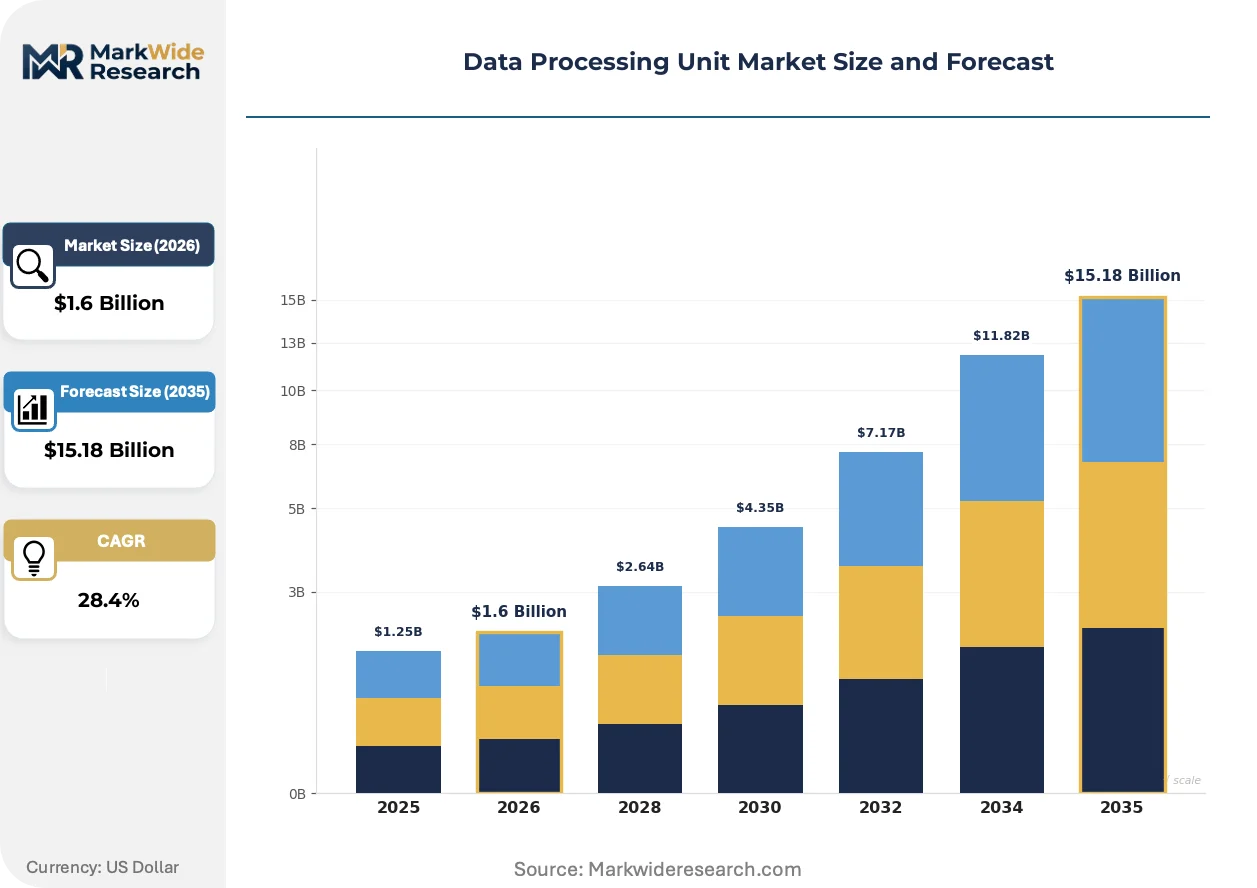
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $15.18 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FPGA, ASIC, CPU, GPU Technology: Deep Learning, Edge Computing, Cloud Computing, Big Data End User: Telecommunications, Automotive, Healthcare, Finance Application: Data Analytics, Machine Learning, Real-Time Processing, Video Rendering |
| Companies Covered | Broadcom, Inc., Marvell Technology Group Ltd., Microsoft Corporation, Yisixin Technology (Shanghai) Co., Ltd., Kalray SA, NVIDIA Corporation, Advanced Micro Devices, Inc., YUSUR Technology Co., Ltd., Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Processing Unit Market Strategic Shifts
Silicon disaggregation and software-defined infrastructure are rewriting DPU competitive boundaries, with programmable logic and fixed-function ASICs diverging into distinct procurement categories.
Chiplet-based DPU architectures are decomposing monolithic silicon into specialized compute, memory, and I/O tiles. Cloud service providers are qualifying these designs for 2024-2025 server refresh cycles. This modularity is decomposing vendor lock-in by enabling mix-and-match acceleration from multiple suppliers.
EU AI Act risk-tier classification is mandating deterministic execution guarantees for DPUs in automated credit, healthcare, and judicial decision systems. Hardware vendors must embed audit trails and failure-mode documentation. European enterprise procurement specifications now exclude non-compliant acceleration hardware from high-stakes deployments.
Hyperscalers are consolidating DPU procurement under direct silicon partnerships, bypassing traditional server OEM channels. This disintermediation compresses margin pools for intermediate integrators. The pattern is most visible in United States and China, where cloud operators possess sufficient volume to justify custom ASIC development.
Data Processing Unit Market Segmentation
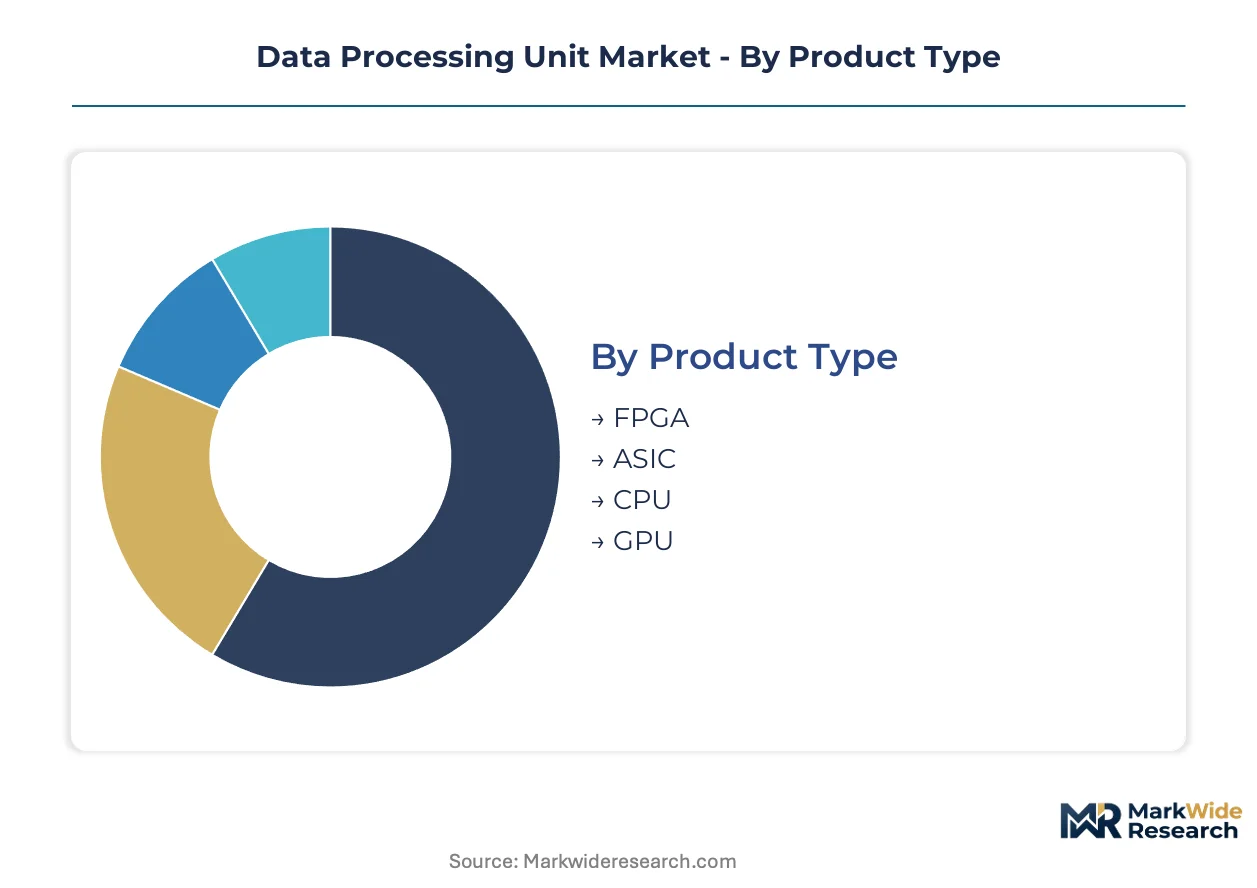
DPU procurement patterns diverge sharply across deployment contexts, with programmable logic competing against fixed-function silicon for infrastructure offload contracts. Segmentation reveals how workload specificity, latency requirements, and certification burdens reshape supplier qualification pathways across cloud, automotive, and enterprise verticals.
Product Type:
ASIC implementations face intensifying substitution pressure from reprogrammable alternatives as hyperscaler protocols evolve faster than silicon refresh cycles.
- FPGA:Field-programmable gate arrays deliver protocol flexibility through reconfigurable logic blocks, enabling post-deployment updates for evolving networking standards. Demand concentrates in enterprise data centers where infrastructure heterogeneity resists standardization. China's MIIT enforcement of evolving GB cybersecurity standards accelerates FPGA preference for compliance adaptability.
- ASIC:Application-specific integrated circuits optimize die area and power efficiency for fixed-function workloads at 5nm and 7nm nodes. United States hyperscalers dominate procurement volume through direct silicon partnerships that bypass traditional OEM channels. NVIDIA's CUDA ecosystem reinforces ASIC lock-in for training workloads despite higher switching costs.
- CPU:General-purpose processors retain infrastructure roles where software legacy and broad compatibility outweigh acceleration benefits. Legacy enterprise workloads in European financial services maintain CPU preference for regulatory audit simplicity.
- GPU:Graphics processing units extend beyond rendering into parallel compute for AI inference, though dedicated DPUs increasingly displace them for pure infrastructure tasks. Automotive edge clusters in Germany leverage GPU-DPU hybrid architectures for autonomous perception pipelines.
ASIC anchors the volume base while FPGA gains share at the steepest rate.
Technology:
Cost tier stratification separates capex-intensive cloud deployments from distributed edge infrastructure with constrained unit economics.
- Deep Learning:Neural network acceleration demands tensor-optimized arithmetic units with high-bandwidth memory integration. United States training clusters consume the dominant share of deep-learning DPU silicon. NVIDIA's dominance in this tier creates vendor concentration risk for hyperscaler supply diversification.
- Edge Computing:Latency-constrained processing at 5G base stations and industrial gateways requires sub-10ms deterministic execution with ruggedized thermal profiles. India's PLI-scheme data-center buildout drives edge DPU packaging investments for domestic telecom and BFSI verticals.
- Cloud Computing:Hyperscale virtualization offloads networking, storage, and security from host CPUs to reclaim cycles for revenue-generating compute. China's GB 40879 energy efficiency mandates force hardware-level acceleration adoption to meet PUE thresholds.
- Big Data:Distributed analytics frameworks accelerate shuffle operations and query execution through in-network computation. European enterprise procurement under EU AI Act risk classification favors DPUs with embedded telemetry for audit trails.
Cloud Computing commands the largest installed base while Edge Computing expands most quickly.
End User:
Customer-type fragmentation creates divergent qualification timelines, with automotive certification cycles spanning 24-36 months against cloud procurement measured in quarters.
- Telecommunications:5G infrastructure and core network virtualization demand DPUs with precise timing for synchronization and line-rate encryption. United States carrier capex concentrates in Open RAN disaggregation programs.
- Automotive:ISO 26262 ASIL-D functional safety certification gates supplier participation in autonomous vehicle programs. Kalray occupies a defensible niche in embedded automotive acceleration against general-purpose rivals. Germany's KBA and United States NHTSA enforcement tighten reliability documentation requirements.
- Healthcare:Medical imaging and diagnostic AI require deterministic latency with FDA or equivalent regulatory validation. HIPAA compliance constraints favor DPUs with hardware-rooted security enclaves.
- Finance:High-frequency trading and risk analytics prioritize sub-microsecond deterministic execution with audit logging for regulatory examination. European procurement under EU AI Act high-stakes decision system rules excludes non-compliant acceleration hardware.
Telecommunications sustains the deepest deployment base while Automotive generates the steepest expansion trajectory.
Application:
Volume concentration in mature analytics workloads contrasts with emerging inference demand reshaping silicon architecture roadmaps.
- Data Analytics:SQL acceleration and columnar processing offload from host CPUs through in-memory computation and predicate pushdown. Legacy enterprise data warehouses in United States financial services maintain this segment's revenue concentration.
- Machine Learning:Training and inference pipelines demand mixed-precision arithmetic with sparsity exploitation and model-parallel coordination. China's domestic cloud operators scale ML DPU procurement fastest under AI self-sufficiency mandates.
- Real-Time Processing:Stream analytics and event-driven architectures require deterministic latency bounds with backpressure handling. Industrial IoT gateways in Japan's METI-supported smart factory programs drive qualification demand.
- Video Rendering:Codec acceleration and frame composition for cloud gaming and content delivery networks exploit fixed-function media pipelines. South Korean content platforms under MFDS broadcast equipment rules anchor regional procurement.
Data Analytics anchors installed capacity while Machine Learning captures the fastest-growing application share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler infrastructure investment concentrates procurement power among cloud operators in three major economies. China's domestic AI buildouts, United States training cluster expansions, and India's emerging data-center capacity each reshape regional supplier qualification pathways.
United States
AWS, Google Cloud, and Microsoft Azure drive DPU volume through direct silicon partnerships that bypass server OEMs. FCC electromagnetic emission rules govern networking gear certification. Northern Virginia's data-center corridor consumes the dominant share of hyperscale DPU deployments for AI training infrastructure.
China
Domestic cloud operators scale DPU procurement fastest under AI self-sufficiency mandates and dual carbon goals. MIIT enforces GB 40879 power usage effectiveness thresholds that force hardware-level acceleration adoption. Beijing-Tianjin-Hebei and Yangtze River Delta clusters anchor domestic DPU demand for state-backed AI infrastructure.
India
PLI scheme incentives for semiconductor assembly and testing attract DPU packaging investments from global suppliers. TRAI spectrum allocations for 5G infrastructure create edge computing demand. Mumbai-Pune and Bengaluru-Chennai corridors concentrate domestic cloud demand from BFSI and telecom verticals.
Germany
Automotive OEMs mandate ISO 26262 ASIL-D certified DPUs for autonomous vehicle programs, creating qualified supplier scarcity. KBA enforcement tightens reliability documentation requirements for silicon components. Baden-Württemberg's automotive engineering cluster drives edge-AI qualification timelines spanning 24-36 months.
South Korea
Content platforms under MFDS broadcast equipment rules anchor regional procurement for video rendering acceleration. Samsung and SK hynix memory integration capabilities shape local DPU packaging preferences. Seoul Capital Area data centers concentrate domestic cloud infrastructure investment with sub-10ms latency requirements.
Data Processing Unit Market Competitive Environment
Player mix skews toward integrated semiconductor conglomerates with captive foundry relationships and custom ASIC design capabilities. Three to five vertically integrated giants capture high-volume cloud contracts, while specialized fabless vendors occupy defensible niches in automotive and edge applications. Strategic archetypes include CUDA-ecosystem incumbents, hyperscaler-direct ASIC designers, and functional-safety specialists. Competitive moves center on silicon disaggregation through chiplet architectures and direct cloud partnerships that disintermediate server OEM channels.
Within the hyperscaler-direct tier, NVIDIA Corporation and Broadcom, Inc. exemplify divergent ecosystem strategies—one leveraging proprietary software lock-in, the other sustaining silicon design leadership through custom ASIC production. Kalray SA occupies a position among functional-safety specialists focused on embedded automotive acceleration. Marvell Technology Group Ltd. sits within the networking-integrated archetype, while Intel Corporation and Advanced Micro Devices, Inc. represent diversified semiconductor conglomerates with DPU portfolios extending from data center to edge deployments. Chinese vendors Yisixin Technology (Shanghai) Co., Ltd. and YUSUR Technology Co., Ltd. anchor domestic supply alternatives under Beijing's import substitution policies.
| Leading Market Players |
|---|
| Broadcom, Inc. |
| Marvell Technology Group Ltd. |
| Microsoft Corporation |
| Yisixin Technology (Shanghai) Co., Ltd. |
| Kalray SA |
| NVIDIA Corporation |
| Advanced Micro Devices, Inc. |
| YUSUR Technology Co., Ltd. |
| Intel Corporation |
| Others |
Value Chain & Pricing Dynamics
Hyperscaler volume concentration in the United States and China generates procurement leverage that compresses unit economics for mid-scale cloud operators while elevating price floors for automotive-grade silicon. Taiwan-based foundry utilization rates above ninety percent transmit capacity scarcity into long-term contract premiums, particularly for 5nm and below process nodes where ASIC designs dominate.
Pricing Analysis
Cost-plus contracts with Taiwan Semiconductor Manufacturing Company index wafer starts to capacity utilization and raw silicon input costs. Pricing stratifies across automotive ASIL-D certified tiers, cloud-scale volume commitments, and enterprise FPGA deployments. Cost compression in cloud ASIC tiers intensifies because hyperscalers negotiate direct silicon partnerships that bypass traditional OEM markups. Mid-scale enterprise buyers exhibit highest price sensitivity due to inability to amortize non-recurring engineering across sufficient volume.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for advanced node DPUs, while Malaysia and Vietnam concentrate assembly and test operations. Silicon wafers, high-bandwidth memory stacks, and advanced packaging substrates constitute critical input dependencies. Single-source vulnerability concentrates in Taiwan Strait geopolitical friction, which amplifies allocation risk for 5nm capacity. Distribution runs through direct hyperscaler procurement channels that disintermediate server OEMs in United States and China markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CUDA software ecosystem lock-in constitutes a platform-economics inflection that rewards interoperability investments and punishes proprietary architecture isolation. Open-source runtime compatibility emerges as the decisive ecosystem battleground.
For Market Incumbents: Compound software ecosystem stickiness through kernel-level optimization for emerging networking protocols. Defensive consolidation requires backward integration into advanced packaging capacity in Malaysia or Vietnam to secure assembly supply. Channel control through direct cloud partnerships neutralizes emerging ASIC design houses threatening hyperscaler relationships.
For New Entrants and Emerging Players: Edge-automotive functional safety certification gaps where NVIDIA and Broadcom under-serve create service-layer entry points. India's PLI-scheme data-center buildout offers the most penetrable geography for packaging and test investments. Go-to-market positioning through 5G infrastructure OEMs leverages Open RAN disaggregation momentum.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fabless specialists with ISO 26262 qualification pipelines and automotive OEM design wins. Long-term viability across the analysis window hinges on chiplet architecture readiness and multi-foundry sourcing flexibility. The decisive inflection signal to watch is hyperscaler direct-silicon partnership announcements that bypass traditional DPU vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Chiplet Architecture Adoption | Modular silicon decomposition enables mix-and-match acceleration from multiple suppliers. |
| Direct Hyperscaler Partnership | Bypassing server OEM channels compresses margin pools for intermediate integrators. |
| ISO 26262 ASIL-D Certification | Automotive functional safety gates create qualified supplier scarcity and pricing power. |
| Open Source Runtime Development | Interoperability investments counter CUDA ecosystem lock-in and reduce switching costs. |
| Multi-Foundry Sourcing | Taiwan capacity diversification mitigates geopolitical allocation risk for advanced nodes. |
Study Parameters
Desk research of hyperscaler capital expenditure disclosures, foundry utilization reports, and regulatory filing databases preceded structured interviews with semiconductor procurement executives, cloud infrastructure architects, and automotive platform engineering leads. Primary fieldwork with DPU vendor product managers and foundry sales directors combined with secondary validation through SEC 10-K filings, MIIT GB standard documentation, and EU AI Act implementation guidance. Bottom-up unit shipment estimates and top-down addressable market sizing underwent iterative triangulation.
Variance decomposition across product type, technology deployment, end-user vertical, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Foundry capacity expansion timelines, hyperscaler AI infrastructure buildout schedules, and automotive qualification cycle durations constituted industry-specific forecast inputs.
Underlying assumptions cover sustained Taiwan foundry access, stable hyperscaler capex trajectories, and incremental EU AI Act enforcement, with deviation risk concentrated in export control framework revisions and automotive program delays. Recalibration cycles align with material shifts in foundry utilization rates and hyperscaler partnership announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global ASIC Bitcoin Mining Hardware Market
Semiconductor Devices
Spintronic Logic Devices Market
Semiconductor Devices
APAC Semiconductor Device for Industrial Applications Market
Semiconductor Devices
Europe Room Cell Module Market
Semiconductor Devices
Global Layer Pads Market
Semiconductor Devices
FPGA Market
Semiconductor Devices
Monocrystalline Half-Chip Module Market
Semiconductor Devices
Global Substrate-Like PCB Market
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
Global Transistor Market
Semiconductor Devices
Europe Printed Circuit Board (PCB) Market
Semiconductor Devices
China Semiconductor Device Market
Semiconductor Devices
IGBT and Super Junction MOSFET Market
Semiconductor Devices
Semiconductor Wafer Frame Market
Semiconductor Devices
Field Programmable Gate Array (FPGA) Market