
 Global Polymerization Initiator Market | 2026-2036
Global Polymerization Initiator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polymerization Initiator Market Outlook
The gap between pharmaceutical-grade azo initiators and bulk commodity peroxides is shifting procurement criteria toward verified decomposition kinetics and trace metal certification. Arkema S.A. leverages its integrated organic peroxide chain from hydrogen peroxide feedstock through formulated derivatives to sustain margin capture across specification tiers. LANXESS AG anchors European supply security through backward integration into dicumyl peroxide precursors at its Belgian and German sites. Nouryon competes on global logistics density, operating temperature-controlled distribution networks that preserve initiator half-life specifications through last-mile delivery.
Polymerization initiators are thermally or photochemically labile compounds that generate free radicals or ionic species at controlled temperatures, typically featuring 10-hour half-life decomposition temperatures between 20°C and 150°C depending on molecular structure; they function as the kinetic gatekeepers that determine molecular weight distribution, crosslink density, and gel content in synthetic polymer manufacturing. Peroxide initiators dominate volume consumption across high-tonnage polyethylene and polyvinyl chloride production, where cost-per-radical efficiency governs procurement decisions. Photoinitiators occupy the fastest-expanding margin pool, driven by ultraviolet-cured coatings and electronics adhesives requiring solvent-free processing and precise cure-depth control. Azo initiators retain structural importance in specialty emulsion polymerization for paints and sealants, where narrow polydispersity requirements favor their predictable first-order decomposition kinetics.
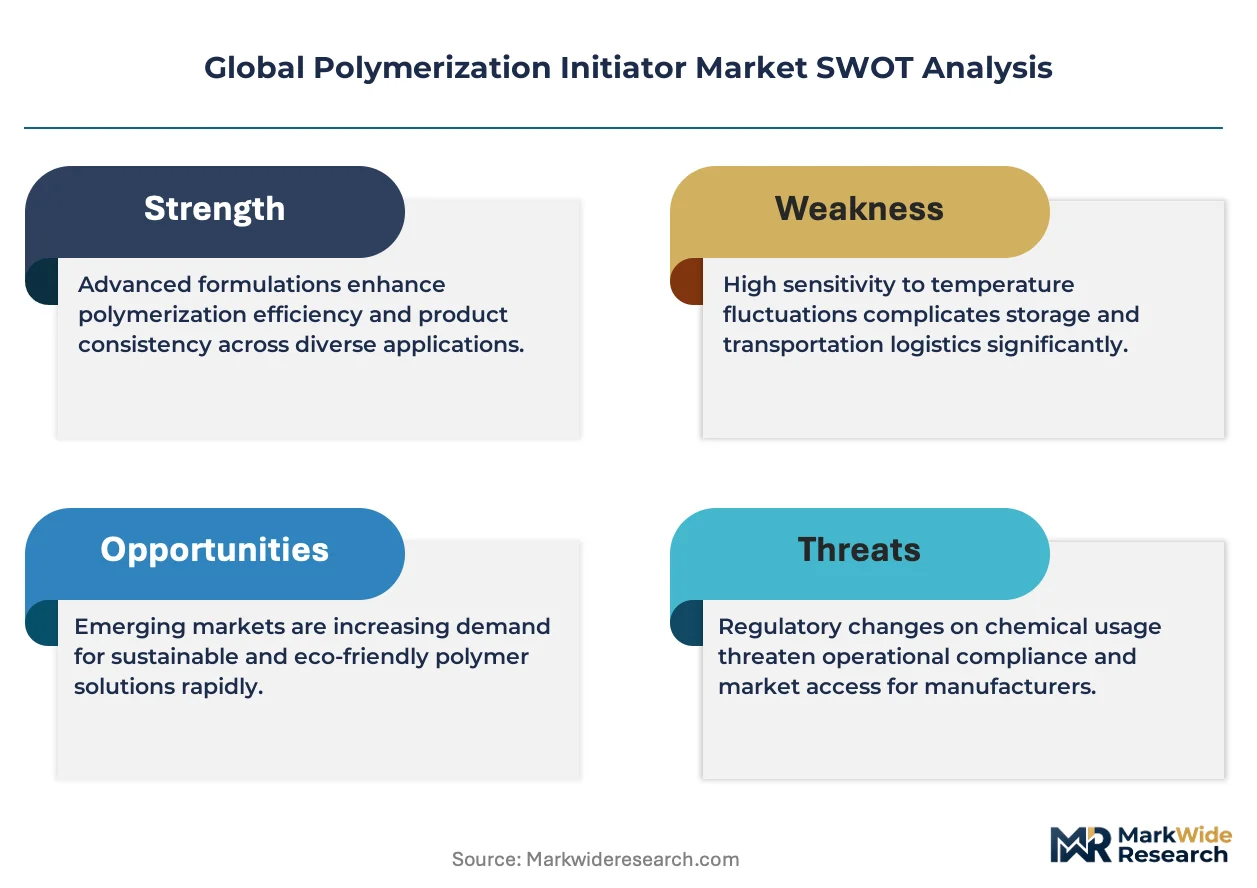
FDA food-contact substance notifications, EPA TSCA Section 5 premanufacture review, and REACH Annex XIV authorization requirements collectively elevate compliance costs for initiators migrating into packaging and consumer goods applications. China's SAMR enforces GB 9685 additive purity standards that disqualify legacy peroxide grades from domestic food-contact polymer supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory when formulation specifications tighten asymmetrically across export destinations.
Market Dynamics
REACH Annex XIV authorization timelines and China's GB 9685 purity mandates are forcing dual-track formulation development, splitting R&D budgets between legacy grade maintenance and next-generation initiator architectures. This regulatory asymmetry compresses product lifecycles and rewards suppliers with pre-certified platform chemistries.
Growth Catalysts
- Food-contact packaging migration:FDA food-contact substance notifications for high-purity peroxides are accelerating qualification cycles for Southeast Asian film extruders serving export markets.
- UV-cured electronics adhesives:Photoinitiator demand from semiconductor packaging and display lamination is outpacing conventional thermal initiator growth in South Korea and Taiwan.
- India's western chemical corridor:Domestic polymer capacity additions around Gujarat are concentrating local initiator procurement, reducing import dependency for polyethylene and PVC producers.
Market Restraints
- Hydrogen peroxide feedstock volatility:Organic peroxide margins compress when chlor-alkali co-product economics destabilize, particularly affecting European producers without captive hydrogen peroxide supply.
- Supplier concentration in temperature-controlled logistics:Cold-chain distribution networks for azo initiators concentrate among three global operators, creating single-point vulnerability for half-life-sensitive shipments.
- First-order kinetic limitations:Azo initiators cannot match peroxide decomposition rate tunability, restricting their penetration into high-pressure polyethylene reactor systems.
Strategic Opportunities
- Brazilian packaging localization:ANVISA alignment with FDA food-contact standards creates opening for pre-certified initiator suppliers to displace European imports in flexible film markets.
- Dual-carbon policy convergence:China's MEE enforcement of carbon intensity benchmarks favors water-based emulsion polymerization using azo initiators over solvent-borne peroxide systems.
- Photoinitiator-dispersion hybrids:Convergence of Type I cleavage photoinitiators with nanoparticle dispersion technology enables thick-section UV curing for wind turbine blade coatings.
Industry Challenges
- Thermal stability certification timelines:10-hour half-life validation protocols require 90-day stability studies, delaying new product introductions by two full selling seasons.
- Cross-contamination controls:Multi-product initiator plants face FDA inspection scrutiny over residual peroxide detection in azo initiator production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polymerization Initiator Market |
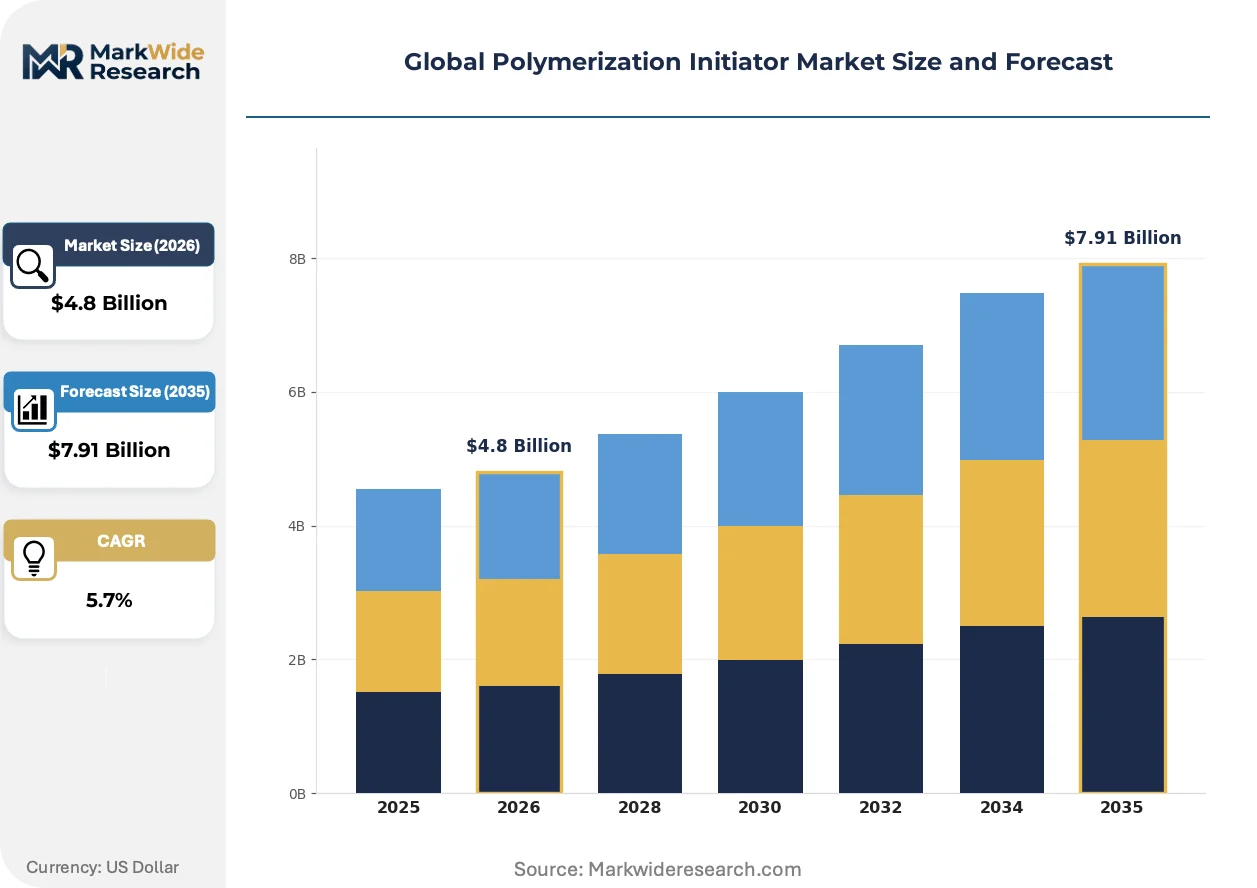
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azo Initiators, Peroxide Initiators, Photoinitiators, Redox Initiators End Use Industry: Packaging, Automotive, Construction, Electronics Application: Coatings, Adhesives, Sealants, Composites Formulation Type: Emulsion, Solution, Suspension, Dispersion |
| Companies Covered | Arkema S.A, LANXESS AG, BASF SE, Nouryon, United Initiators, Adeka Corporation, AkzoNobel, Celanese Corporation, NOF Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polymerization Initiator Market Strategic Shifts
Photochemical curing architectures and predictive decomposition modeling are displacing empirical formulation approaches, compressing development cycles while tightening kinetic specification windows.
Hybrid photoinitiator systems combining Type I cleavage and Type II hydrogen-abstraction mechanisms are modularizing formulation platforms for UV-cured automotive clearcoats. Tier-1 coatings suppliers in Germany and Japan are adopting these dual-mechanism packages to achieve through-cure at 200-micron film builds without solvent flash-off. The technology is modularizing specification hierarchies, allowing single-SKU coverage across multiple substrate classes.
REACH restriction proposals for dibenzoyl peroxide reproductive toxicity classifications are triggering substitution waves in European dental and medical device polymerization. ECHA's 2024-2025 dossier evaluation timeline is compressing supplier response windows to under 18 months. Medical-grade methyl ethyl ketone peroxide alternatives are capturing specification share in German and Italian orthodontic resin markets.
Specification-driven buying committees now mandate trace metal certification down to 10-ppb thresholds before initiator qualification, displacing traditional price-per-kilo procurement metrics. Polymer producers in India's Gujarat cluster are consolidating vendor lists to three approved suppliers per initiator class. This concentration is most visible in pharmaceutical-grade azo initiator sourcing, where CDSCO alignment with ICH Q3D elemental impurity guidelines has become a non-negotiable gate.
Global Polymerization Initiator Market Segmentation
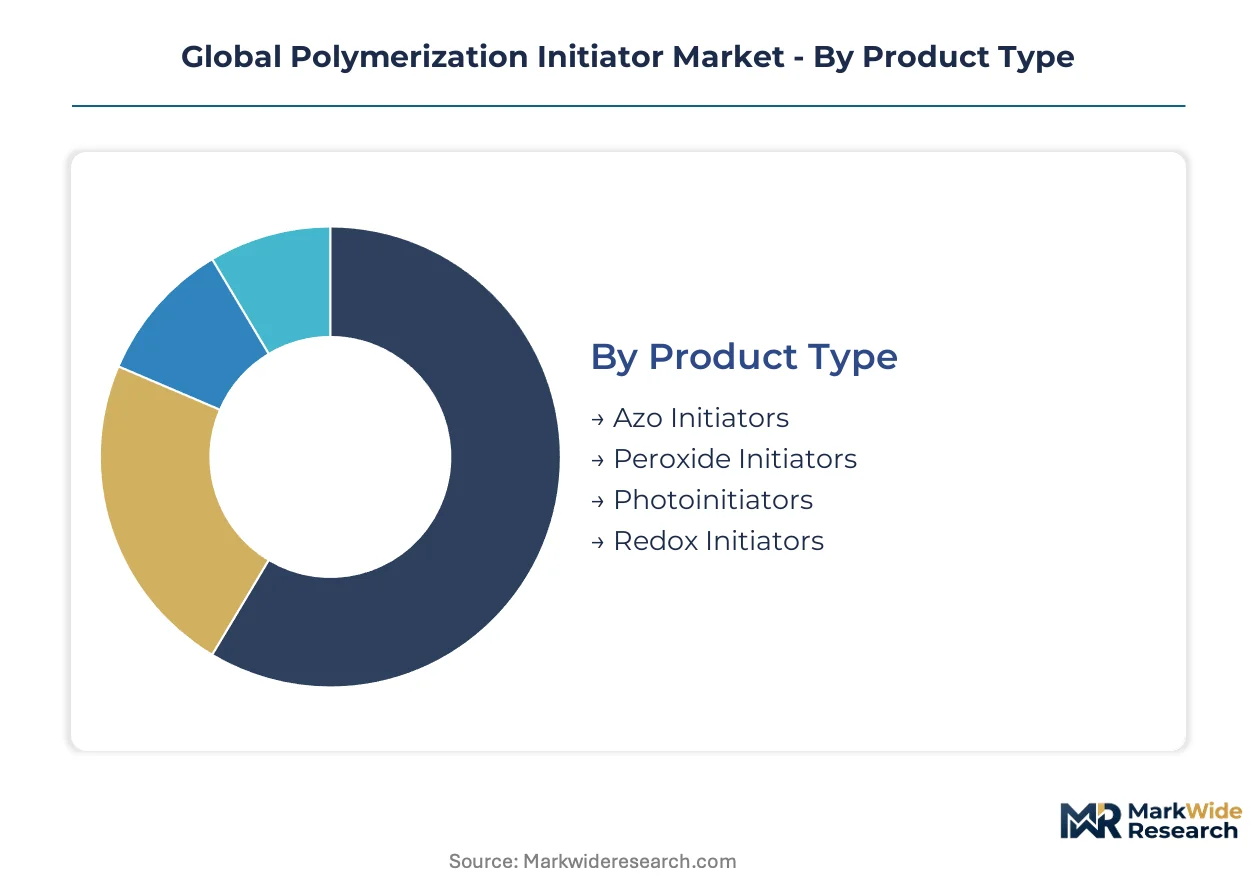
Polymerization initiator procurement decisions hinge on certification alignment across FDA food-contact, REACH Annex XIV, and China's GB 9685 standards. Segmentation reveals which product architectures command premium pricing versus commodity positioning.
Product Type:
Certification burden varies sharply: pharmaceutical-grade azo initiators demand CDSCO and ICH Q3D trace metal validation, while bulk peroxides face REACH reproductive toxicity scrutiny.
- Peroxide Initiators:Hydrogen peroxide-derived organic compounds dominate polyethylene and PVC production volumes. Demand concentrates in India's Gujarat chemical corridor where domestic polymer capacity expansion accelerates local procurement of dicumyl peroxide and benzoyl peroxide grades.
- Photoinitiators:UV-activated Type I cleavage and Type II hydrogen-abstraction systems enable solvent-free curing. South Korean and Taiwanese semiconductor packaging operations drive specification tightening for through-cure at 200-micron film builds in display lamination adhesives.
- Azo Initiators:Nitrogen-based compounds with predictable first-order decomposition kinetics serve specialty emulsion polymerization for paints and sealants requiring narrow polydispersity.
- Redox Initiators:Oxidation-reduction pairs initiate polymerization at ambient temperatures for water-based systems in cold-climate construction applications.
Leading the category by volume: Peroxide Initiators. Growing fastest: Photoinitiators.
End Use Industry:
Margin structure tracks regulatory exposure: food-contact packaging commands 10-ppb trace metal certification, while automotive tolerates broader specification windows.
- Packaging:FDA food-contact substance notifications and China's GB 9685 additive purity standards disqualify legacy peroxide grades from flexible film supply chains. Southeast Asian converters expand purchases of high-activity peroxides to meet shelf-life specifications for export-oriented food-contact films.
- Electronics:UV-cured semiconductor packaging and display lamination demand photoinitiators with precise cure-depth control. South Korean memory chip packaging operations specify initiator half-life stability through temperature-controlled logistics networks.
- Automotive:Hybrid photoinitiator systems with dual-mechanism curing support thick-section clearcoats without solvent flash-off in German and Japanese OEM coating lines.
- Construction:Water-based emulsion polymerization using azo initiators gains preference under China's MEE carbon intensity benchmarks versus solvent-borne peroxide systems.
Highest certification intensity: Packaging. Steepest specification climb: Electronics.
Application:
Application selection dictates kinetic requirements: coatings prioritize tunable decomposition rates, adhesives demand batch-to-batch consistency.
- Coatings:Automotive clearcoats and wind turbine blade protection drive hybrid photoinitiator adoption for thick-section UV curing. German Tier-1 suppliers modularize dual-mechanism packages across substrate classes.
- Adhesives:Semiconductor packaging and electronics lamination require precise cure-depth control. Taiwan-based display manufacturers specify photoinitiator dispersion technology for solvent-free processing.
- Sealants:Narrow polydispersity requirements in architectural and automotive joints favor azo initiator predictability over peroxide rate variability.
- Composites:High-pressure resin transfer molding for aerospace and marine applications demands peroxide decomposition rate tunability unavailable with first-order azo kinetics.
Deepest specification stack: Coatings. Fastest format innovation: Adhesives.
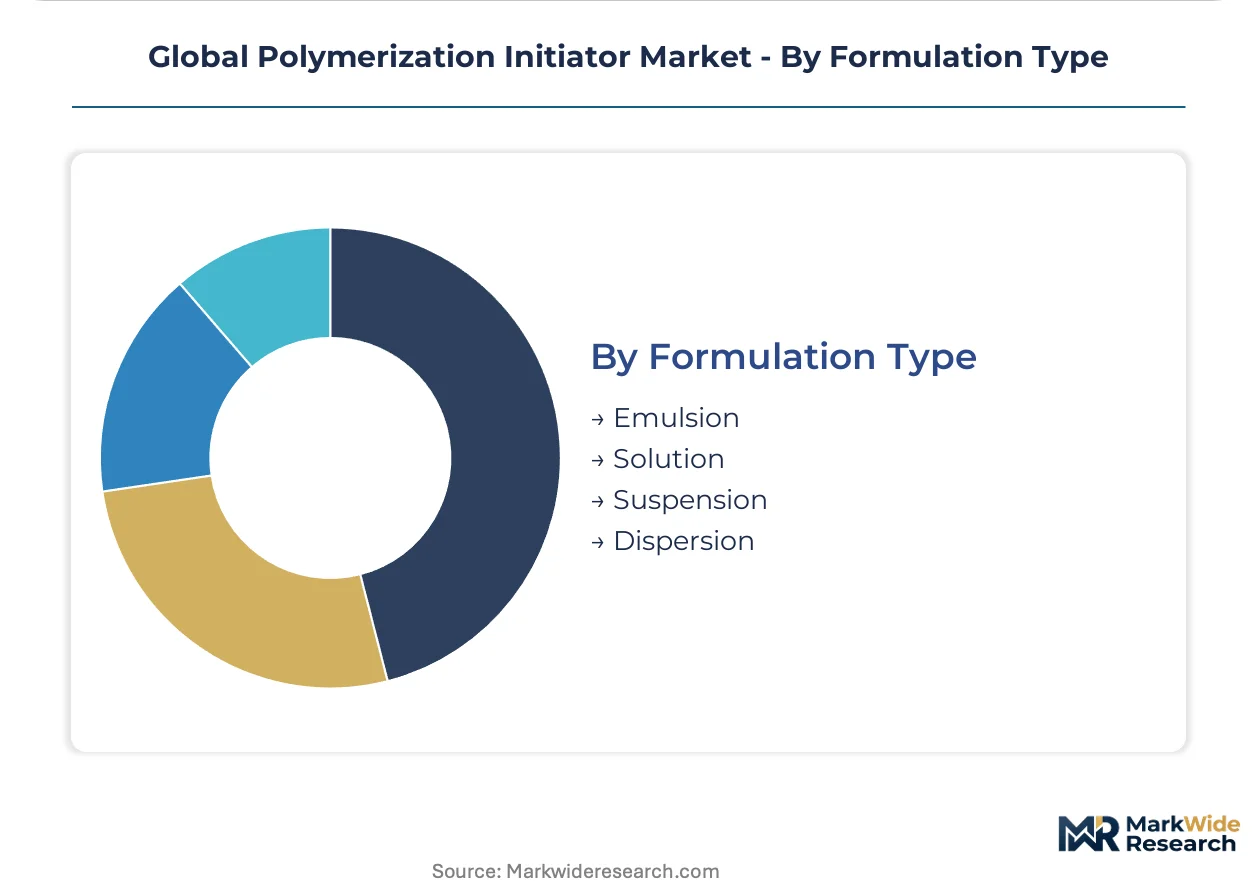
Formulation Type:
Formulation architecture determines supply chain configuration: emulsion systems require cold-chain distribution, solution systems tolerate ambient logistics.
- Emulsion:Water-based systems using azo initiators align with China's dual-carbon policy enforcement. Temperature-controlled distribution networks preserve half-life specifications through last-mile delivery to polymer producers.
- Solution:Solvent-borne peroxide systems face margin compression from chlor-alkali feedstock volatility. European producers without captive hydrogen peroxide supply struggle to match integrated competitor economics.
- Suspension:PVC production dominates this format, with bulk peroxide initiators governed by cost-per-radical efficiency metrics in high-tonnage reactor systems.
- Dispersion:Nanoparticle-photoinitiator hybrids enable thick-section curing applications previously inaccessible to conventional UV systems.
Widest logistics dependency: Emulsion. Greatest feedstock exposure: Solution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's western chemical corridor anchors initiator procurement concentration, where domestic polymer capacity expansion accelerates local sourcing for polyethylene and PVC production lines.
China
SAMR enforces GB 9685 additive purity standards that disqualify legacy peroxide grades from food-contact polymer supply chains. MEE carbon intensity benchmarks favor water-based emulsion polymerization using azo initiators over solvent-borne systems. The Yangtze River Delta concentrates photoinitiator demand from electronics packaging operations serving semiconductor manufacturers.
United States
FDA food-contact substance notifications accelerate qualification cycles for high-purity peroxides serving flexible film export markets. EPA TSCA Section 5 premanufacture review elevates compliance costs for initiators migrating into packaging applications. The Gulf Coast petrochemical corridor sustains bulk peroxide consumption through integrated hydrogen peroxide feedstock availability.
Germany
ECHA's REACH Annex XIV authorization timelines compress supplier response windows for dibenzoyl peroxide reproductive toxicity classifications. Tier-1 automotive coatings suppliers adopt hybrid photoinitiator systems for thick-section clearcoats without solvent flash-off. The North Rhine-Westphalia chemical cluster anchors European supply security through backward integration into dicumyl peroxide precursors.
India
CDSCO alignment with ICH Q3D elemental impurity guidelines mandates trace metal certification down to 10-ppb thresholds for pharmaceutical-grade azo initiators. Domestic polymer capacity additions around Gujarat concentrate local initiator procurement and reduce import dependency. Polymer producers in the western chemical corridor consolidate vendor lists to three approved suppliers per initiator class.
South Korea
MFDS pharmaceutical-grade standards intersect with semiconductor packaging specifications for photoinitiator half-life stability. Memory chip packaging operations drive demand for UV-cured adhesives with precise cure-depth control. Display lamination manufacturers in the Seoul Capital Area specify initiator dispersion technology for solvent-free processing.
Global Polymerization Initiator Market Competitive Environment
Capital-heavy producers compete with asset-light formulators across specification tiers, creating a bifurcated structure where integrated hydrogen peroxide operators capture margin in bulk peroxides while specialized photoinitiator houses command premium positioning. The vendor base organizes around three archetypes: integrated chemical conglomerates with captive feedstock, regional specialists with temperature-controlled distribution networks, and technology-focused innovators in photochemical curing systems. Dominant competitive moves include backward integration into precursor chemicals and strategic partnerships with polymer producers for co-development of application-specific initiator packages.
Among European integrated chemical producers, Arkema S.A. and LANXESS AG exemplify the feedstock-integrated archetype, while Nouryon occupies a position within the logistics-specialist tier through temperature-controlled distribution networks. These three anchors represent distinct strategic postures: captive hydrogen peroxide supply, backward integration into dicumyl peroxide precursors, and global cold-chain density for half-life-sensitive shipments respectively.
| Leading Market Players |
|---|
| Arkema S.A |
| LANXESS AG |
| BASF SE |
| Nouryon |
| United Initiators |
| Adeka Corporation |
| AkzoNobel |
| Celanese Corporation |
| NOF Corporation |
| Others |
Value Chain & Pricing Dynamics
Feedstock-integrated chemical conglomerates with captive hydrogen peroxide supply anchor pricing discipline through margin insulation against chlor-alkali volatility, while asset-light formulators compete on specification agility rather than cost position. This ownership bifurcation concentrates pricing power upstream and compresses margins for non-integrated European producers lacking backward integration into dicumyl peroxide precursors.
Pricing Analysis
Value-based pricing anchored to polymerization yield outcomes governs pharmaceutical-grade azo initiators, where 10-ppb trace metal certification commands three-tier pricing stratification across premium, standard, and economy levels. Price differentiation rests on CDSCO alignment with ICH Q3D guidelines and REACH Annex XIV authorization status. Cost compression in bulk peroxides is intensifying because hydrogen peroxide feedstock volatility destabilizes chlor-alkali co-product economics. Packaging converters in Southeast Asia exhibit highest price sensitivity, while semiconductor packaging operations in South Korea tolerate premium positioning for photoinitiator half-life stability.
Supply Chain Analysis
Certification gating through FDA food-contact substance notifications, REACH Annex XIV authorization, and China's GB 9685 standards fragments supplier qualification and elongates procurement cycles. Supply concentrates in Belgium and Germany for dicumyl peroxide precursors, India for pharmaceutical-grade azo initiators, and South Korea for photoinitiator dispersion technology. Raw material dependencies draw from hydrogen peroxide feedstock, dicumyl peroxide intermediates, and UV-absorbing chromophore precursors. Single-source vulnerability in temperature-controlled logistics for azo initiator half-life preservation creates supply chain risk. Distribution runs through Nouryon's global cold-chain density networks and regional chemical distributor partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH Annex XIV authorization timelines and China's GB 9685 purity mandates erect barrier-to-entry moats favoring pre-certified platform chemistry holders over specification laggards.
For Market Incumbents: Hedge against hydrogen peroxide feedstock volatility through captive supply arrangements or long-term offtake contracts with chlor-alkali operators. Consolidate vendor relationships with polymer producers in India's Gujarat corridor to defend share against emerging regional specialists. Certification investment in CDSCO-aligned ICH Q3D trace metal validation represents the critical lever for pharmaceutical-grade azo initiator positioning. For New Entrants and Emerging Players: Launch via temperature-controlled distribution partnerships targeting Brazil's flexible film markets where ANVISA alignment with FDA standards creates qualification openings for pre-certified suppliers. Photoinitiator-dispersion hybrids for wind turbine blade coatings represent the most penetrable application white-space. Go-to-market execution should emphasize modular dual-mechanism packages for thick-section UV curing without solvent flash-off. For Investors and Strategic Acquirers: Distressed-cycle entries favor logistics-specialist archetypes with cold-chain density in European and Asian corridors where temperature-controlled distribution networks preserve initiator half-life specifications. Long-term viability across the analysis window hinges on regulatory pre-certification asset bases rather than commodity scale. Monitor ECHA dossier evaluation timelines for dibenzoyl peroxide reproductive toxicity classifications as the signal for substitution wave magnitude.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dicumyl Peroxide Precursors | LANXESS AG's Belgian and German sites anchor European supply security against feedstock volatility. |
| Temperature-Controlled Distribution Network Expansion | Nouryon's cold-chain density preserves azo initiator half-life specifications through last-mile delivery. |
| Hybrid Photoinitiator System Development | German Tier-1 coatings suppliers modularize dual-mechanism packages for 200-micron automotive clearcoats. |
| Regulatory Pre-Certification Investment | Arkema S.A.'s integrated organic peroxide chain sustains margin capture across FDA and REACH specification tiers. |
| Regional Manufacturing Localization | Gujarat chemical corridor concentrators reduce import dependency for India's domestic polyethylene and PVC producers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant managers at peroxide manufacturing facilities, procurement leads at downstream polymer producers, distribution channel partners in temperature-controlled logistics, and technical R&D directors in photochemical curing systems. Bottom-up initiator volume estimates triangulated against top-down polymer production capacity figures from Cefic and ACC reports, SEC 10-K disclosures from integrated chemical producers, and customs trade databases tracking hydrogen peroxide derivative flows.
Granularity-level modeling operated at product-type decomposition kinetics, end-use regulatory exposure tier, application film-build specification, and regional production hub clustering. CAGRs were derived from polymer capacity expansion pipelines and initiator intensity coefficients across the projection horizon. Forecast inputs incorporated REACH Annex XIV authorization timeline probabilities, China's MEE carbon intensity benchmark enforcement trajectories, and FDA food-contact notification approval velocities for high-purity peroxide grades.
Regulatory divergence between jurisdictions, hydrogen peroxide feedstock price volatility, and temperature-controlled logistics network disruptions are the dominant revision risks to modeled initiator demand. Forecasts reflect assumptions regarding certification timeline adherence and polymer capacity commissioning schedules. A model refresh is warranted upon material change in ECHA dossier evaluation outcomes or China's GB standards amendment trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyetherketoneketone (PEKK) Market
Polymers & Resins
South America Polyvinyl Chloride (PVC) Market
Polymers & Resins
Polyvinyl Butyral (PVB) Market
Polymers & Resins
Polyimide and Imide Polymers Market
Polymers & Resins
Europe Polyvinyl Chloride (PVC) Market
Polymers & Resins
Rigid Spray Polyurethane Foam Market
Polymers & Resins
Global Amino Resin Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
Ammonium Polyphosphate (Phase II) Market
Polymers & Resins
Middle East Polyethylene Market
Polymers & Resins
Global Bio Based Polyurethane Market
Polymers & Resins
Dispersant Polymer Market
Polymers & Resins
Conductive Polymers Market
Polymers & Resins
PE Resins Market
Polymers & Resins
Global Thermally Conductive Plastics Market
Polymers & Resins
PET Foam Core Market