
 Synthetic Latex Polymers Market | 2026-2036
Synthetic Latex Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Latex Polymers Market Intelligence
REACH compliance thresholds on residual monomer content and VOC emissions is restructuring the cost-of-entry calculus for European latex producers, forcing reformulation investments that favor larger integrated players. BASF SE leverages its Ludwigshafen emulsion complex to sustain captive butadiene supply for styrene-butadiene latex. Dow Inc. anchors North American position through ethylene-based raw material integration and waterborne acrylic technology leadership. Synthomer PLC specializes in nitrile latex for medical glove applications, competing against Asian producers through Malaysian manufacturing scale.
Synthetic latex polymers comprise colloidal dispersions of polymer particles stabilized in aqueous medium, typically manufactured through emulsion polymerization at 40-60% solids content with particle diameters ranging from 50 to 500 nanometers. These materials function primarily as film-forming binders, imparting adhesion, flexibility, and durability to coatings, adhesives, and nonwoven substrates. Styrene-butadiene latex dominates volume in carpet backing and paper coating applications where cost-performance balance determines procurement decisions. Acrylic latex captures premium positioning in exterior architectural coatings due to superior UV resistance and hydrophobicity. Nitrile latex concentrates in disposable medical glove manufacturing, where Malaysian and Thai producers control upstream monomer access.
EPA New Source Performance Standards and OSHA workplace exposure limits govern US manufacturing emissions and residual monomer handling protocols, while China's MEE enforces wastewater discharge standards that raise treatment capital requirements for emulsion plants. The EU ECHA maintains SVHC candidate list scrutiny on acrylic monomers, creating registration burden differentiation between regional and imported supply. Stakeholders must monitor bio-based feedstock substitution timelines and regional carbon border adjustment mechanisms to calibrate capacity placement and product portfolio decisions.
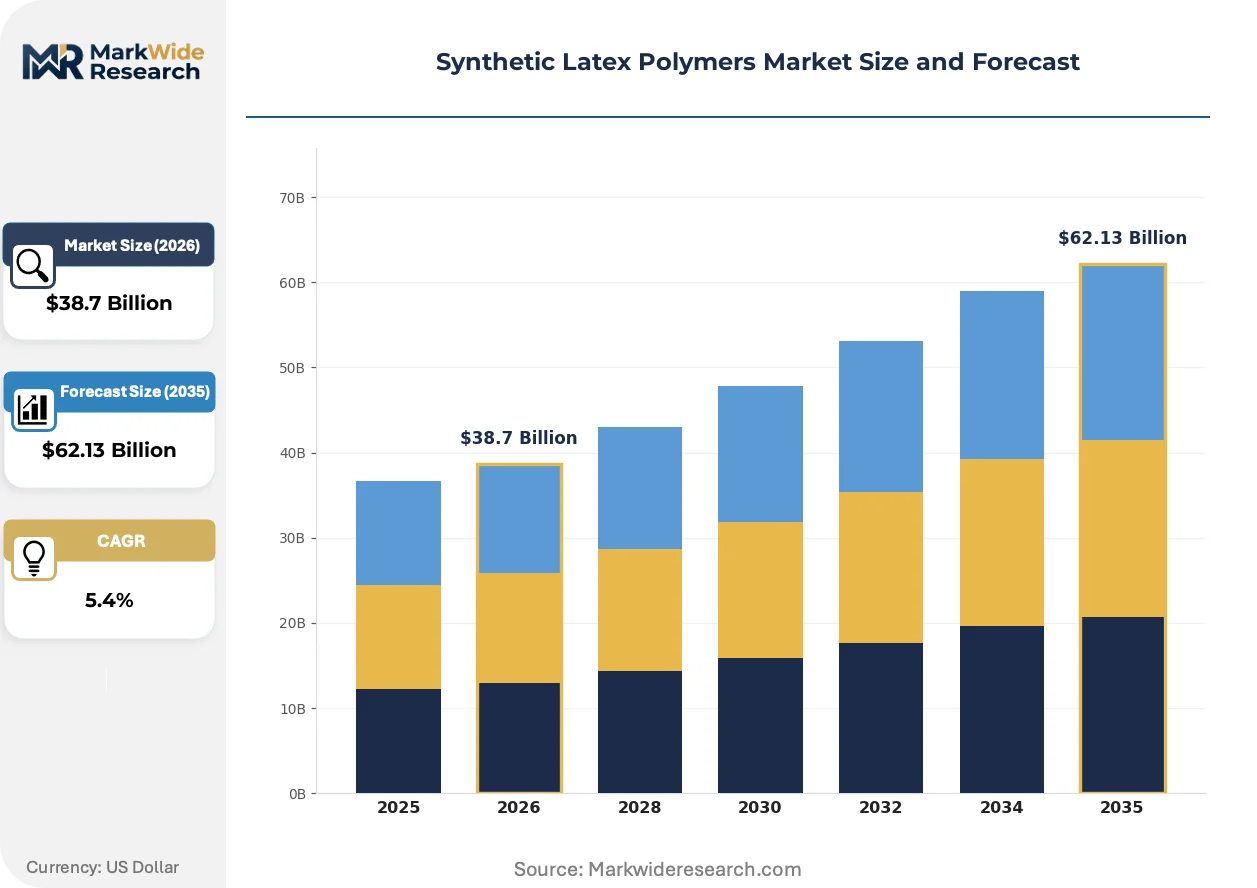
Market Dynamics
Waterborne coating mandates across automotive refinishing and architectural sectors are compressing solvent-borne capacity while redirecting capital toward emulsion polymerization infrastructure. This regulatory-driven formulation pivot is restructuring supplier economics and regional production footprints.
Growth Catalysts
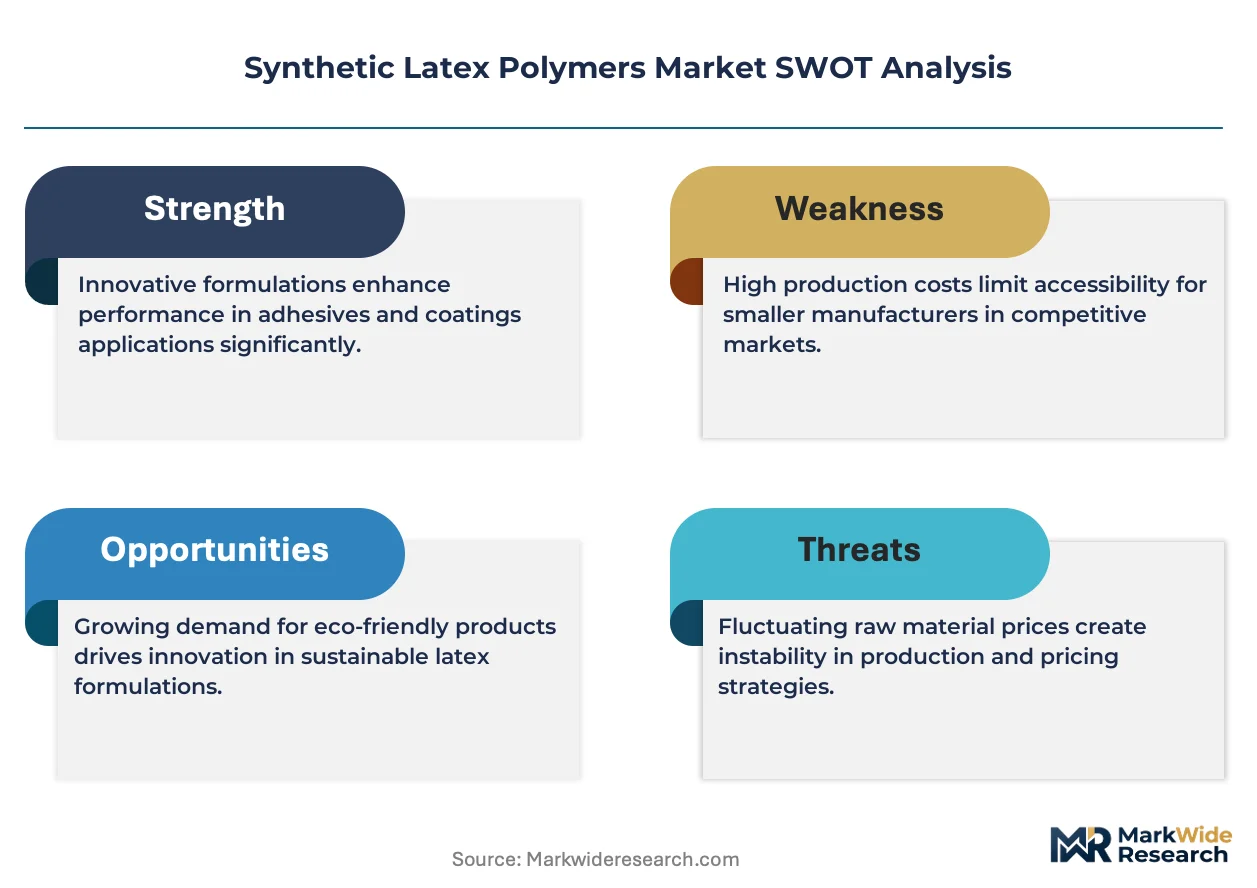
- Automotive waterborne refinish mandates:OEM collision repair networks in Germany and Japan now specify low-VOC basecoats, pulling styrene-acrylic latex volumes into certified supply chains.
- EU REACH Annex XVII VOC limits:The 2020/2184 regulation on decorative coatings is forcing architectural reformulation, expanding acrylic emulsion demand for exterior durability.
- China construction sector pull:Domestic emulsion capacity expansion in Shandong and Jiangsu provinces is reducing import dependency for carpet backing binders.
Market Restraints
- Butadiene feedstock volatility:Styrene-butadiene latex margins compress when naphtha-cracker co-product availability tightens in Gulf Coast petrochemical complexes.
- Asian nitrile latex concentration:Malaysian and Thai producers control 70% of medical glove-grade nitrile capacity, creating single-source vulnerability for European distributors.
- Residual monomer handling costs:EPA New Source Performance Standards raise wastewater treatment capital requirements for US emulsion plants below 50,000 ton annual output.
Strategic Opportunities
- Bio-based acrylic acid pathways:Fermentation-derived feedstocks from Cargill and Arkema pilot facilities offer carbon-intensity certification for EU Green Deal-aligned procurement.
- India construction chemicals penetration:Low emulsion-per-capita consumption versus China creates white space for exterior wall coating binders in Mumbai and Bangalore metro corridors.
- Digital color-matching integration:Cloud-based spectrophotometry in automotive refinish shops is unifying specification databases, favoring latex suppliers with technical service portals.
Industry Challenges
- Emulsion polymerization process control expertise:Shortage of chemical engineers with particle-size-distribution optimization experience limits debottlenecking at mid-scale plants.
- REACH SVHC registration timelines:Acrylic monomer substance evaluation dossiers face 18-month backlog at ECHA, delaying new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Latex Polymers Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylonitrile, Styrene-Butadiene, Polyvinyl Acetate, Nitrile Application: Coatings, Adhesives, Foam, Construction End User: Automotive, Textiles, Footwear, Consumer Goods Technology: Emulsion Polymerization, Solution Polymerization, Bulk Polymerization, Suspension Polymerization |
| Companies Covered | BASF SE, Dow Inc., Arkema Group, Wacker Chemie AG, Synthomer PLC, LG Chem, Asahi Kasei Corporation, Trinseo S.A., H.B. Fuller, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Latex Polymers Market Strategic Shifts & Innovations
Hybrid polymer architectures are dissolving traditional boundaries between acrylic, urethane, and silicone chemistries. This convergence is enabling single-binder solutions that previously required multi-component formulation.
Core-shell particle engineering is unifying previously incompatible performance attributes in architectural coatings. BASF and Dow have commercialized hard-soft phase-separated morphologies that deliver block resistance and low-temperature film formation simultaneously. Exterior coating contractors in Nordic markets are specifying these grades for 5°C application windows, compressing the seasonal construction calendar expansion that previously required solvent-borne alkyd alternatives.
REACH Annex XVII amendments on microplastic release are capturing polymer-containing rinse-off products. The 2023/2059 restriction forces reformulation of certain coating categories, redirecting R&D toward biodegradable film-formers. Decorative paint manufacturers in France and Italy are accelerating waterborne acrylic validation to preempt enforcement actions from national environmental agencies.
Specification consolidation among multinational paint manufacturers is compressing qualified supplier lists. AkzoNobel and PPG have reduced their emulsion vendor bases by 40% since 2020, replacing fragmented regional sourcing with global framework agreements. This concentration is most visible in European architectural coatings, where technical audit requirements now demand ISO 14001 certification and carbon footprint disclosure as table stakes for volume allocation.
Synthetic Latex Polymers Market Segmentation
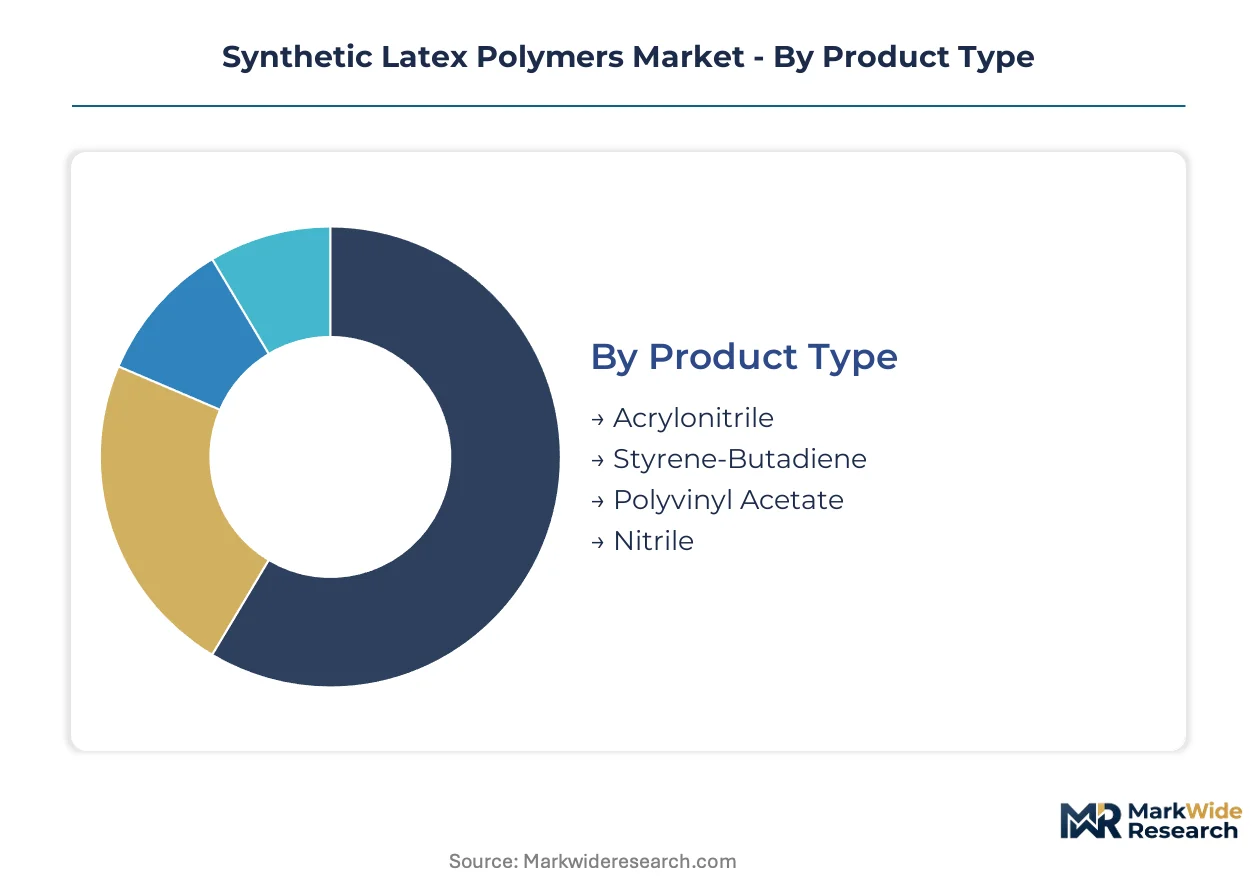
Synthetic latex polymer procurement hinges on balancing film-forming performance against feedstock cost exposure and regulatory compliance thresholds. Segmentation reveals how formulation chemistry, application requirements, and manufacturing technology intersect to determine supplier economics and buyer switching costs across automotive, construction, and medical end-uses.
Product Type:
Cost-performance positioning drives material selection, with monomer feedstock volatility compressing margins differently across each chemistry family.
- Styrene-Butadiene:Copolymer dispersion combining styrene rigidity with butadiene elasticity, manufactured through emulsion polymerization at 50% solids content. Demand concentrates in carpet backing and paper coating applications across China's Shandong manufacturing corridor, where domestic butadiene supply from naphtha crackers determines regional cost competitiveness.
- Nitrile:Acrylonitrile-butadiene copolymer delivering oil resistance and tensile strength for dipped goods manufacturing. Malaysian and Thai producers control upstream monomer access for medical glove grades, creating supply concentration that European distributors navigate through long-term offtake agreements.
- Acrylonitrile:Specialty acrylate-modified dispersions for high-performance adhesives and sealants.
- Polyvinyl Acetate:Cost-optimized homopolymer emulsions for interior architectural adhesives and wood glue formulations.
Volume sits with Styrene-Butadiene; growth tilts toward Nitrile as medical glove demand outpaces carpet sector expansion.
Application:
Formulation mandates from EU REACH and US EPA are restructuring demand toward waterborne systems that displace solvent-borne alternatives.
- Coatings:Film-forming binders for architectural and automotive refinish systems, requiring block resistance and low-temperature coalescence. OEM collision repair networks in Germany and Japan now specify low-VOC basecoats, pulling styrene-acrylic latex volumes into certified supply chains that demand ISO 14001 certification and carbon footprint disclosure.
- Adhesives:Pressure-sensitive and structural bonding applications leveraging tack and peel strength optimization. Construction sector procurement in India's Mumbai and Bangalore metro corridors is expanding consumption for tile adhesives and wall putty binders where emulsion-per-capita penetration remains below Chinese benchmarks.
- Foam:Cellular polymer structures for cushioning and insulation applications.
- Construction:Waterproofing membranes and concrete modification systems.
Coatings commands current volume share; Construction is climbing the fastest as emerging market infrastructure investment accelerates.
End User:
Customer technical requirements span from commodity price sensitivity to validated supply chain certification for regulated medical applications.
- Automotive:Waterborne refinish basecoats and interior trim adhesives requiring color-matching precision and durability testing. Cloud-based spectrophotometry integration in collision repair shops is unifying specification databases, favoring latex suppliers with technical service portals that support digital color formulation.
- Textiles:Nonwoven binders and fabric finishing treatments.
- Footwear:Adhesive systems for sole attachment and synthetic leather coating.
- Consumer Goods:Packaging adhesives and product assembly applications.
Automotive anchors premium pricing; Consumer Goods is gaining share fastest through e-commerce packaging volume expansion.
Technology:
Capital intensity and process control expertise requirements create entry barriers that favor integrated producers with particle-size-distribution optimization capabilities.
- Emulsion Polymerization:Aqueous dispersion process operating at 40-60% solids with 50-500 nanometer particle diameters, stabilized by surfactant systems. EPA New Source Performance Standards raise wastewater treatment capital requirements for US plants below 50,000 ton annual output, consolidating production toward larger integrated facilities.
- Solution Polymerization:Homogeneous reaction in organic solvent media requiring solvent recovery systems.
- Bulk Polymerization:Mass polymerization without diluent, producing high-purity grades for specialty applications.
- Suspension Polymerization:Bead-form process with aqueous dispersant for controlled particle morphology.
Emulsion Polymerization dominates installed capacity; Solution Polymerization shows steepest expansion trajectory for high-performance adhesive grades requiring narrow molecular weight distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the largest share of styrene-butadiene and acrylic latex volumes, with construction sector expansion and domestic emulsion capacity growth creating sustained pull. Regional procurement patterns diverge sharply between mature markets with stringent VOC regulations and emerging economies prioritizing cost-performance balance in infrastructure applications.
United States
Automotive refinishing networks in Michigan and Ohio specify waterborne basecoats for collision repair, compressing solvent-borne capacity. EPA New Source Performance Standards raise wastewater treatment capital requirements for emulsion plants below 50,000 ton annual output. Gulf Coast petrochemical complexes in Texas and Louisiana supply naphtha-cracker co-product butadiene for regional styrene-butadiene latex production.
Germany
OEM collision repair certification programs in Stuttgart and Munich mandate low-VOC coatings, pulling styrene-acrylic latex into qualified supply chains. EU REACH Annex XVII limits on decorative coatings force architectural reformulation toward exterior-durable acrylic emulsions. BASF SE leverages its Ludwigshafen emulsion complex to sustain captive butadiene supply for integrated styrene-butadiene production.
China
Construction sector expansion in Shandong and Jiangsu provinces drives domestic emulsion capacity investment, reducing import dependency for carpet backing binders. MEE wastewater discharge standards raise treatment capital requirements for new emulsion plants. Yangtze River Delta manufacturing clusters concentrate acrylic latex output for architectural coatings serving Shanghai and Hangzhou metro construction.
Malaysia
Medical glove manufacturing in the Klang Valley and Penang anchors nitrile latex demand, with producers controlling upstream acrylonitrile and butadiene monomer access. National environmental regulations on industrial effluent shape plant upgrade timelines. Malaysian manufacturing scale competes against Thai producers for European distributor offtake agreements in disposable glove supply chains.
India
Low emulsion-per-capita consumption versus Chinese benchmarks creates expansion space for exterior wall coating binders in Mumbai and Bangalore metro corridors. BIS standards on architectural coating performance guide procurement specifications for infrastructure projects. Western India chemical clusters in Gujarat are attracting emulsion polymerization investments to serve domestic construction chemicals demand.
Synthetic Latex Polymers Market Key Industry Players
German and US producers anchor one tier through integrated petrochemical feedstock access; Malaysian and Thai specialists hold concentrated positions in nitrile latex for medical applications. The supplier base stratifies between scale-driven integrated players with captive monomer supply and regional emulsion specialists serving construction sector procurement. Three archetypes dominate: petrochemical-integrated multinationals with backward integration into butadiene and acrylic acid; Southeast Asian nitrile latex specialists with medical glove supply chain lock-in; and regional emulsion compounders targeting architectural coatings through technical service proximity. Competitive moves center on capacity expansion in high-growth Asian markets and reformulation partnerships with paint manufacturers facing REACH compliance deadlines.
Within the integrated multinational tier, BASF SE and Dow Inc. exemplify petrochemical-backed emulsion production with captive raw material supply. Synthomer PLC occupies a specialist position in nitrile latex manufacturing, competing through Malaysian production scale against regional Asian producers. These three companies represent distinct strategic postures: integrated chemical conglomerates leveraging feedstock economics, and focused latex specialists capturing value in regulated medical applications through manufacturing concentration.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Arkema Group |
| Wacker Chemie AG |
| Synthomer PLC |
| LG Chem |
| Asahi Kasei Corporation |
| Trinseo S.A. |
| H.B. Fuller |
| Others |
Cost & Logistics Intelligence
EU REACH Annex XVII VOC limits on decorative coatings gate qualified supply and premium-tier pricing access, forcing reformulation investments that stratify emulsion suppliers into certified and non-certified tiers with corresponding price differentials.
Pricing Analysis
Short lead-time premiums and spot inventory discounts structure procurement negotiations across synthetic latex polymer grades. Three-tier pricing separates REACH-certified emulsions from standard architectural grades and economy carpet backing binders. Price differentiation rests on carbon footprint disclosure and ISO 14001 certification as table stakes for multinational paint manufacturer frameworks. Cost compression in styrene-butadiene latex is intensifying because naphtha-cracker co-product butadiene availability tightens in Gulf Coast complexes. Carpet backing procurement teams show highest price sensitivity; automotive refinish collision repair networks demonstrate lowest sensitivity due to OEM certification requirements.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke patterns for emulsion polymer feedstock logistics. Manufacturing concentrates in China, Germany, and Malaysia for distinct chemistries: Shandong corridor for styrene-butadiene, Ludwigshafen complex for acrylic dispersions, Klang Valley for nitrile medical grades. Raw material flows draw from naphtha crackers for butadiene, propylene oxidation units for acrylic acid, and acrylonitrile plants for nitrile latex. Single-source vulnerability concentrates in Malaysian and Thai medical glove-grade nitrile capacity controlling upstream monomer access. Distribution runs through qualified supplier lists managed by AkzoNobel and PPG procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive butadiene supply and in-house acrylic acid production determine margin capture against feedstock volatility.
For Market Incumbents: Extend backward integration into butadiene through naphtha-cracker partnerships or long-term offtake agreements with Gulf Coast petrochemical complexes. Add emulsion capacity in Shandong and Jiangsu provinces to defend position against domestic Chinese producers expanding technical service capabilities. Bio-based acrylic acid pathway investments offer carbon-intensity certification differentiation as EU Green Deal procurement standards tighten.
For New Entrants and Emerging Players: Begin with exterior wall coating binders in Mumbai and Bangalore metro corridors where emulsion-per-capita consumption trails Chinese benchmarks by substantial margins. Target construction chemicals distribution partnerships with regional applicator networks rather than direct multinational paint manufacturer qualification. White space exists in cloud-based spectrophotometry technical service portals supporting automotive refinish digital color-matching integration.
For Investors and Strategic Acquirers: ECHA SVHC registration backlog clearing for acrylic monomer substance evaluation dossiers is the leading indicator that new product introduction velocity will accelerate for compliant suppliers. Mid-scale emulsion plants with particle-size-distribution optimization expertise represent attractive acquisition targets as EPA wastewater treatment capital requirements consolidate production toward integrated players. Watch for bio-based feedstock substitution timelines and regional carbon border adjustment mechanism announcements as inflection signals for portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive butadiene supply from Ludwigshafen naphtha crackers insulates BASF against Gulf Coast volatility. |
| Capacity Expansion | Shandong and Jiangsu province emulsion plants reduce Chinese import dependency for carpet backing binders. |
| Green Manufacturing Transition | Fermentation-derived acrylic acid from Cargill pilot facilities enables EU Green Deal-aligned procurement certification. |
| Long-term Supply Agreement | European distributor offtake contracts with Malaysian producers mitigate medical glove-grade nitrile concentration risk. |
| Joint Venture | Western India chemical clusters in Gujarat attract partnership investments to serve domestic construction chemicals demand. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with emulsion plant managers, procurement leads at downstream paint manufacturers, distribution channel partners, and technical R&D directors combined with ACC and Cefic industry reports, SEC 10-K disclosures, and ECHA registration dossiers. Bottom-up capacity and consumption modeling triangulated against top-down macroeconomic drivers across the synthetic latex polymer value chain.
Data-stream reconciliation across emulsion polymerization technology types, product chemistry families, application end-uses, and regional production hubs generated volume and value outputs over the projection horizon. Segmentation dimensions modeled include grade tier by residual monomer content, end-use industry from automotive refinish to medical gloves, packaging format bulk versus totes, and regional production cluster concentration. CAGRs derived from elasticity-adjusted demand projections incorporating feedstock cost pass-through assumptions and regulatory compliance cost burdens.
Underlying measurement precision varies by segment; coatings and adhesives applications carry tighter precision than emerging construction chemical penetration estimates. Forecasts reflect assumptions on REACH enforcement consistency, naphtha cracker operating rates, and bio-based feedstock scale-up timelines. Periodic stress-testing of base assumptions is recommended against carbon border adjustment mechanism implementation and Malaysian nitrile supply disruption scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyolefin Wax Market
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
Thermoplastic Starch (TPS) Market
Polymers & Resins
China Engineering Plastics Market
Polymers & Resins
Brazil Engineering Plastics Market
Polymers & Resins
Nylon Resins Market
Polymers & Resins
Bio-Based Thermoplastic Elastomer Market
Polymers & Resins
Copolyesters Market
Polymers & Resins
Marine-grade Polyurethane Market
Polymers & Resins
Polyphenylene Sulfide Market
Polymers & Resins
Propylene Terpolymer Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
Europe Medical Polyethylene Market
Polymers & Resins
UV Stabilized Thermoplastic Elastomer for Automotive Market
Polymers & Resins
Global Colored PU Foams Market
Polymers & Resins
Polymer Seals Market